
 Global Dental Membrane and Bone Graft Substitutes Market | 2026-2036
Global Dental Membrane and Bone Graft Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Membrane and Bone Graft Substitutes Market Foresight
Market Context with Strategic Players
Collagen derived from porcine and bovine sources is broadening cost structures across membrane portfolios as manufacturers seek alternatives to synthetic polymers. Geistlich Pharma AG leverages its Swiss manufacturing heritage to dominate the xenograft segment with proprietary collagen processing. Zimmer Biomet competes through hospital system contracts that bundle dental implants with regenerative accessories. BioHorizons specializes in titanium-reinforced barrier membranes for complex ridge augmentation cases.
Technical Definition and Structural Segments
Dental membranes and bone graft substitutes comprise biocompatible barriers and osteoconductive or osteoinductive scaffolds used to regenerate alveolar bone and periodontal tissue, typically manufactured from processed collagen, beta-tricalcium phosphate, or demineralized bone matrix with pore sizes calibrated between 100 and 400 microns to support vascularization. Resorbable membranes lead product-type revenue due to elimination of re-entry surgery, while xenografts capture the fastest growth in graft materials as processing purity improves and religious acceptance broadens. Guided bone regeneration anchors application-level demand because implant placement failures drive predictable membrane utilization, whereas socket preservation represents an emerging margin pool as general dentists adopt grafting into extraction protocols.
Regulatory Frame and Forward-Looking Close
The FDA enforces 21 CFR Part 820 quality system regulations for dental graft manufacturers, while the EU Medical Device Regulation requires notified body certification under stricter biocompatibility testing than the prior Medical Device Directive. Japan's PMDA mandates clinical data from domestic sites for xenograft registration, creating a staggered market entry pattern across developed economies. Stakeholders must monitor how FDA guidance on animal-derived materials evolves, as tightening BSE-related sourcing rules could force supply chain restructuring for collagen-based products.
Market Dynamics
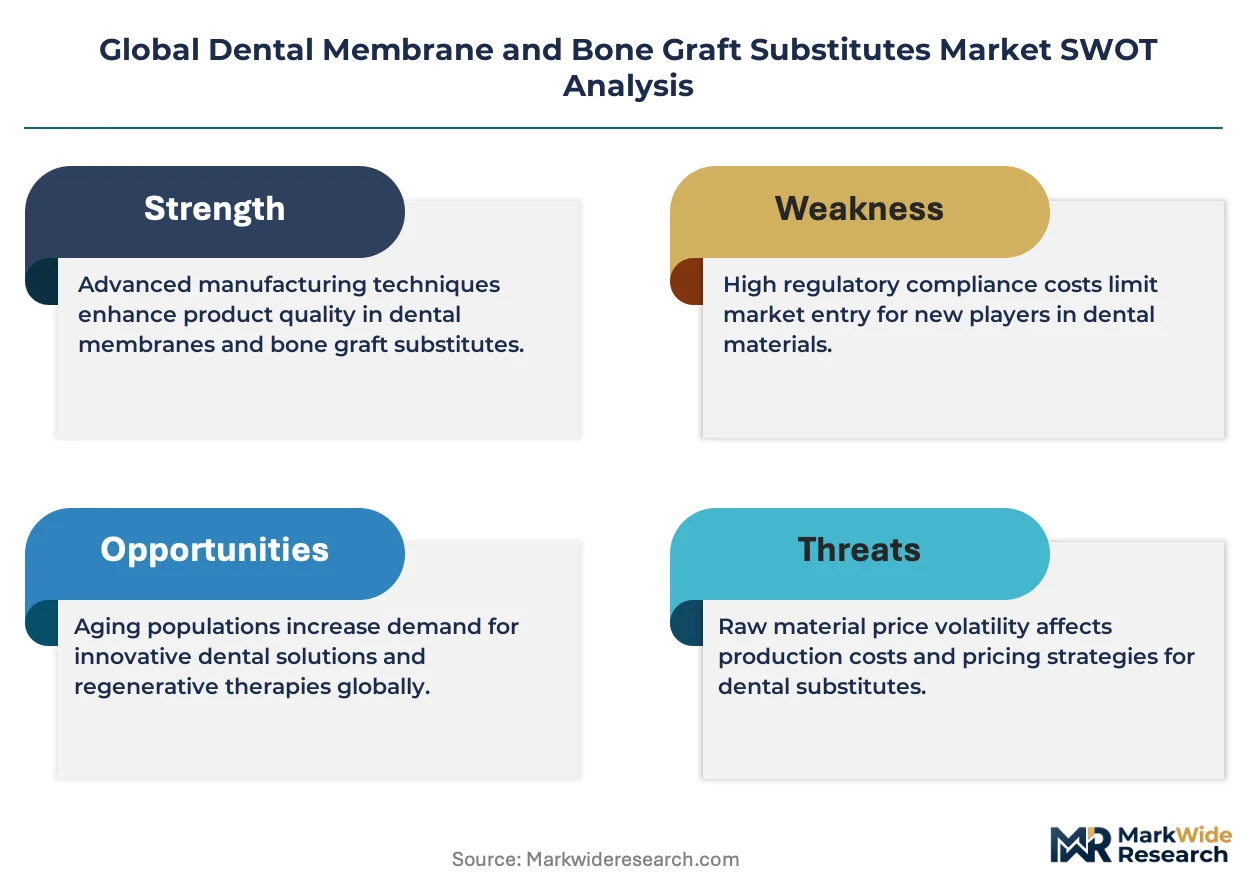
Implantology's migration from specialty to standard-of-care practice is restructuring demand architecture across dental membrane and bone graft substitutes, compressing decision cycles and expanding the addressable clinician base beyond oral surgeons to general practitioners.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The streamlined predicate-device route accelerates product introductions for collagen barrier membranes, reducing time-to-revenue for manufacturers with established biocompatibility dossiers.
- Xenograft Processing Purity:Advancements in viral inactivation and antigen removal protocols for porcine-derived materials are expanding addressable patient populations previously excluded by religious or safety concerns.
- Germany Manufacturing Cluster:Concentrated expertise in regenerative biomaterials around Basel and Freiburg generates supplier spillovers and specialized workforce pools that lower production costs for membrane portfolios.
Market Restraints
- BSE-Related Sourcing Rules:Tightening FDA guidance on bovine collagen origin documentation threatens supply chain continuity for manufacturers dependent on South American hide processors.
- Titanium Price Volatility:Reinforced membrane producers face margin compression from spot-market fluctuations in surgical-grade titanium mesh feedstock.
- Synthetic Polymer Performance Ceiling:Polytetrafluoroethylene barriers exhibit inferior tissue integration compared to collagen alternatives, limiting expansion in aesthetic anterior cases.
Strategic Opportunities
- India Dental Infrastructure Buildout:Government clinic expansion and medical tourism investment create first-mover advantages for xenograft suppliers establishing local sterilization partnerships.
- Digital Surgical Planning Convergence:Integration of cone-beam CT data with 3D-printed patient-specific membranes enables premium pricing for complex ridge augmentation procedures.
- EU MDR Notified Body Certification:Early compliance with strengthened biocompatibility testing requirements positions suppliers for preferential hospital system contracting across France and Italy.
Industry Challenges
- Periodontal Regeneration Protocol Standardization:Absence of consensus surgical technique guidelines complicates clinical training and reimbursement coding for membrane-assisted procedures.
- Animal-Derived Material Traceability:Batch-level documentation requirements under EU Veterinary Health Certificates impose administrative overhead on collagen supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Membrane and Bone Graft Substitutes Market |
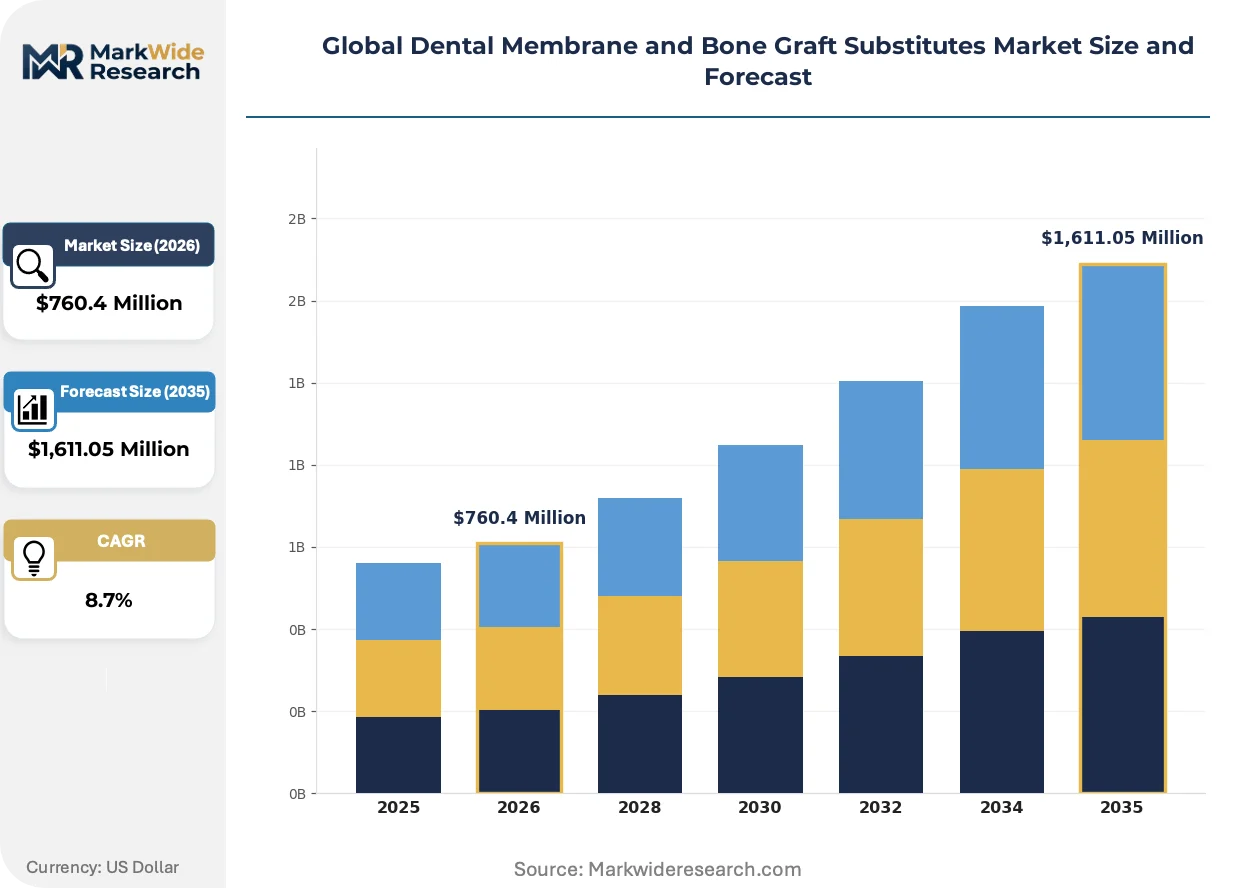
| Market Size in 2026 | $760.4 Million |
| Market Size in 2035 | $1,611.05 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
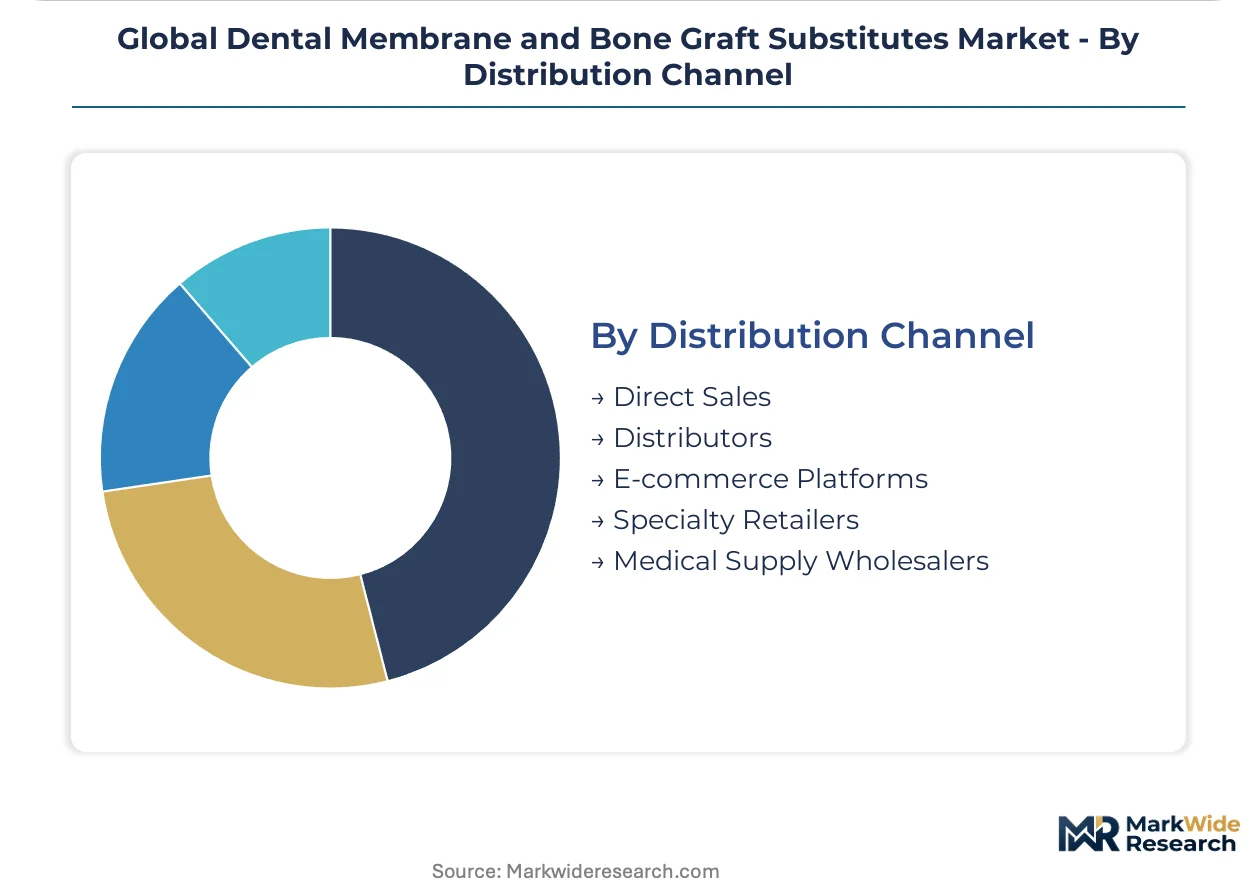
| Segmentation | Product Type: Resorbable Membranes, Non-Resorbable Membranes, Allografts, Xenografts, Synthetic Grafts Application: Guided Bone Regeneration, Ridge Augmentation, Sinus Lift, Periodontal Defect Repair, Socket Preservation End User: Dental Clinics, Oral Surgeons, Periodontists, Maxillofacial Centers, Prosthodontists Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Specialty Retailers, Medical Supply Wholesalers |
| Companies Covered | Dentsply Sirona, Institut Straumann AG, Zimmer Biomet, Medtronic, Geistlich Pharma AG, BioHorizons, Envista Holdings Corporation, RTI Surgical Holdings, Botiss Biomaterials GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Membrane and Bone Graft Substitutes Market Shifts & Advancements
Biomaterial science convergence with digital dentistry workflows is redefining product value propositions, shifting competitive differentiation from raw material sourcing to integrated regenerative ecosystems.
Cross-linked collagen membranes with extended resorption profiles are electrifying complex ridge augmentation protocols by maintaining barrier function beyond twelve weeks. Oral surgeons in academic medical centers are adopting these formulations for staged implant placements requiring substantial vertical bone gain. The technology is electrifying premium segment growth while compressing demand for conventional four-week resorption products.
EU Medical Device Regulation enforcement through notified body recertification deadlines is compressing manufacturer compliance timelines for legacy collagen products. Stricter biocompatibility testing requirements under MDR Annex I are forcing portfolio rationalization among mid-tier suppliers lacking dedicated regulatory affairs capacity. Dental membrane categories with predicate-device histories face disproportionate documentation burdens compared to novel synthetic entrants.
Group purchasing organization consolidation among United States dental service organizations is concentrating procurement leverage for regenerative accessories. Independent oral surgery practices are losing price negotiation autonomy as DSOs centralize implant and membrane purchasing across multi-state networks. California and Texas markets exhibit the most advanced DSO penetration, with bundled contract terms now standard for affiliated specialists.
Global Dental Membrane and Bone Graft Substitutes Market Segmentation
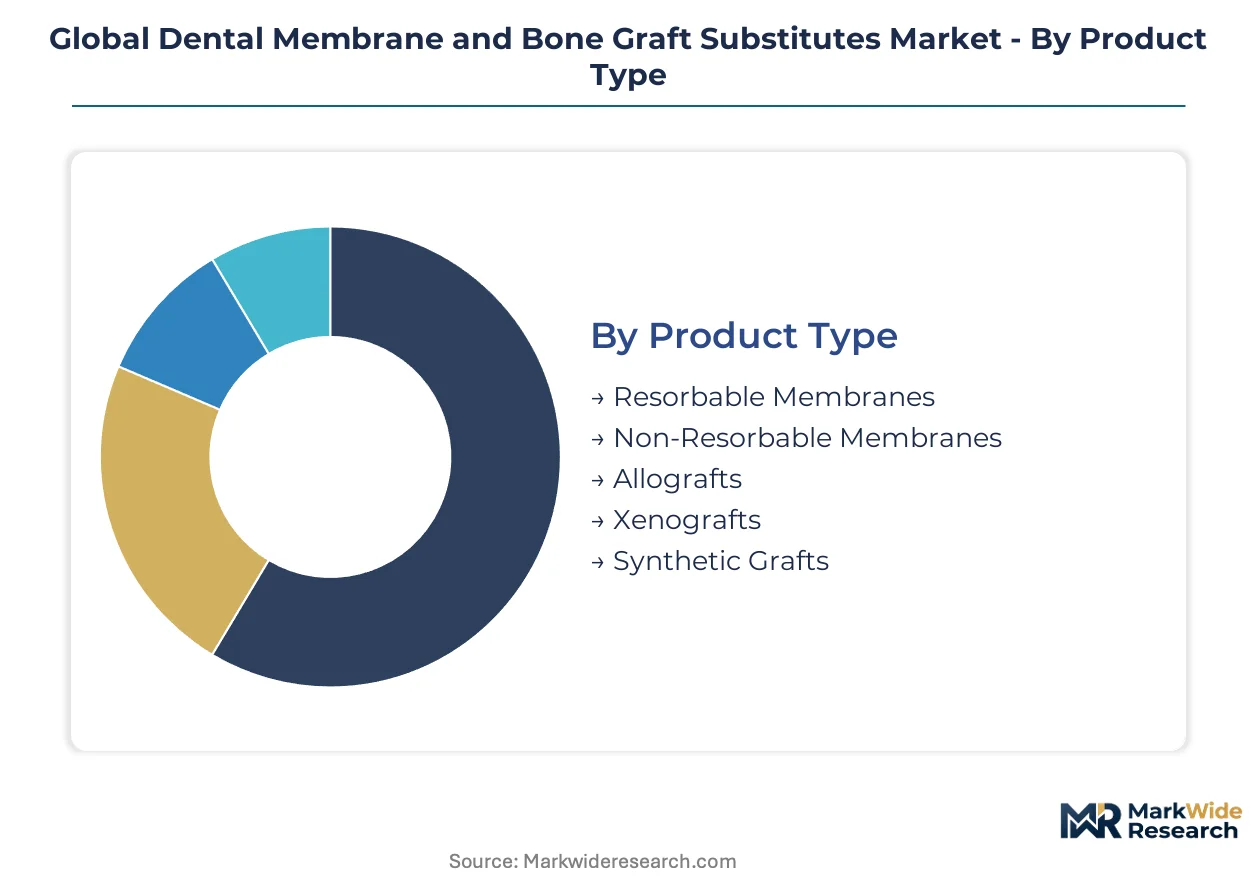
Segmentation in dental regenerative materials reveals how clinical workflow integration and reimbursement coding shape purchasing behavior. Product portfolios must align with procedure-specific performance requirements while navigating distinct procurement channels across practice types.
Product Type:
Upgrade cycles in membrane technology are accelerating as resorbable formulations with extended barrier function displace earlier-generation products in complex cases.
- Resorbable Membranes:Cross-linked collagen barriers with calibrated resorption profiles between 4-24 weeks eliminate re-entry surgery. Demand clusters in private oral surgery practices across Germany and Switzerland where Straumann and Geistlich anchor premium distribution networks.
- Xenografts:Porcine and bovine-derived scaffolds processed through viral inactivation protocols deliver osteoconductive matrices with pore architectures optimized for vascularization. Religious acceptance expansion in Middle Eastern markets and processing purity improvements are broadening addressable patient populations.
- Non-Resorbable Membranes:Polytetrafluoroethylene and titanium-reinforced barriers serve cases requiring extended mechanical support beyond six months.
- Allografts:Demineralized bone matrix from human tissue banks provides osteoinductive signaling for socket preservation protocols.
- Synthetic Grafts:Beta-tricalcium phosphate and hydroxyapatite formulations appeal to clinicians seeking to avoid animal-derived materials entirely.
Volume placements concentrate in Resorbable Membranes; the faster expansion belongs to Xenografts.
Application:
Procedure reimbursement tiers and implant success rate sensitivity determine margin capture across clinical indications.
- Guided Bone Regeneration:Barrier membrane placement concurrent with implant surgery addresses deficient alveolar ridges. Academic medical centers in Basel and Freiburg drive protocol standardization through continuing education programs.
- Socket Preservation:Immediate grafting post-extraction prevents ridge collapse and simplifies future implant placement. General dentistry practices in California and Texas DSO networks are adopting this into standard extraction workflows.
- Ridge Augmentation:Horizontal and vertical bone gain procedures require titanium-reinforced membranes or staged grafting approaches.
- Sinus Lift:Maxillary posterior rehabilitation demands substantial vertical bone regeneration with xenograft or allograft particulate.
- Periodontal Defect Repair:Intrabony and furcation defects utilize resorbable membranes in conjunction with root conditioning.
Revenue density peaks in Guided Bone Regeneration; Socket Preservation is climbing the fastest as generalist adoption accelerates.
End User:
Customer type stratification reflects divergent procurement autonomy and technical sophistication requirements.
- Oral Surgeons:Specialists performing complex ridge augmentation and full-arch rehabilitation specify premium membrane formulations with extended resorption profiles.
- Dental Clinics:General practice settings concentrate volume in socket preservation and straightforward guided bone regeneration with standard resorbable barriers.
- Periodontists:Tissue regeneration specialists drive demand for combination therapy products integrating membranes with growth factors.
- Maxillofacial Centers:Hospital-based trauma and reconstruction units utilize bulk allograft and synthetic scaffolds for large defect management.
- Prosthodontists:Implant-focused restorative specialists prioritize predictable soft tissue outcomes in aesthetic zone cases.
Procurement leverage pools in Dental Clinics; technical specification authority rests with Oral Surgeons.
Distribution Channel:
Channel structure reflects inventory carrying costs and regulatory documentation burdens for animal-derived materials.
- Distributors:Specialized dental surgical distributors with cold-chain capabilities dominate xenograft and allograft logistics in European markets.
- Direct Sales:Manufacturer field forces serve high-volume oral surgery groups and DSO headquarters with consolidated implant-membrane bundling.
- E-commerce Platforms:Digital procurement portals gain traction among independent practitioners for standard resorbable membrane replenishment.
- Specialty Retailers:Regional dental supply houses maintain relationships with smaller practices requiring technical consultation.
- Medical Supply Wholesalers:Broad-line distributors serve hospital systems with consolidated orthopedic and dental regenerative product procurement.
Transaction volume flows through Distributors; E-commerce Platforms are expanding most quickly among independent practitioners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates regenerative dental manufacturing around Basel and Freiburg, where dense supplier networks and specialized workforce pools lower production costs for membrane portfolios. Oral surgeons in private practice represent the fastest-expanding buyer segment as implantology becomes standard care across developed economies.
United States
DSO consolidation in California and Texas compresses procurement autonomy for independent oral surgeons while centralizing implant-membrane bundling across multi-state networks. FDA's 510(k) clearance pathway for bone grafting materials shapes product development timelines and accelerates predicate-device introductions. Boston and New York academic medical centers drive protocol standardization through continuing education programs for ridge augmentation techniques.
Germany
Straumann and Geistlich anchor a dense manufacturing cluster near the Swiss border that generates supplier spillovers for collagen processing expertise. EU Medical Device Regulation enforcement through notified body recertification deadlines compresses compliance timelines for legacy membrane products. The Freiburg-Basel corridor concentrates xenograft processing facilities and specialized sterilization infrastructure.
Switzerland
Geistlich Pharma leverages Swiss manufacturing heritage to dominate xenograft segments with proprietary collagen processing capabilities. Swissmedic maintains stringent biocompatibility testing requirements that exceed prior EU Medical Device Directive standards. The Basel metropolitan area hosts concentrated research facilities for cross-linked membrane formulations with extended resorption profiles.
Japan
PMDA mandates clinical data from domestic sites for xenograft registration, creating staggered market entry patterns compared to Western approvals. Tokyo and Osaka academic dental centers drive adoption of titanium-reinforced barriers for complex ridge augmentation cases. Medical device reimbursement coding under national health insurance influences product selection for periodontal regeneration procedures.
India
Government clinic expansion and medical tourism investment create first-mover opportunities for xenograft suppliers establishing local sterilization partnerships. CDSCO regulatory pathways for animal-derived materials require viral inactivation documentation that mirrors FDA sourcing standards. Mumbai and Delhi dental infrastructure buildout concentrates demand among emerging private practice networks adopting implantology protocols.
Global Dental Membrane and Bone Graft Substitutes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium membrane portfolios consolidating around heritage collagen processors while synthetic graft entrants fragment the mid-tier. The vendor base organizes into three strategic archetypes: integrated implant-membrane bundlers, pure-play regenerative biomaterial specialists, and diversified orthopedic crossovers. M&A activity concentrates on collagen processing capabilities and regional sterilization infrastructure. Geographic expansion through distributor partnerships represents the dominant competitive move for mid-cap suppliers lacking direct sales forces.
Among heritage European specialists, Geistlich Pharma AG and Institut Straumann AG occupy positions that exemplify the integrated premium-tier archetype, combining proprietary processing expertise with dense academic medical center relationships. Zimmer Biomet represents the diversified orthopedic crossover model, leveraging hospital system contracts that bundle dental implants with regenerative accessories. These three anchors demonstrate how competitive positioning depends on supply chain control over animal-derived material sourcing and regulatory dossier depth across multiple jurisdictions.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Institut Straumann AG |
| Zimmer Biomet |
| Medtronic |
| Geistlich Pharma AG |
| BioHorizons |
| Envista Holdings Corporation |
| RTI Surgical Holdings |
| Botiss Biomaterials GmbH |
| Others |
Supply & Pricing Matrix
DSO procurement consolidation across California and Texas dental service organizations anchors pricing power with volume bundlers, compressing margins for standalone membrane suppliers while rewarding integrated implant-membrane bundlers with multi-year contract stability.
Pricing Analysis
Volume placements concentrate in standard resorbable membranes with four-to-eight-week resorption profiles, while premium cross-linked formulations with extended barrier function capture disproportionate margin per unit. Pricing stratifies across premium, standard, and economy tiers based on resorption duration and collagen cross-linking density, with FDA 510(k) predicate-device status commanding modest brand premiums. Cost compression in standard-tier products is intensifying because DSOs centralize purchasing across multi-state networks. Independent oral surgeons exhibit highest price sensitivity due to eroded negotiation autonomy, whereas academic medical centers prioritize technical performance over per-unit cost.
Supply Chain Analysis
Collagen feedstock supply rests on South American bovine hide processors and specialized porcine tissue rendering facilities in Germany and Switzerland. Raw material dependencies include viral-inactivated collagen matrices, surgical-grade titanium mesh for reinforced membranes, and sterilization-grade packaging films. Single-source vulnerability concentrates in Swiss sterilization infrastructure for xenograft terminal processing. Distribution runs through specialized dental surgical distributors with cold-chain capabilities in European markets, while direct sales forces serve consolidated DSO headquarters in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into collagen rendering and sterilization infrastructure is accelerating competitive separation, with players controlling upstream tissue sourcing and downstream regulatory dossiers capturing sustainable margin advantages.
For Market Incumbents: Acquire regional sterilization partnerships to secure xenograft terminal processing capacity and defend against synthetic graft substitutes encroaching on religious-sensitive patient segments. Consolidate distributor relationships in the Freiburg-Basel corridor to lock in specialized workforce pools and lower per-unit logistics overhead for membrane portfolios. For New Entrants and Emerging Players: Enter via socket preservation protocols in India government clinic expansion zones, where local sterilization partnerships create first-mover positioning before heritage suppliers establish domestic processing. Target general dentistry practices in emerging private practice networks adopting implantology standards, leveraging e-commerce platforms for standard resorbable membrane replenishment to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: The window for entry favors mid-cap suppliers with dedicated EU MDR regulatory affairs capacity and established collagen processing capabilities. Long-term viability hinges on controlling animal-derived material traceability documentation under tightening veterinary health certificate requirements. Watch FDA guidance evolution on BSE-related sourcing rules as the critical inflection signal for forced supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Early compliance positions suppliers for preferential hospital contracting across France and Italy. |
| Digital Surgical Planning Integration | Cone-beam CT convergence with 3D-printed patient-specific membranes enables premium pricing for complex ridge augmentation. |
| Local Sterilization Partnership Formation | Domestic processing infrastructure in India and Middle Eastern markets reduces regulatory lag and accelerates market entry. |
| Cross-Linked Membrane Formulation Development | Extended resorption profiles beyond twelve weeks capture premium segment growth from academic medical centers. |
| DSO Direct Sales Force Expansion | Manufacturer field forces serving consolidated implant-membrane bundling secure multi-year contract stability. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with oral surgeons, GPO contracts managers, biomedical engineers, and dental distributor procurement leads. FDA 510(k) clearance databases, EU MDR notified body certification registries, PMDA submission records, and hospital purchasing system data provided validation anchors. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across product-type and application segments.
Granularity-level modeling tracked resorption profile duration, collagen source origin, and reinforcement architecture as technical differentiation dimensions alongside standard product-type, application, end-user, and geographic splits. CAGRs were derived from fitted growth curves calibrated to procedure adoption rates and reimbursement coding evolution. Forecast inputs incorporated DSO penetration trajectories in United States markets and EU MDR compliance cost pass-through assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden FDA BSE sourcing rule tightening or major DSO insolvency events. Forecasts reflect documented assumptions on implantology standard-of-care migration rates and xenograft religious acceptance expansion. A small set of named triggers—regulatory guidance shifts, DSO consolidation acceleration, and synthetic graft performance breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Materials for 3D Printing Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Dental Putty Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Dental Alloys Market
Dental Materials
Dental Plaster Market
Dental Materials
Dental Gypsum Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Acrylic Dental Material Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Dental Amalgam Market
Dental Materials
Nanotechnology Toothpaste Formulations Market
Dental Materials
Dental Wax Market
Dental Materials
Artificial Teeth Market
Dental Materials
Dental Impression Material Market