
 Microfluidics Prototype Market | 2026-2036
Microfluidics Prototype Market Size, Share, and Industry Trends Forecast 2026-2036
Microfluidics Prototype Market Outlook
Prototype customization revenue is reshaping margin distribution across the microfluidics value chain, shifting value capture from standardized chip production toward application-specific design services. Dolomite Microfluidics leverages its modular platform architecture to dominate high-complexity prototyping workflows. Potomac anchors North American demand through precision micromachining capabilities for polymer and glass substrates. ALine, Inc. differentiates via integrated fluidic circuit design that compresses development cycles for diagnostic developers.
Microfluidics prototypes are miniaturized fluid-handling systems fabricated with channel dimensions typically ranging from tens to hundreds of micrometers, engineered to manipulate precise liquid volumes for biochemical reactions, cell sorting, or particle detection. Their primary commercial purpose lies in de-risking product concepts before committing to scaled manufacturing of lab-on-a-chip or droplet-based platforms. Lab-on-a-chip systems command premium pricing due to integration complexity and regulatory validation requirements, while droplet-based systems represent the fastest-expanding segment driven by single-cell analysis demand. Continuous flow systems retain mature positioning in chemical analysis applications where protocol standardization reduces customization needs.
FDA diagnostic device regulations and ISO 13485 quality management standards govern prototype-to-product transitions, with FDA pre-submission pathways shaping development timelines and investment decisions for commercializing microfluidic diagnostics. REACH chemical restrictions in Europe limit certain polymer selections for prototypes destined for clinical translation, compelling material qualification investments early in design cycles. Stakeholders must monitor evolving regulatory harmonization between FDA and EMA on microfluidic-based companion diagnostics, as divergence in validation requirements would fragment development strategies and duplicate compliance costs.
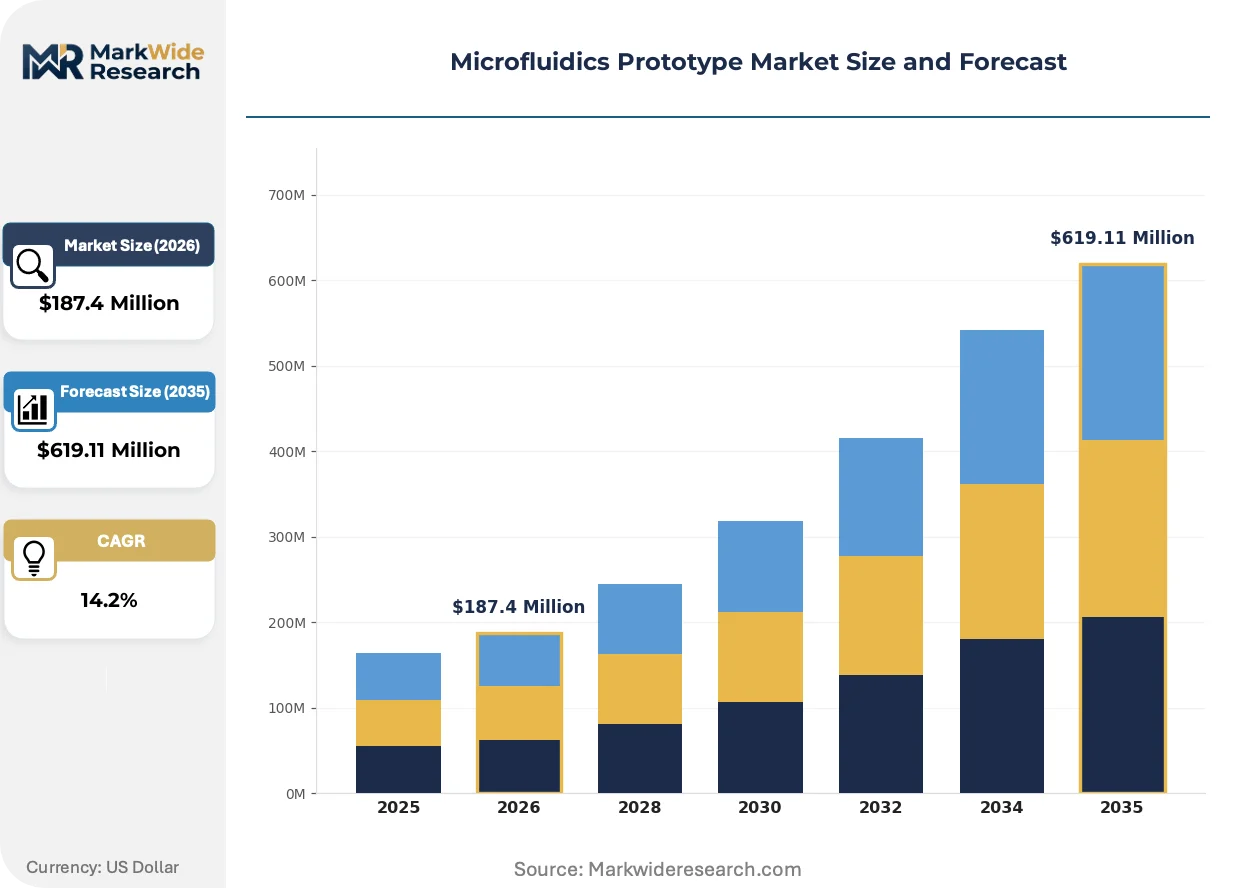
Market Dynamics
Prototype customization revenue is redistributing value capture across the microfluidics value chain, shifting margins from standardized chip fabrication toward application-specific design services as pharmaceutical firms compress drug development timelines.
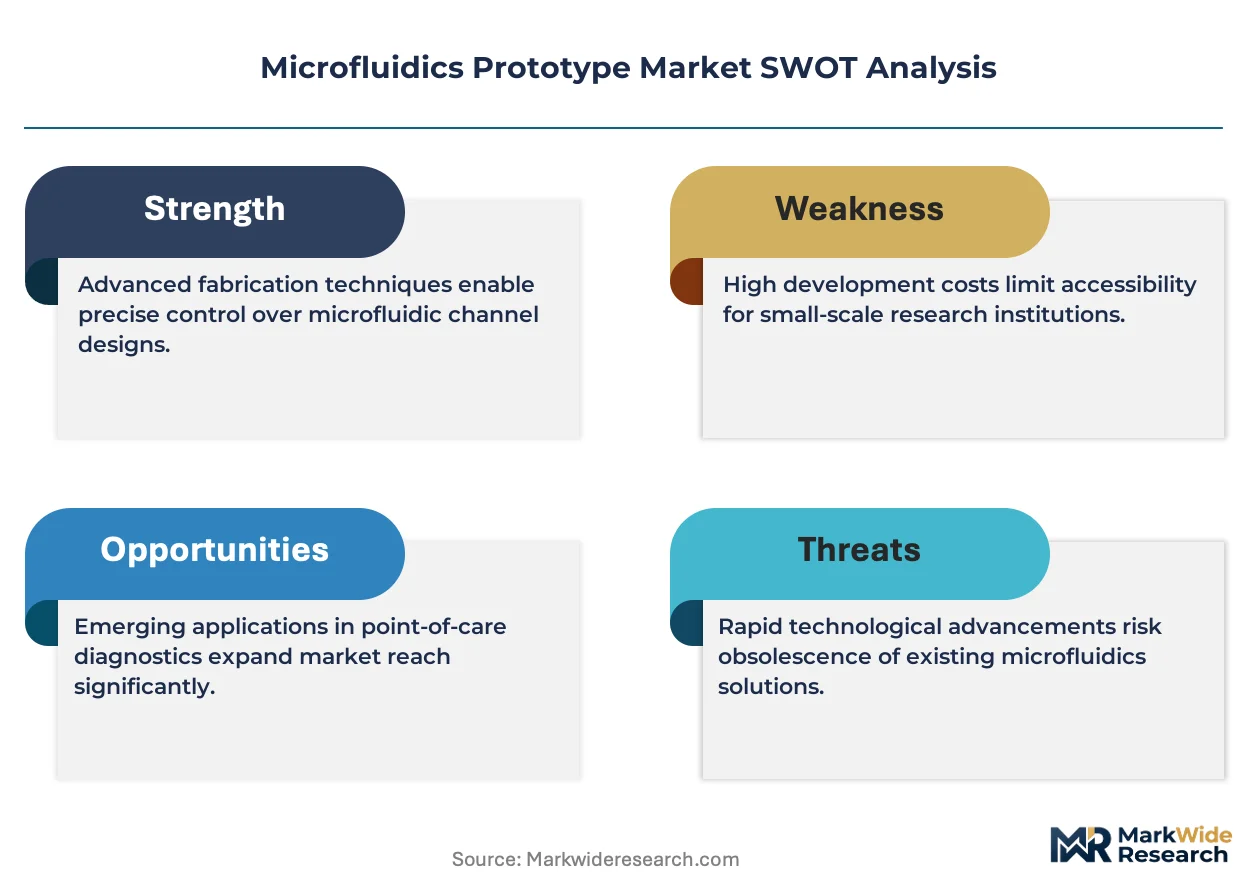
Growth Catalysts
- FDA Pre-Submission Pathways:The FDA's tightening validation requirements for microfluidic-based diagnostic devices are accelerating early-stage prototype investment as developers front-load regulatory de-risking.
- Single-Cell Analysis Demand:Droplet-based microfluidic systems are expanding prototype procurement from academic labs into commercial biotechnology workflows.
- Boston Biotech Cluster:Concentrated R&D spending in Massachusetts is driving specialized prototype fabrication orders for polymer and glass substrate devices.
Market Restraints
- REACH Chemical Restrictions:ECHA limitations on specific polymers for clinical-bound prototypes are forcing early material qualification investments that extend design cycles.
- Precision Micromachining Concentration:North American supply for polymer and glass substrate fabrication remains concentrated among a limited supplier base, creating bottleneck risk.
- ISO 13485 Compliance Burden:Quality management certification requirements for prototype-to-product transitions impose fixed costs that disproportionately burden smaller diagnostic developers.
Strategic Opportunities
- Companion Diagnostics Harmonization:Pending FDA-EMA alignment on microfluidic-based companion diagnostic validation could eliminate duplicate compliance costs for dual-market developers.
- Integrated Fluidic Circuit Design:Convergence of microfluidic architecture with embedded sensor integration is opening premium service tiers for development cycle compression.
- San Diego Biotech Corridor:Underpenetrated prototype service capacity in Southern California relative to R&D density represents geographic expansion potential.
Industry Challenges
- Multiphysics Simulation Expertise Gap:Shortage of engineers proficient in coupled fluid-thermal-structural modeling for complex channel geometries is extending design iteration timelines.
- Cleanroom Capex Requirements:ISO Class 5-7 fabrication environments for clinical-grade prototypes demand capital commitments that strain mid-scale service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microfluidics Prototype Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical Devices, Continuous Flow Systems, Droplet-based Systems, Lab-on-a-chip End User: Academic Research, Biotechnology Companies, Diagnostic Laboratories, Pharmaceutical Firms Application: Drug Development, Disease Diagnostics, Environmental Monitoring, Chemical Analysis Material: Polymers, Glass, Silicon, Metals |
| Companies Covered | Dolomite Microfluidics, Potomac, ALine, Inc., Parallel Fluidics, Inc., Alvéole, thinXXS Microtechnology, uFluidix, Fluigent, MicroLIQUID, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microfluidics Prototype Market Strategic Shifts
Digital prototyping workflows and modular platform architectures are compressing development cycles while regulatory pre-validation is shifting earlier into the design phase.
Additive manufacturing of microfluidic channels through high-resolution stereolithography is rendering obsolete traditional soft lithography master fabrication for iterative design cycles. Biotechnology startups in Boston and San Diego are adopting these digital workflows within two-week iteration windows. The technology is rendering obsolete the six-to-eight-week lead times that previously constrained prototype velocity.
EMA's evolving stance on microfluidic-based companion diagnostic validation is creating regulatory uncertainty for developers pursuing simultaneous US-EU market entry. Divergent validation requirements between FDA and EMA jurisdictions are fragmenting development strategies and forcing parallel track investments. Diagnostic developers are responding by front-loading EMA scientific advice consultations before committing to scaled prototype production.
Pharmaceutical procurement teams are consolidating prototype vendor relationships around full-service design-fabricate-test partnerships rather than transactional chip orders. This consolidation is displacing single-service machine shops in favor of integrated platform providers with in-house metrology and biological testing capabilities. The shift is most visible among mid-cap pharmaceutical firms in the Northeastern United States seeking to internalize supply chain risk.
Microfluidics Prototype Market Segmentation
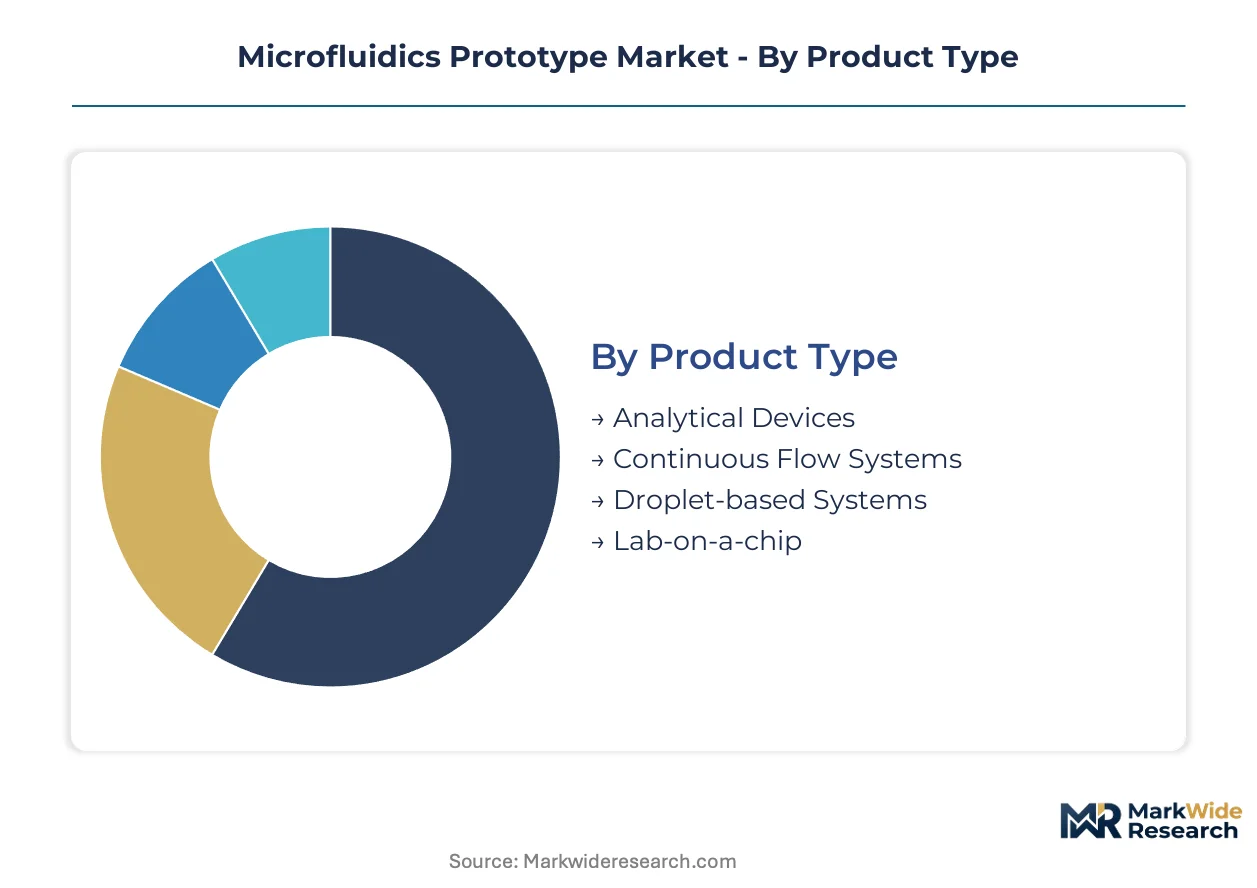
Segmentation in microfluidics prototypes reveals how technical specifications, end-use requirements, and material constraints partition procurement patterns. Pharmaceutical firms and diagnostic developers prioritize different performance thresholds, channel geometries, and regulatory compliance pathways when commissioning prototype fabrication.
Product Type:
Mature continuous flow architectures coexist with emerging droplet-based platforms that are displacing legacy formats in high-growth applications.
- Lab-on-a-chip:Integrated systems consolidate sample preparation, reaction, and detection onto single substrates with channel densities exceeding 100 microchannels per square centimeter. Pharmaceutical firms in Massachusetts and California dominate procurement for companion diagnostic development pipelines where FDA pre-submission requirements mandate integrated validation data.
- Droplet-based Systems:Picoliter-scale aqueous compartments suspended in immiscible carrier fluids enable massively parallel single-cell analysis. Biotechnology companies in Boston and San Diego are expanding prototype orders for CRISPR screening and antibody discovery workflows where throughput scalability determines competitive positioning.
- Continuous Flow Systems:Steady-state liquid processing through fixed channel networks retains established positioning in chemical synthesis and quality control protocols where protocol standardization reduces customization premiums.
- Analytical Devices:Modular detection-integrated platforms serve environmental monitoring and point-of-care diagnostic developers requiring rapid reconfiguration between assay chemistries.
Continuous flow systems retain volume leadership; droplet-based platforms hold the steepest expansion curve.
End User:
Customer type determines procurement scale, with commercial biotechnology operations outspending academic laboratories by an order of magnitude on per-project prototype investment.
- Pharmaceutical Firms:Large-molecule developers commission multi-substrate prototype families to de-risk manufacturing scale-up for microfluidic-based bioprocess monitoring. Internal venture arms at firms headquartered in Basel, Boston, and San Francisco are consolidating vendor relationships around full-service partnerships with integrated biological testing capabilities.
- Biotechnology Companies:Venture-backed cell therapy and gene editing specialists require rapid iteration cycles with two-week design-fabricate-test turnaround. These developers prioritize modular platform providers capable of reconfiguring channel geometries without new mask sets or master fabrication.
- Academic Research:University laboratories drive foundational method development but operate on constrained budgets that favor shared fabrication facilities and open-source design repositories over commercial prototype services.
- Diagnostic Laboratories:Clinical reference labs and hospital-based pathology departments procure prototypes for assay verification studies preceding regulatory submission, with ISO 13485 compliance requirements filtering supplier selection.
Pharmaceutical firms command the largest contract values; biotechnology companies are expanding order volume most rapidly.
Application:
Use-case differentiation separates high-margin regulated diagnostics from price-sensitive environmental monitoring contracts.
- Drug Development:Microfluidic organ-on-chip and tumor spheroid platforms replicate human physiological responses for toxicity screening and pharmacokinetic modeling. Prototype procurement concentrates among mid-cap pharmaceutical firms seeking to compress preclinical timelines and reduce animal study dependencies.
- Disease Diagnostics:Point-of-care and laboratory-based assay platforms require prototypes validated against FDA and EMA companion diagnostic guidelines. Developers front-load regulatory consultation to avoid redesign cycles during formal submission review.
- Chemical Analysis:Process analytical technology and environmental monitoring applications demand chemical compatibility across aggressive solvent and reagent exposures, driving material selection toward glass and fluorinated polymers.
- Environmental Monitoring:Water quality and air sampling microfluidic sensors prioritize cost minimization and field durability over the precision tolerances required for clinical applications.
Drug development absorbs the largest share of high-complexity prototyping capacity; disease diagnostics is climbing the fastest.
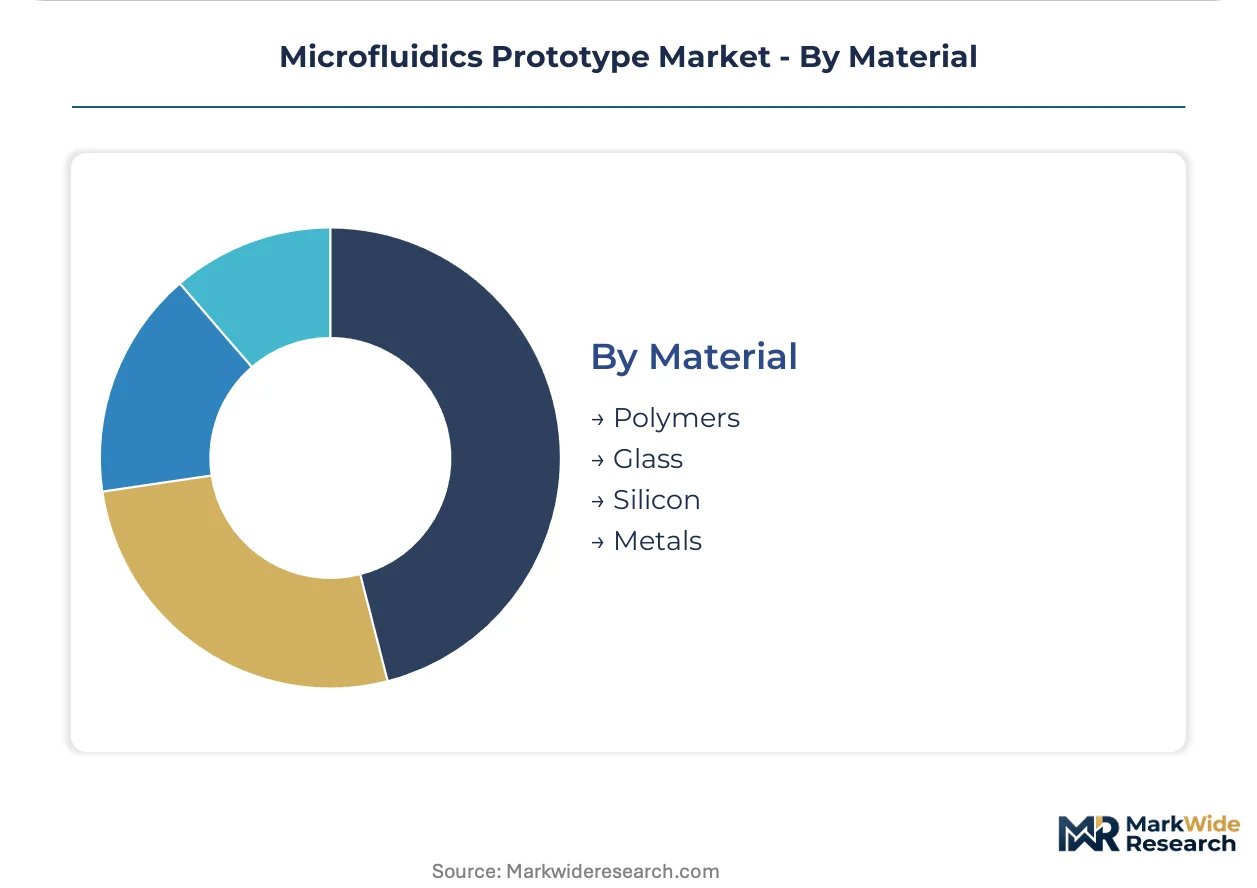
Material:
Substrate selection locks in fabrication methodology, optical properties, and regulatory pathway compatibility for clinical translation.
- Polymers:Thermoplastics and elastomers dominate prototyping volume due to compatibility with rapid replication molding and cost-effective iterative design. Cyclic olefin copolymer and polydimethylsiloxane substrates serve diagnostic developers requiring optical clarity and gas permeability for cell culture applications.
- Glass:Borosilicate and fused silica substrates command premium positioning for applications requiring chemical inertness, thermal stability, and precise channel geometry control. REACH restrictions on certain polymer additives are redirecting clinical-bound prototypes toward glass alternatives despite higher unit costs.
- Silicon:Semiconductor-compatible micromachining enables sub-micron feature resolution for mass spectrometry interfacing and nanopore sensing applications where electrical integration is essential.
- Metals:Stainless steel and titanium prototypes serve high-pressure chemical synthesis and implantable device applications where polymer mechanical properties are insufficient.
Polymers retain volume leadership; glass substrates are gaining share fastest among clinical diagnostic developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prototype buyers in Germany demonstrate the lowest price elasticity, absorbing premium costs for glass substrates and ISO 13485-compliant fabrication, while academic laboratories in India operate under severe budget constraints that favor shared facility access over commercial services.
United States
FDA pre-submission pathways for companion diagnostics are accelerating prototype investment cycles among Boston and San Diego biotechnology clusters. Massachusetts-based pharmaceutical firms commission multi-substrate prototype families to de-risk manufacturing scale-up for microfluidic-based bioprocess monitoring. San Diego's cell therapy specialists prioritize rapid iteration cycles with two-week turnaround requirements.
Germany
REACH chemical restrictions are redirecting clinical-bound prototypes toward borosilicate glass alternatives despite higher unit costs. ECHA limitations on specific polymer additives force early material qualification investments that extend design cycles. Baden-Württemberg precision engineering clusters anchor European demand for high-pressure chemical synthesis prototypes.
China
NMPA tightening of microfluidic diagnostic device validation requirements is front-loading regulatory de-risking into prototype phases. Domestic biotechnology firms in Shanghai and Suzhou are consolidating vendor relationships around full-service design-fabricate-test partnerships. Yangtze River Delta R&D spending is driving specialized fabrication orders for polymer substrate devices.
Switzerland
Swissmedic alignment with FDA companion diagnostic guidelines is reducing duplicate compliance costs for dual-market developers. Basel-headquartered pharmaceutical internal venture arms are consolidating vendor relationships around integrated biological testing capabilities. The country's precision manufacturing heritage supports premium positioning for chemical inertness and thermal stability requirements.
United Kingdom
Academic research laboratories in Cambridge and Oxford drive foundational method development but operate on constrained budgets favoring open-source design repositories. MHRA convergence with EMA microfluidic diagnostic standards is creating regulatory clarity for developers pursuing EU market entry. London-based diagnostic startups are front-loading scientific advice consultations before committing to scaled prototype production.
Microfluidics Prototype Market Competitive Environment
Modular platform specialists and precision micromachining houses split the market between rapid iteration services and substrate-specific fabrication. The vendor base concentrates around integrated providers with in-house metrology capabilities rather than transactional chip fabricators. Two strategic archetypes dominate: full-service design-fabricate-test partnerships and specialized substrate-focused machine shops. Competitive moves center on geographic expansion into underpenetrated biotech corridors and technology licensing for digital prototyping workflows.
Among UK-based modular platform providers, Dolomite Microfluidics exemplifies the integrated architecture approach, while Potomac anchors North American precision micromachining for polymer and glass substrates. ALine, Inc. occupies a position within the full-service partnership tier, representing the convergence of fluidic circuit design with embedded sensor integration capabilities.
| Leading Market Players |
|---|
| Dolomite Microfluidics |
| Potomac |
| ALine, Inc. |
| Parallel Fluidics, Inc. |
| Alvéole |
| thinXXS Microtechnology |
| uFluidix |
| Fluigent |
| MicroLIQUID |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in ISO Class 5-7 cleanroom fabrication across North America and Western Europe concentrates pricing power among incumbent precision micromachining houses, while pharmaceutical procurement teams absorb premium costs for rapid-turnaround prototype families that compress drug development timelines.
Pricing Analysis
After-sales revenue from extended metrology service contracts and biological validation partnerships drives lifetime value capture beyond initial chip fabrication. Three-tier pricing structure across premium, standard, and economy levels separates FDA pre-submission-ready prototypes with full ISO 13485 documentation from academic-grade devices with limited traceability. Cost compression in standard-tier polymer substrates is intensifying because additive manufacturing workflows reduce soft lithography master costs. Biotechnology startups in Boston and San Diego demonstrate lowest price elasticity, while academic laboratories in India operate under severe budget constraints favoring shared facility access.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for borosilicate glass substrate sourcing. Manufacturing concentrates in Germany, the United States, and Switzerland for clinical-grade prototypes requiring REACH-compliant material qualification. Raw material flows draw from cyclic olefin copolymer resin suppliers in Japan, PDMS precursor manufacturers in the United States, and precision-grade borosilicate glass foundries in Germany. Single-source vulnerability persists for high-resolution stereolithography equipment tethered to equipment vendors in the United States and Japan. Distribution runs through direct vendor partnerships with pharmaceutical internal venture arms rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microfluidics prototype demand sits in early-cycle expansion as FDA pre-submission pathways front-load regulatory de-risking into development phases, accelerating procurement velocity among commercial biotechnology operations.
For Market Incumbents: Build switching-cost moats through embedded sensor integration capabilities that lock diagnostic developers into iterative design-fabricate-test partnerships. Incumbent precision micromachining houses should deepen backward integration into captive polymer resin qualification to offset REACH chemical restriction impacts. Capacity addition in San Diego addresses geographic supply-demand imbalance relative to Boston cluster concentration. Certification investment in dual FDA-EMA companion diagnostic validation capabilities captures harmonization tailwinds. For New Entrants and Emerging Players: Southern California's underpenetrated prototype service capacity relative to R&D density offers white-space entry for modular platform providers with two-week turnaround capabilities. Academic-to-commercial transition services for university spinouts represent the most penetrable segment, as shared fabrication facility graduates seek full-service partnerships. Go-to-market positioning should emphasize digital prototyping workflows that render obsolete six-to-eight-week soft lithography lead times through high-resolution stereolithography adoption. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across clinical-grade cleanroom fabrication as ISO 13485 compliance requirements strain mid-scale service providers. The five-to-ten year viability window favors acquisition targets with integrated biological testing capabilities and established pharmaceutical vendor consolidation relationships. Watch FDA-EMA companion diagnostic harmonization progress as the inflection signal for dual-market development strategy viability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Submission Pathway Investment | FDA pre-submission capabilities accelerate client product timelines and deepen partnership stickiness. |
| Modular Platform Architecture Development | Reconfigurable channel geometries without new mask sets compress biotechnology client iteration cycles. |
| Integrated Biological Testing Capability Buildout | In-house metrology and assay validation displaces single-service machine shops in procurement consolidation. |
| Geographic Expansion into San Diego Corridor | Underpenetrated capacity relative to cell therapy R&D density captures rapid-turnaround demand. |
| Dual FDA-EMA Validation Certification | Harmonization-ready documentation eliminates duplicate compliance costs for companion diagnostic developers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA pre-submission filings, ISO 13485 certification databases, and EMA scientific advice records. Primary interviews engaged prototype procurement managers at pharmaceutical firms, regulatory affairs leads at diagnostic developers, and cleanroom operations directors at precision micromachining houses. Secondary validation drew from customs trade data for polymer and glass substrate flows, SEC filings for publicly traded biotechnology equipment vendors, and ClinicalTrials.gov entries for microfluidic-based diagnostic development pipelines. Bottom-up prototype order volume estimates triangulate against top-down pharmaceutical R&D spending allocations across the analysis window.
Forecast inputs span product type segmentation across lab-on-a-chip, droplet-based, continuous flow, and analytical device architectures; end-user categories from pharmaceutical firms through academic laboratories; application differentiation between drug development and disease diagnostics; and material substrate selection across polymers, glass, silicon, and metals. CAGRs derive from regression analysis against historical prototype procurement patterns and pharmaceutical pipeline expansion trajectories. Industry-specific forecast inputs include FDA pre-submission pathway volume trends and single-cell analysis workflow adoption curves across biotechnology operations.
Practitioners should monitor regulatory harmonization progress, additive manufacturing technology maturation, and cleanroom capacity utilization signals for early indicators of forecast deviation. Assumptions underlying projections reflect current FDA and EMA guidance trajectories, REACH chemical restriction enforcement patterns, and pharmaceutical venture funding availability. Macroeconomic contraction in biotechnology capital formation, divergence in FDA-EMA companion diagnostic standards, or breakthrough displacement of microfluidic architectures by alternative single-cell analysis platforms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Asia-Pacific MPU Market
Emerging and Next Generation Technologies
Next Generation Processors Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Flexible Electronics Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Internet of Nano Things Market