
 Global Smart Window Market | 2026-2036
Global Smart Window Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Window Market Foresight
The performance gap between premium electrochromic systems and commodity photochromic alternatives is realigning procurement criteria across construction and transportation sectors. Gentex Corporation leverages its automotive heritage to dominate aviation and marine applications where dimming precision matters. Saint-Gobain anchors European commercial projects through integrated facade systems that bundle glazing with building management interfaces. View Inc. competes on scale by operating one of the largest electrochromic fabrication facilities in the United States.
Smart windows are glazing systems that modulate light transmission, thermal transmittance, or opacity through applied voltage, temperature change, or incident light intensity, typically achieving visible light transmittance swings between 5% and 60% depending on the active layer chemistry. Electrochromic architectures using tungsten oxide and nickel oxide intercalation layers serve commercial buildings where automated daylight harvesting cuts HVAC loads substantially. Suspended particle device technology occupies automotive sunroof and aviation cabin segments where millisecond switching speed justifies higher unit costs. Liquid crystal films sustain niche residential and marine privacy applications despite limited energy performance.
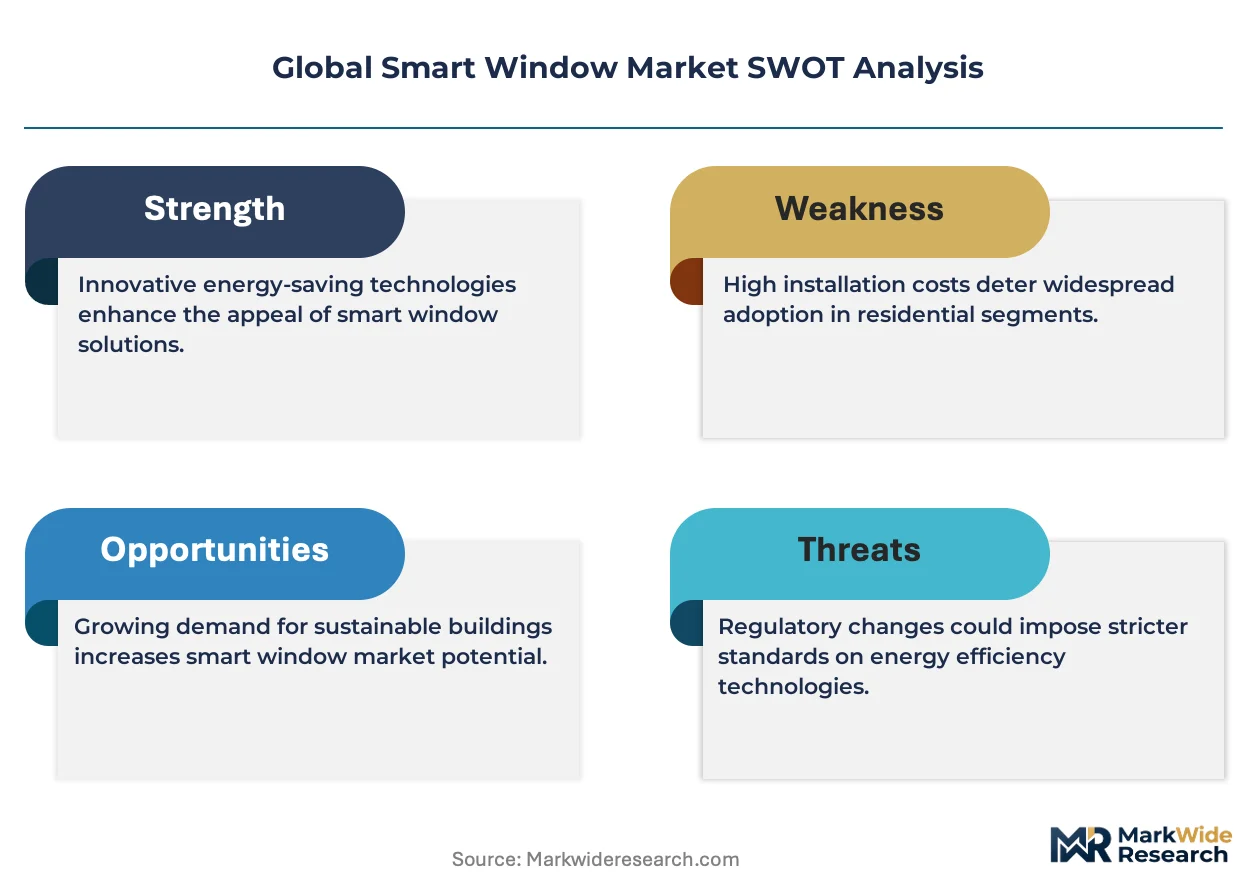
The U.S. Department of Energy's building energy codes and the EU Green Deal's renovation wave directives shape product certification requirements and retrofit incentive eligibility across two of the largest addressable markets. China's GB standards for building energy efficiency and Japan's METI subsidy programs for net-zero buildings add compliance layers that favor suppliers with multi-jurisdiction testing capabilities. Stakeholders must monitor how fragmented national efficiency benchmarks affect product platform standardization and whether sensor-integrated windows shift specification authority from architects to building automation integrators.
Market Dynamics
The electrochromic fabrication bottleneck is concentrating supply among three integrated film-coaters, forcing specification authority toward facade system bundlers and away from standalone glazing distributors.
Growth Catalysts
- EU Green Deal renovation mandates:Germany's federal building efficiency standards and France's RE2020 thermal regulations are accelerating large-scale retrofits across commercial portfolios.
- Aviation cabin retrofit cycles:Airlines replacing aging widebody interiors specify suspended particle device technology for millisecond dimming control in premium seating zones.
- Tungsten oxide intercalation advances:Low-voltage switching thresholds below three volts are expanding electrochromic compatibility with standard building automation protocols.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductor deposition relies on Chinese rare earth processing, exposing fabricators to export quota volatility.
- Photochromic substitution in residential:Lower-cost passive tinting alternatives capture single-family retrofits where automated control delivers marginal HVAC savings.
- REACH substance authorization delays:Nickel oxide electrochromic layers face extended ECHA evaluation timelines, freezing new product introductions in European markets.
Strategic Opportunities
- India's net-zero building code rollout:Bureau of Energy Efficiency mandates for commercial structures above 100 kilowatts create first-mover advantage for certified electrochromic suppliers.
- Sensor-integrated window systems:Convergence of daylight harvesting algorithms with IoT occupancy detection is shifting specification authority toward building automation integrators.
- Marine superyacht refit channels:Liquid crystal privacy films penetrate high-value leisure vessel segments through specialized yacht glazing distributors.
Industry Challenges
- Thin-film coating technician scarcity:Vacuum deposition expertise concentrates among legacy semiconductor fabricators, constraining electrochromic production scaling.
- Multi-jurisdiction certification timelines:Separate UL, CE, and JIS testing protocols extend product launch cycles by eighteen to twenty-four months.
- Legacy BAS integration complexity:Proprietary communication protocols in existing building management systems obstruct seamless electrochromic zone control deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Window Market |
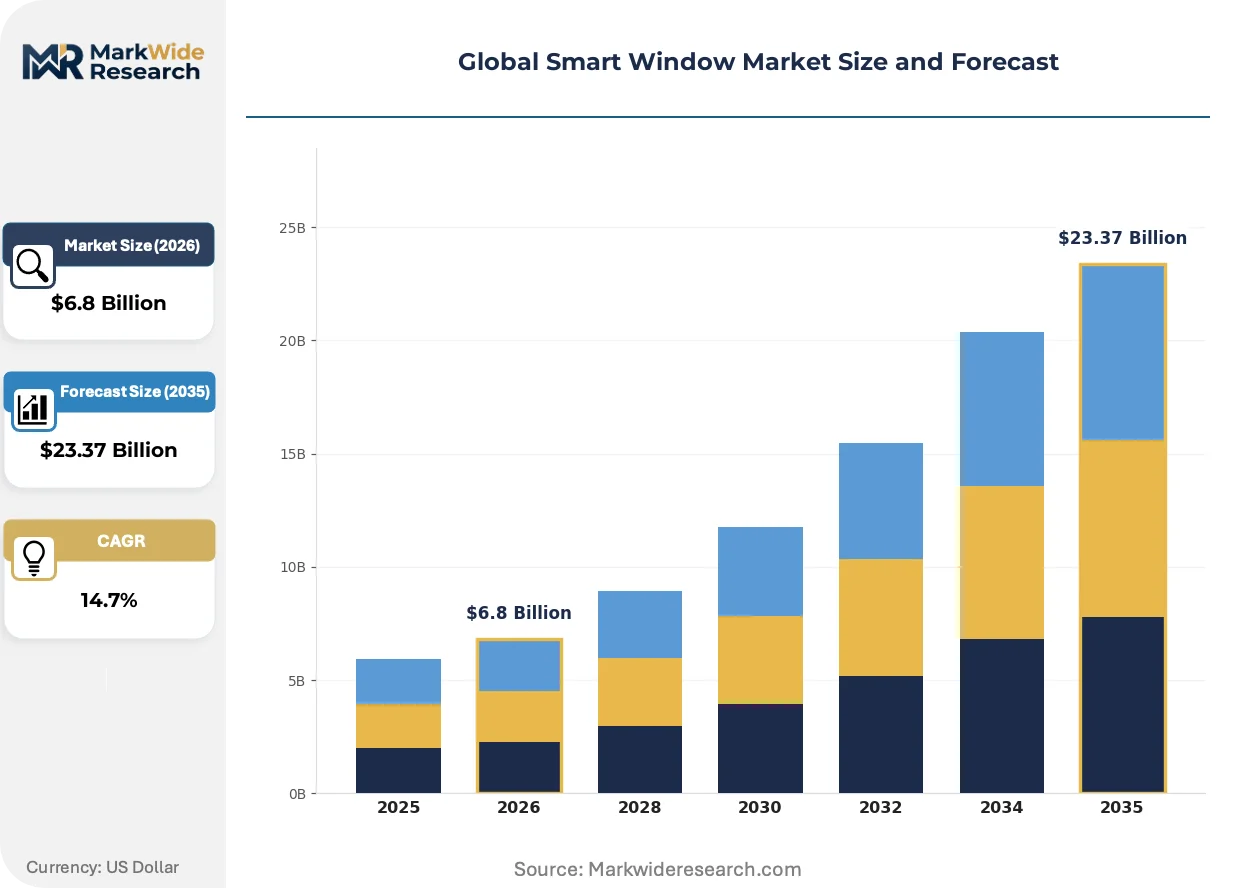
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.37 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochromic, Suspended Particle Device, Thermochromic, Liquid Crystal, Photochromic Technology: Touch Control, Voice Recognition, Motion Sensor, Light Sensor, Temperature Sensor Application: Commercial Buildings, Residential Complexes, Automotive Manufacturers, Aviation, Marine Vessels End User: Construction Firms, Property Developers, Transportation OEMs, Aerospace Companies, Shipbuilders |
| Companies Covered | Gentex Corporation, SAGE Electrochromics, Research Frontiers, View Inc., AGC Inc., Saint-Gobain, Corning Incorporated, Gauzy Ltd., Polytronix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Window Market Shifts & Advancements
Active glazing chemistry is bifurcating between precision-controlled electrochromic architectures and speed-optimized suspended particle alternatives, with specification criteria hardening around integration depth rather than standalone optical performance.
Perovskite-structured electrochromic layers are rewriting thermal modulation economics by achieving comparable visible light transmittance swings at half the voltage input of tungsten oxide systems. Commercial developers in California and the Netherlands are piloting these films in zero-net-energy demonstration projects. The technology is compressing payback periods for automated facade investments from seven years toward four.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents is forcing insulated glass unit manufacturers to reformulate gas fills and spacer systems. Electrochromic fabricators must recertify entire product stacks against revised thermal performance benchmarks. German facade engineering firms are responding by bundling smart glazing with vacuum-insulated panel retrofits to maintain U-value compliance.
Architect specification behavior is rotating toward outcome-based facade performance contracts that guarantee annual HVAC load reductions rather than prescribing specific glazing technologies. This displaces traditional product-substitution bidding in favor of energy service company partnerships. The shift is most visible in Australian commercial development, where Green Star certification credits now reward measured operational outcomes over installed equipment lists.
Global Smart Window Market Segmentation
Smart window procurement splits along technology maturity curves and integration complexity. Upgrade cycles in commercial real estate and transportation retrofits create divergent specification pathways across product types, control interfaces, and end-use applications.
Product Type:
Replacement timelines stretch from fifteen years for electrochromic facade systems to five years for automotive photochromic upgrades, creating tiered aftermarket entry points.
- Electrochromic:Tungsten oxide and nickel oxide intercalation layers enable voltage-driven tint modulation between 5% and 60% visible light transmittance. Germany's federal building efficiency mandate drives large-scale commercial retrofits in Frankfurt and Munich, where automated daylight harvesting cuts HVAC loads substantially.
- Suspended Particle Device:Millisecond switching speed via liquid crystal particle suspension justifies premium pricing in aviation cabin retrofits. Airlines replacing aging widebody interiors specify SPD technology for premium seating zones where dimming precision matters.
- Thermochromic:Passive temperature-responsive vanadium dioxide coatings suit residential markets with limited automation infrastructure.
- Liquid Crystal:Privacy-on-demand films penetrate marine superyacht refit channels through specialized yacht glazing distributors.
- Photochromic:Lower-cost passive tinting captures single-family retrofits where automated control delivers marginal HVAC savings.
Electrochromic sits at the top of the volume ranking, with Suspended Particle Device climbing the fastest.
Technology:
Control interface specification is rotating toward building automation compatibility rather than standalone consumer convenience.
- Touch Control:Capacitive surface interfaces dominate residential retrofits where occupant override remains a priority.
- Voice Recognition:Integration with Amazon Alexa and Google Home ecosystems penetrates high-end residential new construction in California and Texas.
- Motion Sensor:Occupancy-triggered tint adjustment expands in Netherlands commercial buildings pursuing WELL certification credits.
- Light Sensor:Photodiode arrays enabling automated daylight harvesting constitute the standard specification for LEED-targeting developments in Singapore and Sydney.
- Temperature Sensor:Thermistor-integrated feedback loops are gaining share fastest in zero-net-energy demonstration projects where thermal modulation economics determine payback periods.
Light Sensor commands the installed base, while Temperature Sensor expands most quickly.
Application:
Project scale and performance guarantees separate specification authority between facade engineers and transportation interior specialists.
- Commercial Buildings:Integrated facade systems bundling glazing with building management interfaces anchor European projects. Saint-Gobain and View Inc. compete through outcome-based performance contracts guaranteeing annual HVAC load reductions.
- Residential Complexes:Multi-family developers in Japan and South Korea specify liquid crystal privacy films for bathroom and bedroom applications where opacity switching substitutes for mechanical blinds.
- Automotive Manufacturers:Gentex Corporation leverages automotive heritage to dominate sunroof and dimming mirror segments.
- Aviation:Cabin retrofit cycles for Boeing 777 and Airbus A350 fleets drive suspended particle device procurement through specialized aerospace distributors.
- Marine Vessels:Superyacht builders in Italy and the Netherlands integrate electrochromic bridge windows with navigation system dimming protocols.
Commercial Buildings leads by project value, with Aviation showing the steepest expansion trajectory.
End User:
Procurement authority is consolidating toward facade system bundlers and building automation integrators, displacing standalone glazing distributors.
- Construction Firms:General contractors in Australia and Canada are adopting outcome-based facade performance contracts that reward measured operational outcomes over installed equipment lists.
- Property Developers:Institutional developers in France pursuing RE2020 thermal regulations accelerate large-scale retrofits across commercial portfolios in Paris and Lyon.
- Transportation OEMs:Automotive and aviation manufacturers specify millisecond-switching technologies where control latency affects safety certification.
- Aerospace Companies:Airlines and lessors drive retrofit demand through scheduled heavy maintenance checks that synchronize with interior refresh programs.
- Shipbuilders:Italian and Dutch yacht constructors source liquid crystal privacy films through specialized marine glazing channels.
Property Developers dominate contract volume, with Aerospace Companies gaining share fastest on widebody replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thin-film coating technicians concentrate in German and Japanese industrial clusters, anchoring electrochromic fabrication capacity. Chinese rare earth processors control indium tin oxide supply chains. Dutch facade engineers pioneer outcome-based performance contracting models.
Germany
Federal building efficiency mandates drive large-scale commercial retrofits across Frankfurt and Munich property portfolios. The EU Green Deal renovation targets accelerate specification rates for automated daylight harvesting systems. Stuttgart-based facade engineering firms bundle smart glazing with vacuum-insulated panel retrofits to maintain U-value compliance.
United States
California and Texas developers pilot perovskite-structured electrochromic layers in zero-net-energy demonstration projects. The U.S. Department of Energy's building energy codes shape product certification requirements and retrofit incentive eligibility. View Inc. operates one of the largest electrochromic fabrication facilities in the country, concentrating production scale in the western states.
Netherlands
Commercial developers pursuing WELL certification credits specify motion sensor-integrated tint adjustment systems. The EU F-Gas Regulation forces insulated glass unit manufacturers to reformulate gas fills and spacer systems. Amsterdam and Rotterdam facade engineering firms are rotating toward outcome-based performance contracts that guarantee annual HVAC load reductions.
Japan
METI subsidy programs for net-zero buildings add compliance layers favoring suppliers with multi-jurisdiction testing capabilities. Multi-family developers specify liquid crystal privacy films for bathroom and bedroom applications where opacity switching substitutes for mechanical blinds. Osaka and Nagoya industrial clusters concentrate liquid crystal film production expertise.
India
Bureau of Energy Efficiency mandates for commercial structures above 100 kilowatts create first-mover advantage for certified electrochromic suppliers. The country's national building energy efficiency standards are tightening across Maharashtra and Karnataka state codes. Mumbai and Bangalore construction markets are seeing specification authority shift toward facade system bundlers.
Global Smart Window Market Competitive Landscape
Top-tier vendors anchor integrated facade system supply, while mid-tier specialists compete on switching speed and niche applications. The electrochromic fabrication bottleneck concentrates supply among three integrated film-coaters, forcing specification authority toward facade system bundlers. Strategic archetypes include automotive heritage players, integrated glass-chemistry conglomerates, and dedicated electrochromic scale operators. Competitive moves center on backward integration into transparent conductor deposition and strategic partnerships with building automation integrators.
Within the automotive-heritage tier, Gentex Corporation represents the precision-dimming specialist archetype, leveraging established aviation and marine certification pathways. Saint-Gobain and AGC Inc. exemplify integrated glass-chemistry conglomerates with facade system bundling capabilities. View Inc. occupies a position as the scale-driven electrochromic fabricator with large-format production infrastructure. These three anchors demonstrate how competitive positioning stratifies across heritage certification, chemical integration, and manufacturing scale vectors.
| Leading Market Players |
|---|
| Gentex Corporation |
| SAGE Electrochromics |
| Research Frontiers |
| View Inc. |
| AGC Inc. |
| Saint-Gobain |
| Corning Incorporated |
| Gauzy Ltd. |
| Polytronix |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up facade engineering specialists in Germany and the Netherlands anchor pricing discipline through bundled performance contracts that wrap electrochromic glazing with installation and long-term energy guarantees, compressing margin capture for standalone component distributors while rewarding integrated system providers with premium pricing power.
Pricing Analysis
The bundled-vs-unbundled service split separates facade system integrators from standalone glazing distributors. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with UL-listed electrochromic units commanding substantial premiums over uncertified alternatives. Cost compression in residential photochromic tiers is intensifying because Chinese manufacturers are scaling passive tinting production. Single-family retrofit buyers exhibit the highest price sensitivity, while aviation OEMs prioritize switching speed over unit cost.
Supply Chain Analysis
Logistics and freight costs for oversized insulated glass units constrain distribution radius to roughly 500 kilometers from fabrication sites, forcing regional production footprints. Vacuum deposition expertise concentrates in Germany, Japan, and the United States, while indium tin oxide feedstock draws from Chinese rare earth processors. Single-source vulnerability in transparent conductor supply exposes fabricators to export quota volatility. Distribution runs through facade system bundlers and building automation integrators rather than traditional glazing distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Smart Window Market reads as a late-cycle quality story where procurement authority is consolidating toward outcome-based facade performance contracts, with specification criteria hardening around integration depth and measured HVAC load reductions rather than standalone optical performance.
For Market Incumbents: Deploy backward integration into transparent conductor deposition to secure indium tin oxide supply against Chinese export quota volatility. Lock in long-term facade engineering partnerships in Germany and the Netherlands to defend specification authority against emerging building automation integrators. Prioritize multi-jurisdiction certification investment to compress eighteen-to-twenty-four-month product launch cycles. For New Entrants and Emerging Players: India's Bureau of Energy Efficiency mandates for commercial structures above 100 kilowatts opens a window for certified electrochromic suppliers to establish first-mover advantage before incumbent certification timelines catch up. Target marine superyacht refit channels in Italy and the Netherlands where liquid crystal privacy films penetrate through specialized yacht glazing distributors. Pursue direct partnerships with shipbuilders rather than competing through generalist distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier suspended particle device specialists with aviation certification heritage but limited scale expansion capital. Long-term viability hinges on convergence with building automation protocols and sensor integration capabilities. Watch for inflection when outcome-based performance contracts displace traditional product-substitution bidding in Australian and Dutch commercial development markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transparent Conductor Deposition | Captive indium tin oxide supply insulates German and Japanese fabricators from Chinese export quota volatility. |
| Multi-Jurisdiction Certification Investment | Parallel UL, CE, and JIS testing compresses product launch cycles for electrochromic suppliers targeting global commercial portfolios. |
| Sensor-Integrated Window System Development | Convergence of daylight harvesting algorithms with IoT occupancy detection shifts specification authority toward building automation integrators in Netherlands commercial buildings. |
| Facade Engineering Partnership Consolidation | Exclusive bundling agreements with Stuttgart-based and Amsterdam-based engineering firms secure premium project access for integrated system providers. |
| Perovskite Electrochromic Layer Commercialization | Low-voltage switching thresholds below three volts expand compatibility with standard building automation protocols in California zero-net-energy demonstration projects. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facade engineering directors, building automation integrators, electrochromic fabrication plant managers, and commercial real estate developers with secondary validation against U.S. Department of Energy building energy code filings, EU Green Deal renovation target databases, and Bureau of Energy Efficiency mandate documentation. Bottom-up project pipeline analysis and top-down regulatory impact modeling were triangulated to anchor volume and value estimates.
Segment-weighting approaches applied differential growth assumptions across electrochromic, suspended particle device, thermochromic, liquid crystal, and photochromic technology tiers, with further disaggregation by control interface type and end-use application. CAGRs were derived from installed base turnover rates and retrofit cycle synchronization across commercial buildings, aviation, and marine vessels. Forecast inputs incorporated EU F-Gas Regulation compliance timelines and India's net-zero building code rollout pace.
Revisions become necessary when REACH substance authorization timelines for nickel oxide electrochromic layers extend beyond current ECHA evaluation schedules, or when Chinese indium tin oxide export quotas tighten unexpectedly. Forecasts reflect assumptions about thin-film coating technician availability and vacuum deposition equipment lead times. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Metamaterial Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
AI PC Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
Multi-Touch Technology Market
Emerging and Next Generation Technologies
Global Nano Batteries Market
Emerging and Next Generation Technologies
AI Edge Computing Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Nanodiamond Market