
 Siding Market | 2026-2036
Siding Market Size, Share, and Industry Trends Forecast 2026-2036
Siding Market Intelligence
The application mix for siding is broadening from its traditional residential base to encompass more demanding commercial and institutional building projects. James Hardie leverages its dominance in fiber cement to capture share in fire-resistant commercial facades. CertainTeed differentiates through its extensive portfolio of vinyl and polymer products tailored for both new construction and renovation channels. Cornerstone Building Brands sustains a strong position in the North American market through its vast distribution network and multi-material offerings.
Siding constitutes the exterior cladding material applied to the walls of a structure to provide a protective, weather-resistant envelope. Its primary function is to shield the building from sun, rain, and temperature extremes while also contributing significantly to its aesthetic character. While vinyl siding continues to dominate in terms of volume, fiber cement represents the fastest-growing material type due to its durability and fire resistance. The new construction segment dictates large-scale procurement, but the renovation and replacement market offers more stable, higher-margin opportunities.
Product specifications are shaped by a matrix of regulations, including the EU's REACH for chemical content and CE marking for performance declaration. In the United States, EPA guidelines on material lifecycle and disposal influence manufacturing processes, while local building codes dictate fire safety and wind load requirements. Manufacturers must therefore balance investments in material science innovation against the need to comply with an increasingly fragmented and stringent set of regional building standards.
Market Dynamics
Regulatory pressure for enhanced building envelope performance, driven by frameworks like the EU Green Deal, is the central force shaping the siding market. This converges with homeowner investment in resilience and aesthetics, steering material development and specification criteria globally.
Growth Catalysts
- Stricter Building Codes:Mandates for improved thermal performance, such as those within the EU Green Deal, are compelling builders to adopt higher-performing siding systems to meet energy efficiency targets.
- New Construction in Southeast Asia:Rapid urbanization in nations like Vietnam and the Philippines creates large-scale demand for weather-resistant siding in both residential and commercial projects, expanding the market's geographic footprint.
- Fiber Cement Adoption:The material's superior durability, fire resistance, and aesthetic versatility are driving its specification over traditional materials, particularly in regions prone to extreme weather and wildfires.
Market Restraints
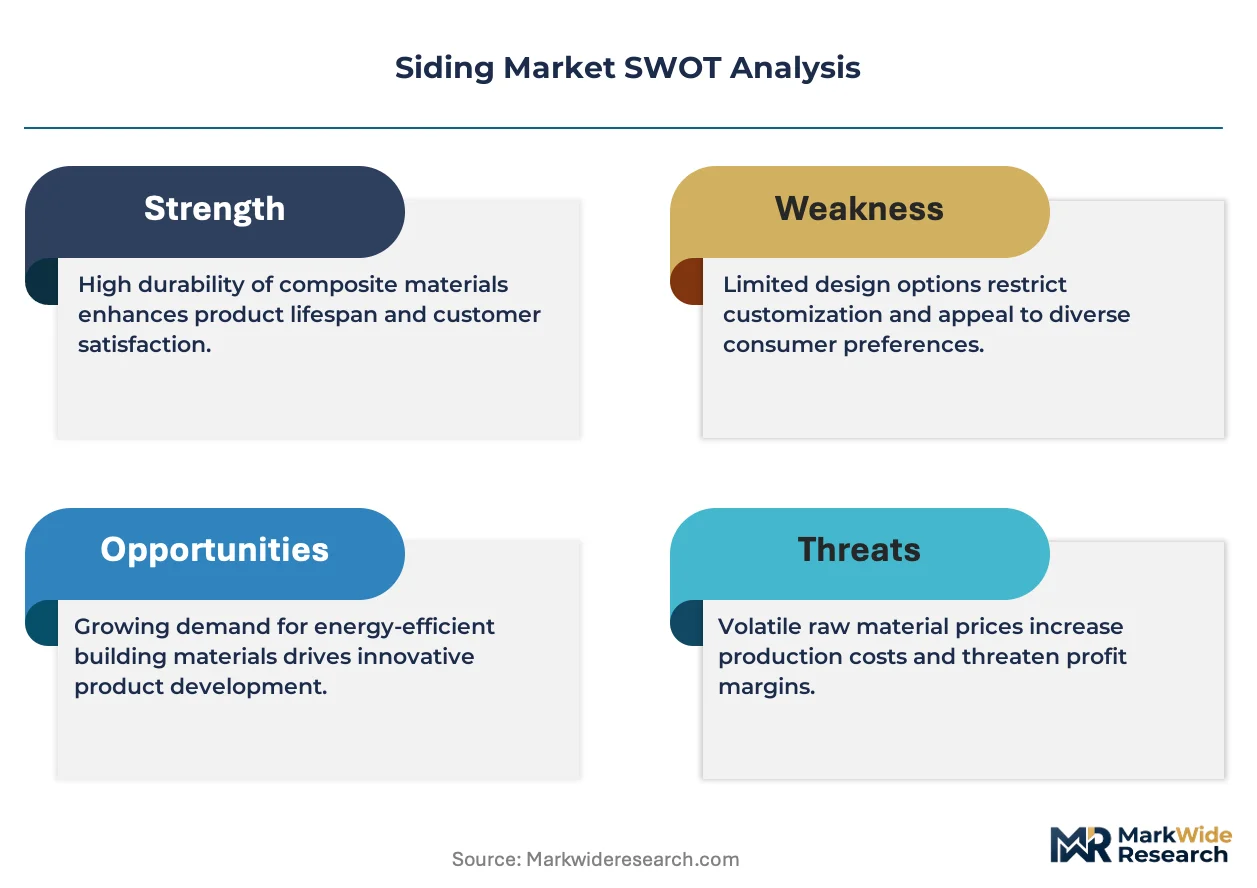
- Input Cost Volatility:Fluctuation in prices for key raw materials, such as PVC resins for vinyl siding and cement for fiber cement products, creates margin pressure and complicates project bidding.
- Skilled Labor Shortages:A deficit of trained installers for more complex systems like fiber cement or insulated siding can lead to project delays, increased costs, and improper installations affecting performance.
- Fragmented Building Codes:The lack of uniform standards across different municipalities and regions requires manufacturers to produce and test multiple product variations, increasing complexity and compliance costs.
Strategic Opportunities
- Digital Visualization Tools:Offering sophisticated software that allows homeowners and architects to visualize siding materials and colors on a digital twin of their project can accelerate decision-making and specification.
- Integrated Cladding Systems:Developing complete wall systems that integrate siding with insulation and water-resistive barriers offers contractors a streamlined, performance-guaranteed solution, creating a new value proposition.
- US Energy Efficiency Incentives:The Inflation Reduction Act (IRA) provides tax credits for energy-efficient home improvements, creating a direct financial incentive for homeowners to upgrade to high-performance insulated siding products.
Industry Challenges
- Logistical Complexity:Managing the transportation and storage of bulky and often fragile siding materials from manufacturing plants to distributed job sites presents significant logistical hurdles and costs for distributors.
- Chemical Content Compliance:Adhering to evolving regulations like the EU's REACH for chemical substances in polymers and coatings requires continuous investment in material science and supply chain verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Siding Market |
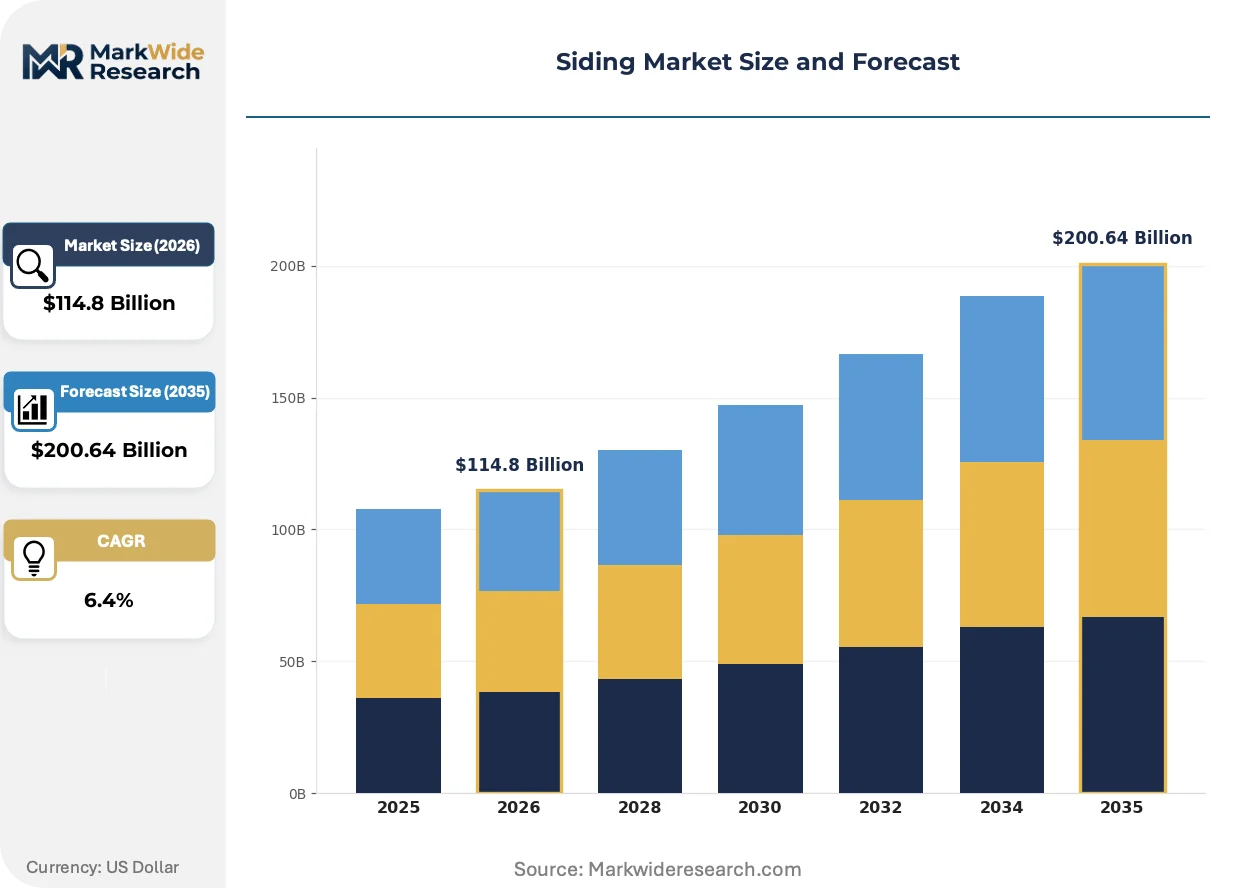
| Market Size in 2026 | $114.8 Billion |
| Market Size in 2035 | $200.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Vinyl, Fiber Cement, Wood, Aluminum, Brick, Stone Installation Type: New Construction, Renovation, Repair, Replacement Application: Residential Buildings, Commercial Complexes, Institutional Buildings, Warehouses Distribution Channel: Direct Sales, Dealers, Home Improvement Centers, Online Retailers |
| Companies Covered | Louisiana-Pacific, Nichiha, James Hardie, ProVia, Allura, CertainTeed, Westlake Royal Building Products, Kaycan, Cornerstone Building Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Siding Market Strategic Shifts & Innovations
Innovations in material science aimed at enhancing durability and sustainability are actively reshaping the siding market. These product developments intersect with new digital design tools and stricter global building performance standards, altering specification criteria for both residential and commercial structures.
Advanced fiber cement formulations incorporate proprietary additives that enhance moisture resistance and dimensional stability. Architects in fire-prone regions are rapidly specifying these next-generation products for superior resilience against environmental stressors. This performance-driven material science is converging with digital printing technologies, allowing for hyper-realistic wood grain and stone textures that challenge traditional material limitations.
The United States' Inflation Reduction Act (IRA) introduced significant tax credits and rebates for residential energy efficiency upgrades. This policy directly incentivizes homeowners to replace old, inefficient cladding with modern insulated siding systems that improve a home's thermal envelope. As a result, the residential renovation segment is experiencing a pronounced shift in product demand toward siding with higher R-values and integrated foam backing.
Homeowner and contractor purchasing decisions are increasingly influenced by digital configuration and visualization tools. This shift diminishes the reliance on physical samples from traditional showrooms, empowering online-first material suppliers and direct-to-contractor channels. The trend is most advanced in the North American residential market, where DIY and professional renovators use manufacturer-provided apps to finalize design choices before procurement.
Siding Market Segmentation
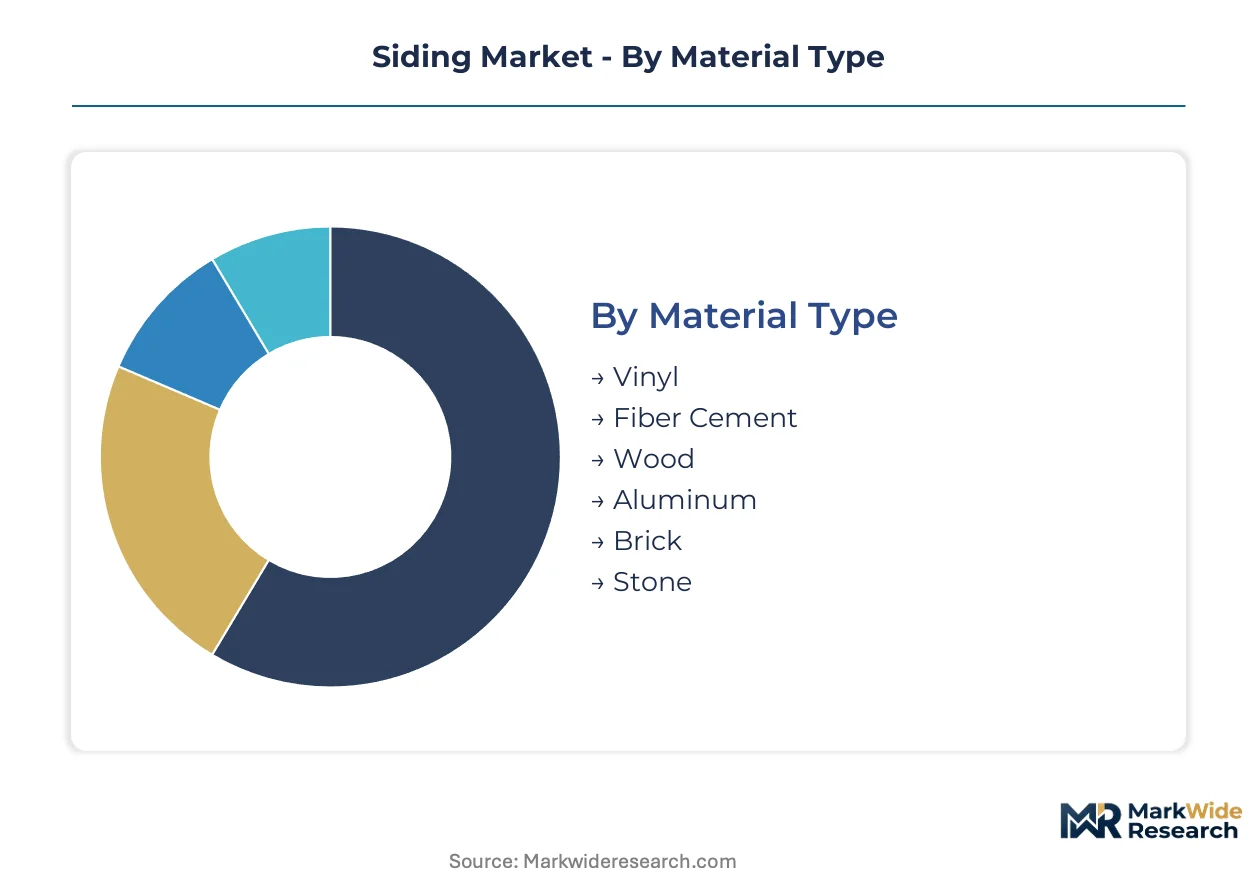
The siding market's structure reflects diverse material needs and installation contexts across global construction. Segmenting the market by material type, installation method, application, and distribution channel reveals distinct value chains and competitive dynamics. Understanding these divisions helps pinpoint areas of concentrated demand and evolving procurement strategies.
Material Type:
Supply concentration in siding materials currently centers on high-volume production of synthetic options, driven by cost-effectiveness and performance attributes. Manufacturers invest heavily in scalable processes for these dominant material types.
- Vinyl:This synthetic polymer-based siding offers cost-effectiveness and low maintenance, making it a primary choice for residential applications across North America. Volume demand for vinyl siding remains high due to its ease of installation and wide color palette.
- Fiber Cement:Composed of cement, sand, and cellulose fibers, this material provides exceptional durability, fire resistance, and aesthetic versatility, seeing increased specification in regions like California and Australia due to wildfire concerns. Demand is concentrating in new construction and high-performance renovation projects.
- Wood:Traditional wood siding options, including cedar and redwood, offer natural aesthetics and insulation properties, appealing to custom home builders in temperate climates.
- Aluminum:Lightweight and corrosion-resistant, aluminum siding serves both residential and light commercial projects, particularly where durability against impact is prioritized.
- Brick:A classic masonry material, brick offers superior durability and fire resistance, predominantly used in new residential construction in the United States and Europe.
- Stone:Natural or manufactured stone cladding provides a premium aesthetic and high durability, often specified for luxury residential and commercial facades.
Today's leader: Vinyl. Tomorrow's challenger: Fiber Cement.
Installation Type:
Installation types present different cost structures for contractors and homeowners, influencing material selection and project budgeting. Labor intensity and material handling costs vary significantly across these segments.
- New Construction:This segment involves large-scale procurement for entire building envelopes, often prioritizing material cost and installation speed for residential developments and commercial complexes. Demand concentrates in rapidly urbanizing areas of Southeast Asia, such as Vietnam and the Philippines.
- Renovation:Focused on upgrading existing structures, this segment offers stable, higher-margin opportunities, driven by homeowner investments in curb appeal and energy efficiency upgrades in established markets like the United States.
- Repair:This involves localized fixes to damaged siding, requiring material matching and specialized labor for small-scale interventions on existing properties.
- Replacement:Full removal and installation of new siding on existing structures, driven by material degradation or aesthetic updates, often influenced by long-term durability considerations.
The new construction segment is expanding most quickly, while renovation provides the most stable revenue streams.
Application:
Volume demand for siding materials varies significantly across different building applications, reflecting distinct performance requirements and aesthetic priorities for each structure type.
- Residential Buildings:This segment constitutes the largest volume of siding demand, driven by single-family homes and multi-unit dwellings, with a strong focus on aesthetics and energy efficiency. Homeowner investments in curb appeal are a primary driver.
- Commercial Complexes:Siding for commercial structures demands high durability, fire resistance, and often specific aesthetic branding, with project scales requiring robust material specifications. James Hardie leverages its fiber cement dominance in this area.
- Institutional Buildings:This includes schools, hospitals, and government facilities, where siding must meet stringent safety codes, long-term durability, and low maintenance requirements.
- Warehouses:Functional and cost-effective siding solutions are paramount for large industrial warehouses, prioritizing weather protection and structural integrity over intricate aesthetics.
Residential buildings command the highest volume, while commercial complexes drive demand for specialized, high-performance materials.
Distribution Channel:
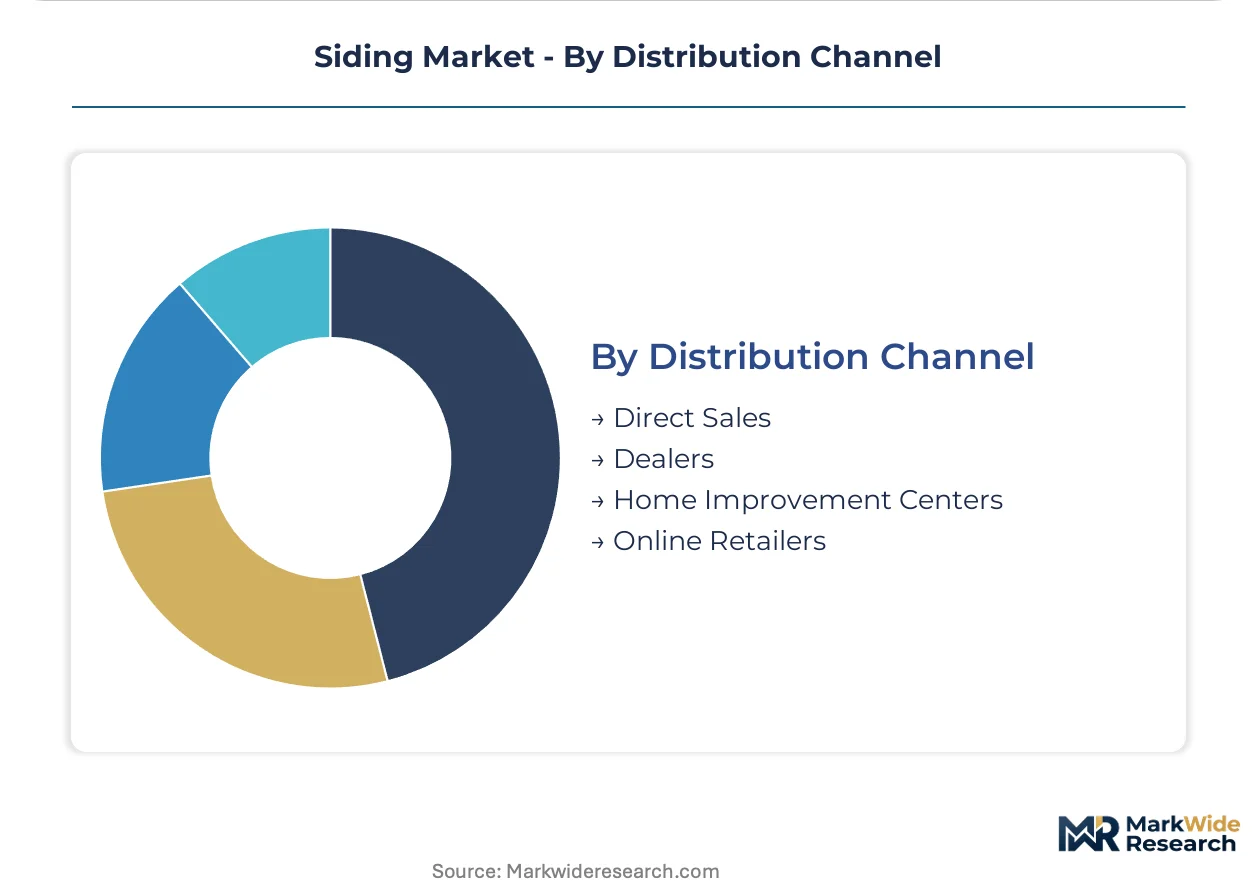
Customer type significantly influences the selection and operation of distribution channels, with professional contractors and DIY homeowners exhibiting distinct purchasing behaviors and service expectations.
- Direct Sales:Manufacturers engage directly with large-scale builders or commercial developers for bulk orders, facilitating custom solutions and direct technical support.
- Dealers:Local and regional dealers serve as primary intermediaries, offering product expertise and logistics support to contractors and smaller construction firms. Cornerstone Building Brands utilizes its vast network here.
- Home Improvement Centers:Retailers like Lowe's or Home Depot cater to both DIY homeowners and professional contractors, providing accessible inventory and design consultation.
- Online Retailers:E-commerce platforms offer convenience and broad product selection, increasingly influencing material specification and procurement for renovation projects.
Procurement patterns are shifting towards a hybrid model, combining traditional dealer support with the convenience of online access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage drives some siding manufacturing decisions, as producers seek regions with less stringent environmental or labor compliance costs. However, increasing global standards for building performance are narrowing these gaps, pushing investment towards material science innovation. This shift influences where new production facilities are located and how products are specified.
United States
Homeowner investments in renovation and new residential construction fuel significant demand for siding materials. The Inflation Reduction Act (IRA) provides tax credits for energy-efficient home improvements, boosting demand for insulated siding systems. Manufacturing hubs in the Midwest, particularly around Ohio and Indiana, focus on high-volume vinyl and fiber cement production.
China
Rapid urbanization and infrastructure development create substantial demand for exterior cladding in commercial and residential projects. China's dual carbon goals are driving the adoption of more sustainable and energy-efficient building materials. Industrial zones in the Yangtze River Delta concentrate on producing diverse siding types for both domestic and export markets.
Vietnam
New construction in residential and commercial sectors generates strong demand for weather-resistant siding. Vietnam's government incentives for foreign investment support the expansion of building material manufacturing capacity. Ho Chi Minh City and Hanoi are experiencing significant construction booms, requiring large volumes of cost-effective cladding.
Germany
Stricter building codes, influenced by the EU Green Deal, mandate improved thermal performance for exterior claddings. The REACH regulation governs chemical content, influencing material formulations for polymer-based sidings. Production facilities in Bavaria and North Rhine-Westphalia specialize in high-performance, sustainable facade systems.
Australia
Demand for durable and fire-resistant siding is high due to extreme weather conditions and bushfire concerns. Australia's National Construction Code sets stringent fire safety and wind load requirements for exterior materials. Manufacturers in New South Wales and Victoria supply fiber cement and other resilient products to a growing market.
Siding Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with established players dominating high-value, performance-driven applications. The market exhibits a tiered structure, from large multi-material conglomerates to niche material innovators. Strategic archetypes include integrated solution providers, material science innovators, and regional distribution powerhouses. Companies frequently engage in strategic partnerships to expand their product portfolios and pursue geographic expansion into high-growth regions.
Within the integrated solution provider archetype, Cornerstone Building Brands and Westlake Royal Building Products exemplify companies leveraging extensive distribution networks and multi-material offerings across North America. James Hardie, a global leader in fiber cement, represents a material science innovator focusing on enhanced durability and fire resistance for demanding applications. CertainTeed, with its extensive portfolio of vinyl and polymer products, also sits within the branded specialist category. These firms anchor significant market share by offering comprehensive product lines and strong brand recognition across diverse construction channels, adapting to regional aesthetic preferences and performance requirements.
| Leading Market Players |
|---|
| Louisiana-Pacific |
| Nichiha |
| James Hardie |
| ProVia |
| Allura |
| CertainTeed |
| Westlake Royal Building Products |
| Kaycan |
| Cornerstone Building Brands |
| Others |
Cost & Logistics Intelligence
EU Green Deal mandates for improved thermal performance directly influence the availability of compliant siding products, allowing manufacturers meeting these standards to command premium pricing for high-performance systems. This regulatory gate also shapes investment in material science innovation.
Pricing Analysis
Distributor margins significantly influence final siding product costs for contractors and end-users. The market operates on a per-unit transactional model for standard products and project-based pricing for custom commercial facade systems. Price differentiation stems from material type, with fiber cement commanding higher prices than vinyl, and specific certifications like fire ratings. Input cost volatility for PVC resins and cement creates upward pricing pressure for manufacturers. New construction buyers prioritize cost-effectiveness, while renovation customers exhibit lower price sensitivity for energy-efficient or aesthetically superior options.
Supply Chain Analysis
Regional distribution centers and local dealer networks are critical for managing bulky siding materials effectively. Global production concentrates in China for diverse materials, the US Midwest for vinyl and fiber cement, and Vietnam for cost-effective options. The industry relies on PVC resins for vinyl products and cement and cellulose fibers for fiber cement manufacturing. Logistical complexity in transporting large, fragile panels represents a significant supply chain risk for manufacturers. Downstream distribution primarily operates through dealers and large home improvement centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The siding market functions as a regulatory compounder, continuously amplifying demand for high-specification exterior claddings. The EU Green Deal, with its stringent thermal performance mandates, specifically drives this trend. This policy environment accelerates material science innovation.
For Market Incumbents:To counter margin pressure from input cost volatility, incumbents should deepen vertical integration into key raw material production. Consolidate regional manufacturing facilities to optimize scale economies and invest in advanced automation for fiber cement production. Expand certification investments for fire-resistant and energy-efficient systems across all product lines. This approach reinforces market leadership against emerging material technologies.
For New Entrants and Emerging Players:Begin with underpenetrated regional markets in Southeast Asia, specifically targeting new construction projects in Vietnam. Focus on cost-effective, weather-resistant polymer-based siding systems tailored to local climate conditions. Leverage digital visualization tools as a go-to-market angle to accelerate specification and homeowner decision-making. Strategic partnerships with local builders can secure early market share.
For Investors and Strategic Acquirers:Roll-up economics work for regional distribution powerhouses because of fragmented local markets and logistical complexities. The siding market offers long-term viability over the next decade, driven by renovation cycles and green building mandates. Target specialist manufacturers of insulated siding systems or digital visualization software providers for strategic acquisitions. Watch for increasing M&A activity among mid-sized regional dealers as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Fiber Cement Production Capacity | Addresses growing demand for fire-resistant materials in regions like Australia and California. |
| Invest in Digital Visualization Platforms | Accelerates homeowner and architect decision-making for complex siding material specifications. |
| Develop Integrated Insulated Cladding Systems | Captures IRA incentives for energy-efficient home improvements in the United States residential market. |
| Enhance Supply Chain Resiliency | Mitigates input cost volatility for PVC resins and cement affecting manufacturer margins. |
| Pursue CE Marking for Polymer Products | Ensures compliance with EU Green Deal thermal performance mandates for European market access. |
Research Approach
Bottom-up residential renovation modeling reconciled against top-down material manufacturer tracking forms the analytical core. This approach combined primary interviews with industry architects, contractors, material scientists, and procurement managers, validated against extensive secondary data. Secondary sources included building code databases, trade association reports, SEC 10-K filings, and environmental agency guidelines. Triangulation across these diverse data points ensured robust market sizing and trend identification.
Historical trendline analysis established baseline market performance across the analysis window. The framework modeled segmentation dimensions including material type, installation method, application, distribution channel, and regional building codes. Compound annual growth rates were derived from projected shifts in demand drivers and technological advancements. Forecast inputs included homeowner renovation spending and new construction starts in key geographies.
Several conditions sit outside the modeled scope, including geopolitical instability and unforeseen raw material supply shocks. Forecasts reflect assumptions regarding regulatory stability and economic growth trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
Germany Prefabricated Houses Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Japan Residential Construction Market
Residential Construction
Global Manufactured Homes Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Prefabricated Homes Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
UK Manufactured Homes Market
Residential Construction
Residential Roofing Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
UK Residential Construction Market