
 Leather Embossing Machine Market | 2026-2036
Leather Embossing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Embossing Machine Market Foresight
Direct-to-tannery distribution is reshaping how leather embossing equipment reaches end users, with Asian manufacturers bypassing traditional dealer networks to capture margin. Crown Machinery Company Limited leverages its Dongguan manufacturing base to sustain cost-competitive rotary press exports across Southeast Asia. Campbell Randall specializes in manual and semi-automatic flat bed units that anchor its position among European artisan workshops. Artsgate Trading Pte Ltd. competes through Singapore-based logistics control, extending rapid spare parts availability to African and Middle Eastern tanneries.
A leather embossing machine mechanically or thermally impresses patterns onto tanned hides using engraved plates, rollers, or laser heads, typically operating at pressures from 50 to 300 tons and temperatures between 80°C and 180°C depending on substrate type. The equipment serves tanneries and leather goods factories seeking to differentiate finished products through tactile surface textures without additional material layers. Rotary technology leads installed base volumes due to throughput advantages in mass footwear production, while laser engraving claims the fastest expansion trajectory as digital pattern libraries enable single-batch customization for accessories and premium bags. Hydraulic flat bed systems retain margin concentration in upholstery applications where thick, full-grain hides demand sustained, uniform pressure across wide working surfaces.
CE marking requirements under the EU Machinery Directive constrain market access for non-certified Asian suppliers, while China's GB standards and MIIT equipment safety rules shape domestic procurement specifications. EPA air quality regulations in the United States limit volatile organic compound emissions from heat press operations, indirectly favoring laser and digital printing technology migrations. Stakeholders must monitor how REACH chemical restrictions and evolving dual carbon goals in China redirect tannery capital toward embossing equipment compatible with chrome-free tanning and reduced-energy finishing lines.
Market Dynamics
Rotary press manufacturers in Dongguan are consolidating supply chains around laser-compatible embossing heads as tanneries face dual carbon compliance deadlines from MIIT. This hardware pivot is compressing replacement cycles for hydraulic flat bed units across Guangdong Province while redirecting R&D budgets toward energy-efficient thermal management systems.
Growth Catalysts
- REACH chemical restrictions:European tanneries are retiring solvent-based finishing lines. Water-compatible press technologies now capture replacement demand across Italy and Germany.
- Luxury automotive upholstery expansion:German OEMs are adding embossed leather capacity for electric vehicle interiors. This creates pull-through for wide-format flat bed systems.
- Laser engraving adoption:Digital pattern libraries enable single-batch customization. Accessories manufacturers in China's Pearl River Delta are retrofitting rotary lines with hybrid laser heads.
Market Restraints
- CE certification barriers:Non-certified Asian suppliers face exclusion from EU procurement. ECHA documentation requirements add twelve to eighteen months to market entry timelines.
- Chrome tanning dependency:Chrome-free substrate compatibility remains uneven across installed press bases. Tanneries face stranded asset risk on legacy equipment.
- Specialized steel supply concentration:Engraved roller production depends on German and Japanese tool steel sources. Geopolitical friction threatens spare parts availability.
Strategic Opportunities
- Sub-Saharan Africa greenfield tanneries:Ethiopian and Kenyan facilities are sourcing semi-automatic flat bed units for artisan-scale production. Artsgate Trading's Singapore logistics hub positions for regional spare parts dominance.
- EPA VOC compliance in the United States:Heat press emission limits are accelerating laser system migrations. California-based upholstery manufacturers represent early adopters.
- Converged digital-thermal workflows:IoT-enabled press monitoring combined with AI-driven pattern optimization is reducing setup waste. Dongguan machinery clusters are piloting integrated control systems.
Industry Challenges
- Engraved die fabrication bottleneck:Master pattern sculptors require seven to ten year apprenticeships. Artisans in Italy's Arzignano district command premium wages that inflate tooling costs.
- Legacy hydraulic system integration:Tanneries operating 1990s-era flat bed presses face control retrofit complexity. Proprietary valve architectures block standardized automation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Embossing Machine Market |
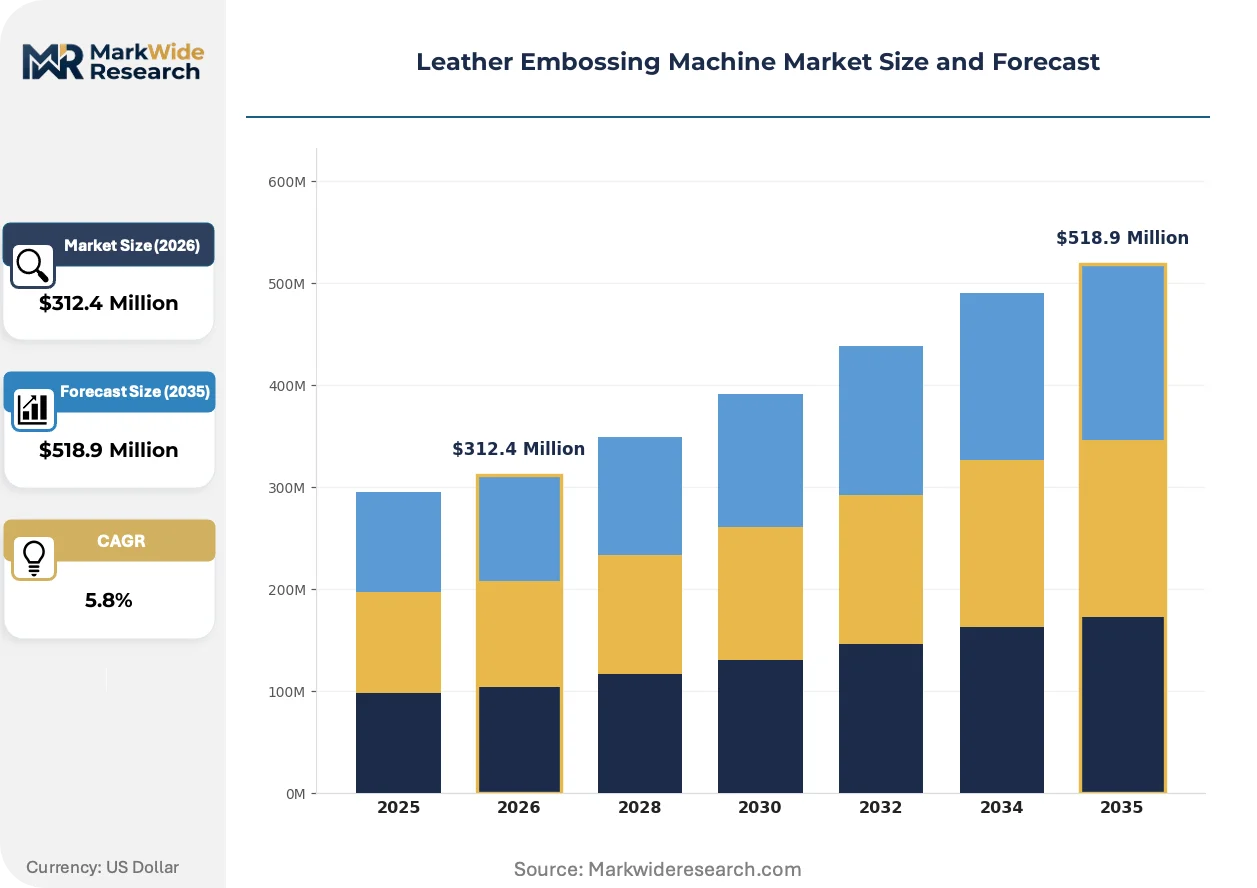
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bed, Cylinder, Rotary, Hydraulic Technology: Heat Press, Laser Engraving, Digital Printing, Manual Application: Footwear, Accessories, Bags, Upholstery End User: Manufacturers, Artisans, Retailers, Hobbyists |
| Companies Covered | Crown Machinery Company Limited, Artsgate Trading Pte Ltd., Campbell Randall, Dongguan City South Nekon Machinery Co., LTD., Hubei Tengcang Building Material Technology Co., Ltd., Shanghai UPG International Trading Co., Ltd, Hangzhouwilling International Co., Ltd., OMAC srl, Cerys Corporation Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Embossing Machine Market Shifts & Advancements
Laser-based pattern transfer is compressing the economics of short-run leather goods production while forcing rotary press incumbents toward hybrid system development. Three interconnected developments are reshaping competitive positioning and procurement criteria.
Diode-pumped solid-state laser embossing is digitizing pattern workflows previously locked to mechanical engraving. Italian luxury bag manufacturers are adopting these systems for prototype-to-production flexibility. This capability is digitizing the economics of batch-size-one manufacturing that rotary technology cannot match.
China's MIIT dual carbon targets are mandating energy consumption disclosures for industrial equipment. Guangdong Province tanneries now require press suppliers to document kWh-per-hide metrics. Heat recovery systems and servo-electric pressure actuation are capturing procurement preference in domestic RFPs.
Direct-to-factory distribution is eliminating traditional machinery dealer networks across Southeast Asia. Dongguan-based manufacturers are establishing captive service centers in Vietnam and Indonesia. This channel restructuring is most visible in footwear production hubs where spare parts lead times previously stretched to six weeks.
Leather Embossing Machine Market Segmentation
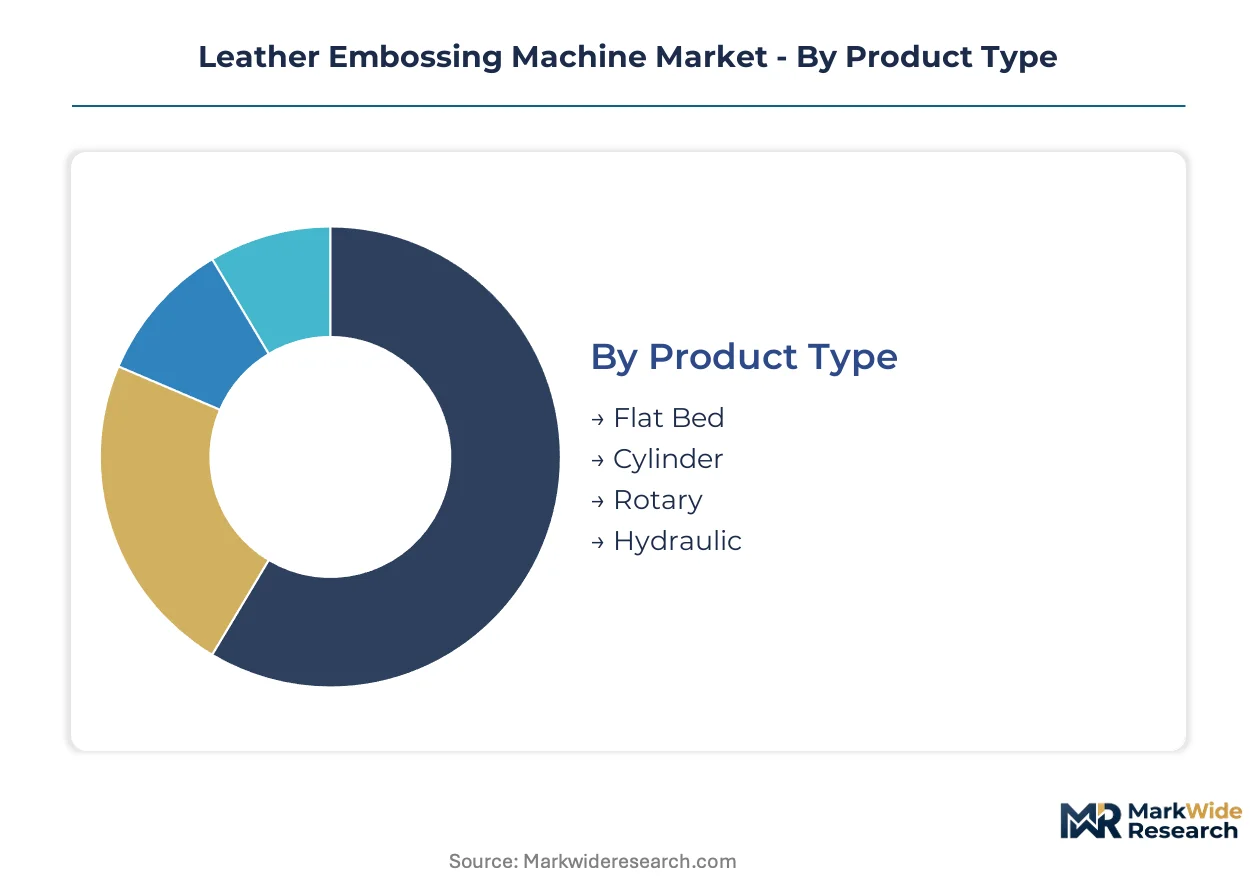
Segmentation in leather embossing equipment determines service contract structures, spare parts stocking intensity, and technical support staffing models across distributor networks. Rotary press installations in high-volume footwear plants demand predictive maintenance programs, while laser systems for accessories manufacturers require software update subscriptions.
Product Type:
After-sales-service intensity varies dramatically across mechanical architectures, with hydraulic systems requiring fluid analysis programs and laser-compatible rotary heads needing optical calibration protocols.
- Flat Bed:Hydraulic flat bed presses apply sustained uniform pressure across wide working surfaces, accommodating thick full-grain hides for automotive upholstery. German OEMs expanding electric vehicle interior capacity are specifying wide-format flat bed systems with heat recovery integration.
- Cylinder:Cylinder presses utilize engraved roller pairs for continuous pattern transfer, dominating mass-production footwear lines in China's Pearl River Delta. Dongguan machinery clusters are retrofitting these systems with hybrid laser heads to meet MIIT dual carbon compliance deadlines.
- Rotary:Rotary configurations lead installed base volumes through throughput advantages in high-volume production environments.
- Hydraulic:Hydraulic actuation systems retain margin concentration in heavy-hide applications requiring precise pressure control.
By volume, Rotary leads. By growth pace, Cylinder is ahead.
Technology:
Technology selection drives capital recovery timelines, with digital systems commanding premium pricing but enabling shorter production runs that artisan workshops prioritize.
- Heat Press:Thermal transfer systems apply engraved plates at 80°C to 180°C operating temperatures, serving traditional tanneries with established solvent-based finishing lines. EPA VOC emission limits in the United States are accelerating migration away from heat-intensive processes toward laser alternatives.
- Laser Engraving:Diode-pumped solid-state lasers digitize pattern workflows through digital pattern libraries, enabling single-batch customization for luxury bag manufacturers. Italian accessories producers are adopting these systems for prototype-to-production flexibility unmatched by mechanical engraving.
- Digital Printing:Digital pattern deposition systems integrate with IoT monitoring platforms for real-time quality control.
- Manual:Hand-operated presses serve entry-level artisans and educational institutions with minimal capital requirements.
Heat Press retains the largest installed base. Laser Engraving is expanding most quickly.
Application:
Application focus determines press specification priorities, with upholstery demanding pressure uniformity and accessories requiring pattern flexibility.
- Footwear:Mass-production shoe factories prioritize rotary press throughput for consistent pattern replication across thousands of units. Guangdong Province tanneries serving export markets specify equipment with documented kWh-per-hide metrics to satisfy domestic procurement requirements.
- Accessories:Small leather goods manufacturers value rapid pattern changeover capabilities for seasonal collections. REACH chemical restrictions are pushing European accessories producers toward water-compatible press technologies that integrate with chrome-free tanning lines.
- Bags:Premium handbag production combines aesthetic precision with durability requirements for high-value finished goods.
- Upholstery:Furniture and automotive seating applications require wide-format processing capabilities for large hide dimensions.
Footwear commands the greatest unit volume. Accessories is gaining share fastest.
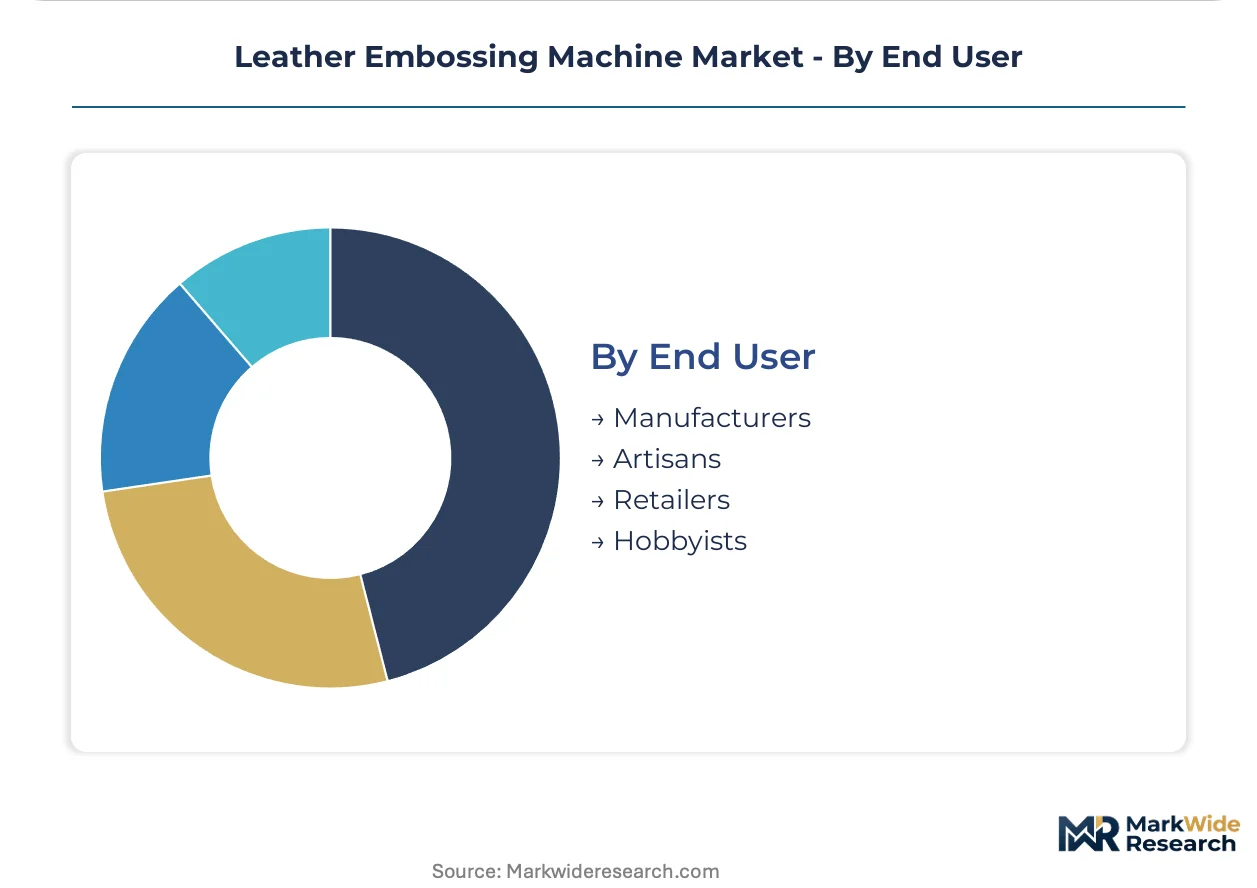
End User:
End-user category shapes distribution channel selection, with manufacturers accepting direct-to-factory procurement while hobbyists rely on dealer networks for training support.
- Manufacturers:Industrial tanneries and leather goods factories operate equipment at 50 to 300 ton pressure ranges for continuous production. Ethiopian and Kenyan greenfield facilities are sourcing semi-automatic units through Singapore-based logistics hubs for regional spare parts availability.
- Artisans:Small-scale workshops in Italy's Arzignano district utilize manual and semi-automatic flat bed units, accepting longer setup times for craft differentiation. Master pattern sculptors command premium wages that inflate tooling costs for this segment.
- Retailers:Brand-owned production facilities integrate embossing capacity for vertical control over surface finishing.
- Hobbyists:Individual practitioners represent minimal revenue concentration but serve as entry-point brand exposure for equipment suppliers.
Manufacturers absorb the majority of capital expenditure. Artisans show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH chemical restrictions and China's MIIT dual carbon mandates are redirecting capital toward water-compatible press technologies. Procurement patterns now favor equipment with documented energy consumption metrics across major manufacturing clusters.
China
Guangdong Province tanneries dominate global rotary press installations, with Dongguan machinery clusters retrofitting hybrid laser heads to meet MIIT compliance deadlines. GB standards and equipment safety rules under MIIT shape domestic procurement specifications. Pearl River Delta accessories manufacturers are piloting IoT-enabled press monitoring for waste reduction.
Germany
Luxury automotive upholstery expansion for electric vehicle interiors drives wide-format flat bed demand from OEM suppliers. CE marking requirements under the EU Machinery Directive constrain non-certified Asian supplier access. Baden-Württemberg and Bavaria host precision tooling workshops serving engraved die fabrication for premium applications.
Italy
Artisan workshops in the Arzignano district utilize manual and semi-automatic flat bed units for craft differentiation. ECHA documentation requirements extend market entry timelines for foreign equipment suppliers. Tuscany and Lombardy concentrate accessories manufacturers adopting laser engraving for prototype-to-production flexibility.
United States
EPA air quality regulations limit volatile organic compound emissions from heat press operations, accelerating laser system migrations. California-based upholstery manufacturers represent early adopters of compliant technologies. The Southeast and Midwest retain automotive seating production requiring wide-format processing capabilities.
Ethiopia
Greenfield tanneries in Addis Ababa and surrounding industrial zones source semi-automatic flat bed units for artisan-scale production. The country's national industrial development strategy prioritizes leather sector expansion for export revenue. Singapore-based logistics hubs position for regional spare parts distribution across Sub-Saharan Africa.
Leather Embossing Machine Market Competitive Landscape
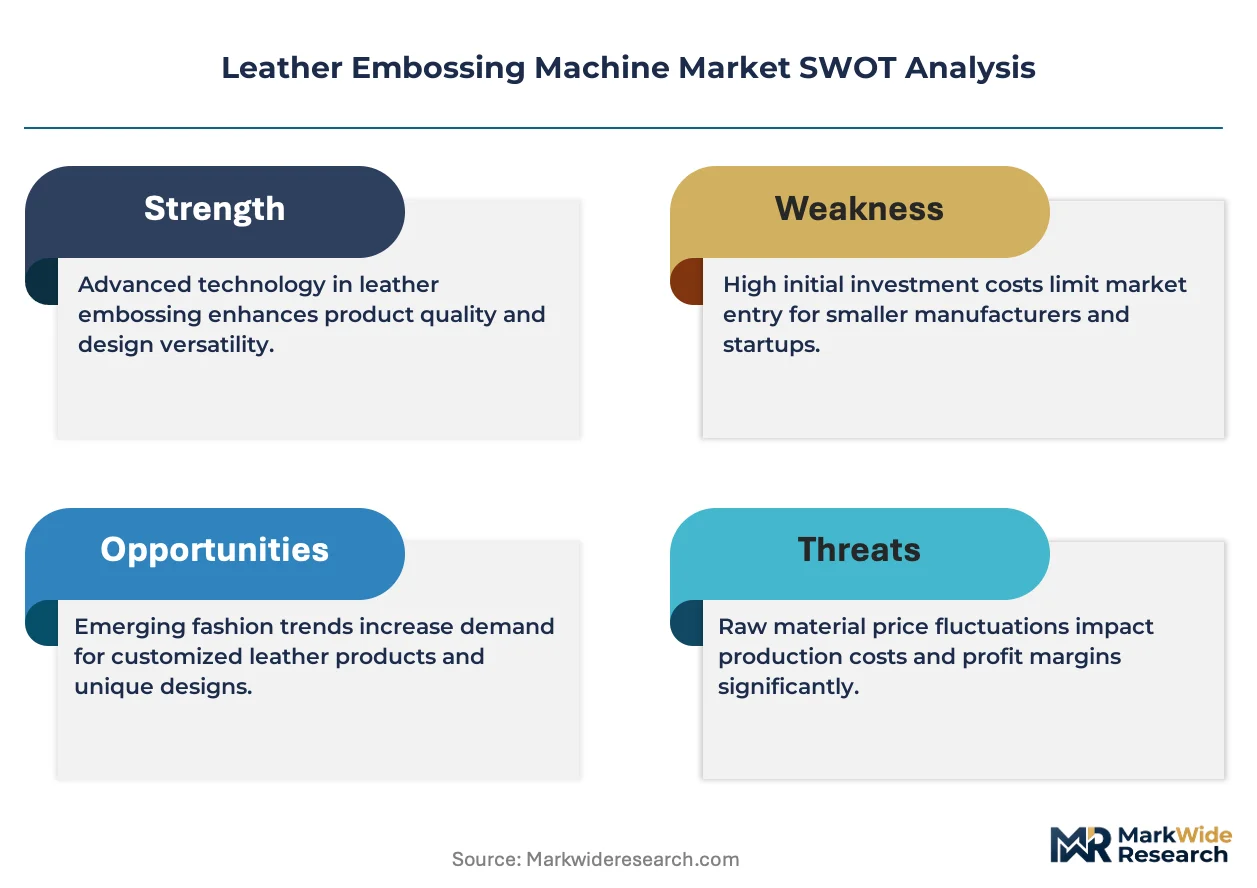
On the supply side, the industry is bifurcated between scale-driven rotary press fabricators and precision-focused flat bed specialists. Chinese machinery clusters dominate volume production through integrated manufacturing bases. European incumbents occupy premium positioning via engraved die craftsmanship and CE-certified engineering. Strategic moves concentrate on hybrid laser-thermal system development and direct-to-factory distribution channel restructuring.
Among Dongguan-based fabricators, Crown Machinery Company Limited and Dongguan City South Nekon Machinery Co., LTD. exemplify the scale-driven archetype serving high-volume footwear production. Campbell Randall occupies a position within the European artisan-tier segment. Artsgate Trading Pte Ltd. represents the logistics-anchored model extending spare parts availability to underserved regions.
| Leading Market Players |
|---|
| Crown Machinery Company Limited |
| Artsgate Trading Pte Ltd. |
| Campbell Randall |
| Dongguan City South Nekon Machinery Co., LTD. |
| Hubei Tengcang Building Material Technology Co., Ltd. |
| Shanghai UPG International Trading Co., Ltd |
| Hangzhouwilling International Co., Ltd. |
| OMAC srl |
| Cerys Corporation Limited |
| Others |
Supply & Pricing Matrix
The Shenzhen-Port Mombasa freight corridor's rate volatility transmits cost pressure through Guangdong machinery clusters while amplifying price spreads between CE-certified European systems and non-certified Asian alternatives. This logistics dynamic concentrates margin capture among integrated manufacturers with captive service networks, forcing price-sensitive tanneries toward direct procurement from Dongguan fabricators.
Pricing Analysis
Certification level (CE/GB/ISO-grade) creates the primary spread across equipment tiers, with CE-marked flat bed systems commanding substantial premiums over domestic Chinese alternatives. Pricing stratifies across premium certified, standard compliant, and economy non-certified tiers based on regulatory documentation depth and after-sales bundling intensity. Cost compression in the economy tier is intensifying because Ethiopian and Kenyan greenfield tanneries prioritize capital efficiency over certification. Artisan workshops in Italy's Arzignano district show least price sensitivity, prioritizing engraved die craftsmanship and spare parts availability over upfront equipment cost.
Supply Chain Analysis
Export control regimes on high-precision laser optics limit flows from German and Japanese suppliers into Chinese machinery integrators, constraining hybrid rotary-laser system assembly rates. Manufacturing concentration centers on China, Germany, and Italy, with engraved roller production drawing from specialized tool steel sources in Japan and Germany. Single-source vulnerability around master pattern sculptors in Italy's Arzignano district threatens tooling cost stability. Distribution runs through direct-to-factory channels across Southeast Asia, bypassing traditional dealer networks in Vietnam and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leather embossing equipment demand is accelerating through dual carbon compliance mandates and laser-digitization inflections that compress replacement cycles across installed bases. This regulatory-technology convergence creates asymmetric opportunity windows for positioned players.
For Market Incumbents: Insulate service revenue streams by establishing captive spare parts hubs in Sub-Saharan Africa before Artsgate Trading consolidates regional logistics control. Deepen backward integration into laser head assembly to reduce dependency on German and Japanese optics suppliers facing export friction. CE certification investment remains essential to defend European automotive upholstery positioning against emerging Asian hybrid system competitors. For New Entrants and Emerging Players: Build out semi-automatic flat bed capacity targeting Ethiopian and Kenyan greenfield tanneries seeking artisan-scale production equipment with regional service coverage. The accessories segment offers most penetrable white-space as Italian luxury bag manufacturers seek prototype-to-production flexibility unavailable from rotary incumbents. Direct-to-factory distribution partnerships with Dongguan machinery clusters provide lowest-friction go-to-market entry. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized leather equipment divisions lacking laser-digitization roadmaps. Long-term viability over the next decade hinges on hybrid thermal-laser system development capability and MIIT compliance documentation depth. Monitor kWh-per-hide disclosure adoption rates across Guangdong Province procurement specifications as inflection indicator for energy-efficient technology preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Laser-Thermal System Development | Dongguan clusters retrofit rotary presses with laser heads to satisfy MIIT dual carbon deadlines. |
| Direct-to-Factory Distribution Expansion | Crown Machinery establishes captive service centers in Vietnam and Indonesia to compress spare parts lead times. |
| CE Certification Investment | Non-certified Asian suppliers face twelve to eighteen month ECHA documentation delays for EU market entry. |
| Sub-Saharan Africa Logistics Hub Establishment | Singapore-based spare parts positioning captures Ethiopian and Kenyan greenfield tannery demand. |
| Energy Consumption Disclosure Compliance | Guangdong procurement now requires documented kWh-per-hide metrics favoring servo-electric actuation. |
Research Methodology
The analysis maps rotary press, flat bed, and laser engraving sub-sectors, each validated through tannery operations managers, machinery procurement leads, and aftermarket service heads. Primary fieldwork combined structured interviews with maintenance directors at Pearl River Delta footwear plants and plant engineers at German automotive upholstery suppliers. Secondary validation drew from MIIT equipment safety filings, ECHA REACH documentation databases, customs trade records, and SEC equipment supplier disclosures. Bottom-up installation base counts were triangulated against top-down capital expenditure estimates from industrial zone development authorities.
Assumptions held fixed include current REACH chemical restriction enforcement intensity and MIIT dual carbon compliance deadline schedules, while variables included laser adoption pace and Sub-Saharan Africa greenfield tannery commissioning rates. The projection framework modeled technology, product architecture, application, and end-user segments across the analysis window. CAGRs were derived from segment-level unit economics and replacement cycle compression factors. Industry-specific inputs incorporated engraved die fabrication bottleneck constraints and chrome-free substrate compatibility transition timelines.
Stress conditions across laser optics supply disruption severity and Ethiopian industrial policy continuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement trajectories and technology cost curves. Material shifts in ECHA documentation processing timelines or MIIT energy disclosure mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Woodworking Circular Saw Blades Market
Tools
CNC Metal Cutting Machine Tools Market
Tools
Europe Paint Spray Guns Market
Tools
Global Cordless Power Tools Market
Tools
Machine Bench Vices Market
Tools
Machine Tools Market
Tools
Blowing Torch Market
Tools
Indexable Tool Inserts Market
Tools
Orbital Sanders Market
Tools
Cutting Tool Inserts Market
Tools
Core Shooter Machine Market
Tools
Vinyl Bending Machine Market
Tools
Cordless Bandsaw Sander Market
Tools
Metal Cutting Tools Market
Tools
Industrial Ladder Market
Tools
Step Ladder Market