
 GRC Cladding Market | 2026-2036
GRC Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
GRC Cladding Market Foresight
Maintenance and lifecycle service contracts is pivoting how GRC cladding suppliers monetize installed facades, shifting revenue from one-time panel sales to recurring building-envelope stewardship. Loveld leverages technical advisory services to sustain long-term client relationships on heritage and commercial projects. Clark Pacific anchors its position through vertically integrated precast manufacturing in the US western region. Fibrobeton differentiates via specialized mold engineering capabilities that reduce custom panel lead times.
Glassfiber reinforced concrete (GRC) cladding consists of cementitious matrix reinforced with alkali-resistant glass fibers, typically containing 5% fiber by weight and achieving flexural strengths of 20-40 MPa depending on spray or premix fabrication method. The material serves primarily as non-load-bearing architectural facade systems offering fire resistance, weather durability, and design flexibility at weights 80% below traditional precast concrete. Panel and tile product types dominate current specification volumes, though prefabricated installation categories are capturing margin pools as general contractors seek reduced site labor exposure. Residential and commercial applications lead absolute demand, with institutional segments showing accelerated specification rates for school and hospital envelope upgrades.
CE marking under Europe's Construction Products Regulation governs GRC cladding market access across EU member states, while China's GB standards and MIIT building material directives shape domestic product compliance thresholds. The US lacks federal cladding-specific regulation, leaving ASTM C1227 and local building code adoptions to fill the standards gap. Stakeholders must monitor how evolving embodied-carbon disclosure rules in Europe and North America reshape material sourcing and manufacturing location decisions.
Market Dynamics
Commercial high-rise developers are consolidating specification power around lightweight facade systems that reduce structural load and accelerate construction schedules. This buyer concentration is compressing margins for GRC panel manufacturers while rewarding suppliers with integrated design-to-installation capabilities.
Growth Catalysts
- Urban Redevelopment Mandates:China's MIIT building material directives prioritize lightweight cladding for density upgrades in tier-one cities. Municipal governments specify GRC for facade retrofits meeting seismic and fire safety codes.
- Embodied Carbon Disclosure:The EU Green Deal and emerging CSRD requirements are accelerating substitution of traditional precast concrete with lower-carbon GRC alternatives in commercial envelope specifications.
- Alkali-Resistant Glass Fiber Advances:Improved AR-glass formulations extending panel service life beyond 50 years are expanding GRC suitability from decorative to primary weatherproofing applications.
Market Restraints
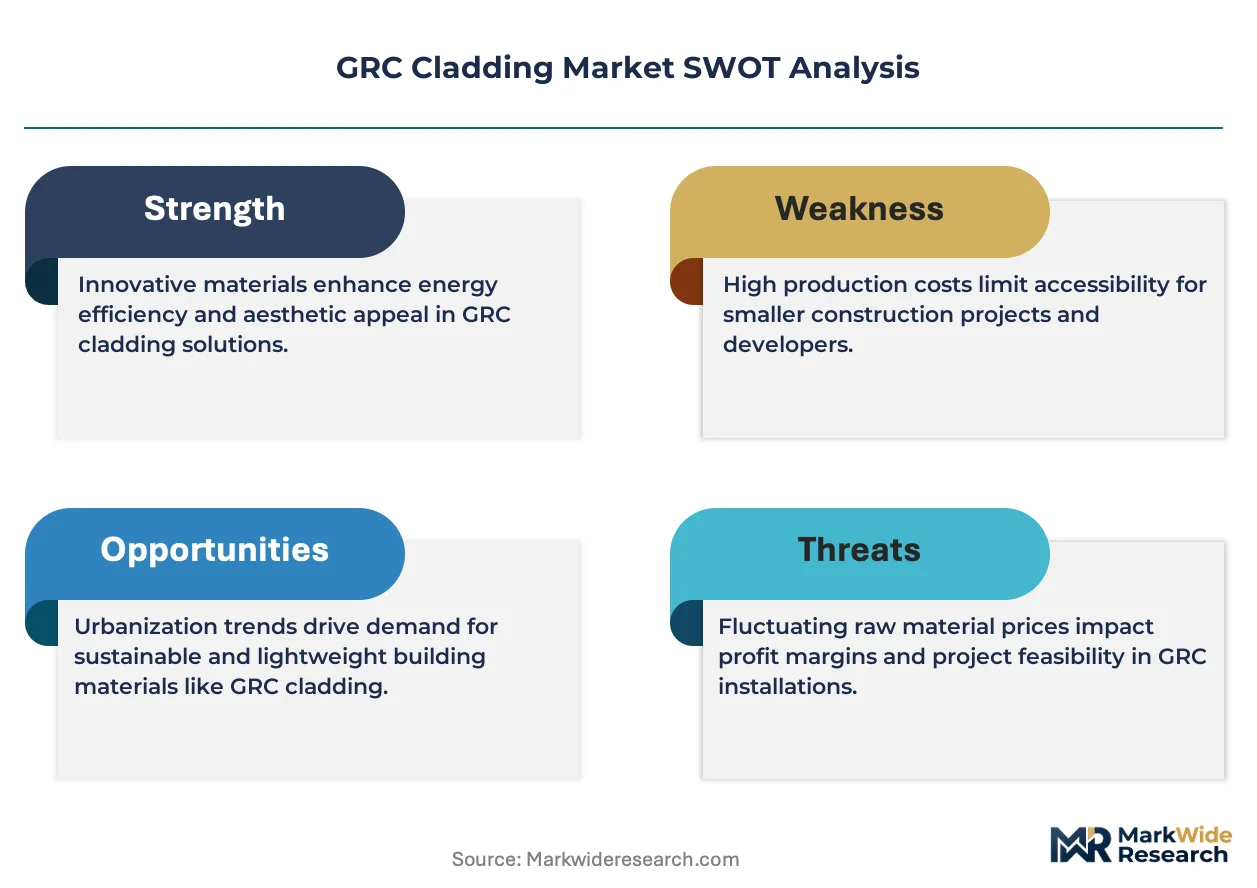
- Cement Price Volatility:Energy-intensive clinker production faces input cost pressure from EU ETS carbon pricing and natural gas supply uncertainty, compressing GRC manufacturer margins.
- Specialized Mold Engineering Bottleneck:Custom panel fabrication requires skilled pattern-making concentrated in Western European and Chinese industrial clusters, creating lead time risk for complex geometries.
- Thin-Section Durability Skepticism:Building insurers and warranty providers in North America impose higher premiums on GRC versus traditional precast, limiting specification in risk-averse institutional segments.
Strategic Opportunities
- India Commercial Construction:BIS certification alignment with European CE marking standards is opening specification pathways for GRC in Mumbai and Bangalore high-rise developments.
- Prefabricated Installation Services:General contractors facing skilled labor shortages are outsourcing complete envelope installation, creating recurring revenue streams beyond panel supply.
- Digital Twin Integration:Convergence of BIM workflows with GRC mold CNC fabrication is compressing design-to-production cycles for complex architectural geometries.
Industry Challenges
- AR-Glass Fiber Supply Concentration:Three specialized manufacturers control global alkali-resistant glass fiber output, creating raw material security risk for GRC producers.
- CE Marking Testing Burden:Extended durability and fire reaction testing under CPR Article 11(1) extends product certification timelines to 18-24 months for new panel formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GRC Cladding Market |
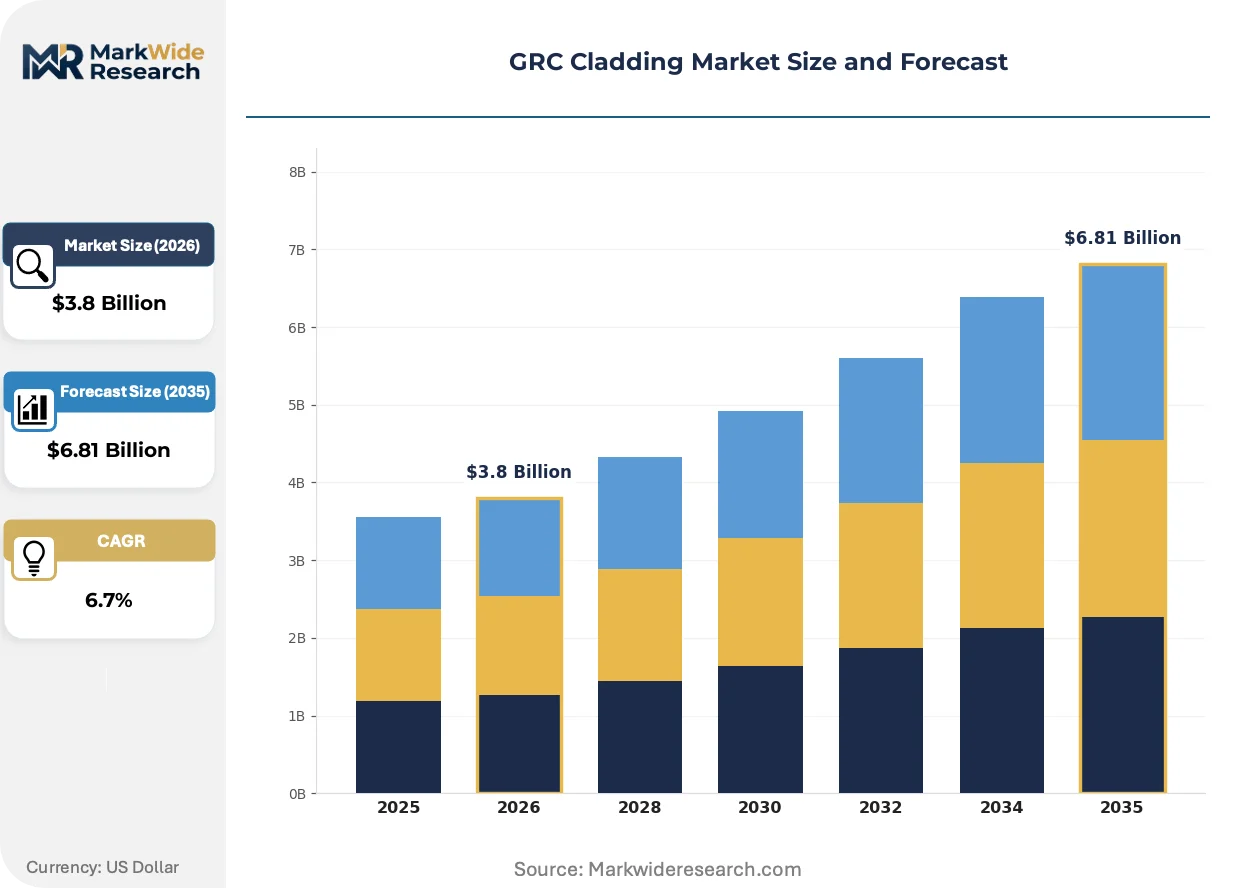
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panels, Tiles, Blocks, Sheets Application: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Renovation, Retrofit, Prefabricated End User: Builders, Architects, Developers, Contractors |
| Companies Covered | ASAHI BUILDING-WALL CO LTD, Loveld, UltraTech Cement Ltd, GB Architectural Cladding Products Ltd, Fibrobeton, Clark Pacific, Willis Construction Co Inc, Ibstock Telling, BB Fiberbeton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GRC Cladding Market Shifts & Advancements
Automation is penetrating GRC manufacturing floors while regulatory pressure on embodied carbon intensifies material substitution decisions. These forces are compressing traditional supply chains and elevating service-based business models.
Hybrid spray-premix manufacturing systems is rewriting production economics for mid-volume custom panel orders. Architectural fabricators in Germany and the UK are adopting robotic spray deposition for standard profiles while retaining hand-layup for complex returns. This dual-mode capability is compressing minimum efficient scale thresholds and enabling smaller batch production without penalty.
REACH substance restrictions on chromium VI compounds are forcing reformulation of GRC surface coatings and anti-efflorescence treatments. ECHA's 2023 sunset date for hexavalent chromium in construction applications has accelerated adoption of titanium dioxide and zinc oxide alternatives. Nordic and Benelux markets are experiencing the fastest specification shifts as public procurement rules embed REACH compliance as a mandatory award criterion.
Design-build procurement consolidation among major general contractors is displacing traditional architect-specified material selection. Turner, Skanska, and Bouygues are embedding preferred GRC supplier panels into early-stage envelope packages, compressing competitive bidding windows. This behavior is most visible in US and UK commercial tower developments where guaranteed maximum price contracts dominate.
GRC Cladding Market Segmentation
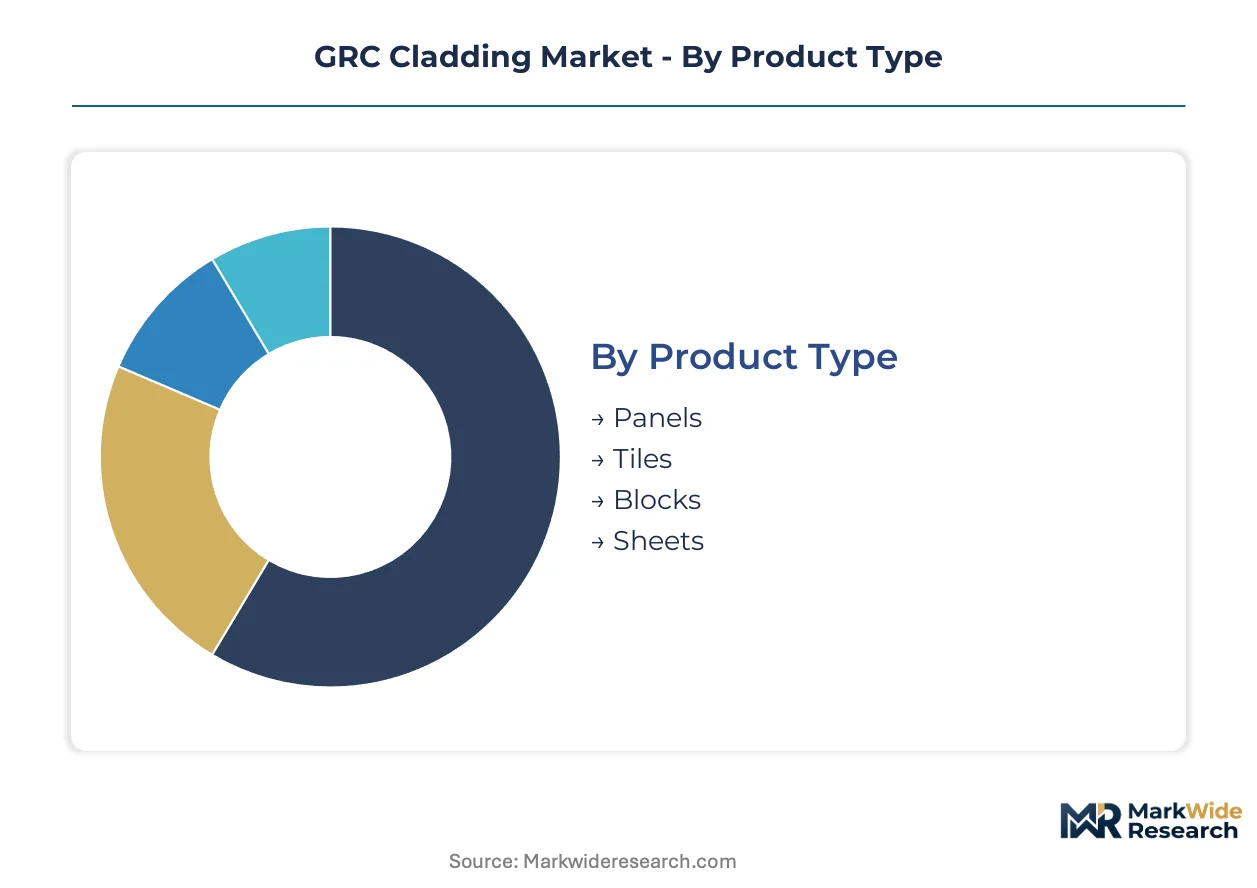
GRC cladding procurement patterns diverge sharply across product formats and installation contexts. Specification power concentrates with distinct buyer types, each driving different technical requirements and margin structures.
Product Type:
Cost tier separates buyers seeking custom architectural expression from those prioritizing standardized coverage.
- Panels:Large-format units typically 10-20mm thick achieve spans exceeding 3 meters with integrated fixing systems. Demand concentrates in China's tier-one cities where municipal redevelopment mandates specify lightweight seismic-compliant facades for high-rise density upgrades.
- Tiles:Smaller modular units enable complex surface articulation through varied joint patterns. German and UK specification favors tiles for heritage retrofit projects requiring CE-marked fire reaction compliance under CPR Article 11.
- Blocks:Solid precast units suit load-bearing hybrid applications with exposed aggregate finishes.
- Sheets:Thin-section flat stock serves interior feature walls and secondary envelope layers.
Volume sits with Panels; growth tilts toward Tiles.
Application:
Margin structure varies by project scale and certification burden.
- Commercial:High-rise towers and office complexes specify GRC for curtain wall systems where weight reduction translates to structural steel savings. US and UK design-build contractors embed preferred suppliers into guaranteed maximum price contracts, compressing competitive bidding windows.
- Residential:Mid-rise apartment and single-family applications favor standardized panel profiles. China's MIIT directives prioritize GRC for urban density upgrades, accelerating specification in Beijing and Shanghai residential towers.
- Industrial:Warehousing and logistics facilities specify utilitarian finishes with minimal custom mold investment.
- Institutional:Schools and hospitals face elevated warranty premiums in North America, limiting penetration despite accelerated specification rates for envelope upgrades.
Commercial commands absolute volume; institutional climbs fastest on safety code alignment.
Installation Type:
Customer type determines whether procurement emphasizes material supply or integrated service delivery.
- New Construction:Greenfield projects allow optimized GRC specification from structural design phase. General contractors facing skilled labor shortages increasingly outsource complete envelope installation to specialized fabricators.
- Renovation:Existing building upgrades require structural assessment and substrate preparation. Nordic public procurement rules embed REACH compliance as mandatory award criterion, favoring reformulated coating systems.
- Retrofit:Facade replacement on occupied buildings demands phased installation minimizing disruption. Seismic retrofit mandates in China's tier-one cities drive specification for lightweight cladding meeting updated safety codes.
- Prefabricated:Factory-integrated panel and insulation systems reduce site labor exposure. UK and German adoption accelerates as BIM workflows converge with CNC mold fabrication.
New construction holds dominant share; prefabricated gains most quickly on labor scarcity.
End User:
Supply concentration shapes which stakeholders control specification pathways.
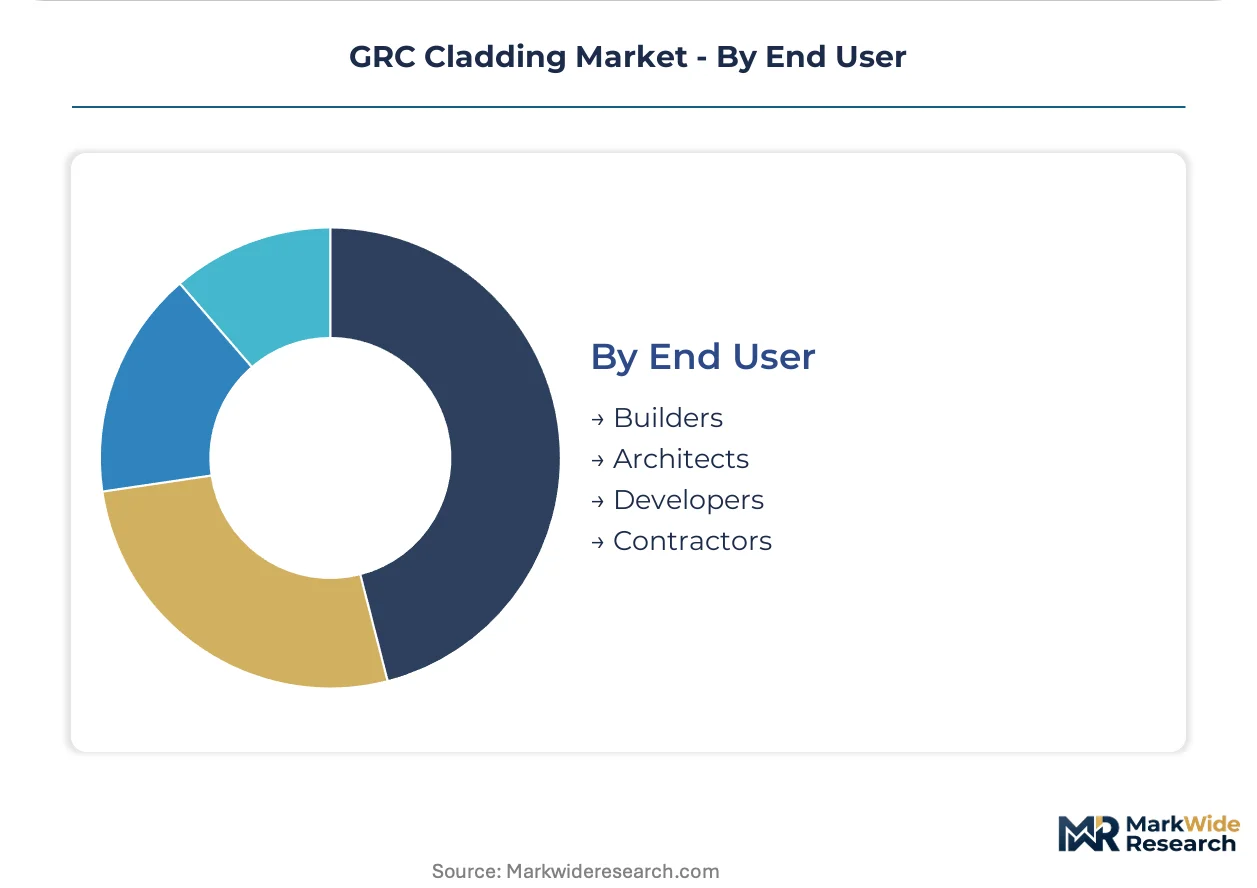
- Builders:Volume-focused procurement prioritizes panel standardization and logistics efficiency. Turner, Skanska, and Bouygues embed preferred GRC suppliers into early-stage envelope packages.
- Architects:Design-led specification demands custom mold engineering and complex geometry capability. Heritage projects in Belgium and Netherlands require REACH-compliant surface treatments.
- Developers:Return-driven decision-making weighs embodied carbon disclosure against first cost. EU Green Deal and emerging CSRD requirements accelerate substitution of traditional precast with lower-carbon GRC alternatives.
- Contractors:Risk-bearing entities seek performance warranties and installation support. North American insurers impose higher premiums on thin-section GRC versus traditional precast, influencing contractor recommendations.
Builders generate largest order flow; developers shift fastest on carbon accounting pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors GRC cladding specification density through municipal redevelopment mandates targeting lightweight seismic-compliant facades in high-rise density upgrades.
China
MIIT building material directives prioritize GRC for urban redevelopment in Beijing, Shenzhen, and Guangzhou tier-one markets. GB standards compliance shapes domestic certification thresholds for facade retrofit projects. Yangtze River Delta fabricators concentrate mold engineering capacity for complex architectural geometries.
United States
Design-build contractors embed preferred GRC suppliers into guaranteed maximum price contracts for commercial tower developments. ASTM C1227 and local building code adoptions fill the federal standards gap absent cladding-specific regulation. Western regional precast manufacturing clusters serve high-rise construction in California and Pacific Northwest markets.
Germany
CE marking under CPR Article 11 governs market access for GRC facade systems across EU member states. REACH substance restrictions on chromium VI compounds force coating reformulation by the 2023 sunset deadline. Industrial fabricators in North Rhine-Westphalia adopt hybrid spray-premix manufacturing for mid-volume custom panel orders.
United Kingdom
Heritage retrofit projects in London and Birmingham specify CE-marked tiles requiring fire reaction compliance under CPR Article 11. BIM workflows converge with CNC mold fabrication to compress design-to-production cycles. Public procurement rules embed REACH compliance as mandatory award criterion in Nordic-influenced specification.
India
BIS certification alignment with European CE marking standards opens specification pathways for Mumbai and Bangalore high-rise developments. Commercial construction acceleration drives demand for lightweight cladding systems. Gujarat and Maharashtra industrial corridors concentrate emerging fabrication capacity for domestic project supply.
GRC Cladding Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered supply positions. The vendor base separates between vertically integrated precast manufacturers and specialized mold engineering boutiques. Three archetypes dominate: western regional fabricators with captive production networks, European technical advisory specialists, and Asian volume producers serving municipal redevelopment pipelines. Competitive moves concentrate on prefabricated installation service expansion and digital twin integration with BIM workflows.
Among the named participants, Clark Pacific exemplifies the western regional integrated manufacturer archetype, while Loveld occupies the European technical advisory specialist position. Fibrobeton represents specialized mold engineering capability concentrated in continental European markets. UltraTech Cement Ltd anchors the volume producer segment with building materials platform leverage. These entities illustrate how geographic origin and organizational structure shape competitive positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| ASAHI BUILDING-WALL CO LTD |
| Loveld |
| UltraTech Cement Ltd |
| GB Architectural Cladding Products Ltd |
| Fibrobeton |
| Clark Pacific |
| Willis Construction Co Inc |
| Ibstock Telling |
| BB Fiberbeton |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators in Belgium and the Netherlands anchor European GRC supply, translating generational mold-engineering expertise into pricing discipline that resists commoditization despite cement cost volatility. Their captive control over pattern-making capacity insulates premium tiers from spot-market pressure while forcing volume buyers toward standardized panel profiles.
Pricing Analysis
Value-based pricing anchored to structural-load reduction outcomes dominates commercial high-rise specification, where GRC's 80% weight advantage against traditional precast translates to measurable steel savings. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked fire-reaction-compliant systems from utilitarian residential grades. Pricing pressure stems from EU ETS carbon pricing on clinker inputs, compressing margins for non-integrated producers. Institutional buyers in North America exhibit highest price sensitivity due to warranty premium differentials, while design-build contractors in US commercial towers show lowest sensitivity when GRC is embedded early in guaranteed maximum price contracts.
Supply Chain Analysis
Skilled pattern-maker availability constrains output in North Rhine-Westphalia industrial clusters and Yangtze River Delta manufacturing zones, capping mold-engineering throughput for complex geometries. Supply concentrates in China, Germany, and the United Kingdom, with emerging capacity in Gujarat and Maharashtra industrial corridors. Raw material security hinges on alkali-resistant glass fiber from three specialized global manufacturers, white cement from EU ETS-exposed kilns, and REACH-compliant titanium dioxide coatings. Single-source vulnerability in AR-glass fiber creates supply chain risk. Distribution runs through design-build contractors embedding preferred suppliers into early-stage envelope packages, displacing traditional architect-led specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GRC cladding operates as a supply-constrained market where specialized mold-engineering bottlenecks prop pricing power for incumbents with captive pattern-making capacity. Capacity scarcity in skilled pattern-makers across Western European and Chinese industrial clusters sustains margin premiums for complex geometries.
For Market Incumbents: Lock in long-term AR-glass fiber supply agreements with the three specialized global manufacturers to neutralize raw material security risk. Expand prefabricated installation service capabilities to capture recurring revenue streams as general contractors outsource complete envelope installation. Deepen backward integration into CNC mold fabrication to compress design-to-production cycles and defend against digital-native entrants converging BIM workflows with automated manufacturing.
For New Entrants and Emerging Players: Digital-channel routes through BIM-integrated specification platforms offer low-friction entry into architect-led procurement for heritage retrofit projects. Target India's Mumbai and Bangalore high-rise developments where BIS certification alignment with European standards opens specification pathways with lower incumbent density. Penetrate through prefabricated installation services for renovation and retrofit segments where labor scarcity drives contractor outsourcing behavior.
For Investors and Strategic Acquirers: CE marking approval under CPR Article 11(1) for new panel formulations is the leading indicator that specialized mold-engineering boutiques have cleared 18-24 month certification barriers and scaled beyond regional project dependency. Long-term viability favors vertically integrated precast manufacturers with western regional production networks and technical advisory specialists with recurring maintenance contract books. Watch for MIIT directive acceleration in China's tier-two cities as signal of municipal redevelopment pipeline expansion beyond tier-one saturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Installation Service Expansion | Captures recurring revenue as Turner, Skanska, and Bouygues outsource envelope installation to reduce site labor exposure. |
| Backward Integration into CNC Mold Fabrication | Compresses design-to-production cycles for complex geometries as BIM workflows converge with automated manufacturing. |
| REACH-Compliant Coating Reformulation | Maintains EU market access after ECHA's hexavalent chromium sunset deadline forced titanium dioxide adoption. |
| AR-Glass Fiber Supply Agreement | Neutralizes raw material security risk from three-manufacturer concentration in global alkali-resistant glass fiber output. |
| Digital Twin Integration with BIM | Enables smaller batch production without penalty by linking architectural specifications directly to robotic spray deposition systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this GRC cladding analysis. Primary interviews with facade engineering consultants, design-build procurement directors, precast manufacturing plant managers, and architectural specification officers combined with secondary validation from ECHA substance restriction databases, CPR Article 11 certification registries, and MIIT building material directive publications. Bottom-up project pipeline tracking across tier-one Chinese cities and top-down construction spend analysis triangulated market sizing.
Granularity-level modeling addressed product type, application, installation context, and end-user archetype across the analysis window. Segmentation dimensions included panel versus tile versus prefabricated system formats, commercial versus residential versus institutional end-use, new construction versus renovation versus retrofit installation type, and builder versus architect versus developer versus contractor procurement control. CAGRs derived from weighted scenario analysis of urban redevelopment mandate acceleration, embodied carbon disclosure adoption curves, and AR-glass fiber supply expansion timelines. Industry-specific inputs incorporated EU ETS carbon price pass-through elasticity and CE marking testing duration distributions.
The model holds under stable regulatory compliance timelines and AR-glass fiber supply continuity; deviation in REACH substance restriction acceleration or MIIT directive enforcement intensity would shift volume projections. Forecasts reflect assumptions on municipal redevelopment pipeline conversion rates and design-build procurement consolidation trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Blind Bolts Market
Building Materials
Construction Coatings Market
Building Materials
Bolt (Fastener) Market
Building Materials
Pozzolana Cement Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Europe Concealed Cistern Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Building and Construction Sheets Market
Building Materials
North America Concrete Admixtures Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
Timber Frames Market
Building Materials
Lightweight Cellular Concrete Market
Building Materials
Fireproof Cladding Market
Building Materials
Dry Mix Mortar Market
Building Materials
LAMEA Engineered Stone Market