
 Air Particle Monitor System Market | 2026-2036
Air Particle Monitor System Market Size, Share, and Industry Trends Forecast 2026-2036
Air Particle Monitor System Market Analysis
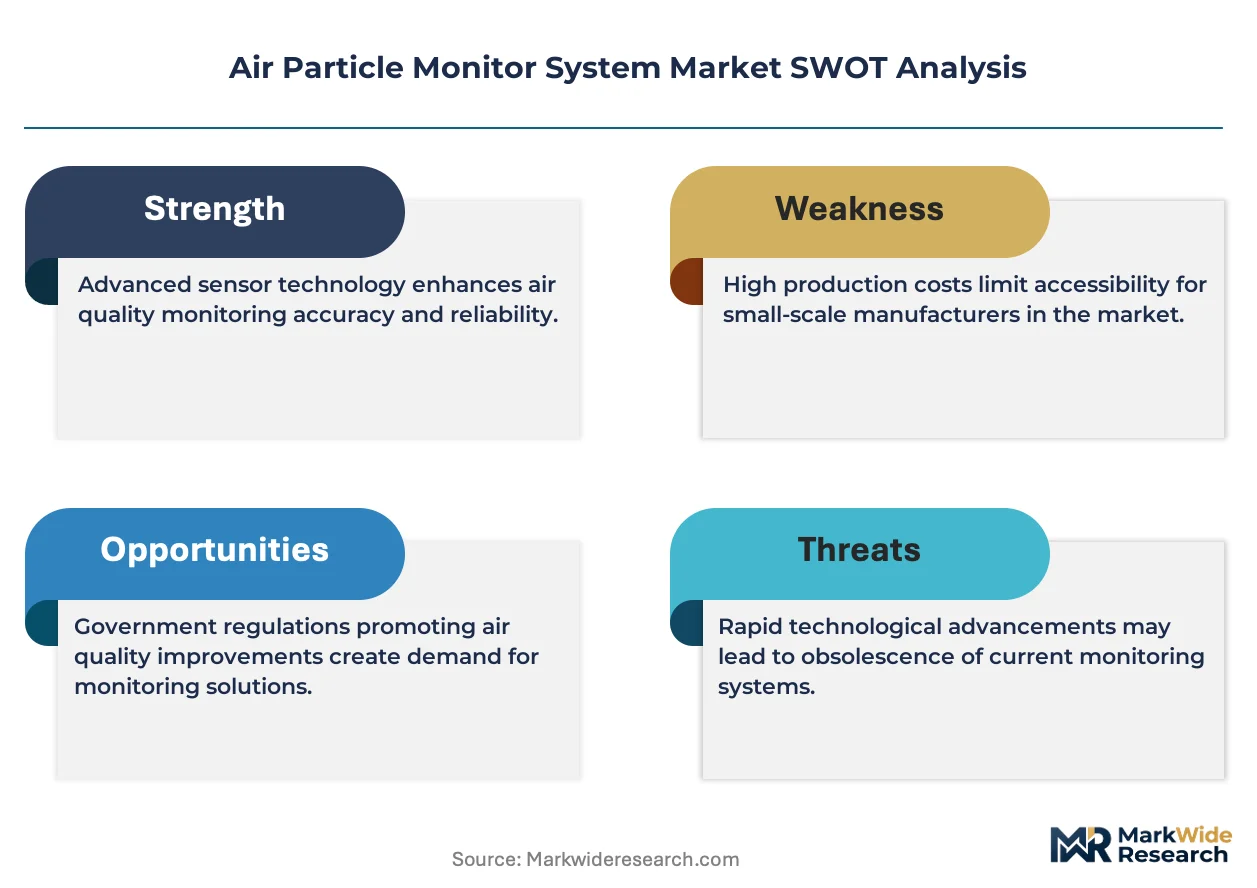
Aftermarket calibration and sensor refurbishment revenue is rewriting profit architecture for incumbent suppliers. Thermo Fisher Scientific leverages its service infrastructure across pharmaceutical cleanroom accounts to sustain recurring revenue streams. Honeywell International anchors its position through backward integration into optical sensor manufacturing, controlling component quality and lead times. Danaher competes on diagnostic precision, extending its life-sciences instrumentation expertise into particle contamination protocols for biologics production.
An air particle monitor system detects and quantifies airborne particulate matter across size fractions from ultrafine particles below 0.1 micrometers to coarse dust above 10 micrometers, typically employing laser scattering or optical interference methods with real-time digital output for regulatory compliance and process control. Continuous monitoring systems dominate institutional procurement where regulatory audit trails require uninterrupted data logging, while portable sensors represent the fastest-expanding category as facility managers deploy flexible spot-checking protocols across distributed manufacturing footprints. Laser scattering technology leads on detection sensitivity for cleanroom and semiconductor applications, whereas electrochemical sensors occupy the value tier for residential and light commercial indoor air quality monitoring.
The EPA enforces National Ambient Air Quality Standards under the Clean Air Act, compelling industrial facilities to install certified continuous monitoring networks with documented calibration protocols. EMA cleanroom guidelines and EU GMP Annex 1 revisions mandate particle count thresholds for sterile pharmaceutical manufacturing, directly specifying monitor sensitivity requirements. OSHA permissible exposure limits for respirable crystalline silica further expand workplace safety-driven installations across construction and mining operations. Stakeholders must weigh capital intensity against regulatory exposure when selecting between owned monitoring infrastructure and third-party compliance-as-a-service models.
Market Dynamics
The air particle monitor system market pivots on regulatory density—tighter EPA National Ambient Air Quality Standards and EU Green Deal industrial emissions targets are mandating denser sensor networks across manufacturing and urban monitoring infrastructure, compressing procurement cycles and elevating certification requirements.
Growth Catalysts
- EPA Clean Air Act enforcement:Industrial facilities must install certified continuous monitoring networks with documented calibration protocols, expanding installed base requirements.
- Semiconductor cleanroom expansion:Taiwan and South Korea fabrication facilities drive unit demand for sub-micron detection capabilities in advanced node production.
- EU GMP Annex 1 revisions:Sterile pharmaceutical manufacturing mandates now specify particle count thresholds and monitor sensitivity requirements, triggering replacement cycles.
Market Restraints
- Optical component supply concentration:Laser diode and photodetector manufacturing concentrates in East Asian suppliers, creating lead time vulnerability for Western monitor assemblers.
- Calibration gas cost volatility:Certified reference materials for span verification face price instability due to noble gas supply constraints.
- Electrochemical sensor substitution:Lower-cost electrochemical alternatives capture residential and light commercial indoor air quality segments, pressuring optical system margins.
Strategic Opportunities
- India urban air quality programs:National Clean Air Programme concentrates procurement for continuous monitoring systems across non-attainment cities with federal funding support.
- Biologics manufacturing expansion:Cell and gene therapy production facilities require contamination control protocols that extend diagnostic precision requirements into new therapeutic categories.
- Cloud-integrated sensor networks:Real-time data aggregation platforms enable compliance-as-a-service models, shifting revenue from hardware to recurring subscription streams.
Industry Challenges
- Metrology technician scarcity:Certified calibration specialists with ISO 17025 competency are concentrated at incumbent service providers, constraining aftermarket expansion.
- Legacy system integration friction:BACnet and Modbus protocol variants across installed building automation systems complicate seamless monitor deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Particle Monitor System Market |
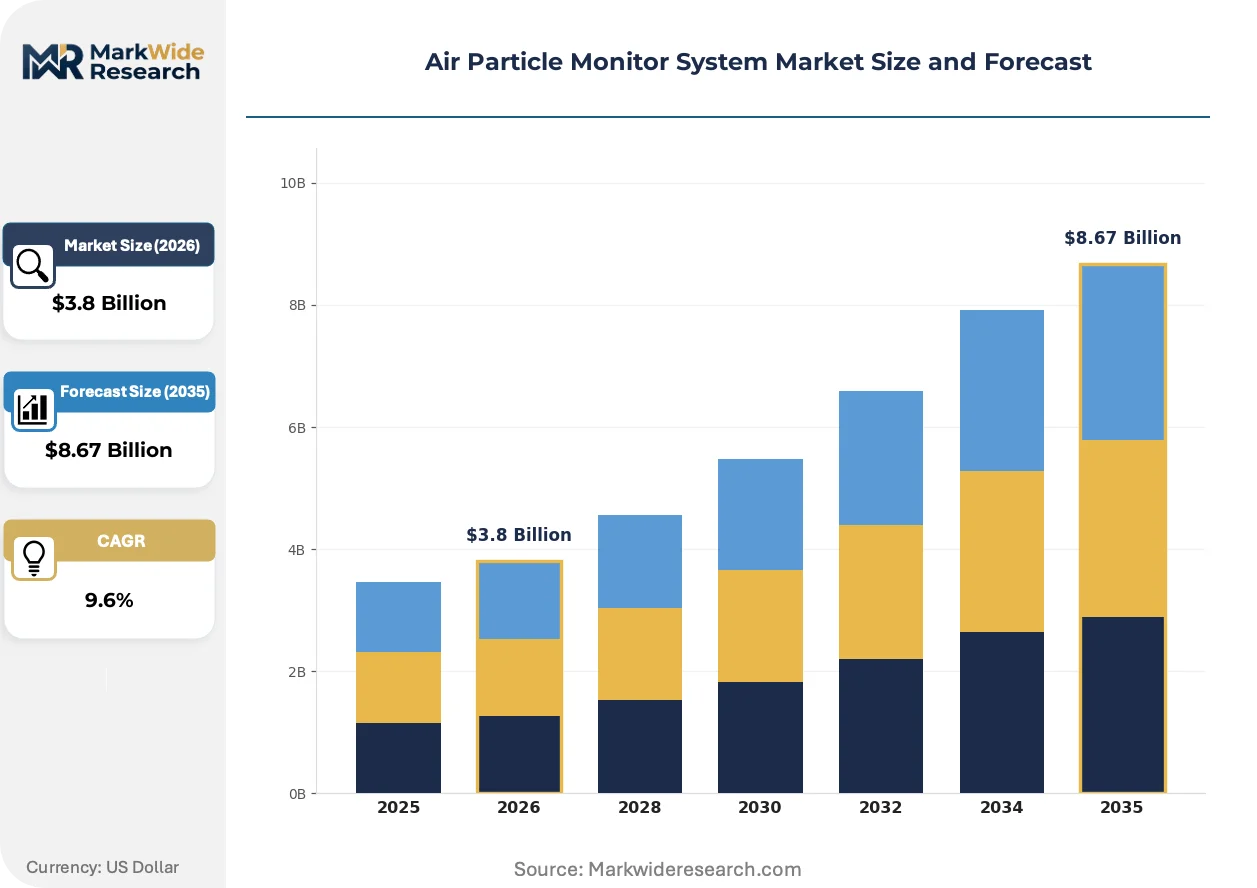
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Monitors, Continuous Monitoring Systems, Portable Sensors, Fixed Systems Technology: Laser Scattering, Optical Sensors, Infrared Sensors, Electrochemical Sensors End User: Industrial Facilities, Research Laboratories, Hospitals, Residential Areas Application: Indoor Air Quality, Environmental Monitoring, Workplace Safety, HVAC Monitoring |
| Companies Covered | Thermo Fisher Scientific Inc., Honeywell International Inc., Siemens AG, Aeroqual Ltd., HORIBA Ltd., Teledyne Technologies Inc., Emerson Electric Co., Danaher Corp., PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Particle Monitor System Market Emerging Trajectories
Sensor miniaturization and edge computing architectures are compressing form factors while expanding deployment flexibility, enabling distributed monitoring footprints that were previously economically unviable for mid-scale facilities.
Laser scattering instrumentation with embedded AI-driven spectral analysis is digitizing particle classification—distinguishing biological from non-biological aerosols in real time without laboratory confirmation. Pharmaceutical sterile filling lines and semiconductor lithography bays are adopting these systems at accelerated procurement cycles. This capability is digitizing compliance workflows, collapsing the delay between detection event and corrective action.
The EU Green Deal's Industrial Emissions Directive revision tightens particulate matter thresholds for energy-intensive installations, compelling cement and steel producers to upgrade from periodic stack testing to continuous emission monitoring systems. German and Polish heavy industry clusters face the most acute compliance deadlines. Process control engineers are responding by specifying monitors with redundant sensor arrays to eliminate single-point failure risks during audit periods.
Facility managers are unbundling hardware procurement from calibration service contracts, negotiating spot-rate maintenance agreements rather than multi-year bundled packages. This disintermediation pressures incumbent suppliers with captive service infrastructure. The shift is most visible across North American and Western European pharmaceutical manufacturing, where procurement teams prioritize operational expenditure flexibility over capital commitment.
Air Particle Monitor System Market Segmentation
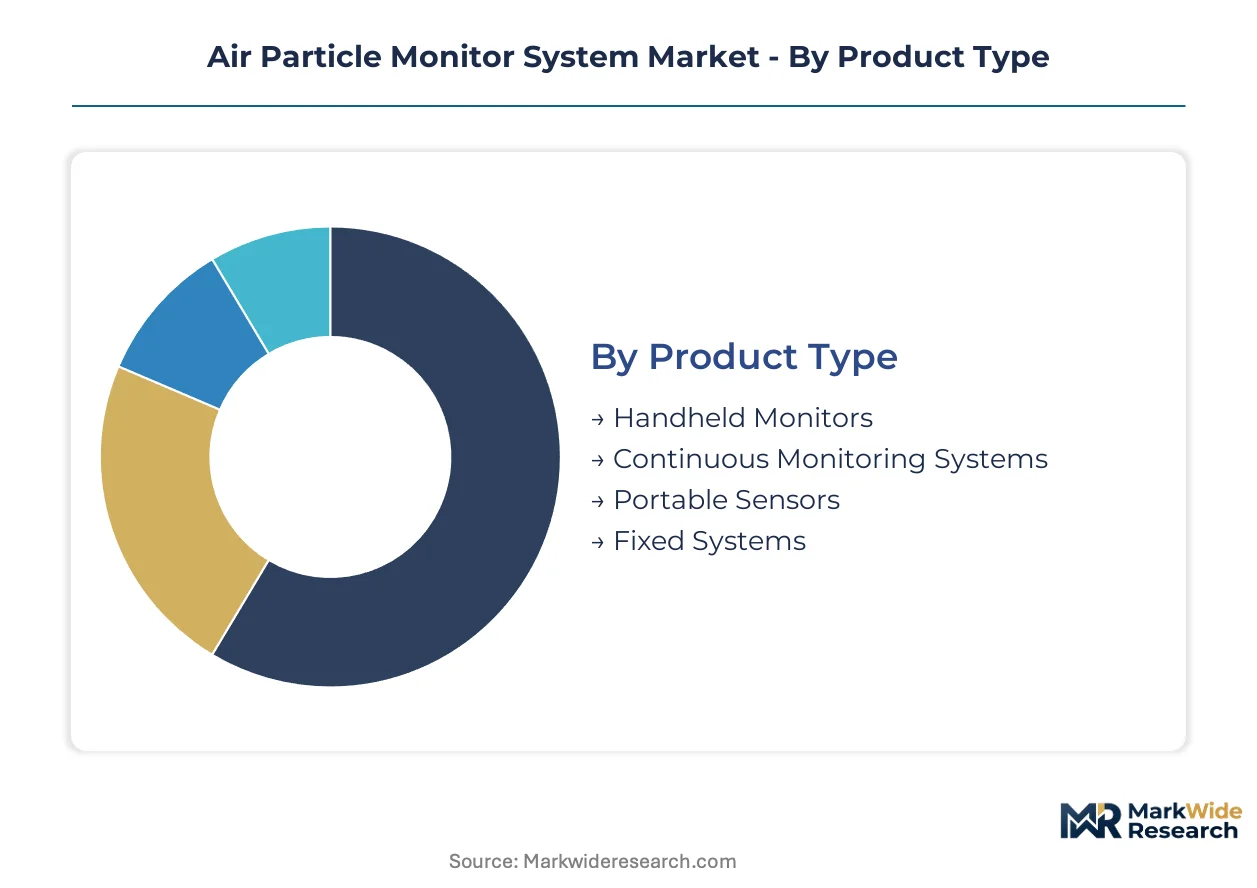
Air particle monitor systems fragment across four structural dimensions that determine procurement economics and replacement cadence. Product type and technology selection drive capital intensity, while end-user verticals and applications dictate certification requirements and data integration protocols.
Product Type:
Replacement cycles vary dramatically across product types, with portable units turning over fastest due to field wear and battery degradation, while fixed installations persist for decade-long depreciation schedules.
- Handheld Monitors:Battery-powered units with integrated displays enable spot-checking protocols across manufacturing floors and construction sites. Demand concentrates in OSHA silica compliance programs across US mining and demolition contractors, where supervisors require immediate verification before shift changes.
- Continuous Monitoring Systems:Rack-mounted or wall-installed units with uninterrupted data logging and regulatory audit trails serve EPA-mandated compliance networks. Taiwan semiconductor cleanrooms and South Korean display panel facilities drive procurement for sub-micron detection with redundant sensor arrays.
- Portable Sensors:Compact wireless units with cloud connectivity support flexible deployment across distributed facility footprints. Facility managers in German pharmaceutical manufacturing favor spot-rate procurement over bundled service contracts.
- Fixed Systems:Permanent installations integrated into building automation infrastructure provide baseline environmental surveillance. Indian urban air quality stations under the National Clean Air Programme deploy these across non-attainment cities.
Continuous monitoring systems dominate installed base. Portable sensors are where expansion concentrates.
Technology:
Technology selection stratifies by detection sensitivity requirements and cost tier, with optical methods commanding premium positioning for cleanroom applications and electrochemical alternatives capturing price-sensitive indoor air quality segments.
- Laser Scattering:Instruments detect particles below 0.1 micrometers through light diffraction analysis, enabling real-time classification of ultrafine aerosols. EU GMP Annex 1 sterile pharmaceutical mandates specify this technology for aseptic filling line validation.
- Optical Sensors:Photodetector arrays measure particle-induced light interference across calibrated size fractions. Honeywell's backward integration into optical component manufacturing secures supply chain control for Western assemblers facing East Asian laser diode concentration.
- Infrared Sensors:Thermal emission detection suits coarse particulate monitoring in industrial stack applications. Cement and steel producers in Poland and Germany deploy these for EU Industrial Emissions Directive compliance.
- Electrochemical Sensors:Lower-cost alternatives measure particulate-induced conductivity changes without optical components. Residential and light commercial indoor air quality markets in China and India favor this value-tier approach.
Laser scattering commands premium positioning. Electrochemical alternatives are climbing the fastest in unit volume.
End User:
End-user verticals diverge sharply in procurement authority, with industrial facilities centralizing capital decisions through engineering departments while hospitals delegate to infection control committees with distinct vendor relationships.
- Industrial Facilities:Manufacturing plants and energy installations deploy certified networks for EPA Clean Air Act and EU Green Deal compliance. German heavy industry clusters face acute deadlines for continuous emission monitoring upgrades.
- Research Laboratories:Academic and government labs require traceable calibration chains for publication-grade data integrity. ISO 17025-accredited service providers concentrate metrology technician capacity for this demanding segment.
- Hospitals:Infection control departments monitor surgical suites and isolation rooms for airborne pathogen containment. US Joint Commission accreditation drives replacement cycles in acute care settings.
- Residential Areas:Smart home integration and consumer wellness trends expand demand for connected indoor air quality monitors. China's urban middle class represents concentrated adoption for PM2.5 visibility applications.
Industrial facilities anchor revenue concentration. Residential areas are gaining share fastest.
Application:
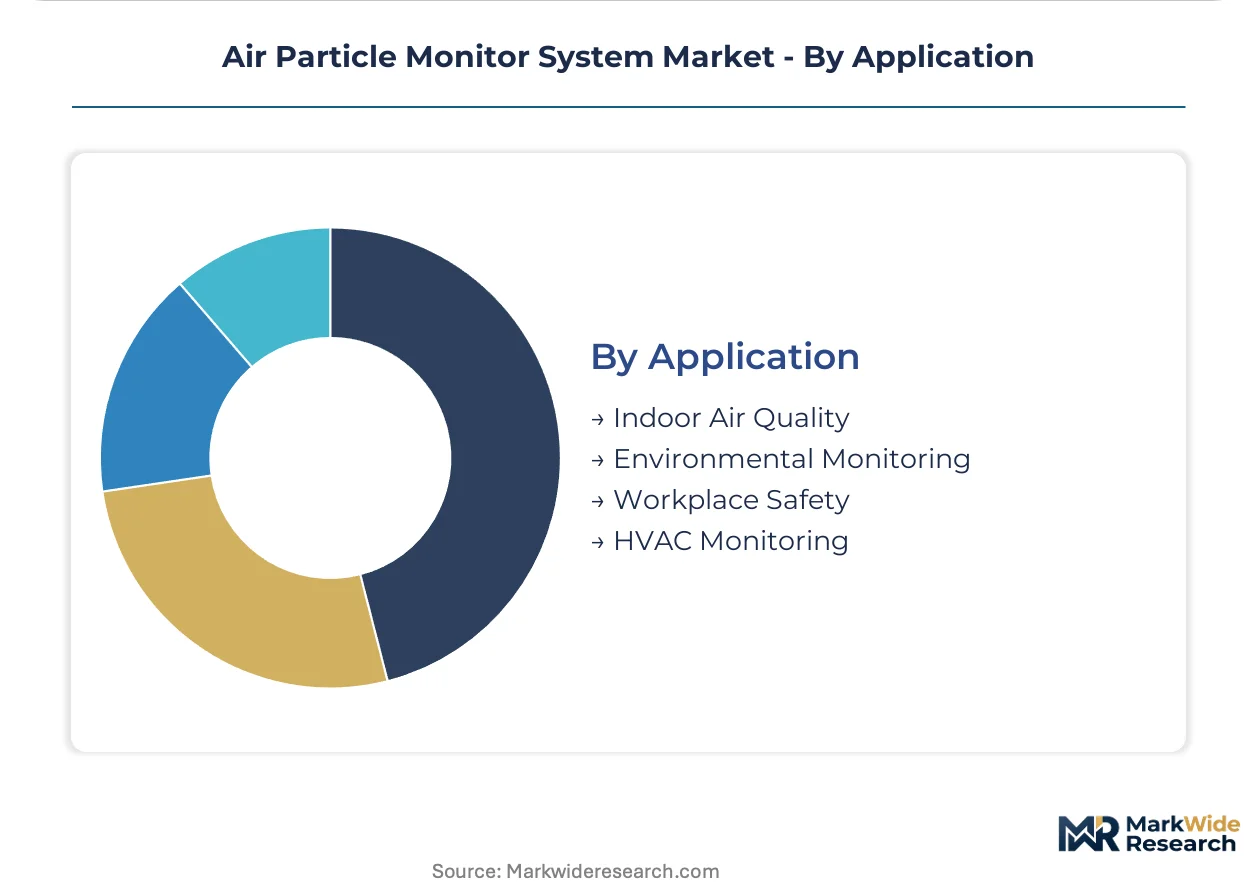
Application focus determines data output specifications, with environmental monitoring requiring regulatory-grade documentation while HVAC integration prioritizes BACnet protocol compatibility over absolute precision.
- Indoor Air Quality:Commercial buildings and educational institutions monitor ventilation effectiveness and occupant exposure. India's green building certification programs drive specification for CO2 and particulate combined sensing.
- Environmental Monitoring:Ambient air quality stations track regulatory compliance against national standards. China's Ministry of Ecology and Environment operates the densest government-funded network for urban PM2.5 surveillance.
- Workplace Safety:OSHA permissible exposure limits for respirable crystalline silica mandate monitoring across construction, mining, and abrasive blasting operations. US Department of Labor enforcement expansion accelerates procurement.
- HVAC Monitoring:Building automation integration enables demand-controlled ventilation based on real-time particle loading. Legacy Modbus protocol variants across installed systems complicate seamless deployment for facility managers.
Environmental monitoring dominates public-sector procurement. Indoor air quality is where private investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Industrial facilities in Germany and South Korea prioritize sub-micron detection for semiconductor fabrication, while China and India concentrate procurement on dense urban monitoring networks for regulatory visibility.
United States
EPA Clean Air Act enforcement drives continuous monitoring installations across power generation and chemical processing. OSHA silica permissible exposure limits mandate workplace safety deployments in construction and mining clusters. Texas Gulf Coast petrochemical corridors and Appalachian mining operations represent concentrated demand for certified calibration protocols.
Germany
EU Green Deal Industrial Emissions Directive revisions compel cement and steel producers to upgrade from periodic testing to continuous emission monitoring. The country's national environmental regulator enforces tightening particulate thresholds. Heavy industry clusters in North Rhine-Westphalia and the Saarland face acute compliance deadlines for redundant sensor arrays.
China
Urban air quality programs under the Ministry of Ecology and Environment expand government-funded monitoring networks for PM2.5 surveillance. The country's national standards body certifies equipment for environmental stations. Yangtze River Delta manufacturing hubs and Beijing-Tianjin-Hebei urban corridors deploy the densest concentrations of continuous monitoring infrastructure.
South Korea
Semiconductor cleanroom expansion at advanced fabrication nodes drives sub-micron detection requirements. The national food and drug safety regulator aligns sterile pharmaceutical mandates with EU GMP Annex 1 revisions. Seoul Capital Area and Busan-Ulsan industrial complexes anchor procurement for laser scattering instrumentation with redundant sensor configurations.
India
National Clean Air Programme concentrates federal funding for continuous monitoring systems across non-attainment cities. The national standards body certifies equipment for urban air quality stations. Maharashtra and Gujarat industrial corridors deploy fixed installations, while Delhi-NCR leads procurement for combined particulate and gaseous pollutant sensing.
Air Particle Monitor System Market Vendor Landscape
Capability concentration sits with diagnostic-precision specialists; scale advantage sits with diversified industrial conglomerates. The vendor base organizes around three strategic archetypes: life-sciences instrumentation houses extending contamination control expertise, industrial automation suppliers leveraging building integration capabilities, and environmental monitoring pure-plays. Dominant competitive moves include backward integration into optical component manufacturing and unbundling of hardware procurement from long-term service contracts.
Within the precision-instrumentation tier, Thermo Fisher Scientific Inc. and Danaher Corp. exemplify archetypes built on diagnostic exactitude and recurring calibration revenue streams. Honeywell International Inc. occupies a position anchored in industrial automation integration and captive supply chain control. Siemens AG represents the European industrial conglomerate model with building technology infrastructure.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Honeywell International Inc. |
| Siemens AG |
| Aeroqual Ltd. |
| HORIBA Ltd. |
| Teledyne Technologies Inc. |
| Emerson Electric Co. |
| Danaher Corp. |
| PerkinElmer Inc. |
| Others |
Supply Flow & Price Mechanics
Shanghai-Ningbo port freight corridors transmit cost volatility directly into optical component landed costs, amplifying price differentiation between laser scattering systems and electrochemical alternatives while compressing margins for Western assemblers lacking captive East Asian manufacturing.
Pricing Analysis
Long-term offtake contracts dominate semiconductor cleanroom procurement in Taiwan and South Korea, locking in volume commitments for sub-micron detection systems. Price differentiation rests on ISO 17025 calibration certification tiers and after-sales service bundling. Cost compression in the residential indoor air quality tier is intensifying because electrochemical substitutes erode optical system margins. Pharmaceutical manufacturers in Germany exhibit lowest price sensitivity due to EU GMP Annex 1 compliance mandates, while Indian municipal buyers under National Clean Air Programme funding face acute budget constraints.
Supply Chain Analysis
Contract manufacturing for laser diodes and photodetector arrays concentrates in Taiwan, South Korea, and Japan, with Foxconn and Pegatron holding substantial EMS capacity for monitor assembly. Raw material dependencies include rare-earth doped optical glass, noble gas calibration standards, and precision-machined sensor housings. Single-source vulnerability in laser diode fabrication creates lead time exposure for Western OEMs. Distribution runs through authorized service networks for continuous monitoring systems, while portable sensors move through industrial distributors and direct e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among German pharmaceutical manufacturing groups and Indian municipal environmental departments is shifting bargaining power toward buyers, forcing vendors to unbundle hardware from service contracts.
For Market Incumbents: Pre-empt electrochemical substitution in light commercial segments by embedding edge AI classification as a premium feature. Secure backward integration into optical component manufacturing to eliminate Taiwan laser diode supply exposure. Capture metrology technician certification capacity before ISO 17025 competency scarcity worsens. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with Indonesia and Vietnam green building codes driving specification for combined particulate and CO2 sensing. Portable wireless sensors for construction silica compliance in US mining regions offer second-mover advantage. Channel through industrial safety distributors rather than competing directly for cleanroom certification. For Investors and Strategic Acquirers: Cloud-native sensor network platforms with recurring SaaS revenue models present the most attractive acquisition archetype for portfolio exposure to compliance-as-a-service trends. Long-term viability hinges on regulatory density expansion rather than hardware replacement cycles alone. Watch EPA enforcement budget allocations and EU Industrial Emissions Directive implementation deadlines as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | Honeywell's captive laser diode production insulates margin from Taiwan supply concentration. |
| Cloud-Integrated Sensor Network Launch | Real-time data aggregation enables subscription revenue from pharmaceutical cleanroom accounts. |
| ISO 17025 Calibration Service Expansion | Certified metrology capacity captures aftermarket profit from EPA-mandated audit trails. |
| AI-Driven Particle Classification Development | Spectral analysis distinguishes biological aerosols for EU GMP Annex 1 sterile manufacturing. |
| Geographic Manufacturing Footprint Diversification | Polish and Czech assembly hubs reduce German heavy industry lead time exposure. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with cleanroom engineering directors, environmental compliance officers, metrology service technicians, and pharmaceutical manufacturing procurement leads; and secondary validation against EPA enforcement databases, EU ETS emissions registries, semiconductor fab capital expenditure disclosures, and Indian Central Pollution Control Board procurement records. Bottom-up unit demand modeling triangulated against top-down market sizing across product type, technology, and end-user verticals.
Forecast inputs considered semiconductor fabrication node transitions, EPA National Ambient Air Quality Standards implementation timelines, and EU Green Deal industrial emissions thresholds across the projection horizon. Segmentation dimensions modeled include detection sensitivity tier, installation permanence, regulatory certification grade, and regional compliance framework. CAGRs derived from regression analysis of historical procurement cycles against regulatory mandate effective dates.
Practitioners should monitor EPA budget appropriations, EU Industrial Emissions Directive enforcement intensity, and noble gas calibration standard supply constraints for early signals of forecast revision. Quarterly review of cleanroom capital expenditure announcements and municipal air quality station procurement awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
China Sensors Market
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
Lidar Ceilometer Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
Middle East and Africa Wireless Sensors Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Reservoir Monitoring System Market
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Digital Barometer Market
Sensors and Controls
Aspiration Control Systems Market
Sensors and Controls
Europe Emission Monitoring System Market