

4K Drawing Tablet with Screen Market Size, Share, and Industry Trends Forecast 2026-2036
4K Drawing Tablet with Screen Market Insights
Freelance artists is collapsing as the dominant buyer archetype as animation studios and architectural firms consolidate purchasing volume. Wacom leverages its heritage in pressure-sensitive electromagnetic resonance technology to sustain premium positioning among professional illustrators. Huion competes aggressively on manufacturing scale, while XPPen specializes in mid-tier pen displays for emerging educational markets.
A 4K drawing tablet with screen integrates ultra-high-definition liquid crystal or OLED display panels with active digitizer layers capable of resolving thousands of pressure levels and tilt angles for stylus input. These devices serve as direct-input workstations where the stylus contacts the same surface displaying the image, eliminating hand-eye disconnection inherent in screenless graphics tablets. Pen display units lead product type segmentation due to their entrenched role in animation pipelines, while standalone drawing tablets represent the fastest-growing category as ARM-based mobile processors enable untethered operation. Electromagnetic resonance technology anchors the premium tier for its precision, whereas capacitive multi-touch dominates volume manufacturing for educational content creation deployments.
FCC certification governs electromagnetic emissions for devices sold in the United States, while CE marking under EU directives mandates electrical safety and electromagnetic compatibility for European market access. Japan's METI enforces energy efficiency standards that shape display panel selection and power management firmware. Stakeholders must monitor how evolving e-waste regulations under RoHS and REACH affect bonded display-digitizer manufacturing processes and component recyclability.
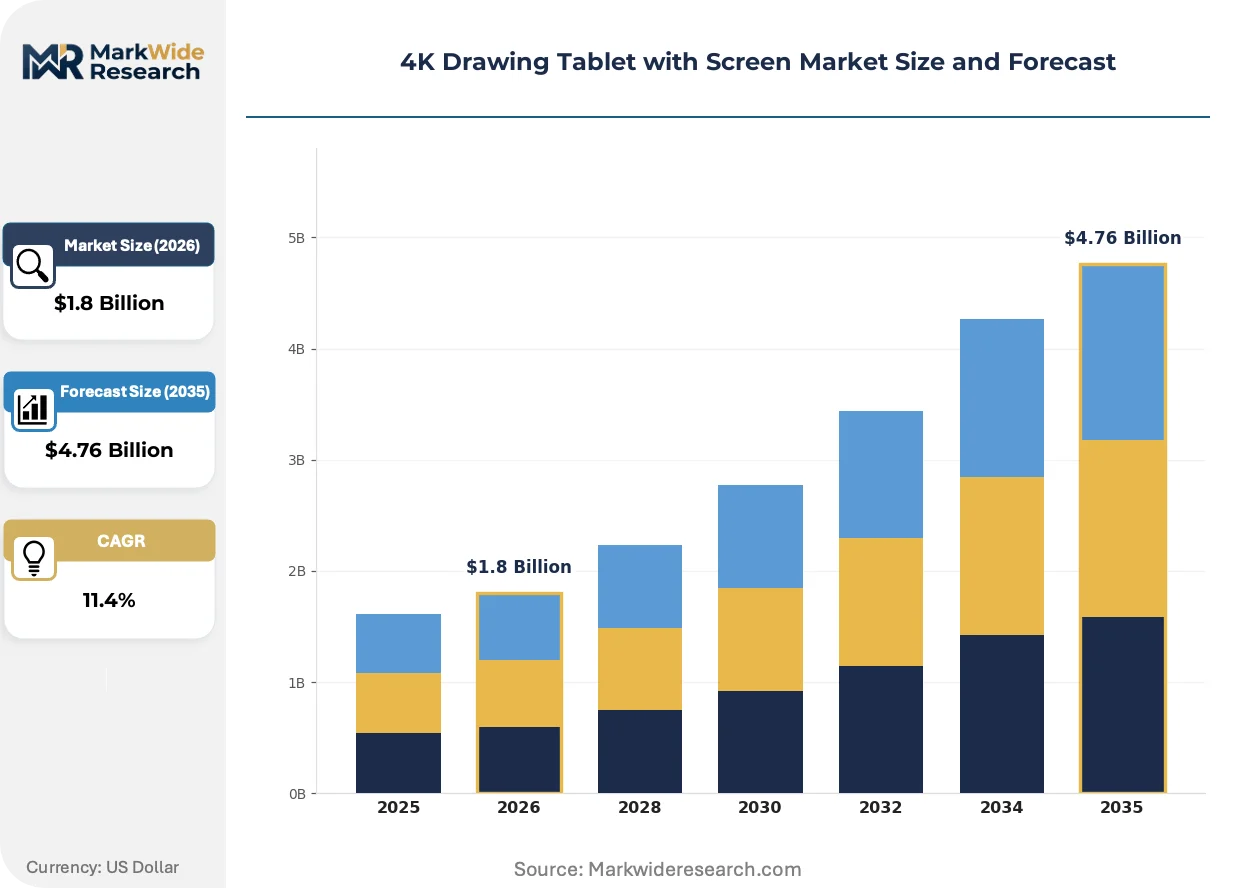
Market Dynamics
Pressure-sensitive electromagnetic resonance technology is consolidating control over premium pen display tiers while capacitive architectures retreat to educational volume segments, compressing the technology stack and reshaping procurement criteria across professional creative workflows.
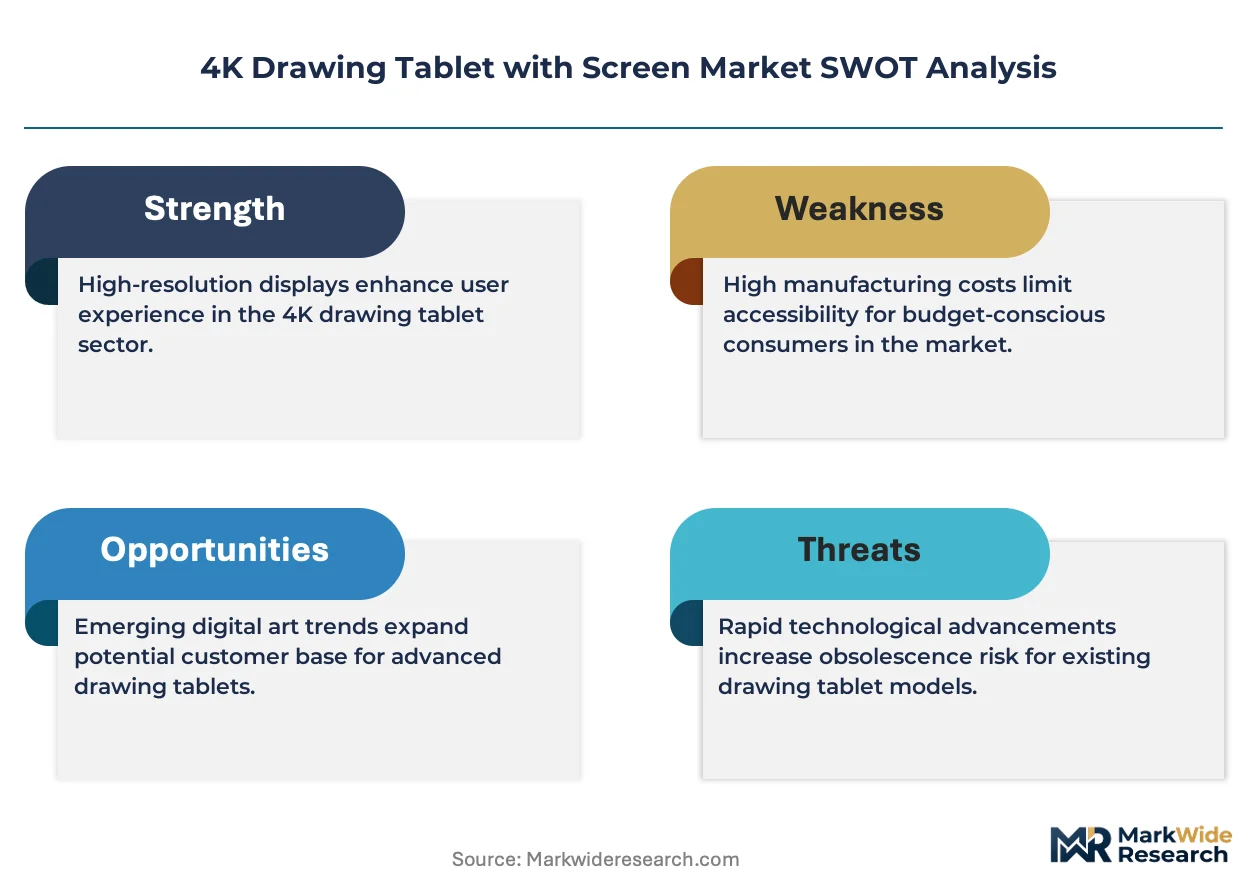
Growth Catalysts
- Remote Animation Production:Animation studios in Japan and South Korea have institutionalized distributed pipelines, mandating direct-input pen displays for storyboard artists and inkers working from satellite offices. This structural shift locks in hardware replacement cycles at enterprise scale.
- RoHS and REACH Compliance:Evolving e-waste regulations across the European Union are forcing bonded display-digitizer manufacturers to redesign assembly processes for component recyclability, accelerating R&D investment in modular construction techniques.
- Educational Content Creation:Mid-tier pen displays are penetrating K-12 and university art programs in the United States, where institutions prioritize cost-effective electromagnetic resonance alternatives to capacitive tablets for digital literacy curricula.
Market Restraints
- Display Panel Cost Volatility:OLED substrate pricing fluctuates with South Korean foundry capacity constraints, squeezing margin structures for manufacturers targeting 4K resolution at sub-premium price points.
- Japan METI Efficiency Mandates:Energy consumption standards enforced by Japan's Ministry of Economy, Trade and Industry limit brightness calibration ranges and complicate firmware development for products seeking access to professional creative clusters in Tokyo and Osaka.
- ARM Processor Substitution:Standalone drawing tablets powered by mobile ARM architectures threaten pen display attach rates among freelance illustrators who previously required tethered workstation setups.
Strategic Opportunities
- India Educational Infrastructure:National Skill Development Corporation initiatives are expanding digital art training capacity across state technical institutes, creating first-mover advantage for manufacturers offering localized electromagnetic resonance pen displays at institutional pricing tiers.
- FCC Certification Arbitrage:United States electromagnetic emissions compliance creates barrier-to-entry value for vendors who pre-certify modular digitizer layers, enabling faster time-to-market for OEM partnerships with display panel suppliers.
- Cloud-Native Workflow Convergence:Integration between pen display hardware and browser-based rendering engines is compressing local compute requirements, opening addressable market expansion among Chromebook-dependent educational buyers in North American school districts.
Industry Challenges
- Calibration Technician Scarcity:Pressure-level accuracy certification requires specialized electromagnetic resonance testing protocols that few field service networks outside Japan and South Korea can execute at scale, constraining after-market support expansion.
- Firmware Fragmentation:Proprietary stylus communication stacks from competing electromagnetic resonance vendors create integration complexity with legacy animation pipeline software used by established studios in Los Angeles and Vancouver.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4K Drawing Tablet with Screen Market Trends and Innovations
Active digitizer layers are undergoing physical compression while maintaining pressure resolution, enabling thinner form factors that challenge conventional display assembly economics and open new industrial design possibilities for mobile-first creative hardware.
Quantum-dot enhanced backlighting is miniaturizing within 4K pen display architectures, delivering wider color gamut coverage without increasing panel thickness. Animation colorists in Burbank and London post-production houses are specifying these configurations for HDR-compliant deliverables. The technology is miniaturizing the gap between professional monitor and pen display color performance, collapsing the need for secondary reference screens in compact home studio setups.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are pressuring manufacturers to transition away from conventional LCD backlighting systems toward solid-state alternatives. Industrial designers in Shenzhen and Taipei are accelerating LED array redesigns to maintain luminance uniformity without regulated refrigerant-based components. Premium pen display lines targeting European commercial sales are most affected, with compliance timelines compressing product refresh cycles by approximately eight months.
Enterprise procurement teams at animation studios are consolidating vendor relationships around hardware-as-a-service models that bundle pen display refresh cycles with technical support and calibration maintenance. Traditional channel distributors in the United States are losing direct access to studio procurement decisions as manufacturers build captive service organizations. This concentration is most visible in California, where major entertainment conglomerates now negotiate master service agreements covering three-year hardware lifecycles across multiple production divisions.
4K Drawing Tablet with Screen Market Segmentation
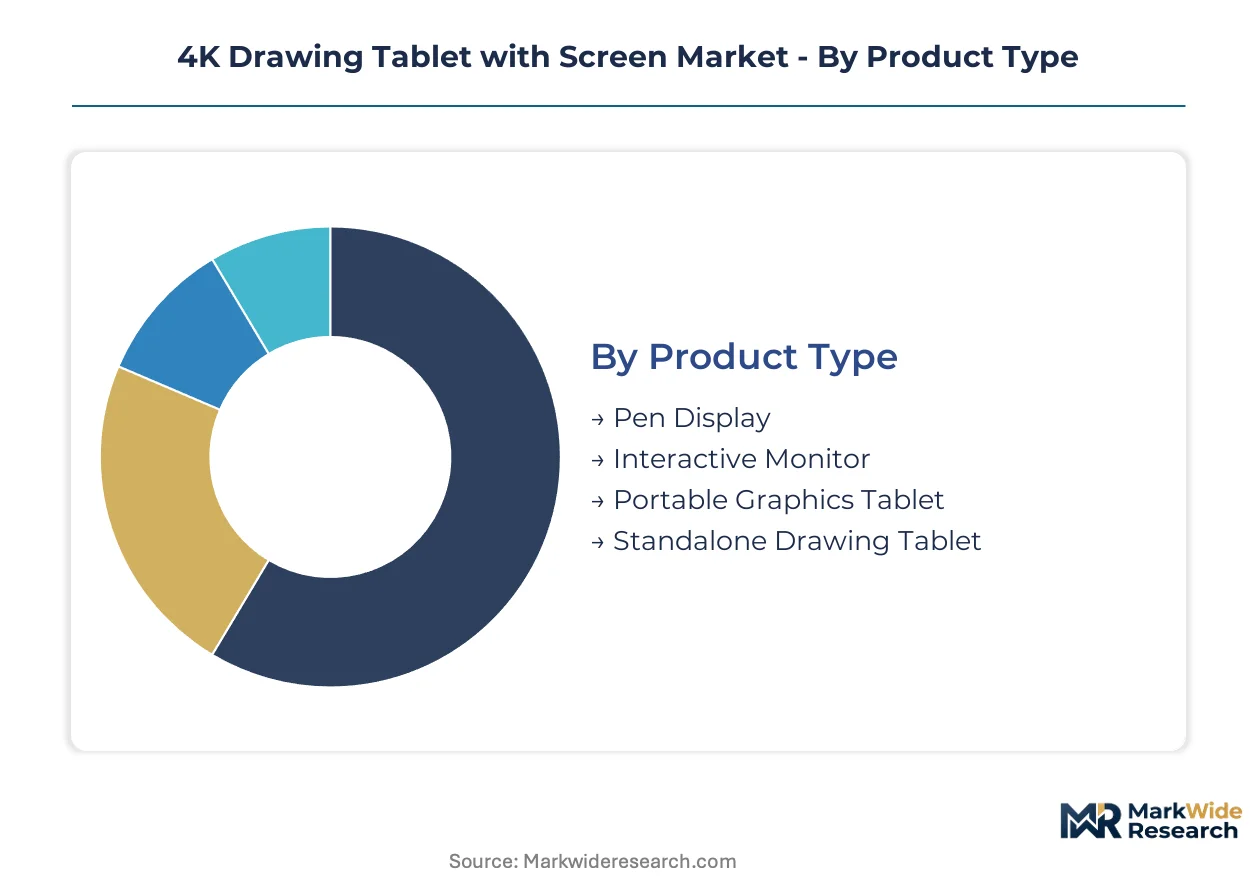
Procurement patterns across the 4K drawing tablet with screen market diverge sharply by technical specification, compliance burden, and end-use workflow intensity. Regulatory differentiation in electromagnetic emissions and energy efficiency standards creates tiered market access that reshapes competitive positioning across product categories.
Product Type:
FCC certification requirements for electromagnetic emissions vary significantly across form factors, with tethered units facing stricter shielding standards than battery-operated alternatives.
- Pen Display:Direct-input workstations integrate 4K LCD or OLED panels with active digitizer layers beneath the display surface. Animation studios in Burbank and Tokyo mandate these units for storyboard artists and inkers operating within distributed production pipelines.
- Interactive Monitor:Larger-format displays exceeding 24 inches target colorists and post-production specialists requiring HDR-compliant output. South Korean foundry capacity constraints on OLED substrates squeeze margin structures for manufacturers targeting professional tiers.
- Portable Graphics Tablet:Compact battery-powered units prioritize mobility over color accuracy for location sketching and concept work.
- Standalone Drawing Tablet:ARM-based mobile processors enable fully untethered operation, threatening pen display attach rates among freelance illustrators.
Pen Display handles the majority of throughput; Standalone Drawing Tablet is the fastest mover on share.
Technology:
Cost tier stratification separates premium electromagnetic architectures from volume capacitive deployments in educational settings.
- Electromagnetic Resonance:Pressure-sensitive digitizer layers resolve thousands of levels and tilt angles through resonant coupling between stylus and sensor grid. Professional illustrators in London and Vancouver specify these configurations for precision linework in commercial animation.
- Capacitive Touch:Passive finger-input layers dominate K-12 deployments where stylus precision is secondary to durability and cost containment.
- Multi-Touch:Gesture-capable surfaces support zoom and navigation shortcuts in browser-based creative workflows.
- Pressure Sensitive:Hybrid architectures combine capacitive base layers with active stylus protocols for mid-tier educational markets.
Electromagnetic Resonance commands the premium tier on margin; Pressure Sensitive is climbing the fastest as institutions upgrade from basic capacitive units.
Application:
Volume concentration correlates with workflow digitization maturity across creative industries.
- Animation Production:Frame-accurate timing and color management requirements drive specification of quantum-dot enhanced panels with hardware calibration. Major entertainment conglomerates in California negotiate master service agreements covering three-year hardware lifecycles.
- Digital Illustration:Freelance workflows prioritize pressure resolution and driver stability across macOS and Windows environments.
- Architectural Drafting:Large-format interactive monitors support CAD precision with stylus input for markup and revision.
- Educational Content Creation:National Skill Development Corporation initiatives across Indian state technical institutes create institutional procurement volume at localized pricing tiers.
Animation Production anchors professional revenue; Educational Content Creation is gaining share fastest as digital literacy curricula expand.
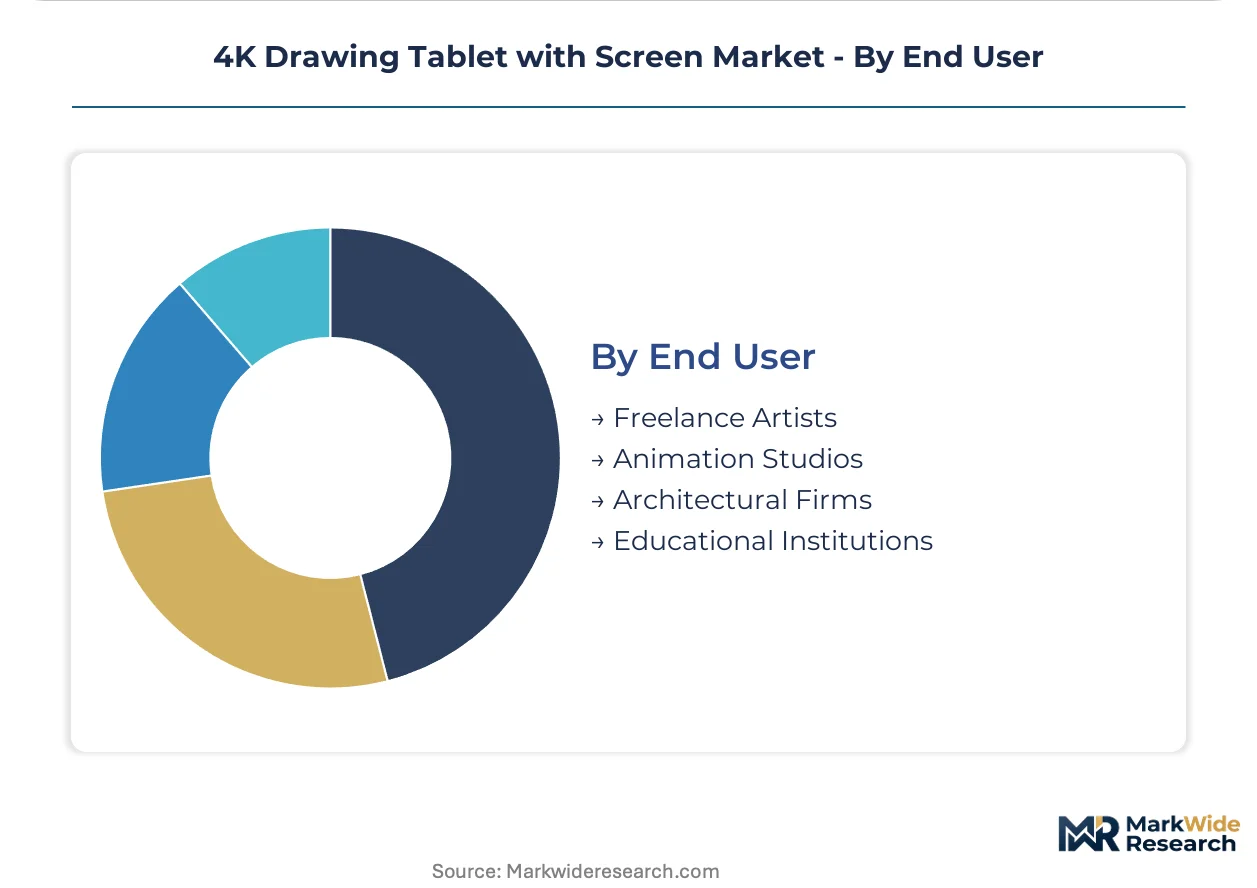
End User:
Customer type determines support infrastructure requirements and replacement cycle velocity.
- Animation Studios:Enterprise procurement teams consolidate vendor relationships around hardware-as-a-service models bundling refresh cycles with calibration maintenance. Captive service organizations are displacing traditional channel distributors in direct studio negotiations.
- Freelance Artists:Individual practitioners prioritize driver stability and cross-platform compatibility over enterprise support tiers.
- Architectural Firms:Technical specification teams evaluate color accuracy against physical material samples for client presentation workflows.
- Educational Institutions:Bulk procurement emphasizes modular construction for component recyclability under evolving e-waste regulations.
Animation Studios dominate enterprise value capture; Educational Institutions are expanding most quickly as infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean display panel foundries export 4K OLED substrates to assembly facilities in China and Taiwan, with finished pen display units flowing primarily to animation studios in Japan, the United States, and Western Europe.
United States
Enterprise procurement teams at Burbank animation studios negotiate hardware-as-a-service agreements bundling three-year refresh cycles. FCC electromagnetic emissions certification creates compliance barriers that favor established vendors with pre-certified modular digitizer layers. Los Angeles and New York anchor professional creative clusters where quantum-dot enhanced panels penetrate post-production colorist workflows.
Japan
METI energy efficiency mandates limit brightness calibration ranges for products seeking Tokyo and Osaka market access. Distributed production pipelines institutionalized during remote work transitions now mandate direct-input pen displays for storyboard artists and inkers operating from satellite offices. Kansai and Kanto regions concentrate replacement cycle velocity among professional illustrators.
South Korea
OLED substrate pricing volatility from domestic foundry capacity constraints squeezes margin structures for manufacturers targeting 4K resolution at sub-premium price points. National animation exports to streaming platforms drive enterprise-scale procurement from Seoul-based production houses. Busan-Ulsan industrial corridors supply bonded display-digitizer assemblies to global OEM partners.
China
Shenzhen and Taipei industrial designers accelerate LED array redesigns to maintain luminance uniformity under EU F-Gas Regulation compliance timelines. Domestic educational procurement emphasizes cost-effective electromagnetic resonance alternatives for digital literacy curricula in state technical institutes. Pearl River Delta manufacturing clusters dominate volume assembly for mid-tier pen display exports.
India
National Skill Development Corporation initiatives expand digital art training capacity across state technical institutes, creating institutional procurement volume at localized pricing tiers. BIS certification requirements shape product specification for vendors entering educational infrastructure tenders. Maharashtra and Karnataka anchor first-mover positioning for electromagnetic resonance pen display deployment in technical education.
4K Drawing Tablet with Screen Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and manufacturing scale dimensions. The vendor base stratifies into three tiers: heritage electromagnetic resonance specialists, volume-oriented manufacturing platforms, and mobile-first ecosystem integrators. Consolidation pressure intensifies as enterprise procurement teams reduce approved vendor lists and captive service organizations displace traditional channel distributors.
Within the heritage specialist tier, Wacom exemplifies premium positioning anchored in pressure-sensitive electromagnetic resonance heritage. Huion occupies a position as a scale-driven manufacturing platform competing aggressively on production volume. XPPen sits within the mid-tier specialization vector targeting emerging educational markets with cost-effective pen display configurations.
| Leading Market Players |
|---|
| Wacom |
| Huion |
| XPPen |
| Xencelabs |
| GAOMON |
| Microsoft |
| Apple |
| Samsung Electronics |
| Samsung |
| Others |
Pricing and Supply Chain Analysis
FCC electromagnetic emissions certification gates both supply qualification and price differentiation simultaneously, as manufacturers bearing pre-certification costs for modular digitizer layers capture premium positioning in United States enterprise procurement while uncertified competitors remain confined to educational volume tiers.
Pricing Analysis
Current-generation electromagnetic resonance pen displays command substantial premiums over prior-generation capacitive alternatives and forthcoming ARM-based standalone tablets. Three-tier pricing structure across premium, standard, and economy levels separates FCC-certified enterprise units from mid-tier educational configurations and uncertified entry-level products. Cost compression in OLED-equipped premium tiers is intensifying because South Korean foundry capacity constraints squeeze margin structures for 4K resolution targets. Animation studios exhibit the least price sensitivity due to hardware-as-a-service bundling, while Indian educational institutions demonstrate acute sensitivity to unit economics.
Supply Chain Analysis
Strategic stockpiling of OLED substrates and electromagnetic resonance sensor grids characterizes procurement behavior among tier-one manufacturers facing South Korean foundry allocation uncertainty. Supply concentrates in South Korea for display substrates, Taiwan for bonded display-digitizer assemblies, and China for volume pen display manufacturing. Component sourcing draws from Japanese precision sensor suppliers, German optical film providers, and domestic Chinese LED array fabricators. Single-source vulnerability in OLED substrate supply creates structural risk for premium product lines. Distribution runs through captive service organizations displacing traditional channel distributors in enterprise animation studio accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as remote production workflows permanently split procurement between enterprise hardware-as-a-service contracts and individual freelance transactions, creating distinct competitive arenas with divergent success requirements.
For Market Incumbents: Consolidate vendor relationships through captive calibration service organizations that displace traditional channel distributors in Burbank and Tokyo animation studio negotiations. Deepen backward integration into electromagnetic resonance sensor grid production to defend margin position against Huion's manufacturing scale advantages. METI efficiency mandate compliance investment creates switching costs that lock Japanese professional creative clusters into refreshed replacement cycles. For New Entrants and Emerging Players: Lead with localized electromagnetic resonance pen displays priced for National Skill Development Corporation tenders across Indian state technical institutes, where first-mover positioning remains unsecured. Target educational content creation as the most penetrable segment given institutional procurement volume expansion and incumbent focus on premium enterprise accounts. Browser-based workflow integration with Chromebook-dependent North American school districts offers a specific go-to-market angle bypassing established driver-stack complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across quantum-dot enhanced backlighting manufacturing as EU F-Gas Regulation compliance accelerates LED array redesign cycles. Long-term viability favors vendors with modular construction capabilities enabling component recyclability under evolving e-waste mandates. Acquisition target archetype: mid-tier electromagnetic resonance specialists with pre-certified FCC modular digitizer layers and existing educational channel relationships. Signal to watch: OLED substrate allocation announcements from South Korean foundries indicating supply constraint duration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Digitizer Pre-Certification | FCC pre-certification compresses OEM partnership time-to-market for display panel suppliers targeting United States animation studios. |
| Hardware-as-a-Service Bundling | Three-year refresh cycle contracts with calibration maintenance displace transactional procurement at California entertainment conglomerates. |
| Cloud-Native Workflow Integration | Browser-based rendering engine compatibility opens Chromebook-dependent educational buyers in North American school districts. |
| Backward Integration into Sensor Production | In-house electromagnetic resonance grid manufacturing defends margin structures against capacitive technology price erosion. |
| Localized Educational Pricing Tiers | BIS-compliant configurations at institutional price points capture National Skill Development Corporation infrastructure tenders in Maharashtra and Karnataka. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with product managers at electromagnetic resonance technology vendors, procurement leads at Burbank animation studios, calibration technicians in Tokyo service networks, and educational technology directors at Indian state technical institutes; alongside secondary validation through FCC equipment authorization databases, METI energy efficiency compliance filings, EU F-Gas Regulation implementation timelines, and South Korean display panel export statistics. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations derived from animation production pipeline counts and educational institution digital art program expansion data.
Across the projection horizon, the analytical framework modeled volume and value outputs across product type segmentation, technology tier stratification, application workflow intensity, and end-user procurement sophistication dimensions. CAGRs emerged from regression analysis against historical replacement cycle velocities, institutional procurement budget trajectories, and regulatory compliance-driven refresh acceleration. Industry-specific forecast inputs incorporated OLED substrate pricing volatility indices and electromagnetic resonance patent expiration schedules affecting competitive entry barriers.
Forecasts assume regulatory continuity in FCC electromagnetic emissions standards, METI energy efficiency mandates, and EU F-Gas Regulation phase-out timelines; material policy shifts would require re-modeling supply qualification economics and product refresh cycle assumptions. Revision becomes warranted when OLED foundry capacity utilization crosses thresholds that eliminate current substrate allocation constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.