
 4K Technology Market | 2026-2036
4K Technology Market Size, Share, and Industry Trends Forecast 2026-2036
4K Technology Market Intelligence
Market Context
The transition from monolithic LCD supply chains toward diversified OLED and microLED fabrication is fragmenting legacy manufacturing networks across East Asia. Samsung Electronics leverages its vertical control over QLED semiconductor materials to sustain pricing power in premium television tiers. BOE Technology Group anchors massive Gen 10.5 LCD capacity in China while competing aggressively on panel cost for commercial displays. Sony Corporation differentiates through broadcast-grade 4K camera-to-screen ecosystems that dominate professional content production workflows.
Technical Definition and Segment Structure
4K technology denotes display and imaging systems with a horizontal resolution of approximately 4000 pixels, typically 3840 × 2160 pixels in consumer formats, delivering four times the pixel density of Full HD for enhanced clarity at large screen sizes. The technology serves commercial and residential markets requiring high-fidelity visual reproduction for entertainment, medical imaging, digital signage, and remote collaboration. Televisions and streaming devices capture the largest revenue pools among product types, though professional displays command superior margins in broadcasting and medical applications. OLED panels represent the fastest-growing technology segment as burn-in mitigation and manufacturing yield improvements expand addressable markets beyond premium smartphones into larger formats.
Regulatory Environment and Outlook
The EU Ecodesign Directive and REACH chemical restrictions shape panel material selection and recyclability mandates across European markets, while the EPA ENERGY STAR program and California Energy Commission standards enforce efficiency minimums in North America. China's GB standards and dual carbon goals from MEE pressure domestic manufacturers toward lower-power backlight architectures and reduced rare-earth phosphor dependence. Stakeholders must monitor how regional efficiency benchmarks diverge and whether harmonization efforts through IEC standards prevent costly product fragmentation across jurisdictions.
Market Dynamics
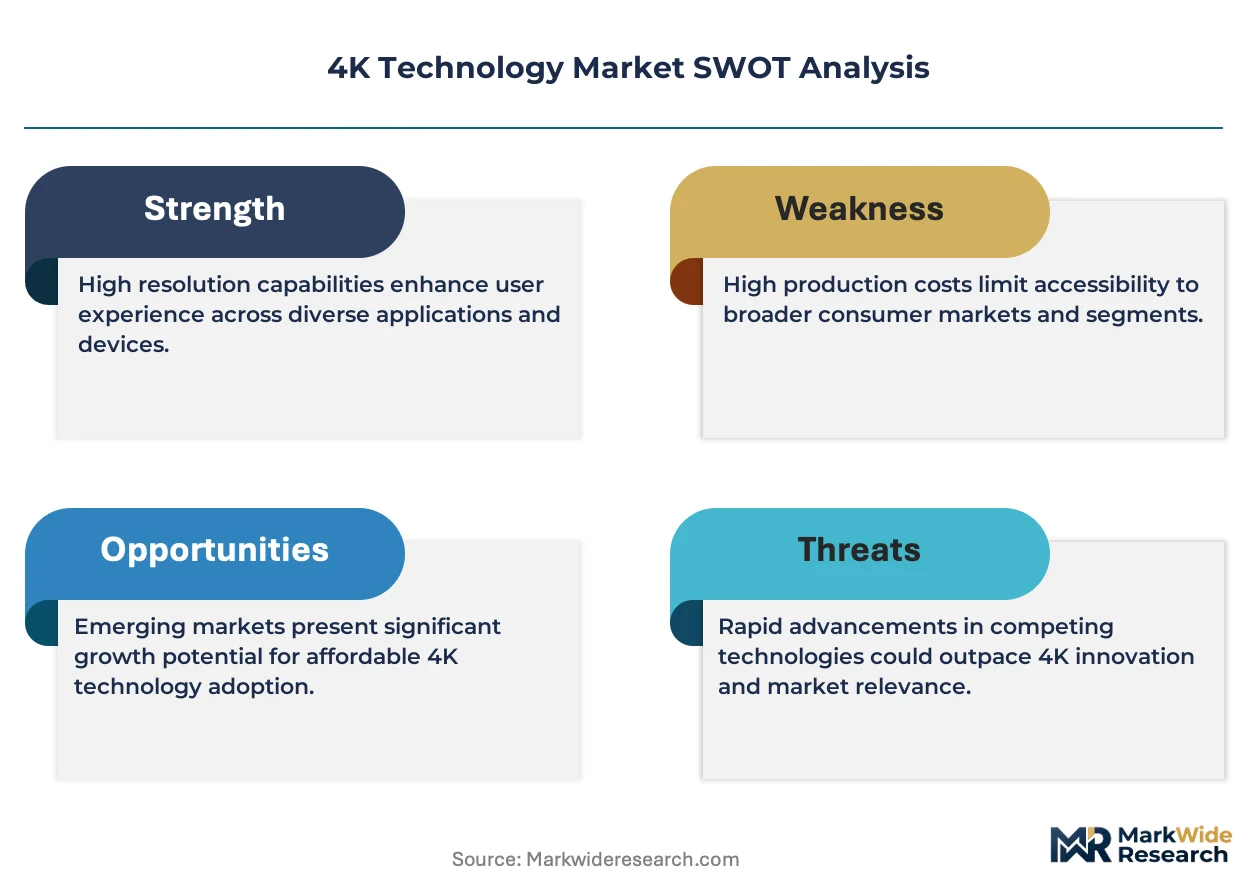
The transition from LCD to OLED and microLED architectures is fragmenting legacy manufacturing networks across East Asia while tightening energy efficiency mandates in Europe and North America reshape panel design priorities.
Growth Catalysts
- EU Ecodesign Directive:Stringent efficiency benchmarks are accelerating backlight innovation and premium panel adoption as manufacturers redesign for compliance.
- Broadcast and streaming content libraries:Content creators are expanding 4K-native production at accelerating rates, creating pull-through demand for compatible displays.
- OLED manufacturing yield improvements:Burn-in mitigation advances are expanding addressable markets beyond smartphones into larger format televisions and commercial signage.
Market Restraints
- Rare-earth phosphor supply concentration:China controls critical rare-earth processing for quantum dot materials, creating input cost volatility and geopolitical exposure for QLED manufacturers.
- Gen 10.5 LCD overcapacity:Massive Chinese fabrication investments have created structural oversupply in large-format LCD panels, compressing margins across mid-tier segments.
- REACH chemical restrictions:European substance regulations limit certain organic compounds in OLED emitter layers, forcing material reformulation and certification delays.
Strategic Opportunities
- Medical imaging displays:Diagnostic radiology and surgical visualization require color-accurate high-resolution panels with stringent calibration standards, commanding substantial margin premiums.
- India's PLI scheme for electronics manufacturing:Production-linked incentives are attracting display assembly investments to serve domestic consumer demand and export markets.
- MicroLED convergence with semiconductor fabrication:Transfer printing and chip-on-glass processes are borrowing from advanced packaging techniques to enable modular, scalable large-format displays.
Industry Challenges
- OLED deposition engineering talent:Vacuum thermal evaporation and inkjet printing expertise remains concentrated among East Asian equipment specialists, constraining new market entrants.
- Gen 8.5+ fab capex intensity:Each OLED or advanced LCD fabrication facility requires multi-billion-dollar investments with extended qualification timelines.
- IEC 62341 display standard harmonization:Divergent regional testing protocols for burn-in, luminance decay, and power consumption create certification complexity for global product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4K Technology Market |
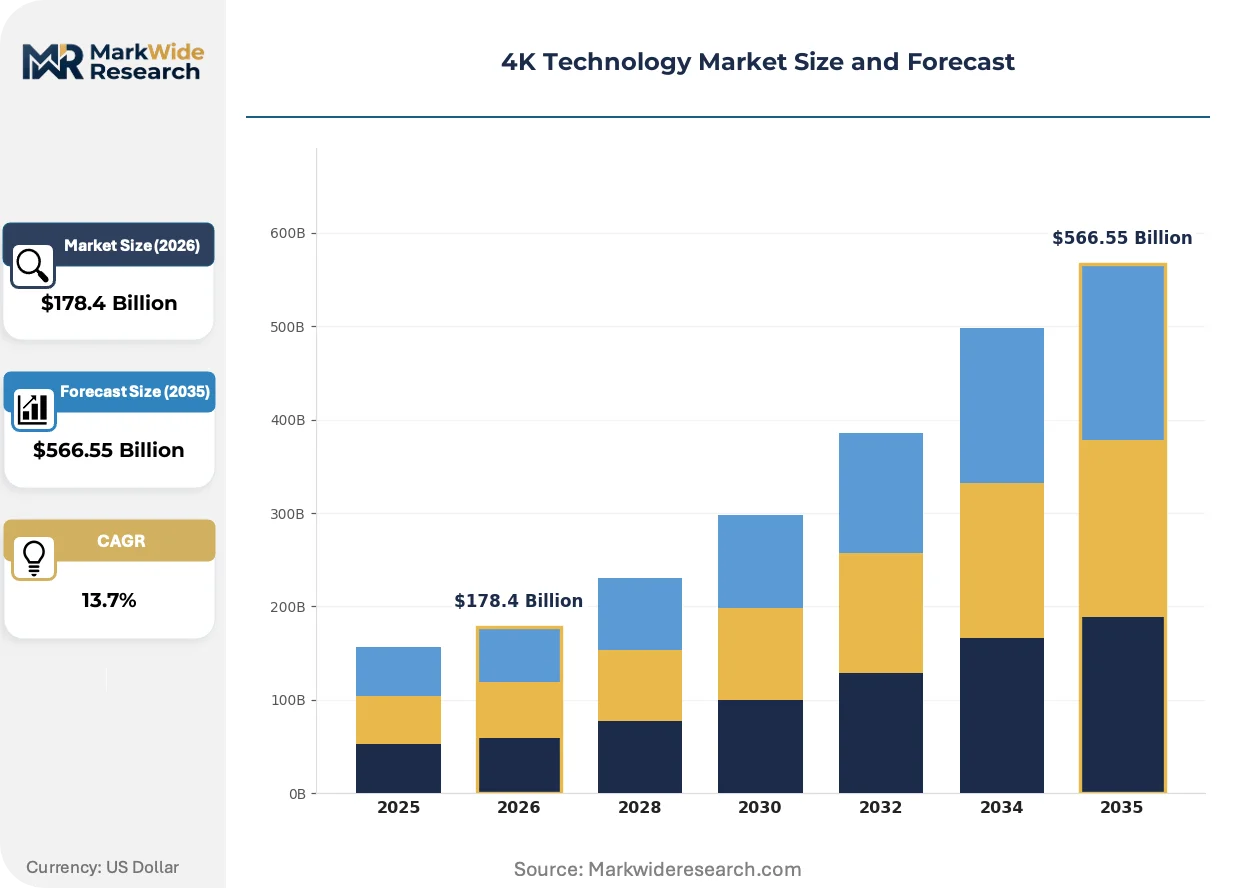
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $566.55 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Televisions, Monitors, Projectors, Streaming Devices Technology: OLED, QLED, LCD, LED Application: Home Entertainment, Professional Displays, Gaming, Broadcasting End User: Residential, Commercial, Educational, Hospitality |
| Companies Covered | Panasonic Corporation, Sharp Corporation, Samsung Electronics, LG Display, Toshiba Corporation, LG Electronics, Hisense, BOE Technology Group, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4K Technology Market Strategic Shifts & Innovations
Display technology is migrating from legacy backlight architectures toward self-emissive and miniaturized LED solutions while regulatory pressure intensifies around embodied carbon and recyclability.
Quantum dot enhancement film is migrating from edge-lit LCD configurations toward direct-lit and QD-OLED hybrid architectures. Television manufacturers are adopting these materials to extend color gamut without abandoning existing fabrication investments. The technology is migrating from premium tiers toward mid-range price bands as film deposition costs decline.
REACH restrictions on cadmium and certain heavy metals are compelling quantum dot suppliers to develop indium phosphide and perovskite alternatives. Material substitution timelines are compressing as ECHA substance evaluations advance through the authorization process. European market access now depends on demonstrating RoHS compliance alongside emerging ecodesign circularity requirements.
Enterprise procurement of commercial displays is consolidating through managed service contracts rather than capital equipment purchases. Systems integrators are bundling installation, calibration, and refresh cycles into multi-year agreements. North American corporate and education verticals are driving this transition as facilities teams outsource AV infrastructure lifecycle management.
4K Technology Market Segmentation
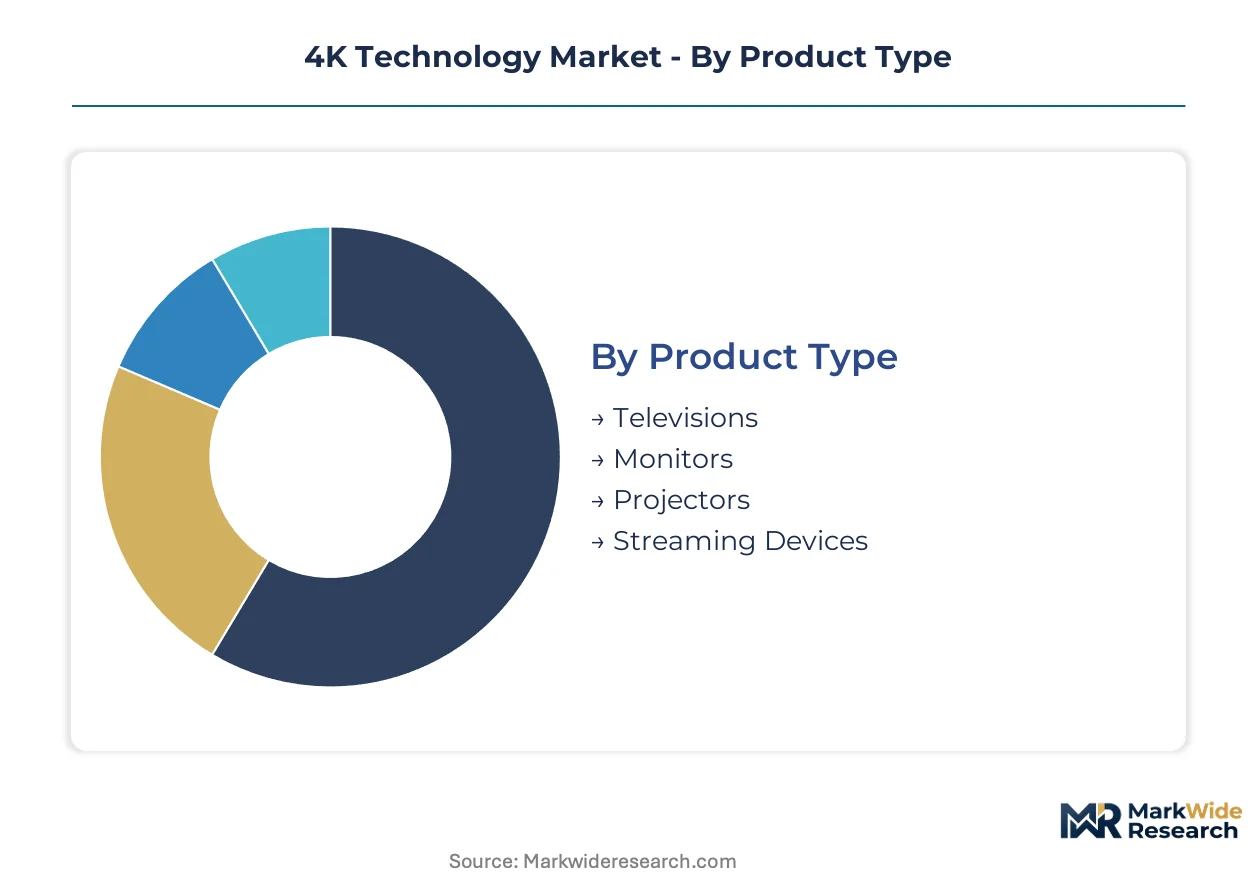
4K technology spans multiple product architectures and use cases where resolution requirements, panel economics, and content ecosystems intersect differently. Understanding how demand fragments across these dimensions reveals where procurement budgets concentrate and which specifications command margin premiums.
Product Type:
Mature categories dominate installed base volumes while emerging formats reshape how 4K content reaches end users.
- Televisions:Large-format panels with direct-lit or mini-LED backlights anchor consumer 4K adoption in residential living spaces. Living room replacement cycles in the United States and Germany concentrate demand for 55-inch and larger screens as streaming services expand native 4K libraries.
- Monitors:Desktop displays with high refresh rates and factory calibration target creative professionals and remote knowledge workers. Post-production studios in Los Angeles and London specify these for color-accurate video editing workflows where 4K resolution matches delivery specifications.
- Projectors:Laser-phosphor and lamp-based imaging systems scale 4K imagery beyond physical panel constraints for temporary installations.
- Streaming Devices:HDMI dongles and set-top boxes decode 4K HDR streams for legacy display hardware, extending content accessibility without full hardware replacement.
Televisions handle the majority of throughput; streaming devices are expanding most quickly as content libraries mature and consumers seek hardware-agnostic upgrade paths.
Technology:
Cost tiers separate legacy volume production from emerging premium architectures with differentiated material stacks.
- OLED:Organic light-emitting diode panels with self-emissive pixels deliver infinite contrast ratios and wide viewing angles without backlight bleed. South Korean fabrication lines in Gumi and Paju supply these for premium televisions where burn-in mitigation algorithms have extended warranty confidence.
- QLED:Quantum dot-enhanced LCD architectures extend color gamut through photoluminescent nanocrystals in film or tube configurations. Samsung and TCL deploy these across mid-to-premium tiers where manufacturing yields remain favorable against OLED cost structures.
- LCD:Liquid crystal display backplanes with LED edge or direct backlighting continue serving price-sensitive volume segments.
- LED:Direct-view LED video walls assemble discrete diode packages for modular large-format commercial installations.
LCD retains the dominant share of unit shipments; OLED is climbing the fastest as manufacturing scale reduces panel costs and content creators standardize on HDR mastering workflows that exploit its contrast performance.
Application:
Customer type stratification separates consumer entertainment from professional workflows with divergent certification and durability requirements.
- Home Entertainment:Consumer viewing environments prioritize screen size, smart platform integration, and streaming service compatibility over calibration precision. Living room installations in Japan and the United Kingdom drive specifications where 4K resolution serves as a baseline expectation for new purchases.
- Professional Displays:Broadcast reference monitors, medical imaging screens, and color-grading panels demand factory calibration and long-term luminance stability. Radiology departments at Mayo Clinic and Charité Berlin specify these for diagnostic confidence where pixel accuracy affects clinical decisions.
- Gaming:Low-input-lag panels with variable refresh rate support target console and PC enthusiasts.
- Broadcasting:Camera-to-transmission chain equipment requires 4K-native acquisition and monitoring for content production pipelines.
Home entertainment absorbs the largest revenue pool; professional displays command the steepest margin premiums per square meter of panel area.
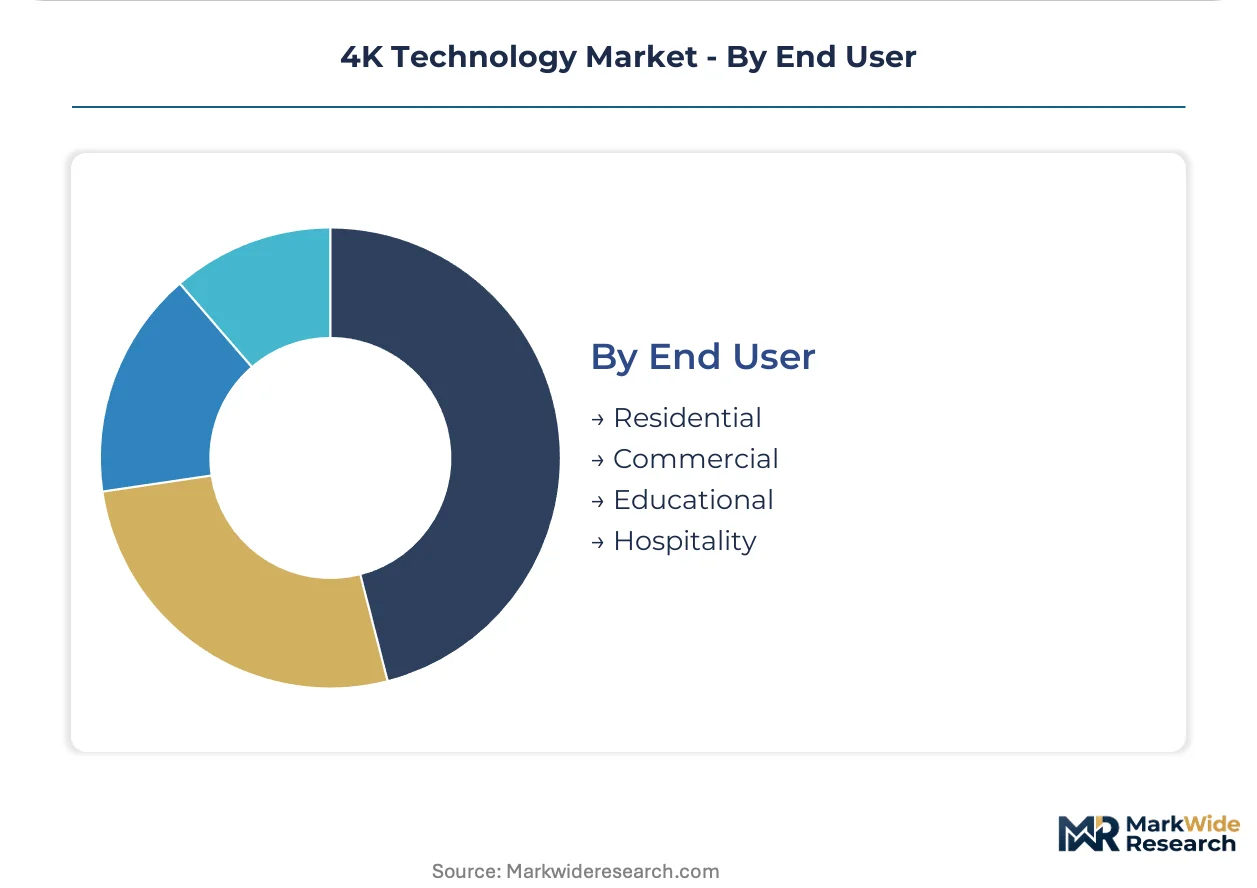
End User:
Volume concentration varies sharply between individual purchasers and institutional procurement with extended replacement cycles.
- Residential:Individual households purchasing through retail and e-commerce channels drive replacement-driven demand where screen size upgrades accompany resolution transitions. Suburban markets in Texas and Florida concentrate volume for living room and home theater installations.
- Commercial:Corporate offices, retail signage, and hospitality venues procure through AV integrators with multi-year service agreements. Hotel chains in Dubai and Singapore specify 4K displays for guest room entertainment where brand standards mandate visual quality benchmarks.
- Educational:K-12 and university classrooms deploy interactive 4K panels for hybrid instruction models.
- Hospitality:Bars, restaurants, and event venues utilize large-format 4K screens for ambient entertainment and sports broadcasting.
Residential purchasers generate the highest unit volumes; commercial deployments are gaining share fastest as facilities management outsourcing consolidates AV infrastructure decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium television buyers cluster in high-income urban centers while manufacturing investment concentrates in East Asian industrial corridors and emerging assembly hubs in South Asia.
United States
Streaming service penetration and sports broadcasting upgrades drive living room replacement cycles. The EPA ENERGY STAR program enforces efficiency minimums for imported displays. Austin and Los Angeles anchor post-production studio demand for broadcast-reference monitors.
China
Domestic streaming platform expansion and smart home integration accelerate household upgrade rates. MIIT GB standards and MEE dual carbon goals pressure manufacturers toward lower-power backlight designs. Hefei and Shenzhen concentrate Gen 10.5 LCD fabrication and OLED pilot line investments.
South Korea
Export-oriented premium television production and semiconductor-material integration sustain technology leadership. KTC certification aligns with IEC display standards for global market access. Gumi and Paju host the world's largest OLED deposition facilities serving international brands.
Germany
Commercial digital signage procurement and medical imaging infrastructure sustain professional display demand. The EU Ecodesign Directive mandates standby power limits and recyclability requirements. Dresden's semiconductor cluster feeds microLED research partnerships with Fraunhofer institutes.
India
Domestic consumer electronics assembly and hospitality sector expansion create pull-through for large-format panels. The PLI scheme for electronics manufacturing attracts display module investments. Noida and Sri City emerging as contract assembly locations for regional distribution.
4K Technology Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered pricing bands where scale advantages in display fabrication clash with ecosystem integration in content-to-screen workflows. The vendor base organizes around three archetypes: vertically integrated panel-to-brand conglomerates, pure-play display manufacturers supplying downstream OEMs, and broadcast-equipment specialists dominating professional reference monitor tiers. Competitive moves center on backward integration into quantum dot materials and strategic partnerships between streaming platforms and hardware manufacturers.
Among East Asian conglomerates, Samsung Electronics and LG Display occupy positions spanning consumer television and panel supply tiers, while Sony Corporation exemplifies the broadcast-specialist archetype with camera-to-screen ecosystem control. BOE Technology Group represents the scale-driven Chinese fabricator competing aggressively on panel cost for commercial display segments. These three anchors illustrate how competitive positioning fragments across manufacturing scale, vertical scope, and professional certification depth.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Sharp Corporation |
| Samsung Electronics |
| LG Display |
| Toshiba Corporation |
| LG Electronics |
| Hisense |
| BOE Technology Group |
| Sony Corporation |
| Others |
Cost & Logistics Intelligence
Rare-earth phosphor supply concentration in China determines both the spread between QLED premium tiers and LCD economy panels and the geographic shape of component sourcing networks. Manufacturers face dual pressure from input cost volatility and EU Ecodesign efficiency mandates that force architectural trade-offs between material stacks.
Pricing Analysis
Long-term indium and gallium supply contracts indexed to Shanghai Metal Exchange benchmarks anchor panel pricing for quantum dot-enhanced displays. Three-tier pricing structure across premium, standard, and economy levels separates OLED self-emissive architectures from QLED-enhanced LCD and basic direct-lit configurations. Cost compression in Gen 10.5 LCD segments is intensifying because Chinese fabrication overcapacity has eliminated margin buffers for mid-tier producers. Residential purchasers in suburban United States markets exhibit highest price sensitivity, while medical imaging departments at institutions like Mayo Clinic accept substantial premiums for calibrated professional displays.
Supply Chain Analysis
Foxconn, TPV Technology, and BOE Technology Group control the majority of display module contract manufacturing capacity for global television brands. South Korea, China, and Japan concentrate OLED deposition equipment, quantum dot material synthesis, and polarizer film production respectively. The supply chain draws from indium phosphide nanocrystals, rare-earth europium phosphors, and Gen 10.5 glass substrates as critical inputs. Single-source vulnerability around Chinese rare-earth processing creates exposure for QLED manufacturers dependent on photoluminescent material supply. Distribution runs through AV integrators for commercial verticals and retail electronics chains for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as streaming service ecosystems and smart home interoperability standards determine hardware replacement pull-through. The shift from capital equipment sales to managed service contracts in corporate and education verticals restructures how procurement budgets flow to display vendors.
For Market Incumbents: Build captive quantum dot material supply as a moat against Chinese rare-earth volatility and emerging perovskite competitors. Samsung Electronics and LG Display should deepen backward integration into indium phosphide synthesis while accelerating burn-in mitigation R&D to extend OLED warranty terms. Capacity addition in Vietnam or India under PLI schemes would diversify geographic exposure against tariff escalation.
For New Entrants and Emerging Players: Mid-market commercial signage in India and Southeast Asia represents the most penetrable entry point given fragmented local integrator networks and price-sensitive hospitality procurement. MicroLED pilot production for modular video walls in corporate lobby applications offers technology differentiation without competing against established OLED television scale. Partner with regional systems integrators offering installation and calibration bundling rather than competing on panel hardware alone.
For Investors and Strategic Acquirers: EU Ecodesign Directive efficiency tier upgrades reshape the acquisition landscape by penalizing legacy LCD exposure and rewarding OLED and microLED technology portfolios. Long-term viability across the analysis window favors fabricators with demonstrated deposition yield improvements and streaming platform distribution partnerships. Monitor cadmium-free quantum dot certification timelines at ECHA as the inflection signal for material substitution winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quantum Dot Materials | Captive indium phosphide supply insulates Samsung and TCL from Chinese rare-earth volatility. |
| Managed Service Contract Expansion | AV integrators in North American education verticals capture recurring revenue from facilities outsourcing. |
| MicroLED Pilot Line Investment | Transfer printing expertise from semiconductor packaging enables modular large-format commercial displays. |
| India PLI Scheme Manufacturing Localization | Noida and Sri City assembly locations reduce landed cost for South Asian consumer and hospitality demand. |
| Ecodesign Compliance Certification | EU standby power and recyclability mandates determine market access for premium television portfolios. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with display technology executives, procurement leads at hospitality chains, broadcast engineering directors, and medical imaging equipment specialists; and secondary validation through SEC 10-K filings of panel manufacturers, MIIT GB standard disclosures, ECHA substance evaluation databases, and hyperscaler streaming content capex disclosures. Bottom-up triangulation against top-down macroeconomic anchors ensured segment-level consistency.
Forecast inputs considered panel shipment volumes, manufacturing yield curves, content library expansion rates, and regulatory compliance cost trajectories across the projection horizon. Segmentation dimensions modeled include technology architecture, product format, application vertical, and end-user procurement pattern. CAGRs derived from logistic diffusion curves for display technology substitution and elasticity-adjusted demand functions for streaming service penetration.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices and cross-border semiconductor equipment trade flows would shift the trajectory. Quarterly review of OLED deposition yield reports and Ecodesign Directive implementation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Touch and Display Integration IC for Tablet Market
Display Technologies
Global Medical Display Market
Display Technologies
Electrochromic Window Market
Display Technologies
Transparent Digital Signage Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Flexible Display Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Rugged Display Market
Display Technologies
8K Display Resolution Market
Display Technologies
Vietnam Displays Market
Display Technologies
3D Display Module Market
Display Technologies
3D Holographic Display Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Collaboration Display Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Smart Privacy Glass Market