
 North America Industrial Display Market | 2026-2036
North America Industrial Display Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Display Market Analytics
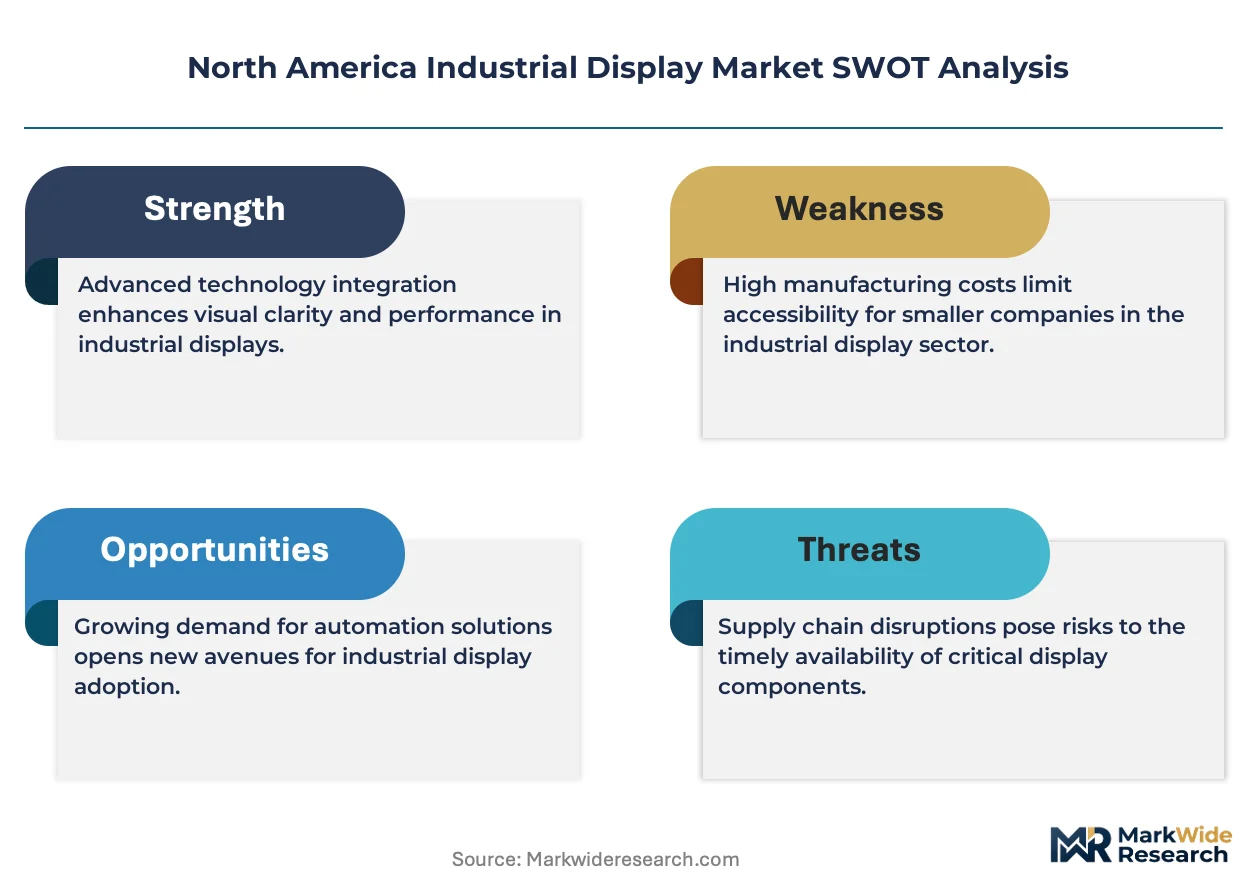
OLED substrates are repositioning product economics across the North America Industrial Display Market as manufacturers trade thickness and power efficiency for legacy LCD dominance in ruggedized environments. Samsung Electronics Co., Ltd. leverages its semiconductor-to-panel verticality to secure supply continuity for high-brightness industrial panels. Advantech Co., Ltd. anchors its competitive stance through embedded computing integration with display modules for factory automation. Rockwell Automation, Inc. dominates the programmable-logic-controller adjacent display segment through tight hardware-software coupling.
North America Industrial Display refers to hardened visual interfaces engineered for factory floors, control rooms, and field operations, typically rated for extended temperature ranges, shock resistance, and continuous operation lifecycles exceeding 50,000 hours. These displays serve as the primary human-machine interface for monitoring process variables, triggering machine commands, and alerting operators to fault conditions in real time. LED-backlit LCD panels retain the largest installed base across manufacturing applications, while OLED variants capture premium niches demanding superior contrast in low-ambient-light control rooms. Embedded installation formats command preference in OEM machine builds, whereas wall-mounted configurations sustain replacement cycles across process industries. System integrators represent the fastest-growing end-user channel as they bundle displays with SCADA and MES software deployments.
NHTSA, OSHA, and FCC frameworks collectively shape display specifications across transportation and general industrial applications, with NHTSA mandating minimum luminance for in-vehicle operator terminals and OSHA enforcing readability standards to reduce control-room human error. The FCC's electromagnetic emissions rules constrain display driver circuit designs, particularly for portable and embedded units deployed near wireless communication equipment. Stakeholders must weigh panel technology transitions against recertification timelines and supply chain qualification protocols.
Market Dynamics
OLED substrate migration is compressing legacy LCD economics across factory floors as manufacturers recalibrate brightness-versus-efficiency trade-offs for continuous-operation environments. NHTSA luminance mandates and OSHA ergonomic readability standards are tightening in parallel, forcing display vendors to synchronize panel transitions with recertification timelines.
Growth Catalysts
- Automotive Assembly Expansion:Michigan and Ohio factory floors are scaling touchscreen HMI deployments for real-time production monitoring. These installations demand hardened interfaces rated for extended temperature ranges and shock resistance.
- NHTSA Safety Mandates:Federal luminance requirements for in-vehicle operator terminals are cascading into adjacent industrial specifications. Display vendors must certify panels against minimum brightness thresholds before deployment.
- SCADA-MES Integration:System integrators are bundling displays with software deployments across the Great Lakes manufacturing corridor. This channel concentrates demand in Ontario, Michigan, and Illinois process industries.
Market Restraints
- OLED Supply Concentration:Substrate production clusters in East Asia create qualification bottlenecks for North American industrial panel vendors. Supply continuity risks intensify during technology transition windows.
- FCC Emissions Compliance:Electromagnetic interference rules constrain driver circuit designs for portable and embedded units deployed near wireless equipment. Recertification cycles extend product launch timelines.
- LCD Legacy Lock-In:LED-backlit LCD panels retain the largest installed base across manufacturing applications. Replacement economics favor incremental upgrades over full technology migrations.
Strategic Opportunities
- Canadian Process Industries:Ontario petrochemical and food processing facilities show underpenetrated demand for wall-mounted control room displays. Replacement cycles in these verticals lag US adoption curves.
- Embedded Computing Convergence:Factory automation OEMs are specifying display modules with integrated edge computing capabilities. This bundling creates margin expansion opportunities beyond commodity panel sales.
- OSHA Ergonomic Guidelines:Federal readability standards are tightening control room design specifications. Vendors certifying against updated guidelines capture specification advantages in safety-critical deployments.
Industry Challenges
- Recertification Timeline Compression:Panel technology transitions must align with NHTSA and FCC recertification windows. Misaligned qualification schedules strand inventory and delay revenue recognition.
- Legacy System Integration:New display deployments must interface with existing programmable logic controllers and SCADA architectures. Protocol mismatches require custom engineering that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Display Market |
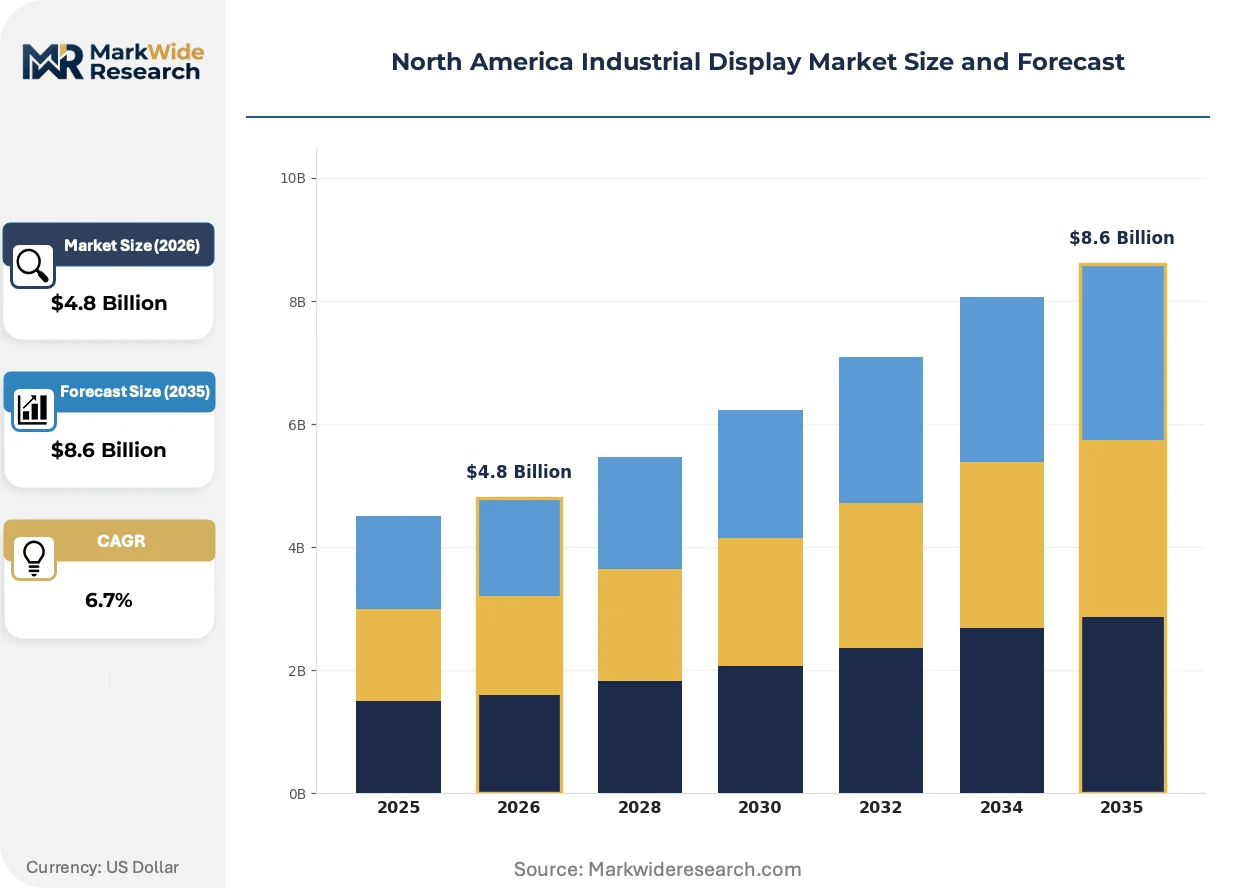
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, LCD, OLED, CRT Application: Manufacturing, Transportation, Retail, Healthcare End User: OEMs, System Integrators, Distributors, Resellers Installation: Wall-mounted, Freestanding, Embedded, Portable |
| Companies Covered | Samsung Electronics Co., Ltd., LG Display Co., Ltd., Advantech Co., Ltd., Siemens AG, Sharp NEC Display Solutions, Panasonic Holdings Corporation, Schneider Electric, Rockwell Automation, Inc., Winmate, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Display Market Evolving Landscape
Display substrate economics are actively restructuring procurement priorities across industrial buyer segments. Panel vendors are repositioning around brightness efficiency rather than unit cost as the primary specification lever.
MicroLED backlighting is electrifying contrast performance in low-ambient-light control rooms. Process industry operators in Texas and Louisiana refineries are specifying these panels for 24-hour continuous monitoring stations. The technology is electrifying competitive positioning around mean-time-between-failures metrics that legacy edge-lit designs cannot match.
OSHA ergonomic guideline updates are mandating minimum character height and luminance ratios for control room displays. These federal standards are compressing vendor specification sheets toward uniform readability thresholds. Automotive assembly plants in the Great Lakes corridor face the most immediate compliance pressure due to parallel NHTSA terminal requirements.
System integrators are unbundling after-sales service contracts from initial hardware procurement across Midwest manufacturing deployments. This purchasing pattern shift is displacing traditional distributor markup structures with direct vendor relationships. The behavioral change is most visible in Illinois and Michigan where SCADA-MES bundling concentrates buyer leverage.
North America Industrial Display Market Segmentation
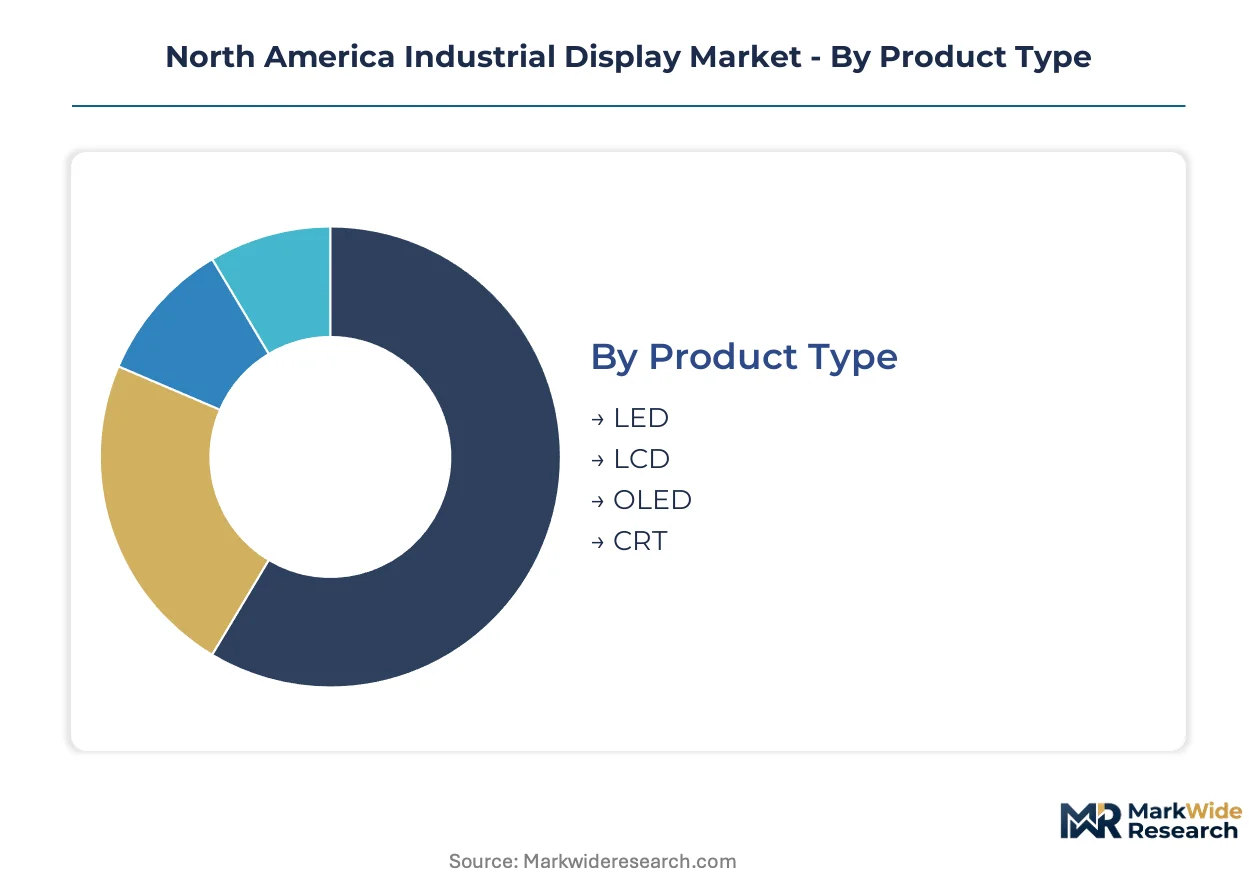
Industrial display procurement patterns diverge sharply across technology generations and deployment contexts. Panel substrate sourcing, installation constraints, and end-user channel economics create distinct margin profiles that vendors must navigate simultaneously.
Product Type:
Supply concentration in East Asian substrate fabrication governs panel availability and qualification timelines for North American industrial vendors.
- LED:Direct-lit LED backlights deliver superior luminance uniformity for NHTSA-mandated in-vehicle terminals. Michigan automotive assembly plants specify these panels for factory-floor HMIs where OSHA readability standards apply.
- LCD:Twisted-nematic and in-plane-switching variants retain the largest installed base across Great Lakes manufacturing corridors. Replacement economics favor incremental LED-backlit upgrades over full technology migrations in Illinois process industries.
- OLED:Active-matrix organic emitters capture premium control room niches demanding infinite contrast ratios. Supply bottlenecks constrain deployment scale during technology transition windows.
- CRT:Vacuum-tube legacy systems persist in hardened military and nuclear applications requiring radiation tolerance. Obsolescence-driven replacement cycles concentrate in Department of Energy facilities.
Today's leader: LCD. Tomorrow's challenger: OLED.
Application:
End-use verticals impose divergent certification burdens and operating environment specifications.
- Manufacturing:Factory automation deployments dominate volume demand across Ontario, Michigan, and Illinois. SCADA-MES integration requirements favor embedded computing convergence in display specifications.
- Transportation:NHTSA luminance mandates cascade from commercial vehicles into adjacent industrial terminal requirements. Ohio logistics hubs drive specification standardization for fleet management interfaces.
- Retail:Point-of-sale and digital signage applications prioritize slim form factors over ruggedization. FCC emissions compliance constrains driver design for wireless-proximate installations.
- Healthcare:FDA device regulations and HIPAA privacy requirements govern diagnostic and patient-facing displays. Cleanroom compatibility specifications limit vendor qualification pools.
Manufacturing commands current volume leadership. Transportation exhibits the steepest specification upgrade trajectory.
End User:
Channel structure determines margin capture and customer lifetime value economics.
- OEMs:Machine builders in Wisconsin and Indiana specify display modules for captive integration into factory equipment. Volume commitments secure preferential pricing and supply allocation.
- System Integrators:SCADA-MES bundling concentrates buyer leverage across the Great Lakes corridor. Direct vendor relationships are displacing traditional distributor markups in Illinois and Michigan.
- Distributors:Inventory-holding intermediaries serve fragmented replacement demand in secondary manufacturing markets. Working capital intensity constrains geographic coverage.
- Resellers:Value-added configuration services capture margin in specialized verticals requiring custom mounting or interface adaptation. Technical support obligations extend revenue recognition timelines.
System integrators are climbing fastest. Distributors face structural compression.
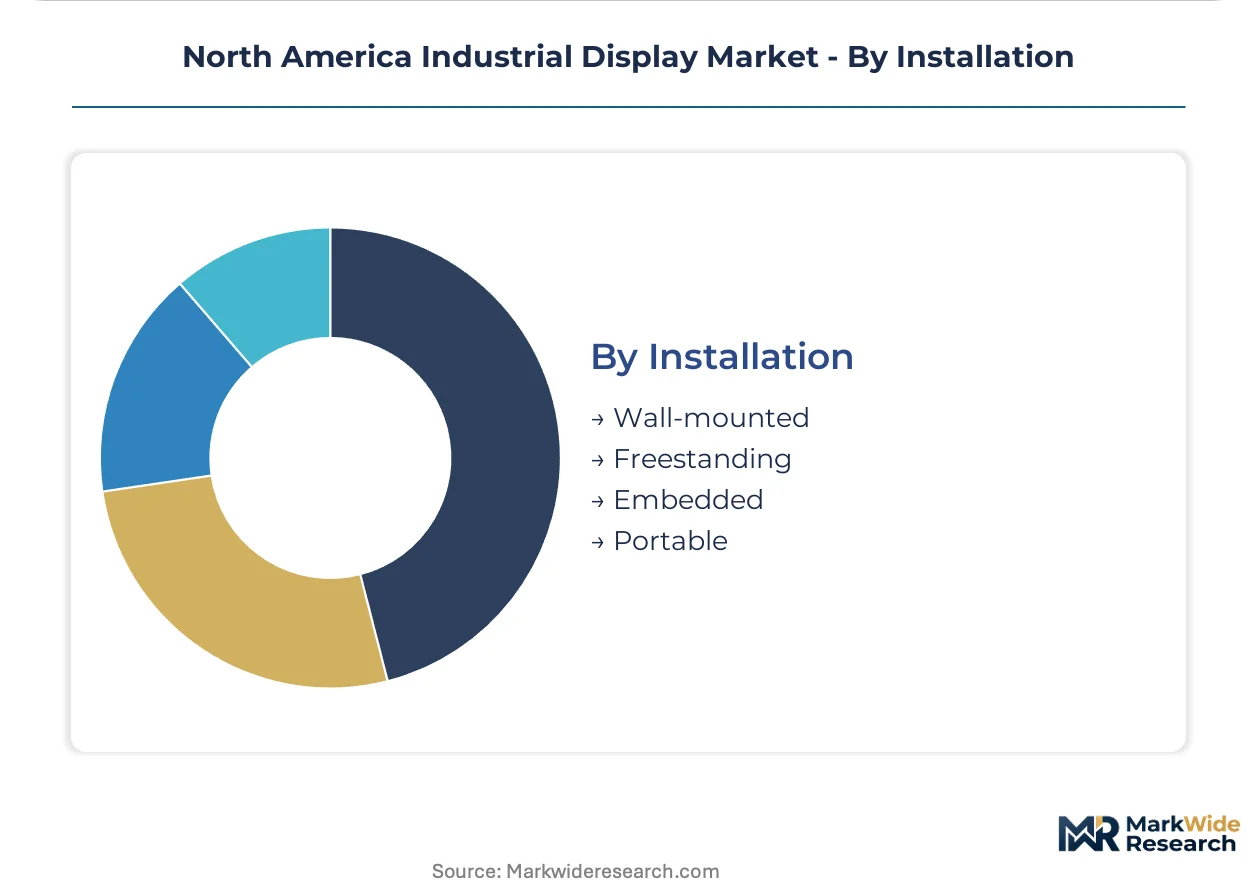
Installation:
Physical mounting constraints dictate thermal management, ingress protection, and service accessibility requirements.
- Wall-mounted:Control room configurations dominate process industry deployments in Texas and Louisiana refineries. OSHA ergonomic guidelines mandate minimum character height and viewing angle specifications.
- Freestanding:Mobile operator stations serve automotive assembly lines requiring line-side reconfiguration flexibility. Castor-mounted enclosures must survive shock loading during repositioning.
- Embedded:Panel-PC integration formats command preference in OEM machine builds where space constraints preclude external enclosures. Heat dissipation design determines maximum ambient temperature ratings.
- Portable:Battery-powered units support field maintenance and temporary commissioning activities. FCC emissions rules constrain wireless-proximate deployments in petrochemical facilities.
Embedded formats anchor OEM specification. Wall-mounted configurations sustain replacement cycle visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes manufacturing corridor spanning Michigan, Ohio, and Ontario anchors North American industrial display procurement, with automotive assembly plants and process industries driving specification standards across the continent.
United States
Michigan and Ohio automotive assembly plants are scaling touchscreen HMI deployments for real-time production monitoring. NHTSA luminance mandates for in-vehicle operator terminals cascade into adjacent industrial specifications, tightening brightness requirements. Illinois process industries concentrate SCADA-MES integration demand, with system integrators bundling displays across Chicago-area manufacturing facilities.
Canada
Ontario petrochemical and food processing facilities show underpenetrated demand for wall-mounted control room displays, with replacement cycles lagging US adoption curves. Health Canada and PMRA frameworks govern equipment certification in pharmaceutical and food processing verticals. Toronto and Hamilton manufacturing clusters are specifying embedded display modules for factory automation OEMs.
Mexico
Nuevo León and the Bajío Region automotive supplier parks are expanding display deployments for tier-one component manufacturing. Mexico's federal labor safety regulations align with OSHA ergonomic guidelines for control room readability standards. Querétaro and Guanajuato industrial corridors are integrating North American-sourced HMI panels into export-oriented assembly operations.
North America Industrial Display Market Competitive Landscape
Global majors compete with regional champions across technology integration and supply chain proximity. The vendor base stratifies around three tiers: diversified electronics conglomerates with captive panel production, industrial automation specialists bundling hardware with software ecosystems, and focused display manufacturers serving ruggedized niche applications. Two dominant competitive moves are reshaping positioning: backward integration into semiconductor and substrate supply chains, and strategic partnerships between panel vendors and system integrators to bypass traditional distribution channels.
Within the diversified electronics tier, Samsung Electronics Co., Ltd. and LG Display Co., Ltd. exemplify scale-driven substrate sourcing advantages. Rockwell Automation, Inc. occupies a distinctive position coupling programmable logic controller expertise with adjacent display hardware. Advantech Co., Ltd. represents the embedded computing convergence archetype, bundling industrial PCs with integrated display modules for factory automation OEMs.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Display Co., Ltd. |
| Advantech Co., Ltd. |
| Siemens AG |
| Sharp NEC Display Solutions |
| Panasonic Holdings Corporation |
| Schneider Electric |
| Rockwell Automation, Inc. |
| Winmate, Inc. |
| Others |
Value Network & Pricing Analysis
Display engineering talent clustering in Michigan and Ontario feeds labor-cost differentials into pricing-tier spreads across the North America Industrial Display Market. Assembly technician wage premiums in Detroit and Windsor widen the gap between premium OLED control room panels and standard LCD factory-floor units.
Pricing Analysis
Input-cost pass-through from East Asian substrate fabrication governs panel pricing dynamics across North American industrial display tiers. Three-tier pricing structure across premium, standard, and economy levels separates infinite-contrast OLED modules from LED-backlit LCD workhorses and legacy TN-panel replacements. Certification grade—specifically UL 60950-1 and NHTSA luminance compliance—drives price differentiation alongside volume scale. Cost compression in standard-tier LCD modules is intensifying because Korean and Taiwanese substrate suppliers are consolidating output toward higher-margin OLED lines. System integrators bundling SCADA-MES deployments show least price sensitivity, while replacement buyers in secondary manufacturing markets exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with South Korean OLED substrate suppliers, where Samsung Display and LG Display control active-matrix emitter production. Geographic supply concentration spans South Korea, Taiwan, and Japan for semiconductor backplanes, driver ICs, and polarizer films. Raw material dependencies include indium tin oxide for transparent electrodes, glass substrates from Corning's Kentucky and Taiwan facilities, and rare-earth phosphors for LED backlights. Tariff exposure on Chinese-sourced LCD glass and Taiwanese driver ICs constrains margin flexibility for North American panel assemblers. Distribution runs through direct vendor relationships with system integrators in Illinois and Michigan, displacing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Industrial Display Market reads as a late-cycle quality story. OEM specification shifts toward embedded computing convergence and OSHA ergonomic compliance favor vendors with certification depth over commodity panel assemblers.
For Market Incumbents: Deploy backward integration into driver IC and substrate supply chains to secure allocation during OLED transition windows. Rockwell Automation and Advantech anchor positions through hardware-software coupling and embedded computing bundling respectively; challengers must match this integration depth or cede specification control. Capacity addition in Mexico's Nuevo León corridor offers tariff-advantaged assembly proximity to Texas and Louisiana process industries. Certification investment in updated OSHA readability standards captures specification advantages in safety-critical deployments. For New Entrants and Emerging Players: Begin with Ontario petrochemical and food processing facilities, where wall-mounted control room display replacement cycles lag US adoption curves by 24-36 months. Canadian process industries show underpenetrated demand for NHTSA-luminance-compliant panels as Health Canada frameworks gradually align with US ergonomic standards. Target embedded computing convergence for Wisconsin and Indiana factory automation OEMs specifying panel-PC integration formats. Direct vendor relationships with SCADA-MES system integrators bypass distributor markups and accelerate revenue recognition. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking display hardware to complete control-system ecosystems. Long-term viability hinges on substrate technology transition timing—OLED qualification bottlenecks create 5-10 year windows for LCD-legacy cash harvest versus OLED-premium growth capture. Acquisition target archetype: mid-cap display specialists with captive UL/NHTSA certification libraries and established system integrator channel relationships. Watch OSHA guideline revision timing as inflection indicator; updated ergonomic mandates trigger replacement cycles that favor certified incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Captive OLED emitter supply secures allocation priority during Korean supplier transition windows. |
| Embedded Computing Convergence | Panel-PC bundling captures margin expansion beyond commodity display sales in factory automation. |
| OSHA Certification Investment | Readability standard compliance captures specification advantages in safety-critical control room deployments. |
| Direct System Integrator Relationships | Bypassing distributor markups concentrates buyer leverage across Great Lakes SCADA-MES bundling. |
| Mexican Manufacturing Footprint | Nuevo León assembly proximity reduces tariff exposure for Texas and Louisiana petrochemical deliveries. |
Research Methodology
Bottom-up factory automation and process industry modeling reconciled against top-down panel substrate tracking forms the analytical core. Primary interviews with plant engineers, OEM procurement teams, system integrators, and aftermarket service heads across Michigan, Ohio, Illinois, and Ontario were validated against secondary sources including NHTSA regulatory filings, OSHA ergonomic guideline updates, SEC 10-K disclosures from listed display vendors, and customs data on panel substrate imports. Triangulation between end-user demand signals and supply-side capacity announcements ensures statistical integrity.
Input-output matrices map panel substrate availability through semiconductor backplane, driver IC, and optical film conversion stages to finished industrial display shipments. Segmentation dimensions include technology generation, installation format, end-user channel, and application vertical across the projection horizon. CAGRs derive from installed base replacement cycle analysis, technology transition elasticity estimates, and regulatory compliance deadline impacts. Forecast inputs incorporate NHTSA luminance mandate phase-in schedules and OSHA guideline revision timelines.
Caveats apply where Korean OLED supplier allocation decisions, FCC emissions rule reinterpretations, or automotive assembly plant capital expenditure freezes could materially shift the outlook. Forecasts reflect documented assumptions about substrate technology transition pacing and system integrator channel consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
OLED Panel Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Global Display Controllers Market
Display Technologies
Flexible Screens Market
Display Technologies
4K Technology Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
Global Ferro Liquid Display Market
Display Technologies
PMOLED Display Market
Display Technologies
Privacy Screens Market
Display Technologies
Microdisplay Market
Display Technologies
Global Projector Market
Display Technologies
TFT LCD Panel Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Global Monochrome Display Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Display Control and Management System Market