
 Nanoparticle Size Analysis Instruments Market | 2026-2036
Nanoparticle Size Analysis Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoparticle Size Analysis Instruments Market Foresight
China is reconfiguring its analytical instrumentation supply chain through domestic precision manufacturing investments. Anton Paar leverages its Austrian engineering heritage to dominate high-end rheometry-integrated particle analysis. Malvern Panalytical anchors the European installed base with deep application expertise in laser diffraction. Bettersize Instruments competes aggressively on cost-performance ratios for emerging Asian laboratories.
Nanoparticle size analysis instruments measure particle dimensions from sub-nanometer to micrometer scales using light scattering, electron microscopy, or field-flow fractionation techniques, with detection limits and dynamic range determining instrument selection for specific material systems. The primary purpose spans quality control in drug formulation, catalyst development, and environmental monitoring where particle distribution directly impacts product performance or regulatory compliance. DLS and laser diffraction segments command the largest installed bases due to their maturity in pharmaceutical quality control workflows, while microfluidics-based methods represent the fastest-expanding technology category as labs seek reduced sample volumes and higher throughput. SEM instrumentation occupies the premium tier with margin pools concentrated in semiconductor and advanced materials R&D where nanoscale resolution proves non-negotiable.
FDA nanotechnology guidance and EMA reflection papers on nanomedicine quality documentation are elevating analytical rigor for particle size distribution reporting in drug submissions. ISO 13320 and ISO 22412 standards govern laser diffraction and DLS methodology respectively, creating compliance-driven replacement cycles among regulated industries. REACH registration requirements in Europe and EPA nanomaterial reporting rules in the United States further tighten the specification envelope for environmental and industrial applications. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP chapters on light scattering methods, as divergence in acceptance criteria could fragment instrument qualification protocols across major pharmaceutical export markets.
Market Dynamics
Pharmaceutical quality control budgets are expanding as FDA and EMA nanomedicine guidelines tighten particle characterization requirements for drug submissions, forcing instrument replacement cycles and capability upgrades across regulated manufacturing facilities.
Growth Catalysts
- EMA Reflection Papers:The European Medicines Agency's quality documentation standards for nanomedicines mandate validated particle size distribution reporting, compelling drug sponsors to invest in compliant analytical infrastructure.
- Biologics Manufacturing:Monoclonal antibody and mRNA vaccine production lines require sub-micron characterization for aggregate detection, creating dedicated instrument procurement workflows in fill-finish facilities.
- Laser Diffraction Maturity:ISO 13320-compliant laser diffraction systems anchor pharmaceutical QC protocols, with established method transferability reducing qualification burden for multi-site manufacturers.
Market Restraints
- Helium Supply Concentration:Field-flow fractionation systems depend on helium carrier gas, with Qatar and the United States controlling over 80% of global supply, exposing instrument operators to price volatility and allocation constraints.
- Electron Microscope Cost Structure:Scanning electron microscopy platforms require noble metal sputter coating consumables and dedicated vibration isolation infrastructure, elevating total cost of ownership beyond mid-sized laboratory budgets.
- Method Transfer Friction:Divergent pharmacopeial acceptance criteria between USP, EP, and JP chapters on light scattering create redundant qualification protocols for multinational pharmaceutical exporters.
Strategic Opportunities
- Microfluidics Convergence:Integration of microfluidic sample handling with DLS detection is virtualizing workflow automation, reducing technician intervention and enabling 24-hour unattended operation in high-throughput screening environments.
- India CDMO Expansion:Contract development and manufacturing organizations in India are building analytical capabilities to serve export markets, creating instrument demand from facilities seeking EU and US regulatory alignment.
- Environmental Monitoring Mandates:EPA nanomaterial reporting rules and REACH registration requirements in Europe are extending particle analysis beyond pharmaceuticals into industrial chemical compliance workflows.
Industry Challenges
- Metrology Talent Scarcity:Qualified technicians capable of validating DLS and laser diffraction methods against pharmacopeial standards are concentrated in Germany, the United States, and Japan, constraining facility expansion in emerging markets.
- Legacy System Integration:Modern particle analyzers must interface with 21 CFR Part 11-compliant LIMS and electronic batch record systems, requiring custom software validation that extends deployment timelines by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoparticle Size Analysis Instruments Market |
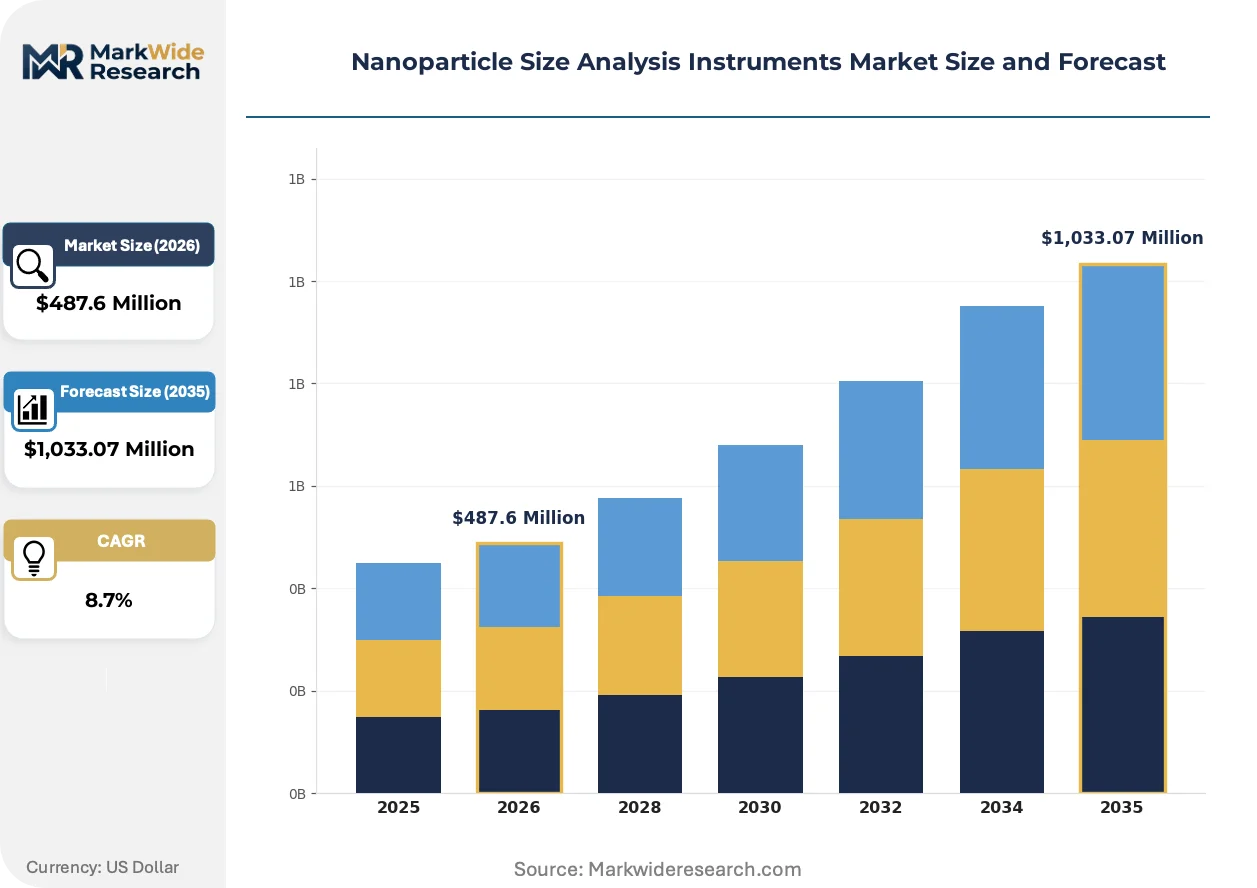
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DLS, NTA, SEM, FFF Technology: Laser Diffraction, Ultrasound, Microfluidics, Image Analysis Application: Pharmaceuticals, Biotechnology, Environmental Analysis, Material Science End User: Research Laboratories, Quality Control, Academic Institutions, Industrial R&D |
| Companies Covered | Anton Paar, Bettersize Instruments, Malvern Panalytical, Shimadzu Corporation, Brookhaven Instruments Corporation, HORIBA Scientific, Microtrac MRB, FRITSCH GmbH, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoparticle Size Analysis Instruments Market Shifts & Advancements
Instrument architectures are converging around reduced sample consumption, automated method execution, and cloud-connected compliance documentation, compressing the gap between research-grade flexibility and production-line repeatability.
Microfluidic DLS platforms are virtualizing sample preparation workflows by integrating automated dilution, filtration, and injection modules that previously required manual technician handling. Biopharma QC laboratories in Switzerland and Massachusetts are deploying these systems for release testing of lipid nanoparticle formulations. The technology is virtualizing headcount requirements in high-cost labor markets while improving reproducibility through elimination of operator-to-operator variability.
REACH registration requirements in Europe are elevating analytical rigor for industrial chemical manufacturers marketing nanomaterial-containing products. The European Chemicals Agency's substance evaluation process demands comprehensive particle size distribution data across production batches, not just R&D samples. German and Dutch specialty chemical producers are responding by embedding inline particle monitoring into continuous manufacturing lines rather than relying on offline laboratory testing.
Service unbundling is reshaping how mid-sized laboratories acquire analytical capability. Rather than capital purchase of SEM or FFF systems, facilities in South Korea and Singapore are adopting instrument access models where per-sample fees replace depreciation schedules. This consumption pattern is most visible among university core facilities and startup CDMOs managing cash flow constraints while building method portfolios for client qualification audits.
Nanoparticle Size Analysis Instruments Market Segmentation
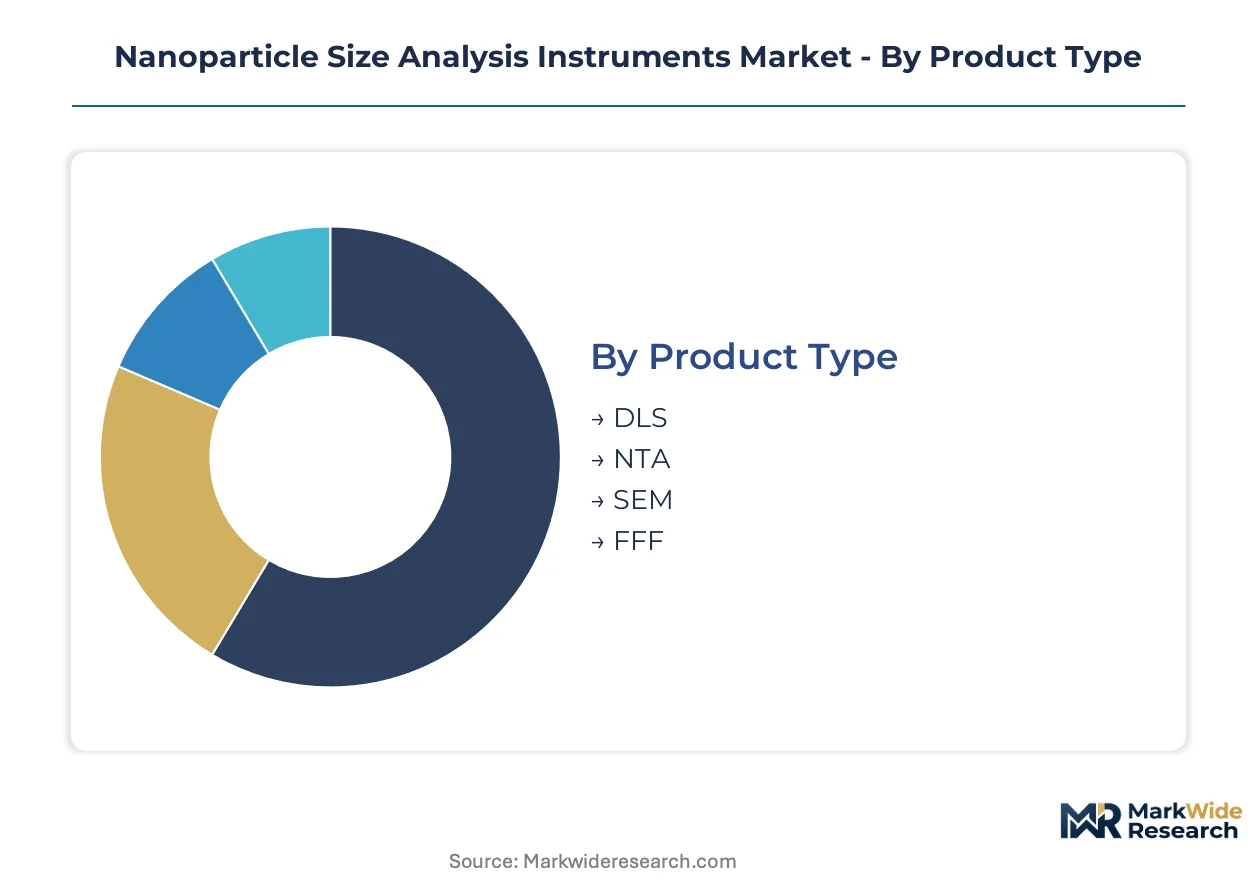
Segmentation in nanoparticle size analysis instruments reveals distinct service intensity patterns across product architectures. DLS platforms require annual laser calibration and detector alignment contracts, while electron microscopy systems demand vacuum pump maintenance and filament replacement programs that anchor multi-year service agreements.
Product Type:
After-sales service intensity varies sharply across instrument architectures, with electron microscopy platforms consuming 25-40% of lifetime cost in maintenance contracts versus 10-15% for light scattering systems.
- DLS:Dynamic light scattering systems measure Brownian motion-induced intensity fluctuations to derive hydrodynamic diameter distributions. Pharmaceutical QC laboratories in Switzerland and Massachusetts deploy these for lipid nanoparticle release testing, with ISO 22412 compliance driving replacement cycles among regulated manufacturers.
- SEM:Scanning electron microscopy platforms deliver nanoscale resolution through focused electron beam rastering and secondary electron detection. Semiconductor R&D facilities in Japan and Germany require noble metal sputter coating consumables and vibration isolation infrastructure that elevates total cost of ownership beyond mid-sized laboratory budgets.
- NTA:Nanoparticle tracking analysis tracks individual particle trajectories under optical microscopy for direct particle-by-particle sizing.
- FFF:Field-flow fractionation separates particles by size in an open channel without stationary phase, with helium carrier gas dependency exposing operators to Qatar and United States supply concentration risks.
By volume, DLS leads. By growth pace, FFF is ahead.
Technology:
Technology selection determines capital commitment tiers, with laser diffraction systems anchoring mid-range budgets and microfluidics platforms commanding premium positioning for automation integration.
- Laser Diffraction:Mature ISO 13320-compliant systems measure angular intensity patterns of scattered laser light across micron to millimeter ranges. Established method transferability reduces qualification burden for multi-site pharmaceutical manufacturers in Germany and the United States.
- Microfluidics:Integrated sample handling with DLS detection virtualizes workflow automation through automated dilution, filtration, and injection modules. Biopharma QC laboratories deploy these for 24-hour unattended operation in high-throughput screening environments.
- Ultrasound:Acoustic spectroscopy measures attenuation and velocity of ultrasound waves through particle suspensions for concentrated sample analysis without dilution.
- Image Analysis:Camera-based particle characterization captures morphological data beyond equivalent spherical diameter for irregular particle systems.
Laser diffraction holds the largest installed base. Microfluidics shows the steepest expansion trajectory.
Application:
Application focus shapes compliance burden intensity, with pharmaceutical workflows demanding 21 CFR Part 11 validation and environmental monitoring requiring REACH batch documentation.
- Pharmaceuticals:FDA nanotechnology guidance and EMA reflection papers mandate validated particle size distribution reporting for nanomedicine submissions. Drug sponsors invest in compliant analytical infrastructure across North American and European manufacturing facilities.
- Environmental Analysis:EPA nanomaterial reporting rules and REACH registration requirements extend particle analysis into industrial chemical compliance workflows. German and Dutch specialty chemical producers embed inline monitoring into continuous manufacturing lines.
- Biotechnology:Monoclonal antibody and mRNA vaccine production lines require sub-micron characterization for aggregate detection in fill-finish facilities.
- Material Science:Catalyst development and advanced ceramics R&D rely on particle distribution data to correlate synthesis conditions with functional performance.
Pharmaceuticals dominates revenue contribution. Environmental Analysis is climbing the fastest.
End User:
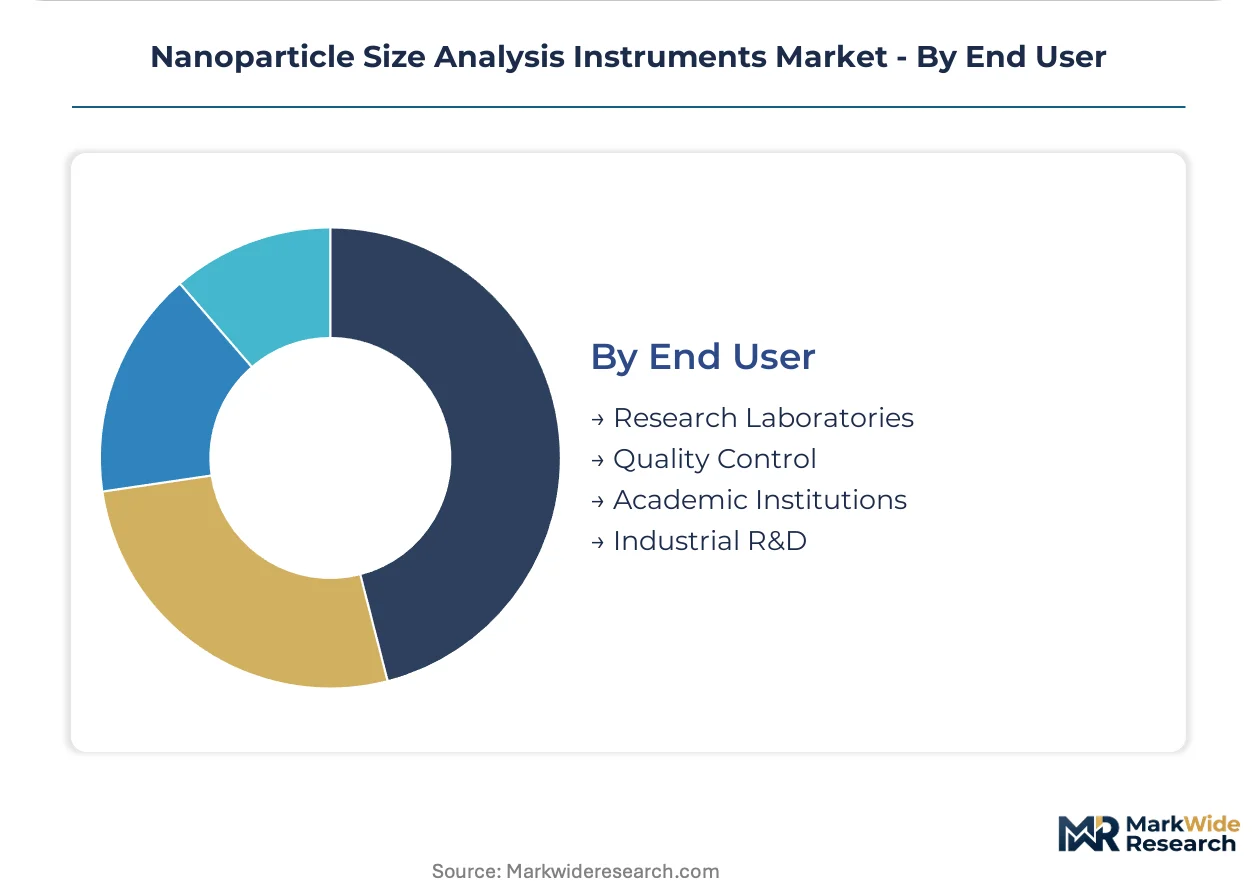
End user category determines procurement authority and replacement cycle timing, with industrial R&D holding discretionary capital and quality control operating on fixed compliance-driven schedules.
- Quality Control:Regulated manufacturing facilities operate on forced instrument replacement cycles as FDA and EMA guidelines tighten characterization requirements. Multi-site pharmaceutical manufacturers prioritize ISO-compliant systems with established method transferability.
- Research Laboratories:Core facilities in South Korea and Singapore adopt instrument access models where per-sample fees replace depreciation schedules, managing cash flow constraints while building method portfolios.
- Academic Institutions:University laboratories face budget constraints that favor cost-performance ratios and shared equipment access arrangements.
- Industrial R&D:Corporate research centers in advanced materials and electronics sectors prioritize resolution specifications and application support depth over initial capital cost.
Quality Control captures the largest equipment volume. Research Laboratories are gaining share fastest through service unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nanotechnology guidance and EMA reflection papers on nanomedicine quality documentation are elevating analytical rigor for particle size distribution reporting in drug submissions. ISO 13320 and ISO 22412 standards govern laser diffraction and DLS methodology respectively, creating compliance-driven replacement cycles among regulated industries.
United States
Pharmaceutical manufacturers in Massachusetts and North Carolina are expanding quality control budgets for sub-micron characterization. FDA nanotechnology guidance tightens particle characterization requirements for drug submissions, forcing instrument replacement cycles across regulated manufacturing facilities. The Greater Boston biotech cluster drives demand for DLS systems in lipid nanoparticle release testing workflows.
Germany
Precision instrumentation clusters in Bavaria and Baden-Württemberg serve advanced materials and biologics development. REACH registration requirements elevate analytical rigor for industrial chemical manufacturers marketing nanomaterial-containing products. German specialty chemical producers in the Rhine-Ruhr region embed inline particle monitoring into continuous manufacturing lines.
Japan
Semiconductor R&D facilities in Tokyo and Osaka require nanoscale resolution for process development. METI industrial standards support domestic precision manufacturing investments in analytical instrumentation. The Kansai region anchors electron microscopy demand for advanced ceramics and catalyst research.
Switzerland
Biopharma QC laboratories in Basel deploy microfluidic DLS platforms for 24-hour unattended operation. Swissmedic regulatory alignment with EMA standards ensures instrument qualification protocols meet export market requirements. The Lake Geneva biotech corridor concentrates demand for high-throughput screening environments.
India
Contract development and manufacturing organizations in Maharashtra and Gujarat are building analytical capabilities to serve export markets. CDSCO regulatory harmonization efforts drive instrument procurement from facilities seeking EU and US regulatory alignment. The Hyderabad-Visakhapatnam pharmaceutical belt generates demand for ISO-compliant laser diffraction systems.
Nanoparticle Size Analysis Instruments Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three strategic archetypes: heritage engineering houses with Austrian or Japanese precision manufacturing lineages, diversified analytical platforms with broad application expertise, and cost-optimized challengers serving emerging Asian laboratories. Competitive moves center on microfluidics convergence for workflow automation and service unbundling models that replace capital purchases with per-sample access fees.
Within the heritage engineering tier, Anton Paar leverages its Austrian engineering lineage to dominate high-end rheometry-integrated particle analysis. Malvern Panalytical anchors the European installed base with deep application expertise. Bettersize Instruments occupies the cost-performance position for emerging Asian laboratories seeking regulatory alignment without premium capital commitment.
| Leading Market Players |
|---|
| Anton Paar |
| Bettersize Instruments |
| Malvern Panalytical |
| Shimadzu Corporation |
| Brookhaven Instruments Corporation |
| HORIBA Scientific |
| Microtrac MRB |
| FRITSCH GmbH |
| Beckman Coulter |
| Others |
Supply & Pricing Matrix
Helium supply concentration between Qatar and the United States determines both the premium tier spreads for field-flow fractionation systems and the supply chain shape for high-resolution particle characterization. Instrument vendors price FFF platforms at substantial premiums to offset carrier gas volatility exposure, while mid-range laser diffraction systems compete on capital efficiency without noble gas dependencies.
Pricing Analysis
Price spreads between Austrian-engineered premium systems and Asian cost-optimized alternatives exceed threefold across identical detection specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence, with ISO 13320-compliant pharmaceutical-grade systems commanding substantial premiums over research-tier configurations. Cost compression in the economy tier is intensifying because emerging Indian CDMOs prioritize regulatory alignment over performance margins. Academic institutions exhibit highest price sensitivity; semiconductor R&D facilities in Japan demonstrate lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for precision optical components and detector arrays. Manufacturing concentrates in Germany, Japan, and Austria for high-end interferometry modules. Noble metal sputter coating consumables for SEM platforms draw from South African and Russian platinum-group metal supply. Single-source vulnerability for helium carrier gas exposes FFF operators to allocation constraints. Distribution runs through authorized regional service centers that bundle installation validation with multi-year maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where pharmacopeial compliance creates switching costs that lock pharmaceutical manufacturers into validated instrument ecosystems.
For Market Incumbents: Build certification moats by embedding 21 CFR Part 11 software validation directly into hardware shipments, reducing customer deployment timelines against emerging Asian challengers. Deepen application expertise in lipid nanoparticle workflows for mRNA vaccine quality control, a segment where method transfer friction protects installed bases. Acquire microfluidics specialists in Switzerland or Massachusetts to virtualize unattended operation capabilities. For New Entrants and Emerging Players: Build out service-unbundled access models targeting South Korean and Singaporean university core facilities where per-sample fees replace capital purchases. White-space concentrates in Indian CDMO analytical capabilities seeking EU and US regulatory alignment without premium capital commitment. Lead with ISO 22412-compliant DLS platforms priced at mid-tier positioning against heritage European engineering houses. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized application expertise over diversified analytical breadth. Long-term viability rests on pharmacopeial entrenchment and recurring service revenue attachment rates. Target acquisition archetype: mid-cap European DLS specialists with validated pharmaceutical customer bases and helium-independent technology architectures. Watch for EMA-USP pharmacopeial divergence as inflection signal forcing redundant instrument qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidics Convergence | Virtualizes technician headcount in Swiss biopharma QC laboratories through automated sample handling. |
| Service Unbundling Model | Replaces capital purchase cycles with per-sample access fees for South Korean university core facilities. |
| Regulatory Certification Investment | Accelerates FDA submission readiness for nanomedicine sponsors requiring validated particle distribution data. |
| Helium Supply Diversification | Mitigates Qatar concentration risk for field-flow fractionation operators through alternative carrier gas R&D. |
| Indian CDMO Partnership | Aligns analytical infrastructure with CDSCO harmonization efforts for EU and US export market access. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical quality control directors, analytical instrumentation procurement managers, regulatory affairs specialists at nanomedicine sponsors, and university core facility directors, then refined through secondary validation. Sources included FDA nanotechnology guidance documents, EMA reflection papers on nanomedicine quality, ISO 13320 and ISO 22412 standards documentation, and SEC filings from precision instrumentation manufacturers. Bottom-up instrument shipment data was triangulated against top-down pharmaceutical R&D spending allocations.
Demand-supply balance across the projection horizon anchored the analytical framework, with segmentation modeled by technology type, application intensity, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from instrument replacement cycle timing, compliance-driven upgrade mandates, and emerging market laboratory buildout rates. Industry-specific inputs included pharmacopeial harmonization progress between USP, EP, and JP chapters, and helium supply allocation volatility from Qatar and United States production.
Stress conditions across carrier gas supply disruption, pharmacopeial divergence scenarios, and emerging market CDMO capital constraint severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and replacement cycle elasticity. Material shifts in EMA nanomedicine guidance stringency or helium export policy from Qatar would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Laser Probe Market
Analytical Instruments
Life Science and Analytical Instruments Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Mass Spectroscopy Market
Analytical Instruments
Thermoluminescent Dosimeter (TLD) System Market
Analytical Instruments
Microchip Electrophoresis Market
Analytical Instruments
High Purity Gas Flow Meter Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
3D Touch Probe Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Precision Balances Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
High-Sensitivity Luminometers Market