
 Waste Heat Recovery System Market | 2026-2036
Waste Heat Recovery System Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Heat Recovery System Market Analysis
Advanced alloys and ceramic composites are repositioning heat exchanger economics in high-temperature industrial settings. Siemens Energy leverages its turbine integration expertise to anchor large-scale ORC deployments across European heavy industry. Thermax Limited dominates the Indian subcontinent through localized engineering and captive power co-generation offerings. General Electric competes on aerospace-derived recuperator technology adapted for stationary industrial gas turbines.
Waste heat recovery systems capture thermal energy from exhaust streams, process off-gases, and cooling circuits, typically operating across temperature differentials from 80°C to over 1,000°C depending on source quality and working fluid selection. These installations primarily serve to displace purchased electricity, reduce fuel consumption, or feed district heating networks in energy-intensive facilities. Organic Rankine Cycle technology leads in low-to-medium temperature applications below 300°C, where silicone-based and hydrocarbon working fluids now displace earlier refrigerant chemistries under evolving environmental protocols. Steam Rankine Cycle systems retain primacy in high-temperature steel, cement, and refinery settings where saturated steam integrates directly with existing boiler infrastructure. The retrofit installation segment carries distinct margin dynamics, requiring custom engineering to accommodate legacy ducting and space constraints rather than standardized new-build configurations.
The EPA enforces emissions thresholds under the Clean Air Act that indirectly compel efficiency investments, while the EU Green Deal and REACH framework constrain working fluid chemistries and mandate lifecycle carbon accounting for industrial assets. India's BIS energy efficiency standards and PLI scheme for capital goods manufacturing shape local procurement patterns and domestic content requirements. Stakeholders must track evolving carbon border adjustment mechanisms and working fluid phase-down schedules to preserve project economics and equipment certification pathways across jurisdictions.
Market Dynamics
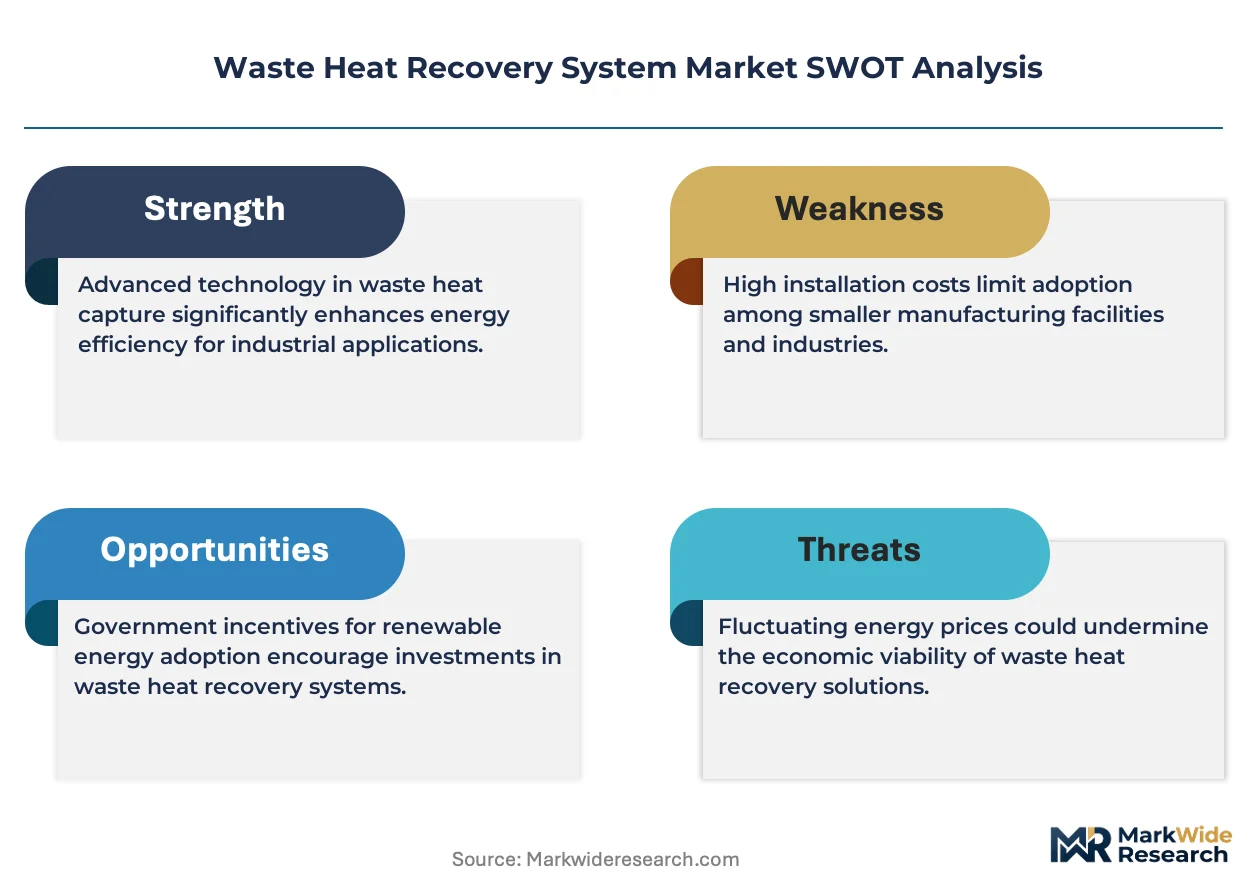
The EU F-Gas Regulation is compressing refrigerant options for Organic Rankine Cycle systems, forcing rapid chemistry transitions across European heavy industry while cement and steel producers in India scale installations under tightening BIS energy efficiency mandates.
Growth Catalysts
- EU Green Deal carbon accounting:Lifecycle emissions mandates for industrial assets compel steel and chemical complexes to retrofit waste heat recovery, anchoring project pipelines in Germany's Rhine-Ruhr corridor.
- India's PLI scheme for capital goods:Domestic content requirements accelerate localized engineering and captive power co-generation offerings, expanding WHR installations among cement manufacturers cutting kiln energy intensity.
- Silicone-based working fluids:Low-global-warming-potential chemistries displace earlier refrigerants under environmental protocols, enabling ORC deployment in low-to-medium temperature applications below 300°C.
Market Restraints
- Alloy input cost volatility:Nickel and cobalt price swings destabilize heat exchanger economics for advanced ceramic composite designs in high-temperature settings.
- REACH framework compliance friction:Working fluid registration timelines and toxicity testing requirements delay equipment certification pathways across European jurisdictions.
- Steam Rankine substitution threat:Saturated steam systems retain primacy in cement and refinery settings where direct boiler integration outweighs ORC flexibility advantages.
Strategic Opportunities
- Carbon border adjustment mechanisms:Emerging trade rules on embedded emissions create compliance-driven demand for WHR retrofits among export-oriented Indian cement and steel producers.
- District heating network integration:Urban energy planning in German industrial cities opens new revenue streams for low-grade heat offtake from chemical complexes.
- Aerospace-derived recuperator adaptation:Cross-industry technology transfer from stationary gas turbines enables efficiency gains in high-temperature exhaust streams.
Industry Challenges
- Retrofit engineering talent scarcity:Custom ducting design and legacy space constraint accommodation require specialized mechanical engineers in short supply across European project pipelines.
- Working fluid phase-down synchronization:Mismatched national implementation schedules for F-Gas Regulation restrictions complicate multi-jurisdiction equipment certification and spare parts inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Heat Recovery System Market |
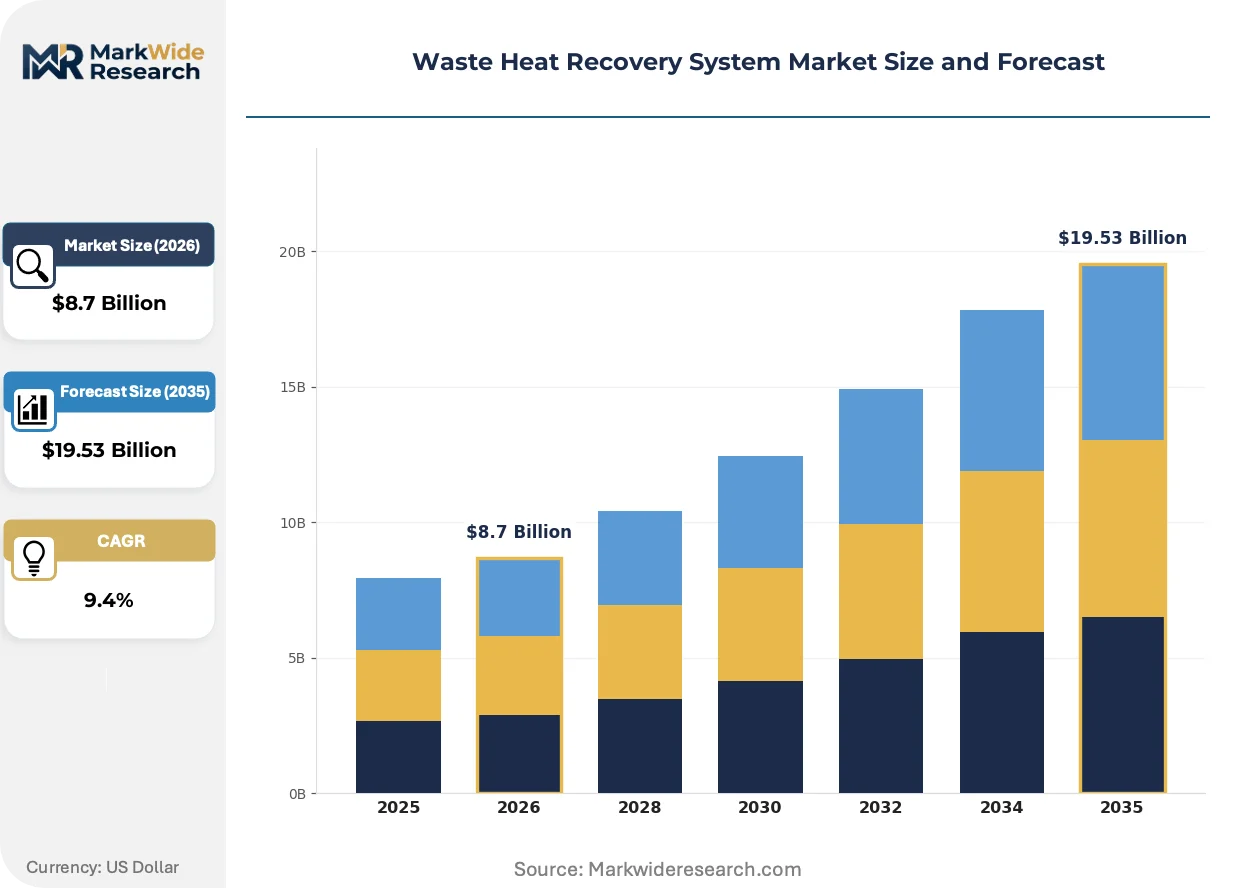
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Organic Rankine Cycle, Steam Rankine Cycle, Combined Heat and Power, Thermoelectric Generators Application: Industrial Processes, Power Generation, District Heating, Automotive End User: Manufacturing, Oil & Gas, Chemical, Food & Beverage Installation: On-site, Retrofit, New Build, Modular |
| Companies Covered | ABB, Bosch Industriekessel GmbH, Siemens Energy, Forbes Marshall, IHI Corporation, Mitsubishi Power, Ltd., Turboden S.p.A., Thermax Limited, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Heat Recovery System Market Emerging Trajectories
Technology trajectories in waste heat recovery are compressing equipment form factors while regulatory chemistry constraints and procurement model evolution reshape competitive positioning across temperature-grade segments.
Supercritical CO2 power cycles are electrifying the competitive landscape for low-to-medium temperature applications. Steel and chemical producers in Germany's industrial corridor are piloting compact turbomachinery that eliminates working fluid toxicity concerns entirely. This architecture is electrifying project economics by reducing footprint requirements and eliminating refrigerant compliance overhead.
The EU F-Gas Regulation's accelerated phase-down schedule for high-global-warming-potential refrigerants is constraining ORC working fluid portfolios. Equipment manufacturers must recertify systems for hydrocarbon and silicone-based alternatives, compressing development timelines. Indian cement producers face parallel pressure as BIS standards align with international environmental protocols, forcing chemistry transitions in new-build installations.
Energy service company contracting is displacing direct equipment procurement among capital-constrained industrial buyers. German steel complexes and Indian cement groups increasingly favor heat-as-a-service arrangements where vendors retain ownership and optimize performance. This shift concentrates risk with technology providers while accelerating deployment velocity among buyers prioritizing balance sheet preservation.
Waste Heat Recovery System Market Segmentation
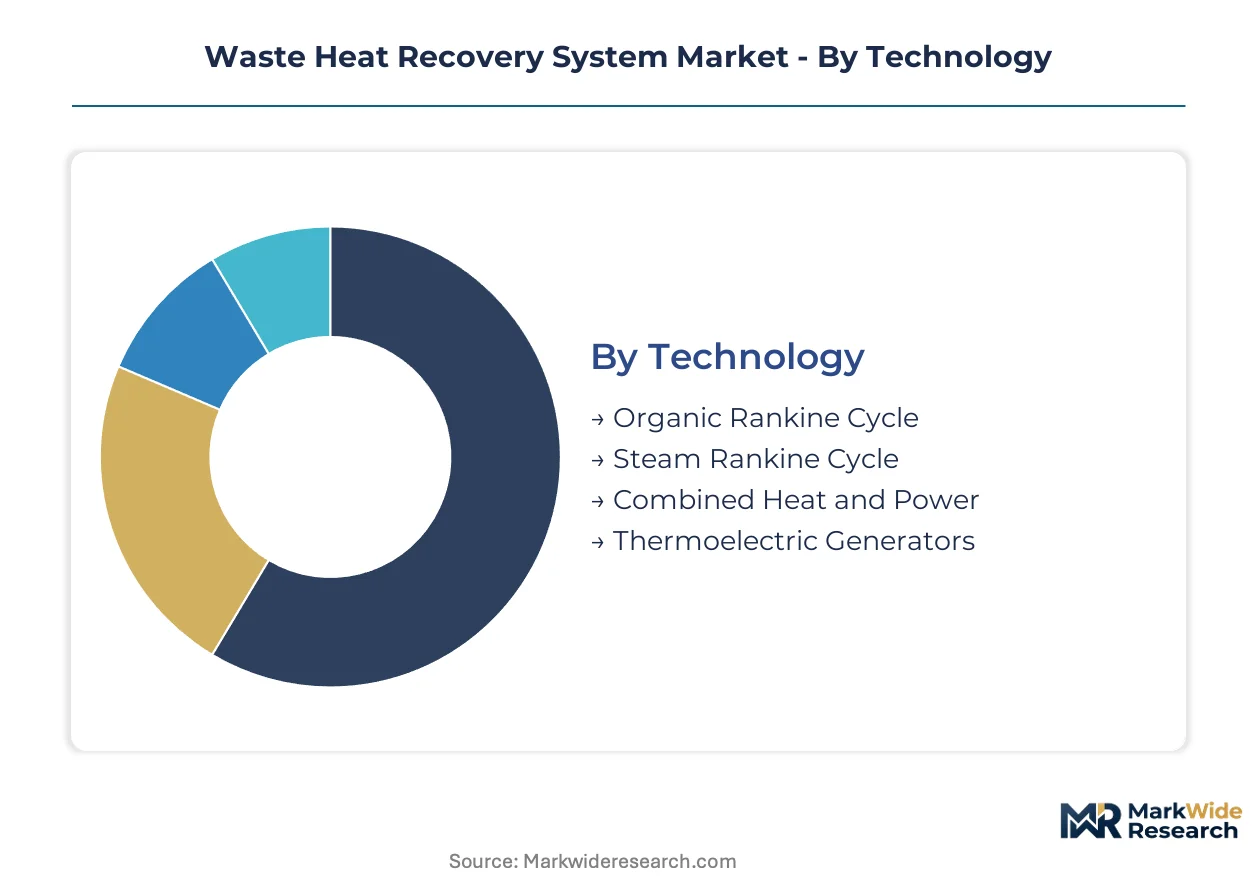
Technology selection determines working fluid chemistry, temperature range, and integration complexity across industrial settings. Application context shapes whether systems displace purchased electricity, feed process heat loops, or supply district networks. End-user sector dictates scale economics and regulatory exposure, while installation type governs margin profiles and engineering talent requirements.
Technology:
Organic Rankine Cycle systems command premium pricing for low-to-medium temperature flexibility, while Steam Rankine Cycle retains volume dominance through direct boiler integration in high-temperature settings.
- Organic Rankine Cycle:Silicone-based and hydrocarbon working fluids enable operation from 80°C to 300°C, displacing earlier refrigerant chemistries under EU F-Gas Regulation constraints. German steel and chemical complexes in the Rhine-Ruhr corridor anchor ORC deployments seeking to satisfy EU Green Deal lifecycle carbon accounting mandates.
- Steam Rankine Cycle:Saturated steam systems integrate directly with existing boiler infrastructure in cement and refinery settings above 300°C. Indian cement manufacturers expanding WHR installations favor SRC for kiln energy intensity reductions under tightening BIS standards.
- Combined Heat and Power:Captures thermal and electric output simultaneously for maximum energy utilization in integrated industrial facilities.
- Thermoelectric Generators:Solid-state conversion eliminates moving parts for remote or maintenance-constrained applications.
Today's leader: Steam Rankine Cycle. Tomorrow's challenger: Organic Rankine Cycle.
Application:
Industrial process integration generates the deepest retrofit pipelines, whereas power generation and district heating create divergent revenue models and offtake structures.
- Industrial Processes:Exhaust stream capture from kilns, furnaces, and crackers displaces fuel consumption directly at the point of use. Cement and steel producers in Germany and India concentrate procurement here under carbon accounting and energy efficiency mandates respectively.
- Power Generation:Standalone electricity output feeds grid connections or captive industrial loads, requiring distinct interconnection approvals and tariff structures.
- District Heating:Low-grade heat offtake from chemical complexes supplies urban networks in German industrial cities, opening new revenue streams beyond facility boundaries.
- Automotive:Exhaust heat recovery from internal combustion engines and hybrid powertrains addresses fuel economy regulations in passenger and commercial vehicle segments.
Industrial Processes anchor current deployment volumes. District Heating is climbing the fastest as urban energy planning accelerates.
End User:
Manufacturing and oil & gas sectors split the market between discrete production facilities and continuous process operations with contrasting heat source profiles.
- Manufacturing:Metal fabrication, glass production, and ceramics operations generate intermittent high-temperature exhaust requiring flexible recovery architectures.
- Oil & Gas:Refinery crackers and gas processing turbines produce steady high-grade heat streams ideal for SRC integration with existing steam systems.
- Chemical:Reactor off-gases and distillation columns yield medium-temperature sources suited to ORC deployment with silicone-based working fluids.
- Food & Beverage:Pasteurization and drying processes generate lower-temperature waste heat recoverable through compact ORC units.
Manufacturing captures the broadest segment breadth. Chemical is gaining share fastest as REACH compliance and carbon border pressures intensify.
Installation:
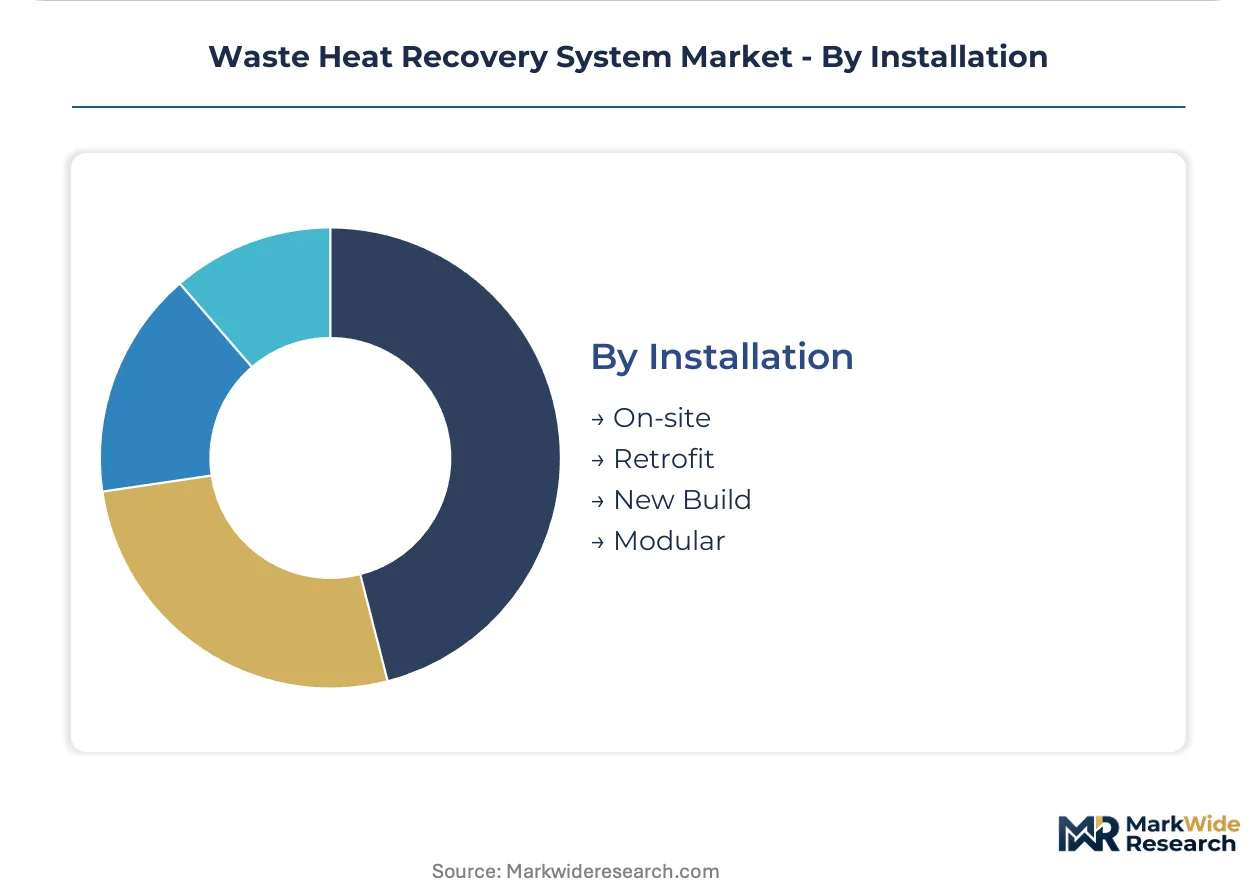
Retrofit engineering commands custom margins for legacy accommodation, while new-build and modular formats compete on standardization and deployment velocity.
- On-site:Permanent installations with dedicated civil works and utility connections maximize efficiency for anchor industrial facilities.
- Retrofit:Custom ducting design and space constraint accommodation require specialized mechanical engineers in short supply across European project pipelines, compressing margins but locking in long-term service relationships.
- New Build:Greenfield integration enables optimized layout and standardized equipment selection, reducing engineering overhead.
- Modular:Skid-mounted or containerized units accelerate deployment for capital-constrained buyers favoring heat-as-a-service contracting models.
Retrofit dominates value capture today. Modular formats show the steepest expansion trajectory as energy service company contracting displaces direct procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr industrial corridor anchors European deployment volumes for waste heat recovery systems, with steel and chemical complexes driving retrofit project pipelines under EU carbon accounting mandates.
Germany
Steel producers in the Rhine-Ruhr corridor and chemical complexes along the Rhine riverbank dominate procurement activity. The EU F-Gas Regulation accelerates working fluid transitions for Organic Rankine Cycle installations. Duisburg and Leverkusen industrial zones concentrate large-scale retrofit engineering contracts seeking compliance with EU Green Deal lifecycle emissions requirements.
India
Cement manufacturers expanding kiln waste heat recovery installations represent the fastest-growing demand segment. The BIS energy efficiency standards and PLI scheme for capital goods manufacturing enforce domestic content requirements. Gujarat and Rajasthan cement belts concentrate new-build WHR deployments as producers cut energy intensity under tightening national mandates.
United States
Refinery and petrochemical complexes along the Gulf Coast generate steady demand for high-temperature steam Rankine systems. The EPA enforces emissions thresholds under the Clean Air Act that indirectly compel efficiency investments. Texas and Louisiana industrial corridors anchor project activity where saturated steam integrates with existing boiler infrastructure.
China
Steel mills and non-ferrous smelters in the Yangtze River Delta and Pearl River Delta drive system adoption. The MIIT dual carbon goals and GB standards for industrial energy efficiency shape procurement patterns. Shanghai and Jiangsu province manufacturing clusters concentrate deployments as state-owned enterprises retrofit legacy facilities.
Japan
Power generation equipment suppliers and integrated steelworks anchor steady demand for advanced heat exchanger technologies. The METI industrial decarbonization roadmap and JIS standards for energy recovery equipment guide technology selection. Chubu and Kansai industrial regions concentrate deployments where aerospace-derived recuperator designs transfer to stationary gas turbine applications.
Waste Heat Recovery System Market Vendor Landscape
Global majors compete with regional champions across technology integration depth and local engineering presence. The market structure splits between diversified industrial conglomerates with turbine expertise and specialized heat recovery engineering firms with captive power co-generation capabilities. Three archetypes dominate: integrated energy technology providers, localized industrial boiler specialists, and ORC system pure-plays. Competitive moves concentrate on strategic partnerships for working fluid chemistry transitions and geographic expansion through energy service company contracting models.
Among diversified industrial technology providers, Siemens Energy and General Electric exemplify scale-driven positions leveraging turbine integration heritage, while Thermax Limited occupies a specialized tier focused on localized engineering and captive power offerings in high-growth Asian markets. Turboden S.p.A. represents the ORC pure-play archetype with concentrated expertise in low-to-medium temperature applications. These anchors illustrate how competitive positioning splits between breadth-driven technology integration and depth-focused thermal engineering specialization.
| Leading Market Players |
|---|
| ABB |
| Bosch Industriekessel GmbH |
| Siemens Energy |
| Forbes Marshall |
| IHI Corporation |
| Mitsubishi Power, Ltd. |
| Turboden S.p.A. |
| Thermax Limited |
| General Electric |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between aerospace-derived recuperator systems and standard alloy heat exchangers manifests in both pricing premiums and supply chain sourcing strategies. German steel producers command tier-one pricing for ceramic composite designs while Indian cement manufacturers anchor volume procurement through localized boiler-grade fabricators.
Pricing Analysis
Input-cost pass-through from nickel and cobalt alloy markets destabilizes heat exchanger economics for high-temperature ceramic composite designs. Three-tier pricing structure across premium aerospace-recuperator, standard alloy-tubular, and economy modular-skid levels differentiates by certification grade and after-sales service bundling. Cost compression in economy modular formats is intensifying because Indian PLI scheme domestic content requirements compress margins for non-localized suppliers. Cement manufacturers in Gujarat and Rajasthan exhibit highest price sensitivity, while German chemical complexes along the Rhine-Ruhr corridor absorb premiums for REACH-compliant working fluid integration.
Supply Chain Analysis
Advanced alloy supply rests on German specialty steel producers, Japanese precision metal fabricators, and Indian domestic foundries scaling under PLI incentives. Heat exchanger manufacturing draws from nickel superalloy feedstock, ceramic composite precursors, and silicone-based working fluid chemistries. Single-source vulnerability concentrates in aerospace-derived recuperator technology licensed from turbine OEMs. Distribution runs through EPC contractors anchoring large-scale retrofit projects in industrial corridors, with modular skid formats bypassing traditional channel structures through direct energy service company contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with the EU F-Gas Regulation's accelerated refrigerant phase-down creating non-discretionary replacement demand across European heavy industry.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Siemens Energy and Turboden S.p.A. should accelerate hydrocarbon and silicone-based working fluid recertification to preempt F-Gas Regulation compliance gaps. Backward integration into heat exchanger alloy supply buffers nickel price volatility threatening ceramic composite margins. Channel control through heat-as-a-service contracting locks in long-term retrofit relationships as Indian cement producers shift procurement models. For New Entrants and Emerging Players: Capital-constrained mid-size chemical producers in Germany's secondary industrial zones represent the most penetrable buyer archetype. These facilities lack in-house engineering bandwidth for custom ducting design but face EU Green Deal lifecycle carbon accounting mandates. A white-space target emerges in modular ORC skids with pre-engineered integration packages. Go-to-market execution should anchor on performance-guaranteed contracting that transfers operational risk from balance-sheet-constrained buyers. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized retrofit engineering talent scarcity compresses project execution timelines across European pipelines. Long-term viability favors technology providers with captive working fluid chemistry portfolios and established energy service company contracting infrastructure. Acquisition targets should display concentrated expertise in low-to-medium temperature ORC applications with silicone-based fluid integration. Watch F-Gas Regulation implementation synchronization across EU member states as the inflection indicator for spare parts inventory valuation and multi-jurisdiction certification pathway economics.| Strategic Initiative | Industry Significance |
|---|---|
| Working Fluid Chemistry Transition | Equipment recertification for hydrocarbon and silicone-based alternatives accelerates under EU F-Gas Regulation constraints. |
| Heat-as-a-Service Contracting | Energy service company models displace direct procurement among capital-constrained Indian cement and German steel producers. |
| Retrofit Engineering Talent Acquisition | Custom ducting design capabilities lock in long-term service relationships across European project pipelines. |
| Modular Skid Standardization | Containerized formats accelerate deployment velocity for mid-size chemical complexes lacking in-house engineering bandwidth. |
| Carbon Border Adjustment Preparation | Export-oriented Indian cement producers invest in WHR retrofits to preserve EU market access under emerging trade rules. |
Methodological Framework
Multiple input streams — primary interviews with plant engineers, EPC contractors, and aftermarket service heads; secondary validation through customs data, SEC filings, and IEA industrial efficiency reports; and technical specification databases — were reconciled through bottom-up and top-down triangulation. Plant engineers at cement and steel facilities provided operational performance benchmarks. EPC contractors disclosed project pipeline timelines and retrofit engineering capacity constraints. Aftermarket service heads detailed spare parts inventory planning and working fluid transition schedules. Secondary sources included trade flow data for heat exchanger alloy inputs, utility regulatory filings, and industrial energy efficiency program disclosures.
Data-stream reconciliation anchored the analytical framework across technology type, temperature grade, installation format, and regional regulatory cluster. Segmentation dimensions modeled included Organic Rankine Cycle versus Steam Rankine Cycle technology, retrofit versus new-build installation, and industrial corridor concentration. CAGRs were derived from installed base growth trajectories and replacement cycle timing. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down schedules and India's PLI scheme capital goods manufacturing incentives.
Underlying measurement precision varies by segment; Steam Rankine Cycle deployments in cement and refinery settings carry tighter precision than emerging supercritical CO2 pilot installations. Forecasts reflect assumptions regarding regulatory implementation timelines and alloy price stabilization. Working fluid chemistry transition delays, carbon border adjustment mechanism adoption rates, and retrofit engineering talent availability constitute primary revision triggers. A small set of regulatory implementation schedules, alloy commodity price movements, and energy service company contracting penetration rates warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Efficiency Solutions
Residential Energy-Efficient Technologies Market
Energy Efficiency Solutions
Energy Efficiency Gamification Market
Energy Efficiency Solutions
Energy Retrofits Market
Energy Efficiency Solutions
Energy Efficient Windows Market
Energy Efficiency Solutions
Economizer Market
Energy Efficiency Solutions
Energy Retrofit Systems Market
Energy Efficiency Solutions
Energy Efficient Lighting Market
Energy Efficiency Solutions
Energy Efficient Warehouse Lighting System Market
Energy Efficiency Solutions
Global Energy Efficient Lamps and Ballasts Market
Energy Efficiency Solutions
Energy Efficient Lighting Technology Market
Energy Efficiency Solutions
Residential Air to Water Heat Pump Market
Energy Efficiency Solutions
Heat Pump Water Heater Market
Energy Efficiency Solutions
Energy-Saving Constant Humidity Storage Cabinet Market