
 Power Analyzers Market | 2026-2036
Power Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Power Analyzers Market Outlook
EU F-Gas Regulation is pivoting the competitive calculus for power analyzer vendors serving industrial refrigeration and HVAC system integrators. Yokogawa Electric Corporation leverages its heritage in precision measurement to dominate calibration-intensive segments across European metrology labs. Hioki E.E. Corporation anchors its position through deep specialization in portable field instruments for electrical maintenance teams. Keysight Technologies differentiates via R&D intensity in high-frequency digital sampling architectures for semiconductor fabrication power monitoring.
Power analyzers are precision electrical measurement instruments that quantify voltage, current, power factor, harmonic distortion, and energy consumption across single-phase and three-phase systems, typically operating from DC to multi-megahertz bandwidths with accuracy classes down to 0.01%. Their primary purpose centers on verifying power quality compliance, optimizing energy efficiency, and certifying electrical equipment performance against IEC and IEEE standards. Three-phase analyzers command the largest installed base in heavy industrial automation applications where motor drive diagnostics and transformer load balancing generate recurring demand. Portable units represent the fastest-expanding category as maintenance departments shift from centralized bench testing toward distributed, point-of-use power quality verification.
FDA 21 CFR Part 11, EU MDR electromagnetic compatibility requirements, and IEC 61000-4-30 power quality measurement standards collectively tighten the specification envelope for analyzers deployed in regulated manufacturing environments. These frameworks compel vendors to embed traceable calibration certificates, tamper-evident data logging, and Class A measurement compliance as baseline market-access requirements. Stakeholders must weigh the accelerating convergence of wireless connectivity and smart grid protocols against the cybersecurity certification burden that now accompanies networked power instrumentation procurement decisions.
Market Dynamics
Grid modernization mandates across industrial economies are compressing replacement cycles for legacy power quality instrumentation while simultaneously elevating cybersecurity requirements for networked measurement systems. This dual pressure is fragmenting procurement authority between plant engineering departments and corporate IT security functions.
Growth Catalysts
- IEC 61000-4-30 Class A compliance:European heavy industry faces mandatory power quality documentation for grid connection agreements, forcing analyzer upgrades across German automotive stamping plants and French aluminum smelters.
- Semiconductor fabrication expansion:Advanced node chip manufacturing in Taiwan and South Korea requires sub-cycle harmonic monitoring for precision voltage regulation, creating specialized demand for high-bandwidth analyzers.
- Industrial heat pump electrification:The EU F-Gas Regulation's refrigerant phaseout timeline is accelerating HVAC system retrofits, each requiring pre- and post-installation power signature verification.
Market Restraints
- Precision resistor supply concentration:Bulk metal foil and wirewound resistor production concentrates in Eastern European and Japanese specialty component houses, exposing analyzer manufacturers to 18-24 month allocation cycles.
- Calibration infrastructure scarcity:National metrology institutes in emerging industrial economies lack traceable 50 ppm power reference standards, limiting market access for premium accuracy tiers.
- Software-defined instrument substitution:High-speed digitizers paired with PC-based analysis platforms threaten mid-range standalone analyzer volumes in R&D environments.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for electronic components and industrial automation are attracting analyzer assembly investments to Gujarat and Tamil Nadu industrial corridors.
- Wireless sensor fusion:Convergence of IEEE 802.11ah (HaLow) industrial Wi-Fi with power analyzer front-ends enables distributed monitoring without dedicated cabling infrastructure.
- Data center PUE certification:Colocation providers in Singapore and Ireland now require continuous power quality logging for LEED and BREEAM compliance, opening subscription-based monitoring contracts.
Industry Challenges
- Embedded firmware security certification:IEC 62443 industrial cybersecurity standards impose 12-18 month validation timelines for networked analyzers, delaying product releases.
- Field calibration skill scarcity:Maintenance organizations lack technicians trained in three-phase system analysis and harmonic decomposition, constraining portable analyzer utilization rates.
- Legacy SCADA integration friction:Proprietary Modbus and DNP3 implementations in 1990s-era plant control systems resist seamless connection to modern analyzer data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Analyzers Market |
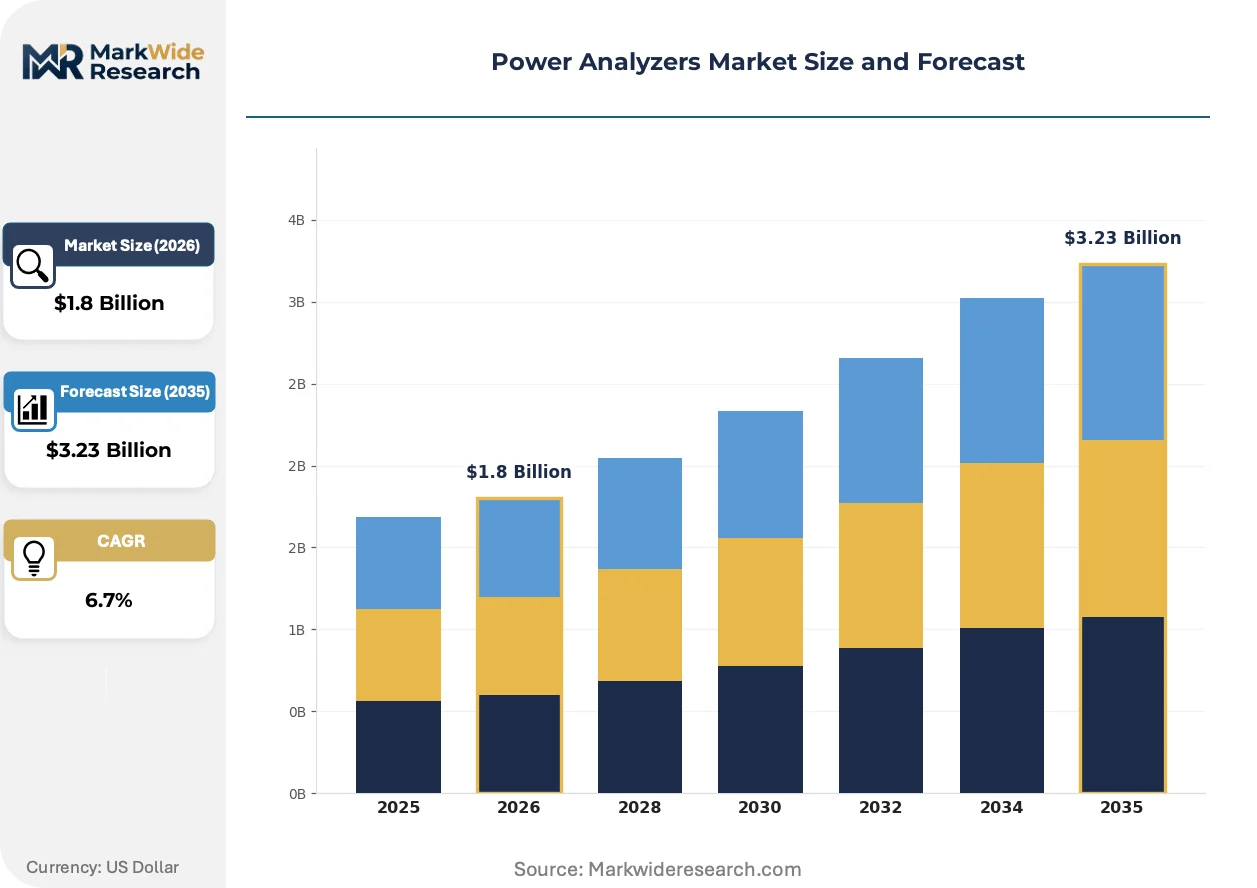
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Portable, Bench-Top Application: Industrial Automation, Energy Measurement, Equipment Testing, Research & Development End User: Manufacturers, Utilities, Laboratories, Educational Institutions Technology: Analog, Digital, Wireless, Smart |
| Companies Covered | Fluke Corporation, Yokogawa Electric Corporation, Hioki E.E. Corporation, Tektronix, Dranetz Technologies, Keysight Technologies, Rohde & Schwarz, PCE Deutschland GmbH, Chroma ATE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Analyzers Market Strategic Shifts
Measurement hardware architectures are fragmenting into specialized subsystems optimized for either laboratory precision or field ruggedness, with software layers absorbing the integration burden. This bifurcation is compressing development timelines while expanding addressable application scope.
Digital sampling front-end hardware is modularizing around interchangeable input conditioning cards. Analyzer vendors now ship chassis with swappable voltage and current modules spanning millivolt-level leakage detection to kilovolt distribution monitoring. Automotive battery test labs in Germany and Japan are adopting this architecture to repurpose single instruments across cell cycling, pack validation, and inverter efficiency mapping. The approach is modularizing what were previously discrete product lines into configurable platforms.
The EU F-Gas Regulation's 2024 tightening of hydrofluorocarbon quotas is mandating refrigerant conversion audits for commercial refrigeration systems. System integrators must document pre- and post-retrofit compressor power signatures to claim efficiency incentives. This compliance workflow is driving portable analyzer rentals through industrial equipment distributors in France, Italy, and Poland rather than capital purchases.
Service contract unbundling is disrupting traditional analyzer revenue models. End-users in North American oil and gas facilities now procure hardware through capital budgets while purchasing calibration and firmware update subscriptions through operating expenditure channels. Equipment lessors and third-party metrology laboratories are capturing the recurring service margin that manufacturers previously retained.
Power Analyzers Market Segmentation
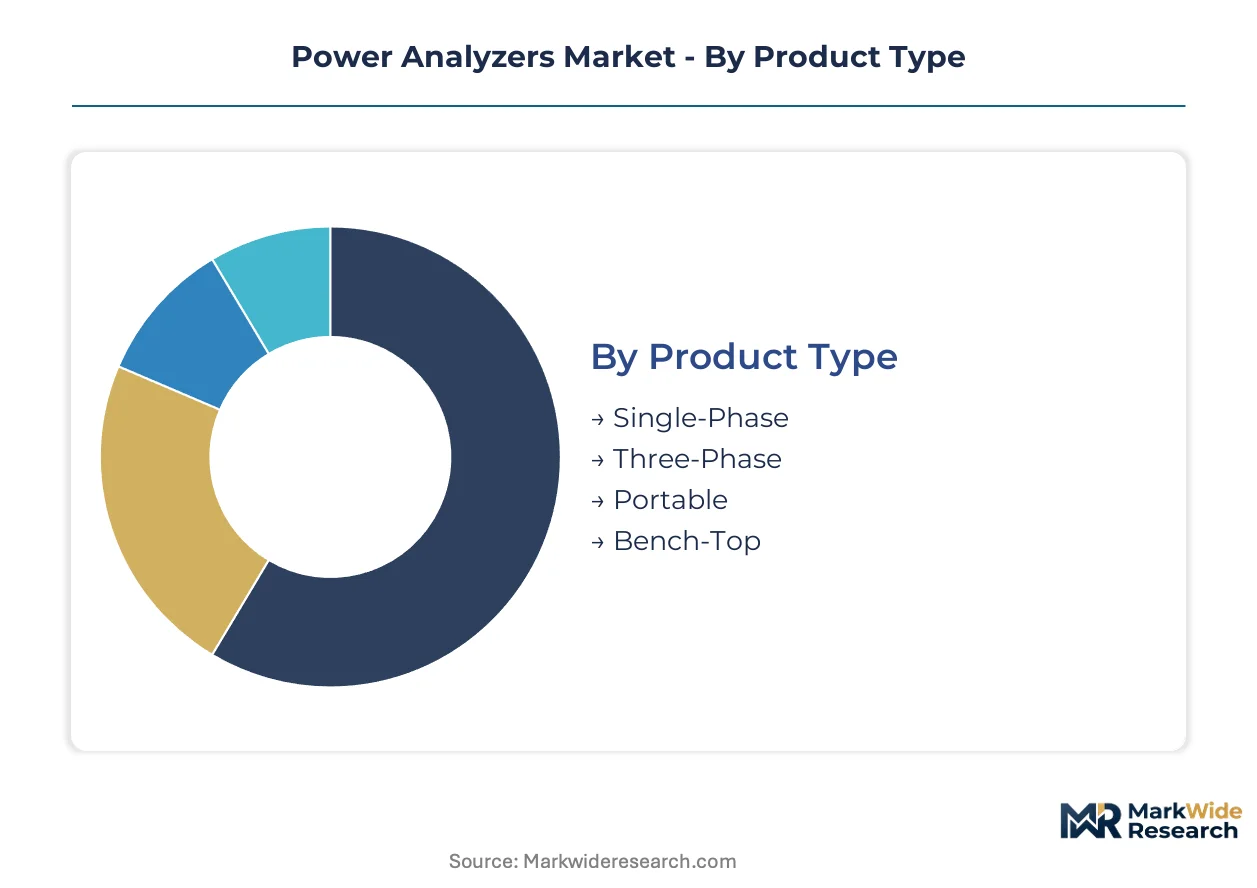
Power analyzer segmentation reflects divergent procurement priorities between precision laboratory environments and distributed industrial maintenance operations. Vendors must configure hardware architectures, connectivity protocols, and service models to match distinct accuracy requirements and deployment contexts across each category.
Product Type:
Customization intensity varies sharply across this category, from configurable modular platforms to fixed-function portable units.
- Three-Phase:These instruments measure voltage, current, and power parameters across three-phase electrical systems with accuracy classes down to 0.01%, incorporating harmonic analysis and transient capture capabilities. Demand concentrates in German automotive stamping plants and French aluminum smelters where IEC 61000-4-30 Class A compliance is mandatory for grid connection agreements. Leading the category by volume: Three-Phase. Growing fastest: Portable.
- Portable:Battery-powered field instruments with ruggedized enclosures and wireless data logging enable point-of-use power quality verification without bench infrastructure. Maintenance departments at US oil refineries and Japanese steel mills are shifting from centralized testing toward distributed deployment models, compressing replacement cycles for legacy bench equipment.
- Single-Phase:Compact analyzers for residential and light commercial applications measure voltage, current, and power factor on single-phase circuits. These instruments dominate residential solar inverter commissioning workflows in Australia and residential heat pump installations in Scandinavia.
- Bench-Top:Laboratory-grade systems with isolated inputs and programmable automation interfaces serve calibration laboratories and semiconductor test floors. Taiwan's advanced node chip fabrication facilities require these units for sub-cycle harmonic monitoring in precision voltage regulation applications.
Three-Phase units generate the highest absolute revenue. Portable configurations are expanding most quickly as maintenance organizations decentralize testing protocols.
Application:
Margin profiles diverge across this category based on certification requirements and replacement frequency.
- Industrial Automation:Motor drive diagnostics, transformer load balancing, and conveyor system efficiency verification consume the largest installed base of three-phase analyzers. German factory automation investments and Japanese robotics manufacturing lines generate recurring demand for harmonic distortion analysis and power factor correction validation.
- Equipment Testing:Pre-shipment verification of electrical equipment against IEC and IEEE standards requires traceable calibration certificates and tamper-evident data logging. This application commands premium pricing tiers due to regulatory documentation burdens.
- Energy Measurement:Utility-grade revenue metering and sub-metering for commercial building management systems utilize analyzers with revenue-grade accuracy certifications. India's PLI scheme for electronic components is attracting assembly investments to serve this segment domestically.
- Research & Development:High-bandwidth sampling architectures for power electronics development face substitution pressure from software-defined instruments using high-speed digitizers paired with PC-based analysis platforms.
Industrial Automation anchors category volume. Equipment Testing delivers the steepest margin expansion.
End User:
Procurement authority fragmentation shapes vendor engagement models across this category.
- Utilities:Grid modernization programs in the US and EU are compressing replacement cycles for legacy power quality instrumentation while elevating cybersecurity requirements. FERC interconnection standards and EU F-Gas Regulation compliance workflows drive analyzer procurement for substation monitoring and distributed energy resource integration.
- Manufacturers:Industrial electrification investments in automotive, steel, and chemical processing require pre- and post-retrofit power signature verification. FDA 21 CFR Part 11 and EU MDR electromagnetic compatibility requirements tighten specification envelopes for regulated manufacturing environments.
- Laboratories:National metrology institutes and third-party calibration houses demand traceable 50 ppm power reference standards, limiting market access for vendors lacking calibration infrastructure partnerships.
- Educational Institutions:University engineering programs and vocational training centers procure entry-level analyzers for curriculum deployment, with procurement concentrated in India's technical education expansion and German dual vocational training systems.
Utilities dominate capital expenditure volumes. Manufacturers are gaining the fastest procurement momentum through electrification mandates.
Technology:
Architecture maturity determines competitive differentiation pathways across this category.
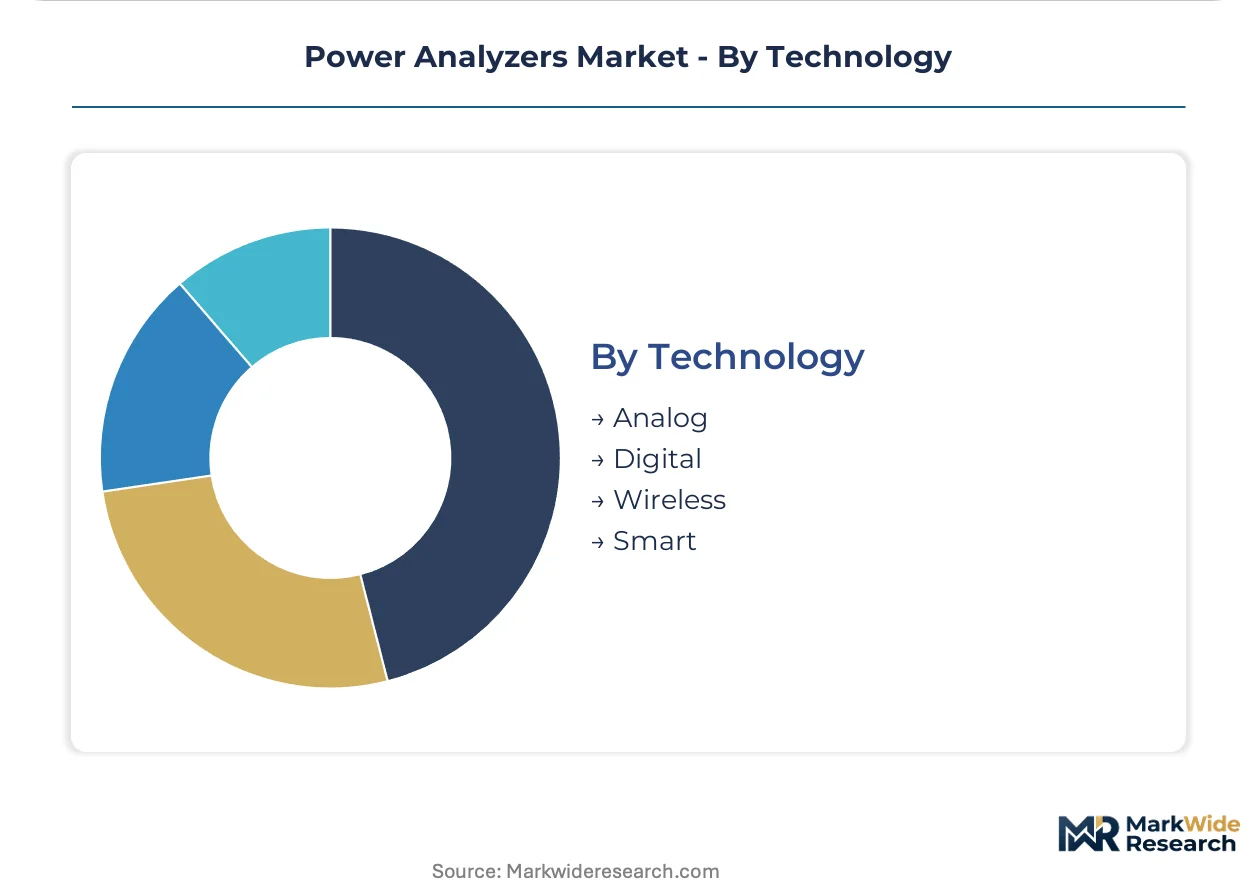
- Digital:High-speed sampling front-ends with FPGA-based real-time processing and software-configurable measurement algorithms now dominate new installations. These architectures enable modular input conditioning cards spanning millivolt-level leakage detection to kilovolt distribution monitoring.
- Smart:Embedded edge computing with IEEE 802.11ah (HaLow) industrial Wi-Fi connectivity enables distributed monitoring without dedicated cabling infrastructure. Singapore and Ireland data center operators deploy these for continuous PUE certification and LEED compliance logging.
- Wireless:Battery-powered sensor nodes with mesh networking protocols serve temporary monitoring applications in hazardous environments where cabling is impractical. IEC 62443 cybersecurity certification imposes validation timelines that delay product releases in this segment.
- Analog:Legacy electromechanical measurement circuits persist in cost-sensitive applications and environments with extreme electromagnetic interference where digital susceptibility is prohibitive.
Digital platforms command the largest installed base. Smart configurations are climbing the fastest as grid modernization elevates connectivity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronic components and industrial automation has concentrated assembly investments in Gujarat and Tamil Nadu industrial corridors. This tax-incentive architecture is reshaping procurement patterns for precision instrumentation across emerging manufacturing hubs.
Germany
Industrial electrification investments in automotive stamping plants and aluminum smelters drive analyzer procurement. The EU F-Gas Regulation mandates refrigerant conversion audits requiring pre- and post-retrofit power signature verification. Bavaria's factory automation clusters and North Rhine-Westphalia's steel processing corridors anchor the heaviest installed base of three-phase instrumentation.
United States
Grid modernization programs at utilities compress replacement cycles for legacy power quality instrumentation. FERC interconnection standards elevate cybersecurity requirements for networked measurement systems. Texas oil refineries and Gulf Coast petrochemical facilities are shifting toward distributed portable analyzer deployment models.
Japan
Advanced node semiconductor fabrication in Kyushu and Chubu requires sub-cycle harmonic monitoring for precision voltage regulation. METI industrial policy supports domestic production of high-bandwidth sampling architectures. Kansai robotics manufacturing lines generate recurring demand for motor drive diagnostics and power factor correction validation.
Taiwan
TSMC-led chip fabrication expansion creates specialized demand for laboratory-grade bench-top systems with isolated inputs. IEC 61000-4-30 Class A compliance is mandatory for grid connection agreements at science park facilities. Hsinchu Science Park and Tainan Technology Industrial Park concentrate the most sophisticated power quality monitoring infrastructure.
Power Analyzers Market Competitive Environment
Japanese producers anchor one tier; German specialists hold precision calibration segments. The vendor structure fragments across three accuracy tiers rather than consolidating around volume leaders. Strategic archetypes include heritage metrology houses, field-rugged portable specialists, and high-frequency sampling architects. Dominant competitive moves involve modular hardware platformization and service contract unbundling into subscription revenue streams.
Within the heritage precision tier, Yokogawa Electric Corporation and Hioki E.E. Corporation exemplify the calibration-intensive laboratory-to-field spectrum. Keysight Technologies occupies a position representing high-frequency digital sampling specialization for semiconductor fabrication monitoring. These three anchors demonstrate how technical differentiation in bandwidth, accuracy class, and environmental ruggedness stratifies competitive positioning more than geographic scale.
| Leading Market Players |
|---|
| Fluke Corporation |
| Yokogawa Electric Corporation |
| Hioki E.E. Corporation |
| Tektronix |
| Dranetz Technologies |
| Keysight Technologies |
| Rohde & Schwarz |
| PCE Deutschland GmbH |
| Chroma ATE |
| Others |
Value Chain & Pricing Dynamics
German automotive OEM procurement teams and EU utility engineering departments concentrate demand for IEC 61000-4-30 Class A certified units, anchoring a project-based pricing model where certification tier and calibration traceability determine contract value more than unit volume.
Pricing Analysis
Short lead-time premiums of 15-25% apply to portable analyzer orders from US oil refineries and Japanese steel mills facing unplanned maintenance windows. Three-tier pricing structure across premium laboratory-grade, standard industrial, and economy portable tiers separates 0.01% accuracy class bench systems from 0.5% field units. Cost compression in the standard industrial tier is intensifying because modular hardware platforms reduce differentiation between vendors. Maintenance departments at distributed facilities show highest price sensitivity; semiconductor fabrication labs show lowest.
Supply Chain Analysis
Precision resistor supply rests on Eastern European and Japanese specialty component houses, with bulk metal foil and wirewound production cycles extending 18-24 months. FPGA-based sampling front-ends draw from Taiwan and South Korea semiconductor foundries, while ruggedized enclosure manufacturing sources from China and Mexico. Single-source vulnerability in 50 ppm power reference standards limits premium accuracy tier production scaling. Distribution runs through industrial equipment distributors in France, Italy, and Poland for portable rentals, direct OEM sales for laboratory systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital sampling architectures with FPGA-based real-time processing are displacing legacy analog electromechanical circuits, compressing product lifecycles and forcing vendor repositioning across accuracy tiers.
For Market Incumbents: Extend calibration infrastructure partnerships into India's Gujarat and Tamil Nadu industrial corridors before PLI scheme incentives attract modular platform competitors. Backward integration into precision resistor supply buffers allocation cycle exposure. Certification investment in IEC 62443 cybersecurity standards defends against software-defined instrument substitution in R&D environments.
For New Entrants and Emerging Players: Launch via wireless sensor fusion offerings targeting Singapore and Ireland data center PUE certification contracts, where subscription-based monitoring contracts replace capital purchases. India's technical education expansion presents the most penetrable white-space for entry-level analyzer procurement. Channel partnership with industrial equipment lessors captures recurring service margin without manufacturing scale.
For Investors and Strategic Acquirers: The window for entry favors heritage metrology houses with captive calibration laboratory networks and established traceability to national standards. Long-term viability hinges on firmware update subscription attach rates exceeding 60% of installed base. Watch IEC 61000-4-30 Class A mandate expansion beyond EU heavy industry as the inflection signal for premium tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Hardware Platformization | Swappable input cards enable single chassis deployment across German automotive battery test labs. |
| Calibration Service Unbundling | Separate subscription revenue streams capture North American oil and gas operating expenditure budgets. |
| IEC 62443 Cybersecurity Certification | Validation timelines delay product releases but secure utility procurement authority against IT security objections. |
| Wireless Sensor Fusion Development | IEEE 802.11ah integration eliminates dedicated cabling infrastructure for distributed monitoring applications. |
| Backward Integration into Precision Components | In-house resistor production insulates against 18-24 month allocation cycles from Eastern European suppliers. |
Study Parameters
Document review covered SEC 10-K filings from listed instrumentation vendors, IEC and IEEE standards documentation, and EU F-Gas Regulation implementation guidance, complemented by interviews with plant engineering directors at German automotive stamping facilities, maintenance managers at US oil refineries, procurement leads from French aluminum smelters, and calibration laboratory technical directors. Secondary validation drew from customs trade data for precision electrical components, national metrology institute capability directories, and utility grid modernization program disclosures. Bottom-up unit demand estimates and top-down market sizing triangulated across primary and secondary sources.
Installed base projections and revenue forecasts across the analysis window reflect segmentation by product type, application, end user, and technology architecture. The modeling framework incorporated harmonic analysis bandwidth requirements, semiconductor fabrication expansion timelines, and industrial heat pump electrification retrofit schedules as industry-specific demand drivers. CAGRs were derived from regression analysis of historical replacement cycles against regulatory mandate acceleration curves.
Tariff exposure on Chinese-sourced FPGA modules, precision resistor allocation extensions beyond 24 months, and IEC 61000-4-30 mandate adoption delays in emerging economies are the dominant revision risks to forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
South America Nuclear Power Plant Equipment Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Wind Turbine Maintenance Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
Clean Steam Separator Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Asia-Pacific Steam Turbine Market
Power Equipment
Romania Power EPC Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
Chad Power EPC Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
China Power EPC Market