
 G-3 PLC Solutions Market | 2026-2036
G-3 PLC Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
G-3 PLC Solutions Market Foresight
Copper wiring in legacy I/O modules is restructuring G-3 PLC product economics as fiber-optic and industrial Ethernet interfaces gain share in high-speed process environments. Siemens AG leverages its embedded safety firmware portfolio to dominate railway and energy verticals. ABB Ltd. anchors its position through in-house production of AC500-series processors with integrated cybersecurity stacks. Schneider Electric differentiates via EcoStruxure architecture spanning edge controllers to cloud analytics layers.
G-3 PLC solutions are industrial-grade programmable logic controllers engineered for deterministic control with scan cycles below 10 milliseconds, executing ladder logic or structured text across modular backplanes with redundant power and communication paths. Their primary purpose is synchronizing multi-axis machinery, batch processes, and safety interlocks in continuous-operation facilities. Compact PLCs capture the fastest expansion as OEMs embed them directly inside standalone machines rather than centralized rack configurations. EtherNet/IP and PROFIBUS DP remain the dominant fieldbus protocols, though AS-Interface is gaining ground in sensor-level cost-sensitive applications where wiring minimization outweighs bandwidth needs.
The US Department of Energy enforces efficiency standards through FERC Order 2222 that incentivize grid-edge automation, directly expanding PLC deployment in utility infrastructure. Germany's KBA and BSI mandate functional safety certification under ISO 13849 for automotive assembly lines, forcing controller vendors to maintain dual-channel safety PLC portfolios. Japan's METI promotes Smart Factory adoption through JIS-compliant open architectures, reshaping procurement patterns toward interoperable systems. Stakeholders must monitor how cybersecurity labeling requirements evolve across these jurisdictions, as compliance cost asymmetries will redistribute margin pools between integrated platform vendors and specialized component suppliers.
Market Dynamics
The migration from copper-wired I/O modules to fiber-optic and industrial Ethernet interfaces is compressing product economics and forcing controller vendors to absorb legacy support costs while accelerating stack integration.
Growth Catalysts
- FERC Order 2222:The US Department of Energy efficiency standards incentivize grid-edge automation, directly expanding PLC deployment across utility substations and distributed energy resources.
- Semiconductor fabricators:Advanced node manufacturers near Seoul and Pyeongtaek are accelerating adoption of sub-10ms scan cycle controllers for precision wafer handling and vacuum process coordination.
- EU AI Act compliance:Industrial cybersecurity mandates in Germany require connected automation systems to maintain audit trails and risk management frameworks, pulling replacement demand forward.
Market Restraints
- Copper input volatility:Legacy I/O module production remains tethered to copper wiring costs, creating margin compression as fiber-optic alternatives scale.
- South Korean supply concentration:Advanced manufacturing demand clusters around the Seoul-Pyeongtaek corridor, creating geographic dependency risk for component suppliers.
- ISO 13849 certification friction:Germany's KBA and BSI mandates force dual-channel safety PLC portfolios, elevating R&D overhead for mid-tier vendors.
Strategic Opportunities
- Compact PLC embedding:OEMs are embedding controllers directly inside standalone machines rather than centralized rack configurations, opening machine-level retrofit markets.
- AS-Interface sensor networks:Cost-sensitive applications where wiring minimization outweighs bandwidth needs are expanding the addressable base for simplified fieldbus architectures.
- METI Smart Factory procurement:Japan's push for JIS-compliant open architectures reshapes procurement patterns toward interoperable systems, favoring modular stack vendors.
Industry Challenges
- Functional safety engineering scarcity:Dual-channel safety PLC development requires certified engineers, constraining vendor capacity to meet German automotive line mandates.
- Legacy system integration complexity:EtherNet/IP and PROFIBUS DP coexistence demands protocol gateway expertise, extending deployment timelines for brownfield facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | G-3 PLC Solutions Market |
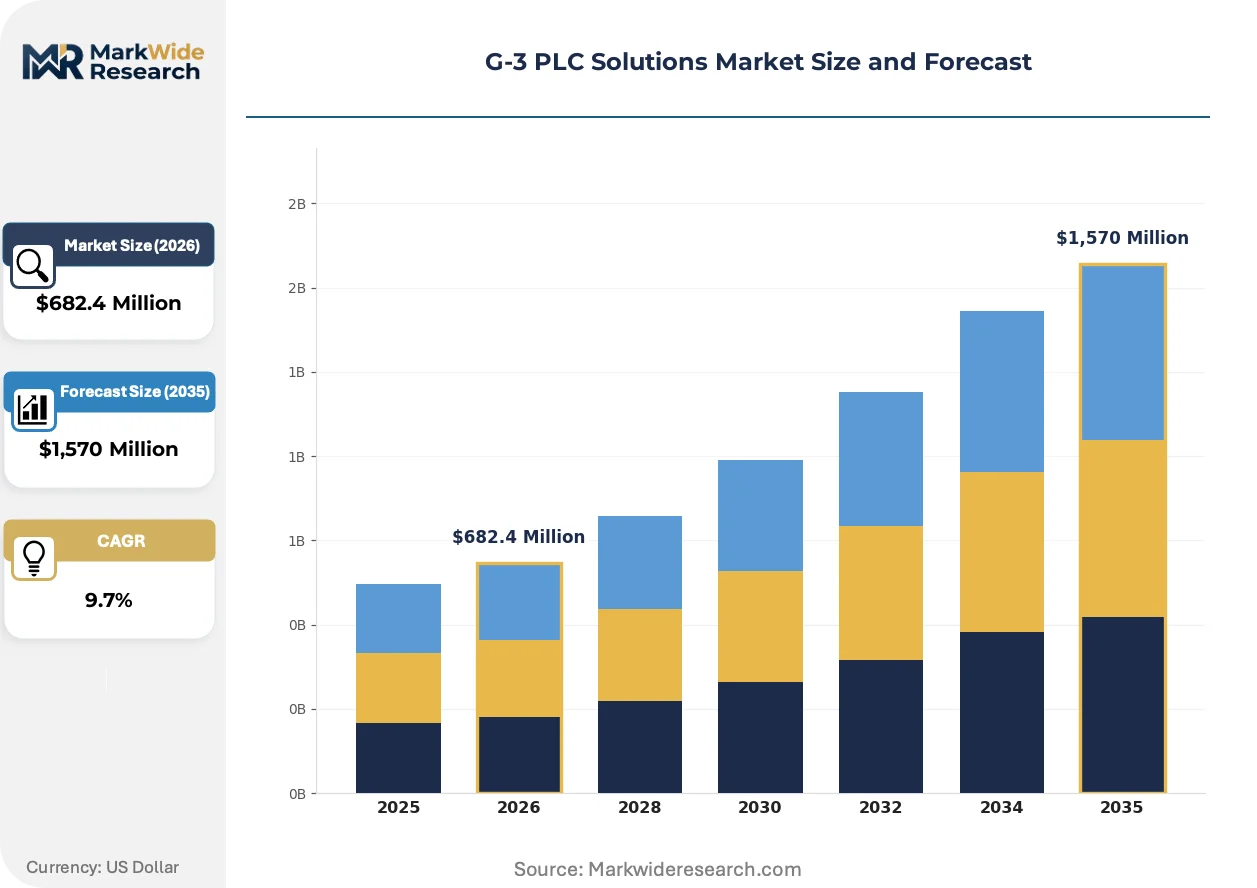
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,570 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular PLC, Compact PLC, Rack-Mounted PLC, Programmable Automation Controller, Safety PLC Technology: EtherNet/IP, Modbus TCP, Profibus DP, DeviceNet, ControlNet, AS-Interface Application: Process Automation, Machine Control, Building Management, Infrastructure Automation, Automotive Assembly, Packaging End User: Manufacturing Plants, Chemical Processing Units, Food & Beverage Facilities, Water Treatment Centers, Semiconductor Fabricators |
| Companies Covered | Siemens AG, ABB Ltd., Schneider Electric, General Electric, Rockwell Automation Inc., Hitachi Ltd., Mitsubishi Electric Corporation, Honeywell International Inc., Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
G-3 PLC Solutions Market Shifts & Advancements
Ethernet-based deterministic control is collapsing the traditional separation between field-level devices and enterprise systems, forcing architectural redesigns across three concurrent vectors.
Time-Sensitive Networking (TSN) extensions over standard Ethernet is unifying motion control and safety traffic onto single cable infrastructure. Automotive assembly lines in Germany and semiconductor fabs in South Korea are adopting TSN-enabled controllers to eliminate separate fieldbus networks. This convergence is unifying previously siloed engineering teams and compressing system integration timelines by removing protocol translation layers.
The EU AI Act's risk classification framework for industrial automation systems is mandating documented algorithmic transparency and human oversight protocols. Machinery OEMs shipping into European markets must now embed logging capabilities and fail-safe mechanisms that exceed traditional functional safety standards. Compact PLC architectures face the steepest compliance burden, as edge devices must now host audit-grade telemetry without compromising deterministic scan performance.
Machine builders are consolidating supplier relationships around platform vendors who deliver controller hardware, safety firmware, and cloud analytics through unified subscription frameworks. The traditional model of discrete component procurement from specialized vendors is contracting in favor of vertically integrated stacks. This consolidation is most visible in South Korea's advanced manufacturing corridor, where fab operators prioritize single-source accountability for uptime guarantees.
G-3 PLC Solutions Market Segmentation
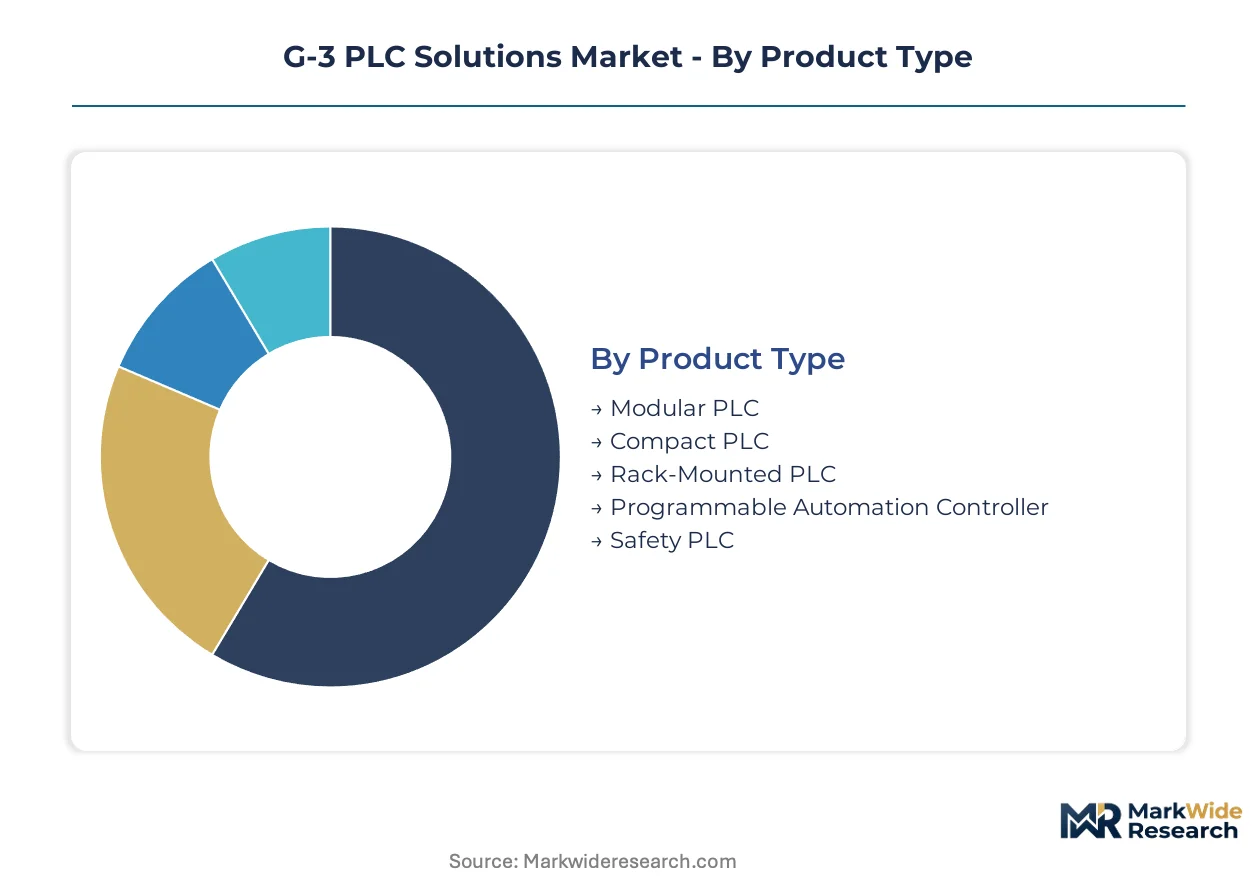
Controller architecture determines integration complexity and lifecycle economics for automation deployments. Segment selection dictates protocol compatibility, safety certification requirements, and supplier consolidation strategies across industrial verticals.
Product Type:
Form factor and modularity define installation topology and maintenance accessibility across facility types.
- Modular PLC:Hot-swappable I/O cards and redundant processor configurations support continuous-operation environments. Demand clusters in chemical processing units along Germany's Rhine-Ruhr industrial belt, where ISO 13849-certified safety interlocks are mandatory for hazardous material handling.
- Compact PLC:Integrated CPU-I/O-power units mount directly inside standalone machinery. OEMs embedding these controllers into packaging equipment and material handling systems drive the steepest expansion trajectory, particularly among South Korean machine builders serving semiconductor fabricators.
- Rack-Mounted PLC:Centralized backplane architectures accommodate high-density I/O for large-scale process plants. Water treatment centers in the US deploy these for SCADA integration under FERC Order 2222 grid-edge automation mandates.
- Programmable Automation Controller:Hybrid architectures merge PLC determinism with PC-based analytics. Food and beverage facilities leverage these for batch recipe management and traceability compliance.
- Safety PLC:Dual-channel redundant logic executes SIL-rated emergency stops and interlocks. Automotive assembly lines in Germany require these under KBA functional safety directives.
Mature deployment sits with rack-mounted PLC architectures in centralized control rooms. Newer deployment is concentrated in compact PLC embedding for distributed machine-level intelligence.
Technology:
Communication protocol selection determines cabling infrastructure, bandwidth allocation, and real-time determinism for motion control applications.
- EtherNet/IP:Standard Ethernet physical layer with CIP application protocol enables IT/OT convergence. Manufacturing plants in Japan adopt these under METI Smart Factory procurement guidelines favoring open architectures.
- Profibus DP:Decentralized peripheral protocol dominates European automotive assembly through deterministic cycle times under 10 milliseconds. German OEMs maintain this installed base despite migration pressures.
- Modbus TCP:Simplified register-based communication suits cost-sensitive building management retrofits. Water treatment centers deploy these for pump station monitoring.
- DeviceNet:CAN-based fieldbus persists in legacy machine control networks. Packaging machinery OEMs support this protocol for backward compatibility.
- ControlNet:Scheduled token-passing architecture guarantees deterministic performance for motion control. Chemical processing units retain these for safety-critical batch sequences.
- AS-Interface:Two-wire bus topology minimizes sensor-level cabling. Expanding most quickly in cost-sensitive discrete manufacturing where wiring reduction outweighs bandwidth constraints.
Protocol diversity reflects generational investment patterns. EtherNet/IP and AS-Interface are gaining share fastest as greenfield deployments prioritize IT convergence and wiring minimization.
Application:
Use-case requirements differentiate scan cycle demands, environmental hardening, and safety integrity levels.
- Process Automation:Continuous flow control with sub-second loop execution dominates chemical processing and water treatment. These installations demand redundant controllers and hardened enclosures for corrosive environments.
- Machine Control:Discrete manufacturing sequences with sub-10ms response times coordinate multi-axis servo systems. Semiconductor fabricators near Seoul and Pyeongtaek drive precision requirements for wafer handling.
- Building Management:HVAC and lighting control prioritize energy efficiency over deterministic performance. FERC Order 2222 incentives accelerate PLC deployment in US utility-scale building automation.
- Infrastructure Automation:Traffic systems and power distribution require extended temperature ranges and vibration resistance. Grid-edge applications expand under distributed energy resource integration.
- Automotive Assembly:Welding, painting, and final trim lines mandate safety PLC architectures. Germany's KBA enforces ISO 13849 certification for all new line installations.
- Packaging:High-speed carton forming and palletizing demand compact PLC embedding. OEMs integrate these directly into machinery to reduce panel footprint.
Process automation represents the largest installed base by controller count. Machine control exhibits the fastest technology refresh cycles as semiconductor capital expenditure accelerates.
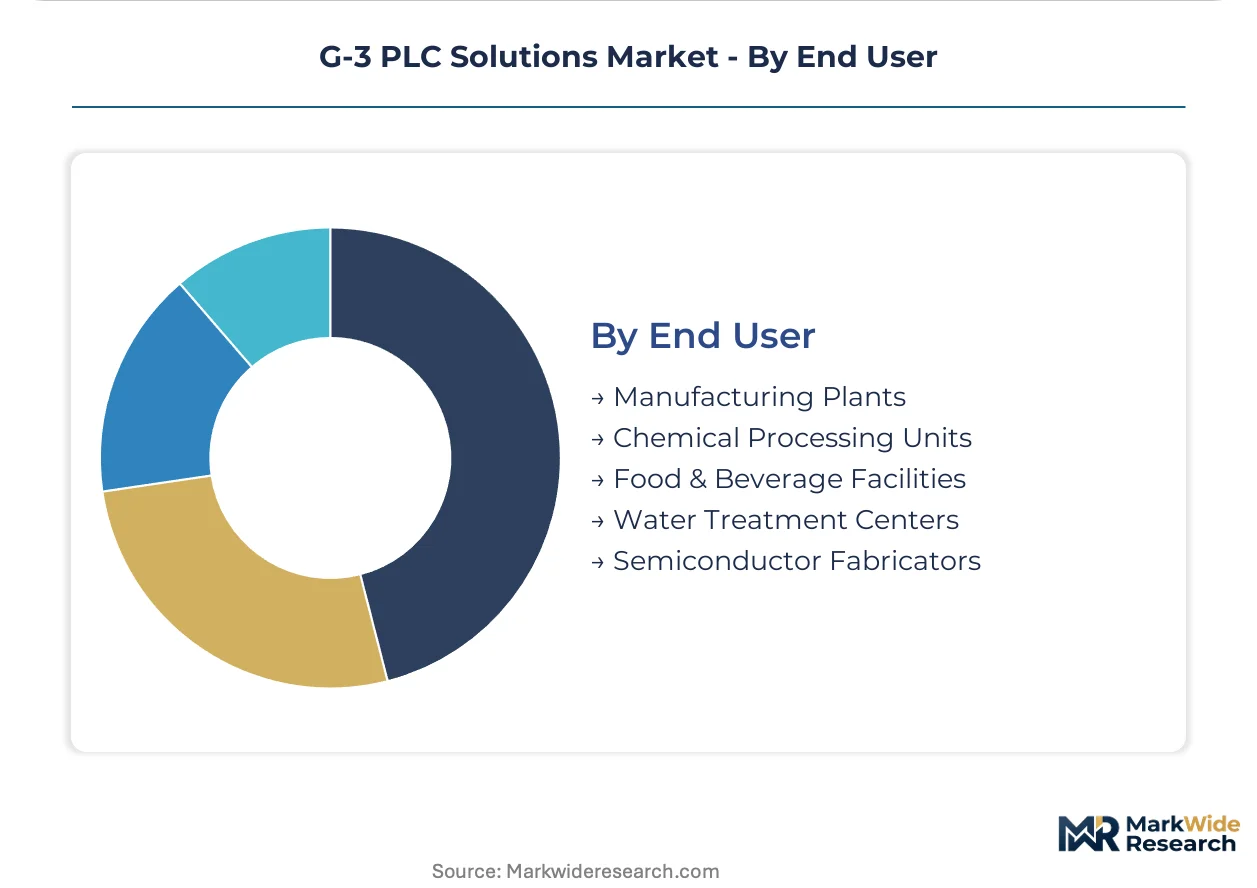
End User:
Facility type determines regulatory exposure, uptime requirements, and supplier relationship structures.
- Manufacturing Plants:Discrete and batch production facilities span automotive, electronics, and consumer goods. METI Smart Factory adoption in Japan reshapes procurement toward interoperable, open-architecture systems.
- Chemical Processing Units:Hazardous area classifications mandate explosion-proof enclosures and safety instrumented systems. Germany's BSI cybersecurity mandates add compliance layers for connected controllers.
- Food & Beverage Facilities:Hygienic washdown requirements dictate stainless steel enclosures and sealed connectors. Recipe traceability drives adoption of PAC architectures with integrated historians.
- Water Treatment Centers:Distributed pump stations and filtration systems require ruggedized controllers with wide temperature specifications. US Department of Energy efficiency standards incentivize automation upgrades.
- Semiconductor Fabricators:Cleanroom environments and vacuum process coordination demand ultra-reliable controllers with sub-10ms scan cycles. South Korean fabs near Seoul and Pyeongtaek concentrate advanced node investment.
Established penetration characterizes manufacturing plants and chemical processing. Semiconductor fabricators command the most demanding specification requirements and fastest replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabricators in South Korea and automotive assembly lines in Germany concentrate the most demanding G-3 PLC specifications. Utility infrastructure in the United States and process automation in Japan follow distinct procurement patterns shaped by national energy and industrial policies.
United States
Grid-edge automation projects expand PLC deployment across utility substations and distributed energy resources. FERC Order 2222 mandates efficiency standards that incentivize automation upgrades at the distribution network periphery. Water treatment centers in the Midwest deploy rack-mounted controllers for SCADA integration under these federal directives.
Germany
Automotive welding and painting lines require dual-channel safety PLC architectures with SIL-rated emergency stops. KBA and BSI enforce ISO 13849 functional safety certification for all new assembly installations. Chemical processing units along the Rhine-Ruhr industrial belt demand redundant controllers for hazardous material handling with explosion-proof enclosures.
South Korea
Advanced node semiconductor manufacturers near Seoul and Pyeongtaek drive demand for sub-10 millisecond scan cycle controllers. METI-equivalent industrial policy accelerates Smart Factory adoption through procurement guidelines favoring interoperable systems. Cleanroom environments and vacuum process coordination command the fastest technology refresh cycles in the Asia-Pacific region.
Japan
Discrete manufacturing facilities adopt EtherNet/IP controllers under METI Smart Factory procurement guidelines promoting open architectures. JIS-compliant interoperability standards reshape vendor selection toward modular stack suppliers. Kansai and Chubu industrial corridors concentrate machine control applications for precision component fabrication.
United Kingdom
Food and beverage facilities deploy programmable automation controllers for batch recipe management and traceability compliance. CSRD-aligned sustainability reporting pressures drive automation investments in energy-intensive processing plants. Packaging machinery OEMs in the Midlands embed compact PLCs directly into carton forming equipment.
G-3 PLC Solutions Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing premium-tier contracts while component suppliers serve retrofit markets. The vendor base clusters around three archetypes: diversified industrial conglomerates with embedded safety firmware portfolios, pure-play automation specialists with modular architectures, and regional system integrators with protocol gateway expertise. Consolidation pressures favor vertically integrated stacks over discrete component procurement. M&A activity targets cybersecurity stack capabilities, while capacity expansion concentrates in South Korean and German manufacturing corridors.
Among diversified industrial conglomerates, Siemens AG and ABB Ltd. occupy positions exemplifying the integrated platform archetype, bundling controller hardware with safety firmware and cloud analytics through unified frameworks. Schneider Electric anchors the European specialist tier with architecture spanning edge controllers to enterprise layers. These three entities represent the dominant competitive positioning as machine builders consolidate supplier relationships around single-source accountability for uptime guarantees.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Schneider Electric |
| General Electric |
| Rockwell Automation Inc. |
| Hitachi Ltd. |
| Mitsubishi Electric Corporation |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Others |
Supply & Pricing Matrix
EU AI Act risk classification for industrial automation gates both qualified component supply and premium-tier controller pricing access. Semiconductor fabricators and automotive OEMs now pay compliance premiums for audit-grade telemetry capabilities embedded at the edge.
Pricing Analysis
High-volume compact PLC shipments split from safety-certified modular systems on margin structure. Three-tier pricing structure across premium SIL-rated, standard industrial-grade, and economy sensor-level controllers separates certification depth. ISO 13849 dual-channel validation commands 40-60% premiums over single-channel equivalents in German automotive procurement. Price erosion runs through copper-wired legacy I/O modules as fiber-optic alternatives scale. OEM machine builders exhibit highest price sensitivity; semiconductor fabs show lowest due to uptime guarantee requirements.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific component hubs compresses margin on rack-mounted PLC shipments to European process plants. Controller manufacturing concentrates in Germany, South Korea, and Japan. Silicon wafer supply for embedded processors draws from Taiwan and South Korea; copper and rare earth magnet sourcing rests on Chinese refining capacity. Single-source vulnerability sits with advanced node semiconductor supply for safety PLC processors. Distribution runs through authorized system integrator networks with certified engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethernet-based deterministic control is displacing legacy fieldbus architectures, forcing vendor consolidation around unified platform stacks. TSN-enabled controllers now unify motion and safety traffic previously handled by separate networks.
For Market Incumbents: Deepen embedded safety firmware capabilities to defend against modular stack vendors attacking German automotive lines. Acquire cybersecurity audit trail specialists before EU AI Act enforcement tightens. Expand captive silicon supply partnerships in South Korea to secure processor allocation for sub-10ms scan cycle controllers.
For New Entrants and Emerging Players: Direct-to-fab engineering services offer low-capital entry into South Korean semiconductor corridor maintenance contracts. Target AS-Interface retrofit markets in cost-sensitive discrete manufacturing where wiring minimization outweighs brand preference. Lead with subscription-based remote diagnostics to bypass incumbent distributor relationships.
For Investors and Strategic Acquirers: KBA safety certification backlog is the leading indicator that dual-channel safety PLC engineering capacity will command scarcity premiums. Position for 5-10 year holding periods as platform consolidation eliminates discrete component vendors. Watch for TSN controller adoption inflection in Japanese METI Smart Factory procurement announcements.
| Strategic Initiative | Industry Significance |
|---|---|
| TSN Controller Platform Launch | Unifies motion and safety traffic for German automotive welding lines seeking cable reduction. |
| Safety Firmware Acquisition | Captures ISO 13849-certified engineering teams scarce in European automation labor markets. |
| South Korean Manufacturing Footprint | Positions for sub-10ms scan cycle demand from Seoul-Pyeongtaek semiconductor fabricators. |
| Cybersecurity Stack Integration | Addresses EU AI Act audit trail mandates exceeding traditional functional safety standards. |
| AS-Interface Channel Partnership | Opens cost-sensitive sensor-level markets where wiring minimization drives procurement decisions. |
Research Methodology
Independent corroboration across plant engineers at semiconductor fabricators, automation procurement leads at German automotive OEMs, and system integrator technical directors underwrites the qualitative findings. Primary fieldwork encompassed maintenance directors, OEM procurement teams, and aftermarket service heads at industrial equipment deployers. Secondary validation drew from SEC filings of listed automation vendors, customs records for PLC component trade flows, and FERC grid-edge automation deployment databases. Bottom-up bill-of-materials costing and top-down vendor revenue triangulation anchored market size estimates.
Comparable historical adoption curves for fieldbus-to-Ethernet transitions anchored the projection framework across the analysis window. Segmentation modeling spanned controller architecture, communication protocol, application vertical, and regional regulatory cluster dimensions. CAGRs derived from fitted S-curves against technology substitution patterns. Forecast inputs incorporated semiconductor capital expenditure cycles and METI Smart Factory procurement timelines.
The model holds under sustained EU AI Act enforcement and stable Asia-Pacific component logistics; deviation in tariff regimes or rare earth export restrictions would shift replacement demand timing. Forecasts embed assumptions regarding TSN standardization velocity and safety engineering labor availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Australia Power EPC Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Wind Turbine Bolts Market
Power Equipment
Digital Power Conversion Market
Power Equipment
Air Preheater Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Wind Turbine Components Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
United States Turbine Control Systems Market
Power Equipment
SCR Power Controller Market
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Power Equipment Testing Market
Power Equipment
United States Power Rental Market