
 Asia-Pacific Fluoropolymer Market | 2026-2036
Asia-Pacific Fluoropolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fluoropolymer Market Insights
Semiconductor equipment buyers is collapsing the once-dominant share held by general chemical processors across the Asia-Pacific fluoropolymer market. Daikin Industries leverages its captive PTFE resin capacity in Japan to serve wafer fabrication tool OEMs with ultra-high-purity grades. Gujarat Fluorochemicals anchors its competitive position through backward integration into fluorspar mining and captive hydrofluoric acid production in India. AGC Inc differentiates via fluorinated ethylene propylene films engineered for extreme ultraviolet lithography chamber linings.
Asia-Pacific fluoropolymers comprise carbon-fluorine backbone polymers, typically synthesized through free-radical polymerization of tetrafluoroethylene and comonomers under precisely controlled pressure-temperature regimes, yielding materials with dielectric constants below 2.1 and continuous service temperatures exceeding 260°C for critical insulation and barrier applications. PTFE retains the largest volume position across the region yet faces margin compression as Chinese producers expand commodity-grade powder output, while PFA captures premium pricing in semiconductor fluid handling where metallic ion contamination must remain below ten parts per billion. ETFE film applications in photovoltaic module front sheets represent the fastest-expanding demand pool, though the segment remains sub-scale relative to incumbent industrial coatings.
Japan's METI enforces fluorocarbon emission caps under its revised Fluorocarbons Recovery and Destruction Law, compelling domestic producers to shift toward low-global-warming-potential polymerization chemistries, while China's MEE implements stricter per- and polyfluoroalkyl substance discharge standards affecting fluoropolymer manufacturing effluent in the Yangtze River Delta. India's BIS certification requirements for fluoropolymer products used in food contact and potable water applications create non-tariff barriers for unqualified imports. Stakeholders must weigh regulatory compliance costs against the technical switching barriers that protect incumbent suppliers in semiconductor-grade segments.
Market Dynamics
Semiconductor-grade fluoropolymer procurement is concentrating in East Asian fabrication clusters, compressing lead times and forcing resin suppliers to co-locate purification facilities near wafer tool OEM assembly plants.
Growth Catalysts
- China's dual carbon goals:The MEE enforces stricter per- and polyfluoroalkyl substance discharge standards in the Yangtze River Delta, compelling manufacturers to adopt low-GWP fluoropolymer alternatives.
- Photovoltaic module assembly:ETFE film demand for front-sheet applications is accelerating as module producers seek lighter, more durable encapsulation materials.
- Extreme ultraviolet lithography:Wafer fabrication facilities across South Korea and Taiwan are expanding chamber lining specifications to FEP films engineered for sub-7nm process nodes.
Market Restraints
- Fluorspar supply concentration:Captive mining operations in China and Mexico control upstream feedstock, exposing processors to concentrate price volatility and export quota fluctuations.
- Japan's Fluorocarbons Recovery and Destruction Law:METI emission caps force domestic producers to retool polymerization chemistries, adding compliance capex without immediate revenue offset.
- Perfluoroalkoxy alkane substitution ceiling:PFA metallic ion contamination thresholds below ten parts per billion create technical barriers that commodity PTFE cannot breach, segmenting the addressable market.
Strategic Opportunities
- India's BIS certification gaps:Unqualified imports face non-tariff barriers in food contact and potable water applications, creating first-mover advantage for certified domestic production.
- Hydrogen fuel cell stack sealing:Proton exchange membrane manufacturers are specifying fluorinated ionomers for high-pressure sealing interfaces in heavy-duty vehicle platforms.
- Thailand's Eastern Economic Corridor:Board of Investment incentives for advanced materials manufacturing are attracting compounders to serve ASEAN automotive wire harness demand.
Industry Challenges
- High-purity resin synthesis talent:Semiconductor-grade fluoropolymer production requires process engineers with plasma etch chamber contamination control expertise, a skill set concentrated in Japan and South Korea.
- Multi-jurisdiction certification timelines:Simultaneous BIS, JIS, and GB standard compliance for pan-Asia-Pacific product launches extends qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fluoropolymer Market |
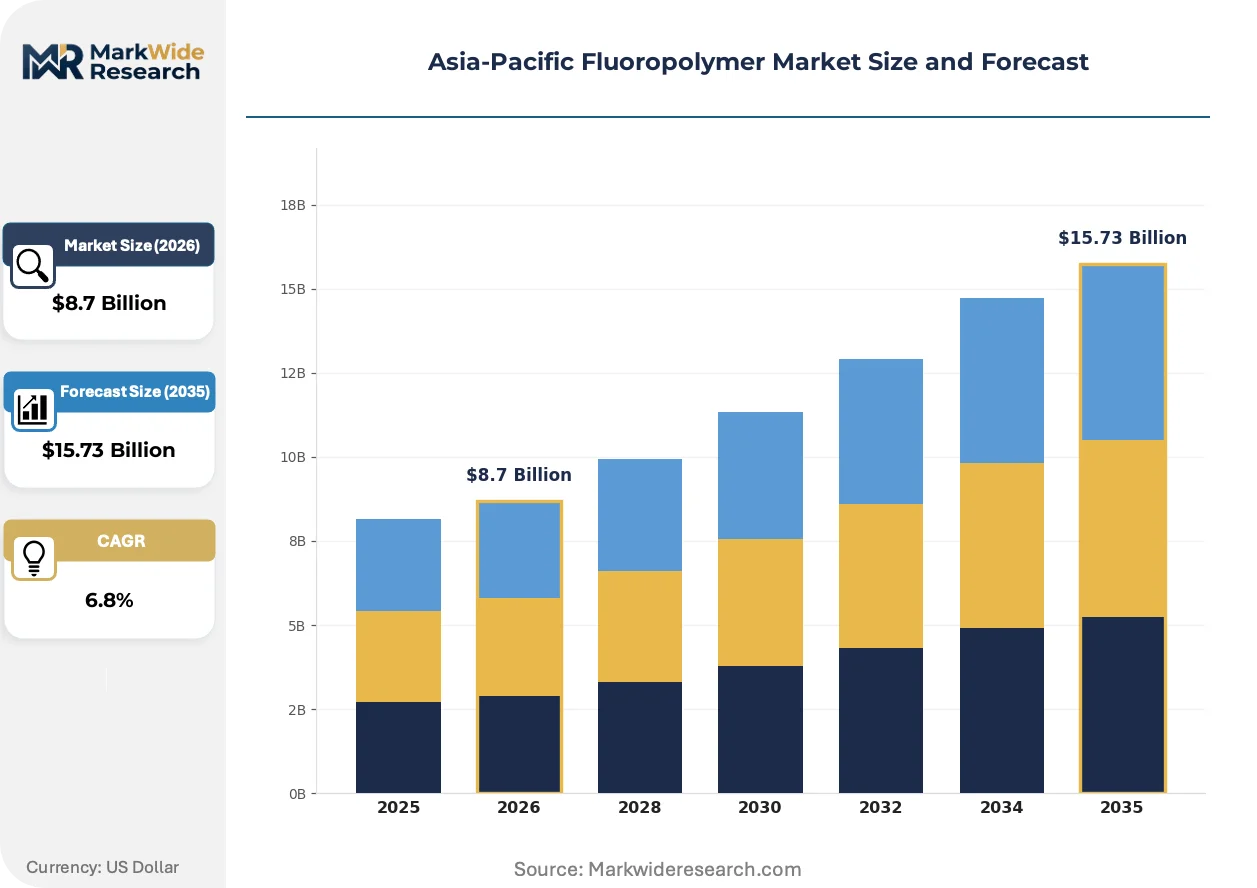
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, ETFE End Use Industry: Aerospace, Automotive, Electronics, Chemicals Form: Powder, Film, Coating, Rod Application: Insulation, Sealing, Non-stick Coating, Gaskets |
| Companies Covered | Daikin Industries Ltd, Arkema, Solvay, Gujarat Fluorochemicals Limited, Dongyue Group, The Chemours Company, 3M Company, Kureha Corporation, AGC Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fluoropolymer Market Trends and Innovations
Fluoropolymer material science is bifurcating between commodity powder grades and ultra-high-purity specifications, with synthesis control and contamination detection becoming the primary axes of supplier differentiation.
Modified perfluoroalkoxy resins with tailored melt-flow indices are miniaturizing fluid handling component geometries in semiconductor wet process equipment. Tool OEMs in Hsinchu and Pyeongtaek are specifying sub-millimeter tolerance injection molded parts for high-density wafer cleaning stations. This dimensional compression is miniaturizing manifold assemblies while maintaining chemical inertness, reducing tool footprint by 30-40% in advanced packaging lines.
China's MEE is implementing stricter effluent discharge standards for per- and polyfluoroalkyl substances in the Yangtze River Delta manufacturing corridor. Fluoropolymer producers with captive wastewater treatment and closed-loop polymerization systems are capturing preferential operating permits. The semiconductor-grade segment is responding by segregating high-purity production lines from commodity operations to prevent cross-contamination liability.
Wafer fabrication facilities are consolidating fluoropolymer component suppliers from 12-15 qualified vendors to 4-6 strategic partners with co-located technical service teams. Direct mill-to-tool supply agreements are displacing regional distributor networks in Taiwan and South Korea. This channel compression is most visible in 300mm fab greenfield projects, where tool OEMs negotiate three-year resin supply locks during equipment procurement.
Asia-Pacific Fluoropolymer Market Segmentation
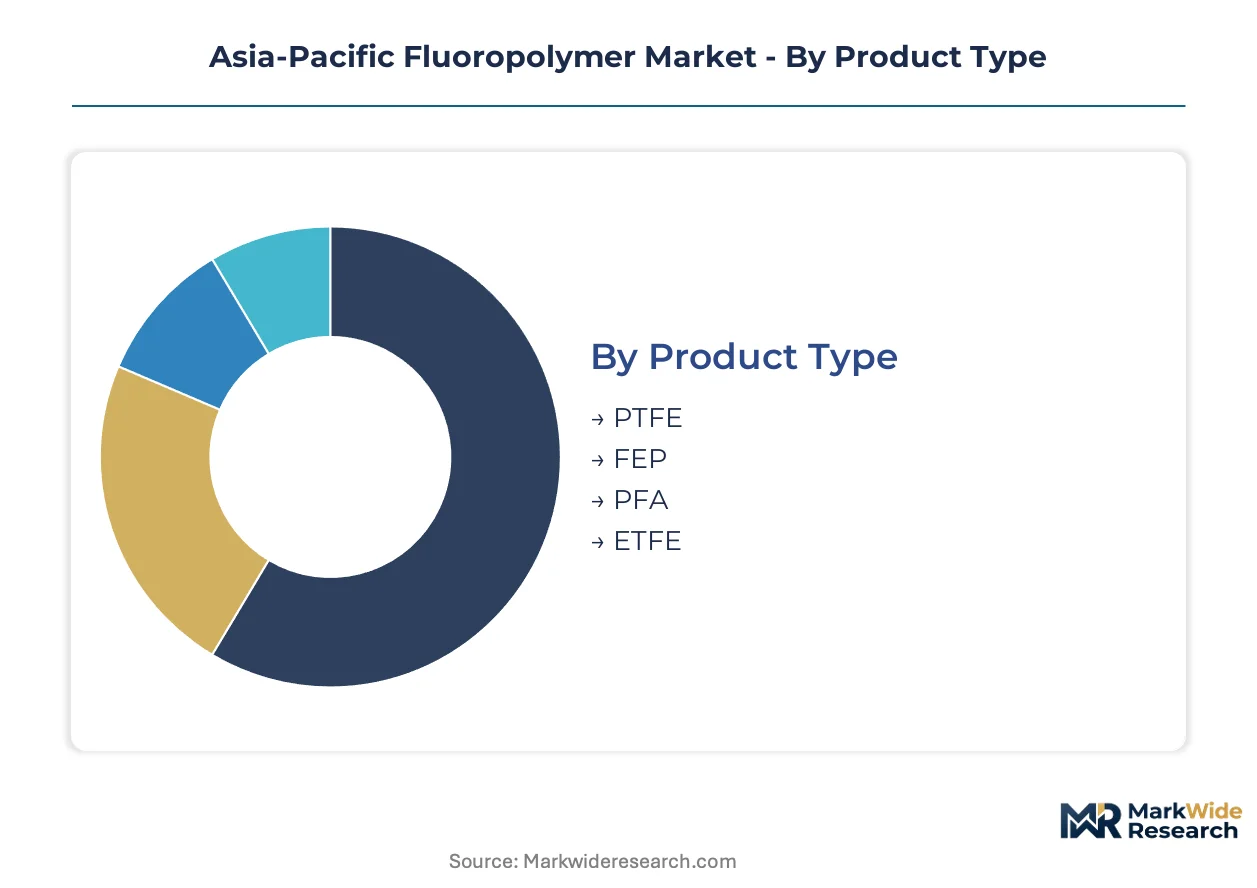
Fluoropolymer procurement patterns across Asia-Pacific diverge sharply by purity grade and end-use criticality. Semiconductor tool OEMs impose contamination thresholds that commodity grades cannot satisfy, forcing suppliers to maintain parallel production lines with segregated purification protocols.
Product Type:
Substitution pressure from lower-cost engineering polymers intensifies for commodity fluoropolymer grades, while ultra-high-purity specifications remain protected by technical switching barriers.
- PTFE:Polytetrafluoroethylene retains the largest volume position through its carbon-fluorine backbone structure delivering dielectric constants below 2.1 and continuous service temperatures exceeding 260°C. Demand concentrates in China's eastern coastal provinces where chemical processing clusters dominate procurement, though margin compression accelerates as domestic producers expand commodity-grade powder output.
- PFA:Perfluoroalkoxy alkane captures premium pricing in semiconductor fluid handling applications where metallic ion contamination must remain below ten parts per billion. Wafer fabrication facilities across South Korea and Taiwan are consolidating suppliers for this grade, forcing resin producers to co-locate purification facilities near tool OEM assembly plants.
- FEP:Fluorinated ethylene propylene serves extreme ultraviolet lithography chamber linings with sub-7nm process node compatibility. AGC Inc engineers specialized films for this specification.
- ETFE:Ethylene tetrafluoroethylene film demand accelerates in photovoltaic module front-sheet applications as producers seek lighter encapsulation materials.
PTFE retains volume leadership; ETFE holds the steepest expansion curve.
End Use Industry:
Customer procurement power varies dramatically across end-use segments, with semiconductor equipment buyers extracting three-year supply locks during greenfield fab construction.
- Electronics:Semiconductor fabrication facilities across East Asia are expanding orders for high-purity fluoropolymer components, compressing qualified vendor lists from 12-15 suppliers to 4-6 strategic partners with co-located technical service teams.
- Chemicals:General chemical processors face collapsing share as electronics buyers capture supplier attention, though China's dual carbon goals and MEE stricter emissions enforcement sustain demand for low-GWP alternatives in the Yangtze River Delta.
- Automotive:Proton exchange membrane manufacturers specify fluorinated ionomers for hydrogen fuel cell stack sealing interfaces in heavy-duty vehicle platforms.
- Aerospace:Wire harness insulation specifications in Thailand's Eastern Economic Corridor attract compounders serving ASEAN procurement.
Electronics commands supplier priority; automotive presents the most rapid demand acceleration.
Form:
Processing method determines achievable purity levels and geometric precision, with injection molding reaching sub-millimeter tolerances unavailable to powder sintering.
- Film:ETFE front-sheet films and FEP lithography chamber linings represent the fastest-expanding demand pool, though the segment remains sub-scale relative to incumbent industrial coatings.
- Coating:Non-stick and corrosion-resistant applications persist in chemical processing equipment throughout China's manufacturing corridor.
- Powder:PTFE powder output from Chinese producers floods commodity markets while high-purity grades require segregated production lines.
- Rod:Machined components for fluid handling manifolds serve semiconductor wet process equipment in Hsinchu and Pyeongtaek fabrication clusters.
Film formats gain share fastest; powder retains production volume dominance.
Application:
Functional performance requirements stratify procurement specifications, with contamination-sensitive applications commanding 3-5x price multiples over industrial grades.
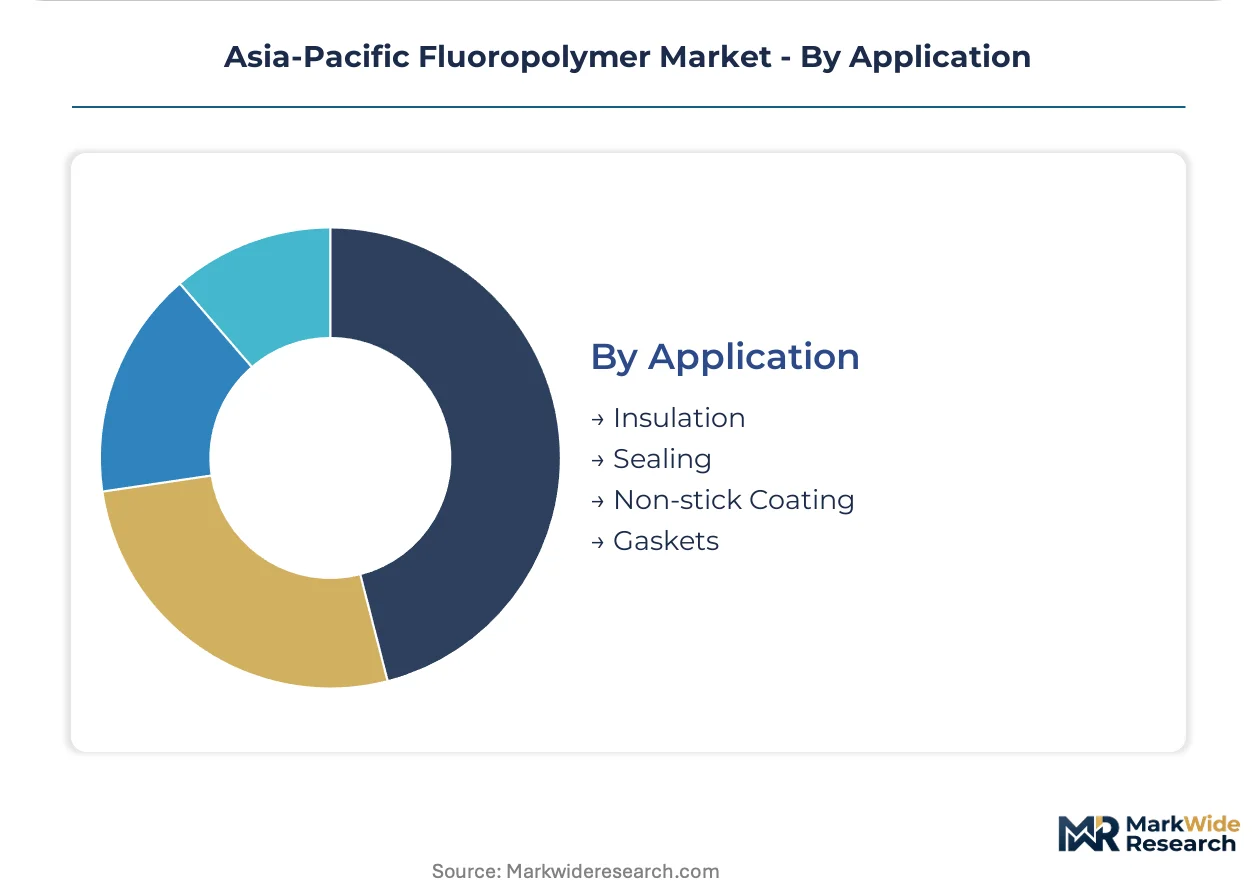
- Insulation:Dielectric applications in wire harness and semiconductor equipment demand precise control of carbon-fluorine backbone polymerization.
- Sealing:High-pressure hydrogen fuel cell interfaces and wafer fabrication fluid handling specify fluorinated ionomers with tailored melt-flow indices.
- Non-stick Coating:Industrial cookware and chemical vessel applications face substitution from ceramic alternatives in cost-sensitive procurement.
- Gaskets:Compression-molded seals for chemical processing equipment serve China's eastern coastal manufacturing bases.
Sealing applications extract the highest unit values; insulation maintains the broadest end-use footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta port network underwrites China's dominance in Asia-Pacific fluoropolymer throughput, connecting Shanghai chemical terminals to fabrication clusters across East Asia.
China
Semiconductor fabrication facilities in Jiangsu and Zhejiang provinces are expanding orders for high-purity fluoropolymer components. MEE enforces stricter per- and polyfluoroalkyl substance discharge standards in the Yangtze River Delta, compelling manufacturers toward low-GWP alternatives. Chemical processing and electronics manufacturing clusters in Shanghai, Suzhou, and Ningbo dominate procurement volume.
Japan
Wafer fabrication tool OEMs in Tokyo and Osaka drive demand for ultra-high-purity fluoropolymer grades. METI enforces fluorocarbon emission caps under its revised Fluorocarbons Recovery and Destruction Law, forcing domestic producers to retool polymerization chemistries. The Kanto region around Tokyo anchors high-purity resin synthesis talent concentrated in plasma etch chamber contamination control.
South Korea
Extreme ultraviolet lithography chamber lining specifications are expanding across fabrication facilities in Pyeongtaek and Hwaseong. The country's national environmental regulator imposes discharge standards affecting fluoropolymer manufacturing effluent near semiconductor clusters. Tool OEMs in the Seoul Capital Area are consolidating qualified vendor lists from 12-15 suppliers to 4-6 strategic partners.
India
Fluorspar mining and captive hydrofluoric acid production in Gujarat anchor backward-integrated supply positions. BIS certification requirements for fluoropolymer products used in food contact and potable water applications create non-tariff barriers for unqualified imports. The Dahej and Ankleshwar industrial corridors concentrate chemical processing demand for low-GWP alternatives.
Taiwan
Wafer fabrication facilities in Hsinchu Science Park are specifying sub-millimeter tolerance injection molded fluoropolymer parts for high-density wafer cleaning stations. The island's environmental protection administration implements effluent standards affecting semiconductor-grade production lines. Direct mill-to-tool supply agreements are displacing regional distributor networks in 300mm fab greenfield projects.
Asia-Pacific Fluoropolymer Market Competitive Landscape
Listed leaders compete with private specialists across purification-grade segmentation, creating a tiered structure where scale-driven commodity producers face margin compression while ultra-high-purity specialists capture protected pricing. Three archetypes dominate: Japanese conglomerates with captive resin capacity, Indian backward-integrated miners, and European diversified chemical groups. Capacity co-location near tool OEM assembly plants and segregated production lines for high-purity grades represent the dominant competitive moves.
Among Japan-based diversified chemical groups, Daikin Industries and AGC Inc exemplify the premium-tier vector through their positioning in semiconductor-grade specifications. Gujarat Fluorochemicals Limited occupies a position within the backward-integrated archetype, representing Indian producers with upstream control over fluorspar feedstock. These three companies anchor the competitive spectrum from commodity powder to extreme ultraviolet lithography-compatible films.
| Leading Market Players |
|---|
| Daikin Industries Ltd |
| Arkema |
| Solvay |
| Gujarat Fluorochemicals Limited |
| Dongyue Group |
| The Chemours Company |
| 3M Company |
| Kureha Corporation |
| AGC Inc |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between wafer fabrication tool OEMs and Japanese resin suppliers lock in three-year supply commitments while capping price volatility for semiconductor-grade fluoropolymers. These arrangements tether pricing visibility to co-located purification capacity, forcing buyers to accept premium positioning in exchange for contamination-controlled feedstock security.
Pricing Analysis
Volume-discount tiering structures separate semiconductor-grade PFA from commodity PTFE powder by certification threshold rather than base chemistry alone. Three-tier pricing stratification across ultra-high-purity, industrial-grade, and commodity levels reflects metallic ion contamination limits and melt-flow index precision. Cost compression in Chinese commodity powder output is intensifying because domestic producers are expanding unsegregated production lines. Chemical processors in the Yangtze River Delta exhibit the highest price sensitivity, while EUV lithography tool OEMs accept premium positioning without negotiation leverage.
Supply Chain Analysis
Strait of Malacca transit underwrites fluoropolymer resin movement from Japanese purification facilities to Taiwanese and South Korean fabrication clusters, creating logistics vulnerability for just-in-time delivery schedules. Feedstock draws from Chinese and Mexican fluorspar mining operations, Japanese hydrofluoric acid synthesis, and Indian captive acid production. Single-source vulnerability concentrates in high-purity resin synthesis talent anchored in Japan's Kanto region. Distribution runs through direct mill-to-tool agreements displacing regional distributor networks in Hsinchu and Pyeongtaek.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and contamination certification renewals are expanding faster than base resin sales as fabrication facilities outsource purity validation and regulatory compliance documentation.
For Market Incumbents: Secure segregated production line investments in Jiangsu and Zhejiang provinces before MEE effluent standards harden operating permits for mixed-grade facilities. Deepen captive fluorspar positions through offtake agreements with Mexican concentrate exporters to offset Chinese export quota volatility. Defend against commodity PTFE margin erosion by accelerating FEP film capacity for EUV lithography chamber specifications. For New Entrants and Emerging Players: Lead with BIS certification acquisition for food-contact and potable-water fluoropolymer grades in India's Dahej and Ankleshwar corridors, where unqualified imports face procedural exclusion. Target hydrogen fuel cell stack sealing applications in heavy-duty vehicle platforms, specifying fluorinated ionomers for high-pressure interfaces. Pursue joint qualification programs with Thailand's Eastern Economic Corridor wire harness compounders to bypass established Japanese supply relationships. For Investors and Strategic Acquirers: Backward-integrated Indian specialists with captive acid production and BIS certification readiness represent the most defensible acquisition profile. Long-term viability hinges on segregated high-purity manufacturing capabilities that commodity expansions cannot replicate. Watch for MEE operating permit suspensions in the Yangtze River Delta as an inflection indicator for regional supply restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Mining | Gujarat Fluorochemicals anchors cost position through captive concentrate supply from Indian deposits. |
| Co-located Purification Facility Expansion | Daikin Industries serves Tokyo and Osaka tool OEMs with mill-to-tool resin delivery eliminating distributor margins. |
| Low-GWP Polymerization Chemistry Retooling | METI emission caps force Japanese producers toward compliant process redesign without immediate revenue offset. |
| BIS Certification Investment for Food-Contact Grades | First-movers in Indian potable water applications capture preferential procurement from infrastructure projects. |
| Direct Supply Agreement Consolidation | Taiwanese 300mm fabs are compressing qualified vendor lists from twelve suppliers to four strategic partners. |
Research Methodology
Desk research of customs trade databases, SEC chemical sector filings, and MEE regulatory notices preceded structured interviews with fluoropolymer plant managers, semiconductor tool OEM procurement leads, and distribution channel partners across East Asia. Primary fieldwork with resin synthesis engineers and contamination control specialists validated secondary trade flow estimates. Bottom-up capacity modeling and top-down end-use demand triangulation anchored volume projections.
Variance decomposition across grade tier, end-use industry criticality, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segmented demand elasticity and substitution threshold analysis. Modeled inputs included wafer fabrication capacity expansion schedules, EUV lithography tool deployment rates, and photovoltaic module front-sheet specification shifts.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor capital expenditure cycles or abrupt fluorspar export restriction scenarios would require recalibration. Forecasts reflect documented assumptions regarding MEE enforcement intensity and METI emission cap implementation. Practitioners should keep alternative scenarios live as dual carbon policy trajectories and hydrogen fuel cell commercialization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polylactic Acid Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Natural Oil Polyols (NOP) Market
Polymers & Resins
Polycarbonate Resin Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Phenoxy Resins Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Global Hydroxypropyl Cellulose Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market