
 Global Impregnating Resins Market | 2026-2036
Global Impregnating Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Impregnating Resins Market Intelligence
The performance gap between high-temperature, solvent-free resins and lower-cost commodity polyester formulations is hardening. ALTANA (ELANTAS) specializes in high-performance electrical insulation materials for demanding applications. BASF SE leverages its vast chemical production scale to compete across multiple resin chemistries. Von Roll positions its offerings for high-voltage applications in power generation, differentiating on reliability and thermal endurance for critical infrastructure.
Impregnating resins are low-viscosity liquid polymers designed to penetrate and fill voids within porous materials, particularly electrical windings and motor stators. Upon curing, they form a rigid, solid mass that provides enhanced dielectric strength, mechanical stability, and thermal conductivity to the component. Epoxy resins lead the high-performance segment due to superior adhesion and chemical resistance. Applications in transformer manufacturing and industrial motors represent mature, high-volume segments with significant price competition.
The European Union's REACH and RoHS directives mandate the restriction of hazardous substances, influencing resin formulation and material selection. In the United States, EPA regulations on volatile organic compounds (VOCs) drive the shift toward solvent-free or water-based systems. Stakeholders must navigate the strategic decision between investing in premium, regulation-compliant formulations and competing in the high-volume, price-sensitive commodity markets.
Market Dynamics
The fundamental market dynamic is the growing bifurcation between high-performance, regulation-compliant formulations and price-sensitive commodity grades. Environmental mandates, particularly the EU's REACH regulation and US EPA rules on VOCs, are forcing this strategic divergence across the industry.
Growth Catalysts
- Renewable Energy Expansion:Demand for high-performance insulating resins is directly linked to the manufacturing of wind turbine generators and solar power inverters, which require materials with exceptional thermal and mechanical stability.
- Regulatory Compliance Push:The EU's REACH and RoHS directives are compelling manufacturers to innovate, developing safer, solvent-free, and monomer-free resin systems that create new premium market segments.
- Asian Manufacturing Hubs:China's dominance in industrial motor and electronics production provides a massive, concentrated volume market, while manufacturing growth in Southeast Asian nations creates new pockets of demand.
Market Restraints
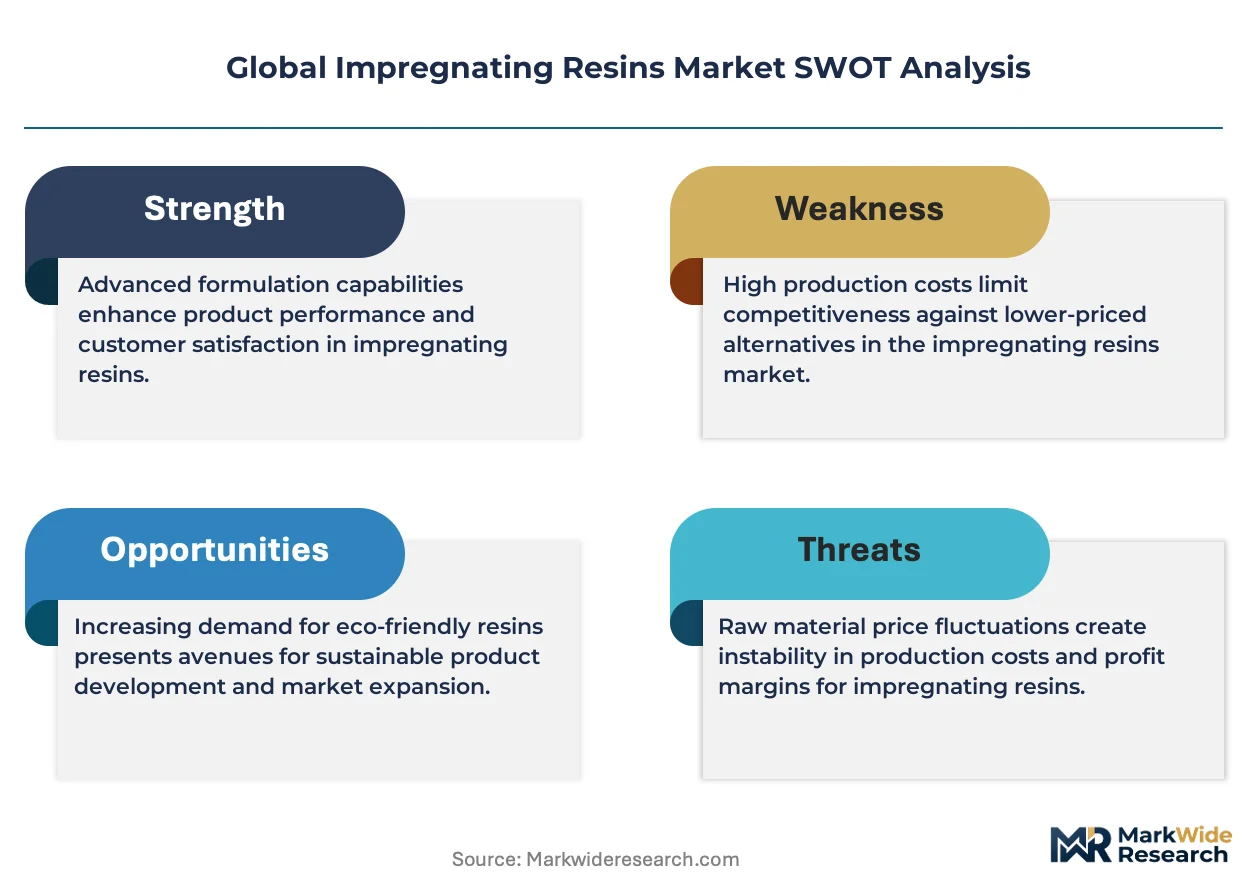
- Raw Material Volatility:The supply chain is exposed to price fluctuations in key petrochemical feedstocks, such as bisphenol-A (BPA) and epichlorohydrin for epoxy resins, which can compress manufacturer margins.
- Technical Performance Gaps:A significant performance and cost differential persists between high-end solvent-free systems and traditional, lower-cost solvent-based polyester resins, slowing adoption in price-sensitive applications.
- Substitution Threats:In certain low-voltage or less demanding applications, alternative insulation technologies like self-bonding magnet wire or advanced potting compounds can displace traditional impregnating resins.
Strategic Opportunities
- Electric Vehicle Powertrains:The rapid growth of electric vehicles presents a major opportunity for resins designed for the impregnation of high-RPM motor stators and for encapsulating battery module components for thermal management.
- Bio-Based Formulations:Developing resins from renewable or recycled feedstocks addresses sustainability mandates and appeals to end-users with strong corporate ESG goals, particularly in Europe and North America.
- High-Voltage DC Components:The expansion of HVDC power transmission infrastructure requires specialized resins with superior dielectric strength and resistance to partial discharge for use in transformers, bushings, and insulators.
Industry Challenges
- Divergent Regulatory Hurdles:Manufacturers face complexity and high costs in qualifying products for multiple markets, each with distinct standards, such as the EU's REACH, the US EPA's VOC limits, and China's GB standards.
- Formulation Expertise Scarcity:There is a limited talent pool of polymer chemists and application engineers capable of developing new resin systems that meet conflicting demands for higher performance, lower cost, and stricter environmental compliance.
- Lengthy Qualification Cycles:Gaining approval for resins in critical applications like power generation or automotive involves extensive and time-consuming testing, delaying revenue generation from new product innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Impregnating Resins Market |
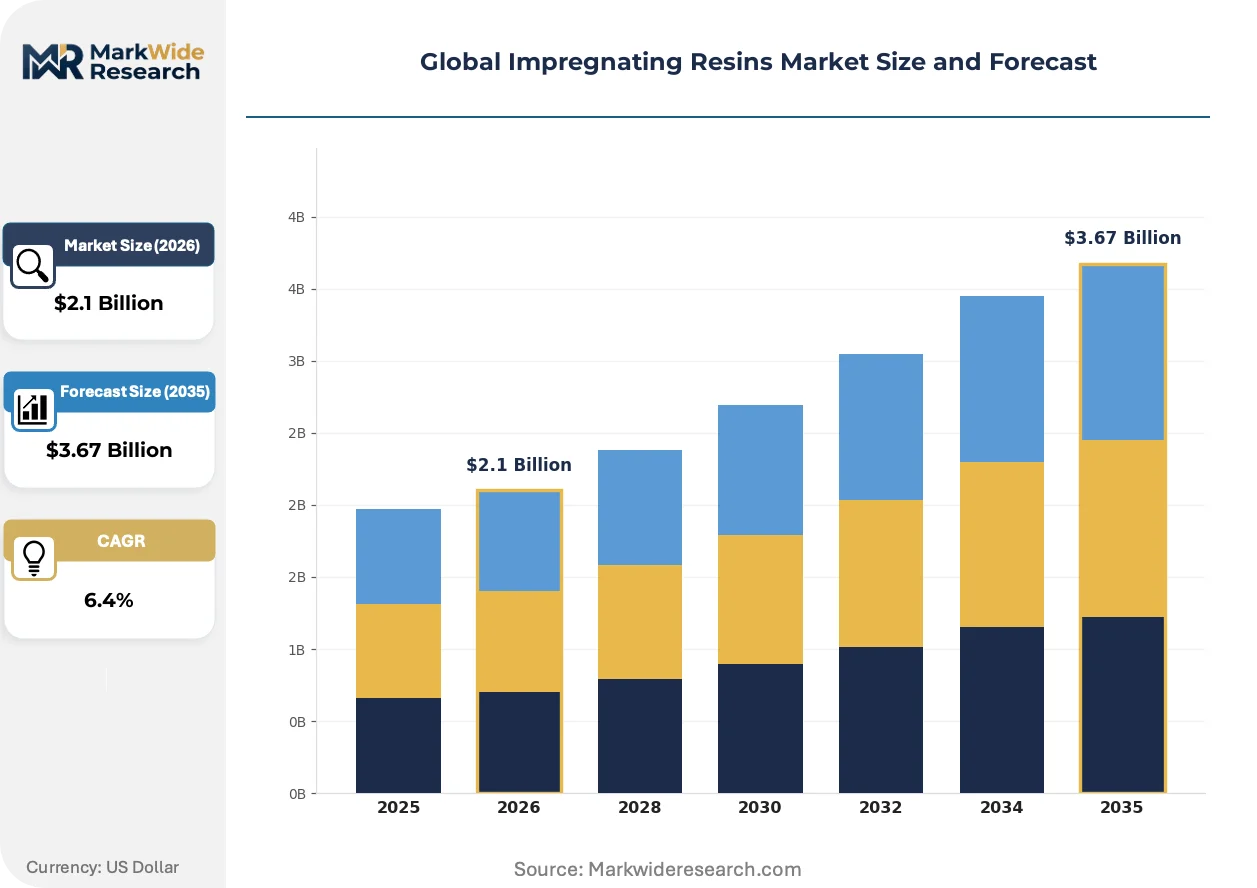
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Resins, Polyester Resins, Acrylic Resins, Polyurethane Resins, Phenolic Resins Technology: Vacuum Pressure Impregnation, Brush Coating, Dip Coating, Curtain Coating, Roller Coating Application: Electrical Insulation, Magnet Wire Coating, Transformer Manufacturing, Generator Stators, Coil Protection End User Industry: Power Generation Equipment, Electrical Appliances, Electronics Manufacturing, Industrial Motors, Renewable Energy Systems |
| Companies Covered | 3M, BASF SE, Axalta Coating Systems, Henkel AG & Co. KGaA, Huntsman International LLC, ALTANA (ELANTAS), Von Roll, Kyocera Corporation, Hitachi Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Impregnating Resins Market Strategic Shifts & Innovations
Innovations are centered on enhancing thermal performance and environmental compatibility to meet the demands of next-generation electrical systems. The market is shifting as regulatory pressures and new end-use requirements redefine material specifications and performance benchmarks for electrical insulation.
Solvent-free resin systems, particularly those based on advanced epoxy or unsaturated polyester chemistries, provide superior insulation properties without releasing volatile organic compounds during application. Manufacturers of high-voltage motors, transformers, and generators are steadily adopting these materials to meet stringent environmental regulations and improve workplace safety. This technology is absorbing the market share previously held by traditional solvent-borne varnishes in applications where reliability and regulatory compliance are paramount.
European chemical regulations, led by ECHA through the REACH and RoHS frameworks, are forcing the reformulation of entire product portfolios. These rules restrict or ban specific hazardous monomers, catalysts, and diluents commonly used in legacy resin systems. The industrial motor and power tool segments are most affected, prompting a shift toward compliant, albeit often more expensive, water-based or 100% solids formulations to maintain access to the EU market.
A notable behavioral shift is occurring as original equipment manufacturers increasingly prioritize lifecycle performance and supply chain transparency over initial purchase price. This change disrupts the commodity-driven sales model, creating an advantage for suppliers that provide comprehensive technical support, application engineering, and robust documentation for regulatory compliance. This trend is most pronounced within the German automotive and Japanese power generation supply chains.
Global Impregnating Resins Market Segmentation
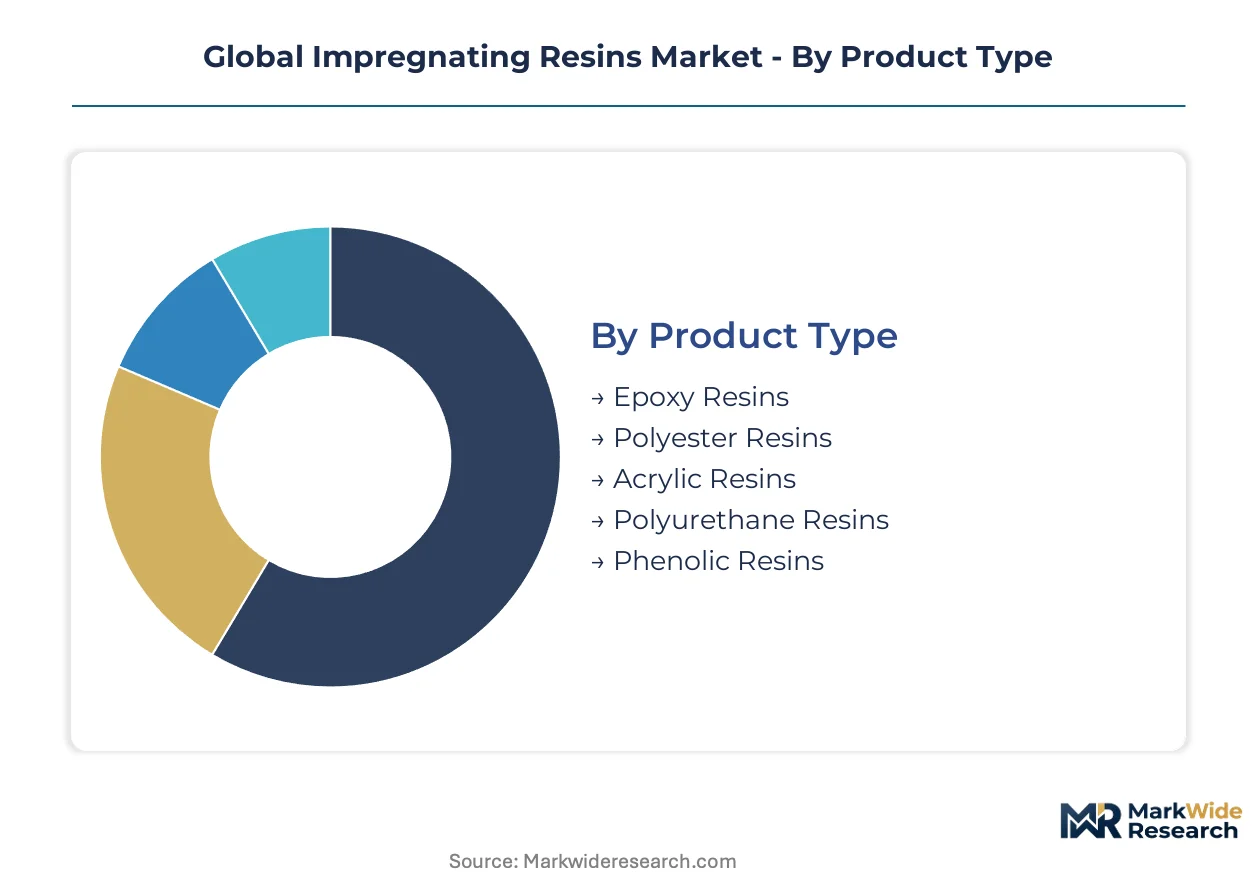
The impregnating resins market is segmented to reveal the diverse material requirements and application specificities across various industries. This granular breakdown aids stakeholders in understanding distinct performance benchmarks and regulatory compliance needs. Identifying these segments illuminates where investment and innovation are most impactful.
Product Type:
The capital intensity associated with manufacturing impregnating resins varies significantly by product type, reflecting the complexity of chemical synthesis and raw material sourcing.
- Epoxy Resins:Epoxy resins are thermosetting polymers characterized by excellent adhesion, chemical resistance, and superior dielectric properties, making them ideal for high-performance electrical insulation. Demand concentrates in advanced power generation equipment and electric vehicle powertrains, driven by requirements for thermal stability and mechanical robustness.
- Polyester Resins:Polyester resins, particularly unsaturated polyester resins, offer a balance of cost-effectiveness and good electrical and mechanical properties, suitable for general-purpose applications. Volume demand is substantial within industrial motors and consumer electronics manufacturing in China, where price competitiveness is a primary purchasing criterion.
- Acrylic Resins:Acrylic resins provide good weatherability and UV resistance, often utilized in applications requiring outdoor exposure or flexible coatings.
- Polyurethane Resins:Polyurethane resins offer flexibility and abrasion resistance, finding use in applications needing impact absorption and vibration damping.
- Phenolic Resins:Phenolic resins are known for high thermal stability and mechanical strength, frequently employed in high-temperature electrical components.
Most installed capacity flows through Polyester Resins. Expansion is steepest in Epoxy Resins.
Technology:
The cost tier of impregnation technology often reflects a trade-off between process efficiency, material utilization, and the required performance tier of the final component.
- Vacuum Pressure Impregnation:Vacuum Pressure Impregnation (VPI) involves evacuating air from porous materials before introducing resin under pressure, ensuring deep penetration and void-free insulation for critical components. This technology is crucial for high-voltage transformers and large wind turbine generators, where insulation integrity is paramount for operational reliability.
- Dip Coating:Dip coating involves submerging components into an impregnating resin bath, allowing the resin to penetrate by capillary action, suitable for high-volume production of smaller electrical parts. This method sees widespread use in manufacturing basic industrial motors and electronic coils, particularly in Southeast Asian production hubs.
- Brush Coating:Brush coating is a manual application method for localized insulation or repair, common in prototyping or low-volume specialized electrical work.
- Curtain Coating:Curtain coating applies a continuous film of resin by passing components through a falling curtain of liquid, offering high throughput for flat or uniformly shaped parts.
- Roller Coating:Roller coating uses rotating rollers to apply resin to flat substrates or wires, providing precise thickness control for magnet wire insulation.
High-performance applications predominantly rely on Vacuum Pressure Impregnation methods. Dip Coating remains a foundational process for mass production across various electrical components.
Application:
Volume demand for impregnating resins is heavily influenced by the scale of manufacturing in specific application areas, particularly within mature industrial sectors.
- Electrical Insulation:Electrical insulation applications utilize resins to provide dielectric strength and protect components from environmental factors, preventing shorts and ensuring operational safety in diverse systems. This segment experiences consistent demand from power distribution networks and consumer appliance manufacturing, driven by safety standards and product longevity requirements.
- Transformer Manufacturing:Transformer manufacturing uses impregnating resins to fill voids in windings, enhancing dielectric strength and thermal dissipation for efficient power conversion and distribution. This application is critical for grid infrastructure development in countries like India and Brazil, where electricity demand continues to grow significantly.
- Magnet Wire Coating:Magnet wire coating involves applying a thin, durable insulating layer to copper or aluminum wire, essential for efficient electromagnetic coil performance.
- Generator Stators:Generator stators require robust impregnating resins to withstand high mechanical stress and thermal cycling in power generation units.
- Coil Protection:Coil protection applications encapsulate electrical coils to shield them from moisture, chemicals, and vibration, ensuring reliability in harsh operating conditions.
The largest segment by volume is Electrical Insulation, reflecting its pervasive need across numerous end-uses. Transformer Manufacturing is experiencing a notable uplift due to global infrastructure investments.
End User Industry:
Different end-user industries impose distinct regulatory pressures and performance specifications on impregnating resins, influencing formulation and supply chain requirements.
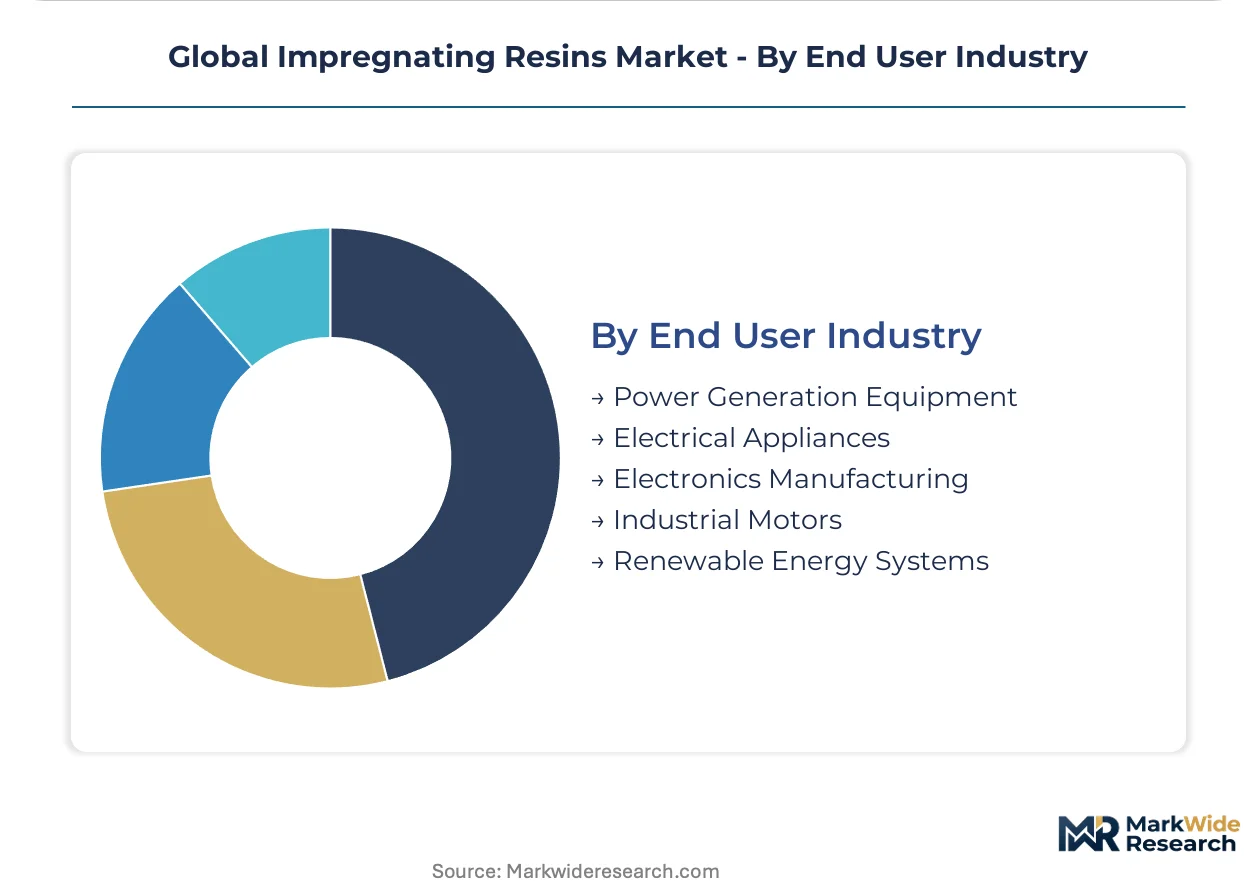
- Renewable Energy Systems:Renewable energy systems, including wind turbine generators and solar inverters, demand impregnating resins with exceptional thermal stability and long-term reliability under fluctuating environmental conditions. Demand is particularly strong in the European Union, driven by ambitious decarbonization targets and supportive policy frameworks.
- Industrial Motors:Industrial motors represent a mature end-user segment for impregnating resins, requiring materials that provide robust electrical insulation and mechanical stability for continuous operation in manufacturing and automation. China's extensive industrial base accounts for a significant portion of the global demand in this sector.
- Power Generation Equipment:Power generation equipment, encompassing turbines and generators, relies on resins for critical insulation in high-voltage and high-temperature environments.
- Electrical Appliances:Electrical appliances utilize impregnating resins for insulating motor windings and electronic components, ensuring safety and durability in household and commercial products.
- Electronics Manufacturing:Electronics manufacturing employs resins for encapsulating sensitive components, providing protection against moisture, vibration, and thermal stress in consumer and industrial devices.
The Renewable Energy Systems sector demonstrates the most dynamic growth trajectory for resin consumption. Industrial Motors, however, continue to represent the largest established market for these materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A specialized talent pool for polymer chemistry and electrical engineering anchors regional demand for impregnating resins across key manufacturing hubs. These centers of expertise drive innovation and application development for advanced insulation materials. Regulatory frameworks and industrial policies significantly shape the market landscape in each geography.
China
China's extensive electronics and industrial motor manufacturing bases drive substantial demand for impregnating resins. The country's GB standards for electrical products influence material selection and performance requirements. Industrial clusters in the Yangtze River Delta and Pearl River Delta regions exhibit high-volume consumption for both commodity and specialized formulations.
Germany
Germany's robust automotive and power generation equipment sectors require high-performance impregnating resins for demanding applications. The EU's REACH and RoHS directives compel manufacturers to invest in compliant, safer resin systems. Major engineering and chemical hubs like Bavaria and North Rhine-Westphalia lead in developing and adopting advanced solvent-free technologies.
United States
The United States market sees demand from renewable energy infrastructure and specialized industrial applications. EPA regulations on volatile organic compounds (VOCs) accelerate the shift toward solvent-free and water-based resin solutions. Manufacturing centers in the Midwest and Southeast regions contribute to consistent demand for electrical insulation materials.
India
India's expanding power distribution networks and growing industrial base fuel the need for impregnating resins in transformer manufacturing. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for electrical insulation products. Urban industrial zones, particularly around Mumbai and Chennai, are key consumption points for these materials.
Japan
Japan's focus on high-voltage power generation equipment and precision electronics creates demand for resins with superior thermal and dielectric properties. METI (Ministry of Economy, Trade and Industry) guidelines support the development of advanced materials for energy efficiency. Industrial complexes in the Kanto and Kansai regions are significant consumers of specialized impregnating resins.
Global Impregnating Resins Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the impregnating resins market, creating a structural bifurcation. The market exhibits a tiered structure, with specialized providers focusing on high-performance formulations and large chemical companies competing across broader portfolios. Strategic archetypes include innovation-driven specialists, volume-focused commodity suppliers, and diversified chemical conglomerates. Dominant competitive moves involve technology innovation to meet regulatory demands and strategic partnerships for market access.
On the premium-tier vector, ALTANA (ELANTAS) represents a specialist in high-performance electrical insulation materials for demanding applications. BASF SE, a German-based chemical giant, exemplifies a diversified player leveraging its vast chemical production scale to compete across multiple resin chemistries. Von Roll positions its offerings for high-voltage applications in power generation, anchoring the segment for reliability and thermal endurance in critical infrastructure.
| Leading Market Players |
|---|
| 3M |
| BASF SE |
| Axalta Coating Systems |
| Henkel AG & Co. KGaA |
| Huntsman International LLC |
| ALTANA (ELANTAS) |
| Von Roll |
| Kyocera Corporation |
| Hitachi Chemical Co. Ltd. |
| Others |
Cost & Logistics Intelligence
The European Union's REACH and RoHS directives, mandating hazardous substance restrictions, reshape impregnating resin procurement. This regulatory pressure forces suppliers to invest in compliant formulations, directly influencing production costs and market pricing structures.
Pricing Analysis
Bundled service offerings, including application engineering and robust regulatory documentation, enable value-based pricing for specialized impregnating resins. Price differentiation stems from strict regulatory compliance, particularly for EU markets, and superior thermal endurance properties. Pricing softness affects commodity polyester formulations due to raw material volatility in petrochemical feedstocks. Buyers in China's industrial motors sector exhibit high price sensitivity, contrasting sharply with the lower sensitivity in European renewable energy system developers.
Supply Chain Analysis
Rigorous certification and qualification processes for impregnating resins gate market access, particularly for critical infrastructure applications. The supply of key feedstocks, such as bisphenol-A and epichlorohydrin, draws from concentrated chemical production hubs in China and Germany. Raw material price volatility, stemming from petrochemical market fluctuations, represents a significant supply chain risk for resin manufacturers. Distribution runs through direct sales channels for major original equipment manufacturers, supplemented by specialized distributors serving smaller or regional customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The impregnating resins market acts as a regulatory compounder, where environmental mandates amplify demand for specialized materials. The EU's REACH regulation, prohibiting hazardous substances, specifically drives the shift towards safer, high-performance resin systems.
For Market Incumbents:Lock in long-term supply agreements with key raw material providers to mitigate petrochemical price volatility. Deepen application engineering support for high-voltage DC components and EV powertrains to counter substitution threats from advanced potting compounds. Invest in R&D for next-generation solvent-free and bio-based formulations to maintain regulatory compliance. Prioritize obtaining certifications for new premium market segments in Europe and North America.
For New Entrants and Emerging Players:Online technical platforms can offer smaller, specialized resin formulations directly to niche manufacturers. Target the rapidly growing electric vehicle powertrain and high-voltage DC components segments with innovative, regulation-compliant materials. Penetrate markets in Southeast Asia by offering cost-effective, yet compliant, solutions for consumer electronics. Focus on bio-based formulations to appeal to end-users with strong corporate ESG goals in Europe.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized formulators possessing proprietary, regulation-compliant resin technologies for high-performance applications. The market outlook for premium impregnating resins remains robust over the next decade, driven by electrification and renewable energy mandates. Target acquisition candidates with established expertise in solvent-free epoxy or bio-based polyurethane systems. The signal to watch is the adoption rate of advanced insulation materials in China's electric vehicle manufacturing sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Epoxy Resins | Increases supply of high-performance materials for renewable energy and EV applications in Europe. |
| Green Manufacturing Transition | Reduces environmental footprint, aligning with EU and US regulatory mandates for sustainable production. |
| Long-term Supply Agreement for Feedstocks | Secures stable pricing and availability of critical raw materials like bisphenol-A for manufacturers. |
| Product Launch of Bio-Based Resins | Addresses sustainability mandates and attracts end-users with strong corporate ESG objectives. |
| Strategic Partnership with EV OEM | Integrates resin development directly into electric vehicle powertrain design cycles, ensuring fit-for-purpose solutions. |
Research Approach
Direct dialogue with polymer chemists, application engineers, procurement leads at major OEMs, and regulatory compliance officers informed this analysis. Primary insights were triangulated with extensive secondary research from ECHA REACH filings, EPA VOC reports, and industry association publications. A rigorous bottom-up and top-down approach validated market sizing and segmentation. This dual validation ensures robust data integrity.
Volume and value projections were generated using a proprietary analytical framework, evaluating market dynamics across the analysis window. The model integrated segmentation by product type, technology, application, end-user industry, and regional regulatory environment. Compound annual growth rates derived from historical trends, demand drivers, and expert projections. Key inputs included renewable energy capacity additions and electric vehicle production forecasts.
Raw material price shocks, unforeseen regulatory shifts, and disruptive technological breakthroughs are the dominant revision risks. The projections reflect assumptions about market conditions and technological adoption. Deviation in raw material pricing or regulatory enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Long-Chain Polyamide Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Global Acrylic Solid Surface Market
Polymers & Resins
Global Linear Low Density Polyethylene Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Sodium Polyacrylate Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Polycarbonate Diols Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
N-Vinylformamide Market
Polymers & Resins
Propylene Terpolymer Market