
 North America Polyamide Market | 2026-2036
North America Polyamide Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polyamide Market Insights
Aftermarket component refurbishment is reshaping margin distribution across the North America polyamide value chain. INVISTA leverages its integrated adiponitrile capacity to sustain feedstock cost advantages across Gulf Coast operations. DuPont de Nemours Inc. anchors premium PA 66 positioning through specialized thermal-stability grades targeting under-the-hood automotive applications. Ascend Performance Materials dominates the merchant resin channel with backward-integrated hexamethylenediamine supply.
Polyamides comprise thermoplastic polymers characterized by repeating amide linkages along the backbone, with PA 6 and PA 66 representing the dominant commercial grades distinguished by six-carbon and twelve-carbon monomer structures respectively. These materials deliver melting points between 220°C and 265°C, tensile strengths exceeding 80 MPa, and inherent resistance to hydrocarbons and abrasion, serving primarily as metal substitutes in load-bearing mechanical components. PA 6 granules occupy the largest volume position due to cost-efficient caprolactam polymerization routes and broad injection-molding compatibility across automotive and consumer goods. PA 11 and PA 12 powders command specialized margin pools in additive manufacturing and powder coatings where bio-based feedstocks and lower moisture absorption justify price premiums.
The EPA and NHTSA coordinate Corporate Average Fuel Economy standards that elevate polyamide penetration in engine-bay and structural automotive applications through metal replacement. California's Air Resources Board imposes additional emissions-performance thresholds that filter material qualification lists for suppliers serving West Coast OEM assembly. OSHA workplace-exposure limits for caprolactam vapor shape plant-investment decisions across Texas and Louisiana chemical corridors. Stakeholders must track bio-based PA platform scale-up timelines and recycled-content mandates from Quebec and California as these jurisdictions advance circular-economy frameworks.
Market Dynamics
Automotive lightweighting mandates from EPA and NHTSA are compressing metal-to-polyamide substitution timelines across powertrain and structural applications, forcing resin suppliers to qualify higher thermal-stability grades faster than traditional development cycles allow.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Tightened thresholds for model year fleets push OEMs toward glass-filled polyamide engine covers and intake manifolds that cut mass without sacrificing dimensional stability under thermal cycling.
- Querétaro automotive cluster expansion:Mexico's centralized OEM assembly corridor draws compounders to localize compounding capacity, shortening lead times for just-in-sequence resin delivery to transmission and HVAC module plants.
- Caprolactam polymerization efficiency gains:Continuous hydrolytic PA 6 processes now achieve conversion rates above 99 percent, narrowing the cost gap with PA 66 in high-volume injection molding applications.
Market Restraints
- Adiponitrile supply concentration:Four producers control over 85 percent of global hexamethylenediamine precursor capacity, exposing PA 66 compounders to force majeure risk and volatile contract pricing.
- OSHA caprolactam exposure limits:Eight-hour time-weighted average thresholds of 4 mg per cubic meter necessitate capital-intensive vapor-recovery systems at Texas and Louisiana polymerization facilities.
- Long-chain bio-based PA 11 feedstock constraints:Castor oil crop yields in India and Brazil fluctuate with monsoon patterns, creating raw material uncertainty for specialty nylon producers targeting medical and oil-field segments.
Strategic Opportunities
- California recycled-content mandates:Assembly Bill 1793 establishes minimum post-consumer resin thresholds for automotive interior components by 2030, creating first-mover advantage for compounders with validated mechanical recycling streams.
- Additive manufacturing powder qualification:Laser sintering of PA 12 and PA 11 powders is penetrating jigs, fixtures, and end-use aerospace ducting where lot-to-lot consistency and moisture resistance command 40-60 percent premiums over injection grades.
- Quebec circular-economy framework:Provincial extended producer responsibility programs for industrial plastics create offtake certainty for chemical recyclers targeting depolymerization of carpet and fishing net waste streams back to caprolactam monomer.
Industry Challenges
- Multi-physics simulation talent scarcity:Predictive modeling of fiber orientation and weld-line strength in glass-filled grades requires expertise in moldflow and structural finite element analysis that resides at compounders and Tier 1s, not OEM engineering departments.
- Automotive material qualification timelines:PPAP submission and production part approval processes for under-hood applications stretch 18-24 months, locking resin specifications years ahead of vehicle launch and delaying formulation innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polyamide Market |
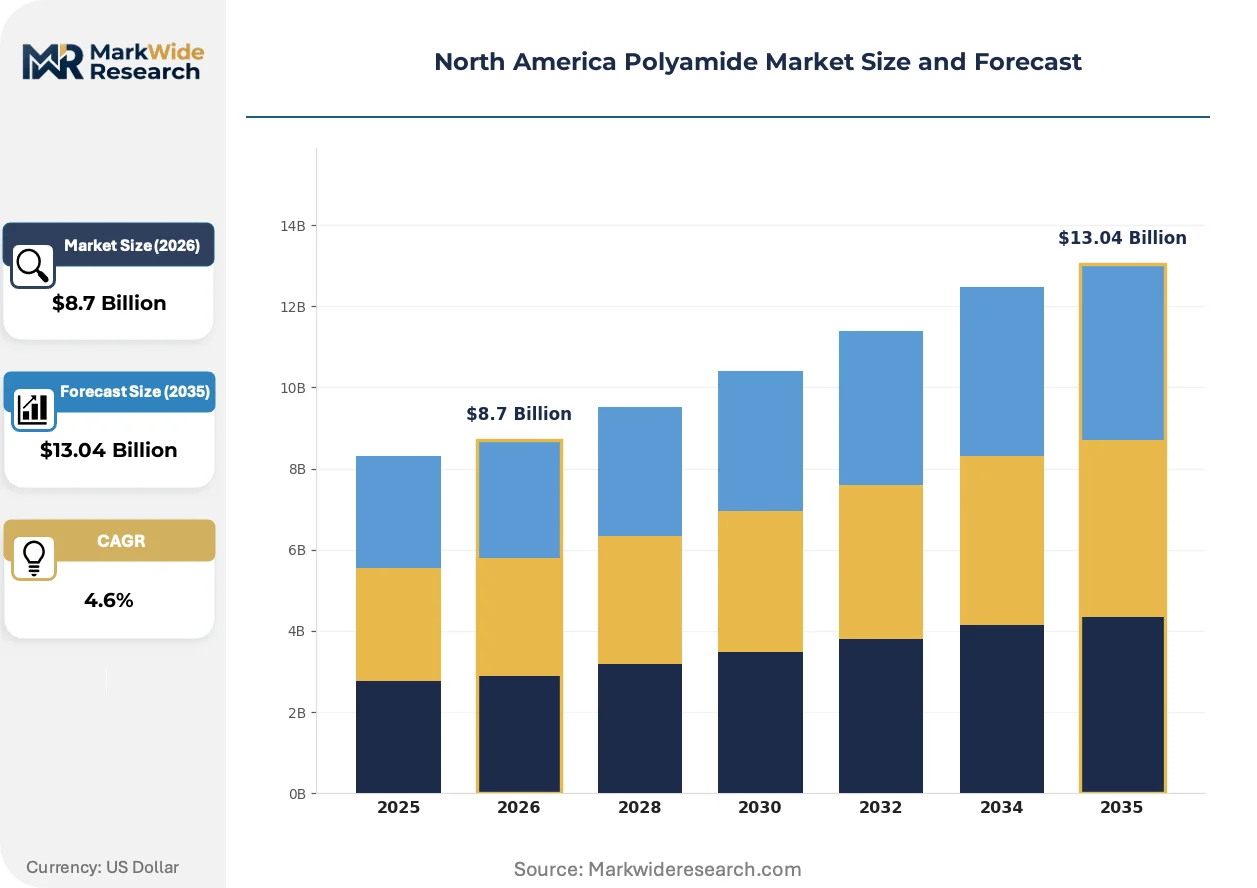
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA 6, PA 66, PA 11, PA 12 Form: Granules, Powder, Sheets, Films End User: Automotive, Textiles, Electronics, Food Packaging Application: Components, Coatings, Adhesives, Fibers |
| Companies Covered | INVISTA, Arkema, BASF SE, Huntsman Corporation, AdvanSix Inc., DuPont de Nemours Inc., Celanese Corporation, EMS-Chemie, Ascend Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polyamide Market Trends and Innovations
Material substitution logic is shifting from simple density-based metal replacement toward functional integration, where polyamide compounds now combine thermal management, electromagnetic shielding, and vibration damping in single molded assemblies.
Glass-reinforced PA 66 is migrating from conventional 30-35 percent loadings toward 50-60 percent high-fill grades that enable direct metal substitution in transmission brackets and battery module frames. Tier 1 suppliers in Michigan and Ohio are qualifying these compounds for 150°C continuous-use applications previously reserved for aluminum die castings. The shift is compressing the addressable market for magnesium transmission housings while expanding compounder technical service requirements for mold design and fiber attrition control.
California Air Resources Board Low-Emission Vehicle III regulations are tightening evaporative emission standards for fuel system components, disqualifying standard PA 6 grades that fall short of permeation resistance thresholds. This is accelerating fluoropolymer-lined polyamide tank and line approvals where multi-layer co-extrusion bonds PA 12 outer layers to ETFE or PVDF inner barriers. West Coast OEM assembly plants now specify these constructions for hybrid vehicle fuel systems where thermal cycling from start-stop operation degrades conventional materials.
Automotive procurement organizations are consolidating resin specifications across platform architectures, reducing approved material lists from 200-plus grades to fewer than 50 core SKUs with regional color and additive variations. Tier 2 compounders face exclusion unless they qualify for multiple OEM programs simultaneously, favoring suppliers with captive adiponitrile or caprolactam integration. The consolidation is most visible in Detroit Three purchasing corridors where single-source agreements now span five-to-seven year horizons with price-volume banding tied to benzene and natural gas indices.
North America Polyamide Market Segmentation
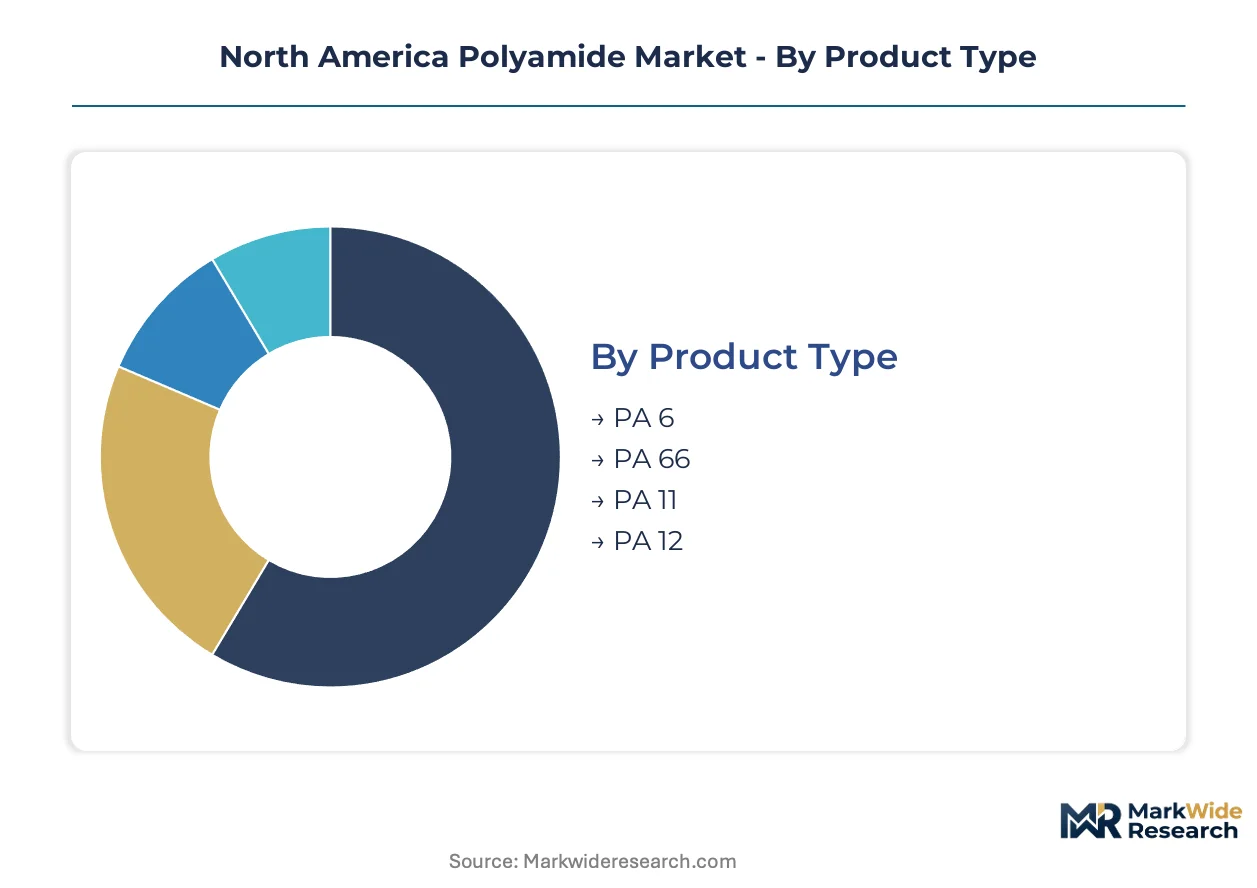
Polyamide segmentation in North America reflects divergent technical requirements across automotive powertrain engineering, medical device manufacturing, and industrial coating applications. Each dimension—product chemistry, physical form, end-use sector, and functional application—carries distinct margin profiles and qualification barriers that shape supplier strategy.
Product Type:
Use-case spectrum spans commodity thermoplastics in high-volume injection molding to bio-based specialty grades commanding formulation premiums.
- PA 6:Caprolactam-derived polymer with melting point near 220°C serves as the workhorse for automotive under-hood components and textile fibers. Michigan and Ohio assembly corridors consume granules for intake manifolds and engine covers where cost efficiency outweighs thermal ceiling limitations.
- PA 66:Hexamethylenediamine-adipic acid condensation delivers 265°C melting point and superior creep resistance for transmission brackets and thermal management modules. EPA fuel-economy mandates accelerate metal replacement in load-bearing powertrain applications previously reserved for aluminum die castings.
- PA 11:Castor oil-derived biopolymer offers low moisture absorption and flexibility for fuel lines and pneumatic tubing in agricultural equipment.
- PA 12:Laurolactam-based grade provides exceptional dimensional stability and chemical resistance for medical catheters and powder coatings in industrial fluid handling.
Established volume favors PA 6; emerging adoption favors PA 66 in electrified powertrain architectures.
Form:
Physical configuration determines processing economics and addressable equipment base across extrusion, molding, and additive manufacturing.
- Granules:Standard pelletized feedstock dominates injection molding and extrusion lines across automotive Tier 1 plants in Querétaro and Detroit corridors. Continuous hydrolytic polymerization advances have tightened conversion costs, reinforcing granule supremacy in high-throughput applications.
- Powder:Micronized grades enable selective laser sintering for jigs, fixtures, and end-use aerospace ducting where lot-to-lot consistency commands substantial premiums over conventional molding compounds.
- Sheets:Compression-molded plate stock serves thermoformed housings and wear pads in material handling equipment.
- Films:Biaxially oriented and cast constructions deliver oxygen barrier properties for multilayer food packaging and industrial lidding applications.
Granules capture the broadest equipment compatibility; powder is climbing the fastest in additive manufacturing qualification pipelines.
End User:
Customer concentration varies from consolidated OEM procurement organizations to fragmented specialty compounders serving niche specifications.
- Automotive:Detroit Three and transplant OEMs drive specification consolidation toward fewer than 50 core SKUs with regional variations, favoring suppliers with captive monomer integration. NHTSA Corporate Average Fuel Economy standards compress metal-to-polyamide substitution timelines across structural and powertrain applications.
- Textiles:Carpet fiber and industrial yarn producers in Georgia and South Carolina consume PA 6 chip for bulk continuous filament and staple fiber spinning.
- Electronics:Connector housings and cable management systems require flame-retardant compounded grades meeting UL 94 V-0 thresholds.
- Food Packaging:Film and multilayer barrier structures must satisfy FDA food contact notification requirements for caprolactam migration limits.
Automotive procurement concentration favors integrated resin-compounder operations; food packaging regulatory complexity favors specialized film extruders with validated compliance histories.
Application:
Functional deployment ranges from discrete mechanical components to continuous surface treatments with divergent technical service requirements.
- Components:Molded brackets, housings, and structural assemblies constitute the dominant value pool, with glass-filled grades achieving direct metal substitution in battery module frames and transmission supports. California Air Resources Board evaporative emission regulations disqualify standard grades for fuel system applications, accelerating fluoropolymer-lined multi-layer constructions.
- Coatings:Powder and liquid formulations protect metal substrates in agricultural machinery and oil-field equipment where abrasion resistance extends service intervals.
- Adhesives:Hot-melt and reactive systems bond dissimilar substrates in automotive interior assembly and flexible packaging lamination.
- Fibers:Staple and filament yarn serve carpet face fiber, tire cord, and industrial belting where tensile strength and fatigue resistance justify polymer premium over polyester alternatives.
Components command the deepest technical service engagement; coatings are gaining share fastest in corrosion protection for renewable energy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Mexico's automotive corridors exhibit acute price sensitivity to resin fluctuations, while U.S. and Canadian compounders absorb premiums for thermal-stability grades without volume elasticity shifts. This demand-elasticity contrast shapes supplier investment priorities across the tri-national landscape.
United States
EPA Corporate Average Fuel Economy standards compress metal-to-polyamide substitution timelines across Michigan and Ohio assembly belts. OSHA caprolactam exposure limits of 4 mg per cubic meter force capital deployment toward vapor-recovery systems at Texas and Louisiana polymerization plants. Detroit's Tier 1 supplier base consolidates approved material lists from 200-plus grades to under 50 core SKUs.
Canada
Quebec's circular-economy framework establishes extended producer responsibility for industrial plastics, creating offtake certainty for chemical recyclers targeting carpet and fishing net waste streams. The province's depolymerization facilities convert post-consumer polyamide back to caprolactam monomer for reuse in automotive applications.
Mexico
Querétaro's centralized OEM assembly corridor draws compounders to localize compounding capacity, shortening lead times for just-in-sequence resin delivery to transmission and HVAC module plants. NHTSA fuel-economy alignment with EPA standards ensures regulatory continuity for U.S.-bound vehicle production.
North America Polyamide Market Competitive Landscape
Capability concentration sits with integrated resin-compounder operations; scale advantage sits with adiponitrile and caprolactam producers commanding captive feedstock supply. The market structures around three tiers: monomer-integrated majors, specialized compounders with regional logistics dominance, and niche bio-based grade developers. M&A activity targets backward integration into hexamethylenediamine supply, while capacity expansion concentrates along Gulf Coast chemical corridors to exploit natural gas feedstock economics.
Within the integrated major tier, INVISTA leverages Gulf Coast adiponitrile capacity to sustain feedstock cost advantages, while DuPont de Nemours Inc. anchors premium PA 66 positioning through specialized thermal-stability grades. Ascend Performance Materials occupies the merchant resin channel with backward-integrated hexamethylenediamine supply, exemplifying the scale-driven archetype that dominates high-volume automotive procurement.
| Leading Market Players |
|---|
| INVISTA |
| Arkema |
| BASF SE |
| Huntsman Corporation |
| AdvanSix Inc. |
| DuPont de Nemours Inc. |
| Celanese Corporation |
| EMS-Chemie |
| Ascend Performance Materials |
| Others |
Pricing and Supply Chain Analysis
Gulf Coast barge corridors connecting Texas and Louisiana polymerization hubs to Michigan assembly plants concentrate logistics costs that amplify feedstock pricing power among adiponitrile producers while forcing compounders to absorb premiums for thermal-stability grades serving EPA-mandated automotive applications.
Pricing Analysis
Aftermarket component refurbishment and extended service contracts now capture lifetime value exceeding original resin sales for Tier 1 suppliers. Three-tier pricing structure across premium thermal-stability grades, standard injection-molding compounds, and economy textile-chip tiers reflects certification barriers and captive monomer integration. Pricing pressure stems from automotive procurement consolidation compressing approved material lists. Mexican OEM buyers exhibit acute price sensitivity, while U.S. compounders absorb premiums without volume elasticity shifts.
Supply Chain Analysis
Export-control scrutiny on advanced polymerization catalyst technologies limits equipment flows to certain jurisdictions, constraining capacity expansion options outside integrated majors. Supply concentrates in the United States, Germany, and China, with hexamethylenediamine and caprolactam as critical dependencies. Single-source vulnerability pervades adiponitrile supply where four producers dominate global precursor capacity. Distribution runs through merchant resin channels anchored by backward-integrated compounders serving just-in-sequence automotive delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated Detroit Three procurement organizations that have compressed approved material lists from over 200 grades to fewer than 50 core SKUs, fragmenting margin pools for non-integrated compounders.
For Market Incumbents: Insulate margin positions through captive adiponitrile or caprolactam integration that neutralizes feedstock volatility threatening PA 66 compounders. Expand technical service capabilities for high-fill glass-reinforced grade qualification as metal substitution timelines compress under NHTSA fuel-economy mandates. Lock in five-to-seven year single-source agreements with price-volume banding tied to benzene and natural gas indices before procurement consolidation excludes merchant resin suppliers.
For New Entrants and Emerging Players: Bio-based PA 11 and PA 12 grades for medical catheters and additive manufacturing powders represent the most penetrable entry point where castor oil feedstock constraints and lot-to-lot consistency requirements deter commodity competition. Quebec's circular-economy framework for carpet and fishing net chemical recycling offers offtake certainty for depolymerization ventures. Target compounders lacking backward integration with toll-manufacturing partnerships that leverage existing Gulf Coast polymerization assets.
For Investors and Strategic Acquirers: Specialized compounders with validated mechanical recycling streams and California AB 1793 compliance pathways offer acquisition exposure to recycled-content mandate premiums. Long-term viability hinges on circular-economy framework adoption across North American jurisdictions. Monitor bio-based PA platform scale-up timelines and recycled-content threshold enforcement as inflection indicators for specialty grade margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adiponitrile | Captive hexamethylenediamine supply neutralizes force majeure risk from concentrated global producers. |
| High-Fill Grade Capacity Expansion | 50-60 percent glass-reinforced PA 66 compounds displace aluminum in transmission brackets under EPA mandates. |
| Chemical Recycling Scale-Up | Quebec EPR programs create offtake certainty for caprolactam recovery from carpet waste streams. |
| Additive Manufacturing Powder Qualification | Laser sintering of PA 12 commands 40-60 percent premiums over injection grades in aerospace ducting. |
| California Compliance Investment | AB 1793 recycled-content thresholds favor first-movers with validated post-consumer resin streams. |
Research Methodology
A spread of perspectives from resin-compounder procurement leads, OEM platform engineers, Tier 1 supplier technical directors, and chemical recycling facility operators converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from customs and trade data, ACC industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up volume modeling across grade tiers, end-use industries, and regional production hubs triangulated against top-down market sizing from producer capacity disclosures.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry, physical form, end-use sector, and functional application alongside automotive content-per-vehicle trajectories under evolving fuel-economy standards. CAGRs derived from elasticity-adjusted volume projections and value-per-ton trends. Industry-specific forecast inputs encompassed benzene-natural gas spread correlations and automotive platform standardization timelines.
Practitioners should monitor adiponitrile supply disruptions, recycled-content mandate enforcement schedules, and bio-based feedstock crop yield volatility for early signals requiring forecast reassessment. Material shifts in EPA-NHTSA regulatory alignment or circular-economy framework adoption across additional provinces would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Antimicrobial Plastics Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Polystyrene Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Polybutylene Succinate (PBS) Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
Polyimides Market
Polymers & Resins
Epoxy Resin Market