
 Wearable Adhesives Market | 2026-2036
Wearable Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Adhesives Market Analytics
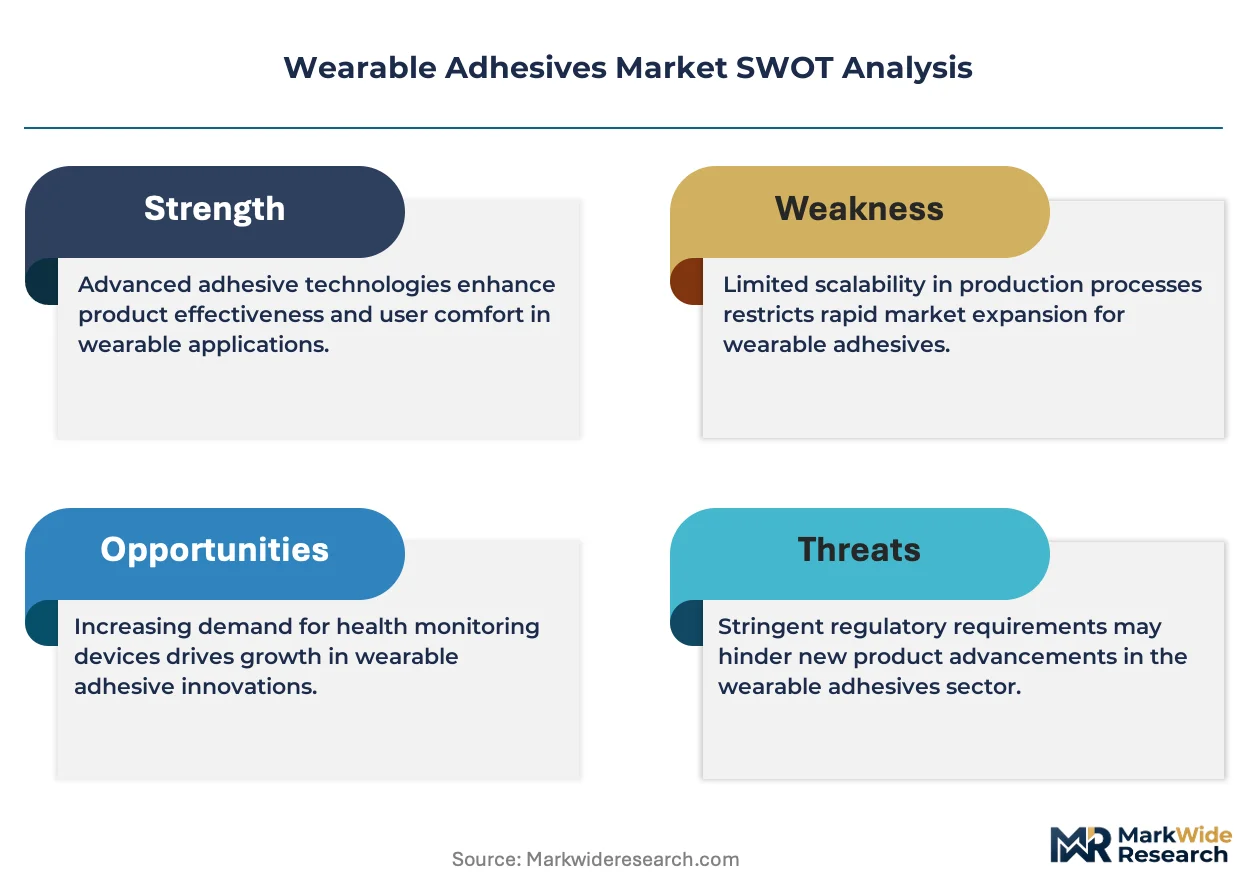
ISO 10993 biocompatibility certification is unwinding the competitive landscape, forcing smaller compounders to outsource toxicology testing while established firms consolidate market access. 3M Company leverages its vertical integration from fluoropolymer synthesis to finished tape converting, sustaining pricing power across hospital and consumer channels. Henkel AG & Co. KGaA anchors European supply through its medical-grade acrylic platform, while Adhezion Biomedical, LLC specializes in cyanoacrylate skin-bonding chemistry for emergency and surgical closure applications.
Wearable adhesives comprise pressure-sensitive, thermosetting, and heat-activated formulations engineered for extended skin contact, typically incorporating hypoallergenic acrylics, silicones, or hydrocolloids with moisture-vapor transmission rates between 300 and 2500 g/m²/day to prevent maceration during seven-to-fourteen-day wear cycles. Their primary purpose is to affix medical devices, fitness sensors, and drug-delivery systems to human skin without irritation or mechanical failure. Skin adhesives dominate value capture due to premium pricing for hypoallergenic and breathable formulations, while pressure-sensitive technology leads volume because of its compatibility with high-speed roll-to-roll coating and cleanroom lamination processes used in continuous glucose monitor manufacturing.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines, with both agencies demanding extensive cytotoxicity and sensitization data for new adhesive chemistries. The EPA and ECHA additionally restrict residual monomer content through TSCA and REACH frameworks, pushing manufacturers toward solvent-free UV-curable systems. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring, as CMS coverage decisions directly influence volume commitments from diabetic care and cardiology device OEMs.
Market Dynamics
ISO 10993 biocompatibility testing requirements are restructuring competitive access, forcing smaller compounders to surrender margin on outsourced toxicology validation while vertically integrated manufacturers capture hospital procurement contracts through captive certification capabilities.
Growth Catalysts
- FDA 510(k) pathway expansion:Streamlined clearance for continuous glucose monitor adhesives accelerates OEM time-to-market for fourteen-day wear formulations.
- Japan's aging demographic:METI reimbursement codes for home-based cardiac monitoring expand addressable patient populations for extended-wear patches.
- Solvent-free UV curing:This manufacturing shift eliminates residual monomer concerns under REACH and TSCA frameworks while reducing volatile organic compound emissions.
Market Restraints
- Medical-grade silicone supply:Dow and Wacker Chemie control over seventy percent of high-purity elastomer feedstock, creating single-source vulnerability for hydrocolloid compounders.
- ECHA monomer restrictions:REACH Substance of Very High Concern listings for residual acrylates force reformulation cycles that extend qualification timelines by eighteen to twenty-four months.
- Skin irritation liability:Hypoallergenic certification failures expose manufacturers to class-action exposure in US federal courts, compressing risk-adjusted returns on novel chemistries.
Strategic Opportunities
- Pediatric wearable expansion:Neonatal monitoring patches remain underpenetrated due to limited ISO 10993-10 sensitization data for infant dermal contact, creating first-mover advantage for dedicated toxicology investment.
- EU MDR Article 117:Device-integral adhesive requirements under the 2017/745 regulation favor European compounders with notified body relationships, disadvantaging importers.
- Silicone-acrylic hybridization:Convergence of moisture-vapor transmission control with pressure-sensitive processing compatibility enables seven-day wear cycles in tropical climates.
Industry Challenges
- Cleanroom coating capacity:Roll-to-roll lamination for continuous glucose monitor manufacturing requires ISO Class 7 infrastructure that demands fifteen to twenty million dollar capital deployment per production line.
- ISO 10993-5 cytotoxicity backlog:Contract research organization queue times for in vitro testing now exceed six months, delaying product launches regardless of technical readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Adhesives Market |
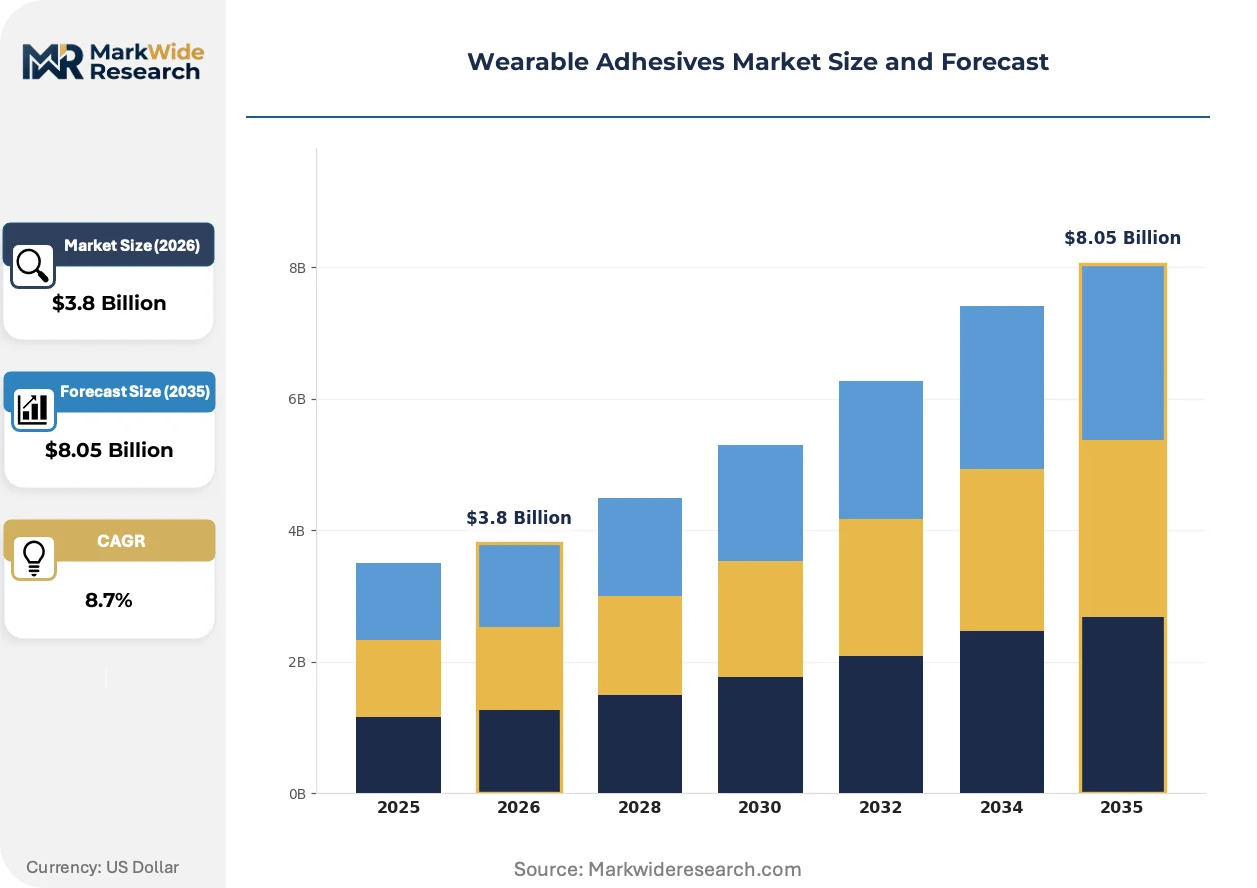
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Adhesives, Textile Adhesives, Medical Tapes, Waterproof Adhesives Technology: Pressure-Sensitive, Thermosetting, Heat-Activated, Solvent-Based End User: Healthcare Providers, Sports Industry, Consumer Electronics, Defense Sector Application: Monitoring Devices, Medical Devices, Wearable Fitness Tech, Personal Care |
| Companies Covered | 3M Company, Avery Dennison Corporation, Henkel AG & Co. KGaA, H.B. Fuller Company, Scapa Group Ltd., Adhesives Research, Inc., Polymer Science, Inc., Adhezion Biomedical, LLC, Lohmann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Adhesives Market Evolving Landscape
Material convergence and regulatory digitization are compressing traditional qualification timelines while fragmenting the vendor base between certified specialists and commodity suppliers.
Silicone-acrylic hybrid adhesives are fragmenting the historical segmentation between breathable silicone gels and processable acrylics. Continuous glucose monitor manufacturers in Germany and Massachusetts are qualifying these formulations for ten-day wear cycles. The technology is fragmenting procurement patterns as OEMs reduce qualified supplier lists from twelve to four vendors capable of dual-chemistry synthesis.
EU MDR Annex I general safety and performance requirements are tightening post-market surveillance obligations for skin-contact adhesives. Manufacturers must now maintain clinical follow-up data for five years after device launch. Cardiac patch developers in Ireland and the Netherlands are responding by integrating RFID traceability into release liners.
Hospital procurement departments are consolidating adhesive sourcing through group purchasing organizations, displacing direct OEM-contractor relationships. This concentration is most visible in US health systems where three buying consortiums now control sixty percent of medical-grade tape volume. Compounders are responding with dedicated contract manufacturing organizations staffed for just-in-time converting.
Wearable Adhesives Market Segmentation
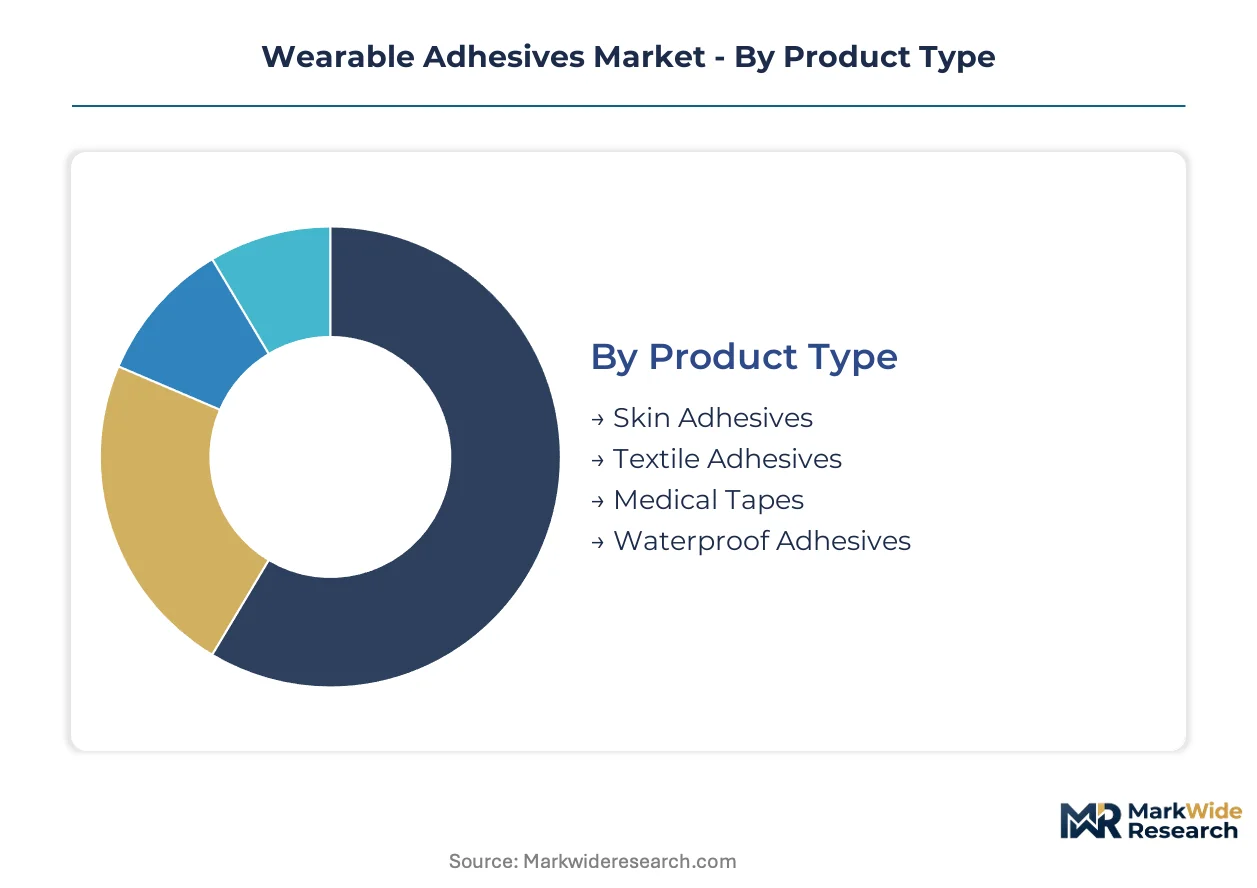
Wearable adhesive formulations face divergent qualification pathways depending on skin contact duration and device classification. Segmentation reveals how ISO 10993 testing burdens concentrate in clinical applications while consumer electronics tolerate shorter certification cycles.
Product Type:
FDA 510(k) clearance requirements and EU MDR Article 117 obligations stratify margins across adhesive categories, with extended-wear clinical formulations commanding premium pricing against commodity consumer grades.
- Skin Adhesives:Hypoallergenic acrylic, silicone, and hydrocolloid compositions engineered for seven-to-fourteen-day dermal contact with moisture-vapor transmission rates between 300 and 2500 g/m²/day. Continuous glucose monitor OEMs in Massachusetts and Germany specify these formulations for extended-wear cardiac and diabetic monitoring patches where ISO 10993-5 cytotoxicity certification is mandatory.
- Medical Tapes:Woven and non-woven backing materials laminated with pressure-sensitive adhesives for device fixation and surgical draping. Hospital procurement consolidation through US group purchasing organizations concentrates volume here, with three buying consortiums now controlling sixty percent of medical-grade tape commitments.
- Textile Adhesives:Polyurethane and hot-melt formulations bonding sensors to fabric substrates in fitness apparel.
- Waterproof Adhesives:Marine-grade and shower-resistant coatings for swim-trackable wearables.
Established volume favors medical tapes; emerging adoption favors skin adhesives.
Technology:
Manufacturing capital intensity separates technologies, with cleanroom roll-to-roll coating infrastructure demanding fifteen to twenty million dollar deployment per production line.
- Pressure-Sensitive:Tackifier-modified acrylics and synthetic rubbers enabling immediate adhesion without thermal activation. High-speed converting compatibility drives volume leadership in continuous glucose monitor manufacturing where ISO Class 7 lamination is standard.
- Heat-Activated:Pre-applied films requiring thermal trigger for bonding, common in textile-integrated sensors where substrate heat sensitivity complicates processing.
- Thermosetting:Cross-linked epoxies and polyurethanes for permanent device encapsulation.
- Solvent-Based:Conventional coatings facing ECHA REACH and EPA TSCA residual monomer restrictions.
Capital deployment favors pressure-sensitive; regulatory pressure favors solvent-free alternatives.
End User:
Reimbursement codes determine addressable demand, with CMS remote therapeutic monitoring coverage expanding hospital-at-home volumes against out-of-pocket consumer electronics.
- Healthcare Providers:Hospitals, clinics, and home health services requiring FDA 510(k) cleared or EU MDR certified adhesives for cardiac patches, infusion pumps, and wound care devices. Japan's METI reimbursement for home-based monitoring expands this segment through aging demographic demand.
- Consumer Electronics:Fitness tracker and smartwatch manufacturers tolerating shorter biocompatibility validation for fourteen-day replacement cycles.
- Sports Industry:Performance monitoring and injury prevention applications.
- Defense Sector:Ruggedized biometric tracking for personnel monitoring.
Regulatory rigor favors healthcare providers; volume scale favors consumer electronics.
Application:
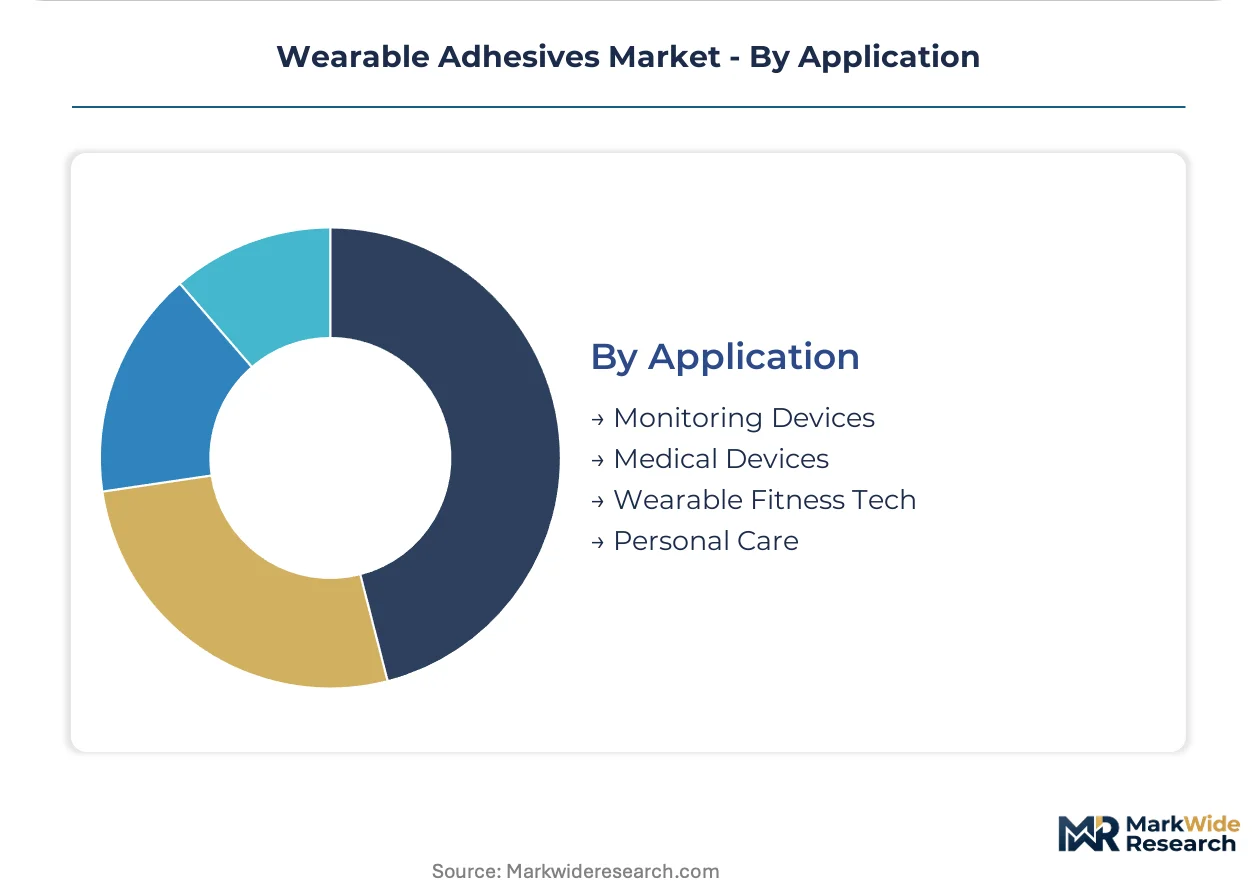
Wear duration and skin contact area dictate material selection, with multi-day monitoring demanding breathable silicone-acrylic hybrids against single-use personal care films.
- Monitoring Devices:Continuous glucose monitors, cardiac patches, and sleep trackers requiring moisture management and gentle removal. Silicone-acrylic hybrid qualification for ten-day wear cycles is fragmenting procurement patterns as OEMs reduce qualified suppliers.
- Medical Devices:Drug-delivery systems, ostomy appliances, and surgical closures where ISO 10993-10 sensitization data is mandatory.
- Wearable Fitness Tech:Activity trackers and biometric sensors with shorter replacement intervals.
- Personal Care:Cosmetic patches and beauty devices with minimal regulatory burden.
Technical complexity favors monitoring devices; margin pressure favors personal care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policies and aging demographics are concentrating adhesive demand in markets with established home-health infrastructure. CMS remote therapeutic monitoring codes, Japan's METI home-care expansion, and Germany's DiGA fast-track for digital therapeutics are accelerating patch-based diagnostic deployment.
United States
CMS coverage for continuous glucose monitor adhesives drives hospital-at-home volumes. FDA 510(k) pathway streamlines fourteen-day wear formulations for diabetic care OEMs. Massachusetts and California clusters house the dominant continuous glucose monitor manufacturers qualifying silicone-acrylic hybrids.
Germany
EU MDR Article 117 device-integral adhesive requirements favor domestic compounders with notified body relationships. ECHA REACH residual monomer restrictions push manufacturers toward solvent-free UV-curable systems. The Rhine-Ruhr and Bavaria regions concentrate cleanroom coating capacity for cardiac patch production.
Japan
METI reimbursement codes for home-based cardiac monitoring expand addressable patient populations. PMDA biocompatibility standards align with ISO 10993-5 cytotoxicity protocols for extended-wear applications. Tokyo-Osaka corridor hosts specialized toxicology contract research organizations serving patch developers.
China
NMPA medical device classification for skin-contact adhesives is tightening qualification timelines for imported formulations. Domestic fitness tracker OEMs tolerate shorter biocompatibility validation for consumer-grade wearables. Shenzhen and Shanghai clusters drive volume for textile-integrated sensor adhesives.
United Kingdom
MHRA post-Brexit regulatory autonomy is diverging from EU MDR implementation timelines for adhesive-integrated devices. NHS long-term plan targets remote monitoring for chronic disease management. Cambridge and Oxford medical device clusters are qualifying pediatric monitoring patches for neonatal applications.
Wearable Adhesives Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with captive medical-grade certification capabilities. Market access concentrates among compounders maintaining in-house toxicology validation and ISO 10993 testing infrastructure. Three strategic archetypes dominate: vertically integrated tape converters controlling fluoropolymer-to-finished-product pipelines, regional medical-grade acrylic specialists serving European hospital procurement, and cyanoacrylate-focused surgical closure compounders. Competitive moves center on cleanroom capacity expansion for continuous glucose monitor supply and notified body relationship cultivation under EU MDR.
Within the diversified chemical tier, 3M Company and Henkel AG & Co. KGaA represent contrasting geographic anchors for procurement consolidation. 3M exemplifies the vertically integrated archetype with control from raw polymer synthesis through finished tape converting. Henkel occupies a position as the European medical-grade acrylic platform serving hospital group purchasing organizations. Adhezion Biomedical, LLC sits within the surgical closure specialist tier, focusing on cyanoacrylate skin-bonding chemistry for emergency applications.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Scapa Group Ltd. |
| Adhesives Research, Inc. |
| Polymer Science, Inc. |
| Adhezion Biomedical, LLC |
| Lohmann GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Solvent-free UV-curable systems replacing solvent-based acrylics are redrawing supply geography toward Germany and Massachusetts cleanroom clusters while compressing margins for compounders locked into legacy coating infrastructure. This substitution simultaneously elevates capital barriers for new entrants and concentrates pricing power among vertically integrated manufacturers with captive polymer synthesis.
Pricing Analysis
Certification level creates the primary spread across the wearable adhesives market, with ISO 10993-5 cytotoxicity-validated formulations commanding substantial premiums over consumer-grade alternatives. Three-tier pricing structure separates FDA 510(k)-cleared clinical grades from CE-marked medical tiers and unvalidated economy batches. Cost compression in standard-grade segments is intensifying because hospital procurement consolidation through US group purchasing organizations squeezes contract margins. Consumer electronics OEMs exhibit highest price sensitivity due to fourteen-day replacement cycles, while cardiac patch developers accept premium positioning for extended-wear reliability.
Supply Chain Analysis
Germany and the United States anchor cleanroom roll-to-roll coating capacity for continuous glucose monitor adhesive production. Medical-grade silicone feedstock draws from Dow and Wacker Chemie facilities, while high-purity acrylic monomers feed from BASF and Arkema operations. Single-source vulnerability pervades hydrocolloid compounders dependent on consolidated elastomer suppliers. Distribution runs through device OEM direct procurement contracts and hospital group purchasing organization channels, with just-in-time converting relationships displacing spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable adhesives market functions as a regulatory-moat business where ISO 10993 certification entrenchment creates switching costs that lock hospital procurement contracts and fragment competitive entry. This defensive structure rewards early movers who internalized toxicology validation capabilities.
For Market Incumbents: Consolidate cleanroom coating capacity in Massachusetts and Bavaria to capture continuous glucose monitor volume commitments from diabetic care OEMs. Deepen backward integration into fluoropolymer synthesis to defend margin position against raw material volatility from Dow and Wacker Chemie supply concentration.
For New Entrants and Emerging Players: Lead with pediatric monitoring patch formulations where ISO 10993-10 sensitization data scarcity has stalled incumbent qualification timelines. Target neonatal applications in Cambridge and Oxford medical device clusters, leveraging contract research organization partnerships in the Tokyo-Osaka corridor to compress toxicology validation cycles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European medical-grade acrylic specialists holding notified body relationships under EU MDR Article 117. Five-to-ten-year viability hinges on CMS remote therapeutic monitoring reimbursement expansion and METI home-care code proliferation. Watch FDA 510(k) backlog clearance velocity as inflection indicator for OEM volume commitment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO Class 7 roll-to-roll infrastructure captures continuous glucose monitor OEM contracts in Massachusetts clusters. |
| Backward Integration into Polymer Synthesis | Captive fluoropolymer production sustains pricing power across hospital and consumer distribution channels. |
| EU MDR Notified Body Relationship Cultivation | Device-integral adhesive certification under Article 117 favors domestic European compounders over importers. |
| Pediatric Toxicology Investment | Dedicated ISO 10993-10 infant dermal contact data creates first-mover positioning in underpenetrated neonatal segments. |
| Solvent-Free UV Curing Transition | Elimination of residual monomer concerns aligns with ECHA REACH and EPA TSCA compliance trajectories. |
Research Methodology
Operator-level perspectives from adhesive compounders, continuous glucose monitor OEM procurement directors, hospital GPO contracts managers, and contract research organization toxicologists anchored the qualitative base. Primary interview insights triangulated against FDA 510(k) submission databases, ECHA REACH substance registrations, CMS Medicare reimbursement code filings, and customs trade flow records. Bottom-up segment sizing across product type, technology, end user, and application dimensions converged with top-down macro validation.
Sensitivity analysis stress-tested volume and value outputs across the analysis window against regulatory approval timeline variations and raw material supply disruption scenarios. Segmentation modeling incorporated wear duration requirements, skin contact area specifications, moisture-vapor transmission performance tiers, and regional reimbursement framework clusters. CAGRs derived from fitted growth curves calibrated to OEM device launch schedules and hospital procurement cycle data.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways, EU MDR Article 117 implementation timelines, and METI reimbursement code stability; material policy shifts in any regime would require re-modeling. Specific risks include ECHA monomer restriction acceleration, ISO 10993-5 cytotoxicity testing queue prolongation, and medical-grade silicone supply concentration events. Recalibration cycles align with material shifts in CMS coverage determinations and OEM qualification pattern changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Europe EVA Adhesives Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
India Construction Chemicals Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
India Adhesives Market