
 Low Density Polyethylene Market | 2026-2036
Low Density Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Low Density Polyethylene Market Intelligence
Multi-sourced feedstock procurement is decoupling from traditional naphtha-integrated refining models across the LDPE value chain. Dow leverages its Gulf Coast ethane access to sustain cost-advantaged autoclave production. SABIC anchors Middle Eastern supply through its Yanbu complex, while Borealis AG differentiates via its Borstar technology platform and European circular-economy partnerships.
Low density polyethylene is a branched thermoplastic polymer synthesized through high-pressure free-radical polymerization, typically operating at pressures above 1000 bar and temperatures between 120°C and 350°C, yielding densities of 0.910–0.940 g/cm³ with crystallinity below 60%. Its molecular architecture delivers exceptional clarity, flexibility, and moisture-barrier performance, making it indispensable for food preservation films, medical device packaging, and agricultural greenhouse covers. Films dominate product-type value pools given their penetration across retail and industrial packaging, while healthcare applications command premium positioning due to sterilization-grade compliance requirements. Agricultural films represent the fastest-growing application segment as climate-adaptive farming expands substrate protection demand across water-stressed growing regions.
FDA food-contact regulations, EPA emissions standards for high-pressure polymerization facilities, and REACH substance restrictions collectively shape formulation chemistry and plant siting decisions in major LDPE-producing jurisdictions. China's GB standards and evolving MEE environmental enforcement are tightening permissible volatile organic compound thresholds, accelerating capital deployment toward emission-controlled reactor technologies. Stakeholders must monitor regulatory divergence between EU circular-content mandates and US IRA-aligned clean manufacturing incentives to optimize regional capacity allocation without locking into stranded asset configurations.
Market Dynamics
China's MEE emissions enforcement and dual carbon goals are forcing LDPE producers to abandon legacy high-pressure autoclave configurations in favor of emission-controlled reactor systems, reshaping capital deployment timelines across Asian manufacturing corridors.
Growth Catalysts
- Flexible packaging demand:Food preservation films and pharmaceutical blister packs anchor volume expansion as retail distribution networks densify across India and Vietnam.
- REACH circular-content mandates:European Union regulatory pressure is pulling post-consumer recycled LDPE into food-contact applications previously reserved for virgin resin.
- Agricultural substrate protection:Climate-adaptive farming techniques are accelerating greenhouse film replacement cycles in water-stressed growing regions of Spain and California.
Market Restraints
- Naphtha-ethane feedstock volatility:Crude oil price swings compress margin predictability for non-integrated producers lacking captive ethane access.
- Middle Eastern supply concentration:Over half of export-oriented LDPE capacity clusters in Saudi Arabia and Kuwait, creating single-source vulnerability for European compounders.
- Linear low-density substitution:LLDPE's superior puncture resistance is displacing conventional LDPE in heavy-duty shipping sacks and industrial liners.
Strategic Opportunities
- Underpenetrated Vietnamese processing:Northern industrial zones around Hai Phong lack sufficient extrusion capacity to convert imported resin into finished films.
- US IRA clean manufacturing credits:Section 45Q carbon capture incentives reward producers retrofitting high-pressure polymerization facilities with emission abatement systems.
- Digital inventory platforms:B2B resin marketplaces are compressing procurement cycles for mid-sized converters previously dependent on distributor networks.
Industry Challenges
- High-pressure reactor engineering talent:Specialized knowledge of free-radical polymerization kinetics at 1000+ bar is concentrating among retiring cohorts at major chemical engineering firms.
- FDA food-contact notification timelines:Novel additive packages for recycled-content LDPE face 180-day premarket review cycles that delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Density Polyethylene Market |
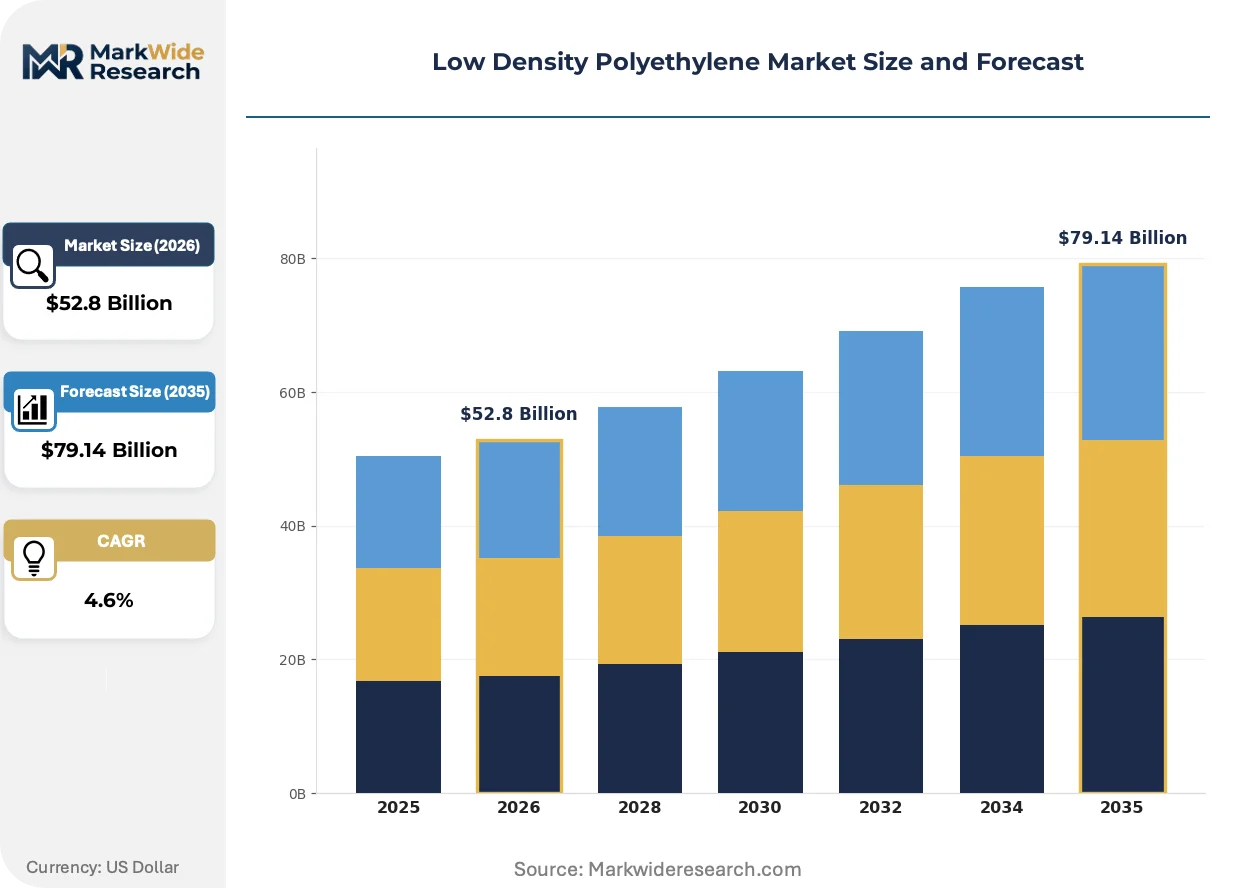
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $79.14 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Bags, Containers, Liners Application: Packaging, Agricultural, Consumer Goods, Healthcare End User: Manufacturers, Retailers, Hospitals, Distributors Distribution Channel: Online, Direct Sales, Wholesalers, Retail Stores |
| Companies Covered | SABIC, Braskem, Dow, Borealis AG, INEOS, ExxonMobil Corporation, China Petroleum & Chemical Corporation, Chevron Phillips Chemical Company, LyondellBasell Industries Holdings B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Density Polyethylene Market Strategic Shifts & Innovations
Process intensification and molecular architecture control are compressing the traditional trade-off between clarity and mechanical strength, enabling next-generation films to penetrate premium packaging segments previously dominated by multilayer structures.
Advanced metallocene catalyst systems are unifying molecular weight distribution control with long-chain branching precision. Medical device packaging manufacturers in Germany and Switzerland are adopting these resins at twice the rate of standard converters. The technology is unifying sterilization-grade compliance with downgauging economics, collapsing the premium gap between pharmaceutical and general-purpose films.
China's evolving GB standards for volatile organic compound emissions are mandating closed-loop vent recovery on all new high-pressure polymerization installations. Domestic producers in Zhejiang and Jiangsu provinces are retrofitting existing autoclave trains with thermal oxidizer systems ahead of enforcement deadlines. Food-contact film extruders face reformulation requirements as MEE inspectors tighten residual monomer thresholds.
Converter procurement patterns are fragmenting as regional brand owners establish direct resin relationships to secure recycled-content certificates for ESG reporting. Large multinational packaging groups are disintermediating traditional distributors in favor of toll-compounding arrangements with certified circular feedstock suppliers. This shift is most pronounced in the Netherlands and California, where extended producer responsibility laws mandate minimum recycled content in flexible packaging.
Low Density Polyethylene Market Segmentation
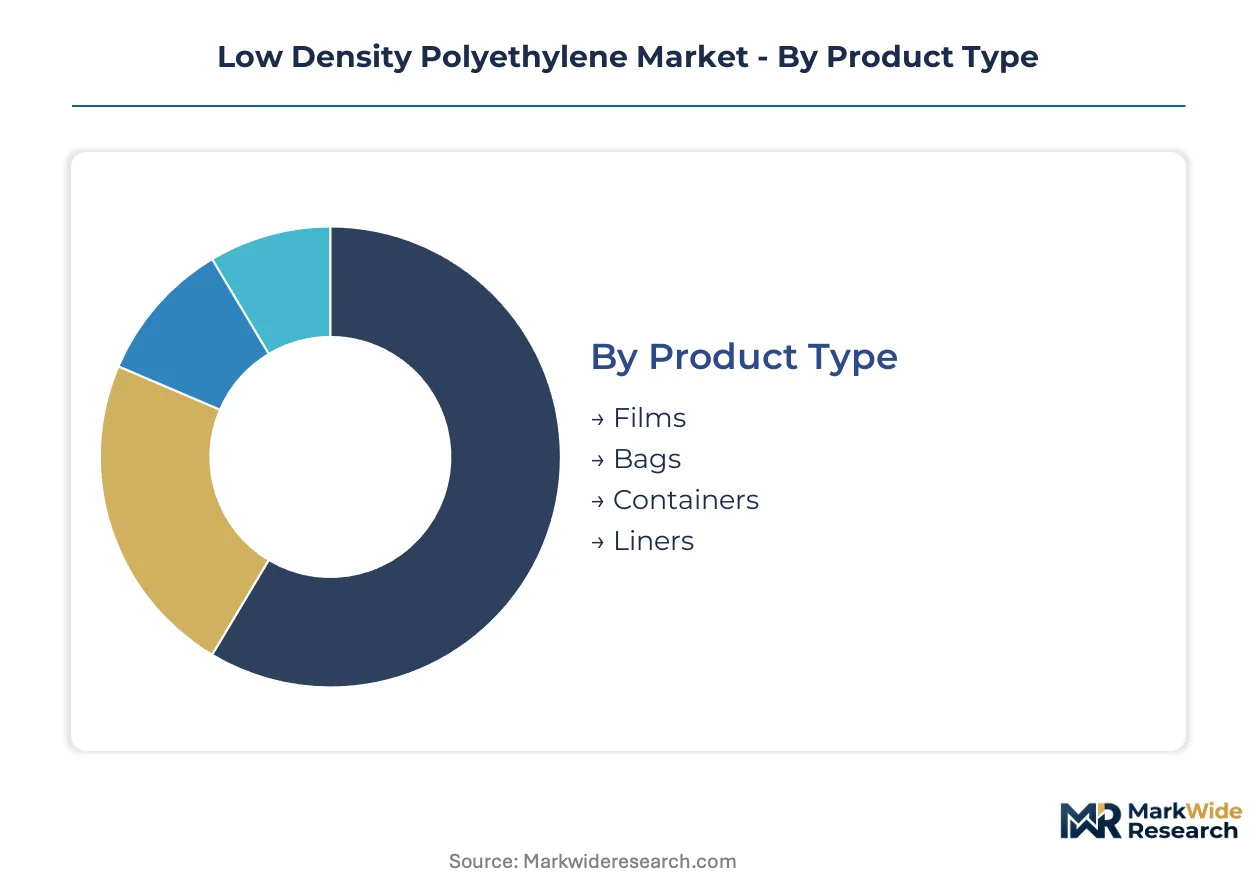
LDPE segmentation reveals how molecular architecture maps to divergent margin structures. Film-grade resins command premium positioning through clarity specifications, while commodity extrusion grades compete on throughput economics. Understanding these tiered value pools enables capacity allocation decisions across reactor configurations.
Product Type:
Customization intensity varies sharply across this category, with medical-grade films requiring batch-level certification while commodity liners ship to generic specifications.
- Films:Transparent, flexible sheets produced through blown or cast extrusion, typically 10-200 microns thick. Food-contact film demand concentrates in India's retail modernization corridors, where cold-chain expansion is accelerating multilayer barrier adoption. FDA notification timelines for novel additive packages compress margin predictability for specialty grades.
- Bags:Converted film structures ranging from thin-gauge grocery sacks to heavy-duty industrial totes. E-commerce fulfillment networks in Vietnam and Indonesia are pulling gusseted bag specifications toward higher dart-impact resistance. Virgin resin mandates in California and the Netherlands are forcing reformulation toward certified recycled-content grades.
- Containers:Rigid hollow articles produced through injection or blow molding. Dairy and condiment packaging in Germany and Switzerland favors clarity-optimized grades with narrow molecular weight distribution.
- Liners:Protective barriers for drums, boxes, and bulk transport vessels. Industrial chemical handling in Texas and Louisiana drives drum liner specifications toward stress-crack resistance.
Most installed capacity flows through Films. Expansion is steepest in Liners as bulk chemical logistics densify across Asian manufacturing corridors.
Application:
Volume concentration sits with packaging, though margin extraction follows regulatory complexity into healthcare and agricultural segments.
- Packaging:Flexible food preservation, pharmaceutical blister packs, and retail display films. REACH circular-content mandates are pulling post-consumer recycled LDPE into food-contact applications previously reserved for virgin resin in the Netherlands and Belgium. Downgauging economics favor metallocene-catalyzed grades with enhanced puncture resistance.
- Agricultural:Greenhouse covers, mulch films, and silage wrap. Water-stressed growing regions in Spain and California are accelerating replacement cycles for UV-stabilized greenhouse films. Climate-adaptive farming techniques are expanding substrate protection demand beyond traditional Mediterranean production zones.
- Consumer Goods:Toys, housewares, and disposable cutlery. BIS quality certification requirements in India are tightening dimensional tolerance specifications for injection-molded articles.
- Healthcare:Sterilization-grade pouches, IV bags, and medical device packaging. German and Swiss manufacturers are adopting metallocene resins at twice the rate of standard converters, unifying sterilization compliance with downgauging economics.
Packaging absorbs the majority of reactor output. Healthcare climbs the fastest as sterilization-grade compliance requirements tighten across European medical device regulations.
End User:
Procurement scale and technical sophistication create distinct service requirements across this category.
- Manufacturers:Integrated converters with captive extrusion or molding operations. Northern Vietnam's industrial zones around Hai Phong lack sufficient extrusion capacity to process imported resin into finished films, creating toll-compounding opportunities.
- Retailers:Brand owners specifying direct resin relationships for ESG reporting certificates. Extended producer responsibility laws in California and the Netherlands mandate minimum recycled content in flexible packaging, fragmenting traditional distributor relationships.
- Hospitals:Healthcare systems with sterilization-grade procurement protocols. Swissmedic and FDA dual-notification requirements extend qualification timelines for novel resin grades.
- Distributors:Intermediary networks facing disintermediation pressure from B2B digital marketplaces. Mid-sized converters previously dependent on distributor inventory are compressing procurement cycles through resin marketplaces.
Manufacturers channel the dominant resin flow. Retailers are gaining share fastest as ESG reporting mandates force direct supplier relationships.
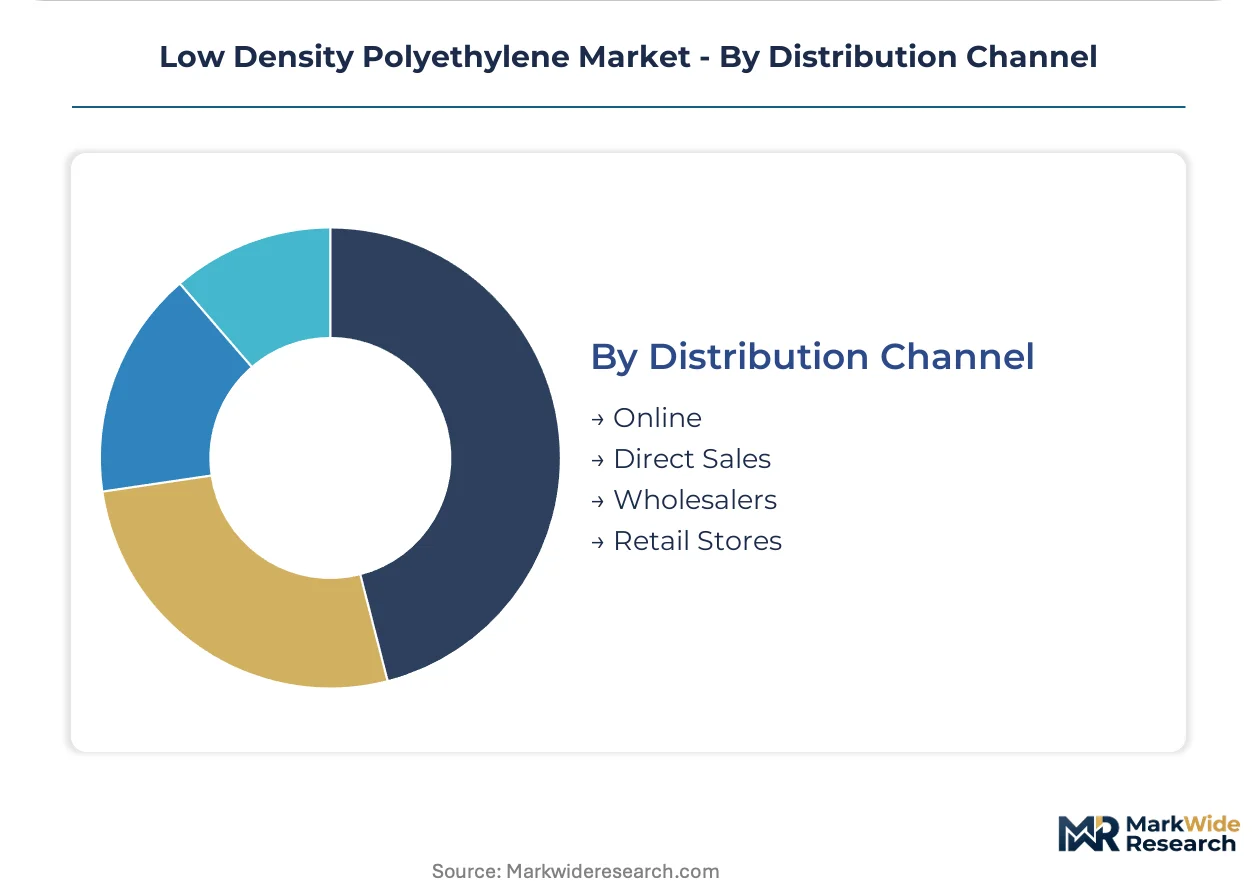
Distribution Channel:
Digital penetration fragments legacy channel structures, though high-volume contracts sustain direct sales relationships.
- Online:B2B resin marketplaces and digital procurement platforms. Mid-sized converters in India and Vietnam are migrating spot purchases away from traditional distributor networks toward platform-based inventory discovery.
- Direct Sales:Long-term offtake agreements between producers and integrated converters. Dow's Gulf Coast ethane access sustains cost-advantaged autoclave production sold through direct contracts.
- Wholesalers:Regional inventory aggregators serving fragmented converter bases. Northern European compounders rely on Rotterdam-hub wholesalers to manage Middle Eastern supply concentration risk.
- Retail Stores:Limited specialty resin sales through trade-counter formats. Small-batch specialty grades for prototype molding circulate through technical distributor storefronts in Germany and Switzerland.
Direct Sales handles the majority of volume contracted. Online channels are expanding most quickly as procurement digitization penetrates mid-tier converter segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors global LDPE processing capacity, with Zhejiang and Jiangsu provinces hosting concentrated autoclave reactor installations serving food-contact film demand across Asia-Pacific manufacturing corridors.
China
Flexible packaging for cold-chain retail and pharmaceutical blister packs drives resin consumption in Shanghai and Ningbo industrial zones. MEE emissions enforcement and dual carbon goals are forcing producers to retrofit legacy high-pressure autoclave trains with thermal oxidizer systems ahead of 2025 deadlines. Zhejiang province's chemical clusters are deploying capital toward emission-controlled reactor technologies to maintain operating permits.
United States
E-commerce fulfillment networks and agricultural greenhouse film replacement cycles sustain demand across Texas and Louisiana chemical corridors. EPA emissions standards for high-pressure polymerization facilities shape plant siting decisions, while Section 45Q carbon capture incentives reward emission abatement retrofits. Dow leverages Gulf Coast ethane access to sustain cost-advantaged autoclave production sold through direct offtake contracts.
Germany
Medical device packaging manufacturers in Bavaria and Baden-Württemberg adopt metallocene-catalyzed resins at elevated rates for sterilization-grade compliance. REACH circular-content mandates pull post-consumer recycled LDPE into food-contact applications previously reserved for virgin resin. The Ruhr industrial region maintains compounder capacity serving pharmaceutical and dairy packaging specifications.
India
Retail modernization corridors in Maharashtra and Gujarat accelerate multilayer barrier film adoption as cold-chain infrastructure expands. BIS quality certification requirements tighten dimensional tolerance specifications for injection-molded consumer goods. Northern industrial zones around Hai Phong lack sufficient extrusion capacity, creating toll-compounding opportunities for imported resin conversion.
Saudi Arabia
Export-oriented LDPE capacity clusters in Yanbu and Jubail supply European compounders facing Middle Eastern supply concentration risk. SABIC anchors regional production through integrated refining-petrochemical complexes with captive ethane feedstock. The kingdom's industrial cities are expanding specialty-grade output for healthcare and agricultural film applications.
Low Density Polyethylene Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue circular-economy certification and regional toll-compounding partnerships. The market exhibits tiered concentration with integrated petrochemical majors controlling feedstock-advantaged capacity while mid-scale compounders specialize in medical-grade and recycled-content formulations. Strategic archetypes span Gulf Coast ethane-integrated producers, European circular-economy specialists, and Asian toll-compounding intermediaries. Dominant competitive moves include backward integration into cracker assets and technology licensing for emission-controlled reactor systems.
Among Middle Eastern ethane-integrated majors, SABIC and Sinopec occupy positions exemplifying feedstock-advantaged scale. Dow represents the Gulf Coast archetype with cost-optimized autoclave production. European circular-economy positioning is anchored by Borealis AG, which sits within the sustainability-tier through technology platform differentiation and regional recycling partnerships.
| Leading Market Players |
|---|
| SABIC |
| Braskem |
| Dow |
| Borealis AG |
| INEOS |
| ExxonMobil Corporation |
| China Petroleum & Chemical Corporation |
| Chevron Phillips Chemical Company |
| LyondellBasell Industries Holdings B.V. |
| Others |
Cost & Logistics Intelligence
Extended producer responsibility laws in California and the Netherlands mandating minimum recycled content in flexible packaging are forcing converters to secure certified circular feedstock certificates, compelling resin producers to reconfigure blending operations and absorb premium costs for traceability systems.
Pricing Analysis
Ethane-naphtha spread volatility passes through directly to LDPE margin structures, with Gulf Coast ethane-integrated producers commanding cost advantages over European naphtha-dependent operators. Three-tier pricing structure across sterilization-grade, food-contact certified, and commodity extrusion levels separates premium medical resins from standard film grades. Cost compression in commodity extrusion tiers is intensifying because LLDPE substitution erodes volume commitments. Mid-sized Vietnamese converters exhibit highest price sensitivity due to thin working capital buffers, while German medical device manufacturers show least sensitivity given sterilization-compliance requirements.
Supply Chain Analysis
Container freight rates from Yanbu and Jubail to Rotterdam remain critical cost components for European compounders sourcing Middle Eastern LDPE. Geographic supply concentration clusters in Saudi Arabia, China, and the United States, with over half of export-oriented capacity anchored in the kingdom's industrial cities. Raw material dependencies rest on ethane feedstock from associated gas production, naphtha from refining operations, and metallocene catalyst systems. Single-source vulnerability from Middle Eastern supply concentration creates structural risk for Northern European compounders lacking alternative sourcing. Distribution runs through long-term direct offtake agreements for integrated converters, with spot market liquidity concentrated in B2B digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LDPE markets function as a geographic-arbitrage play between Gulf Coast ethane economics and European circular-content premiums, with the spread between these cost bases widening under divergent regulatory trajectories.
For Market Incumbents: Deepen backward integration into cracker assets to lock in feedstock cost advantages against naphtha price swings. Incumbent producers should accelerate emission-controlled reactor retrofits ahead of China's MEE enforcement deadlines to defend operating permits in Zhejiang and Jiangsu provinces. Capacity consolidation around Hai Phong industrial zones captures toll-compounding demand from Vietnamese converters lacking extrusion infrastructure. For New Entrants and Emerging Players: Mid-sized Indian converters with BIS certification requirements but limited technical R&D capacity represent the most penetrable buyer archetype. New entrants should pursue toll-compounding partnerships with Zhejiang-based producers to access emission-compliant reactor capacity without capital-intensive greenfield investment. Digital inventory platforms offer go-to-market acceleration for spot-market liquidity provision. For Investors and Strategic Acquirers: Asymmetric upside sits with circular-economy specialists possessing certified recycling partnerships and food-contact regulatory clearances. Long-term viability over the projection horizon favors producers with dual feedstock flexibility and metallocene technology licensing. Acquisition targets should demonstrate thermal oxidizer retrofits or captive ethane access. The signal to watch is MEE enforcement intensity in Yangtze River Delta chemical clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cracker Assets | Gulf Coast ethane access sustains cost-advantaged autoclave production against naphtha volatility. |
| Emission-Controlled Reactor Retrofit | Thermal oxidizer installations preserve operating permits under China's tightening MEE standards. |
| Metallocene Catalyst Licensing | German medical device manufacturers adopt these resins at twice standard conversion rates. |
| Circular Feedstock Certification | REACH mandates pull post-consumer recycled LDPE into Dutch food-contact applications. |
| Toll-Compounding Partnership | Northern Vietnam's extrusion capacity gap creates conversion opportunities for imported resin. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at high-pressure polymerization facilities, procurement leads at flexible packaging converters, distribution channel partners in Rotterdam and Singapore hubs, and technical R&D directors at catalyst suppliers. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA emissions disclosures. Bottom-up reactor capacity modeling and top-down demand segmentation triangulated volume estimates.
Segment-weighting approaches distributed value across film-grade, bag-grade, container-grade, and liner-grade tiers, with further disaggregation by food-contact certification, sterilization compliance, and agricultural UV-stabilization specifications. End-use splits across packaging, agriculture, consumer goods, and healthcare applications informed demand elasticity assumptions. CAGRs were derived from installed capacity expansion timelines and substitution elasticity parameters. Forecast inputs incorporated ethane-naphtha spread projections and regulatory enforcement intensity indices.
Underlying measurement precision varies by segment; commodity extrusion grades carry tighter precision than emerging recycled-content formulations due to established trade flows. Forecasts reflect assumptions about MEE enforcement timelines and IRA credit permanence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
C5 Resin Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Bio-Based Polypropylene Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
Polyisobutylene (PIB) Market