
 Global UV Curable Resins and Formulated Products Market | 2026-2036
Global UV Curable Resins and Formulated Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global UV Curable Resins and Formulated Products Market Outlook
East Asian petrochemical producers is realigning capacity toward oligomer-grade acrylates serving radiation-curable formulations. Arkema leverages integrated acrylic acid chains in France and Thailand to sustain feedstock cost advantages for oligomer production. Allnex Netherlands B.V. anchors European supply of polyester and epoxy acrylates, while Covestro AG competes through aliphatic urethane acrylate specialization for high-performance coatings.
UV curable resins and formulated products comprise photoinitiator-doped oligomer and monomer blends that polymerize within seconds under ultraviolet or electron beam irradiation, achieving tack-free surfaces with solvent-free processing. These formulations serve industrial finishing, graphic arts bonding, and protective layer applications where throughput speed and low volatile organic compound emissions replace thermal drying systems. Coatings and adhesives command the largest value pools due to automotive clearcoat and electronics encapsulation demand, while UV LED technology displaces mercury vapor curing fastest as semiconductor source efficiency improves and mercury bans tighten across manufacturing jurisdictions. Photoinitiator chemistry remains the most contested innovation frontier, with Type I cleavage and Type II hydrogen abstraction systems optimized for 365 nm versus 395 nm LED peak wavelengths.
REACH registration requirements in Europe, EPA New Chemicals Program oversight in the United States, and China's GB standards for industrial coatings collectively restrict free-radical photoinitiator chemistries and mandate migration testing for food-contact applications. EMA and FDA device regulations further steer medical-grade adhesive formulations toward biocompatible urethane acrylates with exhaustive extractables profiles. Stakeholders must monitor photoinitiator substitution timelines and regional wavelength standard harmonization to align capital deployment with shifting curing infrastructure requirements.
Market Dynamics
Mercury vapor lamp bans across manufacturing jurisdictions are forcing immediate capital redeployment toward UV LED curing infrastructure, compressing equipment replacement cycles and rewiring procurement priorities for coating line operators.
Growth Catalysts
- REACH chemical safety mandates:German electronics manufacturers are retrofitting coating lines to eliminate solvent-based thermal drying, accelerating specification of acrylate oligomer systems for flexible circuit board protection.
- UV LED source efficiency gains:Semiconductor emitter improvements at 395 nm peak wavelength now deliver energy parity with mercury vapor at one-third the operating cost, pulling adoption in East Asian fabrication clusters.
- Food-contact migration testing protocols:Stricter extractables requirements under FDA and EFSA frameworks are filtering formulation choices toward Type II hydrogen abstraction photoinitiators with superior low-migration profiles.
Market Restraints
- Acrylic acid feedstock volatility:Oligomer-grade acrylate supply concentrates among integrated petrochemical producers in France and Thailand, exposing formulators to monomer price swings tied to propylene cracking economics.
- Photoinitiator wavelength lock-in:Capital-intensive LED curing installations commit operators to specific peak wavelengths, constraining formulation flexibility when 365 nm and 395 nm source standards diverge across jurisdictions.
- Thermal curing substitution persistence:High-temperature epoxy systems retain cost advantage in thick-film industrial coatings where UV penetration depth remains insufficient.
Strategic Opportunities
- Medical-grade adhesive certification:EMA and FDA device regulations are creating premium formulation tiers for biocompatible urethane acrylates with exhaustive extractables documentation.
- India industrial coating upgrade cycle:BIS standards alignment with VOC emission protocols is opening specification windows for radiation-curable systems in automotive and furniture finishing.
- UV-EB hybrid curing convergence:Electron beam pre-gelation followed by UV surface cure is enabling high-speed lines for pressure-sensitive adhesives in packaging applications.
Industry Challenges
- Formulation chemist scarcity:Free-radical polymerization expertise for photoinitiator-oligomer matching is concentrating among aging specialists in European coating technology centers.
- Legacy mercury line decommissioning:Japanese and German manufacturers face compressed timelines to replace vapor lamp infrastructure ahead of national bans without disrupting automotive clearcoat production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global UV Curable Resins and Formulated Products Market |
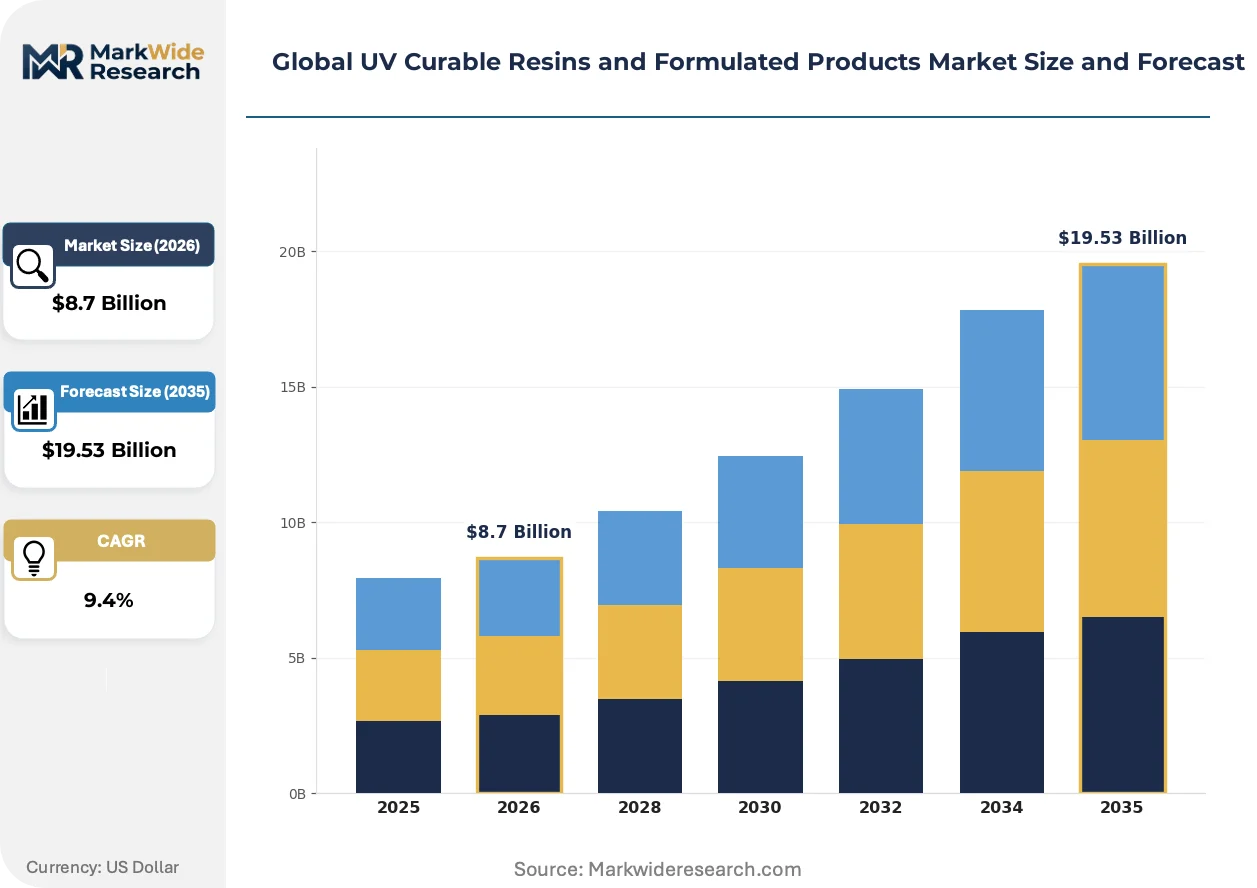
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Inks, Adhesives, Composites Application: Automotive, Electronics, Medical Devices, Packaging Technology: Photoinitiator, UV LED, Mercury Vapor, Electron Beam End User: Manufacturers, Contractors, Designers, Researchers |
| Companies Covered | Arkema, Alberdingk Boley GmbH, Allnex Netherlands B.V., Miwon Specialty Chemical Co., Ltd., Resonac Holdings Corporation, BASF SE, IGM Resins, DIC Corporation, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global UV Curable Resins and Formulated Products Market Strategic Shifts
Photoinitiator chemistry optimization is rewriting competitive positioning as LED wavelength standardization battles reshape formulation R&D priorities across coating and adhesive segments.
UV LED curing systems are rewriting throughput economics in electronics encapsulation. Flexible circuit board manufacturers in Taiwan and South Korea are specifying 395 nm peak wavelength arrays for instant tack-free surfaces. This wavelength concentration is rewriting photoinitiator development roadmaps as Type II hydrogen abstraction systems displace legacy cleavage chemistries.
China's GB standards for industrial coatings are rewriting compliance baselines for VOC emissions in manufacturing provinces. MEE enforcement protocols are accelerating line retrofits in Guangdong and Jiangsu electronics clusters. Domestic formulators are responding with localized oligomer production to bypass import dependency for acrylate feedstocks.
Automotive OEMs are consolidating adhesive specifications around single-source UV-curable platforms to compress qualification timelines. Tier-1 suppliers in Germany and Japan are abandoning multi-chemist procurement in favor of urethane acrylate systems with pan-regulatory pre-certification. This consolidation is most visible in EV battery module bonding where thermal management requirements intersect with flame-retardant mandates.
Global UV Curable Resins and Formulated Products Market Segmentation
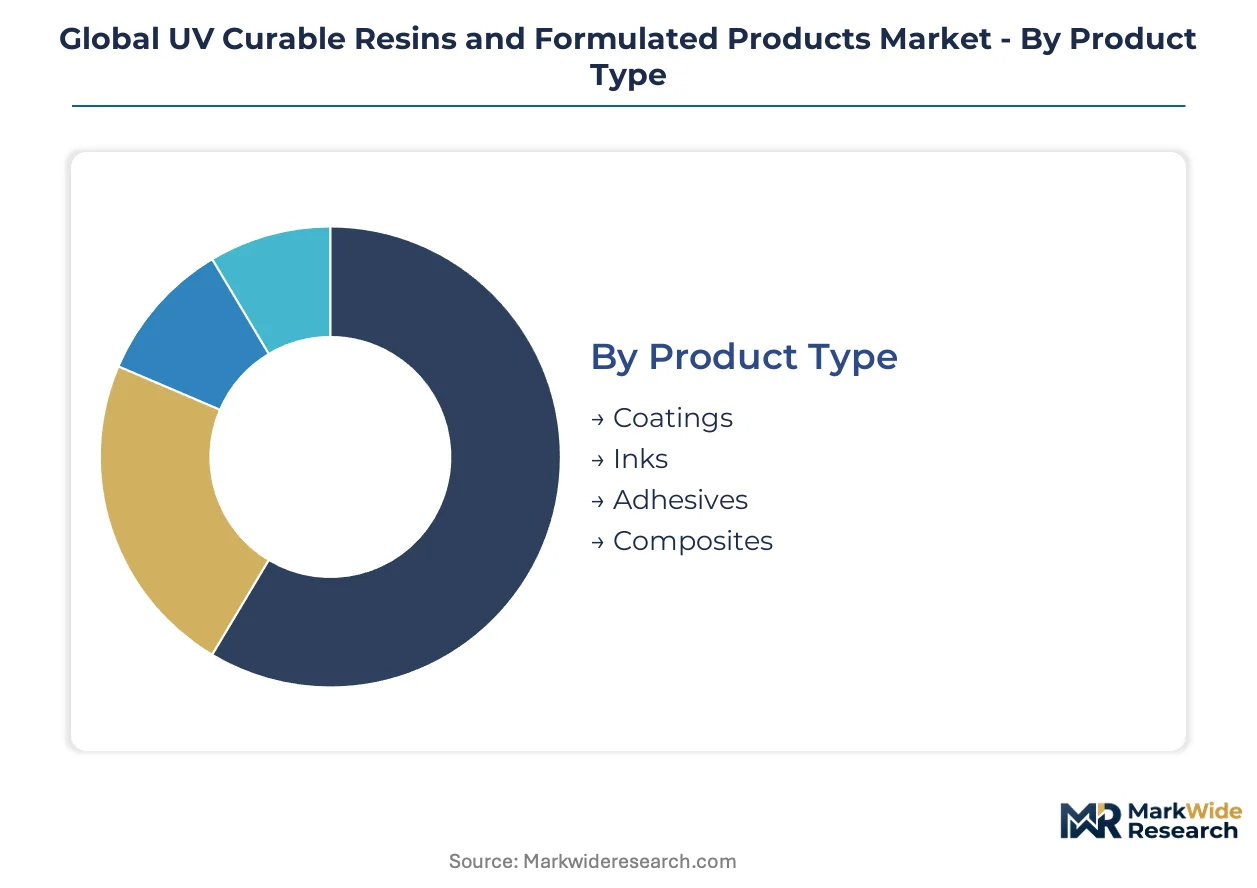
UV curable formulations demand precise segmentation because photoinitiator chemistry, curing wavelength, and end-use certification requirements create non-interchangeable supply chains. Regulatory boundaries between food-contact packaging and implantable medical devices enforce strict formulation silos that resist cross-segment sourcing.
Product Type:
Certification burdens vary sharply across product categories, with medical adhesives requiring FDA and EMA device master files while industrial coatings navigate REACH registration and VOC emission protocols.
- Coatings:Acrylic and urethane acrylate oligomer systems dominate automotive clearcoats and electronics conformal coatings. German automotive OEMs specify aliphatic urethane acrylates for exterior durability, while East Asian electronics clusters drive 395 nm LED-compatible formulations for flexible circuit protection.
- Inks:Pigmented acrylate monomer blends serve narrow-web label printing and packaging decoration. Migration-tested formulations for food-contact applications command premium pricing under FDA and EFSA extractables protocols.
- Adhesives:Biocompatible urethane acrylates with exhaustive extractables documentation serve medical device bonding.
- Composites:Fiber-reinforced formulations target rapid tooling and prototype manufacturing.
Coatings sits at the top of the volume ranking, with adhesives climbing the fastest.
Application:
Cost tier stratification separates commodity automotive refinish coatings from medical-grade adhesives requiring lot-level biocompatibility certification.
- Automotive:OEM clearcoats and refinish systems specify high-gloss urethane acrylates with scratch resistance. Japanese and German manufacturers consolidate around single-source platforms to compress qualification timelines for EV battery module bonding.
- Electronics:Conformal coatings and encapsulants protect flexible circuit boards in Taiwan and South Korea fabrication clusters. UV LED curing at 395 nm peak wavelength has displaced mercury vapor lines for instant tack-free processing.
- Medical Devices:Implantable and diagnostic equipment adhesives demand EMA and FDA device master files with migration-tested photoinitiator packages.
- Packaging:Narrow-web labels and folding carton applications prioritize low-migration Type II hydrogen abstraction photoinitiators for food-contact compliance.
Electronics captures the largest value pool, with medical devices expanding most quickly.
Technology:
Customer infrastructure lock-in creates distinct procurement segments based on installed curing equipment and wavelength standard adoption.
- Photoinitiator:Type I cleavage and Type II hydrogen abstraction chemistries are optimized for 365 nm versus 395 nm LED peak wavelengths. Formulation flexibility constrains operators with capital-intensive LED installations committed to specific wavelengths.
- UV LED:Semiconductor emitter improvements at 395 nm now deliver energy parity with mercury vapor at reduced operating cost. East Asian electronics manufacturers are retrofitting lines ahead of national mercury bans.
- Mercury Vapor:Legacy installations face compressed decommissioning timelines in Germany and Japan.
- Electron Beam:Hybrid UV-EB systems enable high-speed pressure-sensitive adhesive lines with pre-gelation followed by surface cure.
UV LED leads installed base growth, with electron beam gaining share fastest in packaging applications.
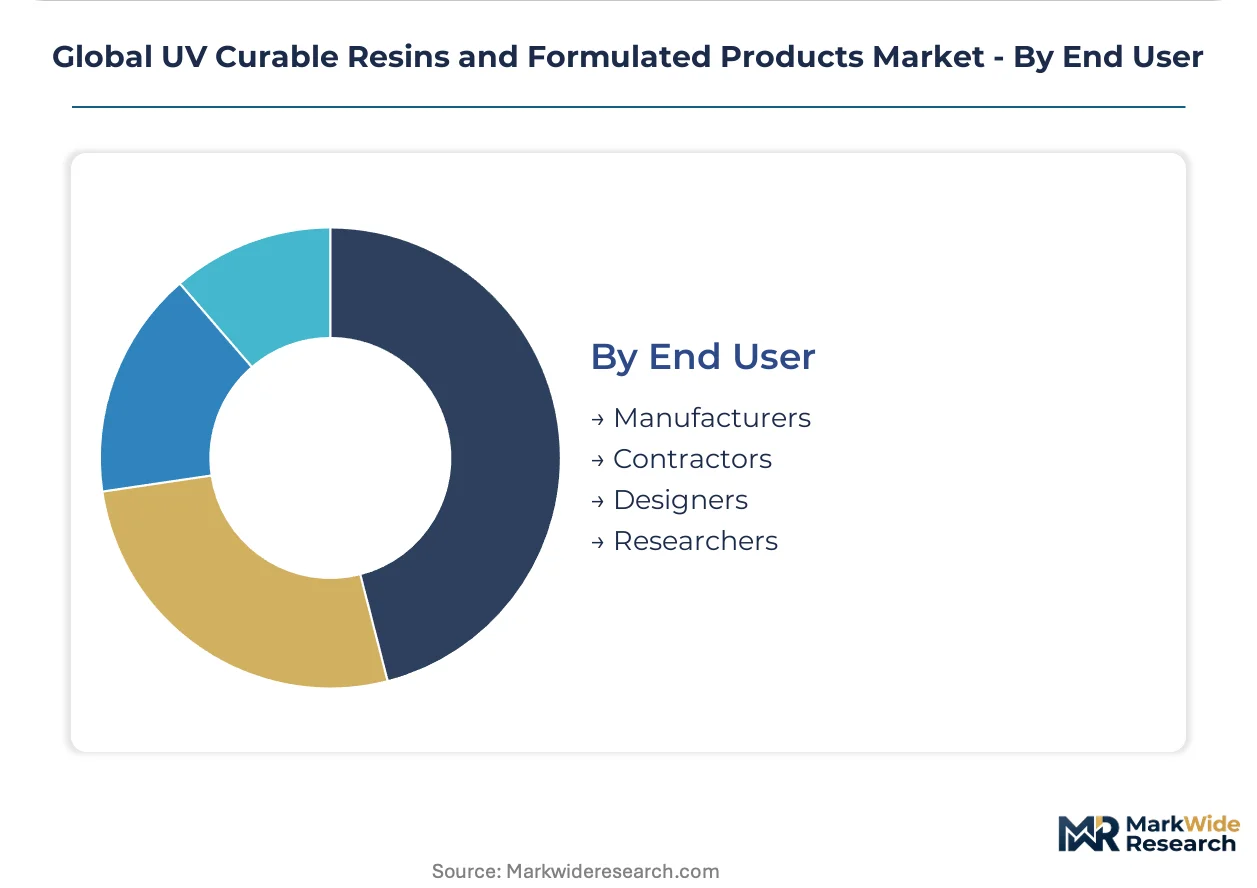
End User:
Supply concentration patterns differ between integrated manufacturers with captive formulation capabilities and specification-dependent contractors.
- Manufacturers:Tier-1 automotive and electronics producers specify directly with oligomer suppliers. Arkema and Allnex serve these accounts through technical service partnerships for custom acrylate development.
- Contractors:Industrial coating applicators procure formulated products through distribution. Price sensitivity concentrates in refinish and wood coating segments.
- Designers:Product development consultancies specify materials for prototype-to-production transitions.
- Researchers:Academic and government laboratories drive photoinitiator innovation with funding from national advanced manufacturing programs.
Manufacturers dominate procurement volume, with contractors representing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting UV curable resin production toward jurisdictions where REACH compliance costs and mercury vapor phase-out timelines create competitive gaps. Formulators are relocating oligomer synthesis to Thailand and South Korea to exploit integrated petrochemical feedstocks while serving European electronics manufacturers facing compressed equipment replacement deadlines.
Germany
Automotive OEMs in Stuttgart and Munich are consolidating adhesive specifications around single-source UV-curable platforms for EV battery module bonding. KBA enforcement of mercury vapor equipment bans is compressing decommissioning timelines for coating lines. The Rhine-Ruhr industrial corridor hosts retrofit activity for aliphatic urethane acrylate clearcoat systems.
China
MEE enforcement of GB standards for industrial coatings is accelerating line retrofits in Guangdong electronics clusters. Domestic oligomer production is expanding to reduce import dependency for acrylate feedstocks. Shenzhen and Suzhou fabrication hubs are specifying 395 nm LED curing arrays for flexible circuit board encapsulation.
Japan
METI mercury vapor lamp prohibitions are forcing immediate capital redeployment toward UV LED infrastructure ahead of national deadlines. Nagoya and Osaka automotive coating lines face compressed replacement cycles without disrupting production schedules. Resonac and DIC supply chains anchor photoinitiator development for 395 nm wavelength systems.
United States
EPA New Chemicals Program oversight is restricting free-radical photoinitiator introductions for food-contact packaging applications. FDA extractables protocols are filtering formulation choices toward Type II hydrogen abstraction systems. Michigan and Ohio automotive refinish clusters are adopting UV-curable clearcoats for VOC emission compliance.
South Korea
Busan-Ulsan petrochemical complexes are realigning capacity toward oligomer-grade acrylates for radiation-curable formulations. MFDS medical device regulations are steering adhesive specifications toward biocompatible urethane acrylates with exhaustive documentation. Seoul Capital Area electronics fabricators are displacing mercury vapor lines with UV LED curing for instant tack-free processing.
Global UV Curable Resins and Formulated Products Market Competitive Environment
French and Thai producers anchor one tier through integrated acrylic acid chains; German and Dutch specialists hold formulation expertise for high-performance coatings. The vendor base separates into petrochemical-integrated oligomer suppliers, independent formulators with photoinitiator matching capabilities, and regional distributors serving contractor segments. Strategic archetypes include backward-integrated acrylate producers, wavelength-specialized LED-compatible formulators, and medical-grade certification specialists. Capacity expansion in East Asian oligomer synthesis and strategic partnerships for UV-EB hybrid system development represent dominant competitive moves.
Among European chemical conglomerates, Arkema and Covestro AG exemplify integrated production archetypes with captive acrylic acid and aliphatic urethane acrylate specialization respectively. Allnex Netherlands B.V. occupies a position within the independent formulator tier serving pan-regulatory coating specifications across automotive and industrial segments.
| Leading Market Players |
|---|
| Arkema |
| Alberdingk Boley GmbH |
| Allnex Netherlands B.V. |
| Miwon Specialty Chemical Co., Ltd. |
| Resonac Holdings Corporation |
| BASF SE |
| IGM Resins |
| DIC Corporation |
| Covestro AG |
| Others |
Value Chain & Pricing Dynamics
Acrylic acid feedstock costs cascade through oligomer-grade acrylate pricing tiers, with integrated French and Thai petrochemical producers capturing margin advantages that independent formulators in Germany and Japan cannot match. REACH compliance burdens and mercury vapor decommissioning timelines concentrate procurement power among buyers with direct oligomer supplier relationships, compressing distributor margins in contractor-served segments.
Pricing Analysis
Distributor margins compress most acutely in industrial coating segments where contractor procurement dominates. Three-tier pricing structure across medical-grade, industrial-performance, and commodity-economy levels reflects certification burden stratification, with FDA and EMA device master files commanding substantial premia over REACH-registered industrial grades. Pricing pressure stems from LED curing infrastructure capital commitments locking buyers into wavelength-specific formulations with limited sourcing flexibility. Tier-1 automotive and electronics manufacturers exhibit lowest price sensitivity due to qualification timeline costs, while refinish and furniture coating contractors drive aggressive spot-market negotiation.
Supply Chain Analysis
Single-source vulnerability sits with oligomer-grade acrylate supply anchored in France and Thailand, where Arkema and integrated Southeast Asian petrochemical complexes control upstream acrylic acid chains. Formulation expertise concentrates in Germany and the Netherlands, drawing from propylene cracking economics and specialized aliphatic urethane acrylate production. Supply chain risk centers on regulatory restriction, as REACH registration timelines and EPA New Chemicals Program oversight delay photoinitiator introductions. Distribution runs through technical service partnerships for integrated manufacturers and regional distributors for contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where specification consolidation around biocompatible urethane acrylates and 395 nm LED-compatible formulations rewards incumbent certification investments. Demand is shifting toward premium tiers as automotive OEMs abandon multi-chemist procurement in favor of pan-regulatory pre-certified platforms.
For Market Incumbents: Lock in wavelength-specific formulation partnerships with LED curing equipment manufacturers to constrain competitor access to qualified specification pipelines. Deepen backward integration into photoinitiator chemistry to defend margin position against raw material volatility and regulatory substitution timelines. Prioritize EMA and FDA device master file maintenance as emerging Korean and Chinese formulators challenge medical-grade certification barriers. For New Entrants and Emerging Players: Launch via regional distribution partnerships targeting Indian automotive refinish and furniture coating contractors facing BIS standards alignment pressure. Exploit white-space in UV-EB hybrid curing systems for packaging pressure-sensitive adhesives, where incumbent formulators lack dedicated technical service infrastructure. Target electron beam pre-gelation formulations as the most penetrable technology segment, with equipment-agnostic chemistry reducing wavelength lock-in barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where photoinitiator-oligomer matching expertise concentrates among aging European specialists without succession planning. Long-term viability favors backward-integrated acrylate producers with captive feedstock and wavelength-optimized formulation libraries. Acquisition target archetype: mid-cap independent formulators with FDA device master files and established technical service relationships in German automotive or East Asian electronics clusters. Signal to watch: Japanese and German mercury vapor decommissioning timelines accelerating distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive feedstock supply insulates Arkema and Thai producers from propylene cracking volatility. |
| 395 nm LED-Compatible Formulation Development | Type II hydrogen abstraction photoinitiator optimization serves Taiwan and South Korea electronics clusters. |
| FDA and EMA Device Master File Investment | Biocompatibility certification creates defensible premium tiers in medical device adhesive specifications. |
| UV-EB Hybrid System Partnerships | Electron beam pre-gelation capability opens packaging applications beyond wavelength-constrained UV lines. |
| India Distribution Channel Expansion | BIS standards alignment creates specification windows for radiation-curable automotive and furniture coatings. |
Study Parameters
Direct dialogue with plant managers at oligomer synthesis facilities, procurement leads at German and Japanese automotive OEMs, distribution channel partners serving industrial coating contractors, and technical R&D directors at photoinitiator suppliers grounded qualitative assessment. Secondary validation drew from ECHA REACH registration databases, FDA 510(k) and PMA filings for medical device adhesives, customs and trade data for acrylate feedstock flows, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up formulation demand modeling and top-down petrochemical capacity analysis were triangulated against equipment installation data from LED curing system manufacturers.
Bottom-up volume aggregation across coatings, inks, adhesives, and composites segments was cross-checked against top-down petrochemical feedstock allocation data. Segmentation dimensions included product certification tier, curing wavelength standard, end-use industry, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles for mercury vapor equipment, LED emitter efficiency improvement curves, and REACH-driven formulation substitution timelines. Industry-specific forecast inputs incorporated MEE enforcement intensity in Chinese manufacturing provinces and METI decommissioning deadlines in Japan.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt photoinitiator regulatory bans or accelerated mercury vapor phase-outs in unscheduled jurisdictions. Forecasts reflect documented assumptions regarding LED wavelength standard harmonization and oligomer-grade acrylate capacity expansion timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Polyisoprene Latex Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
South-East Asia Low-Density Polyethylene (LDPE) Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Europe Polyols Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Renewable Polyethylene Market
Polymers & Resins
Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
PEKK Market