
 Global One Component Polyurethane Foam Market | 2026-2036
Global One Component Polyurethane Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Global One Component Polyurethane Foam Market Intelligence
The availability of trained contractors and installers for correct application is redrawing the competitive landscape for foam manufacturers. Soudal Group leverages its extensive distribution network to reach a broad base of construction professionals and DIY users. Sika AG, in contrast, specializes in high-performance sealants and adhesives for demanding industrial and construction applications, securing a strong position in projects with stringent technical requirements.
One component polyurethane foam is a pre-polymerized isocyanate and polyol mixture packaged in an aerosol can. The foam expands and cures into a semi-rigid or flexible structure upon contact with atmospheric moisture, serving primarily as an air sealant and thermal insulator. Rigid foam variants lead the market for wall and roof insulation applications due to their superior thermal resistance. In parallel, flexible foam and sealants represent a significant category for soundproofing and filling joints where movement is anticipated.
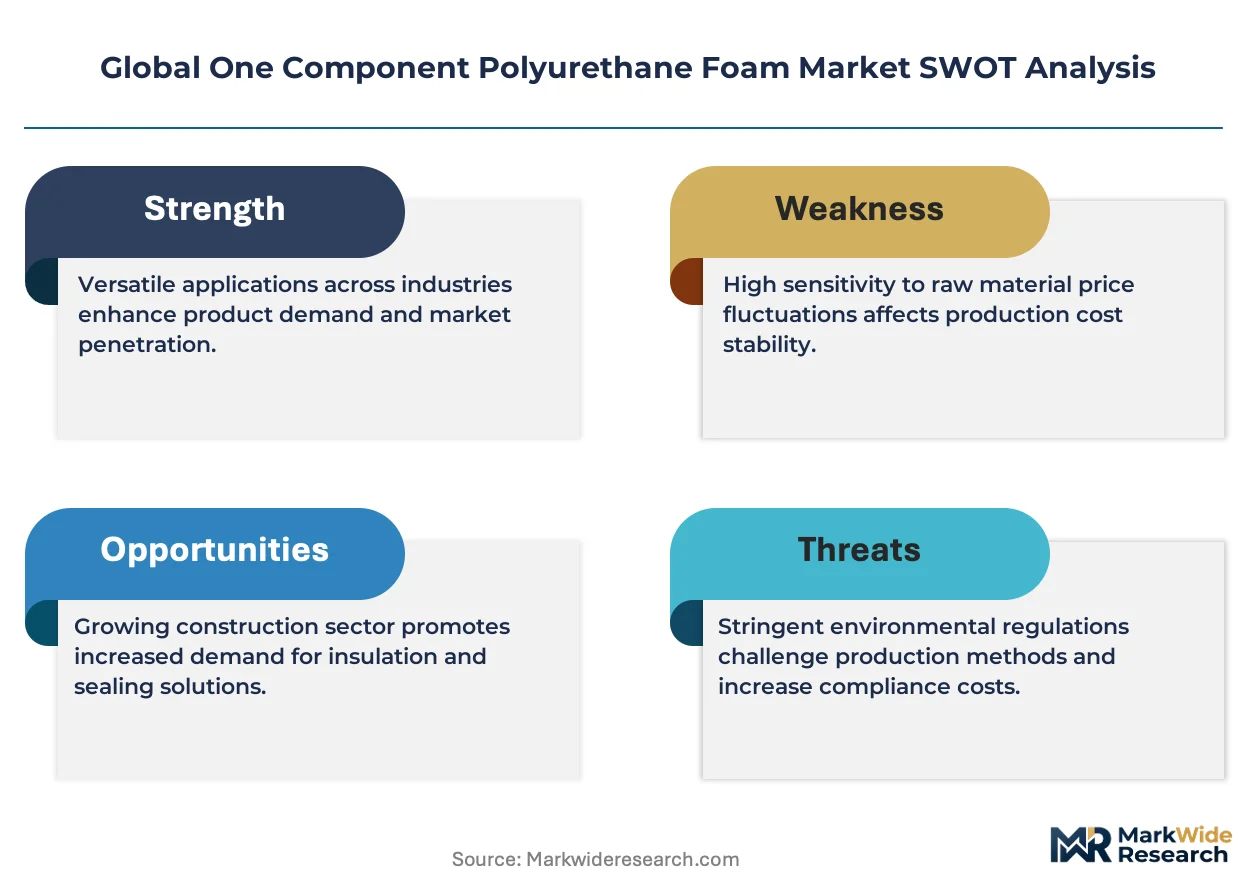
Regulatory frameworks like the European Union's REACH and the US EPA's rules on volatile organic compounds (VOCs) govern the chemical composition of foams. These standards directly influence product formulation and market access, pushing manufacturers toward lower-VOC alternatives. Future competitive advantage hinges on developing formulations that meet stricter environmental standards without compromising application performance or cure time.
Market Dynamics
The imperative for enhanced building energy efficiency, codified in stringent government regulations, serves as the primary structural force shaping the market. This creates non-discretionary demand for high-performance insulation materials, directly benefiting one component polyurethane foam manufacturers.
Growth Catalysts
- Energy Efficiency Mandates:Stricter building codes under frameworks like the EU Green Deal compel the use of superior insulation materials to improve thermal performance in new construction and retrofitting projects.
- Residential Retrofitting:Demand from the renovation sector, particularly in mature markets like Germany and the United States, for upgrading wall and roof insulation in older homes drives significant volume.
- Low-VOC Formulations:The development of products with lower volatile organic compound content expands market access by meeting health and environmental standards required for indoor applications and green building projects.
Market Restraints
- Raw Material Volatility:Price fluctuations for key chemical precursors, specifically isocyanates and polyols, directly impact production costs and create margin pressure for foam manufacturers.
- Substitution Threat:Competition from traditional insulation materials such as mineral wool and expanded polystyrene (EPS) remains a significant barrier, especially in cost-sensitive residential construction projects.
- Regulatory Compliance Burden:Navigating complex chemical regulations, including the European Union's REACH framework, increases administrative costs and can delay the introduction of new foam formulations.
Strategic Opportunities
- Emerging Market Construction:Untapped demand in rapidly urbanizing countries in Southeast Asia and Latin America presents a significant growth frontier as their building standards begin to modernize.
- Specialized Industrial Applications:Use in niche segments, such as sealing and bonding in electric vehicle battery assemblies or for acoustic insulation in modular construction, offers avenues for high-margin product development.
- Bio-Based Feedstocks:Formulating foams with polyols derived from renewable sources like soy or castor oil creates a competitive advantage with customers prioritizing sustainability and circular economy principles.
Industry Challenges
- Installer Skill Scarcity:A shortage of trained contractors with the technical expertise for correct foam application can lead to improper installation, undermining product performance and brand reputation.
- Certification Timelines:The extensive time and capital required to obtain necessary fire safety and environmental certifications for new products act as a barrier to innovation and market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global One Component Polyurethane Foam Market |
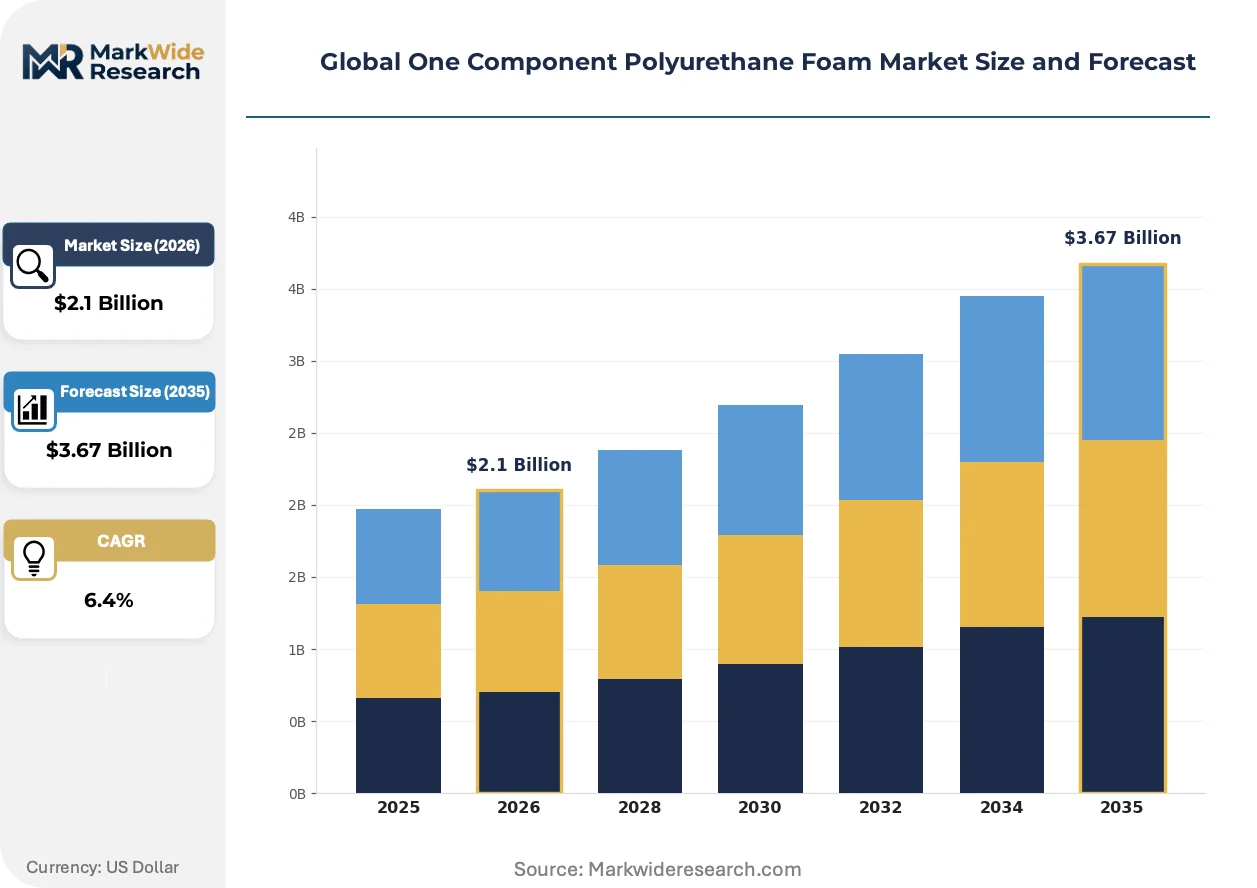
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Spray Foam, Sealants Technology: High-Pressure Dispensing, Low-Pressure Dispensing, Handheld, Pneumatic Application: Roof Insulation, Wall Insulation, Floor Insulation, Soundproofing End User: Construction Contractors, HVAC Installers, Industrial Fabricators, Homeowners |
| Companies Covered | Soudal Group, Henkel AG & Co. KGaA, Sika AG, The Dow Chemical Co, BASF SE, Huntsman Corp, Selena Group, Den Braven, Tremco CPG Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global One Component Polyurethane Foam Market Strategic Shifts & Innovations
Product innovation is increasingly guided by the dual pressures of environmental regulation and end-user demands for higher performance. This dynamic forces a strategic realignment in formulation, prioritizing sustainable inputs and compliance with global chemical standards without compromising application efficiency.
Bio-based polyols derived from renewable feedstocks are emerging as a sustainable alternative to petroleum-based chemical inputs. Formulators and manufacturers pursuing green building certifications, such as LEED or BREEAM, are the primary adopters of these materials. The introduction of these sustainable inputs is decomposing the market's historical dependence on petrochemical supply chains, creating new sourcing paradigms.
The European Union's F-Gas Regulation is actively phasing down the use of high global warming potential (GWP) blowing agents like hydrofluorocarbons (HFCs). This directive compels manufacturers to reformulate products using low-GWP alternatives such as hydrofluoroolefins (HFOs) or carbon dioxide. Rigid foam products for building insulation are the most affected category, with producers across the EU investing heavily in compliant technologies.
A notable shift toward specification-driven purchasing by architects and building engineers is altering procurement. This trend diminishes the influence of contractors making brand choices based on local distributor availability, elevating the importance of technical data and performance certifications. This behavior is most visible in large commercial construction projects across North America and Western Europe, where technical compliance is paramount.
Global One Component Polyurethane Foam Market Segmentation
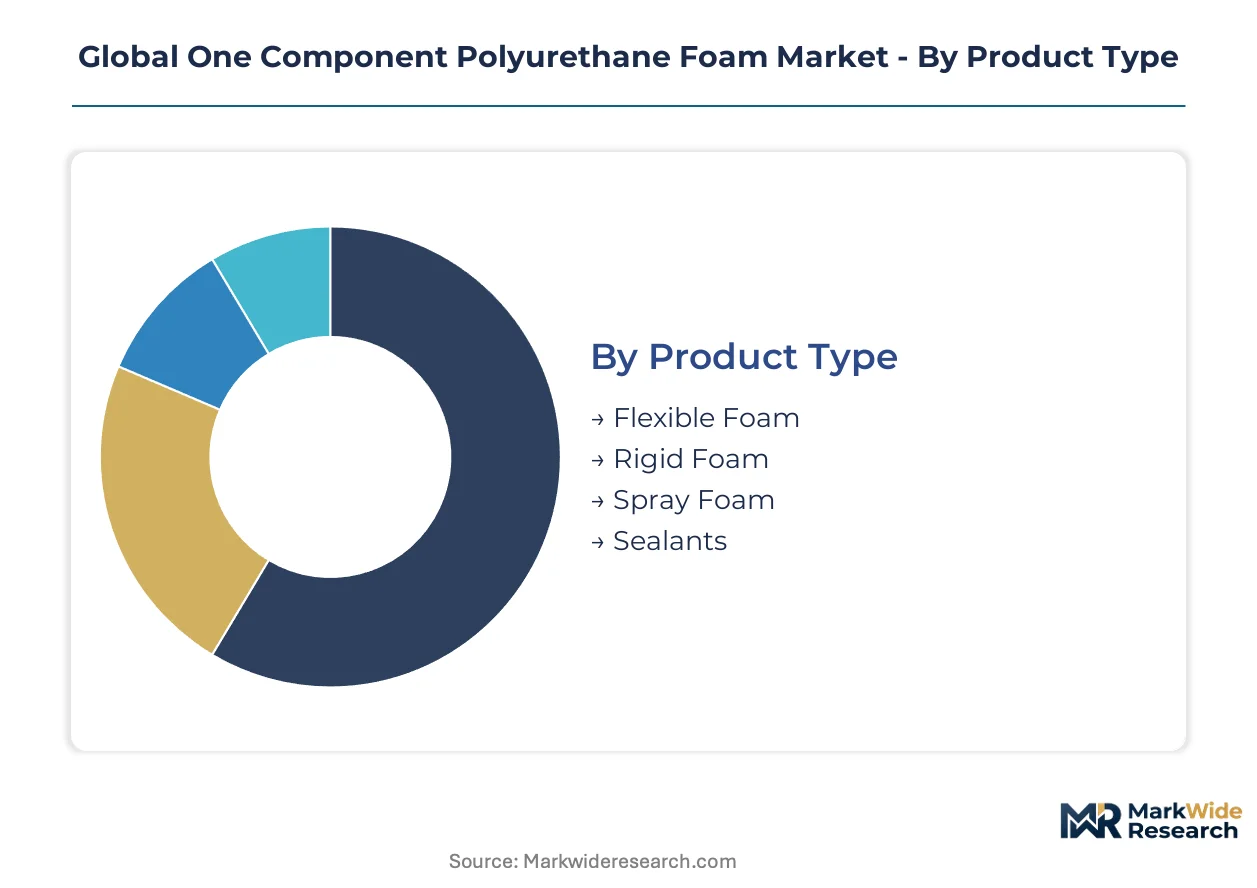
Market segmentation reveals the diverse pathways through which one component polyurethane foam products meet specific performance requirements and regulatory mandates. Understanding these distinct segments allows manufacturers to tailor formulations, distribution strategies, and technical support to address varied end-user needs. This granular view identifies both established demand centers and emerging opportunities across the global market landscape.
Product Type:
Regulatory differentiation significantly influences product formulation and market access across various foam types.
- Rigid Foam:This product type offers superior thermal resistance, making it indispensable for wall and roof insulation applications. Demand concentrates in Germany for residential retrofitting projects, driven by strict energy efficiency mandates under the EU Green Deal.
- Sealants:Formulated primarily for air sealing and gap filling, these products play a critical role in achieving building envelope integrity. Their adoption is accelerating in North America due to US EPA regulations on volatile organic compounds and increasing emphasis on indoor air quality.
- Flexible Foam:These foams provide semi-rigid or flexible structures, often utilized in soundproofing applications and for sealing joints where movement is anticipated.
- Spray Foam:Applied through specialized equipment, spray foam expands to fill large cavities, delivering comprehensive thermal and air sealing performance.
Rigid Foam handles the majority of throughput; Sealants is the fastest mover on share.
Technology:
Application complexity and scale of use determine the preferred dispensing technology for one component polyurethane foam.
- Handheld:This technology relies on aerosol cans for direct application, offering convenience and ease of use for DIY projects and smaller contractor jobs. Homeowners in the United States frequently use handheld systems for minor repairs.
- High-Pressure Dispensing:These systems deliver foam with precision and speed for large-scale industrial and commercial construction projects. Professional construction contractors often employ high-pressure dispensing for rapid application across expansive surfaces.
- Low-Pressure Dispensing:Offering a controlled flow, low-pressure systems are suitable for sealing and insulating in residential and light commercial settings.
- Pneumatic:Utilizing compressed air, pneumatic dispensing provides consistent material flow for specific industrial fabrication and assembly tasks.
Handheld technologies drive accessibility for individual users, while High-Pressure Dispensing commands the largest professional volume.
Application:
Demand concentration for one component polyurethane foam is directly tied to specific building envelope performance requirements.
- Wall Insulation:This application segment is crucial for enhancing the thermal performance of building envelopes, particularly in retrofitting older structures. Stricter building codes in European countries like France compel the use of high-performance materials for wall insulation.
- Roof Insulation:Critical for preventing heat loss or gain, roof insulation applications utilize foam to create a continuous thermal barrier. Commercial building projects in the United Kingdom prioritize effective roof insulation for energy compliance.
- Soundproofing:Foam products contribute to acoustic comfort by dampening sound transmission within residential and commercial spaces.
- Floor Insulation:Applied beneath flooring, this insulation helps maintain consistent indoor temperatures and reduces energy consumption.
Wall Insulation represents the largest segment by volume, with Roof Insulation showing strong expansion due to commercial project demand.
End User:
Procurement patterns and technical expertise differentiate the requirements of various end-user groups for one component polyurethane foam.
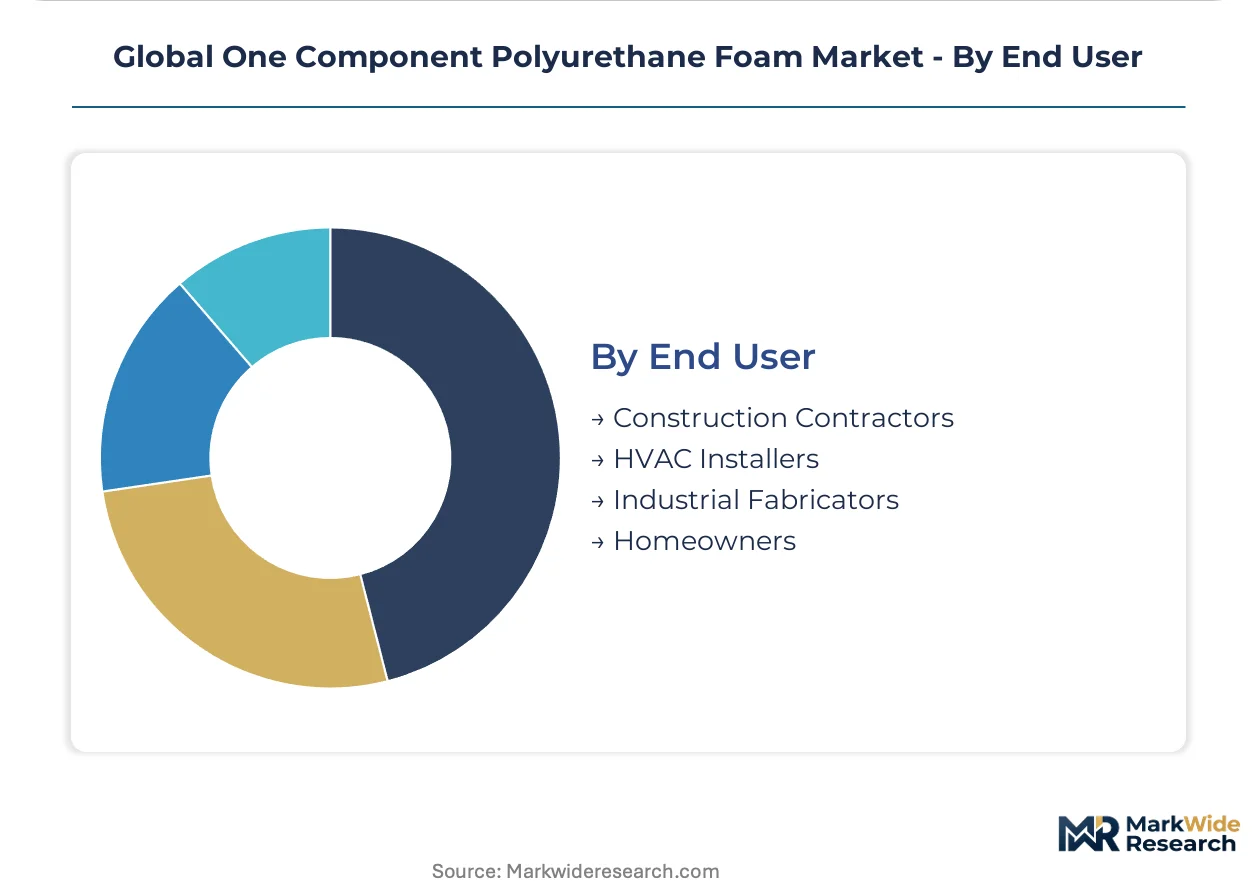
- Construction Contractors:These professionals require high-performance, reliable foam solutions for large-scale projects, often demanding technical data and certifications. Contractors in Canada rely on consistent product quality for diverse building projects.
- Homeowners:DIY users prioritize ease of application, clear instructions, and readily available products for small-scale repair and insulation tasks. The retail channel caters significantly to homeowners across Australia.
- HVAC Installers:These specialists use foam for sealing ducts and pipe penetrations, preventing air leakage and improving system efficiency.
- Industrial Fabricators:Manufacturing processes utilize foam for specialized bonding, sealing, and insulation within various industrial products and assemblies.
Construction Contractors drive the majority of professional procurement, while Homeowners contribute significantly to the retail volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's F-Gas Regulation anchors demand across key European markets for one component polyurethane foam. This framework, alongside the EU Green Deal, drives the need for enhanced energy efficiency in buildings. Such mandates create non-discretionary demand for high-performance insulation materials.
Germany
Strict energy efficiency mandates and a strong focus on residential retrofitting drive demand in Germany. Regulations under the EU Green Deal compel property owners to upgrade thermal performance in existing structures. Bavaria and North Rhine-Westphalia exhibit high activity for upgrading existing building stock.
United States
Demand for air sealing and gap filling is significant in the United States, particularly from homeowners for DIY projects. US EPA regulations on volatile organic compounds influence product formulation for indoor air quality. Major metropolitan areas like New York City and Los Angeles show consistent demand for compliant products.
Canada
Construction contractors in Canada require consistent product quality for diverse building projects across varied climates. Health Canada regulations ensure material safety and performance for both residential and commercial applications. Toronto and Vancouver's robust construction sectors utilize foam for insulation and sealing requirements.
United Kingdom
Commercial building projects in the United Kingdom prioritize effective roof insulation for energy compliance and heat retention. Building regulations, including those for energy performance, compel the use of high-performance insulation. London and Manchester's urban development projects drive demand for advanced thermal barriers.
China
Rapid urbanization and modernization of building standards contribute to growing demand for foam in China's construction sector. The Ministry of Ecology and Environment (MEE) sets standards for material sustainability and emissions. Major industrial hubs like the Yangtze River Delta are seeing increased adoption in new constructions.
Global One Component Polyurethane Foam Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, creating a diversified market structure for one component polyurethane foam. Global chemical giants often leverage extensive R&D capabilities, while regional specialists focus on localized distribution and application expertise. Niche innovators target high-performance formulations for specific industrial applications. Portfolio diversification and strategic partnerships represent dominant competitive moves.
Specialists in advanced construction materials, Sika AG and Henkel AG & Co. KGaA, exemplify companies with broad product portfolios and strong technical support. Sika AG, a Swiss company, occupies a position in high-performance sealants and adhesives for demanding industrial and construction applications, securing a strong presence in projects with stringent technical requirements. Henkel AG & Co. KGaA, a German chemical and consumer goods company, represents a player with extensive reach across professional and DIY segments, leveraging its brand recognition for wider market penetration. Soudal Group, a Belgian manufacturer, anchors the market with its extensive distribution network, effectively reaching a broad base of construction professionals and DIY users, particularly for general-purpose applications.
| Leading Market Players |
|---|
| Soudal Group |
| Henkel AG & Co. KGaA |
| Sika AG |
| The Dow Chemical Co |
| BASF SE |
| Huntsman Corp |
| Selena Group |
| Den Braven |
| Tremco CPG Inc |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for key chemical precursors like isocyanates and polyols lock in both supply access and price visibility for one component polyurethane foam manufacturers. This structure mitigates raw material volatility for major players.
Pricing Analysis
Price spreads for one component polyurethane foam vary significantly across regions, with higher prices in the European Union due to stringent regulatory compliance. Contract-based long-term offtake models dominate professional procurement, while per-unit transactional pricing serves DIY users. Price differentiation stems from product certifications, such as fire safety ratings, and the volume scale of purchase, with raw material volatility for isocyanates exerting upward pressure. Homeowners exhibit higher price sensitivity compared to construction contractors, who prioritize certified performance.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized chemical precursors, impact the global supply chain for one component polyurethane foam. Supply concentration for these inputs centers on chemical manufacturing hubs in Germany, the United States, and China. The market heavily relies on isocyanates and polyols, alongside low-GWP blowing agents, making commodity price volatility a significant structural risk. Distribution runs through a dual model: extensive networks for general-purpose products and specialized channels for high-performance applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The one component polyurethane foam market experiences a shift in buyer power, driven by the consolidation of purchasing influence among architects and building engineers. Their specification-driven procurement diminishes contractor discretion, favoring technically compliant products.
For Market Incumbents:Fortify market leadership by accelerating R&D into bio-based polyols and low-GWP blowing agents, meeting future EU F-Gas Regulation and US EPA standards. Expand installer training programs to counter the installer skill scarcity, ensuring correct application and maintaining brand reputation against improper use. Invest heavily in fire safety and environmental certifications to differentiate products, mitigating the substitution threat from traditional insulation materials. Deepen channel control through strategic partnerships with large construction contractors.
For New Entrants and Emerging Players:Specialized technical support for niche industrial applications represents a service-layer gap where incumbents under-serve. Target high-margin segments such as sealing and bonding in electric vehicle battery assemblies or acoustic insulation in modular construction. Focus on developing customized formulations that meet specific performance criteria and stringent certification requirements. A go-to-market angle emphasizing technical consultation and rapid prototyping will attract industrial fabricators seeking tailored solutions.
For Investors and Strategic Acquirers:Capital is best deployed toward mid-sized manufacturers demonstrating strong R&D capabilities in sustainable formulations and robust market access in high-growth regions. The market's long-term viability is anchored in accelerating demand for energy-efficient buildings and stricter environmental regulations. Target acquisition profiles include niche innovators with proprietary bio-based polyol technologies or regional specialists with established distribution in Southeast Asia. A key signal to watch is the widespread commercialization of low-GWP blowing agents beyond the EU.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Formulation Development | Reduces reliance on petrochemicals, aligning with global green building certifications like LEED. |
| Installer Training Program Expansion | Improves application quality, mitigating performance issues and strengthening brand reputation among contractors. |
| Low-GWP Blowing Agent Transition | Ensures compliance with environmental regulations such as the EU F-Gas Regulation for rigid foam products. |
| Emerging Market Distribution Network Buildout | Captures untapped demand from rapidly urbanizing countries in Southeast Asia and Latin America. |
| Technical Data and Certification Investment | Supports specification-driven purchasing by architects and engineers in North American commercial projects. |
Research Approach
Operator-level perspectives from construction contractors, R&D directors, architects, and raw material suppliers anchored the qualitative base of this study. Primary interviews with these industry stakeholders provided crucial insights, validated against extensive secondary research. Secondary sources included EU Green Deal documents, US EPA reports, and chemical industry association publications. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and consistency.
Sensitivity analysis was applied to key variables within the analytical framework, projecting market trajectories across the analysis window. Segmentation dimensions modeled included product type, application, technology, end-user, and regional regulatory stringency. Compound Annual Growth Rates were derived from historical trends and projected market dynamics. Forecast inputs incorporated anticipated shifts in building code stringency and raw material price forecasts for isocyanates.
Forecasts assume regulatory continuity in the EU Green Deal and US EPA regimes; material policy shifts would require re-modeling. Geopolitical disruptions affecting chemical supply chains or rapid technological breakthroughs in competing insulation materials represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Polypropylene Copolymer Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
Resin Cement for Luting Market
Polymers & Resins
Polybutylene Succinate (PBS) Market
Polymers & Resins
Renewable Polyethylene Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Polyamide Resins Market
Polymers & Resins
Polymer Plastic Plain Bearings Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market