
 Polylysine Market | 2026-2036
Polylysine Market Size, Share, and Industry Trends Forecast 2026-2036
Polylysine Market Intelligence
Customized formulation services for specific end-use applications, such as antimicrobial coatings, is expanding the addressable market for polylysine. This value-added support allows producers to penetrate niche segments beyond bulk preservative sales. JNC Corporation specializes in high-purity grades for sensitive healthcare and cell culture applications. Handary positions its offerings for the natural food preservative market, while Zhengzhou Bainafo Bioengineering leverages its production scale in China to compete on volume and cost for industrial uses.
Polylysine is a naturally occurring homopolymer of the essential amino acid, L-lysine, typically produced through bacterial fermentation using strains of Streptomyces. Its cationic nature at physiological pH allows it to disrupt microbial cell membranes, making it a highly effective antimicrobial agent. The food preservation segment constitutes the largest end-use industry, driven by demand for natural alternatives to synthetic preservatives. Meanwhile, applications for Poly-L-lysine in drug delivery and surface modification for medical devices represent high-value opportunities within the healthcare sector.
Regulatory approvals are critical for market access, with bodies like the United States FDA and the European Food Safety Authority (EFSA) defining its use as a food additive. In Asia, regulators such as China's SAMR and Japan's METI oversee its application in food and cosmetics, setting standards for purity and safety. Successfully navigating these varied regional frameworks remains a key determinant of commercial strategy for manufacturers. Stakeholders must align product development with evolving consumer preferences for natural ingredients and regional regulatory updates.
Market Dynamics
The central market dynamic is the tension between rising consumer demand for clean-label food products and the complex, region-specific regulatory hurdles governing natural antimicrobial agents. This forces producers to balance innovation in applications with rigorous compliance strategies.
Growth Catalysts
- Consumer Preferences:The global shift toward natural and minimally processed foods creates sustained demand for polylysine as a replacement for synthetic preservatives like sorbates and benzoates in the food and beverage industry.
- Regulatory Support:Approvals from bodies like the United States FDA and the European Food Safety Authority (EFSA) for use as a food additive provide critical market access and validate its safety profile for manufacturers.
- Healthcare Applications:Expanding use in high-value biomedical fields, including as an antimicrobial coating for medical devices and a vector for drug delivery systems, opens new revenue streams beyond food preservation.
Market Restraints
- Cost Disadvantage:The production of polylysine via bacterial fermentation is inherently more expensive than the chemical synthesis of alternatives, creating a price barrier for adoption in cost-sensitive, high-volume industrial food applications.
- Performance Limitations:Polylysine's antimicrobial efficacy is pH-dependent, reducing its effectiveness in highly acidic food and beverage products, which can limit its application range compared to broad-spectrum synthetic options.
- Threat of Substitutes:Competition from other natural antimicrobials, such as nisin, natamycin, and various plant-based extracts, presents a significant substitution threat, particularly in niche food preservation segments.
Strategic Opportunities
- Geographic Expansion:Market penetration in emerging economies across South America and Southeast Asia, where the clean-label trend is gaining traction, represents a significant growth opportunity for established polylysine suppliers.
- Functional Food Packaging:The integration of polylysine into active and intelligent packaging films to extend the shelf life of perishable goods is an emerging application with substantial commercial potential.
- Synergistic Formulations:Developing blended preservative systems that combine polylysine with other natural antimicrobials or preservation technologies can create more potent, broad-spectrum solutions that overcome individual limitations.
Industry Challenges
- Regulatory Harmonization:Manufacturers face the challenge of navigating disparate and evolving regulatory standards for purity, labeling, and approved applications across key markets like the US, EU, China, and Japan.
- Production Scalability:Ensuring consistent yield, purity, and antimicrobial activity during the large-scale fermentation of Streptomyces strains requires significant capital investment and advanced bioprocessing expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polylysine Market |
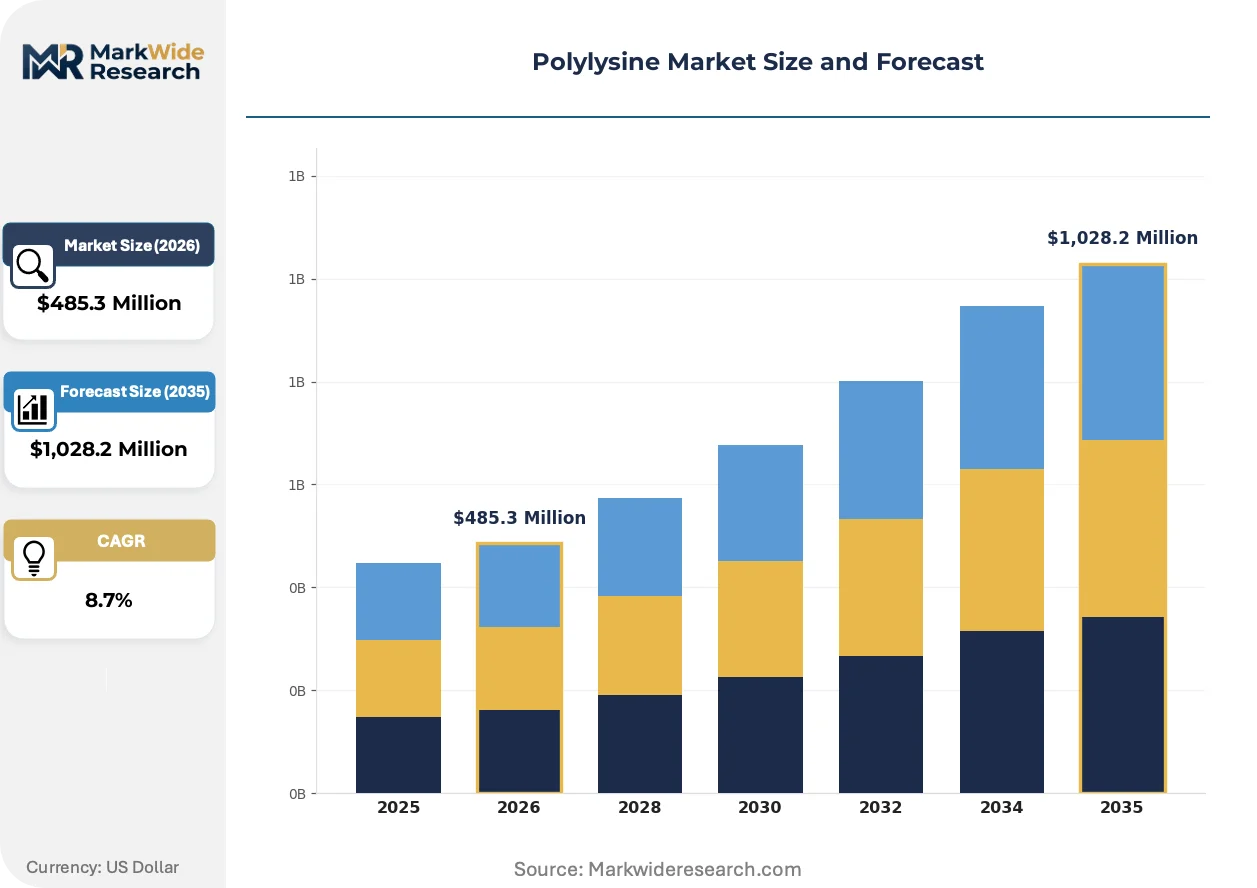
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poly-D-lysine, Poly-L-lysine, Copolymers, Functionalized Polylysine End Use Industry: Healthcare, Cosmetics, Food Preservation, Agriculture Form: Solution, Powder, Hydrogel, Coating Application: Cell Culture, Antimicrobial Agent, Drug Delivery, Surface Modification |
| Companies Covered | Okuna Chemical Industries Co., Handary, JNC Corporation, Chengdu Jinkai Biology, Shandong Freda, Merck & Co., Inc., Siveele B.V., Zhengzhou Bainafo Bioengineering, Chisso Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polylysine Market Strategic Shifts & Innovations
Product development is increasingly focused on customized formulations that target specific microbial challenges in diverse food matrices. This shift from a commodity to a specialty ingredient model is accompanied by innovations in bioprocessing to enhance production efficiency and purity.
Advanced bioprocessing controls are enhancing the efficiency of polylysine synthesis. These systems utilize sensors and software to monitor and adjust critical parameters during the fermentation of Streptomyces strains. Food and biopharmaceutical producers are the primary adopters of this technology. This greater control is automating the optimization of nutrient feeds and environmental conditions, which reduces batch variability and improves final product yield.
European Union food safety regulations continue to favor ingredients with a natural origin and a strong safety dossier. The European Food Safety Authority's (EFSA) ongoing review of food additives reinforces the market position of substances like polylysine. This regulatory environment affects the processed meat, dairy, and baked goods sectors, which are reformulating products to meet clean-label demands and mitigate risks associated with synthetic preservatives.
A notable behavioral shift involves food manufacturers demanding complete supply chain transparency and third-party certifications for ingredients. This moves procurement criteria beyond price to include documented proof of non-GMO status, origin, and purity for preservatives. This trend is most pronounced in the organic food and premium beverage segments in North America and Western Europe, where brand reputation depends on ingredient integrity.
Polylysine Market Segmentation
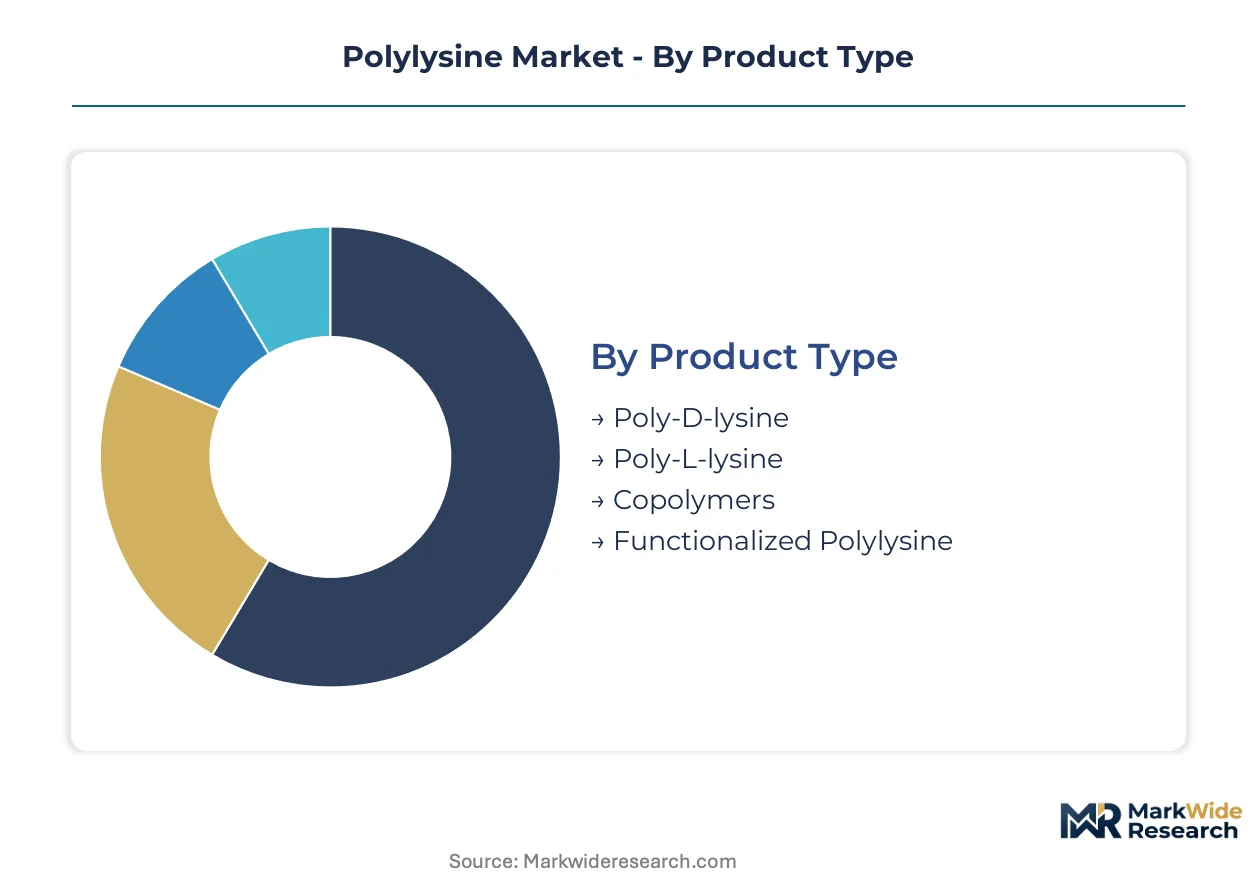
Understanding the polylysine market through detailed segmentation reveals the diverse applications and varying commercial dynamics influencing its expansion. Each segment reflects unique demand drivers, regulatory landscapes, and technological requirements, shaping the strategic decisions of manufacturers and end-users. This granular analysis provides clarity on where value creation and competitive advantages are most pronounced.
Product Type:
The production of specific polylysine types often requires significant capital investment in bioprocessing and purification technologies. Specialized functionalization processes further elevate the upfront costs for producers targeting niche, high-value applications.
- Poly-L-lysine:This naturally occurring homopolymer of L-lysine is typically produced via bacterial fermentation. Demand concentrates in the food preservation sector, driven by consumer preference for natural antimicrobial agents in clean-label products across Europe and North America.
- Functionalized Polylysine:Chemically modified polylysine variants are engineered for enhanced properties, such as improved solubility or targeted binding. This segment sees significant demand in advanced biomedical research and drug delivery systems, particularly in the US and Japan, where R&D investment is high.
- Poly-D-lysine:A synthetic isomer used primarily in cell culture applications to promote cell adhesion and growth.
- Copolymers:These involve polylysine combined with other polymers to create hybrid materials with synergistic properties for specific industrial or medical uses.
Poly-L-lysine absorbs the bulk of installed capacity; Functionalized Polylysine is expanding most quickly.
End Use Industry:
The end-use industries for polylysine are distinguished by their distinct customer types and procurement criteria, ranging from large-scale food processors to specialized healthcare providers. Each sector presents unique challenges and opportunities for product formulation and market penetration.
- Food Preservation:This industry utilizes polylysine as a natural antimicrobial to extend shelf life and enhance food safety. Demand is particularly strong in China's extensive food processing sector due to stringent food safety regulations and a large export market.
- Healthcare:Polylysine finds application in medical devices, drug delivery, and pharmaceutical formulations, leveraging its biocompatibility and antimicrobial properties. High-value opportunities exist in the US and European markets for advanced therapeutic applications.
- Cosmetics:Polylysine functions as a preservative and conditioning agent in personal care products, aligning with the clean-label trend.
- Agriculture:Polylysine is explored as a natural biopesticide or plant growth enhancer in sustainable farming practices.
The regulatory landscape heavily influences adoption in Food Preservation, while Healthcare presents significant untapped potential.
Form:
The maturity of various polylysine forms reflects the evolution of its applications, from foundational bulk formats to highly specialized delivery systems. Different forms cater to specific handling, stability, and application requirements across industries.
- Powder:The most common and stable form, offering ease of storage and transportation for bulk applications. Powdered polylysine is widely adopted in the food additive industry across Asia and Europe due to its cost-effectiveness and long shelf life.
- Coating:Polylysine is integrated into thin films for surface modification, particularly on medical devices or food packaging. This form is gaining traction in the European medical device sector for its antimicrobial properties and biocompatibility.
- Solution:Aqueous formulations provide convenient handling for applications requiring direct incorporation into liquid matrices or sprays.
- Hydrogel:These three-dimensional polymeric networks are used in advanced drug delivery and tissue engineering due to their biocompatibility and controlled release capabilities.
The demand for Powder remains foundational, but innovative uses of Coating are driving new market opportunities.
Application:
Polylysine's applications are differentiated by the volume of material consumed and the specific functional outcome sought. High-volume uses like antimicrobial agents contrast with specialized, lower-volume applications in advanced medical fields.
- Antimicrobial Agent:Polylysine directly inhibits microbial growth in various products, primarily in the food and beverage industry. This application accounts for the largest volume consumption, especially in regions with high processed food production like China and the United States.
- Drug Delivery:Polylysine acts as a carrier for therapeutic agents, enhancing their stability, targeting, and cellular uptake. This high-value application is a focus for pharmaceutical innovation in research hubs across North America and Western Europe.
- Cell Culture:Polylysine promotes cell adhesion and growth on substrates, essential for biotechnology and research laboratories.
- Surface Modification:Polylysine alters material surfaces to improve biocompatibility, adhesion, or antimicrobial properties for various industrial and medical uses.
While Antimicrobial Agent represents the traditional core, advancements in Drug Delivery are opening new frontiers for polylysine utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global polylysine market exhibits a distinct divide between its production hubs and consumption centers. Production is concentrated in regions with advanced bioprocessing capabilities for bacterial fermentation, while demand spans diverse end-use industries worldwide. Polylysine's utility as a natural antimicrobial agent drives its adoption across multiple geographies.
China
China's extensive food processing and export sector drives significant polylysine demand as an antimicrobial agent. The State Administration for Market Regulation (SAMR) oversees its application in food, ensuring safety standards. Production facilities in the Yangtze River Delta region focus on large-scale fermentation to meet industrial requirements.
United States
Demand for clean-label food products and high-value healthcare applications fuels polylysine consumption in the United States. The Food and Drug Administration (FDA) approves polylysine as a food additive, validating its safety profile. Research and development centers in Boston and California explore its use in drug delivery systems.
Germany
European consumer preference for natural ingredients and stringent food safety regulations shape polylysine adoption in Germany. The European Food Safety Authority (EFSA) provides critical market access for natural food additives. Specialized chemical and biotech clusters in Bavaria integrate polylysine into advanced food and medical formulations.
Japan
Japan's advanced biotechnology sector and focus on high-purity ingredients create demand for polylysine in sensitive applications. The Ministry of Economy, Trade and Industry (METI) sets standards for industrial applications including cosmetics and food. Pharmaceutical companies in the Tokyo metropolitan area develop polylysine for cell culture and biomedical research.
Brazil
Emerging economies like Brazil are witnessing growing clean-label food trends, increasing demand for natural preservatives. ANVISA, Brazil's health surveillance agency, regulates food additives, impacting market entry for polylysine. Food and beverage manufacturers in São Paulo integrate polylysine to extend product shelf life for local consumption.
Polylysine Market Key Industry Players
Top-tier vendors anchor the specialized polylysine market by offering high-purity grades for sensitive applications, while mid-sized players often target specific regional food preservation needs. The market structure exhibits a tiered approach, with some companies prioritizing advanced bioprocessing and others competing on volume and cost for industrial uses. Strategic archetypes include bioprocessing specialists, natural food ingredient providers, and biomedical material suppliers. Dominant competitive moves involve continuous investment in bioprocessing efficiency and strategic partnerships for expanded geographic reach and product portfolio diversification.
Among the key players, JNC Corporation exemplifies a focus on high-purity grades for sensitive healthcare and cell culture applications, positioning itself in premium market segments requiring specialized formulations. Handary represents the natural food preservative market, strategically aligning its offerings with evolving clean-label consumer trends across Europe and North America. Zhengzhou Bainafo Bioengineering, a Chinese firm, anchors the industrial uses segment by leveraging its significant production scale to offer cost-effective polylysine for high-volume applications and competes aggressively on price and delivery.
| Leading Market Players |
|---|
| Okuna Chemical Industries Co. |
| Handary |
| JNC Corporation |
| Chengdu Jinkai Biology |
| Shandong Freda |
| Merck & Co., Inc. |
| Siveele B.V. |
| Zhengzhou Bainafo Bioengineering |
| Chisso Co. |
Cost & Logistics Intelligence
Consumer demand for clean-label food products forces polylysine suppliers to invest in specialized formulations and advanced bioprocessing, directly influencing pricing for different market segments.
Pricing Analysis
Cost-down pressure on industrial-grade polylysine accelerates because bacterial fermentation production remains more expensive than chemical synthesis of alternatives. The market operates primarily on a contract-based long-term offtake model for bulk industrial uses. Premium-mid-economy pricing differentiation exists, driven by quality grade, specific regulatory certifications like FDA approval, and customization for particular applications. Industrial food processors are the most price-sensitive buyers, while healthcare and biomedical sectors prioritize performance and purity over cost.
Supply Chain Analysis
Direct-to-manufacturer channels handle the majority of polylysine distribution for food processors and pharmaceutical companies. Geographic supply concentration exists in China, Japan, and European biotech clusters. Production relies heavily on L-lysine as a raw material and specialized Streptomyces strains for fermentation. Production scalability represents a key structural risk, as ensuring consistent yield and purity for large volumes requires significant capital and bioprocessing expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polylysine market is witnessing a vertical-integration race, with players pursuing enhanced bioprocessing capabilities to optimize production costs and expand application reach.
For Market Incumbents:
To counter the cost disadvantage against synthetic preservatives and competition from other natural antimicrobials, incumbents must continuously invest in advanced bioprocessing efficiency. Deepen vertical integration into L-lysine sourcing to secure raw material supply and control input costs. Strategic partnerships with food technology firms can expand the portfolio of customized, broad-spectrum preservative solutions, especially for challenging food matrices.
For New Entrants and Emerging Players:
European Food Safety Authority (EFSA) approvals in Europe opens a window for new entrants focusing on natural food additives. Target niche, high-value applications like functional food packaging or specific healthcare segments requiring advanced biocompatible coatings. A go-to-market angle focusing on synergistic formulations that combine polylysine with other natural antimicrobials offers a differentiated value proposition.
For Investors and Strategic Acquirers:
The window for entry favors bioprocessing specialists with proprietary fermentation technologies or strong regulatory approval portfolios. Long-term viability for polylysine is strong over the next decade due to sustained clean-label trends and expanding biomedical applications. A signal to watch is the successful commercialization of highly cost-effective, large-scale polylysine production methods, which could significantly broaden market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioprocessing Efficiency Investment | Reduces production costs for industrial applications, enhancing competitiveness against synthetic alternatives. |
| Customized Formulation Development | Expands addressable market by tailoring polylysine for specific end-use applications and food matrices. |
| Geographic Market Expansion | Captures demand in emerging economies like Brazil and Southeast Asia, where clean-label trends are growing. |
| Regulatory Approval Pathway Acceleration | Ensures faster market access and product validation across diverse regional food safety authorities. |
| Synergistic Product Blending | Creates more potent, broad-spectrum preservative systems, overcoming individual performance limitations. |
Research Approach
Regulatory body publications from the FDA, EFSA, and SAMR, alongside scientific journals and company annual reports, formed the secondary backbone of this analysis. Primary interviews with food safety experts, bioprocessing engineers, pharmaceutical R&D leads, and procurement managers at food and pharma companies provided critical insights. The study combined bottom-up market sizing with top-down validation through extensive data triangulation.
A bottom-up market sizing approach, cross-referenced with top-down validation, informed the forecast framework across the analysis window. The model segmented the market by product type, end-use industry, form, application, and regional regulatory frameworks. Compound annual growth rates were derived from historical data analysis and projected demand drivers, incorporating consumer preference shifts for natural ingredients and regulatory approval timelines for new applications.
Caveats apply where unforeseen regulatory changes, significant breakthroughs in synthetic preservative alternatives, or major shifts in global food supply chains could materially shift the outlook. Forecasts reflect assumptions documented through a rigorous data collection and validation process. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Polymer Resin Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
South America Thermoplastics Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Global Ultra-High Molecular Weight Polyethylene Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
Global Polymeric Adsorbents Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
Thailand Plastics Market