
 Global ECG Cable and ECG Lead Wires Market | 2026-2036
Global ECG Cable and ECG Lead Wires Market Size, Share, and Industry Trends Forecast 2026-2036
Global ECG Cable and ECG Lead Wires Market Intelligence
Asset-light leasing models for diagnostic equipment are rewriting capital deployment across the ECG cable supply chain. Cardinal Health leverages its distribution scale to bundle cable replacements with device service contracts. GE Healthcare sustains captive manufacturing of shielded lead assemblies for its imaging systems. Koninklijke Philips differentiates through proprietary connector interfaces that lock in recurring cable revenue.
ECG cables and lead wires are insulated conductive assemblies, typically employing silver chloride or copper cores with shielded jackets, engineered to transmit bioelectric signals from patient electrodes to monitoring instrumentation with interference resistance below microvolt thresholds. Their primary purpose is ensuring signal fidelity during cardiac diagnostics across stationary and mobile care settings. Disposable lead wires now dominate volume due to infection control protocols, while conductive polymer technology captures expanding margin pools as hospitals seek latex-free alternatives. Specialized ECG cables for electrophysiology labs command premium positioning given their custom shielding and sterilization compatibility requirements.
The FDA enforces biocompatibility and electrical safety standards under 21 CFR Part 820, while the EU MDR mandates clinical evidence for reusable lead wire classifications, both frameworks elevating barrier costs for new entrants. ISO 13485 certification has become a de facto gate for supplier qualification by major device OEMs. Stakeholders must monitor how cybersecurity addenda to medical device regulations reshape signal transmission architecture and procurement specifications.
Market Dynamics
The ECG cable market is undergoing structural compression as disposable lead wires displace reusable alternatives under infection control mandates, while cybersecurity addenda to medical device regulations force signal transmission architecture redesigns that elevate engineering costs and consolidate supplier tiers.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient cardiac monitoring volumes in the United States, Germany, and China are accelerating replacement cycles for lead wire inventories as procedural throughput rises.
- EU MDR clinical evidence requirements:Reusable lead wire classifications now demand biocompatibility documentation that favors established ISO 13485-certified suppliers with regulatory infrastructure already deployed.
- Conductive polymer substitution:Latex-free alternatives are capturing margin pools as hospitals eliminate natural rubber components from patient-contact assemblies.
Market Restraints
- Silver chloride input volatility:Electrode material costs fluctuate with precious metal markets, compressing margins for manufacturers without long-term supply agreements.
- Shielding technology concentration:Specialized electrophysiology cable production clusters in Germany and Japan create supply vulnerability for North American OEMs seeking custom sterilization-compatible assemblies.
- Wireless ECG patch substitution:Adhesive-based monitoring systems are eroding traditional wired lead wire volumes in low-acuity telemetry applications.
Strategic Opportunities
- Electrophysiology lab specialization:Custom shielding and sterilization compatibility requirements for EP procedures command premium positioning unavailable in standard monitoring segments.
- India hospital infrastructure modernization:Public and private cardiac care facility buildouts are creating procurement windows for cable suppliers with BIS-compliant manufacturing.
- Asset-light leasing integration:Diagnostic equipment rental models enable cable replacement bundling with device service contracts, locking recurring revenue streams.
Industry Challenges
- ISO 13485 certification timeline compression:Major device OEMs now enforce quality management system compliance as a de facto supplier qualification gate, extending onboarding cycles for new entrants.
- Legacy connector interoperability:Proprietary interface designs from established manufacturers create switching friction for hospitals seeking multi-vendor cable sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global ECG Cable and ECG Lead Wires Market |
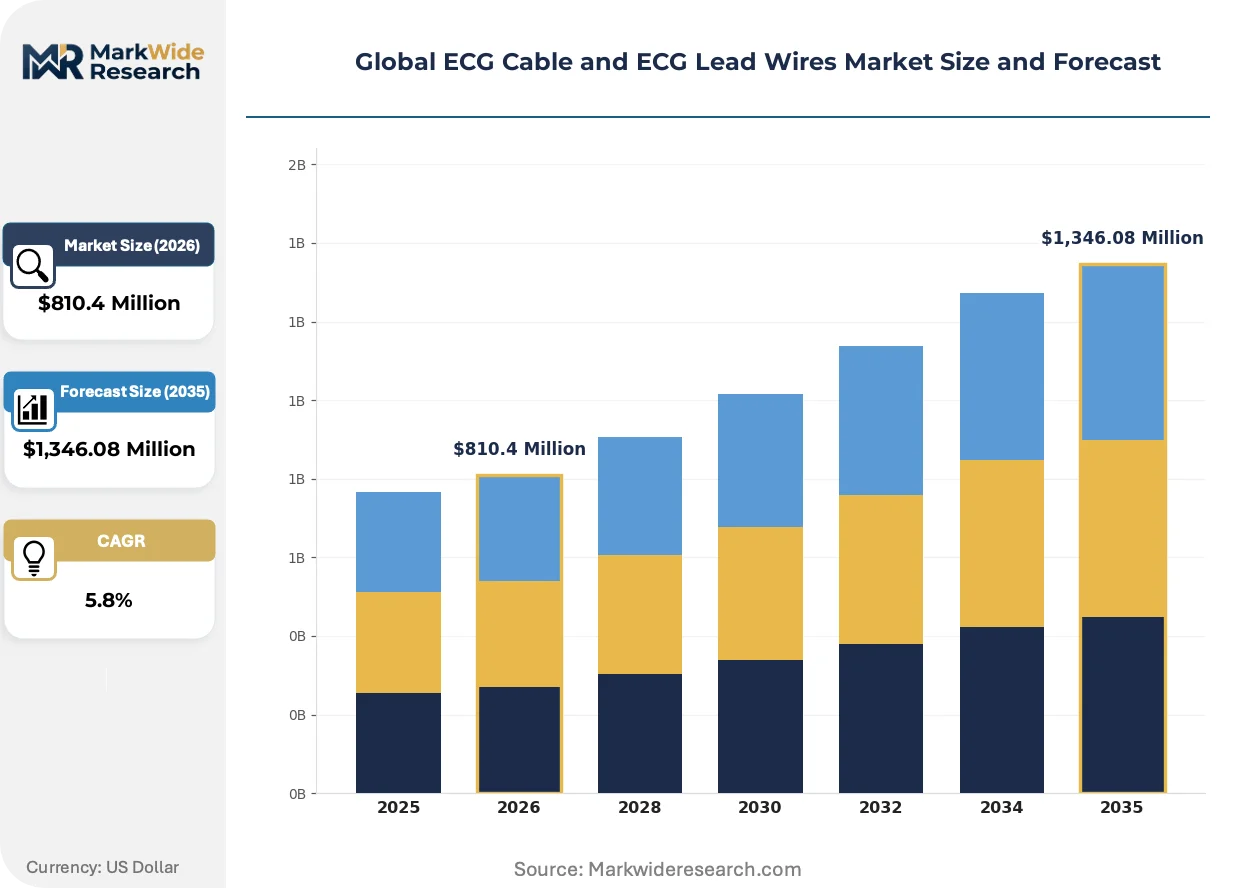
| Market Size in 2026 | $810.4 Million |
| Market Size in 2035 | $1,346.08 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
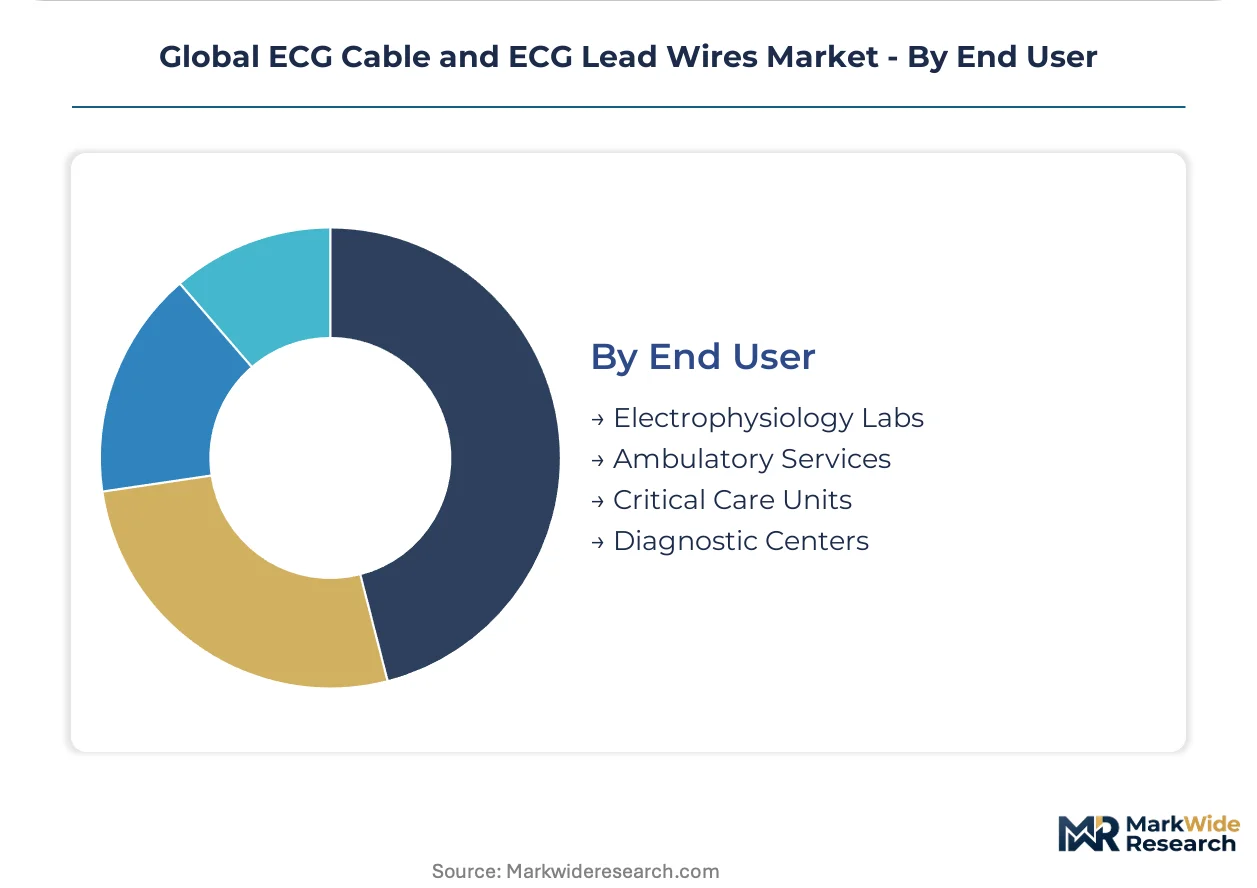
| Segmentation | Product Type: Disposable Lead Wires, Reusable Lead Wires, Standard ECG Cables, Specialized ECG Cables Technology: Silver Chloride, Copper, Conductive Polymer, Carbon Fiber, Gold Plated Application: Cardiac Monitoring, Stress Testing, Holter Monitoring, Surgical Monitoring, Emergency Care End User: Electrophysiology Labs, Ambulatory Services, Critical Care Units, Diagnostic Centers |
| Companies Covered | Cardinal Health, 3M Company, GE Healthcare, Koninklijke Philips, Becton Dickinson and Company, Medtronic, Shenzhen Mindray Bio-Medical Electronics, CONMED Corporation, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global ECG Cable and ECG Lead Wires Market Strategic Shifts & Innovations
Material science advances and regulatory cybersecurity mandates are converging to reshape ECG cable engineering specifications and procurement patterns across cardiac care settings.
Conductive polymer formulations are migrating from niche latex-free alternatives toward mainstream lead wire production as hospitals eliminate natural rubber from patient-contact devices. Academic medical centers in the United States and Germany are specifying polymer cores for new procurement cycles. This shift is compressing traditional PVC-and-copper supply relationships while elevating material science capabilities among qualified vendors.
The FDA's updated medical device cybersecurity guidance is forcing signal transmission architecture redesigns that embed encryption and authentication protocols within cable assemblies. Manufacturers must now document threat modeling and vulnerability management across product lifecycles. Electrophysiology cable suppliers face the steepest compliance burden given the sensitivity of intracardiac signal data their products transmit.
Hospital procurement departments are consolidating cable purchasing through group purchasing organizations and integrated delivery networks, displacing fragmented departmental buying. This concentration is compressing supplier margins while favoring vendors with national distribution scale and service contract bundling capabilities. The United States exhibits the most pronounced procurement centralization, with similar patterns emerging in German hospital networks.
Global ECG Cable and ECG Lead Wires Market Segmentation
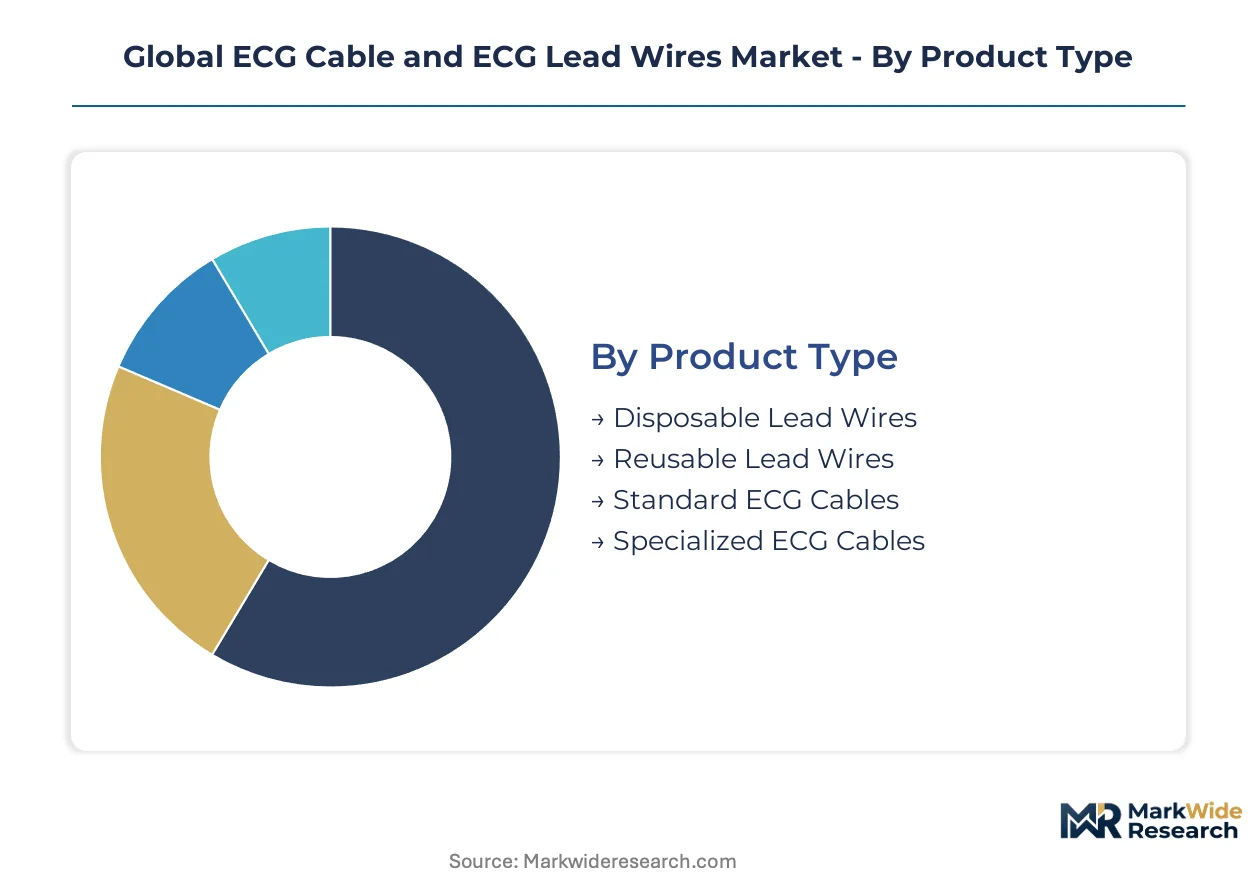
ECG cable and lead wire procurement patterns diverge sharply across product lifecycles, material technologies, and care settings. Hospital infection control mandates and electrophysiology specialization requirements create distinct demand pockets that reshape supplier positioning and margin structures.
Product Type:
Mature disposable formats dominate hospital procurement volumes while reusable alternatives contract under regulatory pressure.
- Disposable Lead Wires:Single-use assemblies with PVC or TPE insulation eliminate cross-contamination risks in high-throughput cardiac units. United States hospital systems now mandate disposable protocols for telemetry floors, compressing reusable wire inventories.
- Reusable Lead Wires:Silicone-jacketed copper cores with sterilization-rated connectors persist in electrophysiology labs where custom lengths and shielding specifications justify reprocessing economics.
- Standard ECG Cables:Shielded multi-conductor assemblies for bedside monitors represent baseline procurement with thin margins.
- Specialized ECG Cables:Custom shielding and sterilization-compatible jackets for EP procedures command premium positioning unavailable in standard segments.
Disposable lead wires retain volume leadership; specialized ECG cables hold the steepest expansion curve.
Technology:
Material cost tiers separate commodity conductors from premium bioelectric interfaces.
- Silver Chloride:Electrode interface material with stable half-cell potential ensures signal fidelity in diagnostic-grade assemblies. Precious metal price volatility compresses margins for manufacturers without long-term supply agreements.
- Copper:Oxygen-free high-conductivity cores dominate standard cable production where cost efficiency trumps biocompatibility specifications.
- Conductive Polymer:Latex-free elastomer formulations capture expanding procurement share as German and United States academic medical centers eliminate natural rubber from patient-contact devices.
- Carbon Fiber:Lightweight conductive cores enable ambulatory Holter configurations where patient mobility dictates cable mass.
- Gold Plated:Corrosion-resistant connector interfaces sustain signal integrity across repeated sterilization cycles in EP lab environments.
Silver chloride retains volume leadership; conductive polymer holds the steepest expansion curve.
Application:
Procedural acuity determines cable specification complexity and replacement frequency.
- Cardiac Monitoring:Continuous telemetry applications in critical care units drive highest-volume cable consumption with standardized 3-lead and 5-lead configurations.
- Stress Testing:Exercise-tolerant shielded assemblies with strain-relief engineering capture demand from outpatient cardiology expansion in China and Germany.
- Holter Monitoring:Lightweight 24-48 hour ambulatory configurations prioritize patient comfort over signal shielding sophistication.
- Surgical Monitoring:Sterilization-compatible lead sets for operating rooms face substitution pressure from wireless patch systems in low-acuity procedures.
- Emergency Care:Rapid-deployment disposable sets for emergency departments emphasize packaging efficiency and immediate readiness.
Cardiac monitoring retains volume leadership; stress testing holds the steepest expansion curve.
End User:
Customer concentration patterns favor integrated delivery networks over fragmented departmental purchasing.
- Electrophysiology Labs:Custom shielding requirements and proprietary connector interfaces lock in specialized cable suppliers with EP-specific certification portfolios.
- Ambulatory Services:Outpatient surgical centers in the United States accelerate replacement cycles as procedural throughput rises, favoring disposable wire procurement.
- Critical Care Units:Hospital telemetry floors consolidate cable purchasing through group purchasing organizations, compressing supplier margins.
- Diagnostic Centers:Independent imaging facilities prioritize cost-optimized standard cables over specialized configurations.
Critical care units retain volume leadership; electrophysiology labs hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in ECG cable assemblies tilt toward net-import dependence in high-acuity care markets while manufacturing capacity clusters in precision electronics hubs. Currency-adjusted procurement costs and regulatory compliance timelines now determine sourcing footprints more than labor arbitrage alone.
United States
Hospital infrastructure modernization drives cable replacement cycles across integrated delivery networks. FDA cybersecurity addenda to 21 CFR Part 820 extend supplier qualification timelines for encrypted signal transmission assemblies. Minneapolis and Cleveland host electrophysiology device clusters where custom shielded cable procurement concentrates.
Germany
Academic medical center expansion in Bavaria and Baden-Württemberg elevates demand for sterilization-compatible EP lab configurations. EU MDR clinical evidence requirements for reusable lead wires favor ISO 13485-certified suppliers with established notified body relationships. Freiburg and Erlangen anchor specialized cable manufacturing for electrophysiology applications.
China
Public hospital cardiac care facility buildouts accelerate procurement of standard monitoring cables. NMPA biocompatibility standards for patient-contact devices elevate barrier costs for domestic suppliers. Shenzhen and Shanghai concentrate disposable lead wire production for both domestic consumption and export assembly.
India
Private hospital infrastructure investment in Maharashtra and Karnataka creates procurement windows for BIS-compliant cable suppliers. CDSCO medical device registration requirements for imported lead wires extend commercialization timelines. Delhi-NCR and Chennai emerge as diagnostic equipment distribution hubs bundling cable replacements with service contracts.
Japan
Aging demographics expand ambulatory cardiac monitoring volumes in Tokyo and Osaka metropolitan areas. PMDA quality management system inspections for foreign manufacturers compress supplier onboarding flexibility. Nagoya and Kyoto host precision connector manufacturing clusters serving domestic EP device OEMs.
Global ECG Cable and ECG Lead Wires Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: diversified health technology conglomerates with captive cable production, specialized medical interconnect fabricators, and regional disposable assembly suppliers. Conglomerates leverage device-service bundling to lock recurring cable revenue. Specialists command premium positioning in EP lab custom configurations. Regional assemblers compete on cost for high-volume disposable procurement. Dominant competitive moves include diagnostic equipment leasing integration and proprietary connector interface development.
Among diversified health technology conglomerates, Cardinal Health, GE Healthcare, and Koninklijke Philips exemplify distinct strategic archetypes. Cardinal Health occupies a position emphasizing distribution scale and service contract bundling. GE Healthcare represents captive manufacturing integration for imaging system compatibility. Koninklijke Philips anchors a tier defined by proprietary connector ecosystems that create switching friction for hospital procurement.
| Leading Market Players |
|---|
| Cardinal Health |
| 3M Company |
| GE Healthcare |
| Koninklijke Philips |
| Becton Dickinson and Company |
| Medtronic |
| Shenzhen Mindray Bio-Medical Electronics |
| CONMED Corporation |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
Overcapacity in Shenzhen disposable lead wire manufacturing compresses supplier pricing power while elevating procurement leverage for United States hospital group purchasing organizations. German electrophysiology cable specialists maintain premium positioning through sterilization-compatible shielding capabilities that command cost-plus contracting.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Cardinal Health and Koninklijke Philips extract brand premiums through proprietary connector ecosystems and bundled service contracts, while ISO 13485 certification tier separates qualified suppliers from commodity assemblers. Cost compression in standard monitoring cables intensifies as Chinese manufacturers expand disposable wire capacity. Ambulatory surgical centers exhibit highest price sensitivity; electrophysiology labs demonstrate least sensitivity due to custom shielding requirements.
Supply Chain Analysis
Export controls on precision shielding alloys limit technology flows from Germany and Japan to North American cable assemblers. Silver chloride electrode materials draw from Chilean and Australian mining operations; conductive polymer formulations rest on South Korean and German petrochemical feedstocks. Single-source vulnerability concentrates in Freiburg and Nagoya electrophysiology component clusters. Distribution runs through Cardinal Health and regional medical device distributors serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in ambulatory cardiac monitoring creates procurement windows as outpatient procedural volumes accelerate replacement cycles across United States, Germany, and China hospital systems.
For Market Incumbents: Pre-empt wireless ECG patch substitution by embedding encryption protocols into cable assemblies ahead of FDA cybersecurity enforcement. Defend electrophysiology premium positioning through backward integration into sterilization-compatible shielding manufacturing in Freiburg and Nagoya clusters. Lock hospital system loyalty via diagnostic equipment leasing models that bundle cable replacements with device service contracts.
For New Entrants and Emerging Players: Mid-market ambulatory surgical centers in India and Southeast Asia represent the most penetrable entry point given CDSCO and BIS compliance gaps among established suppliers. Conductive polymer latex-free alternatives capture margin pools as German and United States academic medical centers eliminate natural rubber. Pursue GPO contract qualification through ISO 13485 certification investment rather than direct hospital sales approaches.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized electrophysiology cable fabricators with EP lab certification portfolios and proprietary connector interfaces. Long-term viability hinges on cybersecurity compliance infrastructure and notified body relationships under EU MDR. Monitor FDA guidance finalization on medical device encryption as inflection indicator for engineering cost escalation and supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Compliance Pathway | Encryption protocol documentation under 21 CFR Part 820 elevates barrier costs for new cable entrants. |
| EU MDR CE Marking Investment | Clinical evidence requirements for reusable lead wires favor ISO 13485-certified suppliers with notified body infrastructure. |
| Hospital System Partnership | Integrated delivery network contracts consolidate procurement through group purchasing organizations. |
| Conductive Polymer R&D Program | Latex-free elastomer formulations capture procurement share from academic medical centers eliminating natural rubber. |
| Electrophysiology Lab Specialization | Custom shielding and sterilization compatibility command premium positioning unavailable in standard monitoring segments. |
Research Approach
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and electrophysiology lab directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and customs trade records. Bottom-up cable volume estimates triangulated against top-down cardiac monitoring device shipments across the analysis window.
Scenario-bracketing framed projections across product type, material technology, application acuity, and end-user concentration dimensions. CAGRs derived from replacement cycle analysis, procedural volume trajectories, and infection control protocol adoption curves. Silver chloride price volatility and cybersecurity compliance cost escalation served as industry-specific sensitivity inputs throughout the modeling period.
Macroeconomic conditions sit as an overlay; deviation in precious metals pricing, hospital capital expenditure cycles, or medical device regulatory enforcement would shift the trajectory. Forecasts reflect documented assumptions regarding ambulatory surgical center expansion rates and conductive polymer substitution timelines. Material shifts in FDA cybersecurity guidance scope or EU MDR clinical evidence requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Defibrillator Pads Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Cranial Implants Treatment Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Eye Massage Device Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
Global Intraosseous Devices Market
Medical Devices
Near Vision Devices Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Latin America Implantable Medical Devices Market
Medical Devices
China Diabetes Devices Market
Medical Devices
Single-Use Assemblies Market