
 Abdominal Compression Garments Market | 2026-2036
Abdominal Compression Garments Market Size, Share, and Industry Trends Forecast 2026-2036
Abdominal Compression Garments Market Insights
Subscription-based replenishment programs for post-surgical garment replacements is realigning how manufacturers monetize patient recovery journeys. 3M leverages its hospital supply chain infrastructure to secure long-term procurement contracts with surgical centers. Marena Group specializes in medical-grade compression fabrics that command premium positioning in cosmetic surgery channels.
Abdominal compression garments are elastic textile devices engineered with graduated pressure ratings, typically 15-30 mmHg, constructed from multi-layer blends of nylon, spandex, and medical-grade neoprene to stabilize core musculature and promote post-operative tissue healing. Their primary commercial purpose spans post-operative recovery management, pain mitigation, and structural body contouring across clinical and consumer settings. Post-surgical applications anchor current revenue volumes due to mandatory physician prescribing protocols, while shapewear segments attract direct-to-consumer margin expansion through aesthetic positioning. Material innovation in breathable neoprene alternatives is displacing traditional rubber-core constructions in high-humidity climates.
FDA Class I device exemptions and ISO 13485 quality management standards govern market entry for medical-claim products in the United States, while CE marking under the EU Medical Device Regulation structures European commercialization requirements. These frameworks elevate compliance costs for new entrants but protect incumbent positions of certified manufacturers. Stakeholders must monitor evolving reimbursement codes for compression therapy as payer policies increasingly tie coverage to clinical outcome documentation rather than device procurement alone.
Market Dynamics
Hospital networks in Germany and the United States are consolidating post-surgical garment procurement through multi-year supply agreements, compressing vendor margins while locking in volume commitments that reshape competitive positioning.
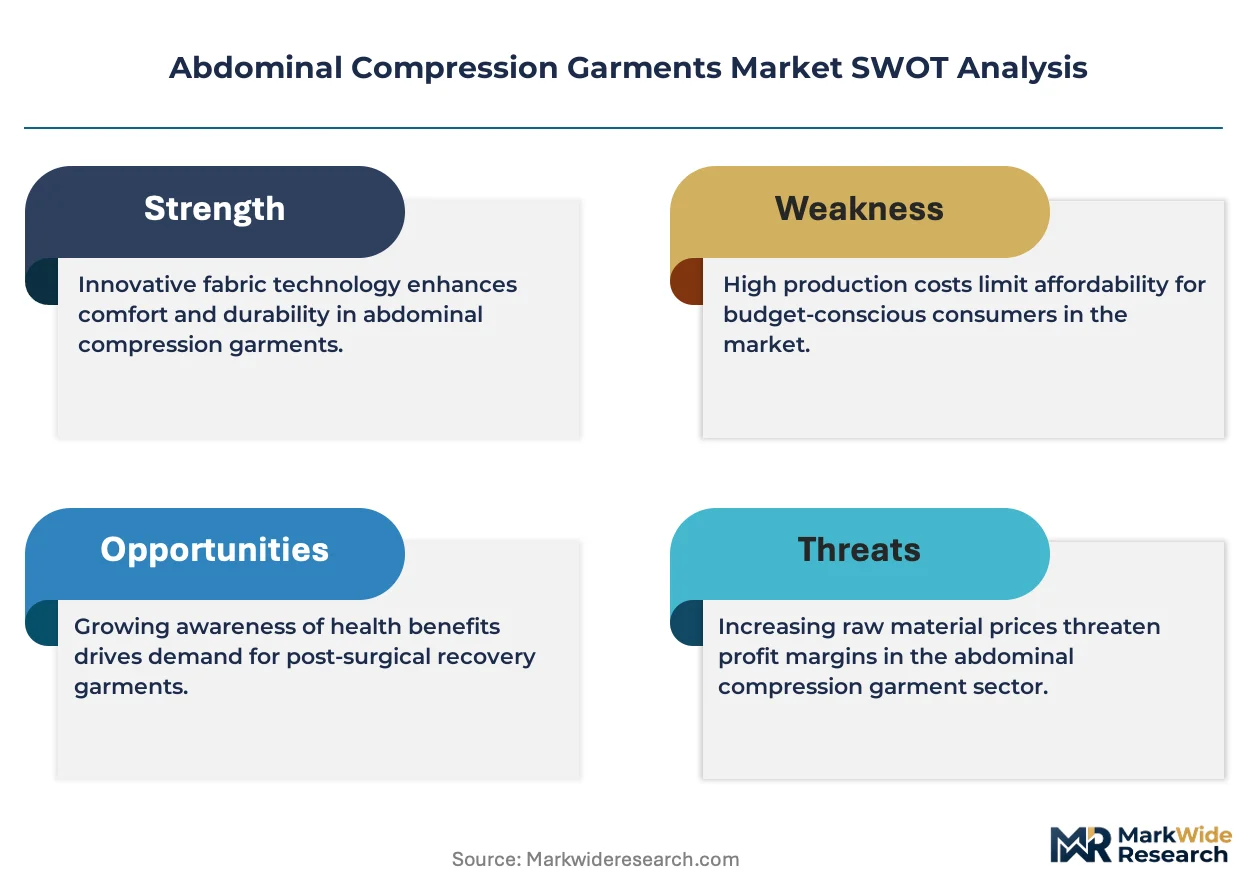
Growth Catalysts
- FDA Class I Device Exemptions:Streamlined 510(k) clearance pathways accelerate product launches for US manufacturers, reducing time-to-revenue for medical-grade compression lines.
- Cosmetic Surgery Channel Expansion:Elective abdominoplasty procedures in Brazil's private clinic network drive direct-to-consumer demand for premium garment tiers.
- Neoprene Alternative Materials:Breathable polymer blends with moisture-wicking properties displace traditional rubber-core constructions in humid climates, expanding addressable markets.
Market Restraints
- Medical-Grade Textile Input Concentration:Nylon-spandex blend supply chains cluster in China's Zhejiang province, exposing manufacturers to tariff volatility and logistics disruption.
- ISO 13485 Certification Timelines:Quality management system audits require 12-18 month implementation cycles, creating barriers for new entrants seeking medical-device claims.
- Over-the-Counter Analgesic Substitution:Oral pain management protocols in India's public hospital system reduce physician prescribing of compression therapy for minor procedures.
Strategic Opportunities
- Subscription Replenishment Models:Post-surgical patients require garment replacement every 4-6 weeks, enabling recurring revenue streams through automated fulfillment.
- EU Medical Device Regulation Harmonization:CE marking mutual recognition agreements with Switzerland and Norway expand addressable European markets without duplicate certification.
- Athletic Recovery Positioning:CrossFit and powerlifting communities in Australia adopt medical-grade compression for core stability, creating consumer-channel price premiums.
Industry Challenges
- Biocompatibility Testing Capacity:ISO 10993 cytotoxicity assessment backlogs at certified laboratories delay product launches by 3-4 months.
- Legacy Hospital ERP Integration:Procurement systems at mid-sized German surgical centers require manual purchase order processing, increasing administrative friction for automated replenishment programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abdominal Compression Garments Market |
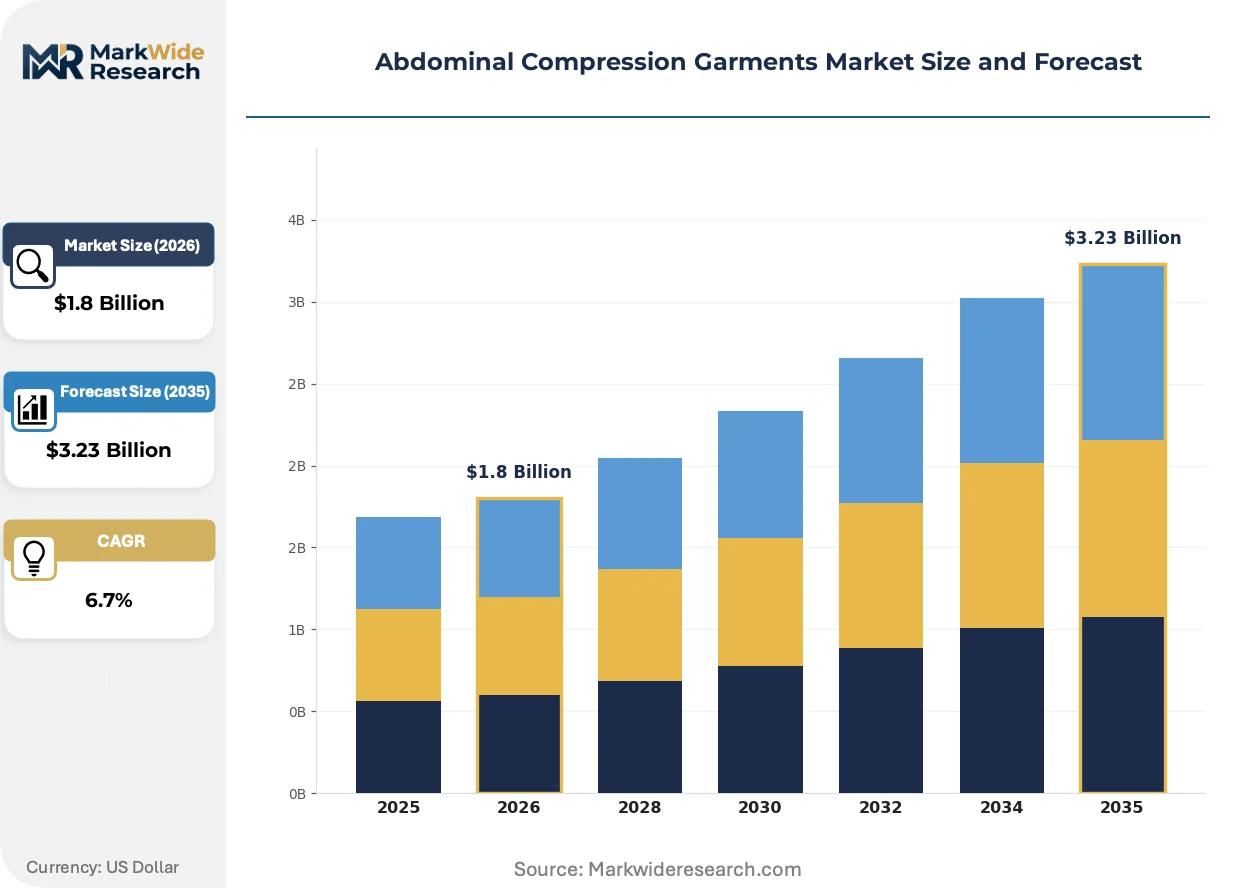
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Post-Surgical, Postpartum, Hernia Support, Sports Compression, Shapewear Material: Neoprene, Cotton, Nylon, Spandex, Polyester End User: Orthopedic Clinics, Physiotherapy Centers, Fitness Centers, Cosmetic Surgery Centers Application: Post-Operative Recovery, Pain Relief, Body Contouring, Injury Prevention, Muscle Support |
| Companies Covered | 3M, Bauerfeind, Cardinal Health, ContourMD, Lohmann & Rauscher, Medi GmbH & Co. KG, Marena Group, SIGVARIS Group, Thuasne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abdominal Compression Garments Market Trends and Innovations
Material science advances and regulatory harmonization are compressing product development cycles while reshaping how compression therapy interfaces with digital health infrastructure.
Smart textile integration is unifying pressure-sensing yarns with Bluetooth-enabled feedback systems. Post-operative recovery clinics in South Korea embed these garments in remote patient monitoring protocols. The technology is unifying compression therapy with telemedicine reimbursement codes, enabling outcome-based contracting with private insurers.
EU Medical Device Regulation (MDR) Article 120 transition deadlines are forcing legacy manufacturers to renew technical documentation for existing CE-marked products. Class I reusable compression garments now require notified body involvement where previously self-certified. German orthopedic networks are accelerating supplier consolidation to reduce compliance auditing overhead across fragmented vendor bases.
Direct-to-consumer channel expansion is fragmenting traditional distributor relationships. Cosmetic surgery patients in Brazil and Mexico research garment specifications through social media platforms before clinic consultations. This behavior shift concentrates marketing spend on influencer partnerships and patient education content, bypassing medical supply wholesalers who historically controlled product visibility.
Abdominal Compression Garments Market Segmentation
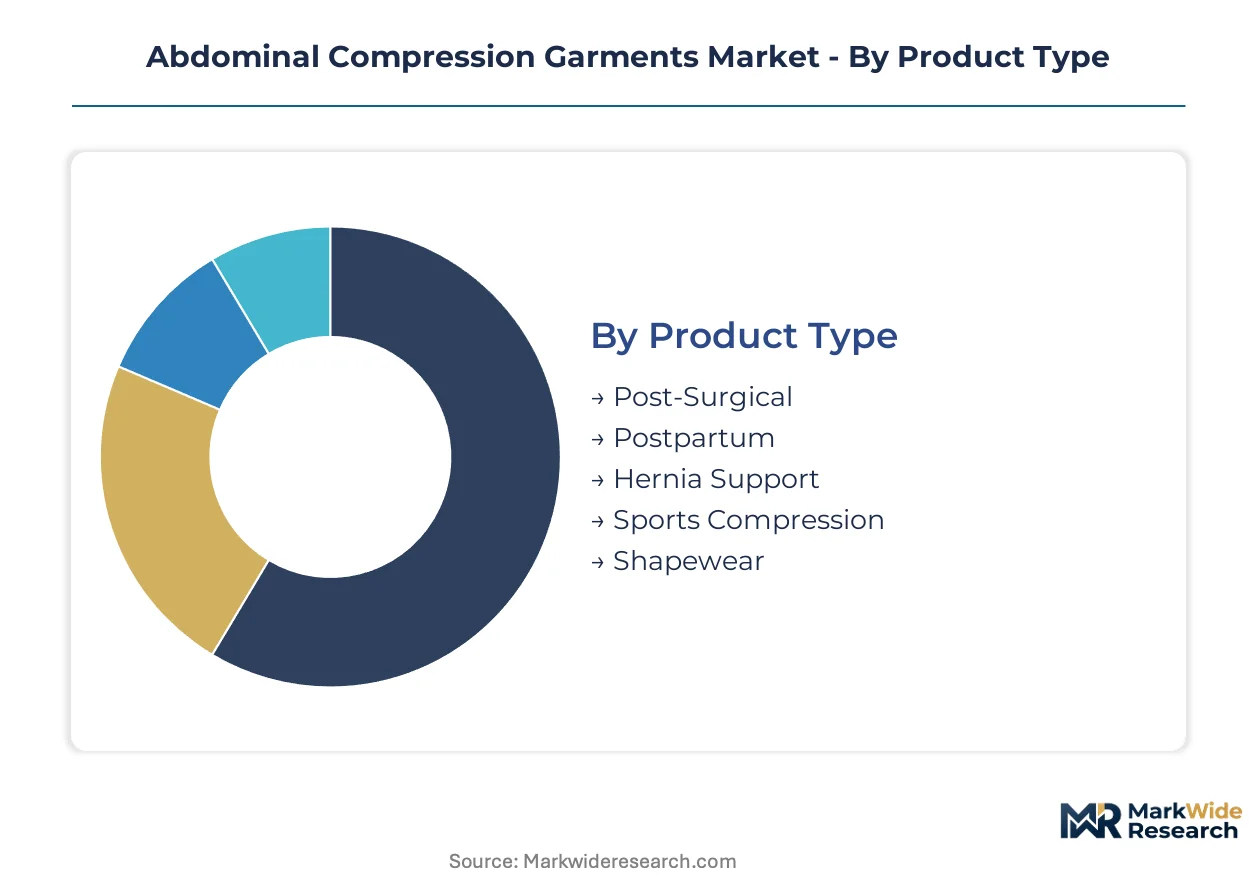
Compression garment purchasing patterns diverge sharply across clinical versus consumer channels, with material specifications and pressure ratings determining reimbursement eligibility versus direct-pay price sensitivity. Manufacturers must engineer distinct product architectures for each segment to capture margin without duplicating compliance overhead.
Product Type:
Pressure ratings and construction methods distinguish medical-grade from consumer-grade offerings, with 20-30 mmHg graduated compression marking the regulatory threshold.
- Post-Surgical:Constructed with medical-grade neoprene cores and antimicrobial linings, these garments deliver 20-30 mmHg graduated pressure for tissue stabilization following abdominoplasty or hernia repair. Demand concentrates in Germany's orthopedic clinic network where physician prescribing protocols mandate specific pressure ratings. ISO 13485 certification requirements lock in incumbent suppliers and exclude consumer-grade competitors.
- Shapewear:Lower-pressure nylon-spandex blends target aesthetic body contouring without medical claims, enabling direct-to-consumer distribution through e-commerce channels. Brazil's cosmetic surgery patients drive premium tier demand, researching specifications via social platforms before clinic consultations. This segment escapes FDA 510(k) requirements, accelerating product refresh cycles.
- Postpartum:Breathable cotton-polyester blends address abdominal wall recovery following cesarean delivery, positioned between medical and consumer classifications.
- Hernia Support:Reinforced panel constructions with rigid anterior stays provide structural support for inguinal and incisional hernia management.
- Sports Compression:Moisture-wicking polymer blends target CrossFit and powerlifting communities in Australia for core stability during high-load movements.
Mature deployment sits with Post-Surgical. Newer deployment is concentrated in Shapewear.
Material:
Raw material selection determines breathability, durability, and regulatory pathway, with polymer chemistry innovations displacing legacy rubber-core constructions.
- Neoprene:Closed-cell synthetic rubber delivers thermal retention and consistent pressure maintenance across 12-18 month garment lifespans. China's Zhejiang province concentrates global neoprene textile production, exposing manufacturers to tariff volatility and logistics disruption. FDA Class I exemptions apply to neoprene-based medical claims.
- Nylon:High-tenacity polyamide fibers provide abrasion resistance and shape retention for extended-wear applications. Spandex blending ratios of 15-25% determine elasticity recovery rates after repeated laundering cycles.
- Spandex:Elastane content governs compression gradient precision and wearer comfort during extended daily use.
- Cotton:Natural fiber content addresses skin sensitivity concerns in postpartum and pediatric applications where breathability outweighs pressure precision.
- Polyester:Hydrophobic synthetic enables rapid moisture transport for athletic recovery positioning and high-humidity climate expansion.
Volume leadership belongs to Neoprene. Steepest expansion trajectory is concentrated in Polyester moisture-wicking formulations.
End User:
Procurement authority and reimbursement structures vary dramatically across facility types, reshaping sales force deployment and pricing architecture.
- Orthopedic Clinics:Germany's clinic networks consolidate purchasing through multi-year supply agreements, compressing vendor margins while guaranteeing volume commitments. These facilities require ISO 13485-certified suppliers with established CE marking under EU MDR Article 120 transition deadlines.
- Cosmetic Surgery Centers:Brazil's private clinic network drives direct-to-consumer demand for premium garment tiers, with patients researching specifications independently before consultations.
- Physiotherapy Centers:Rehabilitation-focused facilities prescribe compression for post-operative mobility protocols and pain mitigation.
- Fitness Centers:Athletic recovery positioning creates consumer-channel price premiums among CrossFit communities in Australia.
Contracted volume concentrates in Orthopedic Clinics. Discretionary premium capture is expanding fastest in Cosmetic Surgery Centers.
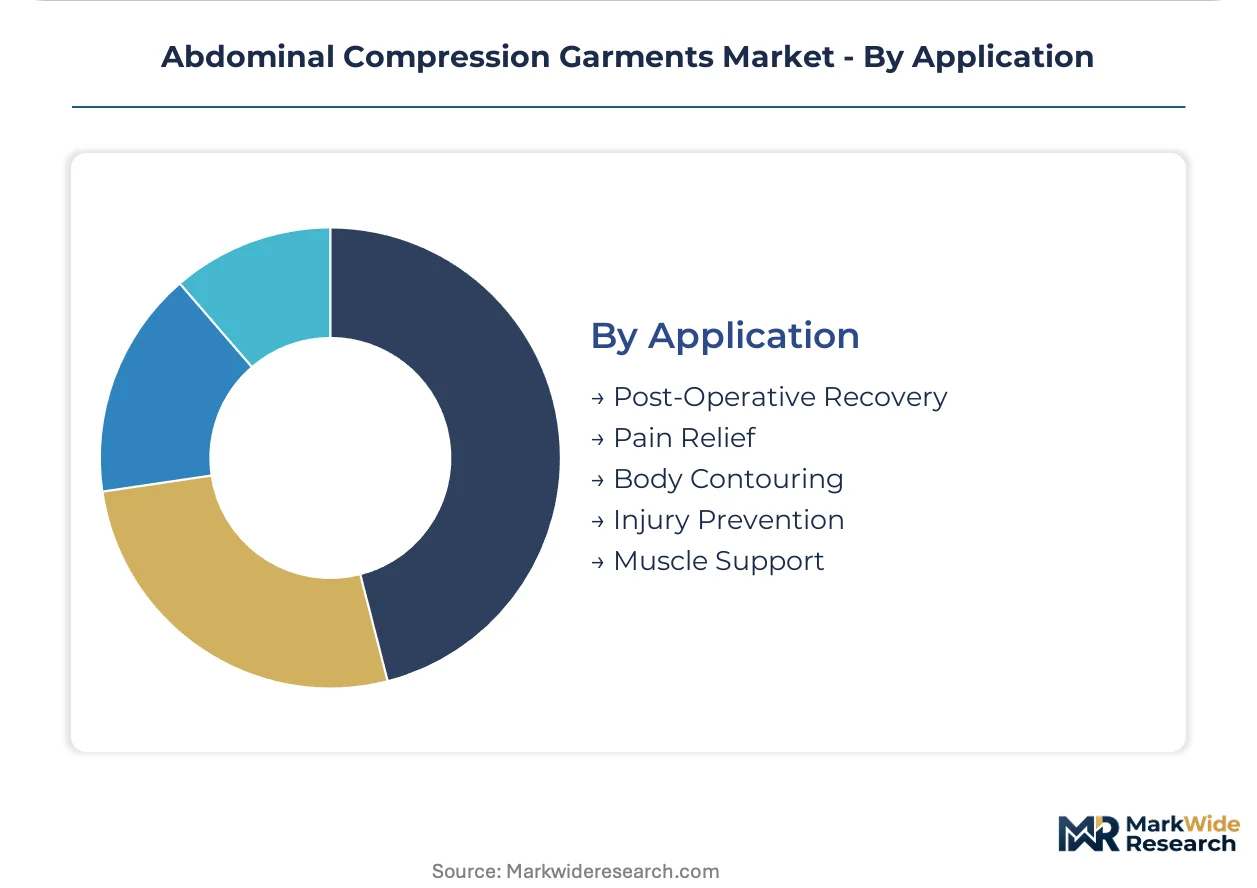
Application:
Clinical outcome documentation requirements increasingly tie reimbursement to therapeutic results rather than device procurement alone.
- Post-Operative Recovery:Mandatory physician prescribing protocols anchor current revenue volumes, with garment replacement every 4-6 weeks enabling subscription replenishment models. South Korean recovery clinics embed smart textile garments in remote patient monitoring protocols, unifying compression therapy with telemedicine reimbursement codes.
- Pain Relief:Oral analgesic substitution in India's public hospital system reduces physician prescribing of compression therapy for minor procedures, constraining volume in price-sensitive settings.
- Body Contouring:Aesthetic applications bypass medical device regulations, enabling faster product launches and direct-to-consumer marketing.
- Injury Prevention:Prophylactic use in athletic settings requires consumer education investments to establish clinical credibility.
- Muscle Support:Core stabilization applications bridge medical and consumer positioning, creating pricing ambiguity.
Reimbursement depth is greatest in Post-Operative Recovery. Direct-pay margin expansion is climbing fastest in Body Contouring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province in China concentrates global neoprene textile production, exposing manufacturers to tariff volatility while German orthopedic clinic networks drive premium medical-grade demand through consolidated procurement.
United States
FDA 510(k) clearance pathways accelerate product launches for medical-grade compression lines. Hospital supply chain infrastructure secures long-term procurement contracts with surgical centers. Post-surgical recovery programs in major metropolitan hospital networks expand garment procurement volumes.
Germany
Orthopedic clinic networks consolidate purchasing through multi-year supply agreements. EU Medical Device Regulation Article 120 transition deadlines force legacy manufacturers to renew technical documentation. The country's notified body involvement requirements for Class I reusable garments accelerate supplier consolidation.
Brazil
Elective abdominoplasty procedures in private clinic networks drive direct-to-consumer demand for premium garment tiers. ANVISA regulatory frameworks shape medical device commercialization requirements. Cosmetic surgery patients research garment specifications through social media platforms before consultations.
South Korea
Post-operative recovery clinics embed smart textile garments in remote patient monitoring protocols. MFDS medical device regulations govern product registration timelines. Seoul-based telemedicine platforms unify compression therapy with reimbursement codes for outcome-based contracting.
Australia
CrossFit and powerlifting communities adopt medical-grade compression for core stability during high-load movements. TGA therapeutic goods administration oversees medical claim classifications. Melbourne and Sydney fitness centers create consumer-channel price premiums for athletic recovery positioning.
Abdominal Compression Garments Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the abdominal compression garments landscape. The market structure exhibits tiered concentration with incumbent medical device manufacturers holding certified positions against emerging direct-to-consumer specialists. Three strategic archetypes dominate: diversified healthcare conglomerates with hospital supply chain integration, specialized medical textile firms with ISO 13485 certification depth, and digitally native shapewear brands bypassing traditional distribution. Competitive moves center on backward integration into polymer supply chains and subscription-based replenishment program deployment.
Within the diversified healthcare tier, 3M leverages established hospital procurement relationships while Marena Group exemplifies specialized medical-grade compression fabric positioning. Among European-certified manufacturers, Bauerfeind and Medi GmbH & Co. KG occupy positions anchored by CE marking compliance and orthopedic clinic network penetration. These named entities represent the certification-driven consolidation dynamic reshaping vendor selection criteria across German and United States hospital systems.
| Leading Market Players |
|---|
| 3M |
| Bauerfeind |
| Cardinal Health |
| ContourMD |
| Lohmann & Rauscher |
| Medi GmbH & Co. KG |
| Marena Group |
| SIGVARIS Group |
| Thuasne |
| Others |
Pricing and Supply Chain Analysis
EU MDR Article 120 transition deadlines gate qualified supply access and premium-tier pricing power, as notified body involvement requirements for Class I reusable garments force hospital networks toward ISO 13485-certified incumbents who command sustained margin premiums over uncertified competitors.
Pricing Analysis
Outcome-based contracting with private insurers anchors value-based pricing for smart textile-integrated garments in South Korean telemedicine platforms. Three-tier pricing structure across premium medical-grade, standard clinical, and economy direct-to-consumer levels stratifies by ISO 13485 certification depth and pressure rating precision. Cost compression in standard clinical tiers intensifies because German orthopedic networks consolidate procurement through multi-year supply agreements. Cosmetic surgery patients in Brazil exhibit lowest price sensitivity, while India's public hospital system shows highest substitution elasticity toward oral analgesics.
Supply Chain Analysis
Ocean freight rate volatility from China's Zhejiang province to European notified body hubs elevates landed costs for neoprene textile inputs. Nylon-spandex blend production draws from China, South Korea, and Germany, with medical-grade neoprene cores sourced from Zhejiang's polymer clusters. Tariff exposure on Chinese textile imports presents structural risk for US manufacturers dependent on Asian supply. Distribution runs through hospital supply chain infrastructure for medical-grade tiers, while direct-to-consumer channels bypass traditional medical wholesalers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR Article 120 notified body involvement requirements erect barrier-to-entry moats protecting incumbent ISO 13485-certified manufacturers from price-erosion by uncertified competitors.
For Market Incumbents: Anchor market position through backward integration into Zhejiang neoprene textile supply chains to neutralize tariff volatility exposure. Deepen hospital system partnership density in Germany's consolidating orthopedic networks before competitor certification cycles complete. Smart textile R&D investment represents the priority defensive lever against direct-to-consumer shapewear brands eroding clinical-channel pricing power.
For New Entrants and Emerging Players: Breathable polyester moisture-wicking formulations targeting Australia's CrossFit communities offer the most penetrable white-space entry. Bypass ISO 13485 certification overhead by positioning in athletic recovery consumer channels where medical claims remain unnecessary. Direct-to-consumer influencer marketing partnerships in Brazil's cosmetic surgery patient communities provide the lowest-friction go-to-market angle.
For Investors and Strategic Acquirers: FDA 510(k) clearance pathway acceleration for US manufacturers is the leading indicator that regulatory arbitrage opportunities are compressing. Five-to-ten year viability favors specialized medical textile firms with dual FDA-CE marking depth over diversified healthcare conglomerates facing channel conflict. Watch for ANVISA regulatory framework tightening in Brazil as the inflection signal for Latin American market access premium repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Notified body involvement under EU MDR Article 120 locks in German hospital network vendor status. |
| Smart Textile Platform Integration | Bluetooth-enabled pressure sensing in Seoul clinics unifies compression therapy with telemedicine reimbursement codes. |
| Backward Integration into Polymer Supply | Captive neoprene textile production in Zhejiang neutralizes tariff exposure on Chinese imports. |
| Direct-to-Consumer Channel Launch | Social media influencer partnerships in Brazil bypass traditional medical supply wholesalers controlling product visibility. |
| Subscription Replenishment Program Deployment | Automated 4-6 week garment replacement cycles convert one-time surgical purchases into recurring revenue streams. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR technical documentation renewal cycles, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with orthopedic clinic purchasing managers, biomedical textile engineers, GPO contracts administrators, and cosmetic surgery clinic operators. Secondary validation drew from FDA device classification databases, CE marking notified body registries, German hospital procurement databases, and ANVISA medical device registration filings. Bottom-up volume modeling across pressure rating tiers and top-down value triangulation against hospital supply chain expenditure reports converged on segment-level estimates.
Segment-weighting approaches applied differential growth assumptions across post-surgical, shapewear, postpartum, hernia support, and sports compression product types, with material chemistry innovation trajectories and end-user procurement authority structures as cross-cutting dimensions. CAGRs were derived from fitted trend extrapolation against historical procurement volume patterns, with neoprene alternative material penetration rates and subscription replenishment program adoption curves as industry-specific forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including unforeseen biocompatibility testing capacity constraints at ISO 10993-certified laboratories, abrupt tariff regime shifts on Chinese textile imports, and payer policy revisions delinking compression therapy reimbursement from clinical outcome documentation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Global Needles Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Cryogenic Vials and Tubes Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Nucleic Acid Isolation and Purification Kits Market