
 Near Vision Devices Market | 2026-2036
Near Vision Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Near Vision Devices Market Foresight
Germany is narrowing its position as a precision optics manufacturing hub for near vision devices. Eschenbach Optik GmbH leverages its Bavarian production base to dominate European distribution of magnifying glasses and low-vision aids. Vispero sustains R&D intensity across electronic video magnifier platforms, while OrCam differentiates through wearable text-to-speech technology for visually impaired users.
Near vision devices correct presbyopia and low vision through optical or electronic magnification, typically employing convex lenses with dioptric powers ranging from +1.00 to +4.00 or digital cameras with liquid-crystal displays for variable electronic enlargement. These devices serve presbyopic individuals, occupational users, and pathological low-vision patients requiring magnification for reading, inspection, or daily tasks. Progressive lenses capture the largest share of prescription value as aging demographics expand the addressable patient pool, while online retail represents the fastest-growing distribution channel as direct-to-consumer lens retailers bypass traditional optical store intermediaries. Magnifying glasses remain a mature, price-competitive segment with thinner margin pools concentrated in private-label pharmacy and supermarket channels.
The FDA regulates electronic near vision aids as Class I or Class II medical devices under 510(k) premarket notification requirements, while the EU Medical Device Regulation mandates CE marking and clinical evaluation for magnifiers sold in Europe. Japan's PMDA and METI enforce JIS standards for optical quality and electromagnetic compatibility, shaping export compliance burdens for multinational suppliers. Stakeholders must monitor evolving digital health classification criteria as software-enabled magnification apps blur regulatory boundaries between consumer electronics and regulated medical devices.
Market Dynamics
The presbyopia correction market is reconfiguring around digital health convergence as smartphone-based magnification applications challenge standalone electronic magnifiers for daily-use scenarios among aging populations.
Growth Catalysts
- Japan's Silver Demographics:METI's active aging policies expand reimbursement pathways for low-vision aids among citizens over 65, sustaining prescription volumes for progressive lens formats.
- EU Medical Device Regulation harmonization:CE marking standardization under MDR Article 52 streamlines cross-border distribution for German and French optical manufacturers serving pan-European pharmacy networks.
- Head-mounted display miniaturization:Micro-OLED panel cost curves from Korean and Taiwanese suppliers enable wearable magnification form factors previously constrained by bulk and battery life.
Market Restraints
- Optical-grade polymer feedstock volatility:Crude-linked pricing for polycarbonate and high-index monomers squeezes margin pools for injection-molded lens producers in Italy and China.
- Single-source dependency in precision grinding:Bavarian and Swiss CNC optical equipment suppliers control 80% of automated lens surfacing installations, creating concentration risk for mid-tier device assemblers.
- Smartphone substitution threshold:Native iOS and Android accessibility suites now deliver 8-15x digital zoom with text recognition, capturing incidental-use cases from dedicated electronic magnifier purchases.
Strategic Opportunities
- India's underpenetrated presbyopia correction:CDSCO streamlined medical device rules and rising disposable incomes in Maharashtra and Karnataka create whitespace for organized optical retail chains.
- Occupational precision inspection convergence:Near vision devices hybridizing with augmented reality overlays serve electronics manufacturing quality control in Shenzhen and Ho Chi Minh City assembly plants.
- Direct-to-consumer lens retail expansion:Online refraction platforms bypassing traditional optician intermediaries capture margin previously allocated to brick-and-mortar fitting fees in UK and Australian markets.
Industry Challenges
- Software-hardware regulatory boundary ambiguity:FDA 510(k) classification criteria for AI-enabled magnification apps remain unresolved, delaying product roadmaps for developers blending camera software with prescription optics.
- Specialized optometrist training gaps:Low-vision rehabilitation certification programs concentrate in university medical centers, creating service accessibility deserts for rural Medicare beneficiaries in US Midwest and Mountain states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Near Vision Devices Market |
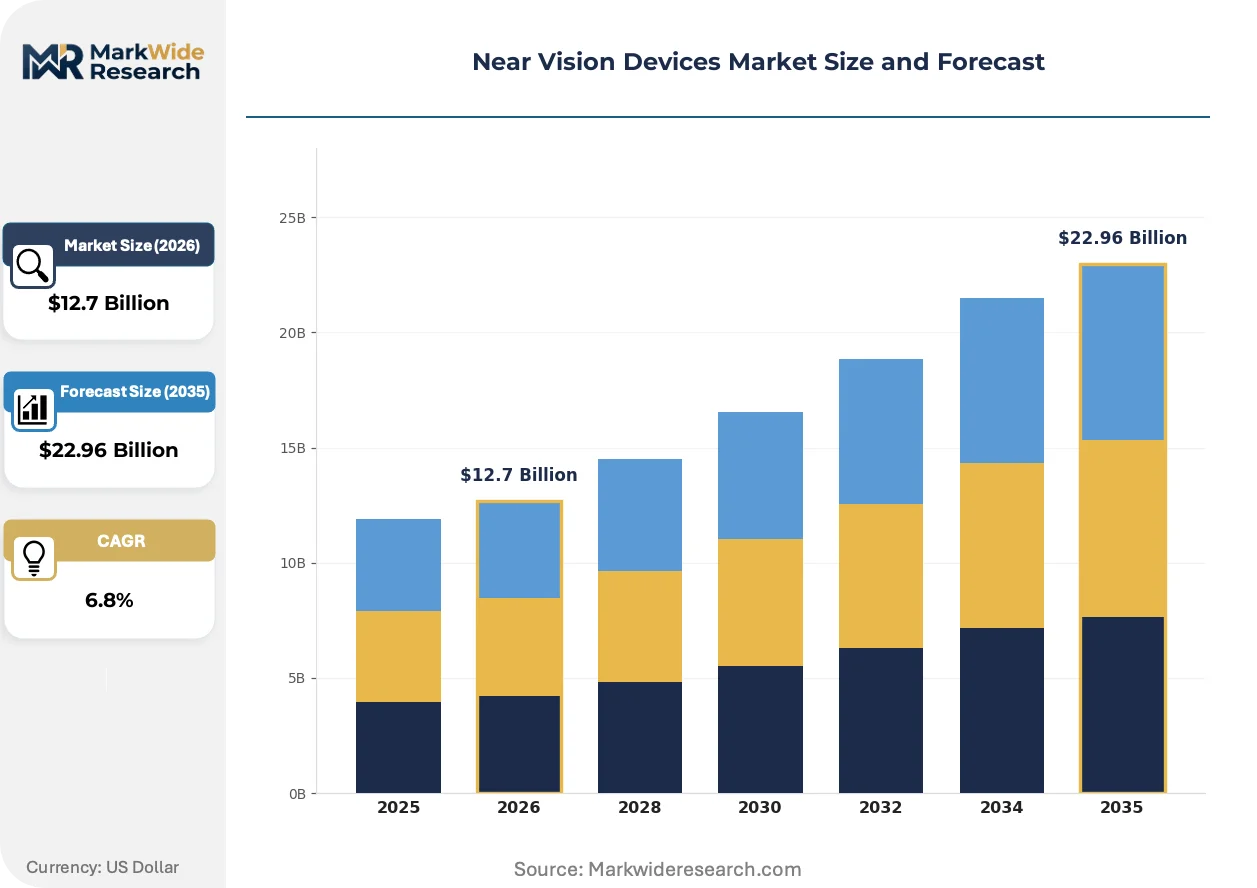
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Bifocal Lenses, Progressive Lenses, Reading Glasses, Magnifying Glasses Distribution Channel: Online Retail, Optical Stores, Pharmacies, Supermarkets End User: Individuals, Healthcare Professionals, Educational Institutions, Senior Citizens Material: Plastic, Glass, Polycarbonate, High-Index Lens |
| Companies Covered | Eschenbach Optik GmbH, HumanWare, Vispero, Optelec International, Enhanced Vision, eSight Corp., IrisVision Global, OrCam, Envision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Near Vision Devices Market Shifts & Advancements
Digital optics is fragmenting the traditional device taxonomy as computational photography, wearable displays, and AI-powered text recognition converge into multifunctional vision assistance platforms.
Wavefront-guided freeform lens surfacing is hybridizing progressive lens manufacturing by replacing traditional semi-finished blank grinding with point-by-point power optimization across the entire surface. German and Japanese optical laboratories are adopting these five-axis generators to reduce peripheral aberration complaints among presbyopic wearers. The technology is compressing remake rates and warranty claims while extending the viable power range for single-piece progressive designs.
Europe's Medical Device Regulation (MDR) clinical evaluation requirements for Class IIA electronic magnifiers are forcing manufacturers to generate post-market surveillance data previously exempt under the Medical Device Directive. French and Dutch notified bodies are interpreting Article 61 strictly for software-enabled devices with diagnostic claims. The compliance burden is favoring established players with regulatory affairs infrastructure over venture-backed entrants.
Subscription-based lens replacement programs are displacing transactional frame-and-lens purchases among urban professional cohorts in US coastal metros and London. Eye care chains bundle annual comprehensive exams with unlimited lens exchanges as myopia progression and presbyopia advancement alter prescriptions. The model concentrates patient lifetime value with vertically integrated retailers while compressing independent optician foot traffic.
Near Vision Devices Market Segmentation
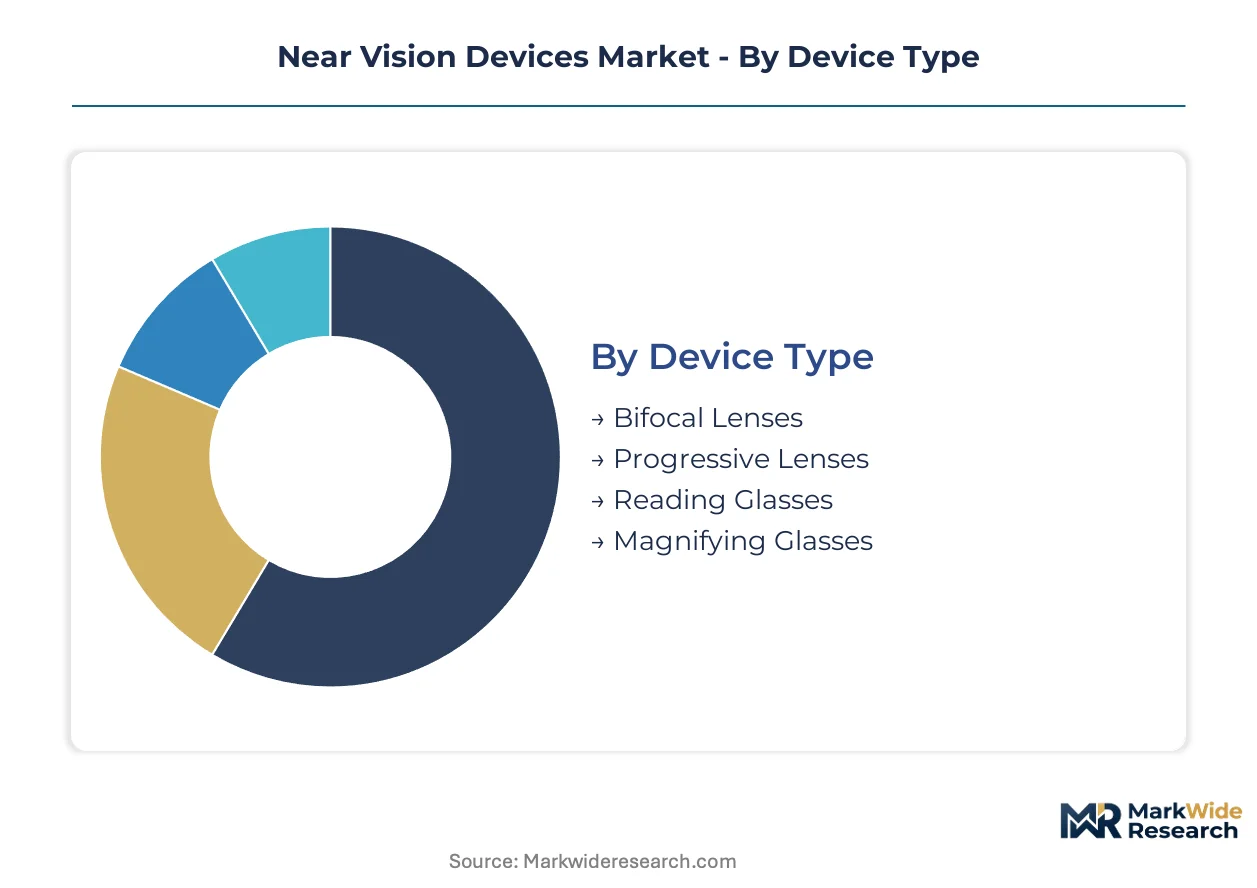
Near vision devices serve distinct user workflows spanning daily reading, clinical diagnostics, and occupational precision tasks. Segmentation reveals how optical laboratories, retailers, and end-users prioritize magnification format, purchase channel, and lens material based on prescription complexity and budget elasticity.
Device Type:
Presbyopia correction spans a use-case spectrum from seamless all-distance vision to task-specific magnification for intermittent near-work.
- Progressive Lenses:Continuous power gradients from distance through intermediate to near zones eliminate visible segment lines. German and Japanese optical laboratories deploy freeform surfacing to reduce peripheral aberration complaints among aging presbyopes requiring full-time wear.
- Reading Glasses:Single-vision convex lenses in standardized dioptric powers (+1.00 to +3.50) address intermittent near-work. Pharmacy and supermarket channels in US Midwest and Southeastern states move high volumes of private-label stock at price points below progressive entry levels.
- Bifocal Lenses:Discrete distance and near segments with visible dividing lines serve cost-conscious presbyopes and certain occupational safety applications requiring clear zone demarcation.
- Magnifying Glasses:Handheld or stand-mounted optical systems with aspheric lenses provide magnification for low-vision users and precision inspection tasks in electronics assembly.
The dominant share belongs to Progressive Lenses, while Reading Glasses is closing the gap fastest through direct-to-consumer online channels bypassing professional fitting fees.
Distribution Channel:
Channel selection tracks customer acquisition cost, prescription complexity, and the need for professional fitting services.
- Online Retail:Direct-to-consumer platforms capture margin pools previously allocated to brick-and-mortar intermediaries. UK and Australian markets show particular traction for lens replacement programs bundling home trial kits with remote refraction support.
- Optical Stores:Full-service opticians dominate progressive lens dispensing through comprehensive eye exams, pupillary distance measurement, and frame adjustment. Independent practices in Bavaria and Lombardy retain loyalty through personalized fitting for complex prescriptions.
- Pharmacies:Over-the-counter reading glasses and basic magnifiers serve immediate-need purchasers. Boots and Walgreens locations stock standardized dioptric powers for presbyopes delaying professional eye exams.
- Supermarkets:Private-label magnifiers and entry-level reading glasses target price-sensitive consumers in mass-market retail environments.
Optical Stores command the largest transaction values, though Online Retail is expanding most quickly as smartphone-based pupillary distance measurement reduces fitting barriers.
End User:
User categories reflect severity of vision impairment, frequency of magnification need, and institutional procurement patterns.
- Senior Citizens:Aging populations across OECD markets drive sustained prescription volume for presbyopia correction and low-vision aids. Japan's METI reimbursement pathways for citizens over 65 sustain progressive lens demand.
- Individuals:Working-age presbyopes and hobbyists purchase reading glasses and electronic magnifiers for discretionary near-work. Occupational users in precision manufacturing require task-specific magnification.
- Healthcare Professionals:Optometrists and ophthalmologists prescribe and dispense therapeutic magnification for pathological low-vision patients. Low-vision rehabilitation certification programs concentrate in university medical centers.
- Educational Institutions:Schools and universities procure electronic video magnifiers and CCTV systems for students with visual impairments.
Senior Citizens generate the highest prescription frequency, while Healthcare Professionals anchor the steepest expansion trajectory as low-vision rehabilitation services expand reimbursement coverage.
Material:
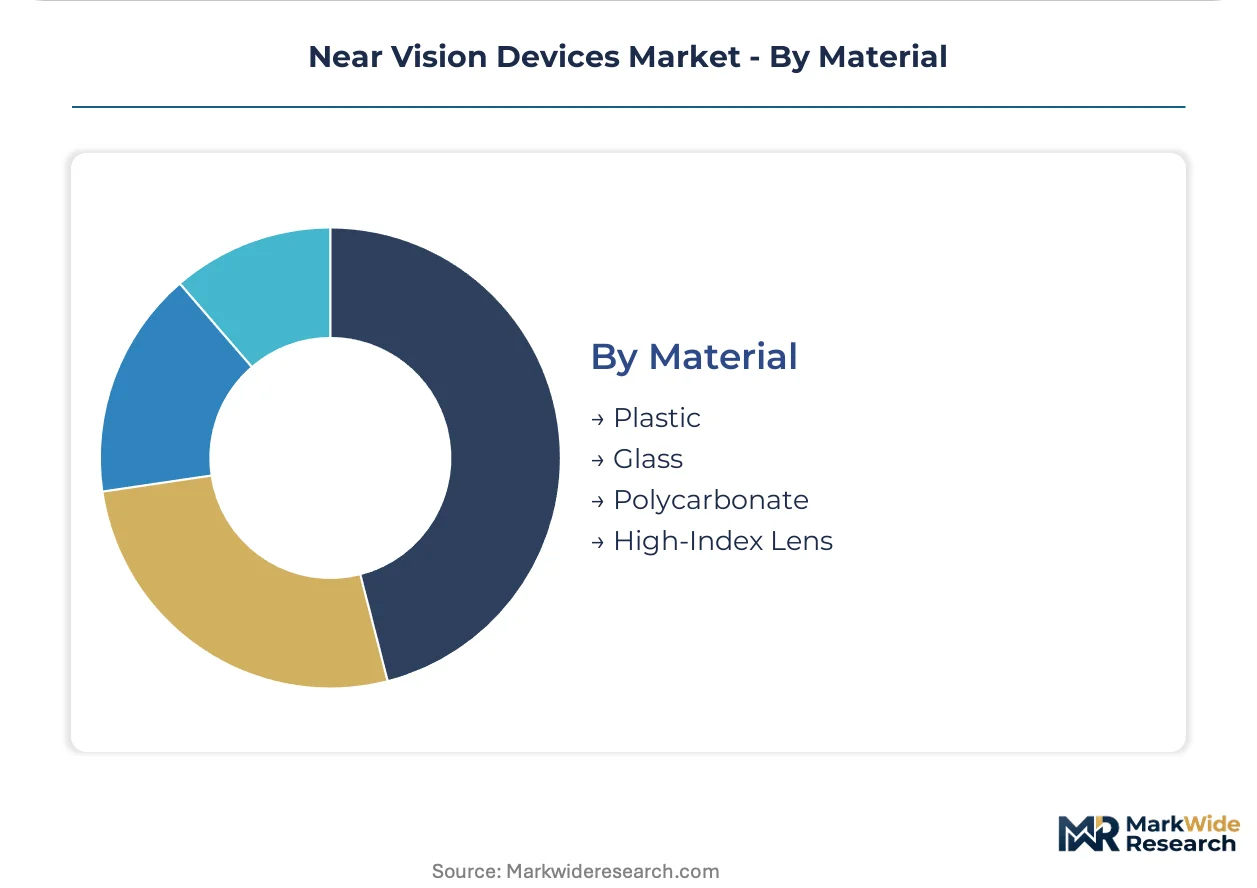
Lens material selection trades optical clarity, impact resistance, weight, and refractive index against cost and manufacturing complexity.
- Polycarbonate:Impact-resistant thermoplastic with inherent UV protection dominates safety eyewear and pediatric applications. Injection molding enables high-volume production for standardized reading glasses.
- High-Index Lens:Dense optical polymers (1.60 to 1.74 refractive index) reduce edge thickness for strong prescriptions. Freeform generators in German laboratories machine these materials for slim progressive profiles.
- Plastic:Standard CR-39 resin offers optical quality at moderate cost for routine prescriptions with moderate dioptric powers.
- Glass:Superior scratch resistance and optical clarity persist in specialized applications despite weight penalties and brittleness concerns.
Polycarbonate holds the volume lead for mass-market production, though High-Index Lens is gaining share fastest as freeform surfacing technology reduces premium pricing differentials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optics manufacturing clusters in southern Germany and the Kansai region supply lens surfacing equipment and freeform generators to optical laboratories worldwide. Japanese and German regulators shape compliance frameworks that govern product entry timelines for electronic magnifiers and progressive lenses.
United States
Medicare reimbursement for low-vision rehabilitation services drives prescription volume for electronic video magnifiers among beneficiaries over 65. FDA 510(k) premarket notification requirements for Class II medical devices create structured entry pathways for wearable magnification technologies. Low-vision rehabilitation certification programs concentrate in university medical centers across the Midwest and Mountain states, creating service accessibility gaps in rural counties.
Germany
Bavarian optical laboratories deploy five-axis freeform generators to reduce peripheral aberration complaints among presbyopic wearers requiring progressive lenses. EU Medical Device Regulation Article 52 harmonizes CE marking standards for electronic magnifiers distributed through pan-European pharmacy networks. Eschenbach Optik leverages its Bavarian production base to dominate European distribution of magnifying glasses and low-vision aids.
Japan
METI active aging policies expand reimbursement pathways for low-vision aids among citizens over 65, sustaining demand for progressive lens formats. PMDA and METI enforce JIS standards for optical quality and electromagnetic compatibility, shaping export compliance burdens for multinational suppliers. Kansai-region optical manufacturers supply precision grinding equipment to domestic laboratories serving the silver demographic.
India
Rising disposable incomes in Maharashtra and Karnataka create whitespace for organized optical retail chains addressing underpenetrated presbyopia correction. CDSCO streamlined medical device rules reduce registration timelines for imported electronic magnifiers and progressive lens blanks. Mumbai and Bangalore host emerging distribution hubs for direct-to-consumer lens platforms bypassing traditional optician intermediaries.
United Kingdom
Online refraction platforms capture margin pools previously allocated to brick-and-mortar fitting fees in London and southeastern population centers. MHRA alignment with EU MDR requirements maintains CE marking recognition for German and French optical manufacturers post-Brexit. Boots pharmacy locations stock standardized dioptric power reading glasses for presbyopes delaying comprehensive eye examinations.
Near Vision Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying optical-grade polymers and precision grinding equipment. The vendor base spans multinational optics conglomerates, specialized low-vision aid manufacturers, and venture-backed wearable technology developers. Three archetypes dominate: precision optics fabricators with captive laboratory networks, electronic magnification platform developers, and direct-to-consumer lens retailers with vertically integrated supply chains. Competitive moves concentrate on M&A to acquire freeform surfacing capabilities and strategic partnerships to embed AI-powered text recognition into hardware form factors.
Among German precision optics specialists, Eschenbach Optik GmbH occupies a position exemplifying the heritage laboratory archetype with Bavarian manufacturing roots. Vispero and OrCam represent contrasting platform strategies—the former anchoring electronic video magnifier development, the latter exemplifying wearable text-to-speech convergence for visually impaired users. These three entities illustrate how regulatory affairs infrastructure and R&D intensity separate established players from venture-backed entrants facing EU MDR clinical evaluation burdens.
| Leading Market Players |
|---|
| Eschenbach Optik GmbH |
| HumanWare |
| Vispero |
| Optelec International |
| Enhanced Vision |
| eSight Corp. |
| IrisVision Global |
| OrCam |
| Envision |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp optical feedstock corridor carries polycarbonate and high-index monomer shipments from BASF Ludwigshafen to Italian lens molders, with freight cost volatility feeding directly into margin compression for mid-tier progressive lens assemblers and widening the price spread between captive-production German laboratories and import-dependent Southern European distributors.
Pricing Analysis
EU MDR Article 52 dictates the pricing tier structure for electronic magnifiers entering European distribution. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked clinical devices from consumer-grade imports and pharmacy private-label stock. Price differentiation hinges on certification grade and optical laboratory brand equity. Pricing pressure stems from smartphone accessibility suites capturing incidental-use magnification demand. Pharmacy channel buyers exhibit highest price sensitivity; hospital procurement committees demonstrate lowest elasticity for therapeutic low-vision aids.
Supply Chain Analysis
Dual-use optical grinding equipment export controls from German and Swiss authorities restrict five-axis freeform generator shipments to certain jurisdictions, constraining laboratory capacity expansion in emerging markets. Manufacturing concentrates in Germany, Japan, and Italy for precision surfacing equipment and lens blanks. Raw material flows draw from Saudi petrochemical feedstocks for polycarbonate resin and Korean micro-OLED panels for electronic magnifier displays. Single-source vulnerability sits with Bavarian CNC equipment suppliers controlling automated lens processing installations. Distribution runs through pan-European pharmacy networks and direct-to-consumer online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near vision devices are crossing into platform economics as AI-powered text recognition and wearable display convergence transforms standalone magnifiers into software-enabled vision assistance ecosystems, with interoperability between prescription optics and smartphone accessibility suites rewriting vendor competitive boundaries.
For Market Incumbents: Pre-empt smartphone substitution by embedding computational photography directly into progressive lens workflows through partnerships with AR headset developers. Consolidate freeform surfacing capacity in Bavaria and Kansai region clusters to defend margin position against Chinese lens blank imports. Priority lever: regulatory affairs infrastructure for EU MDR clinical evaluation compliance.
For New Entrants and Emerging Players: India's Maharashtra and Karnataka metropolitan corridors represent the most penetrable entry point for organized optical retail chains addressing underpenetrated presbyopia correction among rising middle-class demographics. Occupational precision inspection in Vietnamese and Mexican electronics assembly plants offers second white-space target for hybrid AR-magnification devices. Go-to-market angle: direct-to-consumer online refraction platforms with smartphone-based pupillary distance measurement.
For Investors and Strategic Acquirers: Specialized low-vision rehabilitation service networks with captive dispensing relationships anchor the highest acquisition value over extended holding periods. Long-term viability rests on reimbursement pathway expansion for therapeutic magnification rather than discretionary reading aids. Signal to watch: FDA 510(k) clearance velocity for AI-enabled magnification apps as inflection indicator for software-hardware boundary resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Freeform Surfacing Technology Acquisition | German laboratories deploy five-axis generators to reduce peripheral aberration complaints among aging presbyopes. |
| CE Marking Pathway Investment | EU MDR Article 52 compliance separates established players from venture-backed entrants facing clinical evaluation burdens. |
| Direct-to-Consumer Platform Launch | UK and Australian online refraction platforms capture margin pools previously allocated to brick-and-mortar fitting fees. |
| Low-Vision Rehabilitation Partnership | Hospital system alliances in US Midwest and Mountain states address service accessibility gaps for rural Medicare beneficiaries. |
| Micro-OLED Supply Agreement | Korean and Taiwanese panel suppliers enable wearable magnification form factors previously constrained by bulk and battery life. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body guidance documents, and METI reimbursement policy circulars. Interviews with optical laboratory operations directors, low-vision rehabilitation optometrists, GPO contracts managers, and pharmacy category buyers inform demand-side segmentation. Secondary validation draws from PMDA device registrations, CDSCO import notifications, and customs trade data for optical-grade polymer flows. Bottom-up prescription volume modeling triangulates against top-down addressable population estimates for presbyopia correction.
Forecast inputs incorporate device type segmentation across progressive lenses, electronic magnifiers, and reading glasses; distribution channel dynamics spanning optical stores, online retail, and pharmacy networks; and material tier differentiation between polycarbonate, high-index, and standard resin formulations. CAGRs derive from fitted trend analysis across demographic aging curves and reimbursement policy trajectories. Industry-specific inputs include METI active aging policy implementation pace and FDA digital health classification criteria evolution for software-enabled magnification.
Practitioners should monitor regulatory reclassification of smartphone accessibility suites as medical devices, EU MDR notified body capacity constraints, and polycarbonate feedstock pricing volatility for early signals of forecast deviation. Material shifts in FDA 510(k) pathway requirements for AI-enabled optics or EU MDR clinical evaluation stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Electronic Pediatric Nebulizer Market
Medical Devices
Creatinine Meter Market
Medical Devices
Global Gynecology Robotic Surgery Market
Medical Devices
Snare Devices Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Global Monopolar Electrosurgery Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Subcutaneous Injection Ports Market
Medical Devices
IoT Medical Devices Market
Medical Devices
Sleep Apnea Implants Market
Medical Devices
Vaginal Applicators Market
Medical Devices
Epilepsy Treatment Devices Market