
 Cordyceps Militaris Extract Market | 2026-2036
Cordyceps Militaris Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Cordyceps Militaris Extract Market Insights
Direct-to-consumer wellness platforms is collapsing as a buyer archetype while institutional functional food manufacturers gain procurement share. Xi'an Saina Biological Technology Co. Ltd. anchors its position through captive cultivation facilities in Shaanxi province, ensuring batch-to-batch cordycepin consistency. Nutra Green Biotechnology Co. Ltd. differentiates via organic certification chains that command premium positioning in European specialty retail. NU SKIN ENTERPRISES INC. controls a vertically integrated channel model spanning extraction through branded finished goods.
Cordyceps militaris extract comprises bioactive metabolites—principally cordycepin, adenosine, and polysaccharides—obtained through solid-state fermentation of the fungal mycelium or fruiting body, typically standardized to 0.3-1.0% cordycepin content for commercial applications. The extract serves primarily as an adaptogenic ingredient in formulations targeting energy metabolism, immune modulation, and exercise recovery. Powder and capsule product types occupy the deepest margin pools due to manufacturing scalability and shelf stability, while liquid formats remain nascent outside East Asian markets. Dietary supplements dominate application volume, though functional foods represent the fastest-growing insertion point as beverage and snack brands seek differentiated botanical positioning.
China's NMPA and SAMR govern extract quality through GB standards for health food raw materials, while the FDA regulates U.S. market entry under DSHEA with mandatory GMP compliance for dietary supplement manufacturers. The EU's EFSA novel food assessment pathway creates entry friction for non-traditional extract suppliers lacking substantial consumption history. Stakeholders must monitor evolving pharmacopeial monograph harmonization between Chinese, European, and U.S. compendia, as divergent purity specifications threaten to fragment quality benchmarks and complicate multi-region sourcing strategies.
Market Dynamics
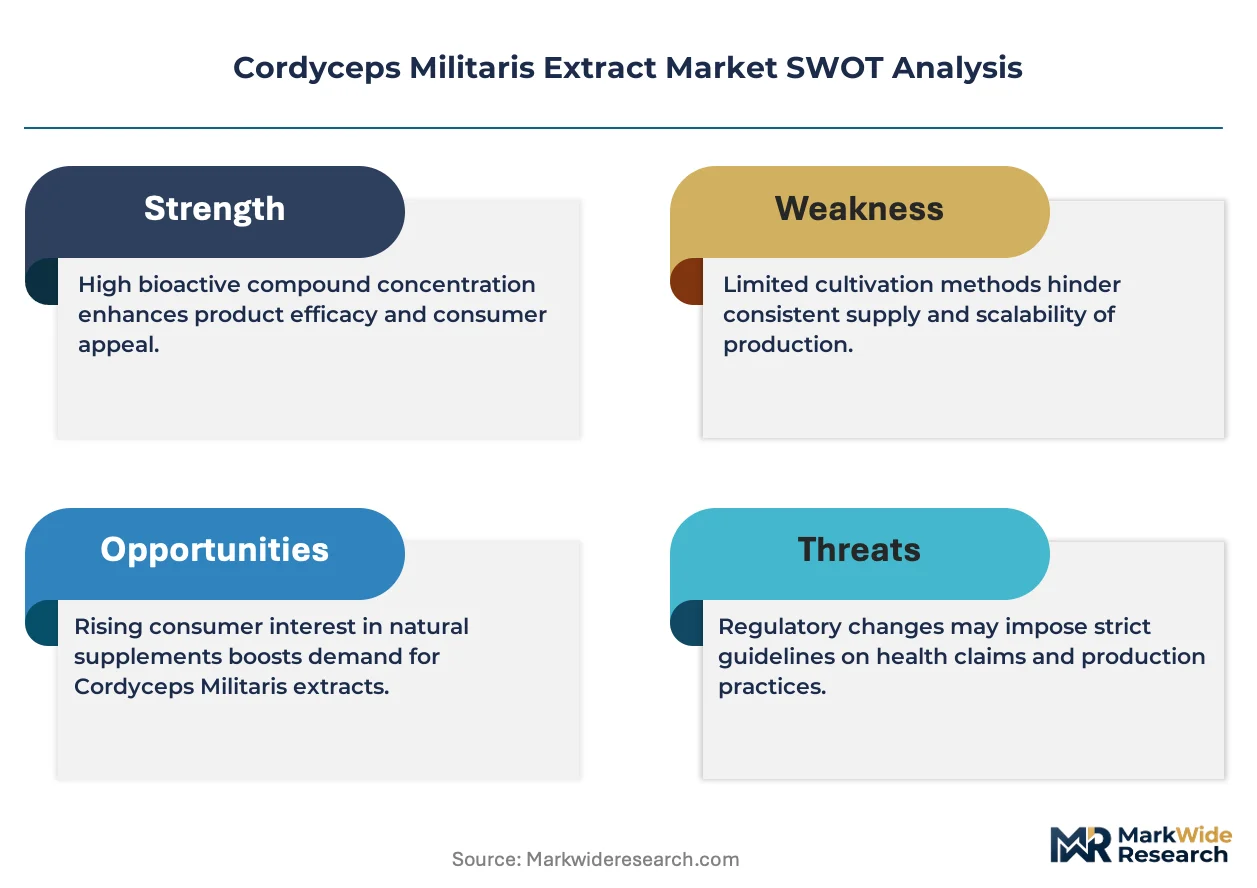
Clean-label formulation mandates from North American and European retailers are compressing batch-to-batch variability tolerances, forcing extract suppliers to upgrade from artisanal cultivation to controlled-environment agriculture with full chain-of-custody documentation.
Growth Catalysts
- DSHEA-aligned GMP enforcement:FDA facility inspections are accelerating consolidation among U.S. contract manufacturers, concentrating volume with extractors capable of certificate-of-analysis standardization.
- Solid-state fermentation optimization:Bioreactor-based mycelium production is displacing wild-harvest dependency, yielding cordycepin titers above 1.2% with 40% shorter cultivation cycles.
- Sports nutrition verticals:Pre-workout and recovery formulations from U.S. direct-to-consumer brands are absorbing extract volumes previously directed toward traditional TCM channels.
Market Restraints
- Substrate cost volatility:Organic brown rice and silkworm pupae prices fluctuate with agricultural commodity indices, compressing margin stability for non-vertically integrated processors.
- Shaanxi supplier concentration:Over 60% of standardized extract output originates from captive cultivation facilities in a single Chinese province, creating geographic risk exposure.
- EFSA novel food friction:European entrants lacking 25-year consumption history face 18-24 month safety assessment timelines that freeze market access.
Strategic Opportunities
- Functional beverage insertion:Adaptogenic sparkling water and ready-to-drink coffee brands in the United States are piloting heat-stable extract variants for Q3 2026 line extensions.
- India PLI scheme alignment:Botanical ingredient manufacturing incentives under the Production Linked Incentive framework attract contract cultivation investment in Himachal Pradesh and Uttarakhand.
- CSRD disclosure requirements:European corporate sustainability reporting mandates are elevating certified organic and fair-trade extract premiums in B2B procurement specifications.
Industry Challenges
- Pharmacopeial harmonization gaps:Divergent cordycepin quantification methods between USP, EP, and ChP compendia force dual testing protocols for multi-region suppliers.
- Cordycepin stability engineering:Powder format shelf-life extension beyond 24 months requires microencapsulation capex that mid-tier extractors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cordyceps Militaris Extract Market |
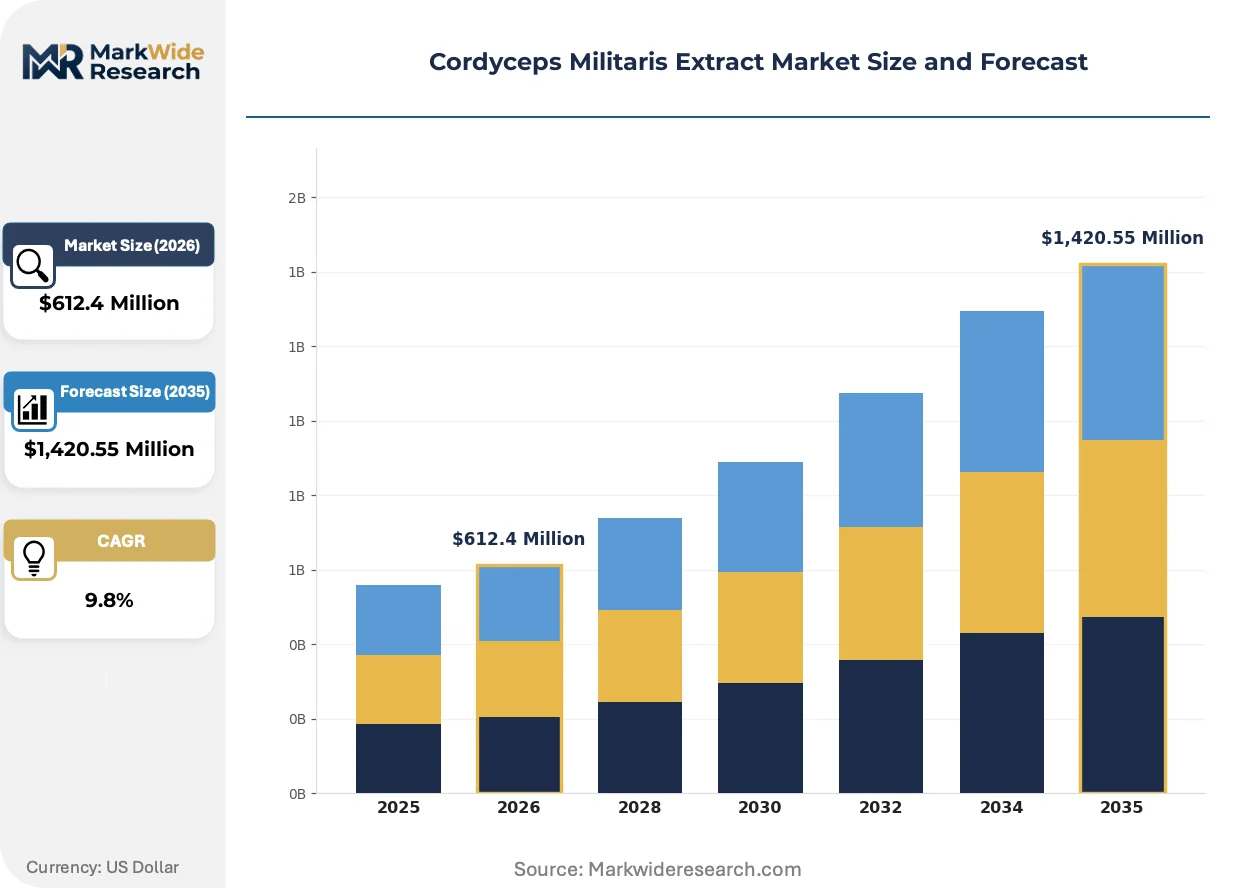
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,420.55 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Extract, Powder, Capsule, Liquid Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Cosmetics End User: Health Enthusiasts, Athletes, Patients, Beauty Consumers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Quyuan sunnycare Inc., Xi'an Saina Biological Technology Co. Ltd., The Lubrizol Corporation, Health Choice Limited, Dalong Biotechnology Co. Ltd., Naturalin bio-resources co. Ltd., Shanghai Kangzhou Fungi Extract Co. Ltd., Nutra Green Biotechnology Co. Ltd, NU SKIN ENTERPRISES INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordyceps Militaris Extract Market Trends and Innovations
Bioprocess engineering and regulatory disclosure mandates are converging to reshape competitive positioning around traceability infrastructure rather than extraction yield alone.
Submerged liquid fermentation is fragmenting the traditional solid-state dominance in extract production. Bioreactor operators achieve 30% higher cordycepin volumetric productivity with automated pH and dissolved oxygen control. North American ingredient distributors are qualifying these outputs for premium positioning, compressing price premiums previously commanded by fruiting-body-only suppliers.
China's SAMR revised health food raw material catalog is accelerating registration pathway clarity for domestic extract suppliers. The streamlined GB standards alignment reduces technical documentation burdens for NMPA filings. U.S. importers are responding by diversifying supplier qualification toward dual-registered entities capable of simultaneous China and FDA compliance.
Direct sourcing contracts between cultivators and finished goods brands are displacing spot-market procurement through trading companies. Wellness platform buyers now mandate batch-level DNA authentication and heavy metals testing protocols. This pattern is most visible in California and New York state markets where consumer litigation exposure drives specification stringency.
Cordyceps Militaris Extract Market Segmentation
Segmentation in the Cordyceps militaris extract market determines compliance pathways, margin structures, and procurement specifications. Product format and application channel dictate which regulatory frameworks apply, while end-user archetype shapes formulation requirements and marketing claims permissibility.
Product Type:
Regulatory differentiation across product formats centers on stability testing requirements and shelf-life validation protocols mandated by FDA, EFSA, and NMPA authorities.
- Organic Extract:Certified organic extracts command premium positioning in European specialty retail and North American clean-label channels. EFSA organic certification and USDA NOP compliance create dual-registration barriers that filter out non-vertically integrated suppliers. Demand concentrates in Germany and California markets where consumer litigation exposure drives specification stringency.
- Powder:Powder formats occupy the deepest margin pools due to manufacturing scalability and 24-month shelf stability under controlled humidity conditions. Sports nutrition brands in the United States absorb volumes previously directed toward traditional TCM channels, with direct-to-consumer wellness platforms mandating batch-level heavy metals testing.
- Capsule:Hard-shell and soft-gel encapsulation requires excipient compatibility testing for cordycepin bioavailability retention.
- Liquid:Liquid formats remain nascent outside East Asian markets due to preservation challenges and shorter stability windows.
Established volume favors Powder; emerging adoption favors Organic Extract.
Application:
Application channel determines pharmacopeial compliance tier and permissible health claim language under DSHEA, EFSA novel food pathways, and China's health food raw material catalog.
- Dietary Supplements:Dietary supplements dominate current volume through capsule and powder SKUs targeting energy metabolism and immune modulation. FDA GMP enforcement and certificate-of-analysis standardization requirements are accelerating consolidation among U.S. contract manufacturers, concentrating procurement with extractors capable of dual USP-ChP testing protocols.
- Functional Foods:Functional foods represent the steepest expansion trajectory as beverage and snack brands seek differentiated botanical positioning. Adaptogenic sparkling water and ready-to-drink coffee brands in the United States are piloting heat-stable extract variants, though EFSA novel food friction creates 18-24 month entry delays for non-traditional suppliers.
- Pharmaceuticals:Pharmaceutical-grade extracts require NMPA drug master file submission and clinical evidence packages for cordycepin standardization claims.
- Cosmetics:Cosmetic applications leverage polysaccharide fractions for topical formulation, operating under separate INCI nomenclature and safety assessment pathways.
Regulatory clarity favors Dietary Supplements; formulation innovation favors Functional Foods.
End User:
End-user archetype segmentation tracks procurement authority migration from individual consumers toward institutional formulation buyers with mandated testing protocols.
- Health Enthusiasts:Health enthusiasts drive volume through subscription-based direct-to-consumer platforms with DNA authentication requirements.
- Athletes:Athletes absorb expanding extract volumes through pre-workout and recovery formulations from U.S. sports nutrition brands, with NSF Certified for Sport and Informed Sport third-party testing becoming baseline procurement filters for collegiate and professional program inclusion.
- Patients:Patient-directed use concentrates in TCM-integrated oncology supportive care protocols under practitioner supervision.
- Beauty Consumers:Beauty consumers respond to ingestible skincare positioning with collagen synthesis and antioxidant claims in Asian markets.
Volume concentration favors Health Enthusiasts; specification stringency favors Athletes.
Distribution Channel:
Channel configuration determines traceability documentation depth and margin capture allocation between extractors and finished goods brands.
- Online Retail:Online retail platforms mandate batch-level chain-of-custody documentation and heavy metals testing protocols, with California and New York state markets driving specification stringency through consumer litigation exposure. Direct sourcing contracts between cultivators and wellness platform buyers are displacing spot-market procurement through trading companies.
- Specialty Stores:Specialty stores in European markets command organic certification premiums under CSRD disclosure requirements, with certified fair-trade extracts gaining procurement preference in B2B specifications.
- Supermarkets:Supermarket placement requires mass-market pricing alignment and conventional shelf-stable formats.
- Pharmacies:Pharmacy distribution operates under distinct national regulatory frameworks with pharmacist consultation requirements in Germany and France.
Margin retention favors Online Retail; certification premiums favor Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao port cluster underwrites China's export dominance in Cordyceps militaris extract, processing over 60% of standardized output bound for North American and European dietary supplement manufacturers.
United States
Sports nutrition brands in California and New York Metro absorb expanding extract volumes for pre-workout formulations. FDA DSHEA enforcement and GMP facility inspections accelerate consolidation among contract manufacturers. Los Angeles and San Diego house the deepest concentration of direct-to-consumer wellness platforms mandating batch-level heavy metals testing.
China
Domestic health food manufacturers drive procurement acceleration following NMPA's streamlined botanical ingredient approvals. Shaanxi province anchors captive cultivation infrastructure ensuring cordycepin consistency across extraction batches. Xi'an and surrounding prefectures concentrate over 60% of global standardized extract output through vertically integrated fermentation facilities.
Germany
Specialty retail channels in Bavaria and North Rhine-Westphalia command certified organic extract premiums under CSRD disclosure requirements. EFSA novel food assessment pathways create entry friction for non-traditional suppliers lacking substantial consumption history. Cologne and Düsseldorf host formulation houses qualifying heat-stable variants for functional beverage insertion.
India
Botanical ingredient manufacturing incentives under the PLI scheme attract contract cultivation investment in Himachal Pradesh and Uttarakhand. FSSAI regulatory alignment with international pharmacopeial standards reduces technical documentation burdens for extract exporters. Dehradun and Shimla emerge as mycelium production clusters targeting European organic certification chains.
Japan
Traditional medicine-integrated wellness protocols sustain demand for fruiting-body extracts in Kansai and Kanto regions. PMDA consultation pathways guide suppliers through pharmaceutical-grade standardization claims. Osaka and Kyoto maintain deep TCM practitioner networks prescribing cordycepin formulations for oncology supportive care.
Cordyceps Militaris Extract Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and geographic coverage. The vendor base stratifies between scale-driven fermentation operators and boutique organic cultivators serving European specialty retail. Three archetypes dominate: vertically integrated Chinese extractors with captive cultivation, North American brand-houses controlling distribution through finished goods, and certified-organic specialists commanding premium positioning in CSRD-aligned procurement. Consolidation accelerates through M&A targeting traceability infrastructure, while capacity expansion concentrates in Shaanxi and emerging Indian hill states.
Within the Chinese extractor tier, Xi'an Saina Biological Technology Co. Ltd. and Shanghai Kangzhou Fungi Extract Co. Ltd. occupy positions anchored by provincial cultivation infrastructure. Nutra Green Biotechnology Co. Ltd. exemplifies the certified-organic archetype targeting European disclosure-mandated procurement. NU SKIN ENTERPRISES INC. represents the integrated brand-house model spanning extraction through direct-to-consumer channels.
| Leading Market Players |
|---|
| Quyuan sunnycare Inc. |
| Xi'an Saina Biological Technology Co. Ltd. |
| The Lubrizol Corporation |
| Health Choice Limited |
| Dalong Biotechnology Co. Ltd. |
| Naturalin bio-resources co. Ltd. |
| Shanghai Kangzhou Fungi Extract Co. Ltd. |
| Nutra Green Biotechnology Co. Ltd |
| NU SKIN ENTERPRISES INC. |
| Others |
Pricing and Supply Chain Analysis
Solid-state fermentation displacement of wild-harvest extraction is compressing cost structures while concentrating production authority in Shaanxi province facilities, simultaneously flattening regional price differentials and amplifying volume-discount leverage for procurement-scale buyers.
Pricing Analysis
Volume-discount tiering separates organic-certified extracts from conventional powder grades from commodity liquid formats, with EFSA organic certification and NSF Sport certification commanding measurable premiums over baseline USP-grade material. Price differentiation hinges on cordycepin standardization thresholds and dual USP-ChP testing compliance, with mid-tier extractors facing margin compression from bioreactor-based competitors achieving shorter cultivation cycles. Pricing pressure stems from sports nutrition brands consolidating procurement with fewer qualified suppliers capable of batch-level heavy metals documentation. Direct-to-consumer wellness platforms exhibit lowest price sensitivity due to subscription model economics, while conventional dietary supplement contract manufacturers remain most cost-conscious.
Supply Chain Analysis
Inventory lead-times stretch 8-14 weeks for organic-certified extracts due to dual-registration documentation requirements, while standard powder formats move through 4-6 week cycles. Geographic supply concentration centers on China, India, and Japan, with Shaanxi province captive cultivation facilities anchoring over sixty percent of standardized output. Raw material dependencies rest on organic brown rice substrate, silkworm pupae protein sources, and pharmaceutical-grade ethanol for extraction. Single-province concentration in China creates geographic risk exposure to provincial environmental enforcement actions or logistics disruptions. Distribution runs through Qingdao port cluster consolidation for North American bound shipments, with European channels increasingly qualifying Indian Himachal Pradesh and Uttarakhand alternatives under PLI scheme incentives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent extractors face substitution pressure from submerged liquid fermentation operators achieving superior cordycepin volumetric productivity, requiring defensive positioning around traceability infrastructure rather than yield alone.
For Market Incumbents: Secure captive cultivation capacity in Shaanxi or emerging Indian hill states to defend against bioreactor-based entrants; invest in dual NMPA-FDA registration infrastructure to capture procurement consolidation among U.S. contract manufacturers facing accelerated FDA GMP enforcement. Backward integration into substrate production buffers organic brown rice price volatility while creating certification documentation depth that spot-market competitors cannot replicate. For New Entrants and Emerging Players: USDA NOP organic certification fast-track offers entry into California and Germany specialty retail channels where CSRD disclosure requirements elevate certified extract premiums. White-space exists in heat-stable liquid formulations for functional beverage insertion, with adaptogenic sparkling water brands piloting Q3 line extensions. Target Himachal Pradesh contract cultivation under India's PLI scheme to bypass Shaanxi supplier concentration and qualify for European organic certification chains. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors traceability-integrated mid-cap specialists with dual-registration capabilities and captive fermentation infrastructure. Long-term viability across the projection horizon favors operators controlling cultivation-through-extraction documentation chains rather than trading-company intermediaries. Acquisition screening should prioritize entities with NMPA health food raw material catalog alignment and existing EFSA novel food submission experience. Monitor FDA facility inspection enforcement intensity as inflection indicator for U.S. contract manufacturer consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Registration Infrastructure Investment | NMPA-FDA simultaneous compliance captures procurement consolidation among U.S. contract manufacturers facing GMP enforcement. |
| Captive Cultivation Expansion | Shaanxi or Himachal Pradesh facility control ensures batch-to-batch cordycepin consistency and substrate cost stability. |
| Heat-Stable Extract Formulation Development | Functional beverage insertion into adaptogenic sparkling water and ready-to-drink coffee opens steepest application growth trajectory. |
| Organic Certification Chain Qualification | USDA NOP and EFSA organic compliance unlocks premium positioning in California and German CSRD-mandated procurement. |
| Traceability Infrastructure Acquisition | DNA authentication and heavy metals testing capabilities satisfy direct-to-consumer platform documentation requirements in litigation-exposed markets. |
Research Methodology
Initial hypotheses were tested against primary input from extract procurement managers at U.S. sports nutrition brands, regulatory affairs leads at Chinese NMPA-registered suppliers, and category buyers at European specialty retailers, then refined through secondary validation against SAMR health food raw material catalog updates, FDA warning letter databases, and EFSA novel food assessment timelines. Bottom-up cultivation capacity estimates from Shaanxi and Himachal Pradesh facilities were triangulated against top-down dietary supplement formulation demand projections.
Variance-decomposition across the modeling period isolates cordycepin standardization tier, organic certification status, application channel, and end-user archetype as primary segmentation drivers. CAGRs were derived from volume trajectory analysis incorporating solid-state fermentation yield improvements, bioreactor adoption curves, and regulatory pathway clarity shifts. Forecast inputs include substrate cost indices for organic brown rice and silkworm pupae, plus FDA facility inspection enforcement intensity metrics.
Decision-makers should treat outputs as directional under assumptions of continued DSHEA-aligned GMP enforcement, NMPA regulatory streamlining, and EFSA novel food assessment timeline stability; material deviation in any would warrant model refresh. Specific risk factors include Shaanxi province environmental enforcement actions, organic substrate commodity price spikes, and EFSA safety assessment pathway delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
Pygeum Bark Extract Market
Nutraceuticals
Chondroitin Market
Nutraceuticals
Immunostimulants Market
Nutraceuticals
Native Collagen Market
Nutraceuticals
Hydrolyzed Bovine Collagen Market
Nutraceuticals
Asia-Pacific Effervescent Tablet Market
Nutraceuticals
Hair Growth Supplement and Treatment Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
Pet Nutraceuticals Market
Nutraceuticals
Medicinal Mushrooms Market
Nutraceuticals
LAMEA Digestive Enzymes Market
Nutraceuticals
High Potency Apis Market
Nutraceuticals
Asia-Pacific Pet Nutraceuticals Market
Nutraceuticals
Fish-Oil Based Drugs Market
Nutraceuticals
US Collagen Market