
 Cranial Implants Treatment Market | 2026-2036
Cranial Implants Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cranial Implants Treatment Market Insights
PEEK polymer is recalibrating cranial implant economics by displacing traditional titanium in elective cranioplasty cases where thermal conductivity and imaging artifact reduction command premium positioning. Stryker Corporation leverages its neurotechnology portfolio to sustain integrated sales from decompression through reconstruction. Zimmer Biomet anchors its position through patient-specific implant workflows, while Integra LifeSciences specializes in regenerative matrices that complement structural implants.
Cranial implants treatment encompasses the surgical restoration of skull integrity using biocompatible constructs engineered to precise anatomical specifications, typically fabricated via CNC milling or additive manufacturing from medical-grade titanium, polyetheretherketone, or porous polyethylene with thickness tolerances below 0.1 millimeters to ensure intracranial pressure regulation and cosmetic outcome. The primary commercial purpose centers on protecting underlying neural tissue, restoring aesthetic contour, and enabling functional recovery following trauma, oncologic resection, or congenital defect. Custom implants capture expanding margin pools as hospitals prioritize anatomical fidelity and reduced operative time over standard off-the-shelf geometries. Ambulatory surgical centers represent the fastest-growing end-user channel as minimally invasive fixation techniques and same-day discharge protocols displace traditional inpatient cranioplasty.
FDA 510(k) premarket notification requirements and EU MDR Class III device regulations impose substantial clinical evidence and quality system burdens that filter market access toward established manufacturers with regulatory infrastructure. ISO 13485 certification and ASTM F136 titanium alloy standards further delineate supplier tiers by manufacturing process control and material traceability. Stakeholders must monitor evolving FDA guidance on patient-matched device documentation and EU notified body capacity constraints that could reshape competitive timelines.
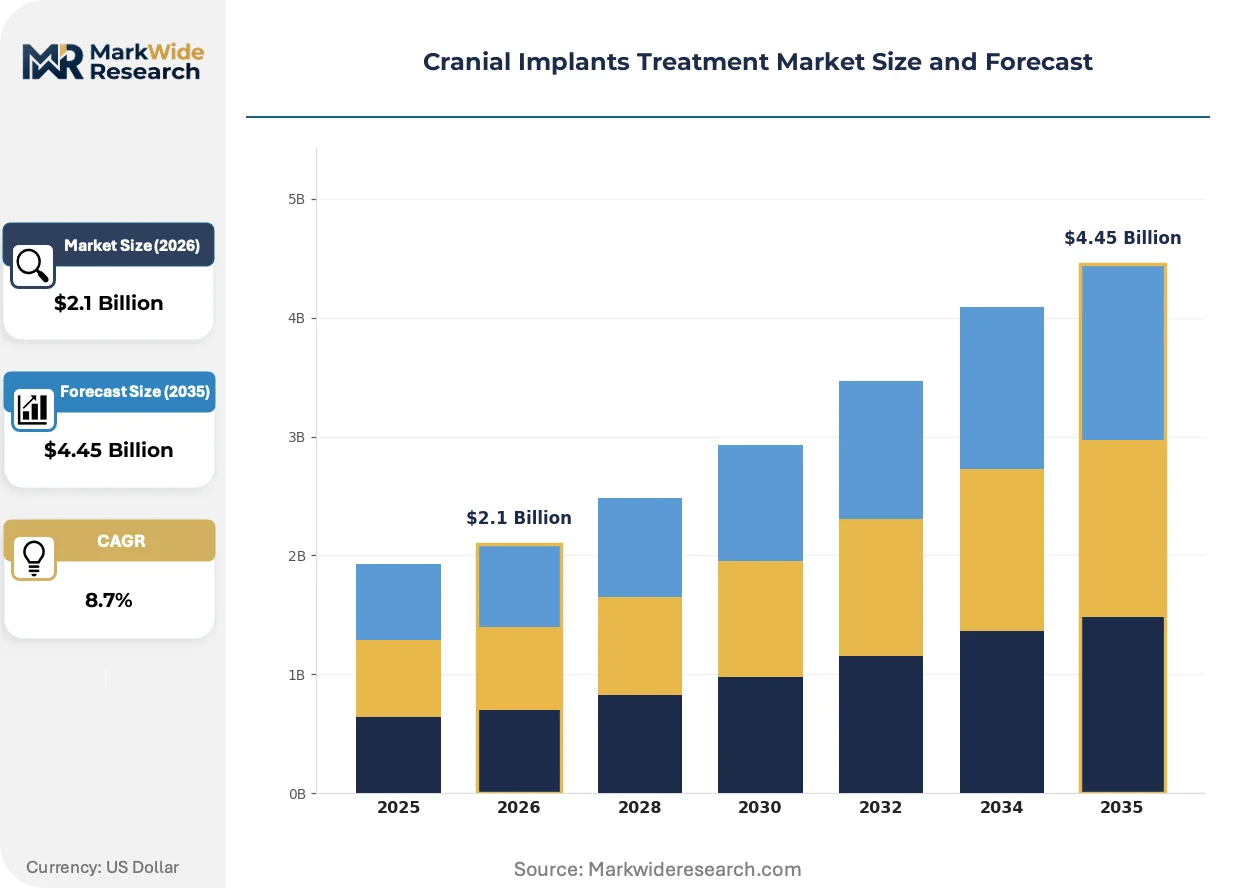
Market Dynamics
The cranial implants treatment market is reconfiguring around patient-matched manufacturing workflows, where additive fabrication and automated design software compress delivery timelines from weeks to days while elevating anatomical precision above standard implant geometries.
Growth Catalysts
- Traumatic brain injury surgical volumes:Rising emergency department admissions across tertiary hospitals in the United States and Germany drive reconstruction procedure demand.
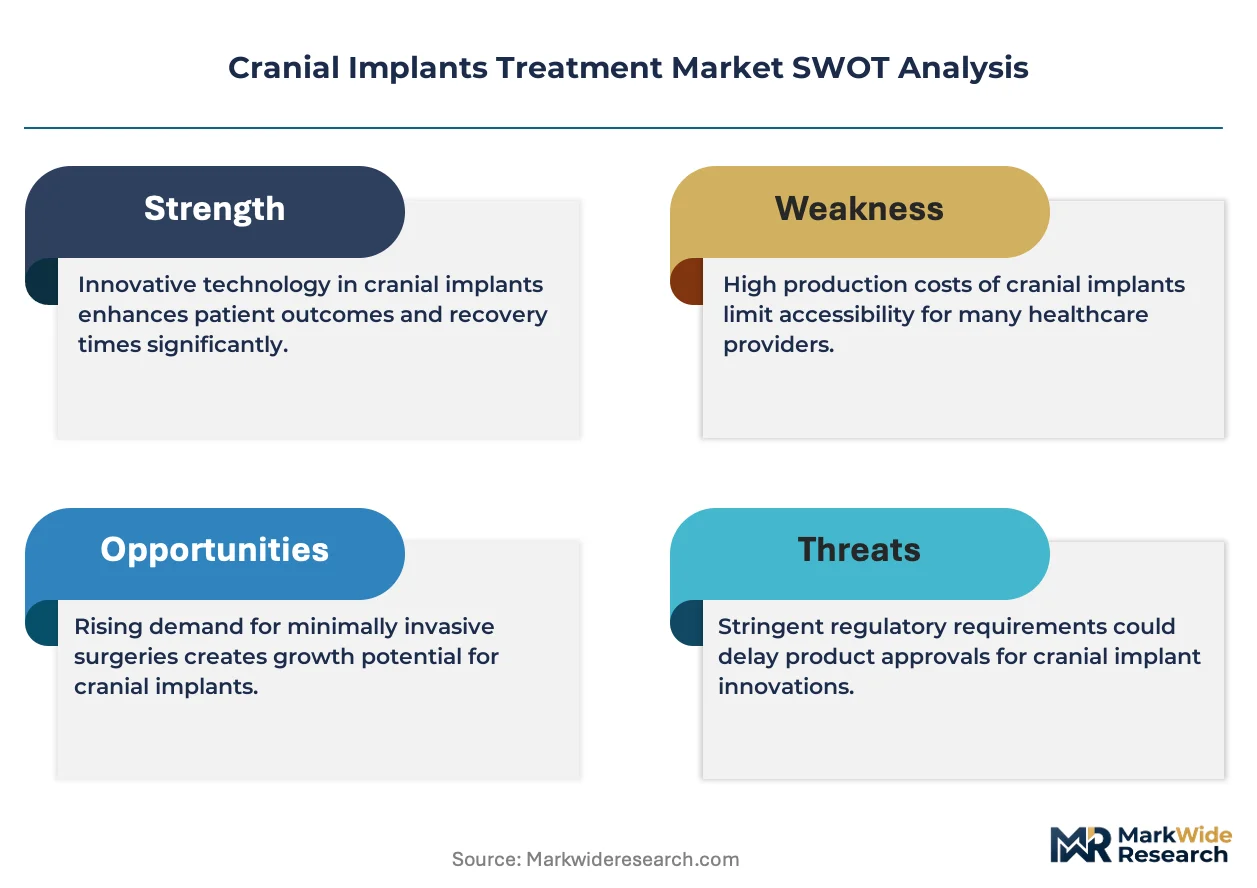
- EU MDR Class III device pathways:Strengthened clinical evidence requirements filter competition toward manufacturers with established quality systems and regulatory infrastructure.
- PEEK polymer thermal properties:Reduced imaging artifact and conductivity advantages accelerate material substitution in elective cranioplasty cases.
Market Restraints
- Titanium alloy supply concentration:ASTM F136-certified feedstock production clusters in a limited supplier base create input vulnerability.
- FDA 510(k) documentation burdens:Patient-matched device guidance expands premarket notification requirements and extends clearance timelines.
- Bioresorbable scaffold limitations:Mechanical integrity degradation rates constrain application in load-bearing cranial defects.
Strategic Opportunities
- Ambulatory surgical center channel expansion:Same-day discharge protocols and minimally invasive fixation techniques open outpatient cranial reconstruction.
- ISO 13485 certification arbitrage:Quality system infrastructure investments position mid-scale manufacturers for contract manufacturing partnerships.
- Japan's aging neurosurgical patient base:Expanding elderly trauma and tumor resection populations create demand for rapid-turnaround custom implants.
Industry Challenges
- CAD-CAM surgical planning integration:Preoperative design software compatibility gaps between implant manufacturers and hospital imaging systems create workflow friction.
- Notified body capacity constraints:EU MDR transition bottlenecks delay conformity assessment timelines and compress commercialization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cranial Implants Treatment Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Implants, Titanium Implants, Composite Implants, Custom Implants End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Material: Biocompatible Polymers, Metals, Ceramics, Biodegradable Materials Procedure Type: Craniectomy, Cranioplasty, Neurosurgery, Trauma Surgery |
| Companies Covered | Stryker Corporation, Zimmer Biomet, Johnson & Johnson Services, Inc., Medtronic, KLS Martin Group, B. Braun Melsungen AG, Integra LifeSciences, OsteoMed, Medartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cranial Implants Treatment Market Trends and Innovations
Additive manufacturing is compressing production economics for patient-specific cranial implants while dissolving traditional boundaries between design, fabrication, and surgical planning functions.
Point-of-care 3D printing is decentralizing implant production by enabling hospital-based fabrication units to manufacture titanium and PEEK constructs from digital surgical plans. Neurosurgery departments at academic medical centers in Germany and the United States are deploying in-house selective laser melting systems to reduce supply chain dependencies. This capability is decentralizing procurement authority from centralized manufacturers to institutional supply chains.
The EU MDR's enhanced clinical evidence requirements for Class III devices are extending development timelines and elevating post-market surveillance obligations. Manufacturers must now demonstrate sustained performance across larger patient cohorts before commercial authorization. Custom implant specialists are responding by consolidating clinical data generation through multi-center registries in France, Germany, and Italy.
Surgeon preference for anatomically precise reconstruction is compressing switching cycles between standard and patient-matched implant categories. Academic medical centers increasingly mandate preoperative virtual surgical planning with implant-specific design validation. This behavioral shift is most pronounced in Japan's tertiary neurosurgery networks, where cosmetic outcome metrics influence institutional purchasing criteria.
Cranial Implants Treatment Market Segmentation
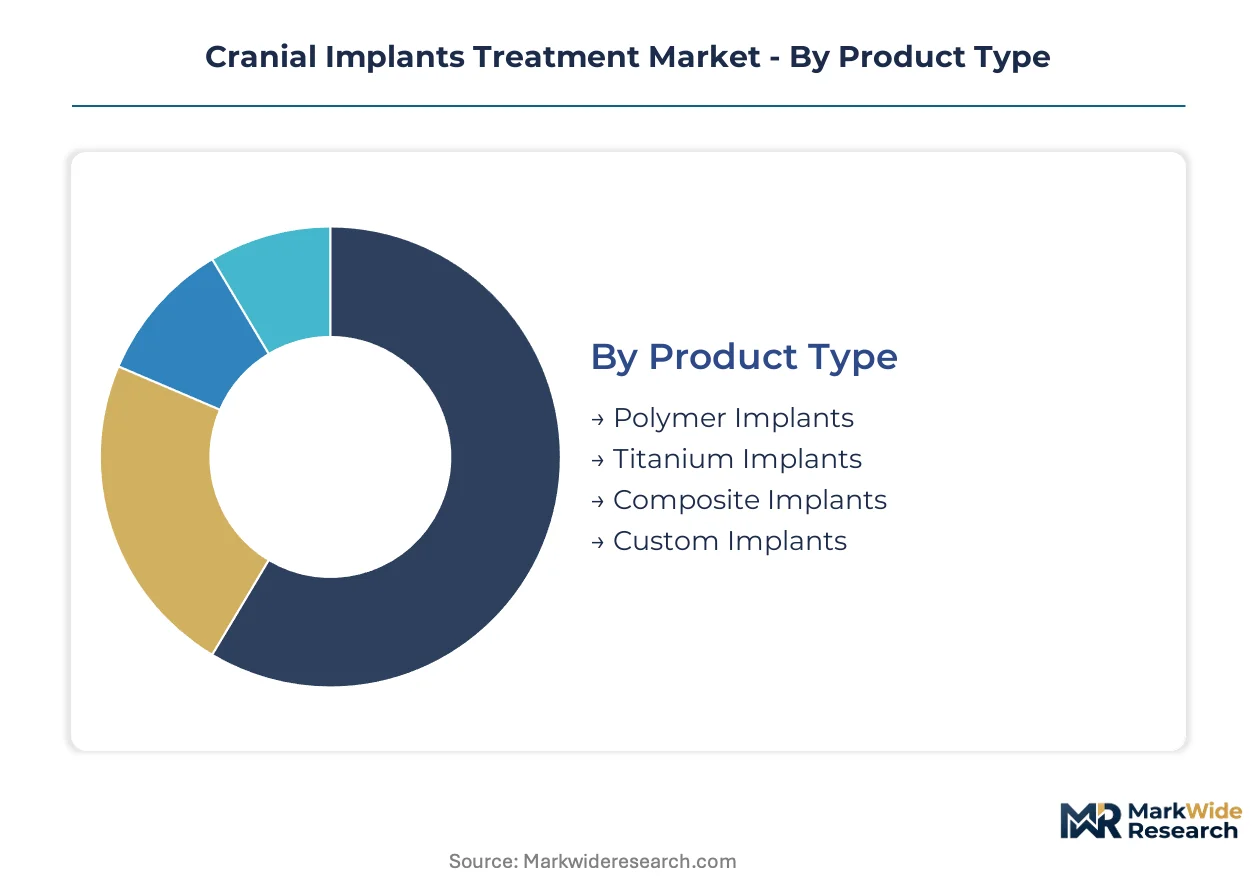
Cranial implant manufacturers calibrate portfolio depth across four intersecting dimensions: material science, procedural application, care setting, and fabrication method. Supply chain configuration varies dramatically by segment, with titanium feedstock concentration in aerospace-linked suppliers contrasting against PEEK polymer's medical-specialty distribution networks.
Product Type:
Supply concentration tilts toward titanium and PEEK polymer conversion specialists, while custom implant workflows fragment across distributed additive manufacturing networks.
- Custom Implants:Patient-matched constructs fabricated via selective laser melting or CNC milling from DICOM-derived anatomical models achieve sub-0.1mm thickness tolerances. Tertiary neurosurgery departments in the United States and Germany prioritize these for complex cranial defect reconstruction where cosmetic outcome metrics drive procurement.
- Titanium Implants:ASTM F136-certified titanium alloy delivers structural integrity for load-bearing applications with established regulatory pathways. Supply concentrates among aerospace-linked feedstock producers, creating procurement vulnerability when medical demand surges against aviation contract priorities.
- Polymer Implants:Medical-grade PEEK formulations reduce thermal conductivity and MRI artifact in elective cranioplasty cases.
- Composite Implants:Hybrid constructs combining metallic strength with polymer biocompatibility address specific mechanical-biological tradeoffs.
Today's leader: Titanium Implants. Tomorrow's challenger: Custom Implants.
End User:
Procurement authority is fragmenting from centralized hospital supply chains toward ambulatory settings as fixation techniques enable same-day discharge protocols.
- Hospitals:Tertiary neurosurgery departments at academic medical centers command the highest implant volumes for trauma and oncologic resection cases. These institutions leverage integrated imaging-to-implant workflows and maintain captive surgical planning capabilities that compress vendor selection cycles.
- Ambulatory Surgical Centers:Minimally invasive cranial fixation techniques and enhanced recovery protocols are expanding outpatient cranioplasty eligibility. These facilities represent the steepest expansion trajectory as reimbursement frameworks adapt to site-of-service cost differentials.
- Specialty Clinics:Focused neurosurgical practices concentrate elective cranioplasty volumes with streamlined preoperative planning.
- Rehabilitation Centers:Post-acute settings coordinate delayed reconstruction for patients requiring staged neurological recovery before cranioplasty.
Procurement gravity: Hospitals. Volume acceleration: Ambulatory Surgical Centers.
Material:
Regulatory clearance pathways stratify by material class, with long-implanted metals enjoying streamlined FDA 510(k) routes compared to novel biodegradable submissions.
- Biocompatible Polymers:PEEK formulations dominate elective reconstruction where imaging compatibility and thermal insulation command premium positioning. PMDA in Japan has accelerated review timelines for polymer implants demonstrating equivalence to predicate devices.
- Metals:Titanium and cobalt-chrome alloys retain structural application dominance despite polymer encroachment in cosmetic-sensitive cases.
- Ceramics:Hydroxyapatite and alumina constructs serve limited osseointegration-focused niches.
- Biodegradable Materials:Polylactic acid and polycaprolactone scaffolds remain constrained by mechanical degradation kinetics in load-bearing defects.
Established advantage: Biocompatible Polymers. Emerging constraint: Biodegradable Materials.
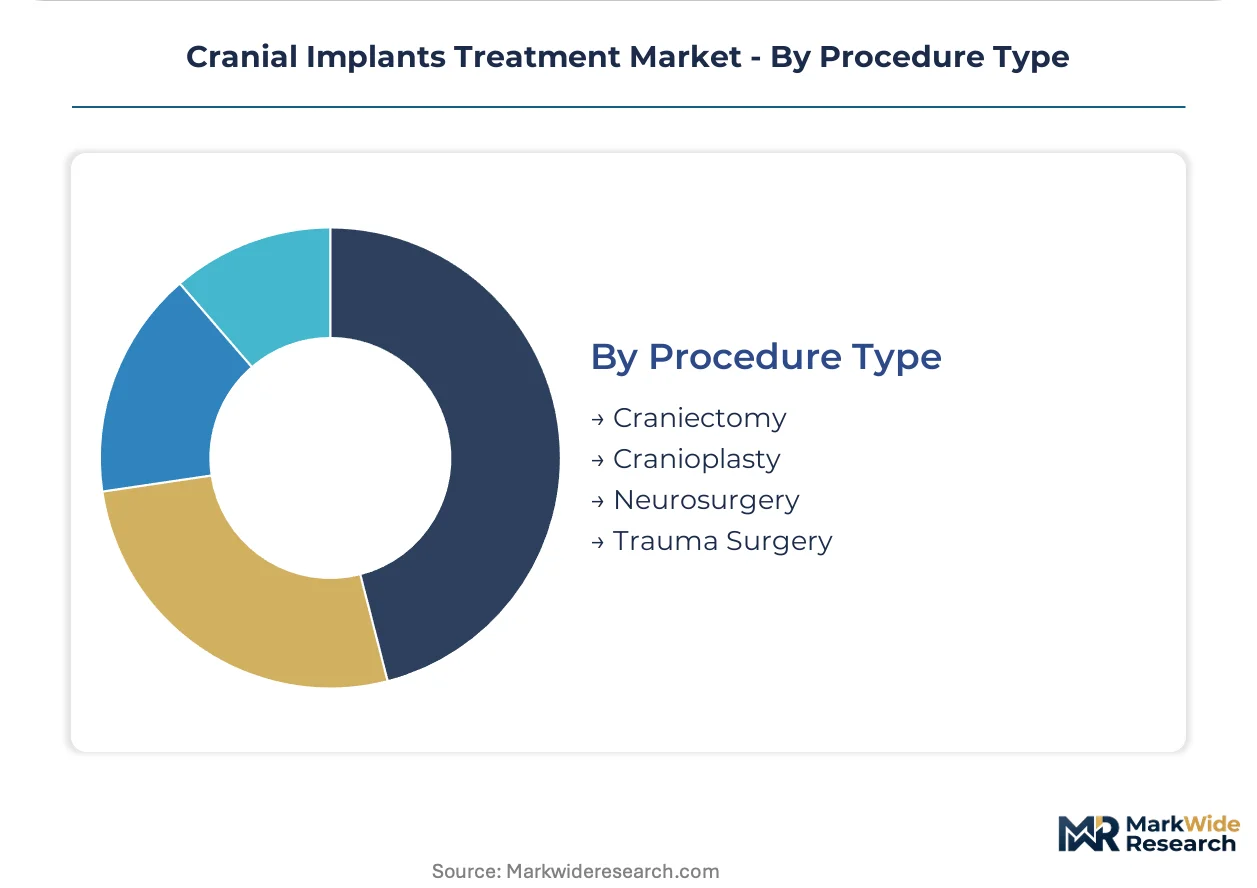
Procedure Type:
Craniectomy volumes drive emergency implant demand with compressed procurement cycles, while cranioplasty permits extended custom fabrication timelines.
- Cranioplasty:Defect reconstruction using patient-matched or standard implants follows initial decompression with elective scheduling flexibility. German neurosurgical networks have pioneered same-admission cranioplasty protocols that compress the decompression-to-reconstruction interval.
- Craniectomy:Emergency decompression creates immediate demand for temporary or definitive implant solutions with constrained vendor selection windows.
- Neurosurgery:Tumor resection and vascular procedures generate planned implant requirements with full preoperative planning cycles.
- Trauma Surgery:Emergency department admission patterns create unpredictable demand spikes concentrated at Level I trauma centers.
Planning advantage: Cranioplasty. Urgency driver: Trauma Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German neurosurgical networks anchor cranial implant demand through integrated trauma and oncology reconstruction workflows, while reimbursement frameworks in the United States and Japan accelerate patient-matched manufacturing adoption.
United States
Level I trauma centers in Houston and Baltimore drive emergency cranioplasty volumes following traumatic brain injury admissions. FDA 510(k) clearance pathways for patient-matched devices impose documentation burdens that filter market access toward established quality system holders. The Texas Medical Center cluster concentrates tertiary neurosurgery capacity with captive surgical planning infrastructure.
Germany
Tertiary hospitals in Munich and Berlin pioneer same-admission cranioplasty protocols that compress decompression-to-reconstruction intervals. EU MDR Class III device regulations extend conformity assessment timelines and elevate post-market surveillance obligations for manufacturers. The Baden-Württemberg medical technology corridor hosts precision machining suppliers serving implant fabricators.
Japan
Aging demographics expand elderly trauma and tumor resection populations requiring rapid-turnaround custom implants. PMDA has accelerated review timelines for polymer implants demonstrating equivalence to predicate devices, streamlining market entry for PEEK formulations. Tokyo's tertiary neurosurgery networks mandate cosmetic outcome metrics in institutional purchasing criteria.
Switzerland
Swissmedic maintains stringent device authorization standards that reinforce quality system differentiation among implant manufacturers. Geneva and Zurich academic medical centers concentrate elective cranioplasty volumes with integrated CAD-CAM surgical planning workflows. The Basel pharmaceutical-medical device cluster supports precision polymer processing capabilities.
United Kingdom
NHS England procurement frameworks prioritize cost-effectiveness in cranial reconstruction while accommodating patient-matched implants for complex defects. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards to preserve market access continuity. London's neurosurgical hubs at Queen Square and King's College Hospital drive complex case referrals.
Cranial Implants Treatment Market Competitive Landscape
Global majors compete with regional champions across regulatory infrastructure and patient-matched manufacturing capabilities. The vendor base stratifies into three tiers: diversified medtech conglomerates with neurotechnology portfolios, orthopedics specialists with cranial extensions, and custom implant pure-plays with additive manufacturing competencies. Dominant competitive moves include M&A to capture patient-matched workflow capabilities and strategic partnerships with hospital-based 3D printing facilities.
Within the diversified medtech tier, Stryker Corporation and Zimmer Biomet exemplify scale-driven positioning through integrated neurotechnology-to-reconstruction portfolios. Integra LifeSciences occupies a specialist position focused on regenerative matrices that complement structural implants. These three companies represent contrasting archetypes: conglomerate breadth, orthopedic extension, and regenerative specialization.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| Johnson & Johnson Services, Inc. |
| Medtronic |
| KLS Martin Group |
| B. Braun Melsungen AG |
| Integra LifeSciences |
| OsteoMed |
| Medartis AG |
| Others |
Pricing and Supply Chain Analysis
Tertiary hospital neurosurgery departments in the United States, Germany, and Japan command procurement authority through centralized GPO contracts and captive surgical planning infrastructure, anchoring a contract-based long-term pricing model where volume commitments secure preferential tier positioning.
Pricing Analysis
ASTM F136 titanium alloy feedstock costs pass through directly to implant pricing, with aerospace-linked suppliers exercising leverage during medical demand surges. Three-tier pricing structure across premium, standard, and economy levels separates patient-matched PEEK constructs from standard titanium geometries and off-the-shelf polymer plates. Cost compression in standard titanium categories is intensifying because hospital procurement committees prioritize inventory reduction over brand premium. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers with integrated design workflows demonstrate lowest sensitivity to unit cost.
Supply Chain Analysis
Medical-grade titanium feedstock supply rests on specialty metal producers in the United States, Germany, and Japan, with PEEK polymer resin concentrated among German and Swiss chemical specialists. CNC machining capacity clusters in the Baden-Württemberg corridor and select US Midwest manufacturing hubs, while additive manufacturing hardware depends on German and American selective laser melting system producers. Single-source vulnerability concentrates in ASTM F136-certified titanium billet supply when aerospace contract volumes surge. Distribution runs through manufacturer-direct hospital contracts and specialized orthopedic distributors serving ambulatory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cranial implants treatment market functions as a stable compounder, with aging demographics across developed economies delivering predictable procedure volume expansion that underwrites sustained revenue visibility.
For Market Incumbents: Extend regulatory infrastructure advantages by deepening EU MDR technical documentation capabilities and accelerating PMDA polymer implant equivalence pathways in Japan. Counter emerging pure-play additive manufacturers by capturing hospital-based 3D printing partnerships before point-of-care fabrication decentralizes procurement authority. Vertical integration into selective laser melting hardware maintenance contracts secures recurring revenue streams.
For New Entrants and Emerging Players: Ambulatory surgical centers in the United States represent the most penetrable buyer archetype, as these facilities lack captive surgical planning infrastructure and prioritize rapid-turnaround implant delivery over established brand relationships. Target same-day discharge protocol adoption curves by developing streamlined custom implant workflows with compressed design-to-delivery timelines. Partner with regional orthopedic distributors to bypass direct hospital contracting barriers.
For Investors and Strategic Acquirers: Diversified medtech conglomerates with neurotechnology portfolios are the most active acquirers in this space, seeking patient-matched manufacturing capabilities to complement decompression-to-reconstruction workflow integration. Long-term viability centers on regulatory data assets and hospital design software integration depth rather than manufacturing scale alone. Watch EU notified body capacity constraints as an inflection indicator for commercialization timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Strengthens conformity assessment readiness against notified body capacity bottlenecks in Germany and France. |
| Hospital-Based 3D Printing Partnership | Captures point-of-care fabrication demand at Texas Medical Center and Munich academic clusters. |
| PEEK Polymer PMDA Equivalence Pathway | Accelerates Japanese market entry leveraging streamlined polymer implant review timelines. |
| GPO Contract Consolidation | Secures procurement authority at Level I trauma centers with compressed vendor selection cycles. |
| CAD-CAM Surgical Planning Integration | Reduces workflow friction between implant manufacturers and hospital imaging systems. |
Research Methodology
Coverage spans the United States, Germany, Japan, Switzerland, and the United Kingdom, with primary inputs from each market combining structured interviews with neurosurgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation. FDA 510(k) premarket notification databases, EU MDR technical documentation filings, PMDA approval records, hospital procurement databases, and CMS Medicare reimbursement data anchor quantitative triangulation. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis converge across the analysis window.
Granularity-level modeling disaggregates projections by material class, fabrication method, procedure type, and care setting, with regional regulatory cluster effects layered across country-specific reimbursement frameworks. CAGRs derive from procedure volume trajectories, implant unit economics, and patient-matched manufacturing penetration curves. Analysis incorporates trauma admission patterns at Level I centers, same-admission cranioplasty protocol adoption rates, and ambulatory surgical center eligibility expansion.
Inputs from regulatory filings and hospital procurement databases were available through the study window; gaps in real-time EU notified body queue data and private manufacturer backlog figures introduce uncertainty bands around commercialization timeline assumptions. Forecasts reflect documented assumptions regarding MDR transition pacing and polymer implant equivalence pathway efficiency. Regulatory guidance evolution, titanium feedstock allocation shifts, and point-of-care 3D printing regulatory clarity constitute a small set of triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Breast Implants Market
Medical Devices
Global Capillary Blood Collection Devices Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Nerve Repair and Regeneration Market
Medical Devices
Global Gynecological Dilators Market
Medical Devices
Heel Incision Devices Market
Medical Devices
Endodontic Files Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Ocular Adhesive Market
Medical Devices
Absorbable Nasal Implant Market
Medical Devices
Global Intragastric Balloon Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Peripheral Embolization Device Market