
 Mobile Heart Monitoring Market | 2026-2036
Mobile Heart Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Heart Monitoring Market Intelligence
Consumer electronics manufacturing in Asia is pivoting toward medical-grade sensor production for wearable devices. Apple Inc. leverages its vast ecosystem to integrate ECG features into its consumer products, targeting the wellness and preventative health market. In contrast, Medtronic plc specializes in clinical-grade implantable recorders and telemetry systems designed for long-term postoperative surveillance. Boston Scientific also competes in the implantable space, while iRhythm Technologies differentiates with its patch-based biosensors approved for arrhythmia detection.
Mobile heart monitoring systems are portable devices that capture cardiac electrical activity, such as single-lead electrocardiography (ECG) signals, outside of a traditional clinical setting. Their primary function is the ambulatory detection and management of conditions like atrial fibrillation, using technologies including photoplethysmography (PPG) sensors and cloud-integrated AI analytics. Wearable monitors and patch devices lead product adoption due to their non-invasive nature and user convenience. Within applications, remote patient monitoring and arrhythmia detection command significant investment from cardiology clinics.
Market access is governed by stringent regulatory approvals, including the FDA's 510(k) clearance in the United States and CE marking under the Medical Device Regulation (MDR) in Europe. These frameworks, alongside standards from Japan's PMDA, mandate rigorous clinical validation for diagnostic accuracy and cybersecurity. Navigating divergent data privacy laws like HIPAA and GDPR while ensuring device interoperability with hospital electronic health record systems remains a central challenge for manufacturers seeking broad market penetration.
Market Dynamics
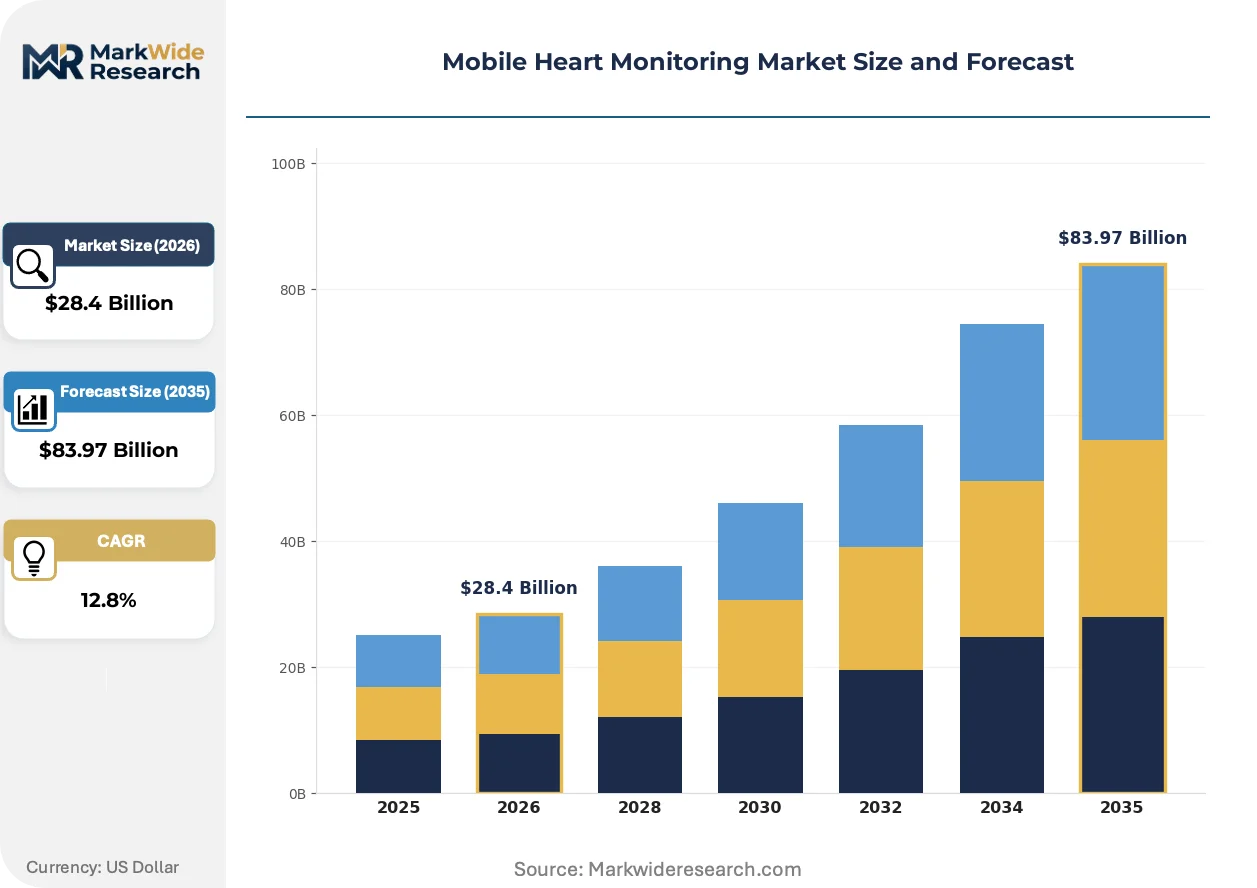
The convergence of consumer-grade wearables with clinical-grade analytics is the central force shaping the mobile heart monitoring market. This shift is driven by advancements in AI for arrhythmia detection and the expansion of telemedicine reimbursement frameworks, moving monitoring from the clinic to the home.
Growth Catalysts
- Favorable Reimbursement:Expanded reimbursement codes for remote patient monitoring in the United States and Germany incentivize cardiology clinics to adopt mobile ECG technologies for chronic disease management.
- Chronic Disease Prevalence:A rising global incidence of conditions like atrial fibrillation necessitates continuous, ambulatory monitoring solutions that function outside of traditional hospital settings.
- AI Integration:The incorporation of artificial intelligence into cloud platforms enhances diagnostic accuracy for arrhythmia detection, improving clinical outcomes and operational efficiency for providers.
Market Restraints
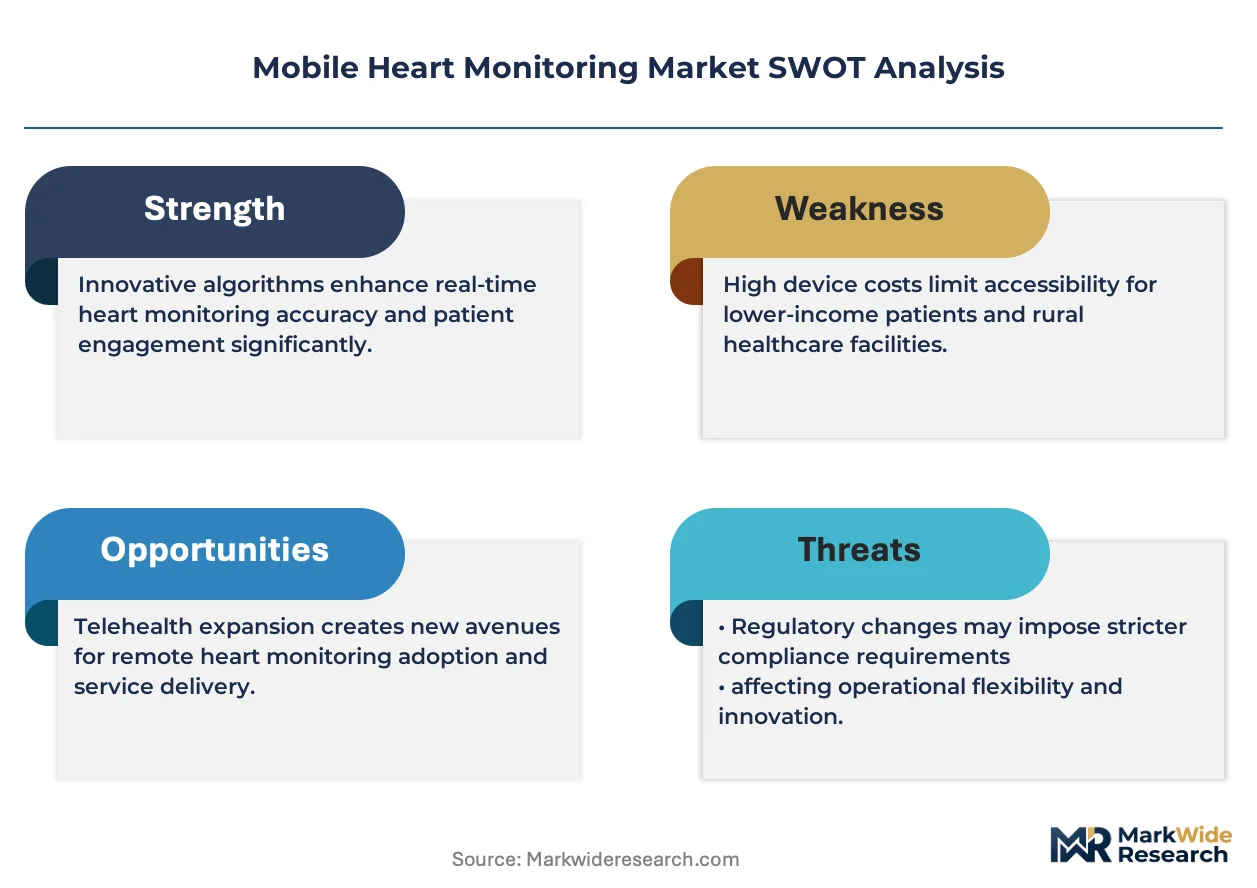
- Data Privacy Compliance:Navigating stringent and divergent data privacy laws, such as GDPR in Europe and HIPAA in the United States, creates significant compliance overhead and cost for manufacturers.
- Clinical Validation Hurdles:The rigorous and lengthy clinical trials required for FDA 510(k) clearance and CE marking under the Medical Device Regulation (MDR) delay market entry for new devices.
- Substitution by Consumer Devices:The growing ECG capabilities in consumer electronics, while not clinical-grade, create a substitution threat for lower-risk patient monitoring applications, impacting the diagnostic segment.
Strategic Opportunities
- Post-Operative Surveillance:Expanding the application of patch-based biosensors and long-term recorders for remote monitoring of post-cardiac surgery patients represents a significant growth area.
- Telehealth Platform Integration:Deepening partnerships with established telehealth service providers offers a new distribution channel to reach patients directly in home-care and preventative health settings.
- Algorithm Development for Comorbidities:Developing AI analytics to detect cardiac complications associated with other chronic diseases, such as diabetes or sleep apnea, opens new diagnostic applications.
Industry Challenges
- EHR Interoperability:Ensuring seamless device integration with disparate hospital Electronic Health Record systems remains a primary operational barrier to achieving efficient clinical workflows.
- Cybersecurity Vulnerabilities:Protecting sensitive patient health information transmitted from wearable devices to the cloud against increasingly sophisticated cyber threats is a constant and resource-intensive challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Heart Monitoring Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $83.97 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Patch Devices, Implantable Recorders, Handheld Devices, Telemetry Systems Technology: ECG Monitoring, PPG Sensors, Wireless Transmission, Cloud Integration, AI Analytics Application: Arrhythmia Detection, Stress Testing, Postoperative Surveillance, Remote Patient Monitoring, Fitness Tracking End User: Cardiology Clinics, Diagnostic Labs, Home Care Providers, Sports Medicine Centers, Telemedicine Services |
| Companies Covered | Medtronic plc, iRhythm Technologies, Koninklijke Philips N.V., Boston Scientific, Zoll Medical Corporation, Apple Inc., Samsung Electronics, AliveCor Inc., BioTelemetry Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Heart Monitoring Market Strategic Shifts & Innovations
A fundamental shift from reactive, episodic cardiac assessment toward proactive, continuous surveillance defines the market's evolution. This transition is enabled by non-invasive sensors and cloud-based analytics, empowering both preventative health management and acute post-operative care.
Advanced AI analytics provide automated interpretation of ECG and photoplethysmography signals captured by wearable devices. Cardiology clinics and remote patient monitoring service providers are rapidly adopting this technology to manage high patient volumes. The software is absorbing the time-intensive manual review of cardiac data, which accelerates the diagnostic workflow for conditions like atrial fibrillation.
Regulatory frameworks are adapting to the pace of software-driven innovation in medical devices. The FDA's digital health guidance and Europe's MDR create specific pathways for validating AI algorithms and mandating robust cybersecurity protocols. Consequently, device manufacturers are embedding regulatory strategy into early-stage product design to streamline market access in the United States and the European Union.
Commercial models are transitioning from one-time hardware sales toward integrated service subscriptions. This approach bundles the monitoring device with data analysis and clinical reporting, displacing the traditional transactional sale of a standalone product. This service-centric model is gaining traction within large hospital networks and cardiology practices focused on value-based care delivery.
Mobile Heart Monitoring Market Segmentation
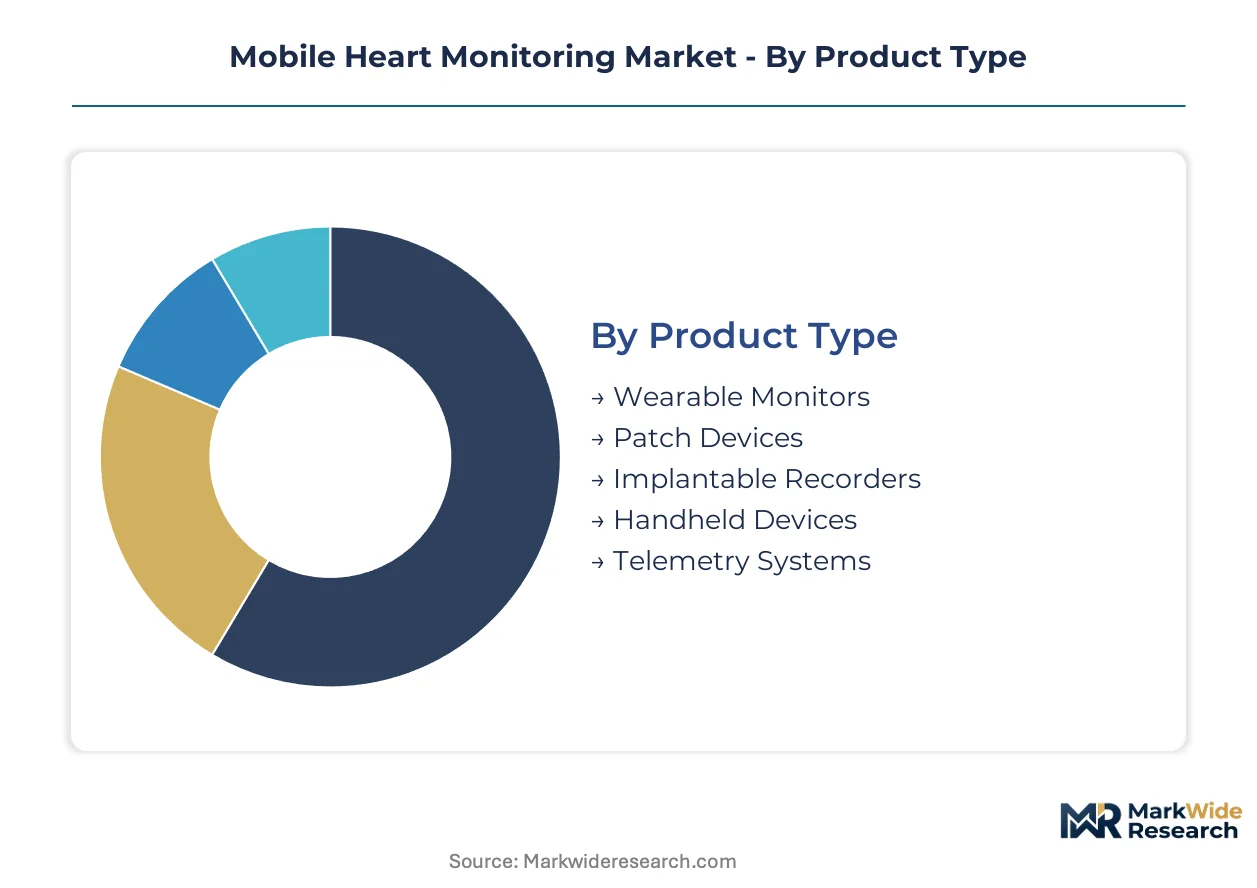
The mobile heart monitoring market segments define distinct product offerings and user applications, reflecting diverse technological capabilities and clinical requirements. Understanding these segments helps manufacturers align product development with specific patient needs and regulatory pathways. This segmentation provides clarity on where investment and innovation are concentrating across the value chain.
Product Type:
Supply concentration in the mobile heart monitoring market leans heavily towards devices optimized for user convenience and continuous data capture. Manufacturers are refining wearable form factors to enhance patient compliance and extend monitoring periods.
- Wearable Monitors:These non-invasive devices, often wrist-worn or chest-mounted, continuously capture cardiac data like ECG signals for extended periods. Demand is concentrating in preventative health and general wellness applications, particularly in regions with established telemedicine infrastructure like the United States.
- Patch Devices:Adhering directly to the skin, these compact biosensors offer discreet, long-term monitoring for arrhythmia detection without wires or bulky equipment. Post-operative surveillance in Europe, driven by MDR compliance, represents a significant demand area for these convenient solutions.
- Implantable Recorders:Surgically placed under the skin, these devices provide multi-year, continuous cardiac monitoring for elusive arrhythmias or post-surgical follow-up.
- Handheld Devices:Portable, on-demand ECG recorders allow for intermittent, user-initiated heart rhythm checks, often used for symptom-triggered events.
- Telemetry Systems:These hospital-based or home-based systems transmit real-time cardiac data over short distances, primarily for acute patient observation.
Today's leader: Wearable Monitors. Tomorrow's challenger: Patch Devices.
Technology:
Maturity levels across mobile heart monitoring technologies vary significantly, from foundational signal acquisition to advanced analytical capabilities. Innovation is rapidly advancing in data interpretation and integration, enhancing diagnostic utility.
- AI Analytics:Software algorithms integrated into cloud platforms automatically interpret complex cardiac signals, identifying arrhythmias and reducing manual review time for clinicians. This technology is gaining share fastest within remote patient monitoring services globally.
- ECG Monitoring:The gold standard for cardiac electrical activity, this technology captures highly accurate single or multi-lead electrocardiogram signals. Demand remains robust in cardiology clinics seeking definitive diagnostic data across all geographies.
- PPG Sensors:These optical sensors detect blood volume changes in the microvasculature, providing a convenient, low-power method for heart rate and rhythm estimation.
- Wireless Transmission:Bluetooth, Wi-Fi, and cellular technologies enable seamless data transfer from monitoring devices to cloud platforms or healthcare providers.
- Cloud Integration:Secure, scalable cloud infrastructure stores, processes, and provides access to patient cardiac data for analysis and clinical review.
AI Analytics is expanding most quickly, while ECG Monitoring holds the largest established base.
Application:
Volume distribution across mobile heart monitoring applications highlights the critical need for continuous surveillance in chronic disease management and diagnostic confirmation. Specific applications drive distinct device requirements and regulatory considerations.
- Arrhythmia Detection:This application focuses on identifying irregular heart rhythms, particularly atrial fibrillation, using continuous or event-based monitoring. It commands significant investment from cardiology clinics in the United States.
- Remote Patient Monitoring:This broad application involves ongoing surveillance of chronic cardiac conditions from outside a traditional clinical setting, improving patient outcomes and reducing hospital readmissions. Germany's favorable reimbursement policies are driving demand.
- Postoperative Surveillance:Monitoring patients after cardiac surgery for complications or recovery progress represents a critical use case for long-term, non-invasive devices.
- Fitness Tracking:Consumer-grade devices primarily use heart rate data for exercise performance and general wellness insights, lacking diagnostic precision.
- Stress Testing:Mobile devices can facilitate ambulatory stress tests, capturing ECG data during physical exertion outside the lab environment.
Demand for Arrhythmia Detection and Remote Patient Monitoring is driving market expansion.
End User:
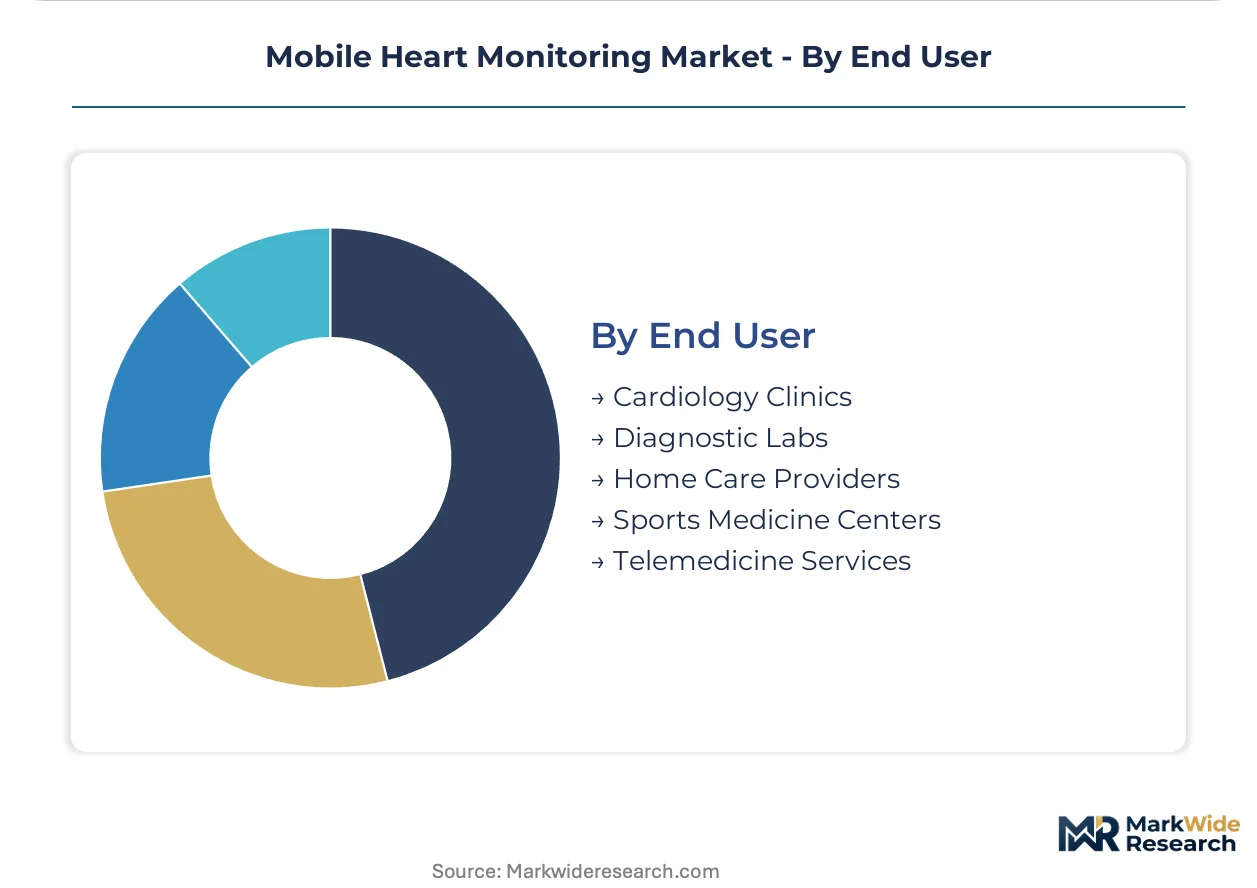
Margin structures for mobile heart monitoring solutions vary across different end-user segments, influenced by service models, reimbursement landscapes, and clinical integration requirements. Specialized clinics often prioritize diagnostic accuracy and seamless EHR integration.
- Cardiology Clinics:These specialized medical practices utilize mobile heart monitors for diagnosing and managing a wide range of cardiac conditions, integrating data into patient care pathways. They prioritize devices with strong clinical validation and EHR interoperability.
- Telemedicine Services:Providers offering virtual healthcare consultations leverage mobile heart monitoring data to remotely assess patient cardiac health, expanding access to care. These services are gaining strategic importance in regions like the United States.
- Diagnostic Labs:These facilities process and analyze cardiac data from various mobile monitoring devices, providing reports to referring physicians.
- Home Care Providers:Organizations delivering healthcare services in patients' homes use mobile monitors to track vital signs and cardiac rhythms for chronic disease management.
- Sports Medicine Centers:These centers use heart monitoring to assess athletes' cardiac function during training and rehabilitation, focusing on performance and safety.
Cardiology Clinics represent the largest segment, while Telemedicine Services are showing rapid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory disparities increasingly influence manufacturing locations for mobile heart monitoring devices, with production often gravitating towards regions offering cost advantages or specialized infrastructure. This dynamic creates a cost-of-compliance gap, impacting where hardware components are sourced and assembled. Manufacturers strategically evaluate regional frameworks to optimize supply chains and market access.
United States
Demand for mobile heart monitoring stems from favorable reimbursement codes for remote patient monitoring and a high prevalence of chronic cardiac conditions. The FDA's 510(k) clearance process mandates rigorous clinical validation for new diagnostic devices. Silicon Valley and Boston's biotech corridor drive innovation in AI analytics and wearable sensor technology.
Germany
Expanded reimbursement policies for digital health technologies significantly incentivize the adoption of mobile ECG solutions in cardiology clinics. CE marking under the Medical Device Regulation (MDR) ensures high standards for device safety and performance. The Munich and Berlin medical technology clusters focus on integrating AI-driven diagnostics with established healthcare systems.
China
A large patient population with rising chronic disease prevalence drives demand for accessible mobile heart monitoring solutions. The NMPA's regulatory pathways are evolving to accommodate advanced medical devices, including AI-enabled diagnostics. Shenzhen's consumer electronics manufacturing base is pivoting towards medical-grade sensor production for global markets.
Japan
The aging population and focus on preventative health contribute to a steady demand for non-invasive cardiac monitoring devices. PMDA standards require robust clinical evidence for diagnostic accuracy and device reliability. Tokyo's medical device industry and research institutions collaborate on miniaturized sensors and advanced data interpretation algorithms.
India
Rising incidence of cardiovascular diseases and expanding telemedicine initiatives fuel the need for affordable, portable heart monitoring systems. The CDSCO's regulatory framework is adapting to fast-track approvals for innovative digital health technologies. Bengaluru's tech ecosystem is emerging as a hub for cloud-based AI analytics development for cardiac data.
Mobile Heart Monitoring Market Key Industry Players
United States producers anchor one tier of the mobile heart monitoring market, focusing on clinical-grade devices and advanced diagnostic capabilities. Asian consumer electronics specialists hold another, driving innovation in user-friendly wearables and mass-market adoption. This creates a tiered competitive structure, balancing stringent medical standards with broad consumer accessibility. The market exhibits a mix of established medical device conglomerates and agile technology startups. Strategic archetypes include clinical-grade device manufacturers, consumer wellness providers, and AI analytics platform developers. Key competitive moves involve technology licensing, strategic partnerships to integrate diverse capabilities, and targeted geographic expansion to capture emerging demand.
Within the established medical device segment, companies like Medtronic plc exemplify the focus on clinical-grade implantable recorders and telemetry systems designed for long-term postoperative surveillance. In contrast, Apple Inc. represents the consumer electronics giant leveraging its vast ecosystem to integrate ECG features into widely adopted products, targeting the wellness and preventative health market. iRhythm Technologies occupies a position as a specialist in patch-based biosensors, differentiating through its focus on convenient, non-invasive arrhythmia detection approved for diagnostic use.
| Leading Market Players |
|---|
| Medtronic plc |
| iRhythm Technologies |
| Koninklijke Philips N.V. |
| Boston Scientific |
| Zoll Medical Corporation |
| Apple Inc. |
| Samsung Electronics |
| AliveCor Inc. |
| BioTelemetry Inc. |
| Others |
Cost & Logistics Intelligence
Specialized medical-grade sensor production costs in Asia influence the final price points of wearable monitors and patch devices sold to cardiology clinics globally. This dynamic shapes the economic viability of new product introductions and market accessibility for diverse patient populations.
Pricing Analysis
Distributor margins for mobile heart monitoring devices vary by product complexity and regulatory clearance. Hybrid subscription and transactional models dominate, bundling monitoring devices with data analysis and clinical reporting services. Price differentiation stems from clinical validation (FDA 510(k), CE MDR) and the breadth of integrated AI analytics features. Pricing softness in the consumer-grade segment reflects the substitution threat from feature-rich smartwatches. Cardiology clinics exhibit lower price sensitivity for clinically validated diagnostic solutions, while home care providers prioritize cost-effectiveness.
Supply Chain Analysis
Semiconductor chip supply for advanced mobile heart monitors relies heavily on East Asian manufacturing hubs. Hardware component production concentrates in China and Japan, leveraging established consumer electronics infrastructure. Specialized biosensors and embedded AI processors are critical dependencies for device manufacturers. Single-source vulnerability for specific medical-grade sensor components poses a structural risk to production timelines. Distribution runs through direct sales channels to cardiology clinics and strategic partnerships with telemedicine service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile heart monitoring market presents a clear margin-expansion narrative. This expansion is driven by the premium-tier shift towards AI-powered diagnostics and integrated service subscriptions.
For Market Incumbents: Hedge against the growing substitution threat from consumer-grade wearables by deepening integration with hospital EHR systems. Incumbents should invest significantly in securing FDA 510(k) and CE MDR clearances for advanced AI algorithms, reinforcing clinical legitimacy. Acquire agile AI analytics startups to enhance diagnostic capabilities, maintaining a competitive edge over emerging tech players.
For New Entrants and Emerging Players: Expanded reimbursement codes for remote patient monitoring in the United States and Germany open a window for specialized patch-based biosensor providers. Target white-space opportunities in post-operative surveillance and comorbidity detection, integrating AI analytics for broader diagnostic applications. Focus on preventative health in established telemedicine markets, offering convenient, non-invasive solutions. Forge strategic partnerships with existing telehealth service providers for rapid market access and patient acquisition.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented AI analytics capabilities meet stringent regulatory requirements for diagnostic accuracy. The market offers strong long-term viability over the next decade, driven by chronic disease prevalence and digital health integration. Target acquisition profiles include specialized biosensor manufacturers and AI algorithm developers with proven clinical validation. The signal to watch is the pace of regulatory approvals for novel AI-driven arrhythmia detection algorithms, indicating market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Certification | Securing FDA 510(k) clearance for AI algorithms validates diagnostic accuracy for cardiology clinics. |
| Telehealth Platform Partnership | Integrating devices with telehealth services expands patient reach and clinical data access for providers. |
| Biosensor Miniaturization R&D | Developing smaller, more discreet biosensors improves patient compliance for long-term monitoring. |
| EHR Interoperability Solutions | Seamless device integration with hospital electronic health records streamlines clinical workflows for physicians. |
| Cybersecurity Protocol Enhancement | Protecting patient health information transmitted from wearable devices builds trust and ensures regulatory compliance. |
Research Approach
Coverage spans the United States, Germany, China, and Japan, with primary inputs from each key geography. The analysis integrates insights from primary interviews with cardiology clinic directors, telemedicine service executives, and medical device engineers. Secondary validation draws from FDA 510(k) clearances, CE marking documentation, national health statistics, and company financial reports. A rigorous bottom-up and top-down triangulation approach ensures data consistency and market sizing accuracy.
The forecast framework decomposes market growth by analyzing the rate of change across key segments. The analytical framework projects market values across the analysis window, considering product type, technology, application, end user, and regional adoption rates. Compound annual growth rates are derived from supply-side capacity additions and demand-side shifts in patient monitoring. Key forecast inputs include chronic cardiovascular disease incidence rates and evolving digital health reimbursement policies.
Revisions become necessary when unforeseen regulatory shifts or major technological disruptions materialize within the mobile heart monitoring ecosystem. Forecasts reflect assumptions regarding market dynamics and adoption trends, but specific risk factors exist. Cybersecurity breaches and rapid AI algorithm advancements are named triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Fetal and Neonatal Monitoring Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
United States Cardiac Holter Monitor Market
Patient Monitoring
Patient Temperature Management Systems Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Bedside Monitors Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
Health Sensors Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
South America Body Temperature Monitoring Market