
 China Diabetes Devices Market | 2026-2036
China Diabetes Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Diabetes Devices Market Outlook
Connected wearable glucose monitoring is rewriting product architecture across China's diabetes care landscape. Sinocare leverages its domestic manufacturing footprint to control costs in blood glucose meter production. Abbott Laboratories anchors the premium continuous glucose monitor segment through sensor miniaturization expertise. Medtronic navigates reimbursement complexity while sustaining R&D intensity in closed-loop insulin delivery systems.
China diabetes devices encompass instruments for glycemic measurement, insulin administration, and metabolic data management, typically integrating electrochemical biosensors with Bluetooth-enabled data transmission to clinical platforms. Their primary commercial purpose centers on reducing hyperglycemic episodes and delaying microvascular complications among diagnosed patients. Pen devices dominate unit volume due to established reimbursement pathways and physician familiarity, while continuous glucose monitors capture expanding margin pools as sensor accuracy improves and out-of-pocket costs decline. Smart devices within the technology dimension are gaining fastest as MIIT promotes connected health infrastructure standards.
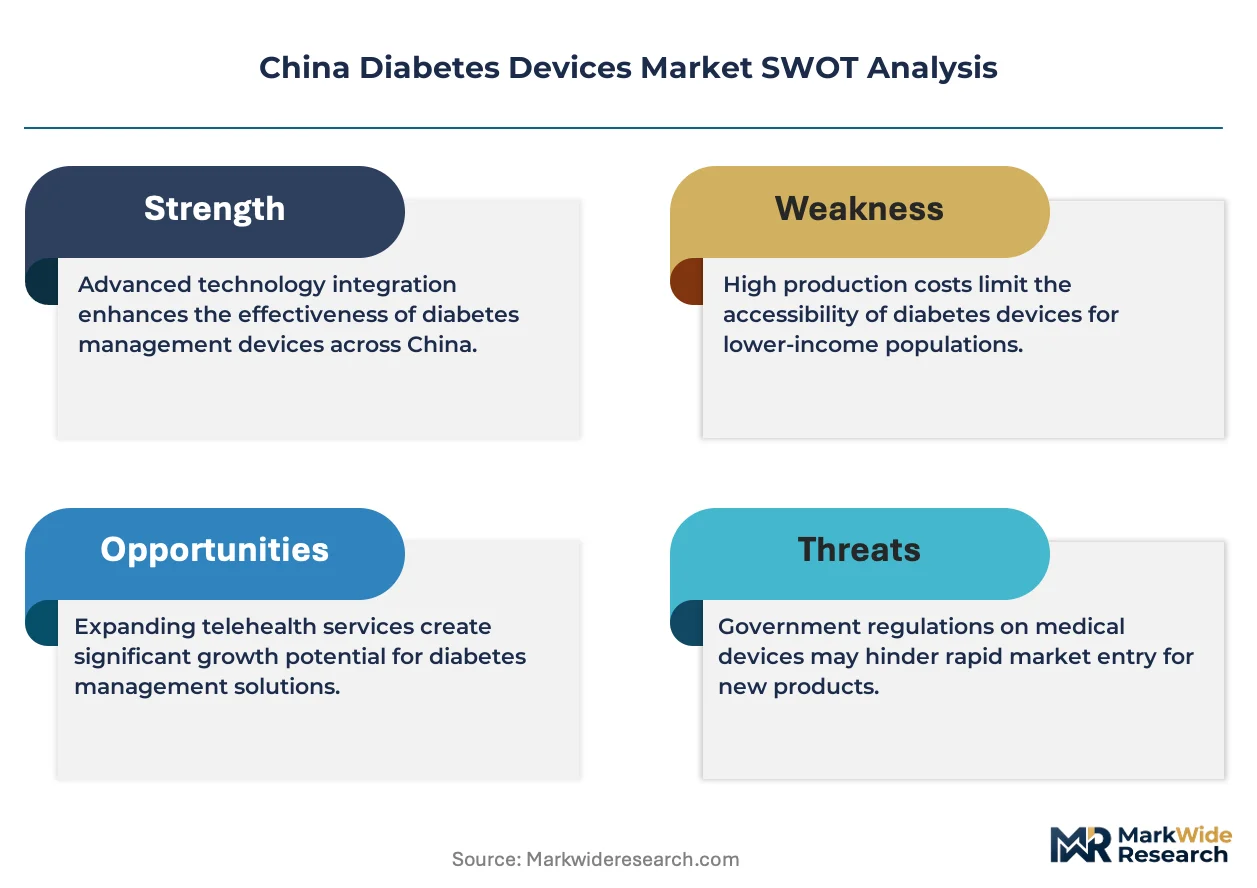
NMPA's medical device classification rules and GB standards for electromagnetic compatibility shape product registration timelines and clinical trial requirements for imported glucose sensors. The country's dual carbon goals pressure manufacturers to reduce disposable plastic components in single-use lancets and test strips. Stakeholders must monitor how provincial reimbursement catalogs incorporate telehealth-linked monitors versus standalone devices.
Market Dynamics
Connected glucose monitoring platforms are compressing product lifecycles as NMPA accelerates digital health approvals and tier-one hospitals demand real-time metabolic data integration. This structural shift is forcing manufacturers to reconfigure R&D pipelines toward software-enabled service models rather than discrete hardware sales.
Growth Catalysts
- MIIT connected health infrastructure standards:Beijing's push for unified data protocols enables seamless hospital-home glucose data flows, reducing clinician review burden while expanding remote patient monitoring eligibility.
- Home care settings:Patients in Shanghai and Beijing are adopting self-management tools at accelerating rates as out-of-pocket sensor costs decline and pharmacy distribution networks deepen.
- Sensor miniaturization:Advances in electrochemical biosensor form factors are enabling 14-day wear times with factory-calibrated accuracy, removing fingerstick confirmation requirements.
Market Restraints
- Reimbursement pathway fragmentation:Provincial health security bureaus maintain inconsistent coverage catalogs for continuous glucose monitors versus blood glucose meters, creating demand uncertainty across tier-two and tier-three cities.
- Imported sensor clinical trial requirements:NMPA's Class III medical device rules mandate local validation studies for foreign-manufactured glucose sensors, extending registration timelines by 18-24 months.
- Single-use plastic component costs:MEE enforcement of dual carbon goals pressures domestic manufacturers to reformulate lancet and test strip materials, raising unit production costs.
Strategic Opportunities
- Telehealth-linked reimbursement expansion:Provincial catalogs in Guangdong and Zhejiang are piloting coverage for cloud-connected monitors, creating precedent for national scale-up.
- Closed-loop insulin delivery convergence:Algorithm-integrated pump-sensor systems represent white space as endocrinology departments seek automated glycemic control solutions.
- Tier-three city pharmacy channels:Underpenetrated distribution in central and western provinces offers volume expansion as retail pharmacy chains consolidate procurement.
Industry Challenges
- Embedded software validation timelines:NMPA's cybersecurity review requirements for Bluetooth-enabled devices add 6-9 months to product launch schedules.
- Clinical data scientist scarcity:Manufacturers struggle to recruit talent capable of interpreting real-world glucose datasets for regulatory submission packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Diabetes Devices Market |
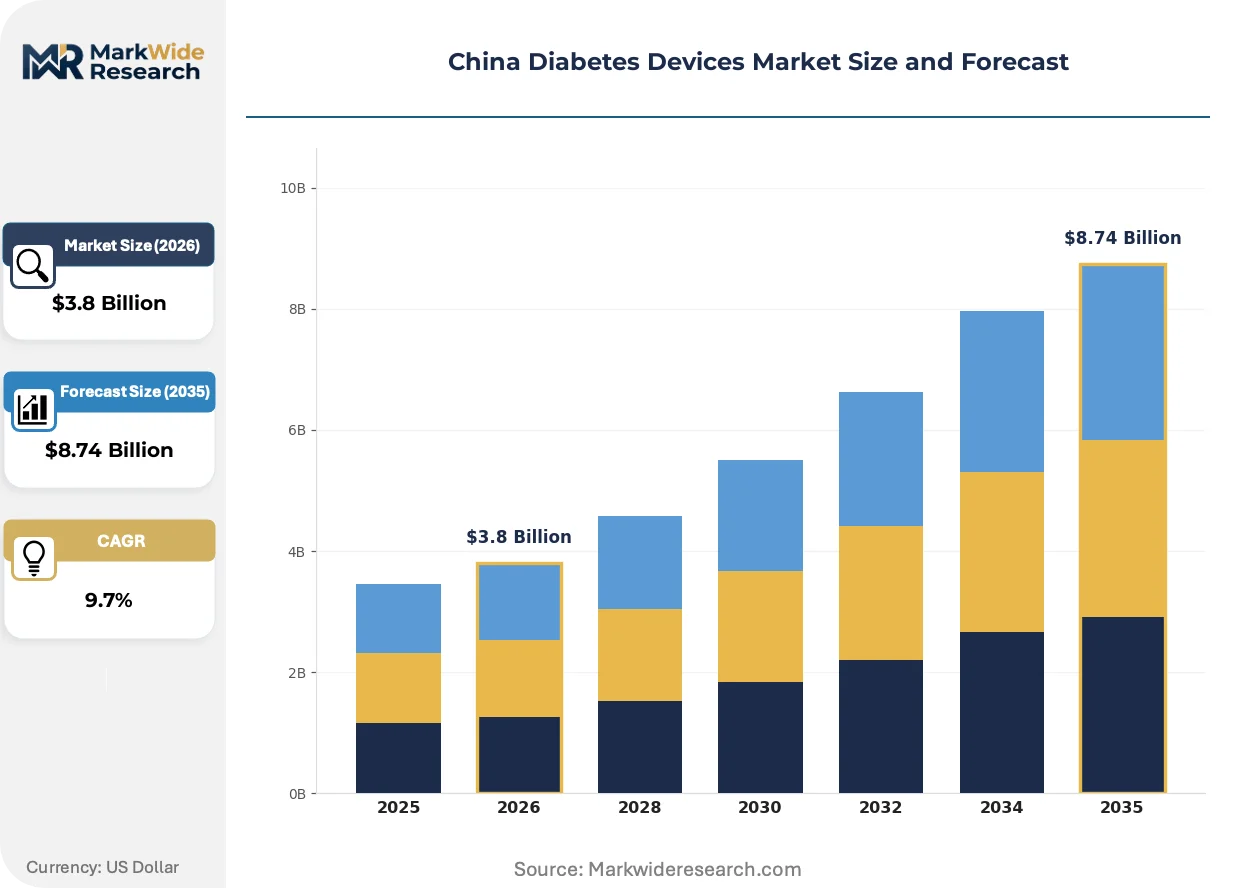
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Continuous Glucose Monitors, Blood Glucose Meters, Pen Devices End User: Hospitals, Home Care Settings, Clinics, Pharmacies Technology: Smart Devices, Wearable Technology, Telehealth Solutions, Mobile Apps Application: Diabetes Management, Patient Monitoring, Insulin Delivery, Data Analytics |
| Companies Covered | Novo Nordisk, Sinocare, F. Hoffmann-La Roche, Becton Dickinson and Company, Ascensia Diabetes Care, Abbott Laboratories, Medtronic, Ypsomed Holding, Sanofi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Diabetes Devices Market Strategic Shifts
Digital health infrastructure investments are compressing the gap between consumer-grade wearables and clinical-grade metabolic monitoring. Three distinct vectors are reshaping how glucose data is captured, transmitted, and monetized across China's healthcare system.
Non-invasive optical glucose sensing is digitizing the measurement experience by eliminating fingerstick blood draws entirely. Early adopters in corporate wellness programs are piloting wrist-worn prototypes for pre-diabetic screening. This technology is digitizing patient acquisition pathways by enabling pharmacy-based screening services that feed downstream device sales.
NMPA's 2023 medical device classification amendments have reclassified certain continuous glucose monitors as Class II rather than Class III products. This regulatory recalibration compresses clinical trial requirements for sensor iterations. Domestic manufacturers in Jiangsu and Zhejiang are responding by accelerating product refresh cycles to 12-18 months.
Hospital procurement committees are consolidating vendor relationships around integrated platform providers rather than standalone meter suppliers. This concentration behavior disrupts traditional distributor networks that built regional scale on blood glucose meter volume. The shift is most visible in Beijing's municipal hospital system, where unified purchasing platforms now favor vendors offering cloud analytics subscriptions.
China Diabetes Devices Market Segmentation
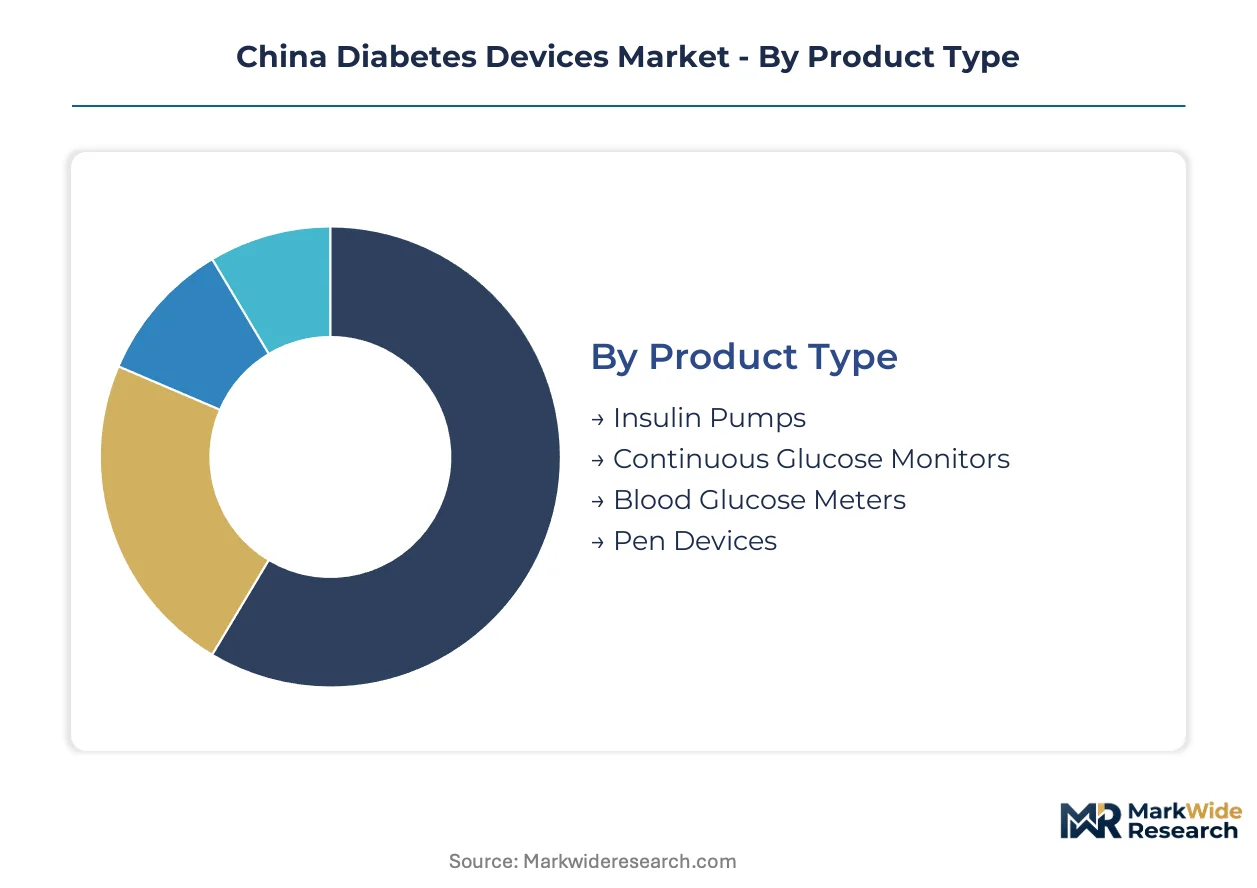
China's diabetes devices market fragments across four distinct dimensions that shape procurement patterns and reimbursement pathways. Product architecture choices determine whether manufacturers compete on sensor accuracy, insulin delivery precision, or data integration capabilities. End-user concentration in tier-one hospitals versus home care settings creates divergent margin structures and regulatory requirements.
Product Type:
Clinical use-cases span intensive insulin therapy, real-time metabolic tracking, episodic glucose checks, and manual injection administration across diverse patient acuity levels.
- Continuous Glucose Monitors:Factory-calibrated electrochemical sensors enable 14-day wear with Bluetooth transmission to clinical platforms. Demand concentrates in Beijing and Shanghai tertiary hospitals where endocrinology departments prioritize real-time hypoglycemic alerts and remote patient monitoring integration.
- Insulin Pumps:Motor-driven reservoir systems deliver basal-bolus dosing with programmable profiles. Adoption clusters in urban centers with established reimbursement catalogs, though NMPA Class III registration requirements extend market entry timelines for imported systems.
- Blood Glucose Meters:Portable electrochemical analyzers using disposable test strips dominate prescription volume through pharmacy channels.
- Pen Devices:Spring-loaded disposable and reusable injection systems anchor insulin delivery in primary care settings.
Established volume favors Pen Devices; emerging adoption favors Continuous Glucose Monitors.
End User:
Procurement authority and reimbursement eligibility diverge sharply across institutional versus retail channels.
- Home Care Settings:Patients self-manage glycemic control through direct-to-consumer purchases and pharmacy prescriptions. Shanghai and Beijing households drive premium sensor adoption as out-of-pocket costs decline and MIIT-connected health infrastructure enables seamless data sharing with clinicians.
- Hospitals:Tertiary endocrinology departments procure integrated pump-sensor systems for inpatient glycemic management. NMPA procurement reforms favor vendors offering cloud analytics subscriptions over standalone meter suppliers.
- Clinics:Community health centers provide episodic glucose testing and insulin initiation services.
- Pharmacies:Retail chains consolidate blood glucose meter distribution and expanding continuous glucose monitor access in tier-two cities.
Institutional procurement concentrates in Hospitals; volume expansion runs through Home Care Settings.
Technology:
Digital maturity separates connected platforms from legacy hardware across the patient journey.
- Smart Devices:Algorithm-enabled glucose meters and pumps with predictive analytics capabilities. Jiangsu and Zhejiang manufacturers accelerate refresh cycles to 12-18 months following NMPA's 2023 reclassification of certain continuous glucose monitors from Class III to Class II.
- Wearable Technology:Skin-adhesive sensors and wrist-worn prototypes for non-invasive optical sensing. Corporate wellness programs in tier-one cities pilot pre-diabetic screening applications.
- Telehealth Solutions:Cloud-connected platforms enabling remote clinician review and automated insulin dosing recommendations.
- Mobile Apps:Patient-facing applications for glucose logging, carbohydrate counting, and medication reminders.
Hardware legacy persists in Wearable Technology; software integration advances fastest in Smart Devices.
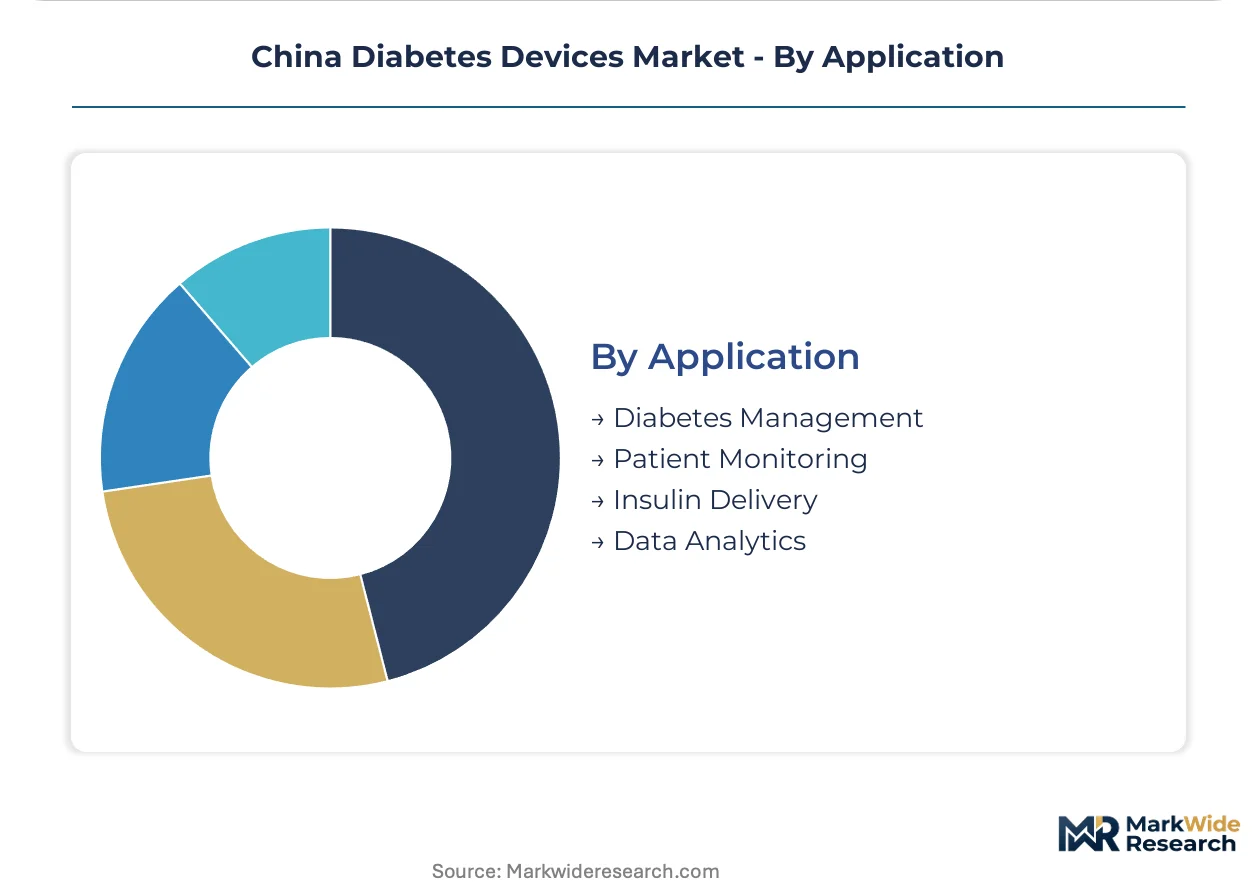
Application:
Functional purpose determines device specification requirements and clinical validation burden.
- Diabetes Management:Comprehensive glycemic control encompassing measurement, medication adherence, and lifestyle modification. Home care patients in Guangdong and Zhejiang pilot cloud-connected monitors as provincial catalogs expand telehealth-linked reimbursement.
- Insulin Delivery:Automated and manual systems for exogenous hormone administration. Closed-loop algorithm integration represents white space as endocrinology departments seek automated glycemic control.
- Patient Monitoring:Continuous or episodic metabolic surveillance for acute and chronic care settings.
- Data Analytics:Population health platforms aggregating real-world glucose datasets for outcomes research.
Discrete functionality dominates Insulin Delivery; convergent platforms reshape Diabetes Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and home care patients concentrate demand in distinct geographic clusters, with tier-one cities driving premium device adoption while provincial expansion targets underpenetrated markets.
Beijing-Tianjin-Hebei
Tertiary hospital networks and MIIT-connected health infrastructure drive demand for cloud-integrated glucose monitors. NMPA procurement reforms favor vendors offering analytics subscriptions over standalone hardware. Beijing municipal hospitals consolidate purchasing around platform providers, disrupting traditional distributor networks.
Yangtze River Delta
Shanghai households lead self-management tool adoption as out-of-pocket sensor costs decline. Provincial health security bureaus pilot telehealth-linked reimbursement for continuous glucose monitors. Jiangsu and Zhejiang manufacturers accelerate product refresh cycles following NMPA's 2023 reclassification of certain devices from Class III to Class II.
Pearl River Delta
Guangdong's pilot coverage programs for cloud-connected monitors create precedent for national scale-up. SAMR enforcement of dual carbon goals pressures manufacturers to reduce disposable plastic components. Shenzhen's electronics ecosystem supports sensor miniaturization and Bluetooth-enabled device production.
Sichuan-Chongqing
Central and western provinces offer volume expansion through retail pharmacy chain consolidation. Reimbursement pathway fragmentation creates demand uncertainty compared to coastal markets. Chongqing's growing endocrinology departments seek automated glycemic control solutions for inpatient management.
Shandong Peninsula
Manufacturing clusters support domestic production of electrochemical biosensors and test strips. MEE environmental compliance raises unit production costs for single-use components. Qingdao and Jinan pharmacy channels deepen distribution reach for blood glucose meters in tier-two cities.
China Diabetes Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent margin structures, with consolidated procurement platforms in tier-one cities favoring integrated vendors while fragmented retail pharmacy networks sustain standalone meter suppliers. The vendor base organizes into three strategic archetypes: multinational platform providers with sensor miniaturization expertise, domestic cost leaders leveraging manufacturing scale, and algorithm-integrated closed-loop specialists. Competitive intensity manifests through strategic partnerships with hospital systems and portfolio diversification into software-enabled service models.
Among multinational platform providers, Abbott Laboratories and Medtronic occupy positions exemplifying premium-tier sensor and pump-sensor integration archetypes. Sinocare anchors the domestic cost-leader tier, representing manufacturers leveraging regional production footprints to control unit economics in blood glucose meter segments.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sinocare |
| F. Hoffmann-La Roche |
| Becton Dickinson and Company |
| Ascensia Diabetes Care |
| Abbott Laboratories |
| Medtronic |
| Ypsomed Holding |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo port corridor's freight cost dynamics concentrate supply-side leverage among Jiangsu and Zhejiang electrochemical sensor manufacturers while forcing three-tier pricing stratification across premium, standard, and economy device tiers. Domestic contract manufacturers exploit this logistics advantage to compress landed costs for Bluetooth-enabled glucose meters, though MEE environmental compliance raises unit economics for single-use plastic components.
Pricing Analysis
Cost-plus contracts with quarterly raw material indexation dominate procurement between domestic manufacturers and hospital GPOs, anchoring price stability for blood glucose meters while allowing margin flexibility for continuous glucose monitors. Price differentiation rests on NMPA Class II versus Class III certification tiers and bundled cloud analytics subscriptions rather than hardware alone. Cost compression in standard-tier pen devices is intensifying because retail pharmacy chains consolidate procurement volumes. Home care patients in tier-two cities exhibit highest price sensitivity; tertiary hospital endocrinology departments demonstrate lowest sensitivity due to integrated platform budgeting.
Supply Chain Analysis
Contract manufacturing capacity concentrates among Jiangsu and Zhejiang EMS providers with dedicated medical device cleanroom certifications, supplemented by Shenzhen electronics specialists for Bluetooth module integration. Electrochemical biosensor membranes, lancet-grade stainless steel, and medical-grade ABS plastics draw from domestic specialty chemical suppliers. Single-source vulnerability persists for imported glucose oxidase enzyme formulations subject to NMPA import registration delays. Distribution runs through consolidated retail pharmacy chains in coastal provinces and fragmented distributor networks in central and western regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital procurement platforms and retail pharmacy chains, fragmenting pricing leverage for standalone meter suppliers while concentrating volume discounts for integrated platform vendors.
For Market Incumbents: Insulate core revenue streams by deepening backward integration into electrochemical biosensor membrane production and securing exclusive GPO contracts with Beijing and Shanghai tertiary hospital systems. Algorithm-integrated closed-loop pump-sensor convergence from Medtronic and domestic challengers threatens premium-tier margins; defensive patent filings around factory-calibration protocols are essential. For New Entrants and Emerging Players: Build out telehealth-linked reimbursement expertise to capture Guangdong and Zhejiang pilot program expansions before national scale-up. Tier-three city pharmacy channels in Sichuan and Chongqing offer the most penetrable white space for continuous glucose monitor volume. A direct-to-clinician digital sampling strategy bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational medtech parents seeking to divest non-core diabetes device portfolios amid China market localization pressures. Long-term viability hinges on software-enabled service model conversion rather than hardware transaction economics. Watch NMPA reimbursement catalog updates for cloud-connected monitors as the inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class II Reclassification Exploitation | Accelerated 12-18 month product refresh cycles compress competitive response windows for imported rivals. |
| Cloud Analytics Subscription Bundling | Beijing municipal hospital procurement reforms favor vendors with integrated data platform offerings over standalone hardware. |
| Telehealth-Linked Reimbursement Strategy | Guangdong provincial pilot programs create precedent for national coverage expansion and recurring revenue streams. |
| Domestic Biosensor Membrane Integration | Backward integration into Jiangsu specialty chemical supply reduces import dependency and NMPA registration risk. |
| Tier-Three Pharmacy Channel Penetration | Consolidating retail chains in central and western provinces offer volume expansion with lower competitive intensity. |
Study Parameters
Operator-level perspectives from hospital procurement committee members, endocrinology department heads, biomedical engineers, retail pharmacy chain category managers, and NMPA regulatory consultants anchored the qualitative base. Secondary validation drew from NMPA medical device registration databases, hospital procurement platform disclosures, provincial health security bureau reimbursement catalogs, MIIT connected health infrastructure standards, and customs import records for glucose sensor components. Bottom-up demand modeling across patient segments triangulated with top-down market sizing from manufacturer production disclosures.
Scenario-bracketing framed the analytical approach across the analysis window, with demand trajectories tested against reimbursement expansion pace and sensor cost decline curves. Segmentation dimensions modeled included product architecture type, end-user procurement channel, technology connectivity tier, and regional regulatory cluster. CAGRs were derived from patient population growth rates, device penetration assumptions, and average selling price evolution by tier. Key inputs encompassed NMPA approval timeline distributions and provincial catalog inclusion probabilities.
Stress conditions across reimbursement pathway fragmentation, dual carbon compliance cost trajectories, and cybersecurity review timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MIIT infrastructure deployment schedules and NMPA classification stability. Quarterly review of provincial health security bureau telehealth reimbursement decisions and NMPA Class III registration queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intraosseous Infusion Device Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Medical Thermometer Market
Medical Devices
Surgical Devices Market
Medical Devices
Reusable Resuscitators Market
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
Middle East and Africa Hip and Knee Reconstruction Devices Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
China Artificial Organs and Bionic Implants Market
Medical Devices
Elbow Fixation Systems Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Male Artificial Urinary Sphincter Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
Subdural Electrodes Market
Medical Devices
Medical Connector Market
Medical Devices
Medical Face Shield Market