
 Global Drone Inspection and Monitoring Market | 2026-2036
Global Drone Inspection and Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drone Inspection and Monitoring Market Intelligence
The focus on subscription-based data analytics is shifting the market's value proposition from hardware sales towards recurring service revenue. DJI leverages its dominant hardware position to offer integrated software suites for enterprise clients across multiple industries. Flyability specializes in collision-tolerant drones for confined space inspection, targeting niche industrial applications like power generation. Skydio differentiates with its AI-powered autonomous flight, reducing pilot cognitive load and improving data consistency.
Drone inspection and monitoring utilizes unmanned aerial vehicles (UAVs) equipped with high-resolution sensors for remote data acquisition. Payloads like LiDAR and thermal imaging cameras capture precise, georeferenced data for asset management and safety compliance. Rotary-wing drones dominate the product landscape due to their hovering capability and maneuverability in complex environments. Infrastructure inspection represents the largest application, driven by maintenance requirements for aging assets in the energy and transportation sectors.
Regulators like the U.S. Federal Aviation Administration (FAA), the European Union Aviation Safety Agency (EASA), and Transport Canada are defining frameworks for Beyond Visual Line of Sight operations. These evolving rules directly influence operational envelopes, pilot certification, and market access for service providers. Consequently, vendor selection will hinge on a platform's ability to demonstrate compliance and integrate with emerging unmanned traffic management systems.
Market Dynamics
The central dynamic in the drone inspection market is the progression of regulations for Beyond Visual Line of Sight (BVLOS) operations. This regulatory evolution by authorities like the FAA and EASA unlocks new applications over vast areas but simultaneously introduces significant compliance and operational complexity for service providers.
Growth Catalysts
- BVLOS Regulations:Evolving frameworks from the FAA and EASA for Beyond Visual Line of Sight flights are expanding the operational scope for linear infrastructure inspection, such as pipelines and power lines, over long distances.
- Industrial Safety Mandates:The Oil & Gas sector's stringent safety requirements for inspecting hazardous or difficult-to-access assets, like flare stacks and storage tanks, drive adoption of drones to minimize human risk.
- Sensor Miniaturization:Advances in shrinking the size and weight of high-fidelity sensors, including LiDAR and multispectral cameras, enable their use on smaller, more agile rotary-wing drones for detailed asset analysis.
Market Restraints
- High Payload Cost:The significant capital expense for advanced payloads, such as survey-grade LiDAR or optical gas imaging (OGI) cameras, presents a financial barrier for smaller inspection service providers.
- Fragmented Pilot Certification:Divergent and complex pilot certification requirements across national aviation authorities, including the FAA in the United States and EASA member states, create compliance hurdles for international operators.
- Endurance and Power Limitations:Limited battery life and flight endurance of most commercially available rotary-wing drones constrain the area covered in a single mission, impacting efficiency for large-scale surveys.
Strategic Opportunities
- Underpenetrated Geographies:The agricultural and infrastructure sectors in Southeast Asian nations offer significant growth potential for drone-based crop health monitoring and construction project management where ground-based methods are inefficient.
- Environmental Monitoring:New applications are emerging in environmental compliance, including monitoring coastal erosion, tracking deforestation, and conducting wildlife surveys for conservation efforts, supported by government and NGO funding.
- AI-Powered Analytics:The convergence of drone-captured imagery with machine learning algorithms creates opportunities for predictive maintenance platforms that can automatically detect defects and forecast asset failure.
Industry Challenges
- Specialized Talent Scarcity:A shortage of personnel possessing hybrid skills in both certified drone piloting and specialized data analysis for industries like energy or civil engineering limits service scalability.
- Data Integration Complexity:Service providers face challenges integrating vast and varied data streams from drone sensors into clients' existing enterprise asset management (EAM) and geographic information system (GIS) software.
- Lack of Data Standardization:The absence of universal standards for drone data formats and reporting creates interoperability issues between different hardware, software, and analytics platforms, complicating workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drone Inspection and Monitoring Market |
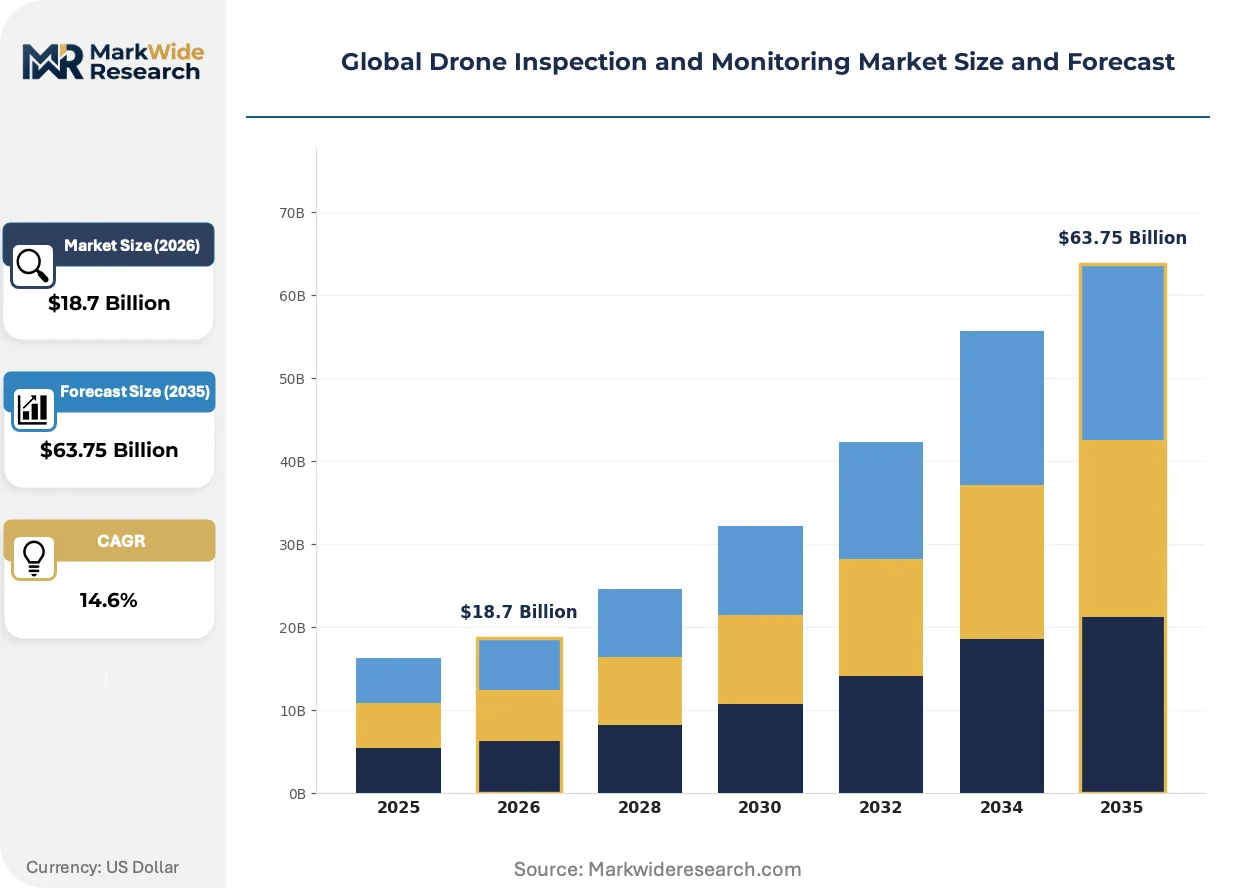
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing Drones, Rotary-Wing Drones, Hybrid Drones, Tethered Drones, Nano Drones Technology: LiDAR, Thermal Imaging, Photogrammetry, Multispectral Imaging, Hyperspectral Imaging Application: Infrastructure Inspection, Agriculture Monitoring, Energy Asset Surveillance, Wildlife Conservation, Construction Progress Tracking End User: Telecommunication Providers, Oil & Gas Operators, Environmental Agencies, Mining Corporations, Public Safety Departments |
| Companies Covered | Easy Aerial, MISTRAS Group, Skydio, Lockheed Martin Corporation, Intertek Group, DJI, Azur Drones, Intel Corporation, Flyability, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drone Inspection and Monitoring Market Strategic Shifts & Innovations
Automation and data intelligence are transforming drone operations from basic remote sensing into integrated analytical workflows. The emphasis is shifting from the vehicle itself to the quality, speed, and actionability of the insights derived from its sensor data, pushing development in onboard processing and AI.
AI-powered autonomous navigation systems use computer vision and sensor fusion to enable drones to fly complex missions without constant pilot input. Infrastructure operators in the energy and telecom sectors are adopting this technology for consistent, repeatable inspections of cell towers and wind turbines. This autonomy is electrifying the competitive landscape by allowing firms to scale fleet operations with fewer highly-skilled pilots, focusing human expertise on data analysis rather than flight control.
The European Union's U-space framework is establishing a digital infrastructure for managing drone traffic in controlled airspace. This policy creates a new market for certified Unmanned Traffic Management (UTM) service providers, who offer digital identification, geofencing, and traffic information services. Service operators in dense urban areas across EU member states are most affected, as they must now integrate their flight operations with these mandatory digital systems to ensure compliance and safety.
A clear behavioral change is the move from one-time hardware purchases toward subscription-based Drone-as-a-Service (DaaS) contracts. This model displaces capital-intensive, in-house drone programs with recurring revenue agreements that bundle hardware, software, certified pilots, and data analytics. The energy and construction sectors, particularly in North America and Europe, are leading this procurement shift to access specialized capabilities while minimizing technology risk and upfront investment.
Global Drone Inspection and Monitoring Market Segmentation
Understanding the distinct segments within the drone inspection and monitoring market clarifies where specific technological advancements and operational requirements converge. This granular analysis highlights the varying demands across product types, sensor technologies, application areas, and end-user industries, guiding strategic investment.
Product Type:
The operational characteristics of drone platforms dictate their suitability for diverse inspection tasks and environments.
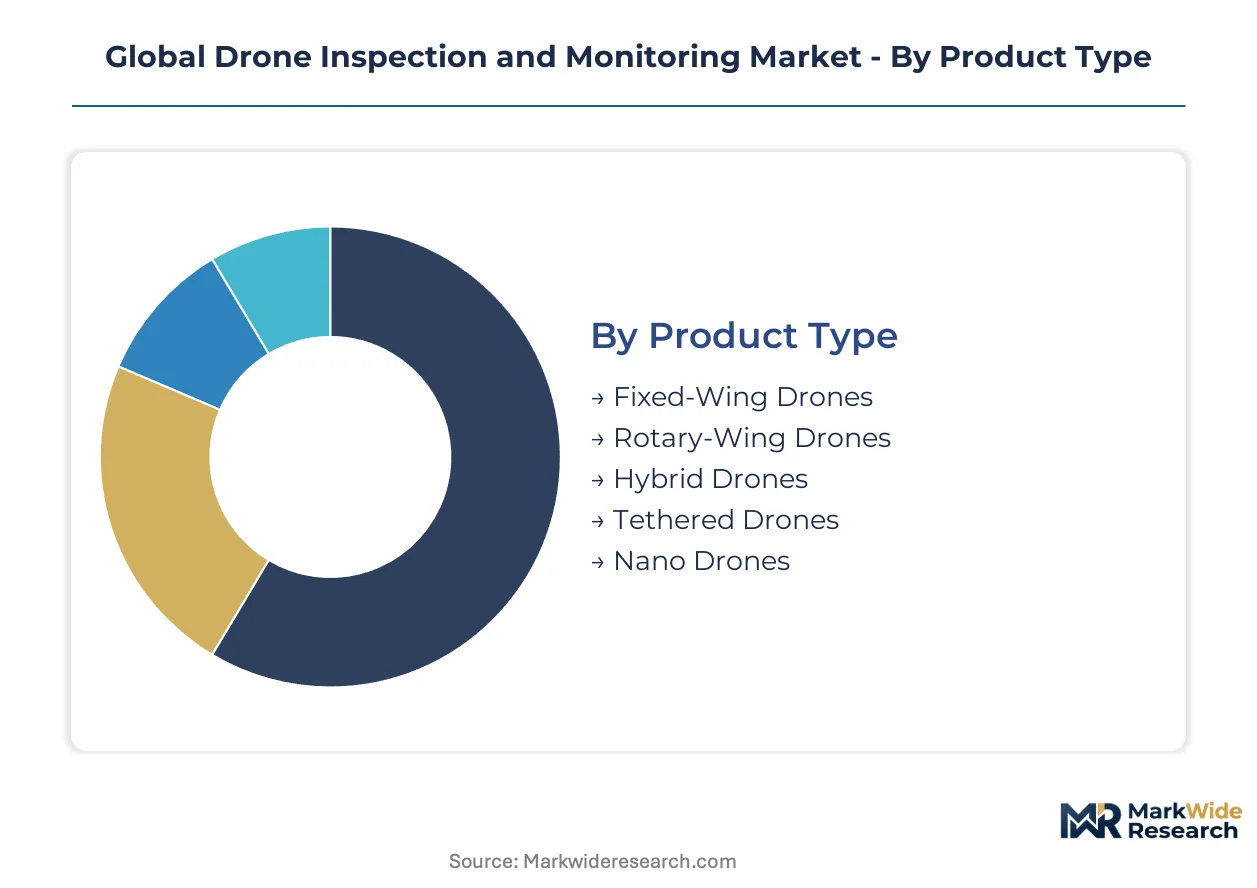
- Rotary-Wing Drones:These platforms feature multiple rotors, enabling vertical take-off and landing (VTOL), hovering capabilities, and precise maneuverability in confined or complex spaces. Infrastructure inspection and energy asset surveillance heavily utilize rotary-wing drones for their agility and stable data capture in close proximity to assets.
- Hybrid Drones:Hybrid models combine the VTOL capabilities of rotary-wing drones with the longer endurance and speed of fixed-wing designs, often using a tilt-rotor or convertible configuration. These systems are gaining traction for linear infrastructure inspections, such as pipelines and power lines, where extended flight times and versatile operational modes are critical for efficiency.
- Fixed-Wing Drones:These aircraft resemble traditional airplanes, offering superior endurance and speed for covering vast areas efficiently.
- Tethered Drones:Connected to a ground station via a physical cable, tethered drones provide continuous power and secure data transmission for extended, stationary surveillance.
- Nano Drones:Extremely small and lightweight, nano drones are designed for highly confined space inspections or discreet surveillance tasks where larger platforms cannot operate.
Rotary-Wing Drones leads on scale; Hybrid Drones leads on momentum.
Technology:
The type of sensor payload integrated into a drone system directly determines the quality and utility of the collected data for specific inspection objectives.
- LiDAR:Light Detection and Ranging technology uses pulsed laser light to measure distances and create highly accurate, three-dimensional models of objects and terrain. Infrastructure operators deploy LiDAR for precise volumetric measurements, vegetation encroachment analysis, and detailed digital twin creation.
- Thermal Imaging:These cameras detect infrared radiation, allowing for the visualization of heat signatures, which is crucial for identifying anomalies like hot spots, leaks, or insulation defects. Energy asset surveillance, particularly in oil and gas facilities, frequently employs thermal imaging for predictive maintenance and safety checks.
- Photogrammetry:This technique involves stitching together multiple overlapping photographs to create 2D maps or 3D models with high visual fidelity.
- Multispectral Imaging:Multispectral sensors capture data across several discrete spectral bands, providing insights into vegetation health and environmental changes beyond what is visible to the human eye.
- Hyperspectral Imaging:Capturing data across hundreds of narrow spectral bands, hyperspectral imaging offers highly detailed material identification and precise environmental monitoring capabilities.
The integration of advanced sensors defines competitive offerings within the market.
Application:
Drone inspection and monitoring solutions are tailored to address specific operational challenges and data requirements across various industrial and environmental contexts.
- Infrastructure Inspection:This segment involves using drones to assess the condition of bridges, roads, railways, and other civil structures for maintenance planning and safety compliance. Aging infrastructure in North America and Europe drives consistent demand for drone-based condition monitoring.
- Energy Asset Surveillance:Drones monitor critical energy infrastructure, including power lines, wind turbines, solar farms, and oil and gas pipelines, to detect faults, prevent outages, and ensure operational safety. Oil & Gas Operators extensively use drones for remote pipeline surveillance, minimizing human exposure to hazardous environments.
- Agriculture Monitoring:Drones equipped with specialized sensors collect data on crop health, irrigation efficiency, and pest detection for precision agriculture practices.
- Wildlife Conservation:UAVs assist in tracking animal populations, monitoring poaching activities, and surveying remote habitats to support conservation efforts.
- Construction Progress Tracking:Drones provide aerial views and data for site mapping, progress monitoring, and volumetric calculations on construction projects.
Maintenance requirements consistently drive infrastructure inspection volumes.
End User:
Different industries leverage drone technology to address unique inspection and monitoring needs, often driven by regulatory compliance, safety mandates, or efficiency gains.
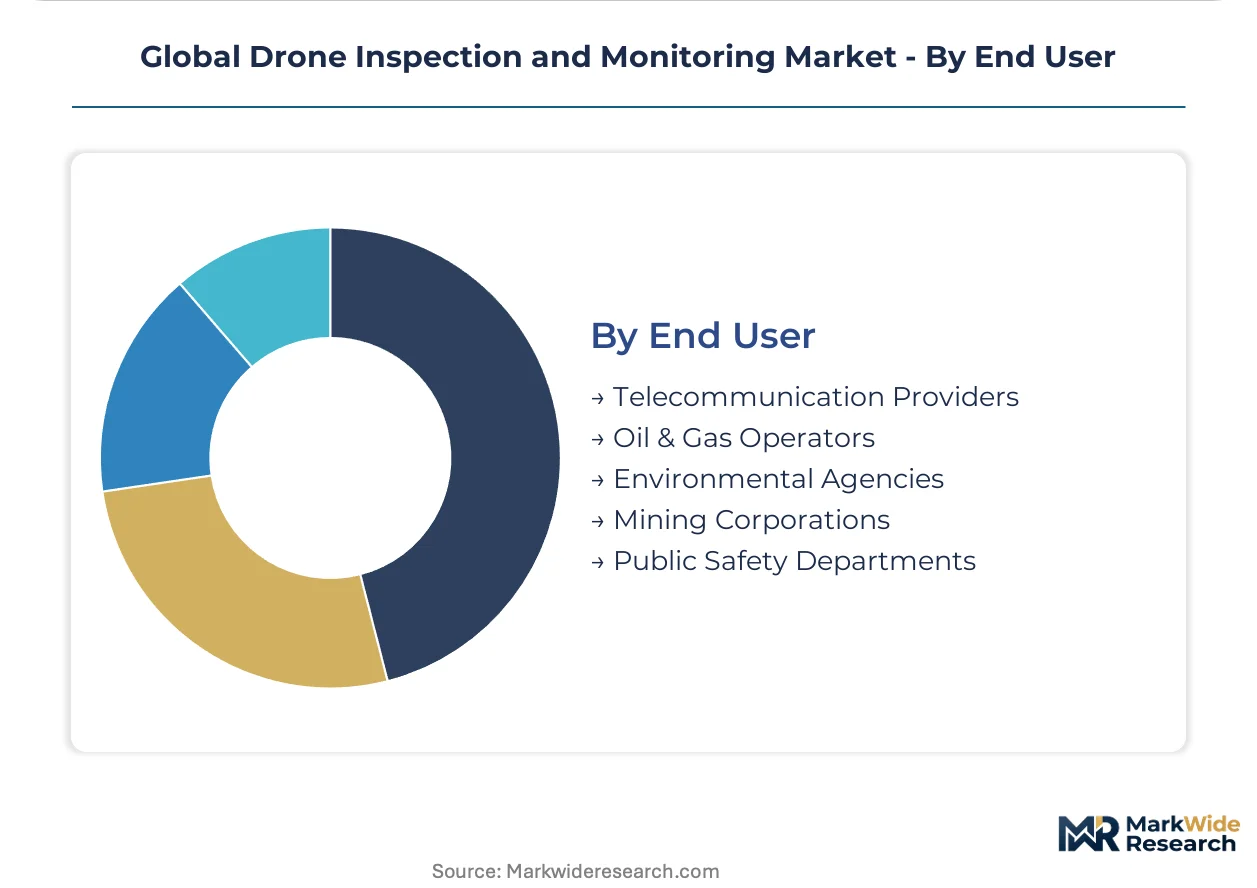
- Oil & Gas Operators:This sector utilizes drones for inspecting extensive pipeline networks, offshore platforms, storage tanks, and flare stacks, reducing human risk in hazardous environments. Stringent safety regulations from bodies like OSHA in the United States mandate comprehensive inspection protocols, favoring drone deployment.
- Telecommunication Providers:Drones inspect cell towers, communication infrastructure, and remote antenna sites, often in challenging terrains, to identify maintenance needs and ensure network uptime. The need for rapid deployment and reduced climber risk drives adoption across global telecom networks.
- Environmental Agencies:These organizations use drones for monitoring pollution, assessing ecological changes, and conducting surveys for habitat management and compliance.
- Mining Corporations:Drones perform tasks such as stockpile volume measurement, pit mapping, and equipment inspection in open-pit and underground mining operations.
- Public Safety Departments:Law enforcement, fire departments, and emergency services deploy drones for situational awareness, search and rescue operations, and incident response.
Industrial sectors with extensive remote assets represent the largest demand pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Canada both exhibit strong demand for drone inspection, driven by extensive infrastructure and remote assets requiring continuous monitoring. European nations like Germany also show significant adoption, focusing on advanced regulatory frameworks. Emerging markets in the Middle East and Oceania are rapidly integrating drone solutions for critical sectors.
United States
Extensive linear infrastructure and a large oil and gas sector drive significant demand for drone inspection services. The U.S. Federal Aviation Administration (FAA) refines Beyond Visual Line of Sight (BVLOS) regulations, expanding operational envelopes. In Texas, drone operations concentrate around oil and gas fields for pipeline and facility monitoring, enhancing safety.
Canada
Vast, remote asset bases in mining and energy sectors create substantial demand for drone inspection across Canada. Transport Canada's evolving regulatory framework supports BVLOS operations, crucial for long-distance infrastructure. Alberta's oil sands region sees concentrated drone deployment for large-scale industrial site monitoring and environmental compliance.
Germany
Industrial automation initiatives and critical energy infrastructure propel drone inspection adoption within Germany. The European Union Aviation Safety Agency (EASA) U-space framework significantly influences operational standards for urban and industrial drone flights. The Ruhr region, with its dense industrial assets, utilizes drones for predictive maintenance and safety inspections.
Australia
Large-scale mining operations and extensive remote infrastructure, including railways and pipelines, are major demand drivers in Australia. The Civil Aviation Safety Authority (CASA) actively develops rules for commercial drone operations, facilitating broader adoption. Western Australia's mining regions deploy drones for stockpile management and asset integrity checks.
Saudi Arabia
Massive oil and gas infrastructure and ambitious new construction projects fuel significant drone inspection demand in Saudi Arabia. The General Authority of Civil Aviation (GACA) establishes clear guidelines for commercial drone use, supporting industrial applications. The Eastern Province, central to the nation's oil production, heavily utilizes drones for comprehensive facility surveillance and pipeline monitoring.
Global Drone Inspection and Monitoring Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the drone inspection market. The market structure exhibits a tiered consolidation, with large aerospace and defense contractors operating alongside specialized hardware and software providers. Strategic archetypes include integrated solution providers, niche technology developers, and comprehensive service firms. Companies primarily engage in strategic partnerships for technology integration and geographic expansion to broaden their market reach.
Integrated solution providers like DJI leverage their dominant hardware position to offer complete drone ecosystems, spanning from flight platforms to data processing software. Specialized firms such as Skydio exemplify innovation in AI-powered autonomous flight, reducing operational complexity for users. Flyability, on the other hand, occupies a niche in collision-tolerant drones, addressing unique inspection challenges in confined spaces. These companies collectively demonstrate the market's emphasis on both broad platform capabilities and highly specific application-driven solutions.
| Leading Market Players |
|---|
| Easy Aerial |
| MISTRAS Group |
| Skydio |
| Lockheed Martin Corporation |
| Intertek Group |
| DJI |
| Azur Drones |
| Intel Corporation |
| Flyability |
Cost & Logistics Intelligence
Industrial safety mandates, particularly from OSHA in the United States, gate qualified drone inspection supply and access to premium-tier pricing. Compliance requirements demand highly certified platforms and operators, creating barriers for entry.
Pricing Analysis
Capacity additions in North America for Drone-as-a-Service providers are reshaping price floors for routine inspections. The dominant pricing structure shifts towards subscription-based DaaS, bundling hardware, software, and certified pilots. Price differentiation stems from specialized sensor payloads like Optical Gas Imaging cameras and the level of BVLOS certification. Pricing pressure stems from the high capital expense of advanced payloads, particularly for smaller inspection service providers, while Oil & Gas Operators exhibit lower price sensitivity for critical asset surveillance.
Supply Chain Analysis
Regional distribution centers for drone hardware and specialized payloads facilitate localized service delivery and support across key markets. Drone manufacturing concentrates in China, the United States, and Switzerland, reflecting distinct technology specializations. The industry depends on critical raw materials and components, including high-fidelity sensors, specialized batteries, and AI processing chips. Single-source vulnerability for advanced sensor components represents a structural supply chain risk, with distribution running through direct sales and value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by AI-powered analytics creating opportunities for predictive maintenance platforms and premium service tiers.
For Market Incumbents:Lock in existing client relationships by expanding subscription-based Drone-as-a-Service offerings that integrate advanced data analytics. Invest in BVLOS certification and full-stack platform development to counter the threat from AI-first competitors focusing on specific verticals. Deepen integration with enterprise asset management systems to solidify value propositions.
For New Entrants and Emerging Players:Specialized system integrators offer a viable channel to penetrate underpenetrated geographies, such as the agricultural sector in Southeast Asian nations. Focus on niche applications like environmental monitoring or construction progress tracking with AI-powered analytics. Offer flexible DaaS models to minimize upfront client investment and accelerate adoption.
For Investors and Strategic Acquirers:Roll-up economics work for BVLOS-certified service providers because high compliance barriers fragment the service landscape. Long-term viability rests on the increasing demand for infrastructure inspection and environmental monitoring. Target acquisition archetypes include niche technology developers specializing in AI or advanced sensor integration. A key signal to watch is the broader adoption and standardization of Unmanned Traffic Management (UTM) systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Autonomous Platforms | This innovation reduces pilot cognitive load and enhances data consistency for repeatable inspections. |
| Expand Subscription-Based DaaS Offerings | This model lowers client's upfront costs and provides recurring revenue streams for service providers. |
| Secure BVLOS Regulatory Certifications | Regulatory compliance expands operational envelopes for linear infrastructure inspection over vast areas. |
| Form Strategic Partnerships with UTM Providers | Integration with UTM systems ensures compliant and safe operations in controlled airspace. |
| Invest in Specialized Sensor Miniaturization | Shrinking sensor size enables more agile drone platforms for detailed asset analysis. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary and secondary research. Primary research involved discussions with drone service providers, enterprise asset managers, sensor developers, and aviation regulators. Secondary data sources included aviation authority publications, technology patent databases, corporate financial reports, and industry trade publications. This approach facilitated bottom-up market sizing and top-down validation.
Segment-weighting across product types, technologies, applications, and end-users formed the basis of the forecast model over the projection horizon. CAGRs were derived from historical trends, expert input, and projected adoption rates for drone solutions. Industry-specific forecast inputs included BVLOS regulation timelines, global infrastructure spending, and sensor miniaturization trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts and technological disruptions. Forecasts reflect assumptions regarding market dynamics and competitive shifts across the modeling period. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Fuel Cell UAV Market
UAV
Solar-Powered UAV Market
UAV
Drone Delivery Services Market
UAV
Drone Payload Market
UAV
Global Smartphone Controlled Drone Market
UAV
Asia-Pacific Tactical UAV Market
UAV
Global Target Drone Market
UAV
Global Aerial Imaging Market
UAV
UAV Lidar Market
UAV
Drone Inspection Service Market
UAV
Drone Wireless Charging Station Market
UAV
Auto-Follow Drone Market
UAV
Asia Pacific Small UAV Market
UAV
Portable Drone Market
UAV
US Commercial Drone Market
UAV
FPV Drone Goggles Market