
 US Commercial Drone Market | 2026-2036
US Commercial Drone Market Size, Share, and Industry Trends Forecast 2026-2036
US Commercial Drone Market Insights
Buyer concentration across agricultural cooperatives and utility providers is restructuring procurement patterns toward fleet-scale unmanned aerial system contracts. Skydio, Inc. leverages autonomous flight stacks to dominate public safety and defense channels. AeroVironment, Inc. sustains vertical integration across airframe design and ground control stations for military-adjacent commercial applications. PrecisionHawk, Inc. specializes in agronomic analytics platforms that anchor recurring software revenue beyond hardware sales.
US commercial drones encompass unmanned aerial vehicles operating below FAA altitude ceilings for commercial data collection, payload delivery, and remote sensing missions. These systems integrate GPS navigation, lithium-polymer power architectures, and composite airframes to execute automated flight paths with sub-meter positional accuracy across industrial, agricultural, and public safety missions. Fixed-wing configurations lead long-range surveying missions where endurance exceeds rotary-wing alternatives, while multi-rotor systems capture infrastructure inspection demand through vertical takeoff precision in confined airspace. AI integration and thermal imaging represent the fastest-expanding technology layers, with Lidar-equipped hybrid platforms commanding premium positioning in topographic mapping segments where point-cloud density determines contract awards.
FAA Part 107 regulations, BVLOS waiver frameworks, and Remote ID mandates shape operational scope, pilot certification requirements, and airspace access tiers for commercial operators. OSHA standards intersect with drone deployment in construction and energy inspection workflows, creating compliance checkpoints that influence platform selection and training protocols. Stakeholders must monitor FAA reauthorization trajectories and state-level privacy legislation to anticipate operational boundary shifts before committing to fleet infrastructure investments.
Market Dynamics
FAA Part 107 expansions and BVLOS waiver frameworks are compressing operational approval timelines, pulling utility providers and agricultural cooperatives toward fleet-scale unmanned system procurement faster than airspace management infrastructure can adapt.
Growth Catalysts
- Texas energy corridor deployment:Utility providers in the Permian Basin and Gulf Coast refining zones are standardizing drone-based pipeline inspection protocols, creating repeatable demand templates for thermal-equipped rotary-wing fleets.
- FAA Remote ID mandates:The 2024 enforcement deadline is forcing legacy fleet obsolescence, generating replacement cycles for compliant platforms with integrated broadcast modules and encrypted telemetry architectures.
- Lithium-polymer energy density gains:Solid-state battery prototypes are extending multi-rotor endurance past 90 minutes, enabling single-flight corridor surveys that previously required multiple battery swaps and ground crew rotations.
Market Restraints
- Sensor payload cost concentration:Thermal imaging cores and Lidar modules remain concentrated among Japanese and German component suppliers, exposing integrators to yen-euro volatility and 12-16 week lead times.
- BVLOS waiver friction:FAA case-by-case approval processes for beyond-visual-line-of-sight operations create 4-8 month certification delays that stall fleet deployment schedules for agricultural spraying and linear infrastructure inspection.
- Pilot certification bottlenecks:Part 107 remote pilot license throughput limits operator supply, constraining scaling velocity for cooperatives seeking to internalize drone operations rather than contract third-party service providers.
Strategic Opportunities
- Florida infrastructure hub penetration:Post-hurricane grid hardening programs are creating dedicated funding streams for automated transmission tower inspection, with municipal utilities piloting subscription-based analytics rather than capital-intensive hardware ownership.
- AI-driven predictive maintenance convergence:Machine learning platforms processing drone-captured thermal data are enabling failure prediction 30-60 days ahead of visible degradation, opening recurring software revenue streams beyond equipment sales.
- California agricultural valley consolidation:Central Valley water district mandates for precision irrigation compliance are driving cooperative-level fleet procurement, with shared-ownership models spreading capital burden across multiple growing operations.
Industry Challenges
- Airspace deconfliction skill scarcity:Operators capable of integrating UTM (Unmanned Traffic Management) protocols with legacy manned aviation systems command 40% wage premiums, constraining workforce scaling for multi-drone command centers.
- Platform-software integration complexity:Agricultural analytics providers face 6-9 month API harmonization cycles when connecting proprietary flight control stacks to third-party agronomic databases, delaying time-to-revenue for new deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Commercial Drone Market |
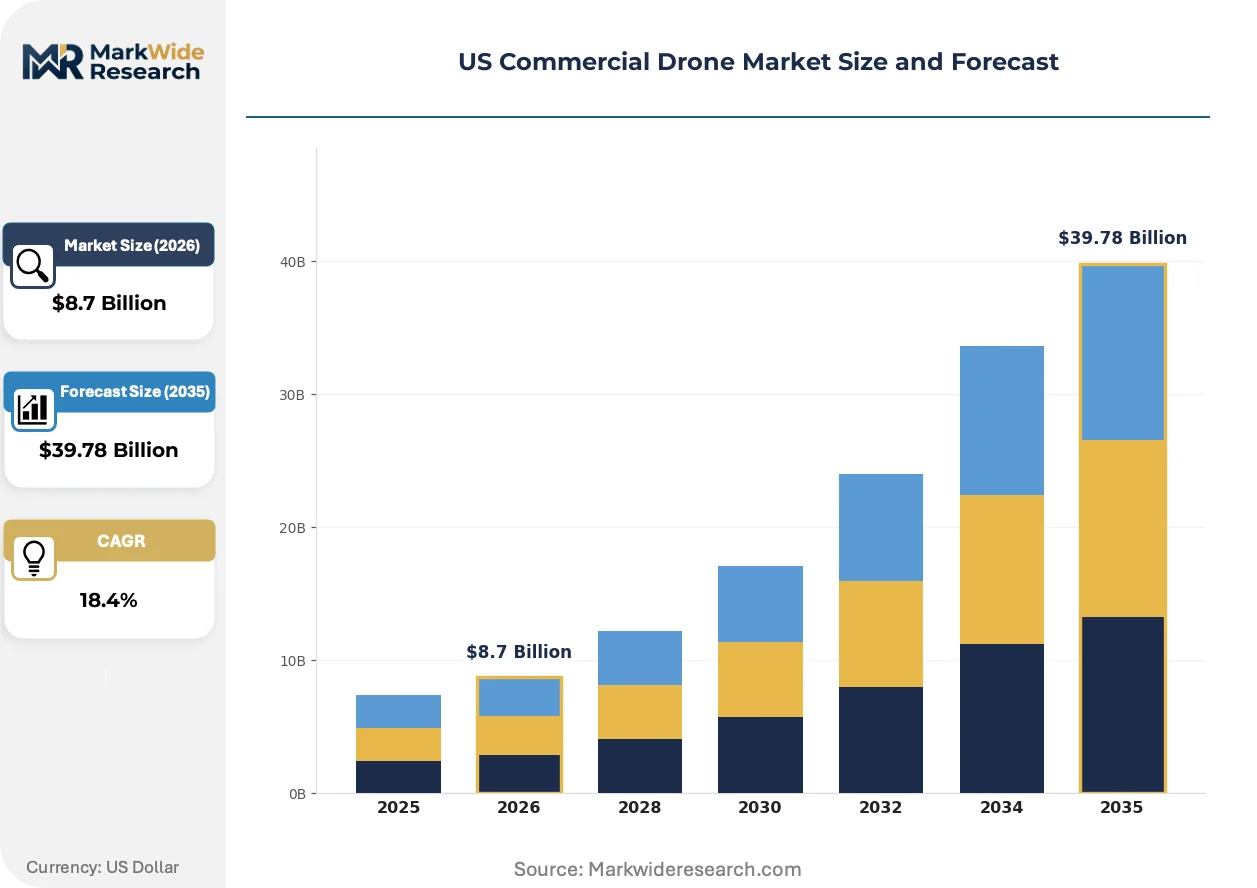
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Infrastructure Inspection, Aerial Photography, Surveying End User: Agricultural Sector, Construction Firms, Real Estate Agencies, Insurance Companies Type: Fixed-Wing, Rotary-Wing, Hybrid, Multi-Rotor Technology: GPS Navigation, AI Integration, Lidar, Thermal Imaging |
| Companies Covered | AeroVironment, Inc., Skydio, Inc., PrecisionHawk, Inc., Freefly Systems Inc., Ascent Aerosystems, BRINC, Inspired Flight Technologies, Inc., Parrot, Matternet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Commercial Drone Market Trends and Innovations
Autonomous flight architectures are compressing the pilot-to-aircraft ratio from 1:1 to 1:many, while thermal-Lidar sensor fusion and outcome-based service contracting are restructuring how buyers capture value from unmanned aerial data collection.
Edge-computing inference engines are converging with onboard NVIDIA Jetson modules to enable real-time defect classification during flight, eliminating ground-station processing delays. Oil and gas inspection teams in the Permian Basin are deploying these configurations for immediate anomaly flagging on pipeline right-of-ways. The technology is converging with 5G private network slices to stream annotated video to distributed command centers, collapsing decision latency from hours to seconds.
FAA reauthorization negotiations are embedding counter-UAS authority expansions that clarify law enforcement interception protocols near critical infrastructure. This regulatory development is accelerating public safety agency procurement of detect-and-respond systems alongside their primary drone fleets. Texas and Florida municipal departments are prioritizing platforms with integrated Remote ID verification and automated geofencing to preempt airspace violation liabilities.
Utility procurement officers are unbundling hardware acquisition from data analytics subscriptions, treating drone platforms as sensor carriers while outsourcing insight generation to specialized software vendors. This purchasing pattern shift is displacing vertically integrated system vendors in favor of modular, API-first architectures. The restructuring is most visible among California agricultural cooperatives and Midwestern electric membership corporations seeking to convert capital expenditures into operational line items.
US Commercial Drone Market Segmentation
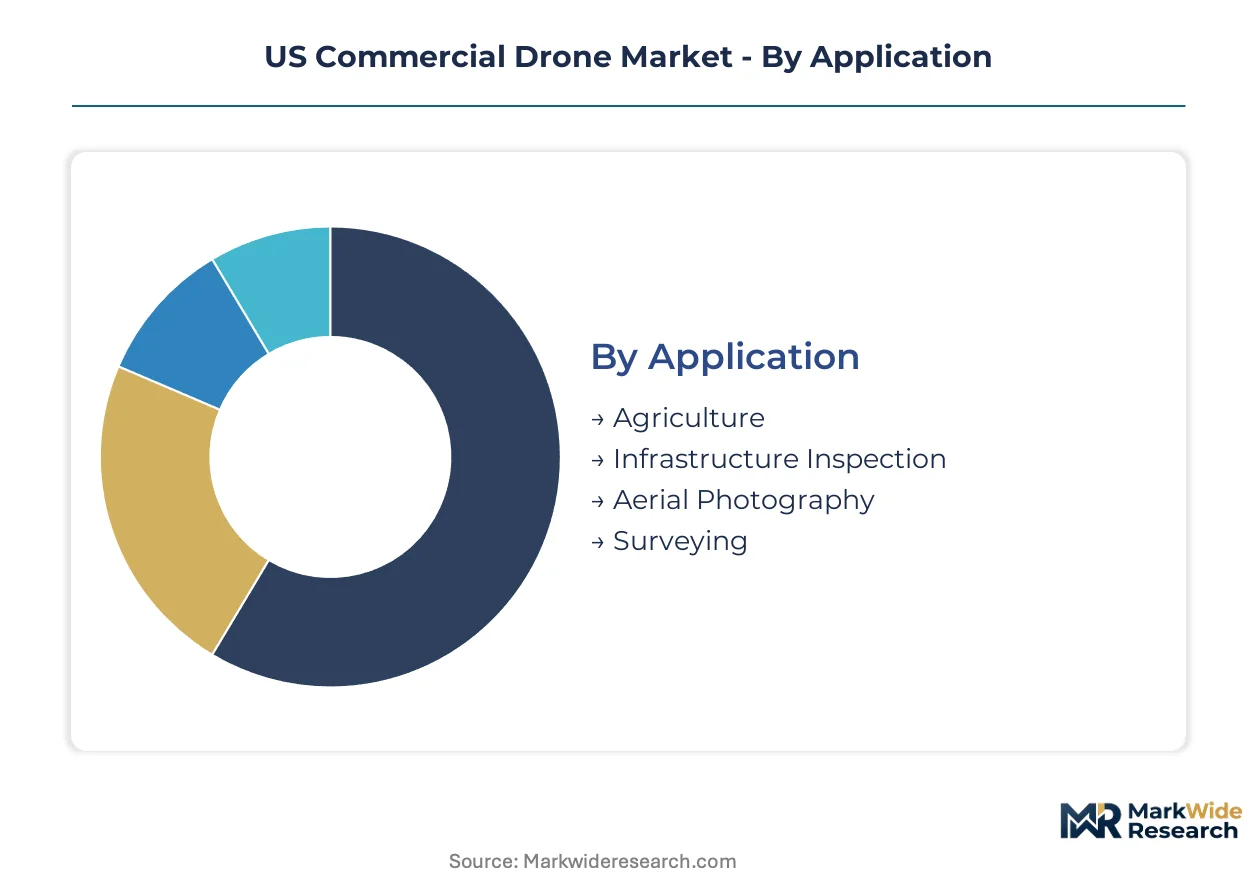
US commercial drone procurement patterns diverge sharply between high-volume commodity applications and premium sensor-integrated deployments. Fleet operators select configurations based on endurance requirements, payload precision, and regulatory compliance tiers rather than hardware specifications alone.
Application:
Volume-driven segments dominate current procurement, while premium analytics-enabled applications capture expanding software attach rates.
- Agriculture:Multi-spectral imaging platforms with NDVI analytics process crop health data across Central Valley irrigation districts. Water district compliance mandates in California are accelerating cooperative fleet procurement for precision moisture monitoring.
- Infrastructure Inspection:Thermal-equipped rotary-wing systems execute automated transmission tower surveys with sub-centimeter positional accuracy. Texas utility providers in the Permian Basin are standardizing these protocols for pipeline right-of-way monitoring.
- Aerial Photography:High-resolution cinema-grade platforms serve real estate marketing and commercial film production with gimbal-stabilized 6K+ capture.
- Surveying:Lidar-equipped fixed-wing configurations generate dense point clouds for topographic mapping and construction site volumetrics.
Today's leader: Infrastructure Inspection. Tomorrow's challenger: Agriculture.
End User:
Customer type determines procurement modality—capital purchase versus subscription analytics—with risk tolerance shaping platform sophistication tiers.
- Agricultural Sector:Cooperatives favor shared-ownership models spreading hardware costs across multiple growing operations. FAA Part 107 pilot certification bottlenecks are pushing these buyers toward third-party service contracts rather than internalized operations.
- Construction Firms:OSHA compliance requirements intersect with drone deployment protocols, creating mandatory training checkpoints that influence vendor selection criteria.
- Real Estate Agencies:Lightweight multi-rotor systems capture property marketing imagery with minimal regulatory overhead.
- Insurance Companies:Catastrophe response teams deploy rapid-assessment fleets for post-disaster claims verification, prioritizing portability over sensor sophistication.
Construction Firms anchor current equipment sales. Insurance Companies are gaining share fastest through outcome-based damage assessment contracts.
Type:
Airframe geometry dictates operational envelope—endurance versus maneuverability tradeoffs that segment buyers by mission profile rather than industry vertical.
- Fixed-Wing:Extended endurance platforms with 90+ minute flight times dominate linear infrastructure surveys across expansive Texas energy corridors. Solid-state battery prototypes are compressing the endurance gap with rotary alternatives.
- Rotary-Wing:Single-rotor helicopters carry heavier sensor payloads for precision agriculture and detailed structural inspection where hover stability matters.
- Hybrid:VTOL configurations with fixed-wing cruise efficiency are commanding premium positioning in topographic mapping segments requiring both range and landing flexibility.
- Multi-Rotor:Quadcopter and hexacopter architectures capture confined-space infrastructure inspection demand through vertical takeoff precision in urban airspace.
Multi-Rotor systems dominate unit volume. Hybrid platforms show the steepest expansion trajectory as BVLOS waivers extend operational range requirements.
Technology:
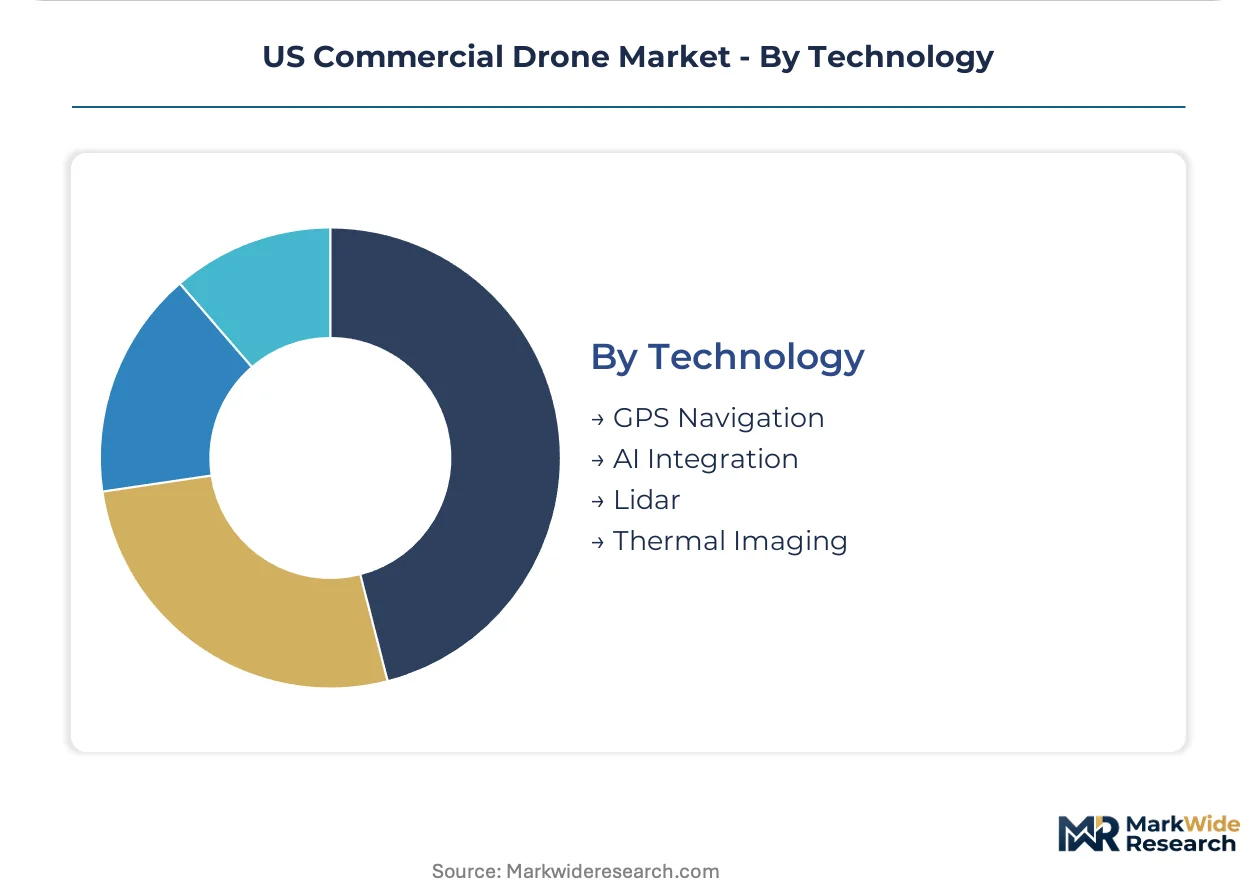
Technology layer selection separates commodity hardware buyers from analytics-driven service providers, with AI integration and thermal imaging commanding the widest pricing spreads.
- GPS Navigation:RTK-GNSS correction systems enable sub-meter positional accuracy for surveying and automated flight path execution. All commercial platforms now integrate this as baseline capability rather than premium tier.
- AI Integration:Edge-computing inference engines with NVIDIA Jetson modules perform real-time defect classification during flight, eliminating ground-station processing delays for oil and gas inspection teams.
- Lidar:Solid-state laser scanning modules generate dense point clouds for topographic mapping and volumetric measurement, though Japanese and German component concentration exposes integrators to currency volatility.
- Thermal Imaging:Infrared cores detect heat signatures for electrical fault prediction and pipeline leak identification, with failure prediction windows extending 30-60 days ahead of visible degradation.
GPS Navigation is universal baseline. AI Integration is climbing the fastest as software revenue models displace hardware-centric sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified Part 107 remote pilots concentrate in Texas, California, and Florida, anchoring operational capacity for utility and agricultural fleet deployments across the contiguous United States.
Texas
Permian Basin energy operators deploy thermal-equipped rotary-wing fleets for pipeline right-of-way monitoring under FAA Part 107 waivers. The Texas Railroad Commission coordinates with FAA Dallas-Fort Worth air traffic control to streamline BVLOS approvals for linear infrastructure surveys. Houston refining complexes and Gulf Coast petrochemical corridors generate concentrated demand for automated flare stack inspection.
California
Central Valley agricultural cooperatives procure multi-spectral imaging platforms to meet water district precision irrigation mandates. California Department of Water Resources regulations require sub-meter moisture monitoring compliance across 9 million irrigated acres. Fresno County and Kern County growing operations pilot shared-ownership fleet models spreading capital costs across multiple farms.
Florida
Post-hurricane grid hardening programs fund automated transmission tower inspection by municipal utilities. Florida Public Service Commission directives prioritize resilience investments in storm-prone regions. Tampa Bay and Miami-Dade infrastructure hubs test subscription-based analytics contracts converting hardware purchases to operational expenditures.
Pacific Northwest
Timber and hydroelectric operators in Oregon and Washington deploy fixed-wing platforms for expansive corridor surveys across rugged terrain. FAA Seattle field offices process BVLOS waivers for forestry management missions over remote watersheds. Columbia River Basin hydropower maintenance teams integrate Lidar-equipped VTOL systems for dam structure monitoring.
Southwest
Arizona and New Mexico mining operations adopt autonomous flight stacks for stockpile volumetrics and tailings pond surveillance. OSHA mining safety inspectors coordinate drone deployment protocols for open-pit hazard assessment. Phoenix-area copper extraction sites standardize thermal inspection for processing equipment heat signature monitoring.
US Commercial Drone Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing, flight control software, and data analytics layers. Market structure tilts toward vertical specialization, with distinct competitive sets forming around defense-adjacent platforms, autonomous navigation stacks, and agronomic software services. Three archetypes dominate: vertically integrated airframe-to-software providers, modular hardware-agnostic analytics platforms, and mission-specific system integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves, as scale constraints in sensor procurement drive alliance formation.
Within the autonomous navigation tier, Skydio, Inc. exemplifies AI-native flight control specialization, while AeroVironment, Inc. occupies a position spanning military-adjacent commercial applications with integrated ground control architectures. PrecisionHawk, Inc. anchors the analytics-first archetype, representing the shift toward recurring software revenue models beyond equipment sales. These three California and Virginia-based entities collectively illustrate the geographic clustering of drone innovation around defense procurement corridors and agricultural technology hubs.
| Leading Market Players |
|---|
| AeroVironment, Inc. |
| Skydio, Inc. |
| PrecisionHawk, Inc. |
| Freefly Systems Inc. |
| Ascent Aerosystems |
| BRINC |
| Inspired Flight Technologies, Inc. |
| Parrot |
| Matternet |
| Others |
Pricing and Supply Chain Analysis
FAA Remote ID compliance mandates are forcing legacy fleet obsolescence, compelling integrators to absorb encrypted telemetry module costs and pass through premium positioning to buyers seeking certified platforms.
Pricing Analysis
Capacity additions in domestic battery assembly are reshaping price floors for multi-rotor platforms, compressing margins on entry-level units while thermal-Lidar configurations maintain premium-mid-economy pricing differentiation. Price differentiation hinges on sensor payload certification tier and after-sales analytics bundling. Pricing pressure stems from agricultural cooperative procurement consolidation favoring shared-ownership models. Construction firms exhibit highest price sensitivity; defense-adjacent buyers show lowest.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Los Angeles anchor hub-and-spoke fulfillment patterns for component procurement and finished platform delivery. Lithium-polymer cells draw from South Korea and Japan; thermal imaging cores and solid-state Lidar modules source from Germany and Japanese suppliers. Single-source vulnerability in precision sensor procurement exposes integrators to yen-euro volatility and extended lead cycles. Distribution runs through authorized dealer networks and direct OEM contracts for fleet-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on solid-state battery cost-down curves and software attach-rate growth in predictive maintenance analytics.
For Market Incumbents: Anticipate modular hardware-agnostic platforms displacing vertically integrated system vendors as utility procurement officers unbundle hardware from analytics subscriptions. Defend position through backward integration into flight control software stacks and FAA certification investment for BVLOS-ready platforms. Prioritize API-first architectures over captive sensor integration.
For New Entrants and Emerging Players: Direct-to-cooperative digital channels bypass incumbent dealer networks and compress customer acquisition costs for agricultural analytics providers. White-space targets include Central Valley shared-ownership fleet management and Florida municipal utility subscription contracting. Penetrate through outcome-based service models converting capital expenditures to operational line items.
For Investors and Strategic Acquirers: Asymmetric upside sits with autonomous navigation software specialists possessing FAA waiver track records and defense procurement relationships. Long-term viability favors platforms with recurring software revenue models over hardware-dependent vendors. Monitor FAA reauthorization counter-UAS authority expansions as regulatory inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Flight Stack Development | Skydio's AI-native navigation compresses pilot-to-aircraft ratios from 1:1 to 1:many in public safety deployments. |
| Sensor Payload Integration | Thermal-Lidar fusion enables 30-60 day failure prediction windows for Permian Basin pipeline operators. |
| API-First Platform Architecture | Modular analytics integration accelerates time-to-revenue for agricultural cooperative deployments. |
| BVLOS Certification Investment | FAA waiver frameworks unlock linear infrastructure inspection contracts across Texas energy corridors. |
| Subscription Analytics Pivot | Software revenue models displace hardware-centric sales among California water district compliance buyers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with FAA certification specialists, utility fleet procurement officers, agricultural cooperative managers, and drone systems integrators with secondary validation against FAA Part 107 waiver databases, EIA energy infrastructure investment records, and California Department of Water Resources compliance filings. Bottom-up platform shipment estimates and top-down addressable market sizing were triangulated for convergence.
Segment-weighted modeling applied differential growth assumptions across fixed-wing, rotary-wing, multi-rotor, and hybrid airframe categories; GPS navigation, AI integration, Lidar, and thermal imaging technology layers; and agriculture, infrastructure inspection, aerial photography, and surveying applications. CAGRs were derived from logistic diffusion curves fitted to adoption data across the projection horizon. Forecast inputs incorporated solid-state battery prototype commercialization timelines and FAA BVLOS waiver approval velocity.
Regulatory reauthorization delays, sensor supply chain disruptions, and pilot certification throughput constraints are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Bubble Drone Market
UAV
Anti-Drone Market
UAV
Global Renewable Drones Market
UAV
North America Small UAV Market
UAV
Small Drone Market
UAV
North America Drones Market
UAV
Auto-Follow Drone Market
UAV
Europe Drone Light Shows Market
UAV
UAV Drones Market
UAV
Aerial Smart Weapons Market
UAV
Nano Drones Market
UAV
Racing Drone Market
UAV
Drone Telematics Market
UAV
Portable Drone Market
UAV
Autonomous Aircraft Cameras Market
UAV
Drone Camera Market