
 Solar-Powered UAV Market | 2026-2036
Solar-Powered UAV Market Size, Share, and Industry Trends Forecast 2026-2036
Solar-Powered UAV Market Outlook
Software-defined mission planning is hardening as a recurring revenue layer atop hardware sales. Titan Aerospace leverages its stratospheric platform heritage to anchor long-duration communications relay contracts. Boeing sustains defense-sector relationships through integrated solar-electric demonstrators. Silent Falcon UAS Technologies specializes in tactical ISR packages for special operations forces.
A solar-powered unmanned aerial vehicle harvests photovoltaic energy through thin-film or crystalline silicon arrays mounted on wings and fuselage surfaces, converting sunlight to electric propulsion with endurance measured in days rather than hours. Fixed-wing configurations dominate commercial and military deployments due to superior lift-to-drag ratios and expansive surface area for cell integration. Defense applications within the end-user dimension command premium pricing and multi-year procurement cycles, while rotary-wing platforms remain nascent but attract agricultural spraying interest for precision crop management.
FAA Part 107 waivers and EASA drone regulation frameworks govern commercial airspace access, with military operators operating under separate national defense authorizations. ISO 21384-3 unmanned aircraft system standards and emerging EU AI Act provisions for autonomous decision-making will reshape product certification requirements. Stakeholders must monitor evolving beyond-visual-line-of-sight rulemakings across multiple jurisdictions to align R&D roadmaps with operational clearance timelines.
Market Dynamics
Defense procurement cycles for persistent surveillance platforms are compressing certification timelines while stretching supplier capacity, forcing hardware manufacturers to embed software-defined mission layers that extend contract durations beyond airframe delivery.
Growth Catalysts
- Beyond-Visual-Line-of-Sight Rulemakings:FAA Part 107 waiver expansions and EASA drone regulation amendments are unlocking commercial airspace access for extended-duration operations, accelerating platform certification investments.
- NATO Persistent Surveillance Demand:Defense ministries across member states are expanding multi-year procurement of stratospheric relay and border patrol platforms, anchoring long-duration production contracts.
- Thin-Film Photovoltaic Integration:Advanced flexible solar cell arrays are achieving higher energy density per wing surface area, enabling multi-day endurance without ground infrastructure dependency.
Market Restraints
- Airworthiness Certification Friction:EASA's evolving standards for autonomous decision-making and FAA's case-by-case waiver processing create timeline uncertainty for commercial operators.
- Battery Energy Density Ceiling:Lithium-sulfur and solid-state storage technologies remain below the threshold for reliable overnight stratospheric operations, constraining mission profiles.
- Specialized Manufacturing Concentration:Crystalline silicon array fabrication for aerospace-grade specifications clusters with limited qualified suppliers, creating input bottleneck risk.
Strategic Opportunities
- Precision Agriculture Spraying:Rotary-wing solar platforms are penetrating crop management applications where chemical payload precision and reduced ground compaction outweigh endurance limitations.
- EU AI Act Autonomy Provisions:Emerging frameworks for certifying autonomous navigation systems will create first-mover advantage for compliant mission planning software vendors.
- Telecommunications Relay White Space:Stratospheric platform-as-a-service models are displacing terrestrial tower infrastructure in remote terrain coverage gaps across Australia and Canada.
Industry Challenges
- Multi-Jurisdictional Certification Burden:ISO 21384-3 unmanned aircraft system standards require parallel compliance investments across FAA, EASA, and national defense authorization frameworks.
- Aerospace-Photovoltaic Talent Scarcity:The intersection of aerostructures engineering and photovoltaic systems design lacks established training pathways, constraining R&D team scaling.
- Legacy Communications Integration:Military and border security agencies require backward compatibility with existing command-and-control networks, adding software architecture complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar-Powered UAV Market |
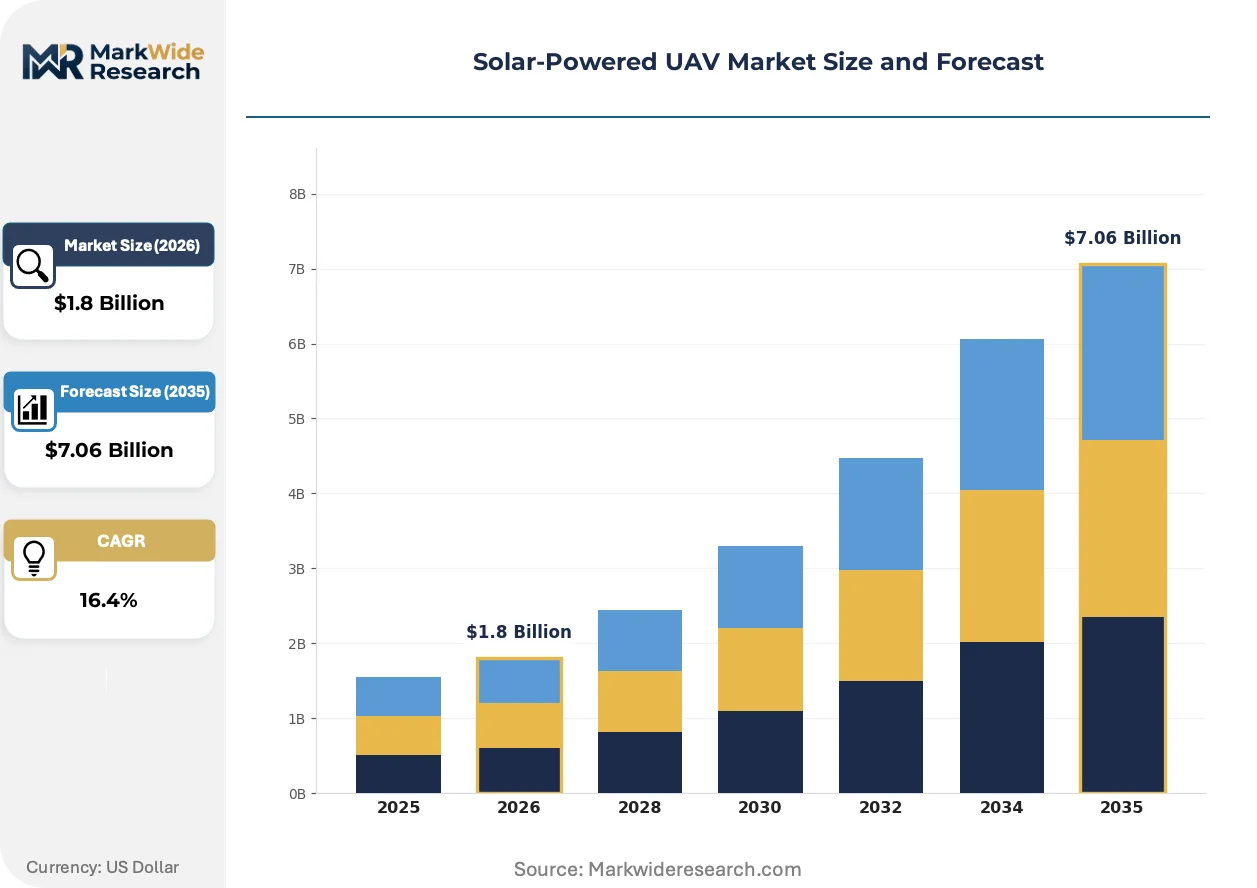
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Wing, Rotary Wing, Hybrid, Micro End User: Agriculture, Defense, Telecommunications, Surveying Application: Surveillance, Mapping, Search & Rescue, Delivery Technology: Solar Cells, Lightweight Materials, Autonomous Navigation, Data Processing |
| Companies Covered | Titan Aerospace, Atlantik Solar, Airbus, VisionWave Holdings, Silent Falcon UAS Technologies, Boeing, Bye Aerospace, Edge Autonomy, AeroVironment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar-Powered UAV Market Strategic Shifts
Software-defined mission architectures are decoupling revenue from hardware shipment cycles, enabling persistent surveillance contracts to generate recurring income through over-the-air capability updates and data analytics subscriptions.
Perovskite tandem solar cell technology is converging with flexible substrate manufacturing to achieve 30% higher conversion efficiency in stratospheric radiation conditions. Defense procurement offices are piloting these arrays on demonstrator platforms ahead of full-rate production decisions. The structural consequence is compressing the performance gap between thin-film and crystalline silicon, forcing incumbent suppliers to accelerate R&D timelines or cede high-altitude contracts.
EASA's drone regulation framework amendments are mandating detect-and-avoid capability for beyond-visual-line-of-sight operations above 120 meters. Commercial operators must retrofit or redesign platforms to satisfy these provisions, diverting engineering resources from endurance optimization. Agricultural spraying and infrastructure inspection segments in Germany and France are experiencing the steepest compliance cost increases.
Border security agencies are consolidating vendor relationships around integrated platform-service bundles rather than discrete airframe purchases. The Department of Homeland Security and comparable agencies in Australia are demanding bundled maintenance, data processing, and personnel training within single-contract structures. This compression of the procurement cycle is visible most acutely in North American and Asia-Pacific defense sectors, where multi-year indefinite-delivery vehicles are displacing annual appropriation requests.
Solar-Powered UAV Market Segmentation
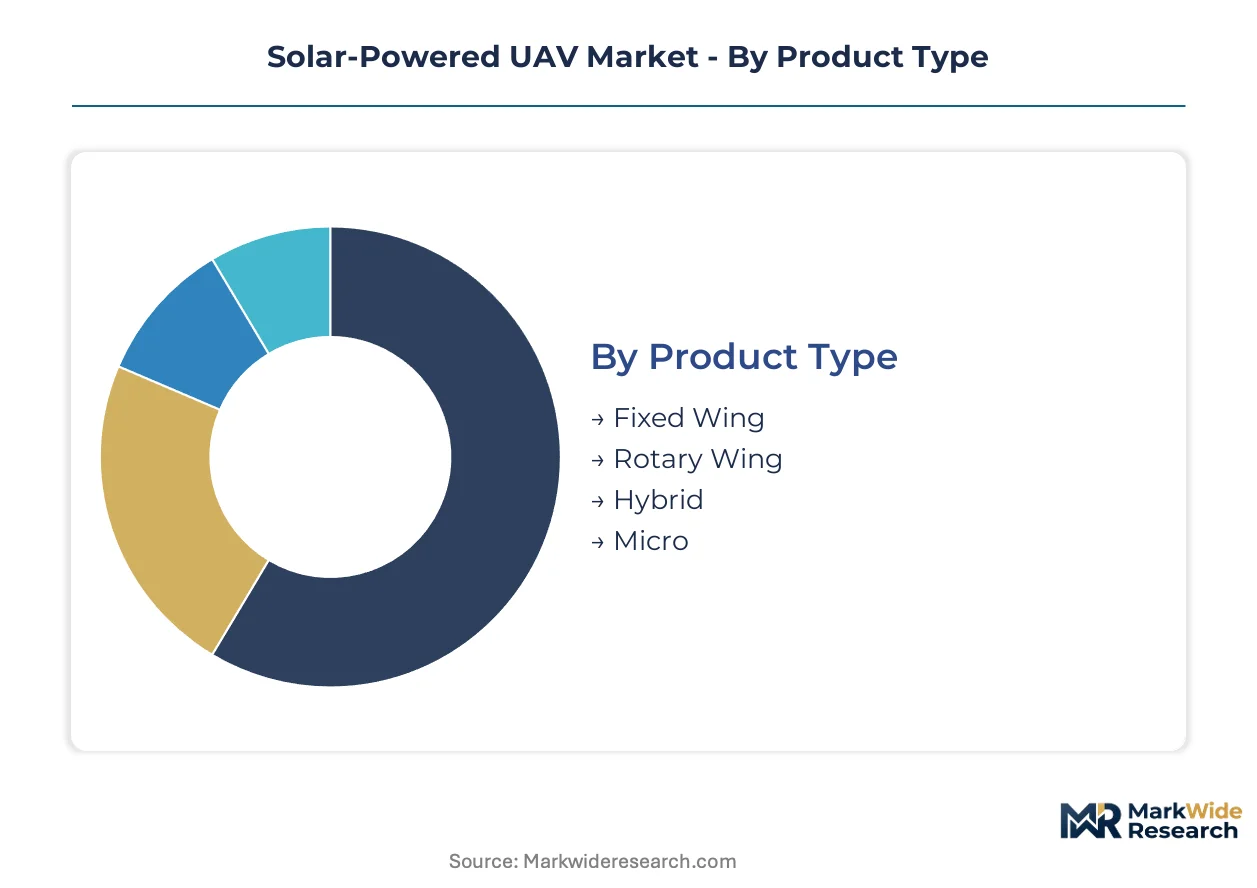
Segmentation in the solar-powered UAV market reveals distinct capital requirements and operational profiles that shape procurement patterns. Fixed-wing platforms demand substantial upfront engineering investment but deliver superior endurance economics, while rotary and hybrid configurations target specialized mission sets with differentiated value propositions.
Product Type:
Capital intensity varies sharply across airframe architectures, with wing surface area and photovoltaic integration complexity driving development timelines and tooling costs.
- Fixed Wing:High-aspect-ratio wings maximize photovoltaic cell coverage and lift-to-drag performance, enabling multi-day stratospheric missions. Defense ministries in the United States and NATO member states concentrate procurement here for persistent surveillance and communications relay, though airframe certification cycles stretch supplier balance sheets.
- Rotary Wing:Vertical takeoff capability eliminates runway dependency and enables precision hover for agricultural spraying and infrastructure inspection. Demand clusters in Australia and France where vineyard and utility corridor applications justify premium platform costs despite reduced endurance.
- Hybrid:Combines fixed-wing transit efficiency with rotary hover capability for complex terrain operations. Specialized search-and-rescue contracts in Switzerland and Canada favor this architecture.
- Micro:Hand-launched platforms with minimal photovoltaic surface rely on ultra-lightweight construction for short-duration tactical reconnaissance.
Fixed Wing absorbs the bulk of installed capacity; Hybrid configurations are expanding most quickly as mission planners seek operational flexibility without deploying multiple platform types.
End User:
Customer procurement sophistication determines contract structures, with defense and telecommunications buyers demanding integrated service bundles while agricultural purchasers prioritize discrete hardware acquisition.
- Defense:Multi-year indefinite-delivery vehicles from the Department of Homeland Security and comparable agencies anchor production volumes. Stratospheric relay and border patrol missions require FAA and EASA certification alignment alongside national defense authorization frameworks, extending sales cycles but securing recurring revenue through software-defined capability layers.
- Telecommunications:Stratospheric platform-as-a-service models displace terrestrial infrastructure in remote coverage gaps across Australia and Canada. Telstra and rural Canadian operators pilot long-duration relay contracts with performance-based pricing tied to uptime metrics.
- Agriculture:Precision crop management in France and Germany drives rotary-wing adoption for chemical application with reduced soil compaction.
- Surveying:Geospatial mapping contracts in Switzerland and Norway exploit extended loiter times for high-resolution terrain capture.
Defense commands the dominant share of contract value; Telecommunications is climbing the fastest as regulatory frameworks mature for beyond-visual-line-of-sight commercial operations.
Application:
Mission duration requirements and payload sophistication create tiered performance specifications that filter platform selection across use cases.
- Surveillance:Persistent area monitoring demands maximum endurance and autonomous navigation reliability. Border security agencies in the United States and Australia specify detect-and-avoid capabilities compliant with evolving EASA amendments above 120 meters, diverting engineering resources from pure range optimization.
- Mapping:Photogrammetric accuracy requirements drive sensor integration complexity and data processing throughput specifications. Swiss and Norwegian geospatial contractors prioritize lightweight LiDAR payloads with real-time orthomosaic generation.
- Search & Rescue:Rapid deployment and thermal imaging integration dominate procurement criteria for alpine and maritime emergency services.
- Delivery:Last-mile medical and supply logistics in remote Canadian and Australian communities test payload-weight tradeoffs against solar charging intervals.
Surveillance retains the largest operational fleet; Search & Rescue is gaining share fastest as alpine and coastal agencies consolidate vendor relationships around integrated platform-service bundles.
Technology:
Component-level innovation determines competitive differentiation, with photovoltaic efficiency and autonomous decision-making architectures attracting disproportionate R&D investment.
- Solar Cells:Perovskite tandem arrays achieving 30% conversion efficiency in stratospheric radiation conditions are compressing the performance gap between thin-film and crystalline silicon. Defense procurement offices in the United States pilot these on demonstrator platforms ahead of production decisions.
- Autonomous Navigation:EASA's EU AI Act provisions for certifying autonomous decision-making systems are reshaping software architecture requirements. First-mover compliance creates vendor advantage in German and French commercial markets.
- Lightweight Materials:Carbon-fiber composite airframes reduce structural mass to extend payload or endurance margins.
- Data Processing:Edge computing architectures enable real-time analytics without ground station dependency, critical for beyond-visual-line-of-sight regulatory compliance.
Solar Cells command the steepest R&D allocation; Autonomous Navigation is accelerating fastest as multi-jurisdictional certification frameworks converge on AI governance standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of photovoltaic arrays and airframe composites clusters in China and Germany, while platform integration and defense procurement concentrate in the United States and NATO member states. Demand for persistent surveillance capabilities is compressing supplier lead times across multiple jurisdictions.
United States
Defense procurement from the Department of Homeland Security and border security agencies anchors platform demand. FAA Part 107 waiver expansions govern beyond-visual-line-of-sight commercial operations, creating certification investment pressure. Colorado and California host stratospheric platform development clusters where Titan Aerospace and Boeing maintain demonstration facilities.
Germany
Precision agriculture spraying in Bavarian and Rhineland vineyards drives rotary-wing adoption for chemical application. EASA drone regulation amendments mandate detect-and-avoid capabilities above 120 meters, diverting engineering resources from endurance optimization. Stuttgart and Munich engineering clusters specialize in autonomous navigation software compliant with emerging EU AI Act provisions.
France
Geospatial mapping contracts in the Alps and vineyard regions exploit extended loiter times for high-resolution terrain capture. ANSM and CNIL oversight intersects with EASA frameworks for autonomous system certification. Toulouse aerospace suppliers integrate perovskite tandem solar cells into demonstrator platforms ahead of production decisions.
Australia
Telstra pilots stratospheric platform-as-a-service models to displace terrestrial tower infrastructure in remote coverage gaps. The country's national aviation regulator processes beyond-visual-line-of-sight waivers for extended-duration operations. Queensland and Western Australia host agricultural spraying deployments where reduced soil compaction justifies premium platform costs.
Switzerland
Alpine search-and-rescue agencies consolidate vendor relationships around integrated platform-service bundles for rapid deployment scenarios. Swissmedic and federal aviation oversight align with EASA frameworks for autonomous navigation certification. Zurich and Geneva engineering clusters specialize in hybrid airframe architectures combining fixed-wing transit with rotary hover capability.
Solar-Powered UAV Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the solar-powered UAV market. The vendor base separates between integrated defense contractors with airframe fabrication capabilities and specialized mission software vendors with recurring revenue models. Three archetypes dominate: stratospheric platform specialists anchoring telecommunications relay contracts, tactical ISR package providers serving special operations forces, and hybrid agricultural platform developers penetrating precision spraying applications. Consolidation pressure is accelerating through multi-year indefinite-delivery vehicles that bundle maintenance and data processing within single-contract structures.
Within the stratospheric platform tier, Titan Aerospace and Boeing exemplify capital-intensive positioning through long-duration communications relay heritage. Silent Falcon UAS Technologies occupies a specialized position in tactical ISR packages for defense applications. These three companies anchor distinct competitive vectors—atmospheric endurance, integrated defense relationships, and mission-specific payload integration—while EASA and FAA certification timelines filter market entry across all archetypes.
| Leading Market Players |
|---|
| Titan Aerospace |
| Atlantik Solar |
| Airbus |
| VisionWave Holdings |
| Silent Falcon UAS Technologies |
| Boeing |
| Bye Aerospace |
| Edge Autonomy |
| AeroVironment |
| Others |
Value Chain & Pricing Dynamics
Certification-grade stratification between FAA Part 107 waiver-compliant platforms and experimental demonstrators manifests in divergent pricing architectures and sourcing footprints. Premium-tier fixed-wing systems command multi-year contract structures with embedded software layers, while agricultural rotary platforms trade at transactional hardware margins with limited aftermarket attachment.
Pricing Analysis
Margin tightening in stratospheric relay platforms reflects EASA detect-and-avoid retrofit requirements diverting engineering resources from endurance optimization. Three-tier pricing structure across defense-grade, commercial-certified, and experimental tiers segments buyer archetypes, with telecommunications operators least price-sensitive due to infrastructure displacement economics and vineyard operators in France and Germany most sensitive to capital recovery timelines. Pricing pressure intensifies in agricultural segments as Chinese photovoltaic array suppliers compress component costs.
Supply Chain Analysis
Domestic-content mandates in Australian defense procurement and US Department of Homeland Security indefinite-delivery vehicles are reshaping final assembly footprints toward customer-proximate integration. Crystalline silicon array fabrication concentrates in China and Germany, carbon-fiber airframe pre-preg draws from Japan and the United States, and solid-state battery development rests on South Korean and Japanese chemistry advances. Single-source vulnerability in aerospace-grade photovoltaic qualification creates input bottleneck risk. Distribution runs through defense procurement offices, telecommunications carriers, and agricultural equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perovskite tandem solar cell technology is displacing crystalline silicon in stratospheric demonstrators, compressing supplier R&D timelines and reshaping competitive positioning across the forecast horizon.
For Market Incumbents: Deepen backward integration into flexible substrate manufacturing to secure perovskite tandem cell supply ahead of defense production decisions. Lock in multi-year indefinite-delivery vehicles with Australian and Canadian telecommunications carriers before regulatory frameworks mature for new entrants. Anchor certification investment in EASA EU AI Act compliance to create software-defined mission planning moats.
For New Entrants and Emerging Players: Agricultural equipment dealers in Queensland and Western Australia represent the most penetrable channel for rotary-wing solar spraying platforms. Target precision viticulture contracts in France and Germany where reduced soil compaction justifies premium positioning. Pursue white-label manufacturing partnerships with established airframe fabricators to bypass FAA Part 107 certification timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in defense contractor acquisition of mission software vendors with recurring revenue models and EASA compliance certification. Long-term viability favors platforms with demonstrated stratospheric endurance and integrated data analytics subscriptions. Watch for FAA beyond-visual-line-of-sight rulemaking finalization as inflection indicator for commercial addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Tandem Cell Integration | Defense procurement offices in the United States pilot demonstrators ahead of production decisions. |
| EASA AI Act Compliance Certification | First-mover software vendors capture German and French commercial autonomy markets. |
| Platform-as-a-Service Bundling | Telstra and rural Canadian operators displace terrestrial tower infrastructure with uptime-based contracts. |
| Hybrid Airframe Architecture Development | Swiss alpine search-and-rescue agencies consolidate vendor relationships around integrated service bundles. |
| Detect-and-Avoid Capability Retrofit | Commercial operators above 120 meters divert engineering resources from pure endurance optimization. |
Study Parameters
Multi-period observation of FAA Part 107 waiver issuance patterns, EASA drone regulation amendment timelines, and defense procurement contract awards anchored the trend analysis, supplemented by interviews with stratospheric platform engineering directors, photovoltaic array procurement leads at airframe integrators, telecommunications network planning officers, and precision agriculture equipment dealers. Secondary validation drew from FAA regulatory dockets, EASA implementing acts, Department of Homeland Security contract announcements, and ISO 21384-3 unmanned aircraft system standards documentation. Bottom-up platform deployment estimates triangulated against top-down addressable market sizing by end-use segment.
Input-output matrices modeled fixed-wing, rotary, hybrid, and micro airframe architectures against defense, telecommunications, agriculture, and surveying end-user categories across the projection horizon. Photovoltaic cell technology tiers, autonomous navigation certification levels, and geographic regulatory clusters formed additional segmentation dimensions. CAGRs were derived from unit economics modeling of endurance-per-dollar metrics and contract value analysis of multi-year indefinite-delivery vehicles. Stratospheric radiation efficiency curves and battery energy density improvement trajectories informed technology adoption assumptions.
Caveats apply where FAA beyond-visual-line-of-sight rulemaking delays, EASA autonomous decision-making standard revisions, or lithium-sulfur battery commercialization failures could materially shift the outlook. Forecasts embed assumptions on photovoltaic conversion efficiency gains and defense procurement cycle compression that may diverge from realized trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Small Drone Market
UAV
Drone Payload Market
UAV
Drone-Based Consulting Services Market
UAV
GCC Drone Pilot Training Market
UAV
Global Smartphone Controlled Drone Market
UAV
North America Small UAV Market
UAV
Global Electric Drone Market
UAV
Drone-As-A-Service Market
UAV
UAV Simulator Software Market
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
North America Drone Software Market
UAV
Global Aerial Survey Services Market
UAV
Nano Drones Market
UAV
Global Drone Light Shows Market
UAV
Global Drone Services Market
UAV
UAV Simulator Market