
 Global Smartphone Controlled Drone Market | 2026-2036
Global Smartphone Controlled Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smartphone Controlled Drone Market Outlook
Lithium-polymer battery chemistry is consolidating as the dominant power architecture across mid-range smartphone-controlled drones, displacing heavier nickel-metal hydride packs that previously constrained flight endurance. DJI leverages captive cell sourcing and vertical assembly lines to sustain cost leadership in recreational and commercial tiers. Autel Robotics competes through R&D intensity focused on obstacle-avoidance algorithms. Skydio anchors its position in the North American enterprise segment with autonomous flight stacks optimized for infrastructure inspection workflows.
Smartphone-controlled drones are unmanned aerial vehicles where flight command, telemetry, and payload management route through iOS or Android interfaces rather than dedicated radio controllers, typically operating via Bluetooth, Wi-Fi, or LTE links with 2.4–5.8 GHz transmission bands and 15–45 minute endurance windows depending on battery configuration and payload mass. Their primary purpose spans aerial data capture, last-mile logistics prototyping, and automated surveillance across commercial and government contexts. Commercial drones occupy the deepest margin pools as enterprise buyers prioritize sensor integration and software ecosystems over unit cost. FPV systems represent the fastest-growing technology segment as real-time video streaming becomes standard even in sub-$500 consumer units. Agricultural drones remain a mature application category where pricing pressure from seasonal demand cycles limits vendor profitability.
The FAA's Remote ID rule and EASA's equivalent drone regulation framework mandate broadcast transponders on most operational categories, reshaping hardware design priorities and creating compliance barriers for uncertified imports. China's MIIT enforces GB-standard radio frequency allocations that affect transmission module certification for devices manufactured or sold domestically. ISO 21384-3 provides voluntary safety benchmarks that large enterprise procurement teams increasingly require. Stakeholders must monitor how fragmented national airspace classifications affect cross-border software update deployment and fleet management platform compatibility.
Market Dynamics
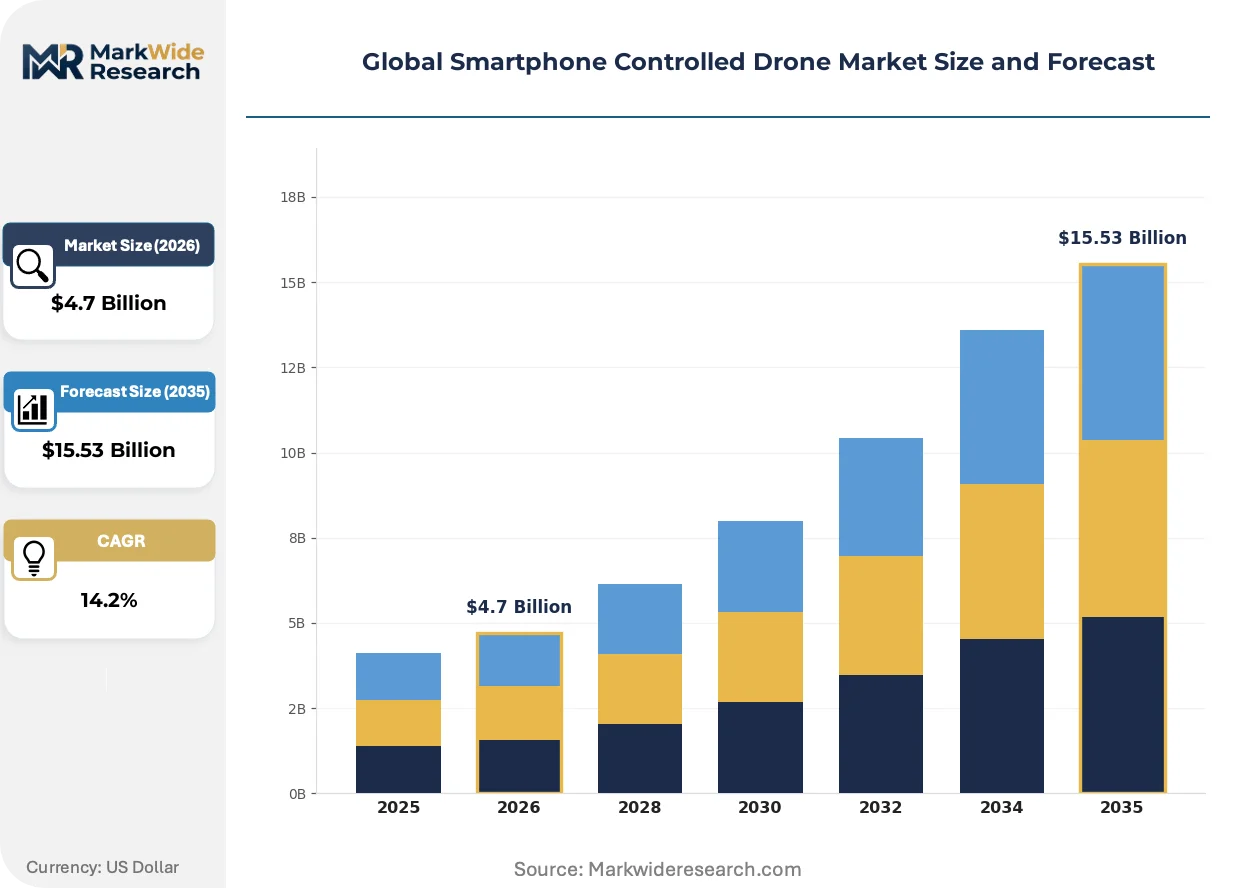
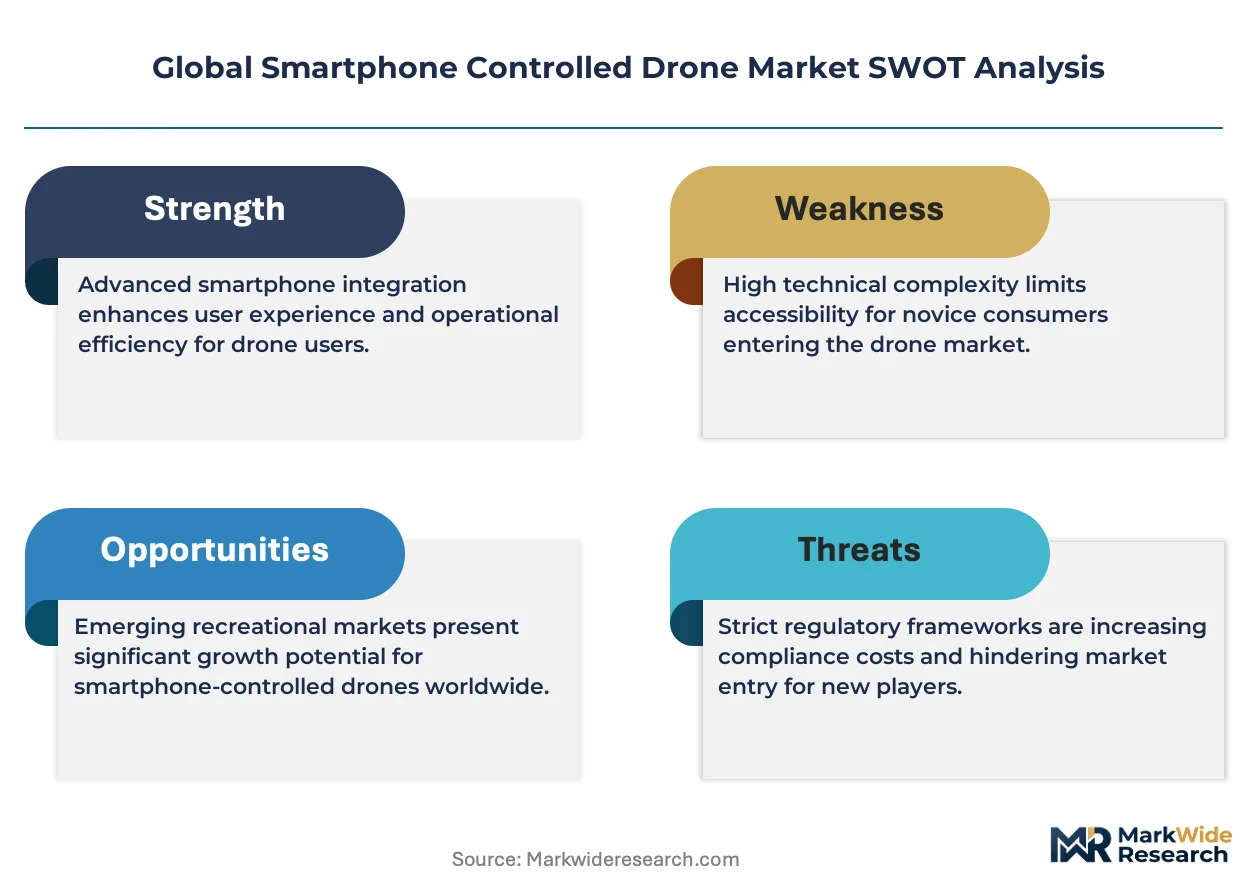
Remote ID mandates from the FAA and EASA are forcing hardware redesign cycles across the entire value chain, compressing certification timelines while creating compliance moats for certified manufacturers against uncertified imports.
Growth Catalysts
- Precision agriculture expansion:Agricultural enterprises in China and the United States are scaling drone fleets for crop monitoring and variable-rate input application, creating sustained replacement demand for smartphone-controlled platforms with integrated multispectral sensors.
- FAA Remote ID rule:The FAA's broadcast transponder mandate is accelerating hardware refresh cycles as operators replace legacy fleets to maintain airspace access, concentrating demand among certified domestic manufacturers.
- FPV streaming standardization:Real-time video transmission is modularizing down to sub-$500 consumer units, expanding the addressable market beyond hobbyists into casual content creators and small-scale inspection contractors.
Market Restraints
- Lithium-polymer supply concentration:Cell production concentrates in China and South Korea, exposing non-integrated assemblers to raw material allocation risk and freight cost volatility during supply shocks.
- Radio frequency fragmentation:China's MIIT enforces GB-standard allocations distinct from FCC and EASA bands, forcing module variants that inflate inventory carrying costs for global product lines.
- Flight endurance physics:Energy density limits in current battery chemistry cap practical mission duration below 45 minutes for payload-capable units, constraining viable use cases against tethered alternatives in persistent surveillance.
Strategic Opportunities
- Indian agricultural mechanization:India's PLI scheme for drone manufacturing offers tariff and subsidy advantages for local assembly operations targeting the country's fragmented smallholder farming base.
- 5G network slicing integration:Convergence between LTE drone control links and carrier-grade 5G latency guarantees is opening beyond-visual-line-of-sight operations for infrastructure inspection without dedicated ground station investment.
- EU AI Act compliance services:The EU AI Act's risk classification for autonomous flight systems creates advisory and software certification revenue streams for vendors bundling compliance tooling with hardware sales.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for real-time flight control and sensor fusion requires specialized talent pools concentrated in aerospace hubs, inflating R&D payroll costs for mid-tier competitors.
- Cross-border software deployment friction:Fragmented national airspace classifications complicate fleet management platform updates, forcing region-locked firmware branches that fragment development resources and delay security patches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smartphone Controlled Drone Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Drones, Recreational Drones, Racing Drones, Agricultural Drones End User: Photography, Agriculture, Delivery Services, Surveillance Technology: GPS Navigation, FPV Systems, Autonomous Flight, LTE Connectivity Application: Aerial Mapping, Infrastructure Inspection, Search & Rescue, Environmental Monitoring |
| Companies Covered | DJI, Parrot SA, Autel Robotics, Skydio, Yuneec International, 3DR, CONTIXO, Draganfly Innovations, Hubsan Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smartphone Controlled Drone Market Strategic Shifts
Flight control architecture is modularizing from monolithic autopilot stacks into separable perception, planning, and execution layers, enabling faster iteration and third-party software integration across price tiers.
Sensor payloads are modularizing from fixed gimbal assemblies to swappable mission-specific modules. Enterprise buyers in Germany and Japan are standardizing on quick-release mechanical and electrical interfaces that allow single airframes to switch between thermal, multispectral, and LiDAR configurations within minutes. This modularity is compressing fleet capital requirements as operators reduce airframe counts while expanding mission flexibility.
EASA's drone regulation framework is tightening operational category boundaries and mandating specific technical standards for certified operations. Hardware manufacturers serving European commercial operators must redesign power distribution and fail-safe systems to meet stricter airworthiness expectations. The framework is accelerating consolidation as smaller vendors lack capital for parallel certification tracks across multiple regulatory jurisdictions.
After-sales service unbundling is disrupting traditional distribution channels. Large agricultural cooperatives in the United States and Brazil are negotiating direct technical support contracts with manufacturers, bypassing regional dealers who previously captured margin on maintenance and training. This pattern is most visible in enterprise segments where fleet scale justifies dedicated field engineering relationships over standardized warranty terms.
Global Smartphone Controlled Drone Market Segmentation
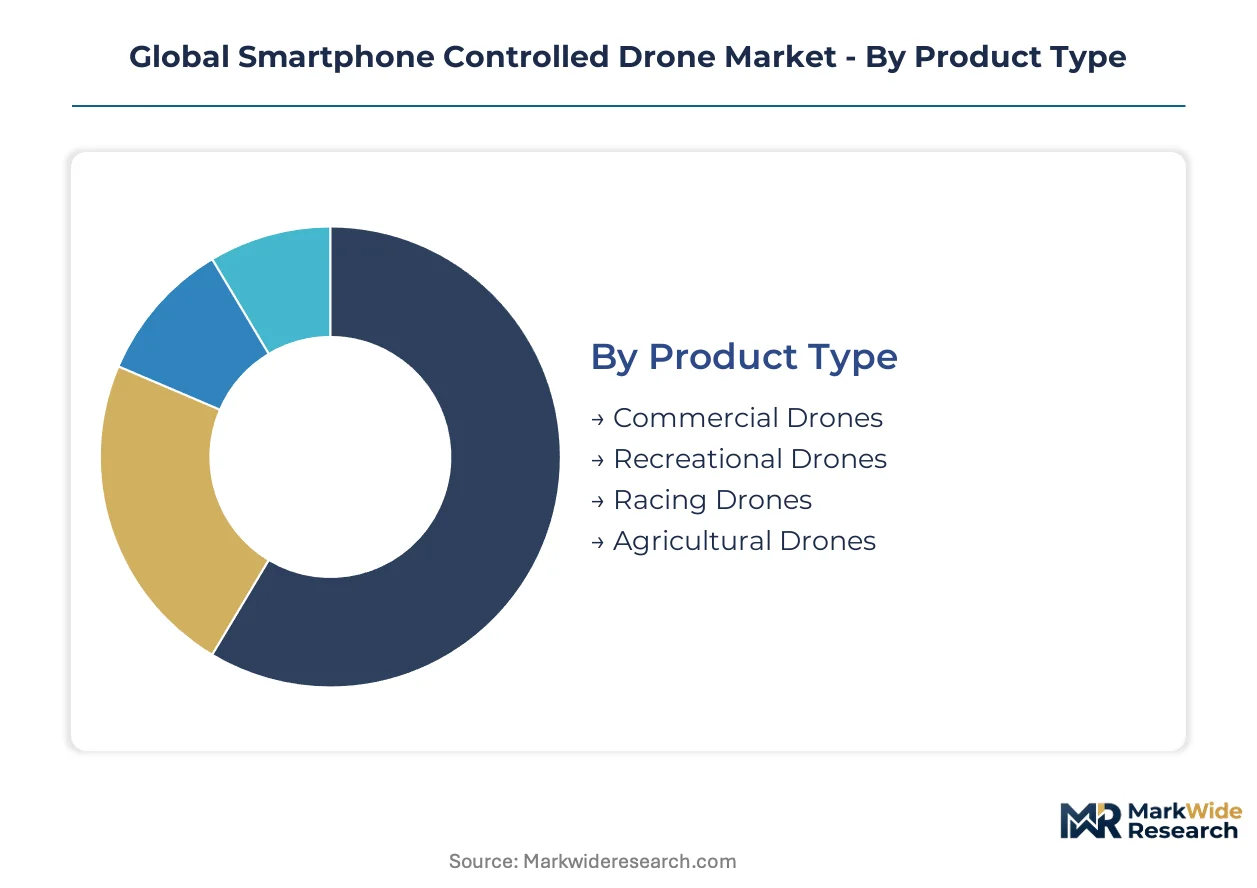
Smartphone-controlled drones serve divergent buyer priorities across product tiers, end-use verticals, and control architectures. Segmentation reveals where hardware margins concentrate and which technology transitions are compressing legacy categories.
Product Type:
Cost tier separates buyers seeking sensor integration from those prioritizing flight duration and unit economics.
- Commercial Drones:Enterprise-grade units carry multispectral and thermal payloads with 30-45 minute endurance. Demand clusters in Germany and Japan where infrastructure inspection contracts require certified airworthiness documentation.
- Recreational Drones:Sub-$500 units dominate unit shipments through consumer electronics retail. Casual content creators in the United States drive replacement cycles as FPV streaming becomes standard even at entry price points.
- Racing Drones:Lightweight carbon-fiber frames optimized for manual acrobatic control through low-latency radio links.
- Agricultural Drones:Spray-capable platforms with variable-rate dispersal systems for crop treatment applications.
Commercial drones lead volumes today; recreational drones are gaining share fastest.
End User:
Application maturity determines whether buyers prioritize software ecosystems or hardware durability.
- Photography:Stabilized gimbal systems with 4K video transmission for real estate and event documentation. Content creators in Brazil and Mexico are expanding addressable demand beyond traditional hobbyist bases.
- Agriculture:Multispectral imaging for crop health indexing and precision input application. Chinese cooperatives are scaling fleet deployments for rice and wheat monitoring across provincial growing regions.
- Delivery Services:Payload-optimized frames with redundant navigation for last-mile logistics prototyping.
- Surveillance:Persistent flight stacks with encrypted data links for perimeter monitoring applications.
Agriculture leads volumes today; delivery services are climbing the fastest.
Technology:
Control link architecture determines operational range and regulatory compliance requirements.
- GPS Navigation:Satellite-based positioning with waypoint programming for automated flight paths. Surveying contractors in Australia rely on RTK-corrected accuracy for cadastral mapping deliverables.
- FPV Systems:Real-time video transmission to smartphone screens or dedicated goggles. The FAA's Remote ID mandate is accelerating hardware refresh cycles as operators replace analog transmission legacy fleets.
- Autonomous Flight:Obstacle-avoidance algorithms enabling hands-off navigation in complex environments.
- LTE Connectivity:Cellular control links extending operational range beyond visual line of sight.
GPS navigation leads volumes today; LTE connectivity shows the steepest expansion trajectory.
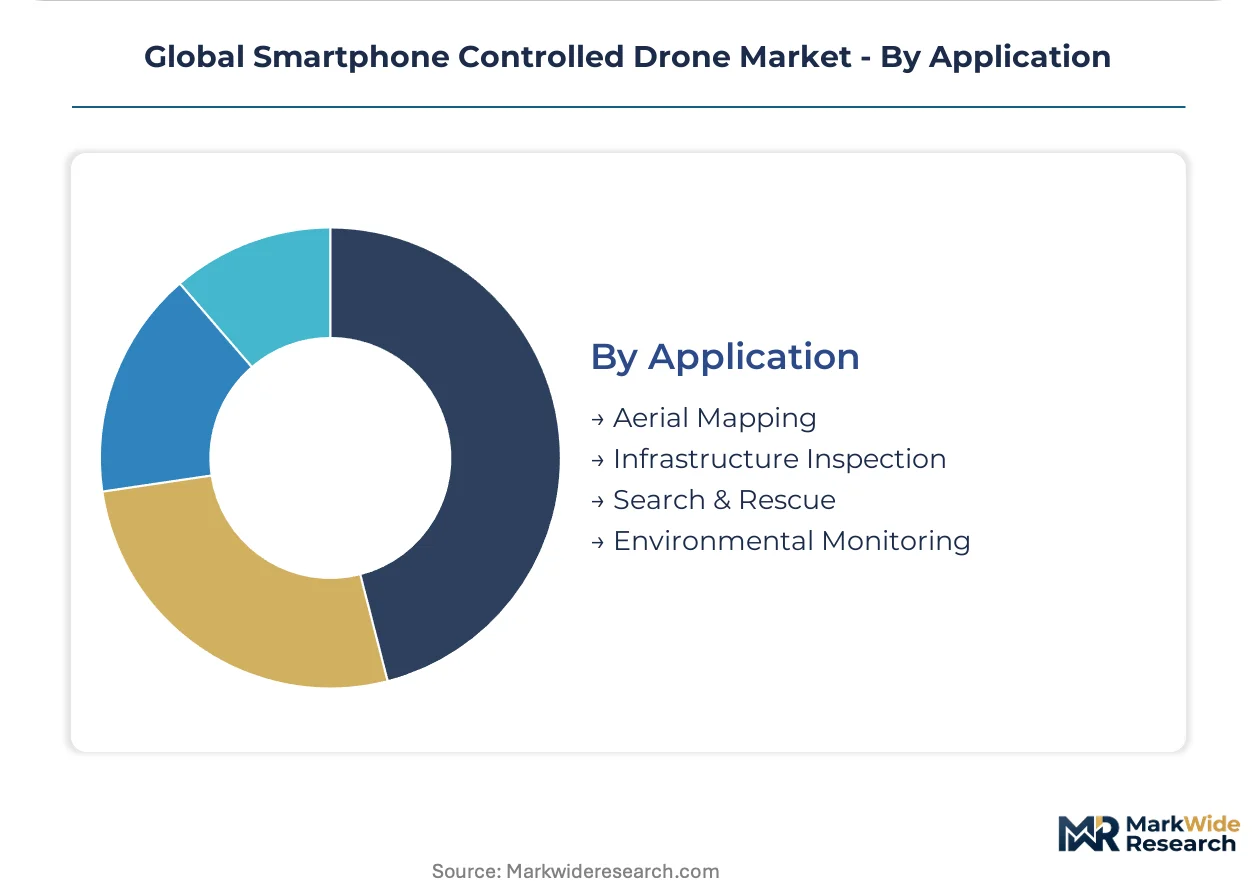
Application:
Mission duration requirements and payload flexibility separate inspection workflows from episodic deployment scenarios.
- Aerial Mapping:Photogrammetry-optimized sensor arrays for topographic survey and 3D reconstruction. Engineering firms in South Korea are standardizing drone-based surveying for construction progress monitoring.
- Infrastructure Inspection:Thermal and visual payload combinations for power line and pipeline assessment. German utility operators are mandating certified maintenance logs that favor established drone service providers.
- Search & Rescue:Thermal imaging and loudspeaker payloads for emergency response coordination.
- Environmental Monitoring:Air quality sensors and water sampling mechanisms for ecological data collection.
Infrastructure inspection leads volumes today; environmental monitoring is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors smartphone-controlled drone manufacturing through dense electronics supply chains and captive battery cell sourcing. The city's ecosystem feeds component flows to certified assemblers in Germany and the United States where enterprise demand concentrates.
China
Precision agriculture cooperatives in Jiangsu and Heilongjiang provinces are scaling multispectral drone fleets for rice and wheat monitoring. MIIT enforces GB-standard radio frequency allocations that force transmission module variants for domestic certification. Shenzhen's Bao'an district hosts the densest concentration of flight controller firmware houses serving both consumer and commercial tiers.
United States
Infrastructure inspection contractors across Texas and California are mandating FAA Remote ID-compliant hardware for utility corridor assessments. The FAA's broadcast transponder rule is compressing replacement cycles as operators retire analog transmission legacy fleets. Skydio's Redwood City engineering base anchors autonomous flight stack development for North American enterprise segments.
Germany
Engineering firms in Bavaria and North Rhine-Westphalia are standardizing drone-based surveying for construction progress monitoring and cadastral mapping deliverables. EASA's drone regulation framework mandates specific technical standards for certified commercial operations. Munich's technical university clusters feed embedded systems talent into flight control firmware development pipelines.
India
Agricultural cooperatives in Maharashtra and Karnataka are piloting variable-rate spray drones for cotton and sugarcane operations. The PLI scheme for drone manufacturing offers tariff and subsidy advantages for local assembly operations. Bangalore's aerospace engineering services sector is expanding firmware validation capabilities for export-oriented manufacturers.
Japan
Surveying contractors in Tokyo and Osaka prefectures rely on RTK-corrected GPS accuracy for infrastructure inspection workflows. METI's industrial standards framework shapes procurement specifications for enterprise drone fleets. Nagoya's precision manufacturing belt supplies quick-release payload interfaces for modular sensor configurations.
Global Smartphone Controlled Drone Market Competitive Environment
Global majors compete with regional champions across certification depth and software ecosystem integration. The vendor base stratifies into three tiers: vertically integrated assemblers with captive battery supply, specialist firmware houses licensing flight control stacks, and contract manufacturers serving white-label retail channels. Dominant competitive moves include hardware redesign cycles to meet fragmented national airspace regulations and direct technical support contracts that bypass traditional dealer networks.
Among vertically integrated assemblers, DJI and Autel Robotics exemplify divergent strategic positions. DJI anchors cost leadership through Shenzhen-based captive cell sourcing and vertical assembly lines spanning recreational and commercial tiers. Autel Robotics occupies a position defined by R&D intensity focused on obstacle-avoidance algorithms. Skydio represents the North American enterprise specialist archetype, with autonomous flight stacks optimized for infrastructure inspection workflows.
| Leading Market Players |
|---|
| DJI |
| Parrot SA |
| Autel Robotics |
| Skydio |
| Yuneec International |
| 3DR |
| CONTIXO |
| Draganfly Innovations |
| Hubsan Technology |
| Others |
Value Chain & Pricing Dynamics
FAA Remote ID compliance gates qualified supply access and premium-tier pricing power, as manufacturers bearing EASA and FAA certification costs capture enterprise contracts while uncertified competitors retreat to recreational tiers with compressed margins. Lithium-polymer cell allocation from Shenzhen suppliers concentrates pricing leverage among vertically integrated assemblers who pass through raw material volatility via quarterly contract adjustments.
Pricing Analysis
Input-cost pass-through dominates smartphone-controlled drone pricing, with lithium-polymer cell volatility from Chinese and South Korean suppliers flowing directly into OEM contract renegotiations. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified enterprise units from recreational tiers and white-label imports. Cost compression in sub-$500 consumer tiers is intensifying because FPV streaming standardization erodes feature differentiation. Agricultural cooperatives exhibit highest price sensitivity due to seasonal fleet replacement cycles, while infrastructure contractors in Germany absorb premiums for certified airworthiness documentation.
Supply Chain Analysis
Warehouse-distribution layers concentrate in Shenzhen's Bao'an district for component aggregation, with regional distribution centers in Dallas and Rotterdam serving North American and European enterprise fulfillment. Flight controller firmware, camera gimbal assemblies, and lithium-polymer cells draw from China, South Korea, and Japan. Single-source vulnerability in MIIT-certified radio frequency modules for domestic Chinese sales forces parallel inventory carrying costs. Distribution runs through direct technical support contracts that agricultural cooperatives negotiate with manufacturers, bypassing traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Smartphone Controlled Drone Market functions as a geographic-arbitrage play where India's PLI scheme offers 20-25% cost advantages against Chinese assembly for export-oriented manufacturers targeting European compliance tiers.
For Market Incumbents: Acquire embedded systems engineering talent pools concentrated in Munich and Redwood City to defend against autonomous flight stack commoditization. Deepen backward integration into lithium-polymer cell sourcing through captive supply agreements with Shenzhen suppliers. Accelerate FAA Remote ID hardware refresh cycles to consolidate enterprise market share before smaller vendors secure parallel certifications. For New Entrants and Emerging Players: Begin with variable-rate spray drone assembly under India's PLI scheme, targeting Maharashtra's cotton cooperatives with localized firmware validation capabilities. Agricultural mechanization in fragmented smallholder markets offers the most penetrable entry point. Pursue direct technical support contracts that bypass established dealer networks capturing maintenance margin. For Investors and Strategic Acquirers: Roll-up economics work for specialist firmware houses because EASA's tightening operational categories force smaller vendors to sell rather than fund parallel certification tracks across multiple regulatory jurisdictions. Five-to-ten year viability hinges on autonomous flight stack differentiation rather than hardware cost leadership. Watch for FAA enforcement actions against uncertified imports as the inflection indicator for certified manufacturer margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Remote ID Hardware Redesign | FAA compliance mandates accelerate replacement cycles among infrastructure inspection contractors in Texas. |
| 5G Network Slicing Integration | Carrier-grade latency guarantees enable beyond-visual-line-of-sight operations without dedicated ground stations. |
| Modular Sensor Payload Development | Quick-release interfaces allow German engineering firms to switch between thermal and LiDAR configurations. |
| Direct Technical Support Contracts | Brazilian agricultural cooperatives bypass regional dealers who previously captured maintenance margin pools. |
| PLI Scheme Local Assembly | Indian tariff and subsidy advantages reduce landed cost for export-oriented manufacturers targeting EASA tiers. |
Study Parameters
Coverage spans China, the United States, Germany, India, and Japan, with primary inputs from each combining flight controller firmware developers, agricultural cooperative procurement managers, infrastructure inspection contractors, and cellular carrier network planning officers. Secondary validation draws from FAA Remote ID rulemaking dockets, EASA drone regulation framework documentation, MIIT GB-standard radio frequency allocations, and Shenzhen customs export records. Bottom-up fleet deployment estimates triangulate against top-down OEM revenue segmentation across commercial, recreational, and agricultural tiers.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window, modeling product type, end-use vertical, control link technology, and regional regulatory cluster dimensions. CAGRs derive from unit shipment trajectories weighted by average selling price evolution in each tier. Industry-specific forecast inputs include lithium-polymer cell production allocation schedules and Remote ID hardware refresh cycle timing assumptions.
Several conditions sit outside the modeled scope, including potential battery chemistry breakthroughs beyond lithium-polymer energy density limits and unilateral national airspace reclassifications that could fragment firmware deployment. Forecasts reflect documented assumptions about regulatory enforcement consistency and raw material supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Solar Powered Drones Market
UAV
UAV Simulator Software Market
UAV
UAV Lidar Market
UAV
Drone Flight Controller System Market
UAV
Solar-Powered UAV Market
UAV
Commercial Drone Market
UAV
Global Drone Services Market
UAV
Global Drone Data Services Market
UAV
GCC Drones Market
UAV
Commercial Drone-Enabled Services Market
UAV
UAV Navigation Systems Market
UAV
Stratospheric Flying Drone Market
UAV
Asia Pacific Commercial Drone Market
UAV
Industrial Drones Market
UAV
Global Multirotor UAV Market
UAV
Global Drone Software Market