
 Drone Inspection Service Market | 2026-2036
Drone Inspection Service Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Inspection Service Market Insights
Autonomous flight path algorithms paired with edge-computing payloads is reconfiguring how inspection data is captured, processed, and delivered to asset operators. Cyberhawk Innovations Limited leverages its offshore wind specialization to anchor recurring contracts with European energy utilities. SkySpecs, Inc. sustains technology leadership through blade-damage-detection algorithms that reduce turbine downtime. Terra Drone Corporation dominates Asia-Pacific infrastructure projects with its survey-grade LiDAR deployments.
Drone inspection service encompasses the commercial use of unmanned aerial systems equipped with stabilized sensor gimbals to acquire georeferenced imagery, point clouds, or thermal signatures of physical assets, typically operating at altitudes below 400 feet with real-time telemetry links to ground control stations. The primary purpose centers on reducing human exposure to hazardous environments while accelerating defect detection cycles across energy, agriculture, and built infrastructure. Structural inspection commands the largest revenue pool among service types due to aging bridges, dams, and industrial facilities requiring compliance-driven assessment frequencies. Photogrammetry leads technology adoption for volumetric and crack-mapping applications, though thermal imaging grows fastest as photovoltaic and electrical grid operators prioritize hot-spot detection. Energy operators represent the most concentrated client type, with procurement patterns tied to capital-intensive asset bases and regulatory inspection mandates.
The FAA's Part 107 framework and evolving BVLOS waiver pathways in the United States govern commercial airspace access, while EASA's Specific Category regulations under EU 2019/947 shape European operational certification requirements. China's CAAC drone registration system and altitude zone restrictions impose additional compliance layers for cross-border service providers. Stakeholders must monitor the divergence between national UAS traffic management frameworks and emerging detect-and-avoid mandates, as harmonization gaps will determine which operators can scale across jurisdictions without duplicating certification investments.
Market Dynamics
Autonomous flight path algorithms paired with edge-computing payloads is reconfiguring how inspection data is captured, processed, and delivered to asset operators across energy and infrastructure verticals.
Growth Catalysts
- FAA Part 107 framework:The United States regulatory pathway for commercial drone operations enables standardized pilot certification and airspace access, accelerating service provider entry into utility-scale renewable asset monitoring.
- Photogrammetry:This volumetric and crack-mapping technology reduces inspection cycle times for aging bridges and industrial facilities, driving compliance-driven procurement from infrastructure operators.
- Texas and California:Concentrated utility-scale solar and wind installations in these states generate recurring demand for continuous aerial monitoring contracts.
Market Restraints
- Detect-and-avoid mandates:Emerging technical requirements for beyond-visual-line-of-sight operations impose hardware and software certification costs that compress margins for mid-tier service providers.
- Sensor payload supply:Stabilized thermal and LiDAR gimbal manufacturing concentrates among specialized component suppliers, creating input cost volatility for inspection fleet operators.
- Pilot certification timelines:FAA Part 107 renewal requirements and practical experience thresholds restrict workforce scaling during seasonal demand surges.
Strategic Opportunities
- EU 2019/947 Specific Category:EASA's operational certification framework creates a harmonized pathway for cross-border service expansion across European energy utilities.
- Photovoltaic hot-spot detection:Thermal imaging adoption for solar farm assessment represents an underpenetrated application with recurring revenue potential.
- Edge-computing convergence:Real-time data processing onboard UAVs is hybridizing with 5G telemetry links to enable immediate defect alerting without ground station dependency.
Industry Challenges
- Airspace deconfliction:Integration with crewed aviation traffic management systems requires coordination with local air traffic control and UAS traffic management platforms.
- Data standardization:Absence of unified formats for georeferenced point clouds and thermal signatures forces redundant processing workflows across client asset management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Inspection Service Market |
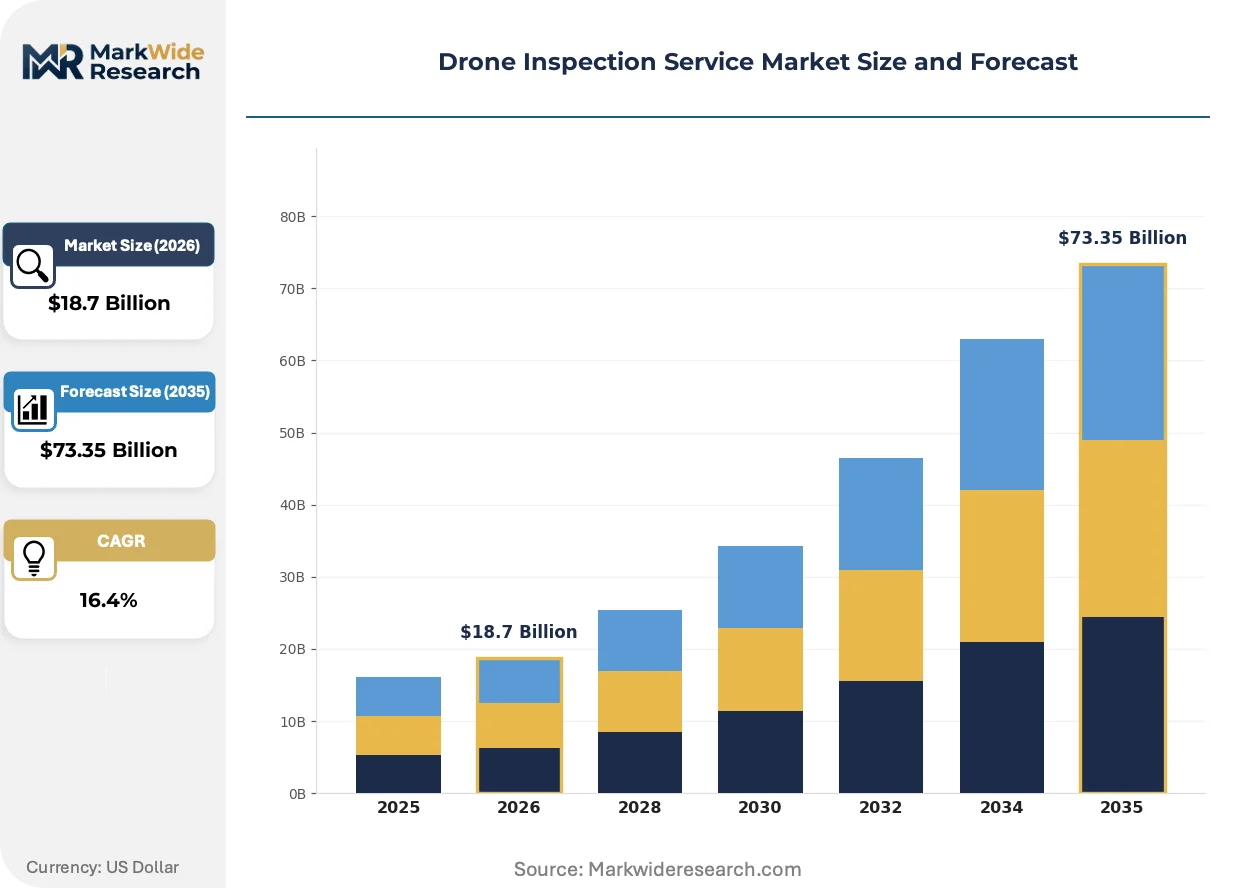
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Structural Inspection, Agricultural Surveying, Pipeline Monitoring, Roof Assessment, Asset Management Technology: LiDAR, Photogrammetry, Thermal Imaging, Multispectral Sensors, Hyperspectral Sensors Client Type: Energy Operators, Agriculture Firms, Construction Companies, Telecommunications Providers, Infrastructure Managers Deployment: Automated Flights, Manual Piloting, Hybrid Models, Remote Monitoring, Data Analytics Integration |
| Companies Covered | Cyberhawk Innovations Limited, SkySpecs, Inc., Terra Drone Corporation, PrecisionHawk, Inc., Aerodyne Group, Sharper Shape, Raptor Maps, Inc., Intertek Group plc, MISTRAS Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Inspection Service Market Trends and Innovations
Edge-computing architectures and AI-driven defect recognition are compressing the latency between aerial data capture and maintenance dispatch decisions across energy infrastructure operators.
Computer vision algorithms for blade-damage detection are hybridizing with thermal anomaly mapping to enable single-flight multi-modal assessments of wind turbine assets. European offshore wind operators are adopting these integrated payloads fastest, reducing turbine downtime through consolidated inspection schedules. The structural consequence is compression of traditional separate visual and thermal inspection contracts into unified service offerings.
EASA's Specific Category regulations under EU 2019/947 are mandating operational risk assessments and defined operational volume boundaries for commercial drone flights. This regulatory framework forces service providers to standardize safety management systems across national markets. Offshore wind inspection contracts in the North Sea and Baltic regions are most affected, with operators consolidating vendor lists to those holding multi-national certifications.
Subscription-based fleet access models are displacing per-flight procurement for utility-scale solar and wind operators. Asset managers in Texas and California are locking in multi-year service agreements with guaranteed inspection frequencies and data delivery timelines. This behavioral shift concentrates purchasing power among integrated service platforms with autonomous fleet capabilities.
Drone Inspection Service Market Segmentation
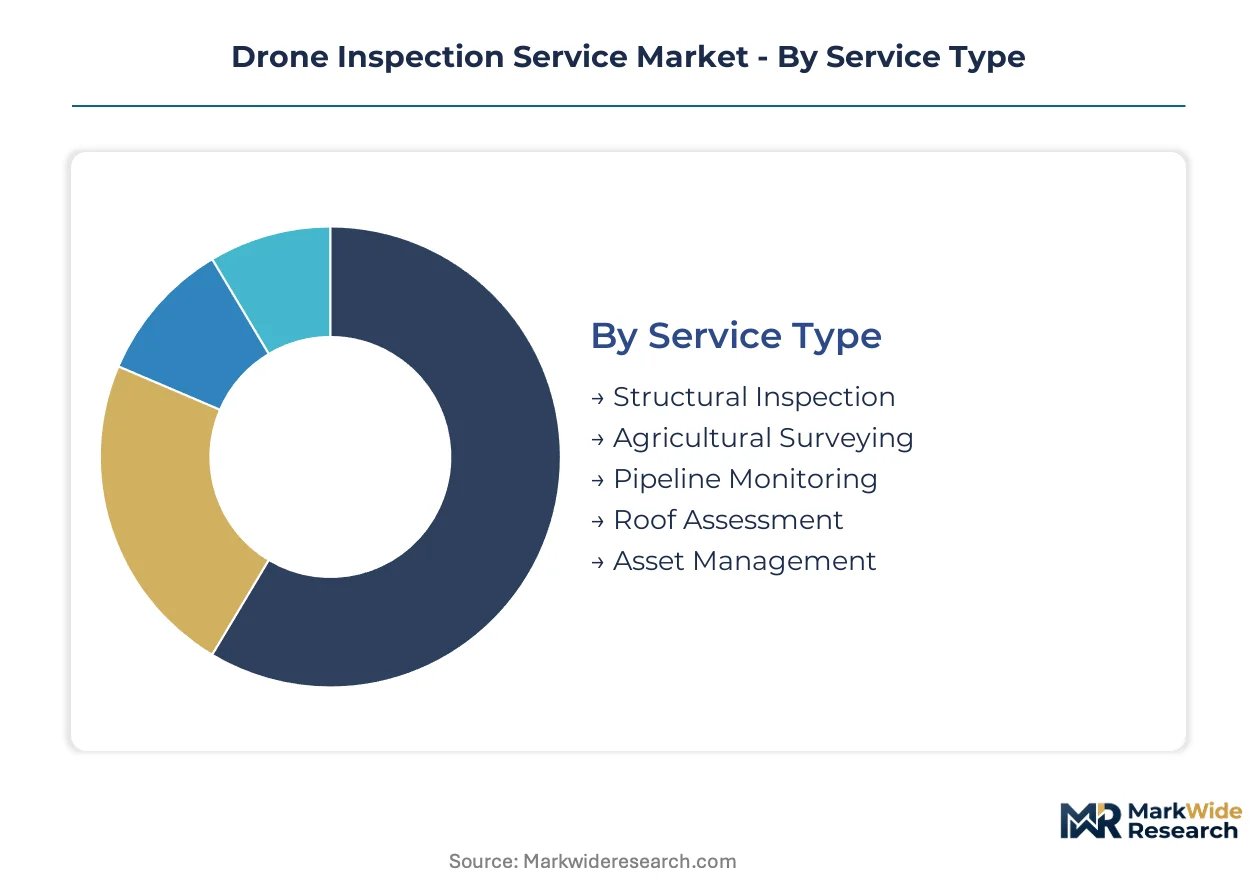
Drone inspection service providers configure delivery models around recurring maintenance contracts versus one-off project engagements. After-sales intensity varies sharply across segments, with energy operators demanding continuous data subscriptions while construction procurement remains transactional. Understanding these service-attachment patterns determines which segments justify fleet specialization investments.
Service Type:
Structural inspection commands the most intensive after-sales relationships, with multi-year data archiving and compliance reporting obligations extending far beyond initial flight delivery.
- Structural Inspection:Georeferenced crack mapping and deformation analysis of bridges, dams, and industrial facilities using stabilized sensor gimbals. Demand concentrates among Texas and California infrastructure managers facing regulatory assessment mandates and aging asset portfolios.
- Agricultural Surveying:Crop health monitoring through multispectral index mapping and volumetric yield estimation. Midwest grain cooperatives and Central Valley irrigation districts drive procurement, with seasonal intensity creating fleet utilization challenges during off-peak months.
- Pipeline Monitoring:Linear asset corridor assessment for leak detection and right-of-way encroachment.
- Roof Assessment:Post-storm damage documentation and insurance claim support for commercial property portfolios.
- Asset Management:Integrated inspection-data-to-CMMS workflows for utility-scale renewable installations.
By volume, Structural Inspection leads. By growth pace, Asset Management is ahead.
Technology:
Technology selection follows cost-tier logic, with premium sensor configurations reserved for high-frequency contract renewals and budget imaging serving spot-market demand.
- Photogrammetry:Dense point cloud generation from overlapping aerial imagery enables millimeter-accurate volumetric measurement and crack detection. Infrastructure operators in earthquake-prone zones prioritize this technology for structural deformation tracking.
- Thermal Imaging:Infrared signature capture for hot-spot detection across photovoltaic arrays and electrical substations. Solar farm operators in Arizona and Nevada represent concentrated demand as module degradation monitoring becomes standard O&M practice.
- LiDAR:Survey-grade laser scanning for vegetation encroachment and topographic modeling.
- Multispectral Sensors:Narrow-band vegetation index calculation for precision agriculture nitrogen management.
- Hyperspectral Sensors:Continuous-spectrum material identification for mineral exploration and contamination mapping.
Photogrammetry dominates current flight hours. Thermal Imaging is expanding most quickly as renewable asset bases mature.
Client Type:
Customer-type segmentation reveals diverging procurement maturity, with energy operators consolidating vendor relationships while agriculture remains fragmented across regional service bureaus.
- Energy Operators:Wind turbine and solar farm owners requiring continuous aerial monitoring under long-term service agreements. Offshore wind developers in the North Sea and Baltic regions anchor the highest-value contracts through bundled inspection and blade-repair dispatch services.
- Infrastructure Managers:Bridge authorities and dam operators with compliance-driven inspection frequencies tied to federal safety ratings. State departments of transportation in the United States consolidate procurement through multi-state cooperative contracts.
- Agriculture Firms:Row-crop and specialty producers purchasing seasonal survey packages.
- Construction Companies:Earthwork volume verification and as-built documentation for project closeout.
- Telecommunications Providers:Cell tower structural assessment and line-of-sight verification.
Energy Operators generate the largest contract values. Infrastructure Managers show the steepest expansion trajectory as federal inspection deadlines approach.
Deployment:
Deployment mode selection correlates directly with margin structure, with automated flights enabling subscription economics and manual piloting preserving project-based pricing flexibility.
- Automated Flights:Pre-programmed waypoint execution with minimal ground control intervention, enabling overnight inspection scheduling and reduced labor cost per asset. Texas utility-scale solar operators favor this mode for monthly fleet-wide thermal surveys.
- Data Analytics Integration:Direct pipeline from aerial capture to predictive maintenance platforms, eliminating manual data handoff delays. European offshore wind utilities require this capability for real-time blade damage alerts integrated with turbine SCADA systems.
- Manual Piloting:Operator-directed flight paths for complex or confined airspace environments.
- Hybrid Models:Automated capture with manual override protocols for obstacle-rich scenarios.
- Remote Monitoring:Ground-station oversight of beyond-visual-line-of-sight operations from centralized control centers.
Automated Flights account for the highest flight-hour volume. Data Analytics Integration is gaining share fastest as asset operators consolidate vendor relationships around outcome-based contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural surplus in drone inspection service exports, shipping specialized offshore wind and utility-scale solar assessment capabilities to European and Asia-Pacific markets while importing component-grade sensors and stabilized gimbal systems from East Asian manufacturing clusters.
United States
Texas and California utility-scale renewable installations anchor domestic demand for automated thermal surveys and blade-damage assessments. The FAA's Part 107 framework and evolving BVLOS waiver pathways govern commercial airspace access, with detect-and-avoid mandates reshaping operational certification requirements. Houston and Los Angeles metropolitan clusters concentrate service provider headquarters and pilot training facilities serving continental energy operators.
Germany
Offshore wind developers in the North Sea and Baltic regions generate concentrated procurement for bundled inspection and blade-repair dispatch services. EASA's Specific Category regulations under EU 2019/947 mandate operational risk assessments and defined operational volume boundaries for commercial drone flights. Hamburg and Bremerhaven anchor the highest-value contract clusters through integrated service platforms with autonomous fleet capabilities.
China
Domestic infrastructure managers and renewable asset operators drive procurement for survey-grade LiDAR deployments and linear asset corridor assessments. The CAAC drone registration system and altitude zone restrictions impose compliance layers for cross-border service providers. Yangtze River Delta manufacturing clusters produce stabilized thermal and multispectral gimbals for regional fleet operators.
United Kingdom
North Sea offshore wind utilities require real-time blade damage alerts integrated with turbine SCADA systems, compressing traditional separate visual and thermal inspection contracts. The country's national aviation regulator shapes operational certification requirements for beyond-visual-line-of-sight flights over marine environments. Aberdeen and Edinburgh clusters concentrate inspection service providers serving North Sea energy infrastructure.
Japan
Precision agriculture nitrogen management and aging dam infrastructure create dual demand streams for multispectral surveying and structural deformation tracking. METI industrial policy frameworks influence commercial drone adoption timelines for infrastructure maintenance applications. Tokyo and Osaka metropolitan areas host integrated service platforms combining automated flight systems with predictive maintenance data pipelines.
Drone Inspection Service Market Competitive Landscape
On the supply side, the industry is consolidating around integrated service platforms with autonomous fleet capabilities and predictive maintenance data pipelines. Mid-tier regional operators face margin compression from detect-and-avoid hardware certification costs and sensor payload supply volatility. Three strategic archetypes dominate: technology-specialized inspection algorithm developers, geography-anchored offshore wind service providers, and diversified industrial testing conglomerates with aerial service divisions. Competitive positioning hardens through multi-year subscription contract lock-ins and cross-border certification harmonization investments.
Among technology-specialized developers, Cyberhawk Innovations Limited and SkySpecs, Inc. exemplify the algorithm-centric archetype, while Terra Drone Corporation occupies a position within the Asia-Pacific infrastructure-focused tier. These entities anchor distinctive competitive vectors without overlapping service territory, reflecting how specialization in blade-damage detection, offshore wind environments, or survey-grade LiDAR deployments creates defensible market positions against generalized competitors.
| Leading Market Players |
|---|
| Cyberhawk Innovations Limited |
| SkySpecs, Inc. |
| Terra Drone Corporation |
| PrecisionHawk, Inc. |
| Aerodyne Group |
| Sharper Shape |
| Raptor Maps, Inc. |
| Intertek Group plc |
| MISTRAS Group, Inc. |
| Others |
Pricing and Supply Chain Analysis
Stabilized thermal and LiDAR gimbal manufacturing concentrates in China's Yangtze River Delta and Japan's precision optics clusters, anchoring margin pools downstream with service providers who bundle sensor-agnostic data platforms rather than hardware-dependent flight operations.
Pricing Analysis
Energy operators anchor subscription-based pricing for automated inspection fleets, with three-tier pricing structure across premium, standard, and economy levels differentiated by sensor payload grade and data analytics depth. Price differentiation stems from BVLOS certification tier and guaranteed response-time SLAs. Margins are tightening due to detect-and-avoid hardware certification costs. Agricultural surveying clients exhibit highest price sensitivity, while offshore wind utilities show least sensitivity given bundled repair-dispatch value.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for thermal sensor and flight controller imports. Component sourcing draws from China, Japan, and South Korea for stabilized gimbals, edge-computing modules, and composite airframes. Single-source vulnerability concentrates in high-precision LiDAR laser emitters. Distribution runs through integrated service platforms with captive maintenance, repair, and overhaul capabilities rather than component resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
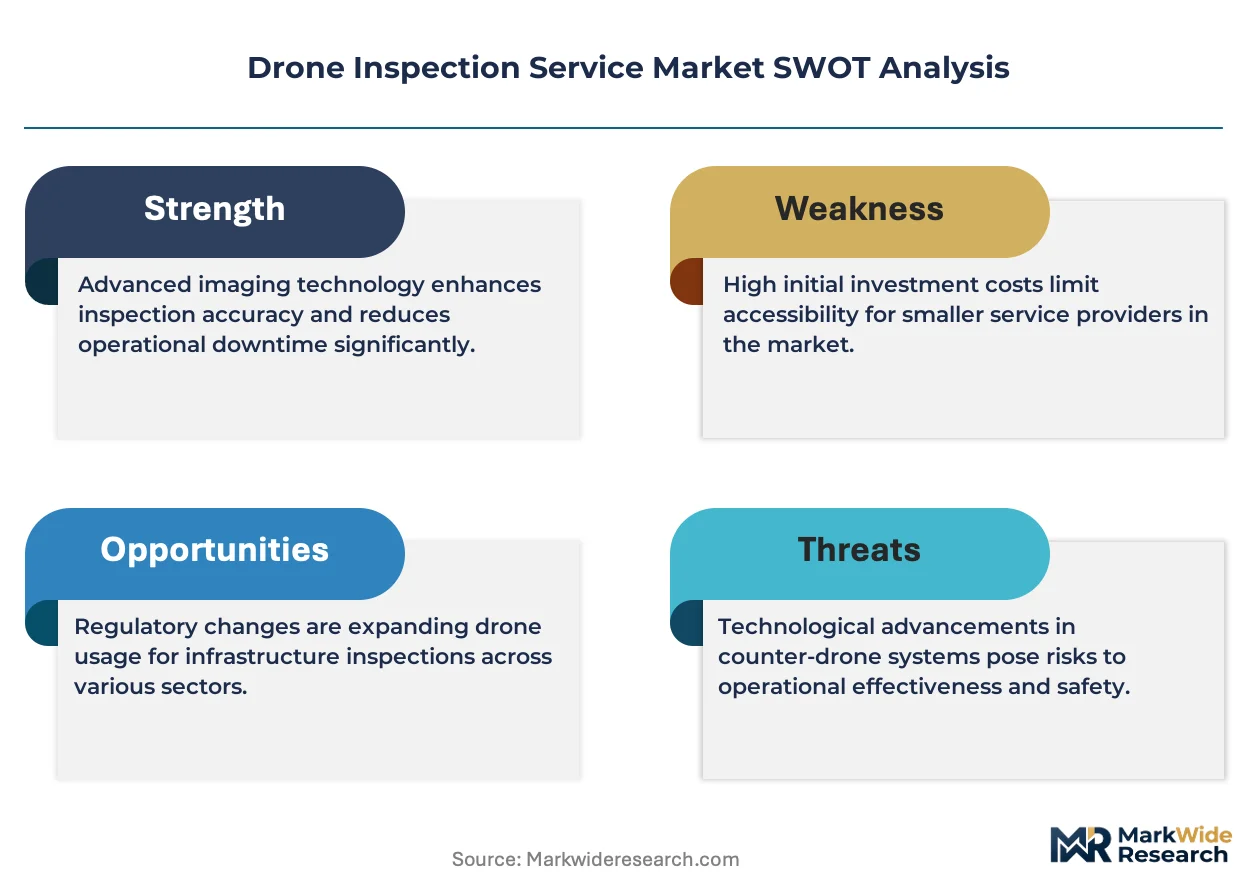
Drone inspection service represents a service-attach opportunity where recurring data subscription revenue expands faster than per-flight hardware deployment, with predictive maintenance platform integration commanding premium attach rates.
For Market Incumbents: Entrench multi-year subscription lock-ins with utility-scale solar and wind operators before EASA detect-and-avoid mandates raise rival certification barriers. Deepen backward integration into edge-computing payload assembly to offset sensor cost volatility. Prioritize cross-border certification harmonization investments under EU 2019/947 to defend against Asia-Pacific challengers. For New Entrants and Emerging Players: Mid-market commercial building portfolios in secondary US metropolitan areas represent the most penetrable entry point given fragmented property management procurement and post-storm insurance documentation demand. Target agricultural cooperatives with seasonal fleet-sharing models to bypass capital intensity. Lead with thermal-roof assessment bundled with HVAC diagnostic referrals. For Investors and Strategic Acquirers: Capital is best deployed toward algorithm-centric inspection developers with proprietary blade-damage or hot-spot detection IP rather than asset-heavy fleet operators. Long-term viability hinges on data platform retention rates and CMMS integration depth. Watch for FAA BVLOS waiver approval velocity as inflection indicator for scalable automation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Subscription Conversion | Locks in Texas and California utility-scale operators against seasonal spot-market competitors. |
| Edge-Computing Payload Integration | Enables real-time defect alerting for North Sea offshore wind SCADA integration requirements. |
| EASA Specific Category Certification | Opens harmonized cross-border service expansion across European energy utility procurement. |
| Predictive Maintenance Platform Partnership | Attaches recurring data revenue to CMMS workflows for infrastructure managers. |
| Detect-and-Avoid Hardware Certification | Meets emerging FAA BVLOS mandates before margin compression affects mid-tier rivals. |
Research Methodology
Cross-validation between primary interviews with utility asset managers, drone fleet operators, and FAA certification consultants and secondary validation through EASA regulatory filings, FAA BVLOS waiver databases, and utility procurement contract disclosures anchors the qualitative findings. Bottom-up fleet deployment estimates and top-down energy O&M spending analysis triangulate market sizing.
Calibration against historical inspection frequency benchmarks and renewable capacity installation pipelines shapes the analytical framework across the analysis window. Segmentation dimensions span service type, sensor technology tier, client vertical, and deployment automation level. CAGRs derive from installed base expansion rates and inspection intensity per megawatt trajectories, with edge-computing adoption curves and regulatory waiver approval timelines as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in renewable energy investment tax credit policy and utility capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions around BVLOS regulatory liberalization and sensor cost decline curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Delivery Drones Market
UAV
GCC Drones Market
UAV
Global VTOL UAV Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
North America Drones Market
UAV
Ultra Micro Drone Market
UAV
United States Drone Services Market
UAV
Anti-Drone Market
UAV
Rotary Blade UAV Drones Market
UAV
Europe Drone Light Shows Market
UAV
Stratospheric Flying Drone Market
UAV
Global Drone Inspection and Monitoring Market
UAV
Drone-Based Consulting Services Market
UAV
US Commercial Drone Market
UAV
Global Multirotor UAV Market
UAV
Solar-Powered UAV Market