
 Tethered Drone System Market | 2026-2036
Tethered Drone System Market Size, Share, and Industry Trends Forecast 2026-2036
Tethered Drone System Market Insights
Carbon fiber composite tethers are replacing traditional copper-heavy power cables, which is realigning product economics toward lighter payloads and extended flight durations. Elistair leverages proprietary micro-tensioning systems to sustain performance in high-wind environments. Acecore Technologies anchors its position through modular payload architectures for cinematography and inspection workflows. Fotokite differentiates with fully autonomous tethered platforms that operate without active piloting.
Tethered drone systems consist of unmanned aerial vehicles connected to ground stations via physical cables that simultaneously transmit power and data, typically employing fiber-optic cores with copper power conductors to enable multi-hour continuous flight at altitudes up to 400 feet. These systems serve persistent aerial operations where battery-limited free-flying drones fail, including border surveillance, emergency communications restoration, and industrial asset monitoring. Tethered surveillance drones dominate current procurement volumes as defense and security agencies prioritize persistent overwatch capabilities. Tethered communication drones represent the fastest-growing product category as telecommunications providers deploy them for rapid network resilience during infrastructure outages. The application segment for search and rescue operations commands premium pricing due to specialized thermal imaging and real-time streaming requirements.
The FAA governs commercial tethered operations through Part 107 waivers and evolving beyond-visual-line-of-sight rulemakings that directly shape market access timelines for US vendors. EASA's drone regulatory framework under the EU U-space initiative imposes stringent airworthiness standards that filter out uncertified equipment suppliers across European markets. ISO 21384-3 unmanned aircraft systems standards provide baseline safety protocols that manufacturers must satisfy for international contract eligibility. Stakeholders must monitor regulatory divergence between permissive experimental frameworks and restrictive type-certification pathways as this tension will determine which vendors achieve scalable deployment.
Market Dynamics
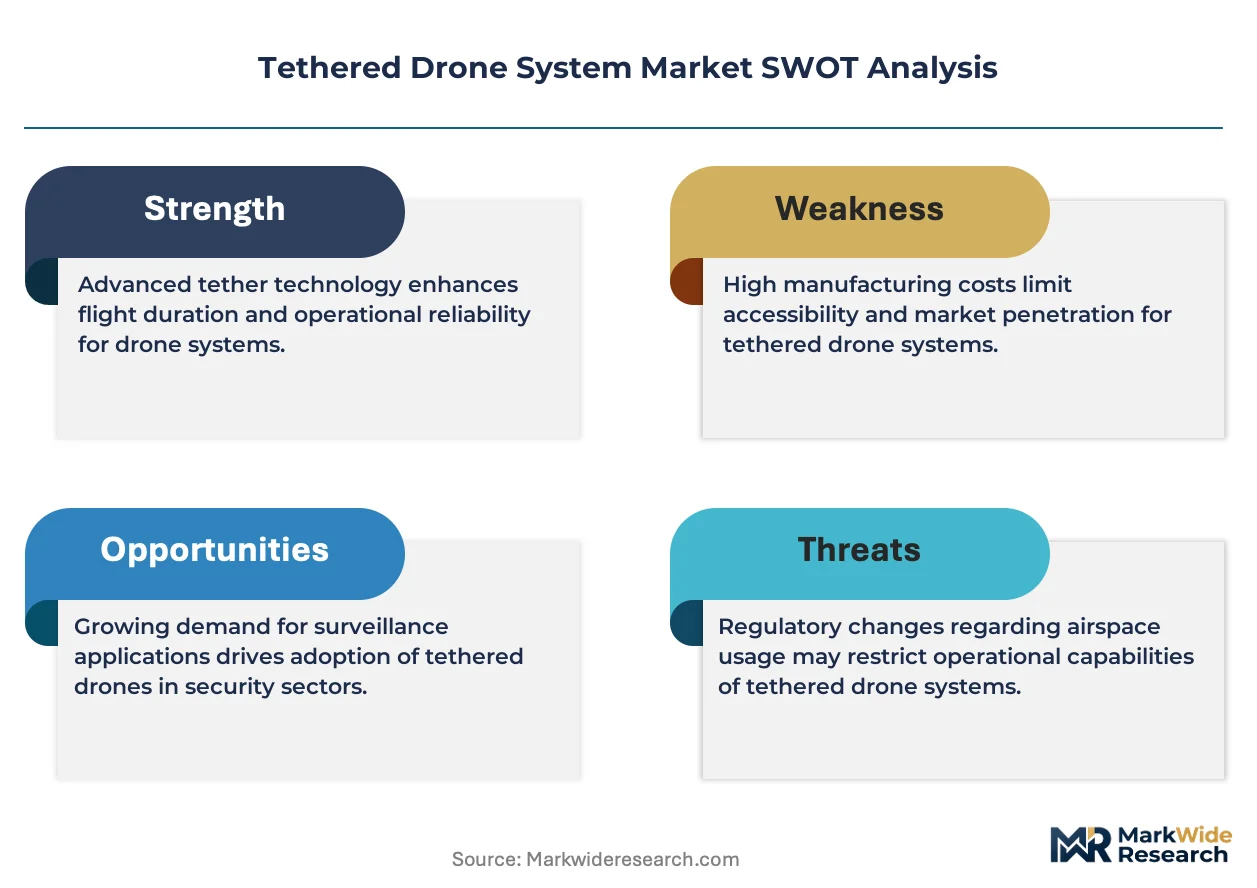
Carbon fiber composite tethers are compressing payload economics while FAA Part 107 waiver reforms compress certification timelines for beyond-visual-line-of-sight operations, forcing vendors to recalibrate engineering and compliance investments simultaneously.
Growth Catalysts
- FAA Part 107 Reforms:Beyond-visual-line-of-sight waiver streamlining accelerates commercial certification timelines for US operators, reducing time-to-deployment for persistent aerial monitoring contracts.
- Fiber-Optic Core Adoption:Hybrid power-data cables with fiber-optic transmission enable real-time high-bandwidth streaming for defense surveillance and emergency communications restoration applications.
- NATO Military Procurement:Persistent aerial monitoring programs across member states expand tethered surveillance platform volumes, prioritizing multi-hour continuous flight capabilities over battery-limited alternatives.
Market Restraints
- Copper Price Volatility:Traditional copper-heavy power conductor costs fluctuate with commodity markets, pressuring margins for manufacturers maintaining legacy tether architectures.
- EASA Airworthiness Standards:EU U-space initiative stringent certification requirements filter uncertified equipment suppliers from European markets, creating regulatory moats for established vendors.
- Free-Flying Drone Substitution:Battery technology improvements in autonomous quadcopters threaten tethered system relevance for short-duration inspection workflows.
Strategic Opportunities
- Telecommunications Network Resilience:Rapid cellular infrastructure restoration during outages creates white space for tethered communication drones as mobile network operators prioritize backup systems.
- Industrial Asset Monitoring:Oil refineries and power generation facilities adopt persistent thermal inspection platforms, opening volume deployment beyond defense and first responder verticals.
- ISO 21384-3 Harmonization:International unmanned aircraft systems safety standards create regulatory tailwinds for manufacturers achieving baseline protocol compliance for cross-border contract eligibility.
Industry Challenges
- BVLOS Pilot Certification:Beyond-visual-line-of-sight operator training programs lag hardware availability, creating operational bottlenecks for scaled deployment.
- Tether Tension Engineering:Micro-tensioning system design expertise concentrates among specialized engineering teams, limiting vendor replication speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tethered Drone System Market |
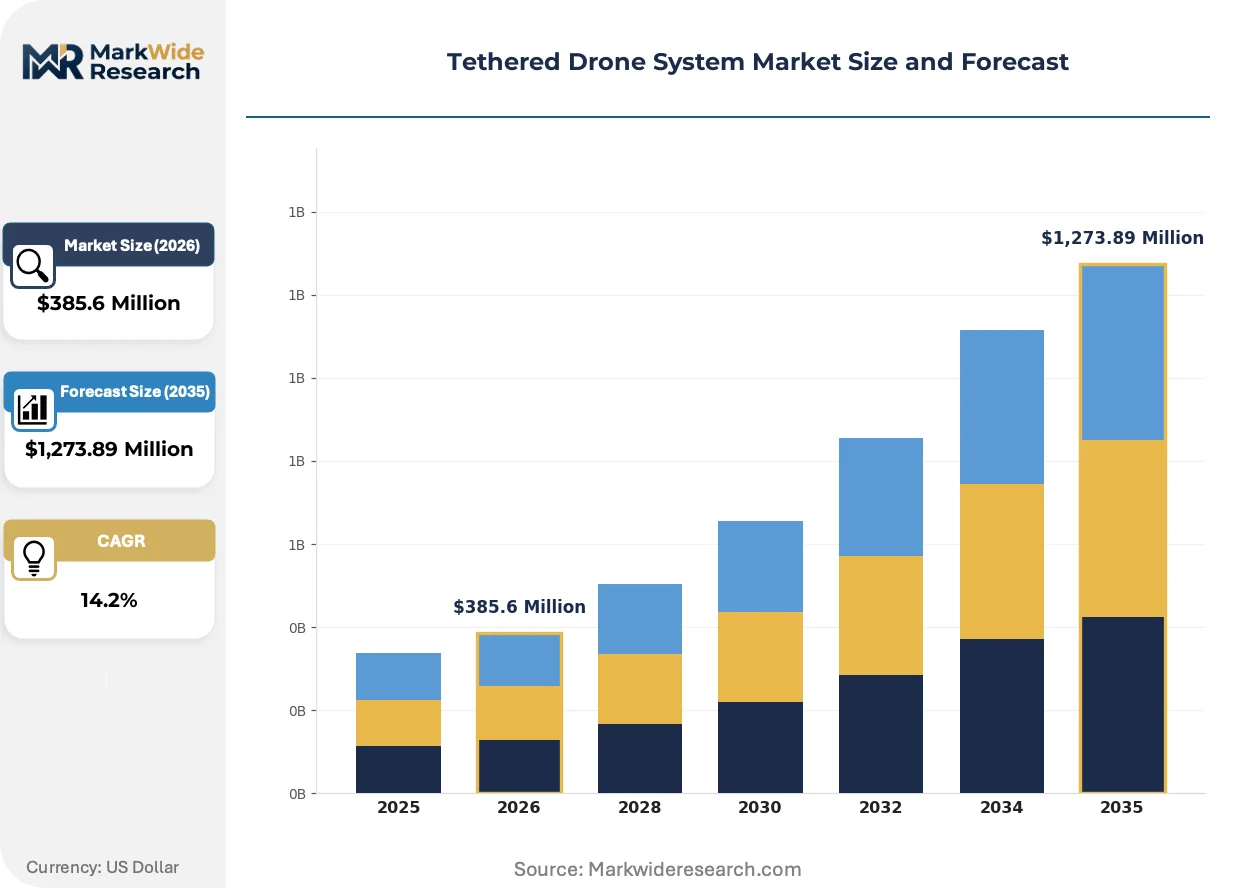
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,273.89 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tethered Surveillance Drones, Tethered Delivery Drones, Tethered Communication Drones, Tethered Inspection Drones End User: Aerospace & Defense, Agriculture, Telecommunications, Construction Application: Monitoring, Data Collection, Communication Relay, Search & Rescue Technology: Electric Propulsion, GPS Navigation, Automated Control, Streaming Systems |
| Companies Covered | Elistair, Acecore Technologies, Fotokite, Easy Aerial, Bharat Electronics, FlyFocus, Aerial IQ, Hoverfly Technologies, Mistral Solutions Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tethered Drone System Market Trends and Innovations
Active reshaping in this market centers on material science breakthroughs in tether construction, regulatory pathway evolution for autonomous operations, and procurement model compression as buyers shift from capital acquisition to operational service frameworks.
Carbon fiber composite tethers are electrifying product economics across the defense and commercial segments. These materials reduce aerial platform weight while maintaining power transmission integrity, enabling extended flight durations above 400 feet. Military surveillance contractors and cinematography studios adopt these architectures aggressively. The structural consequence is electrifying competitive positioning toward lighter payload specialists and away from copper-dependent legacy suppliers.
EU U-space regulatory framework implementation under EASA jurisdiction imposes stringent airworthiness verification protocols. European manufacturers must satisfy type-certification pathways that exceed experimental operational permits. Tethered surveillance platform vendors face compliance timeline compression. Commercial operators in Germany and France respond by consolidating procurement toward pre-certified equipment suppliers.
Service-based contracting is displacing capital equipment purchases among first responder agencies and telecommunications providers. Buyers now prioritize operational availability over hardware ownership, compressing vendor revenue recognition cycles. Equipment-as-a-service models emerge through municipal procurement channels. This behavioral shift concentrates in the United States where defense contractor leasing programs set precedent for commercial adoption.
Tethered Drone System Market Segmentation
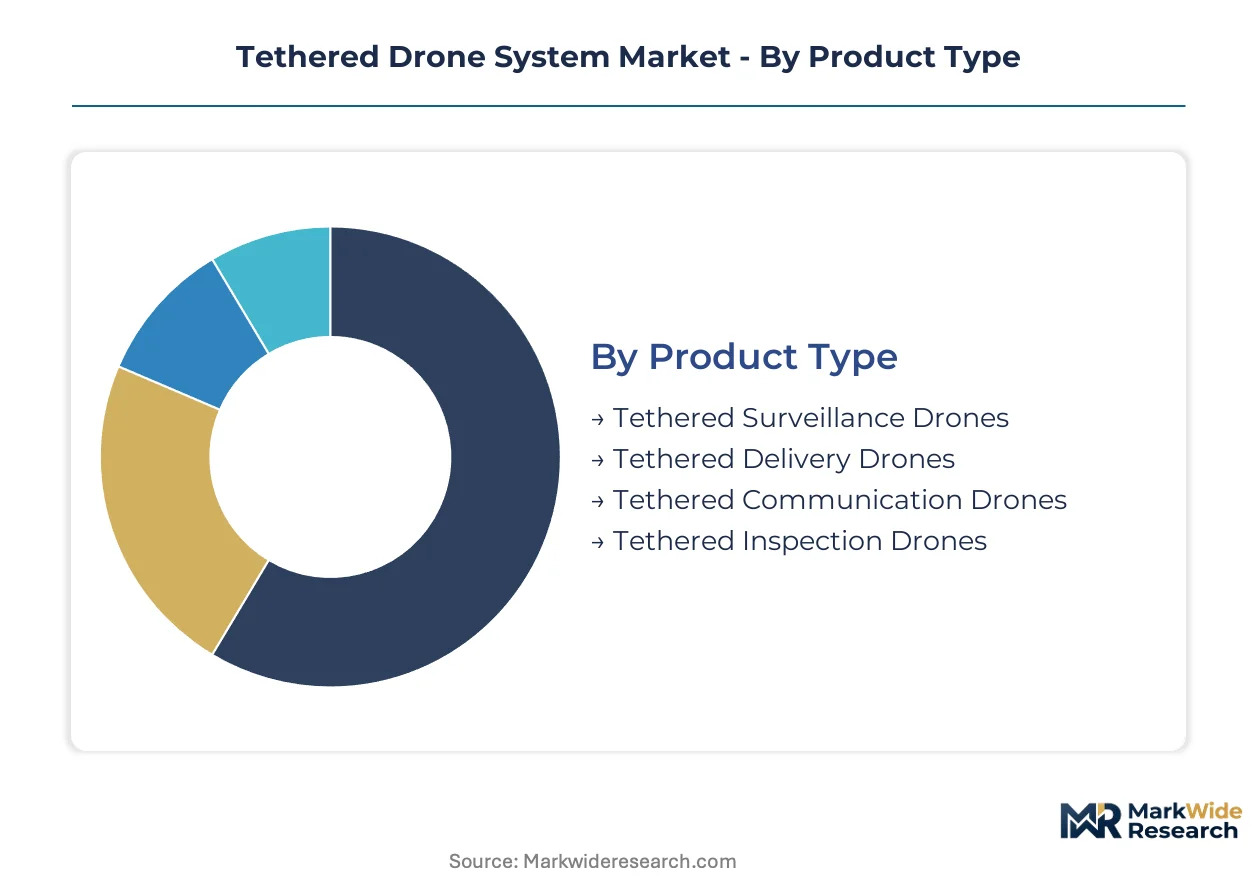
Segmentation in tethered drone systems reveals how procurement priorities diverge between defense agencies demanding persistent overwatch and commercial operators optimizing for rapid deployment economics. Product architecture choices cascade through tether materials, payload modularity, and ground station footprints to determine vendor competitiveness across end-use verticals.
Product Type:
Supply concentration clusters around persistent aerial platforms where fiber-optic tether architectures enable multi-hour flight durations that battery-dependent alternatives cannot match.
- Tethered Surveillance Drones:These platforms integrate thermal imaging arrays and real-time video transmission through hybrid power-data cables for border monitoring and facility security. Defense contractors in the United States and NATO procurement channels absorb the majority of production volumes as persistent overwatch requirements displace rotating free-flying patrols.
- Tethered Communication Drones:Cellular payload modules mounted on tethered platforms restore network connectivity during infrastructure outages through direct fiber-optic backhaul. Telecommunications providers in hurricane-prone coastal regions and remote industrial corridors are expanding procurement as backup resilience mandates tighten.
- Tethered Delivery Drones:Payload-lift configurations transport medical supplies and critical components across constrained airspace with continuous power supply eliminating return-to-base charging cycles.
- Tethered Inspection Drones:Close-proximity sensor platforms examine refinery stacks, power transmission lines, and wind turbine blades with stabilized positioning unaffected by battery depletion.
Tethered surveillance drones absorb the bulk of installed capacity; tethered communication drones are expanding most quickly.
End User:
Cost tier stratification separates defense-grade certified systems from commercial platforms where FAA Part 107 waiver pathways accelerate field deployment.
- Aerospace & Defense:Military surveillance programs require MIL-STD-810G environmental resilience and NSA-approved encryption for classified data transmission through tether lines. Persistent aerial monitoring contracts across NATO member states concentrate procurement toward vendors with established defense contractor relationships.
- Telecommunications:Mobile network operators deploy tethered platforms as cellular-on-wheels alternatives for rapid infrastructure restoration following natural disasters or grid failures.
- Agriculture:Precision crop monitoring applications leverage extended flight duration for multispectral imaging across large acreages without landing for battery swaps.
- Construction:Progress documentation and site security operations adopt tethered systems for continuous visual coverage of multi-year infrastructure projects.
Aerospace & Defense commands premium pricing tiers; telecommunications is gaining share fastest as operational service models displace capital purchases.
Application:
Volume concentration tracks toward operational scenarios where continuous aerial presence delivers measurable advantage over intermittent free-flying coverage.
- Monitoring:Persistent visual and sensor surveillance of critical infrastructure, borders, and emergency incidents with uninterrupted power eliminating coverage gaps. First responder agencies in the United States dominate procurement volumes for active incident management.
- Search & Rescue:Thermal detection payloads with real-time streaming locate missing persons across challenging terrain during extended operations. Premium pricing reflects specialized sensor integration and pilot certification requirements for emergency response coordination.
- Data Collection:Atmospheric sampling, agricultural indices, and environmental metrics gathered through stabilized sensor platforms with consistent positioning.
- Communication Relay:Temporary network infrastructure extension for disaster response, remote operations, and military forward deployment.
Monitoring absorbs the bulk of installed capacity; search & rescue commands the steepest pricing premiums.
Technology:
Margin distribution favors vendors controlling proprietary micro-tensioning and automated control systems that reduce operator skill requirements.
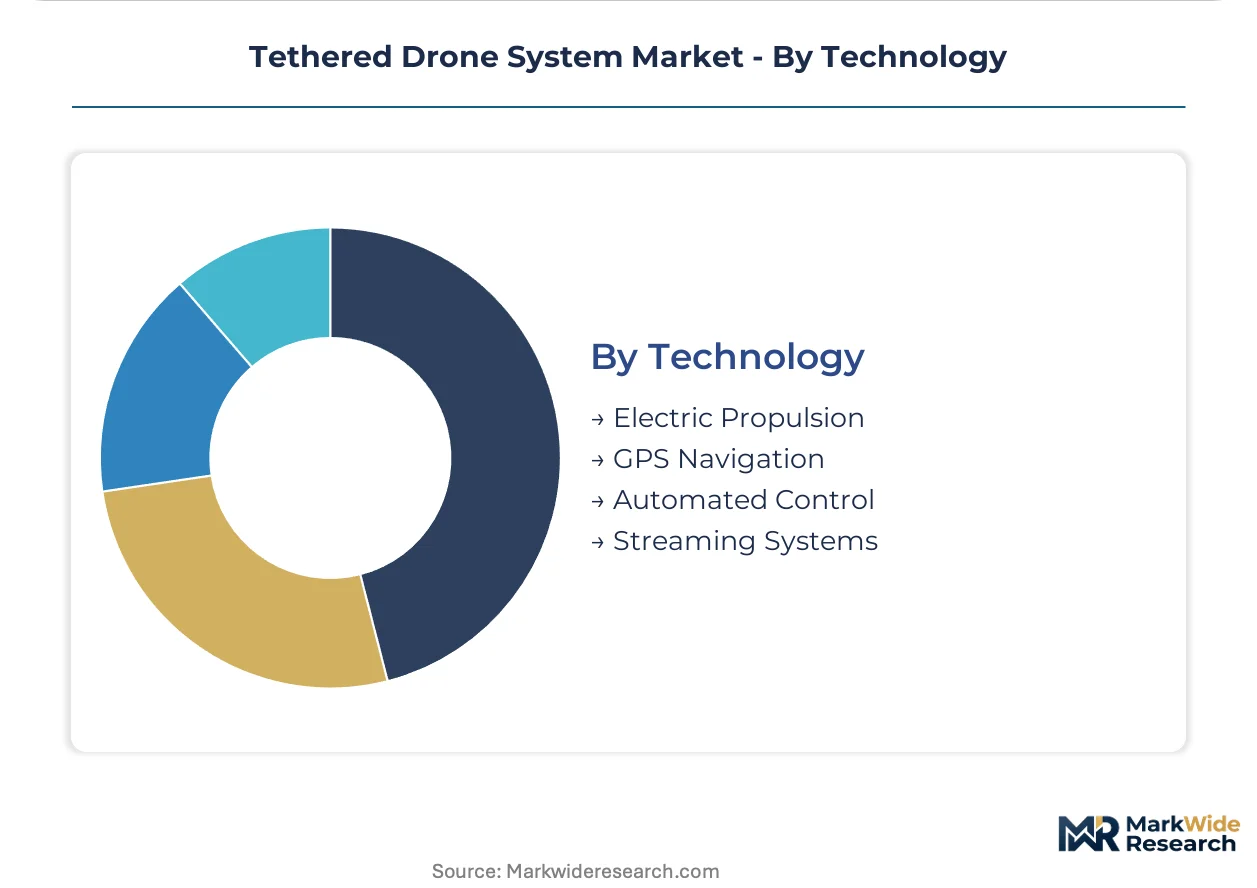
- Automated Control:Autonomous flight management maintains position and altitude without active piloting, enabling single-operator deployment and reducing labor costs for extended missions. Fotokite and comparable platforms eliminate joystick dependency entirely through pre-programmed flight envelopes.
- Streaming Systems:Fiber-optic core transmission delivers high-bandwidth video and sensor data with electromagnetic interference immunity essential for defense and industrial environments.
- Electric Propulsion:Ground-station power conversion drives motor efficiency optimization for payload-lift capacity and flight stability.
- GPS Navigation:Satellite positioning integration enables geofencing and precise station-keeping within defined operational boundaries.
Automated control systems absorb the bulk of engineering investment; streaming systems are climbing the fastest as bandwidth demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense contractors and first responder agencies absorb the dominant share of tethered drone procurement volumes, with persistent aerial monitoring contracts concentrating procurement toward established vendor relationships.
United States
Defense surveillance programs and FAA Part 107 waiver reforms drive procurement acceleration. The FAA governs commercial operations through evolving beyond-visual-line-of-sight rulemakings that compress certification timelines. California and Texas anchor deployment volumes where border security agencies and emergency management departments field persistent overwatch platforms.
Germany
Industrial asset monitoring applications in refineries and power generation facilities expand commercial adoption. EASA's EU U-space initiative imposes stringent airworthiness standards that filter uncertified equipment suppliers. The Ruhr industrial corridor and Bavarian manufacturing clusters concentrate deployment for continuous thermal inspection workflows.
France
Telecommunications network resilience mandates accelerate tethered communication drone procurement for cellular infrastructure backup. EASA drone regulatory frameworks require type-certification pathways exceeding experimental permits. Paris and Lyon metropolitan areas lead operational service model adoption among mobile network operators.
United Kingdom
Search and rescue operations command premium pricing for specialized thermal imaging and real-time streaming capabilities. The Civil Aviation Authority aligns with evolving EU U-space standards while maintaining national certification pathways. London and Southeast England concentrate first responder agency procurement for active incident management.
India
Border surveillance modernization programs expand tethered platform volumes for persistent aerial monitoring. The Directorate General of Civil Aviation issues operational permits under evolving unmanned aircraft systems frameworks. Bangalore and Hyderabad defense technology clusters support indigenous system development for military procurement channels.
Tethered Drone System Market Competitive Landscape
Technology licensing dominates the current landscape as vendors exchange micro-tensioning system patents and fiber-optic transmission architectures. The vendor base stratifies across three tiers: defense-grade certified suppliers, commercial FAA Part 107 waiver holders, and emerging regional fabricators. Two strategic archetypes prevail: lightweight payload specialists leveraging carbon fiber composite tether innovations, and persistent flight platform providers emphasizing multi-hour operational endurance. M&A activity concentrates on acquiring automated control system expertise, while strategic partnerships proliferate between tether manufacturers and ground station integrators.
Among European specialists, Elistair and Acecore Technologies exemplify divergent positioning archetypes. Elistair occupies a position within the micro-tensioning engineering tier, while Acecore Technologies anchors the modular payload architecture segment. Fotokite represents the fully autonomous platform category, eliminating active piloting requirements through pre-programmed flight envelopes. These three entities collectively illustrate how proprietary control systems and material science capabilities determine competitive differentiation in persistent aerial operations.
| Leading Market Players |
|---|
| Elistair |
| Acecore Technologies |
| Fotokite |
| Easy Aerial |
| Bharat Electronics |
| FlyFocus |
| Aerial IQ |
| Hoverfly Technologies |
| Mistral Solutions Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon-footprint disclosure mandates gate qualified supply and premium-tier pricing access, as defense contractors and telecommunications operators now require tether manufacturers to document embodied emissions in carbon fiber composite production and fiber-optic cable assemblies.
Pricing Analysis
Volume concentrates in tethered surveillance drones while margins cluster in tethered communication platforms. Three-tier pricing structure across defense-certified, commercial-grade, and experimental equipment levels separates NATO procurement channels from municipal first responder budgets. Price differentiation hinges on FAA Part 107 waiver status and MIL-STD-810G environmental certification. Pricing pressure stems from copper commodity volatility in legacy tether architectures, with battery-improved free-flying drones eroding entry-level positioning. Telecommunications operators exhibit highest price sensitivity; aerospace and defense agencies absorb premium tiers without volume negotiation.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and South Korea manage hub-and-spoke fulfillment for ground station components and tether spooling systems. Carbon fiber precursor manufacturing draws from Japanese and American suppliers, while fiber-optic core drawing concentrates in China and the Netherlands. Single-source vulnerability sits with specialized micro-tensioning actuator producers in France and Switzerland. Distribution runs through defense contractor integrators and direct municipal procurement channels, bypassing traditional industrial distributors for classified deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tethered drone system market sits in a technology-transition phase as carbon fiber composite tethers displace copper-heavy legacy cables, compressing payload economics and extending flight duration capabilities.
For Market Incumbents: Anticipate free-flying drone battery improvements by accelerating automated control system R&D investments and securing FAA Part 107 waiver expansion for beyond-visual-line-of-sight operations. Deepen backward integration into carbon fiber tether manufacturing to offset copper price volatility exposure. Lock in multi-year service contracts with NATO procurement channels before experimental framework consolidation raises certification barriers.
For New Entrants and Emerging Players: Enter via telecommunications network resilience white space in hurricane-prone coastal regions where mobile operators seek cellular-on-wheels alternatives. Target industrial asset monitoring in German and Indian refinery corridors where persistent thermal inspection demand outpaces defense-grade supplier capacity. Pursue equipment-as-a-service municipal procurement channels that bypass capital equipment purchase approval cycles.
For Investors and Strategic Acquirers: FAA Part 107 waiver reform acceleration is the leading indicator that commercial certification timelines will compress competitive moats around established vendors. Long-term viability favors automated control system specialists with proprietary micro-tensioning IP over hardware-commoditized platform assemblers. Watch EASA U-space type-certification completion rates in Germany and France as the signal for European market access consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Control System Acquisition | Proprietary micro-tensioning IP from Elistair-tier engineering teams eliminates pilot dependency and reduces labor costs. |
| FAA Part 107 Waiver Expansion | Beyond-visual-line-of-sight certification acceleration opens commercial surveillance contracts to non-defense vendors. |
| Carbon Fiber Tether Backward Integration | In-house composite manufacturing insulates margins from commodity copper volatility and Japanese precursor supply constraints. |
| Equipment-as-a-Service Launch | Operational availability contracting displaces capital purchases among US first responder agencies and telecommunications providers. |
| EASA U-space Type Certification | Pre-certified equipment positioning filters uncertified competitors from German and French procurement channels. |
Research Methodology
Multi-period observation of FAA waiver approval timelines, NATO procurement contract awards, and EASA certification completion rates anchored the trend analysis, supplemented by interviews with defense contractor program managers, telecommunications network operations directors, municipal emergency management coordinators, and tether system engineering leads. Secondary validation drew from FAA Part 107 waiver databases, EASA U-space regulatory filings, NATO procurement transparency reports, and ISO 21384-3 compliance registries. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Input-output matrix modeling mapped tether material costs, ground station manufacturing capacity, and operator certification velocity against procurement volume projections across the analysis window. Segmentation dimensions included product architecture, end-use vertical, application scenario, and regulatory certification tier. CAGRs derived from installed base growth rates and replacement cycle compression in military surveillance programs. Industry-specific forecast inputs incorporated fiber-optic bandwidth demand curves and copper commodity futures trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EASA regulatory delay scenarios or accelerated battery technology breakthroughs in competing free-flying platforms. Forecasts reflect documented assumptions regarding waiver reform implementation pace and defense budget continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Military Robots Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
Drone Battery System Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
United States ROV Market
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Drone Tethered Stations Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
High Altitude Long Endurance Market