
 Drone Delivery Services Market | 2026-2036
Drone Delivery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Delivery Services Market Analysis
Healthcare logistics is rebalancing the end-use mix as hospitals and pharmacies deploy autonomous aerial transport for time-critical specimens and pharmaceuticals. Zipline International Inc. dominates long-range medical supply networks across African and American markets. Wing Aviation LLC leverages Alphabet's airspace management technology to sustain suburban grocery and retail delivery operations. Amazon Prime Air anchors its position through in-house production of custom unmanned aircraft with proprietary sense-and-avoid systems.
Drone delivery services encompass autonomous or remotely piloted aerial systems engineered to transport payloads between distribution points and end recipients, typically operating at altitudes below 400 feet with electric propulsion and precision landing within three-meter target zones. These services eliminate last-mile ground congestion while reducing per-delivery labor costs and carbon intensity relative to conventional van fleets. Medicine transport leads service type segmentation due to high value-to-weight ratios and stringent time sensitivity, while retail shipping represents the fastest-expanding category as major e-commerce retailers integrate aerial lanes into fulfillment networks. The less-than-5-kg payload capacity tier captures the dominant volume share, though the 5-10-kg bracket holds concentrated margin pools for specialized pharmaceutical and perishable cargo.
The FAA's Part 135 certification and evolving beyond-visual-line-of-sight waivers govern commercial operations in the United States, while the EASA's Specific Category framework under EU Regulation 2019/947 shapes European market access requirements. China's CAAC drone traffic management trials and Japan's MLIT flight corridor designations add further regulatory complexity for cross-border platform deployment. Stakeholders must monitor which jurisdictions first standardize unified airspace integration protocols, as these decisions will determine where capital-intensive fleet investments achieve regulatory clarity and operational scale.
Market Dynamics
Beyond-visual-line-of-sight waivers from the FAA are compressing route certification timelines while battery energy density improvements are extending operational radii for electric unmanned aircraft systems.
Growth Catalysts
- FAA Part 135 Certification Pathway:The FAA's air carrier certification framework for unmanned aircraft is creating formal commercial operating authority for drone delivery providers in the United States.
- Healthcare Logistics Demand:Hospital networks and pharmacy chains are deploying autonomous aerial transport for time-critical specimen and pharmaceutical shipments.
- Suburban Corridor Density:United States metropolitan peripheries with detached single-family housing provide accessible landing zones and predictable delivery windows.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cathode material processing and cell manufacturing concentrate in East Asian supply chains, exposing fleet operators to input cost volatility and geopolitical friction.
- Airspace Integration Technical Limits:Detect-and-avoid systems face degraded performance in dense urban electromagnetic environments, restricting operations to suburban and rural corridors.
- Ground Infrastructure Capital Requirements:Vertiport construction, charging stations, and maintenance facilities demand upfront investment that constrains bootstrap expansion.
Strategic Opportunities
- EU U-Space Regulatory Framework:EASA's unified airspace management system for unmanned traffic is creating a standardized operating environment across European member states.
- Perishable Grocery Expansion:Temperature-controlled payload compartments enable fresh food delivery, opening new service categories beyond dry goods and pharmaceuticals.
- AI-Powered Dynamic Routing:Machine learning convergence with real-time weather and traffic data is enabling on-demand route optimization that reduces per-delivery energy consumption.
Industry Challenges
- Certified Remote Pilot Talent Scarcity:Commercial drone operators require FAA Part 107 certification with recurrent training, creating a bottleneck for fleet scaling.
- Legacy Warehouse Management Integration:Existing fulfillment software lacks native API support for autonomous aerial dispatch, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Delivery Services Market |
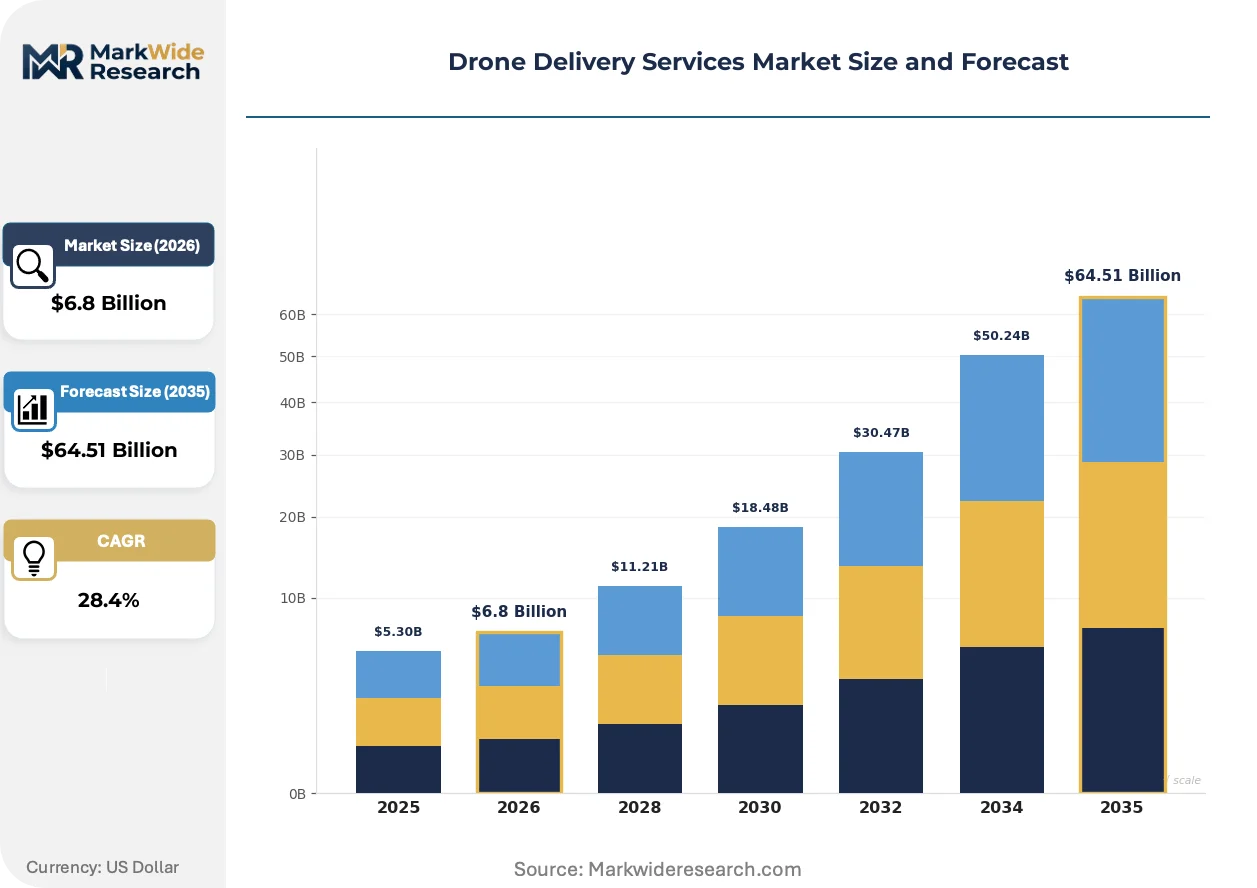
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $64.51 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food Delivery, Medicine Transport, Retail Shipping, Parcel Services End User: Healthcare Providers, E-commerce Retailers, Consumers, Logistics Companies Payload Capacity: Less than 5 kg, 5-10 kg, 10-20 kg, Over 20 kg Operational Range: Urban Areas, Suburban Areas, Rural Areas, Long-Distance |
| Companies Covered | Zipline International Inc., Wing Aviation LLC, Matternet Inc., Manna Drone Delivery, Flytrex Inc., Amazon Prime Air, United Parcel Service of America, Inc., Wingcopter GmbH, Joby Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Delivery Services Market Emerging Trajectories
Autonomous aerial logistics is shifting from pilot demonstration programs toward integrated fulfillment infrastructure as regulatory clarity and technical reliability converge.
Swappable battery architecture is modularizing fleet maintenance protocols. Logistics operators adopting hot-swap systems reduce aircraft downtime from hours to minutes. This modularizing approach compresses capital requirements by enabling smaller fleet sizes to achieve equivalent daily delivery volumes.
EASA's Specific Category framework under EU Regulation 2019/947 is standardizing risk assessment methodologies for unmanned operations. The regulation mandates operational authorization based on specific risk rather than prescriptive design standards. European healthcare networks and retail distributors are responding by consolidating vendor qualification processes around EASA-certified operators.
Hospital procurement departments are unbundling emergency medical logistics from bundled distribution contracts. Standalone aerial courier agreements are displacing incumbent ground-based logistics incumbents for stat laboratory specimens and temperature-sensitive biologics. This pattern is most visible in United States metropolitan hospital systems with Level I trauma centers and centralized laboratory facilities.
Drone Delivery Services Market Segmentation
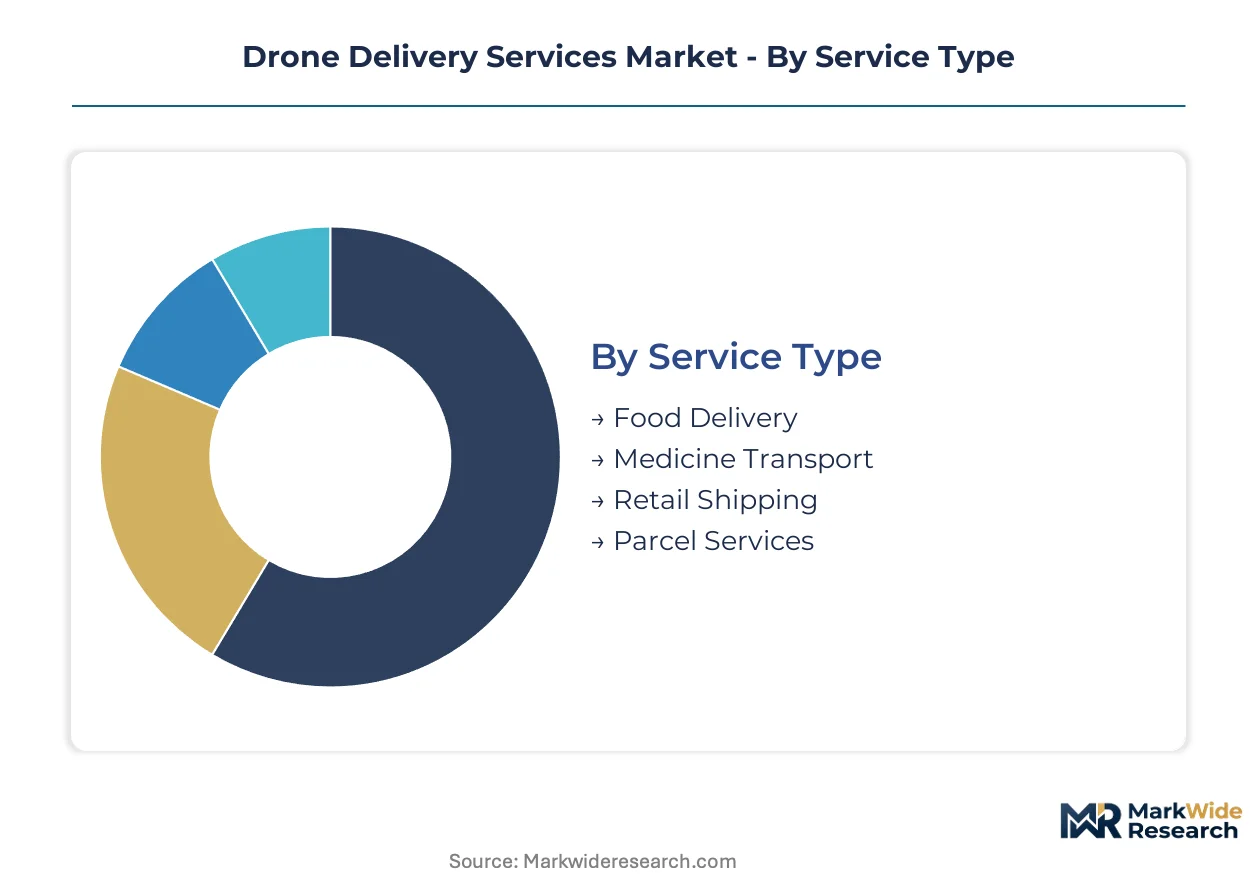
Drone delivery services fragment across operational dimensions that determine fleet configuration, regulatory pathway, and margin structure. Payload constraints and range requirements dictate aircraft selection, while end-use concentration shapes route density and revenue per stop.
Service Type:
Standalone aerial courier networks operate alongside embedded logistics partnerships, with integration depth varying by payload sensitivity and delivery urgency.
- Medicine Transport:Temperature-controlled compartments maintain cold-chain integrity for biologics and stat laboratory specimens. Hospital networks in the United States deploy dedicated aerial lanes between centralized laboratories and satellite clinics, driven by specimen degradation windows measured in hours.
- Retail Shipping:E-commerce fulfillment integration demands API-native dispatch systems compatible with existing warehouse management software. Suburban corridor density in the United States enables predictable delivery windows that anchor customer retention metrics.
- Food Delivery:Thermal insulation and rapid turnaround protocols preserve meal quality during short-haul operations.
- Parcel Services:General cargo networks compete with incumbent ground couriers on cost-per-mile in low-density routes.
Volume placements concentrate in Medicine Transport; the faster expansion belongs to Retail Shipping.
End User:
Procurement authority sits with centralized supply chain functions in institutional buyers versus distributed decision-making among individual consumers.
- Healthcare Providers:Hospital procurement departments unbundle emergency logistics from bundled distribution contracts. Level I trauma centers in the United States negotiate standalone aerial courier agreements for stat specimen transport.
- E-commerce Retailers:Fulfillment network operators integrate aerial lanes into last-mile infrastructure. Amazon Prime Air anchors proprietary fleet deployment with in-house aircraft production.
- Logistics Companies:Third-party carriers adopt unmanned systems to reduce labor cost exposure in rural route extensions.
- Consumers:Direct-to-recipient demand concentrates in premium convenience segments with low price sensitivity.
Healthcare Providers dominate current contract value; E-commerce Retailers are climbing the fastest in fleet commitment scale.
Payload Capacity:
Energy consumption scales non-linearly with mass, compressing economic viability thresholds above specific weight breakpoints.
- Less than 5 kg:Electric multirotor systems achieve maximum endurance efficiency in this bracket. Pharmaceutical single-dose shipments and consumer electronics dominate route manifests.
- 5-10 kg:Specialized pharmaceutical containers and perishable grocery bundles occupy this tier. Temperature-controlled compartments add structural weight that consumes available margin.
- 10-20 kg:Fixed-wing or hybrid lift configurations become necessary for efficient transport. Medical supply kits and consolidated retail shipments stretch battery energy density limits.
- Over 20 kg:Heavy-lift platforms require combustion-hybrid or hydrogen fuel cell propulsion. Industrial parts and emergency relief supplies justify operational complexity.
Unit economics favor Less than 5 kg for route density; 5-10 kg gains share fastest as grocery networks expand temperature-controlled service.
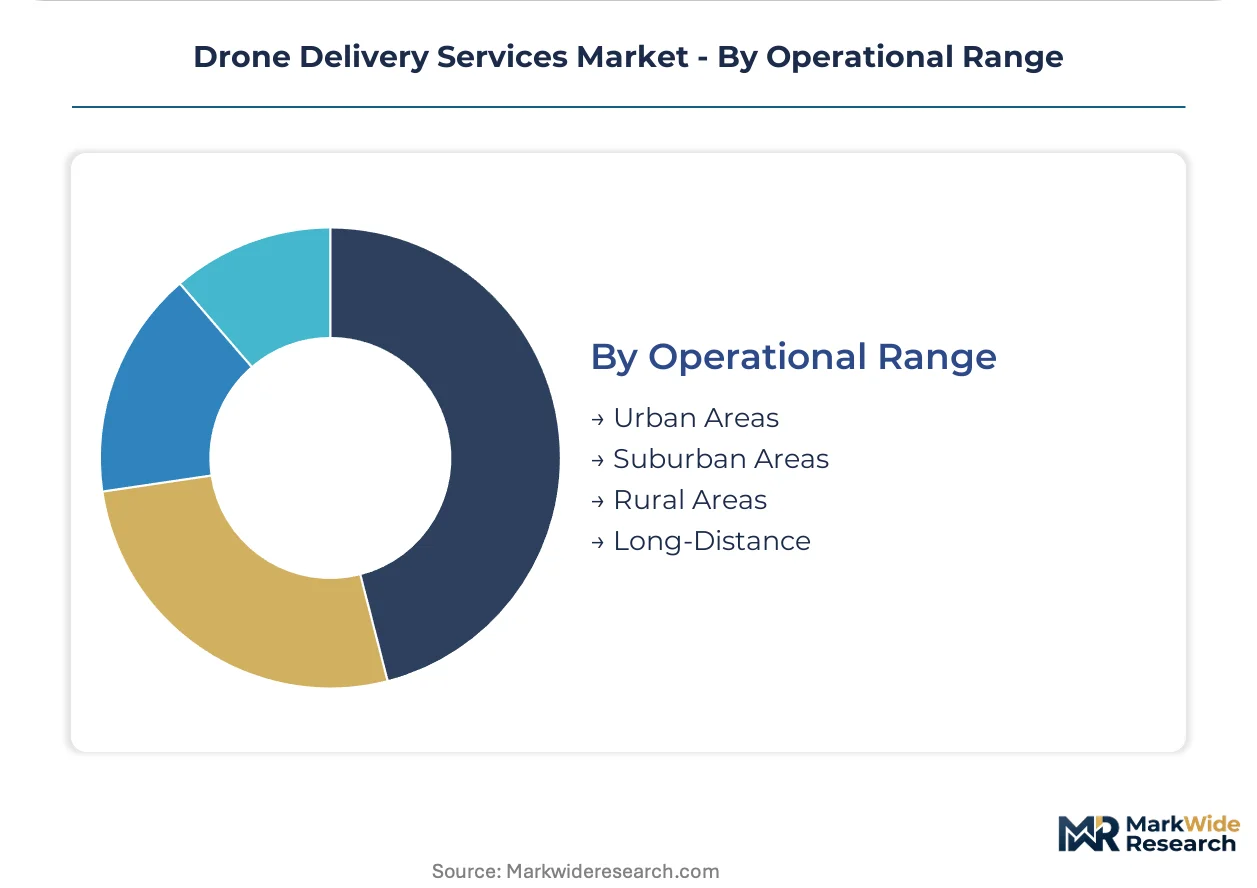
Operational Range:
Regulatory waivers and detect-and-avoid capability determine where autonomous systems receive operational authorization.
- Suburban Areas:Detached single-family housing provides accessible landing zones with minimal electromagnetic interference. The FAA's beyond-visual-line-of-sight waivers concentrate in United States metropolitan peripheries.
- Urban Areas:Dense electromagnetic environments degrade sense-and-avoid performance. Vertiport infrastructure requirements and airspace congestion limit scaled deployment.
- Rural Areas:Sparse population density reduces collision risk but stretches range requirements beyond battery endurance. Zipline International Inc. dominates long-range medical networks across African markets.
- Long-Distance:Cross-jurisdictional operations demand harmonized airspace protocols. EASA's U-Space framework and FAA corridor designations remain uncoordinated.
Suburban Areas anchor current fleet deployment; Long-Distance shows steepest expansion trajectory as cross-border medical networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in the United Arab Emirates and regulatory sandboxes in North Carolina are concentrating capital deployment for autonomous aerial logistics. These designated corridors accelerate certification timelines while shielding operators from standard airspace restrictions. Cross-border harmonization remains fragmented, with each jurisdiction advancing distinct integration protocols.
United States
Suburban sprawl around Dallas-Fort Worth and Phoenix generates dense delivery corridors with accessible landing zones. The FAA's Part 135 air carrier certification and expanding beyond-visual-line-of-sight waivers enable scaled commercial networks. North Carolina's Integration Pilot Program anchors multi-operator testing for medical supply routes between Raleigh-Durham hospital systems.
China
E-commerce fulfillment demand from Alibaba and JD.com drives fleet commitments across the Yangtze River Delta. The CAAC's drone traffic management trials in Shenzhen and Hangzhou establish segregated low-altitude corridors for autonomous cargo. Guangdong Province hosts concentrated manufacturing of electric unmanned aircraft with integrated sense-and-avoid systems.
Germany
Pharmaceutical distribution networks in Baden-Württemberg and North Rhine-Westphalia deploy aerial couriers for temperature-sensitive biologics. EASA's Specific Category framework under EU Regulation 2019/947 standardizes risk-based operational authorization across member states. The Frankfurt Rhine-Main metropolitan region hosts vertiport infrastructure pilots linking university hospitals with centralized laboratories.
Australia
Vast rural distances between mining settlements and remote medical clinics create natural demand for long-range autonomous transport. The Civil Aviation Safety Authority's remotely piloted aircraft system regulations permit beyond-visual-line-of-sight operations in designated corridors. Queensland's drone delivery trials connect coastal distribution centers with inland agricultural communities across the Darling Downs.
Japan
Aging rural populations and mountainous terrain constrain ground-based logistics to island communities and isolated valleys. The Ministry of Land, Infrastructure, Transport and Tourism designates specific flight corridors above Tokyo Bay and Osaka Bay for commercial unmanned operations. Fukushima Prefecture hosts regulatory sandbox programs testing emergency supply drops to disaster-prone coastal municipalities.
Drone Delivery Services Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated operators capturing premium-tier healthcare contracts while third-party fleet providers serve retail fulfillment networks. Market structure tilts toward consolidation among long-range medical specialists and fragmentation among last-mile grocery operators. Three archetypes dominate: vertically integrated technology developers, logistics incumbents with captive aerial divisions, and pure-play drone-as-a-service platforms. Capacity expansion and strategic partnerships with hospital procurement departments represent the dominant competitive moves.
Among North American medical logistics specialists, Zipline International Inc. and Matternet Inc. exemplify the long-range healthcare archetype with established African and American networks. Wing Aviation LLC occupies a distinct position leveraging Alphabet's airspace management heritage for suburban retail density. Wingcopter GmbH represents European engineering-focused fabrication with tilt-rotor configurations suited to pharmaceutical temperature control requirements.
| Leading Market Players |
|---|
| Zipline International Inc. |
| Wing Aviation LLC |
| Matternet Inc. |
| Manna Drone Delivery |
| Flytrex Inc. |
| Amazon Prime Air |
| United Parcel Service of America, Inc. |
| Wingcopter GmbH |
| Joby Aviation |
| Others |
Supply Flow & Price Mechanics
Certified remote pilot concentration in the United States Southwest generates labor-cost differentials that widen pricing-tier spreads between premium FAA Part 135-certified operators and standard-tier providers.
Pricing Analysis
Short lead-time premiums dominate contract structures, with stat medical specimen deliveries commanding substantial markups over scheduled pharmaceutical shipments. Pricing stratifies across premium, standard, and economy tiers based on FAA certification level and payload temperature-control specifications. Cost compression in the economy tier is intensifying because uncertified operators compete on spot inventory availability. Hospital procurement departments exhibit lowest price sensitivity due to specimen degradation windows, while retail fulfillment networks negotiate aggressively on per-delivery rates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fleet demand from Amazon Prime Air and Wing Aviation, while distributor networks serve mid-tier operators. Lithium-ion cell manufacturing concentrates in China, South Korea, and Japan, with cathode material processing anchored in Chinese supply chains. Fleet operators draw from specialized aerospace-grade composites, precision motors, and sense-and-avoid sensor arrays. Single-source vulnerability in rare-earth magnet supply creates exposure to export restriction shocks. Distribution runs through vertically integrated manufacturers and third-party logistics assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous detect-and-avoid systems are displacing legacy ground-based pilot networks, compressing the technology-transition window for operational deployment.
For Market Incumbents: Extend FAA Part 135 certification coverage into additional metropolitan corridors before BVLOS waiver scarcity hardens competitive moats. Acquire specialized temperature-control engineering talent to defend healthcare contract renewals against Wingcopter's pharmaceutical-focused tilt-rotor platforms. Deepen in-house production of custom airframes to reduce exposure to East Asian battery supply volatility. For New Entrants and Emerging Players: Begin with rural medical networks in Australia and Japan where ground infrastructure gaps create natural demand density and regulatory sandboxes lower entry barriers. Target perishable grocery expansion in European suburban corridors under EASA U-Space standardization. Pursue hospital procurement department direct sales rather than incumbent logistics partnership channels. For Investors and Strategic Acquirers: Re-rating potential sits with long-range medical specialists given cross-border corridor harmonization catalysts. Five-to-ten year viability favors operators with African network scale and FAA certification depth over retail-focused suburban players. Monitor EASA-FAA regulatory coordination signals as inflection indicator for capital-intensive fleet investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Regulatory Certification | FAA Part 135 air carrier authorization unlocks scaled commercial route networks in United States suburban corridors. |
| Temperature-Controlled Payload Development | Specialized pharmaceutical compartments enable cold-chain biologics transport for Level I trauma center networks. |
| Swappable Battery Architecture | Modular hot-swap systems compress aircraft downtime from hours to minutes, reducing required fleet size. |
| AI-Powered Dynamic Routing | Machine learning convergence with real-time weather data reduces per-delivery energy consumption for retail networks. |
| Vertiport Infrastructure Partnership | Ground facility construction with municipal authorities anchors landing zone access in dense metropolitan peripheries. |
Methodological Framework
FAA regulatory filings, EASA operational authorization databases, and hospital procurement contract records formed the secondary backbone, supplemented by primary interviews with fleet operations directors, BVLOS certification consultants, pharmaceutical logistics managers, and vertiport infrastructure developers. Bottom-up route density modeling triangulated against top-down market sizing from disclosed fleet commitments and delivery volume estimates.
Historical trendline analysis tracked regulatory waiver issuance patterns and battery energy density improvements across the analysis window. Segmentation dimensions modeled include payload capacity tier, operational range category, end-use vertical, and regional regulatory framework cluster. CAGRs derived from fleet deployment trajectories, operator revenue disclosures, and healthcare logistics contract values. Forecast inputs incorporated lithium-ion supply cost curves and detect-and-avoid technology maturation timelines.
Underlying measurement precision varies by segment; medicine transport carries tighter precision than food delivery due to disclosed hospital contract values. Forecasts reflect assumptions on regulatory harmonization pace and battery chemistry advancement. Practitioners should monitor FAA-EASA corridor coordination announcements and cathode material export policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Small UAV Market
UAV
Europe Tactical UAV Market
UAV
Racing Drone Market
UAV
UAV Payload and Subsystems Market
UAV
Rotary Blade UAV Drones Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
FPV Drone Goggles Market
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
Solar-Powered UAV Market
UAV
Anti-Drone Technology Market
UAV
Enterprise Drone Management Solutions Market
UAV
Firefighting Drone Market
UAV
Multirotor Drones Market
UAV
Global Smartphone Controlled Drone Market
UAV
North America Small UAV Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market