
 Asia-Pacific Tactical UAV Market | 2026-2036
Asia-Pacific Tactical UAV Market Size, Share, and Industry Trends Forecast 2026-2036
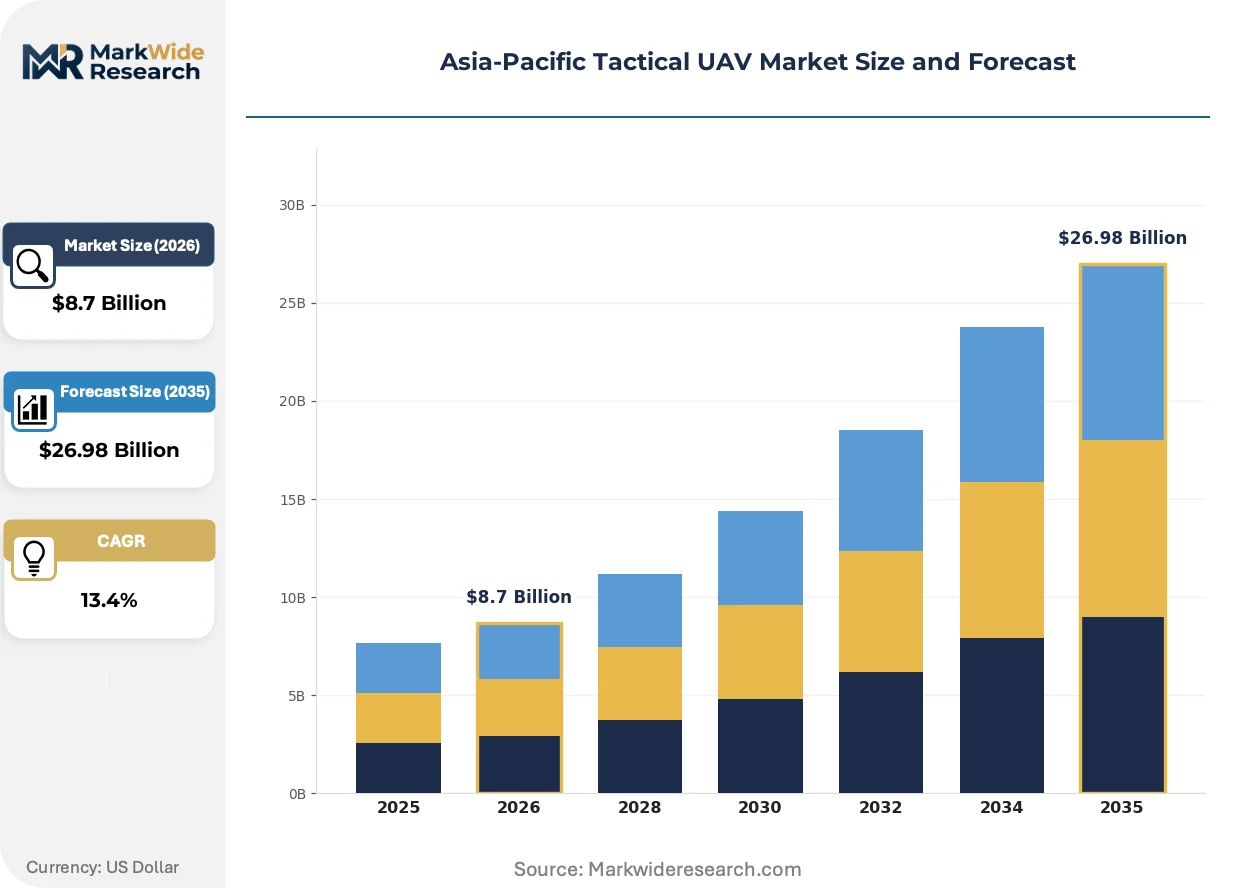
Asia-Pacific Tactical UAV Market Outlook
A capital-intensity divergence between sovereign-backed primes and commercial spin-offs is redrawing vendor hierarchy in Asia-Pacific tactical UAV supply. Elbit Systems Ltd leverages vertical integration across avionics and payload subsystems to sustain margin pools in fixed-wing surveillance contracts. China Aerospace Science and Technology Corporation anchors state-funded production scale for rotary-wing platforms serving People's Liberation Army Theater Commands.
Asia-Pacific tactical UAV denotes unmanned aerial systems designed for military and security operations at ranges below 300 kilometers, typically incorporating electro-optical/infrared sensors, synthetic aperture radar, or signals intelligence packages for real-time battlefield awareness. Fixed-wing configurations dominate endurance-intensive maritime patrol missions across Indonesia's archipelagic waters and the Philippine Exclusive Economic Zone. AI-enabled technology segments are gaining traction as networked swarming protocols mature for suppression of enemy air defense scenarios.
Japan's Ministry of Economy, Trade and Industry (METI) and South Korea's Ministry of Trade, Industry and Energy coordinate export control frameworks affecting cross-border subsystem transfers, while Australia's Defence Trade Controls Act shapes technology access for foreign primes bidding on sovereign capability programs. China's SAMR and MIIT administer domestic certification standards that constrain non-indigenous platform market access. Stakeholders must weigh sovereign capability mandates against supply chain exposure when selecting partnership structures for next-generation program bids.
Market Dynamics
AI-enabled swarming protocols are compressing procurement cycles for networked tactical UAV systems across Southeast Asian defense ministries, forcing primes to restructure subsystem integration timelines around software-first certification pathways.
Growth Catalysts
- Maritime Patrol Modernization:Indonesia's archipelagic navy commands and the Philippine Coast Guard are accelerating fleet replacement programs for endurance-intensive fixed-wing platforms covering exclusive economic zone surveillance.
- Indigenous Platform Mandates:India's revised Defense Acquisition Procedure under DRDO supervision compresses certification timelines for locally developed tactical UAV systems serving Army and Air Force operational requirements.
- Island Chain Surveillance Networks:Japan's southwestern defense corridor and Australia's northern defense corridor are deploying distributed sensor grids requiring interoperable tactical UAV relay nodes.
Market Restraints
- Export Control Fragmentation:Japan's METI and South Korea's MOTIE coordinate divergent technology transfer frameworks that fragment cross-border subsystem sourcing for foreign primes.
- Domestic Certification Barriers:China's SAMR and MIIT administer GB standards that constrain non-indigenous platform market access regardless of technical performance benchmarks.
- Specialized Avionics Concentration:Sovereign-backed primes in Israel and China maintain captive production of flight control computers and encrypted datalinks, limiting second-source options for regional integrators.
Strategic Opportunities
- AI-Enabled Swarming Contracts:Suppression of enemy air defense scenarios across Australia's northern defense corridor are creating demand for networked protocol architectures that commercial software houses can supply.
- Rotary-Wing Maritime Roles:Vertical take-off and landing platforms for shipborne deployment remain underpenetrated in Vietnam and Malaysia compared to fixed-wing saturation in Indonesia.
- Dual-Use Technology Convergence:Synthetic aperture radar miniaturization from commercial remote sensing is crossing into tactical payload specifications, opening vendor entry points outside traditional defense supply chains.
Industry Challenges
- Software-First Certification Expertise:Defense procurement offices lack personnel trained to evaluate autonomous decision algorithms under accelerated DRDO and DSTG timelines, creating bid evaluation bottlenecks.
- Encrypted Datalink Integration:Legacy command systems in Thailand and Malaysia require physical hardware retrofits to accommodate new waveform standards, extending field deployment schedules.
- Cross-Domain Interoperability:Naval, ground force, and coast guard operators maintain incompatible ground control station architectures, forcing primes to engineer multiple interface variants per national tender.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Tactical UAV Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Wing, Rotary Wing, Hybrid, Mini UAV Technology: Autonomous, Remote Piloted, AI-Enabled, Networked End User: Military, Homeland Security, Commercial, Research Application: Surveillance, Reconnaissance, Search & Rescue, Cargo Delivery |
| Companies Covered | Elbit Systems Ltd, Israel Aerospace Industries (IAI), China Aerospace Science and Technology Corporation, Korean Aerospace Industries Ltd, AeroVironment Inc, Defense Research and Development Organization (DRDO), General Atomics, SZ DJI Technology Co Ltd, Textron Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Tactical UAV Market Strategic Shifts
Electro-optical sensor miniaturization and edge-computing payload architectures are restructuring competitive advantage around software-defined mission profiles rather than airframe endurance specifications alone.
Multi-spectral gimbal systems integrating short-wave infrared with synthetic aperture radar are displacing standalone electro-optical configurations in maritime patrol contracts. Royal Australian Navy and Japan Maritime Self-Defense Force procurement offices now specify fused-sensor minimums for archipelagic surveillance tenders. This convergence is compressing supplier margins for pure-play electro-optical houses while rewarding avionics integrators with in-house radar development.
Australia's Defence Trade Controls Act amendments are tightening technology access conditions for foreign primes bidding on sovereign capability programs. The legislation now mandates domestic subsystem assembly percentages that reshape partnership structures for next-generation bids. Korean and Israeli vendors are responding by establishing joint venture entities with Australian engineering firms to satisfy local content thresholds.
Defense ministries across Southeast Asia are unbundling platform procurement from through-life support contracts, enabling specialist maintenance providers to compete separately from airframe primes. This disintermediation is most visible in Indonesian Navy and Philippine Coast Guard programs, where third-party technical support bids now outnumber integrated prime offerings. The shift rewards regional MRO networks with established depot infrastructure over foreign OEMs without local facility investments.
Asia-Pacific Tactical UAV Market Segmentation
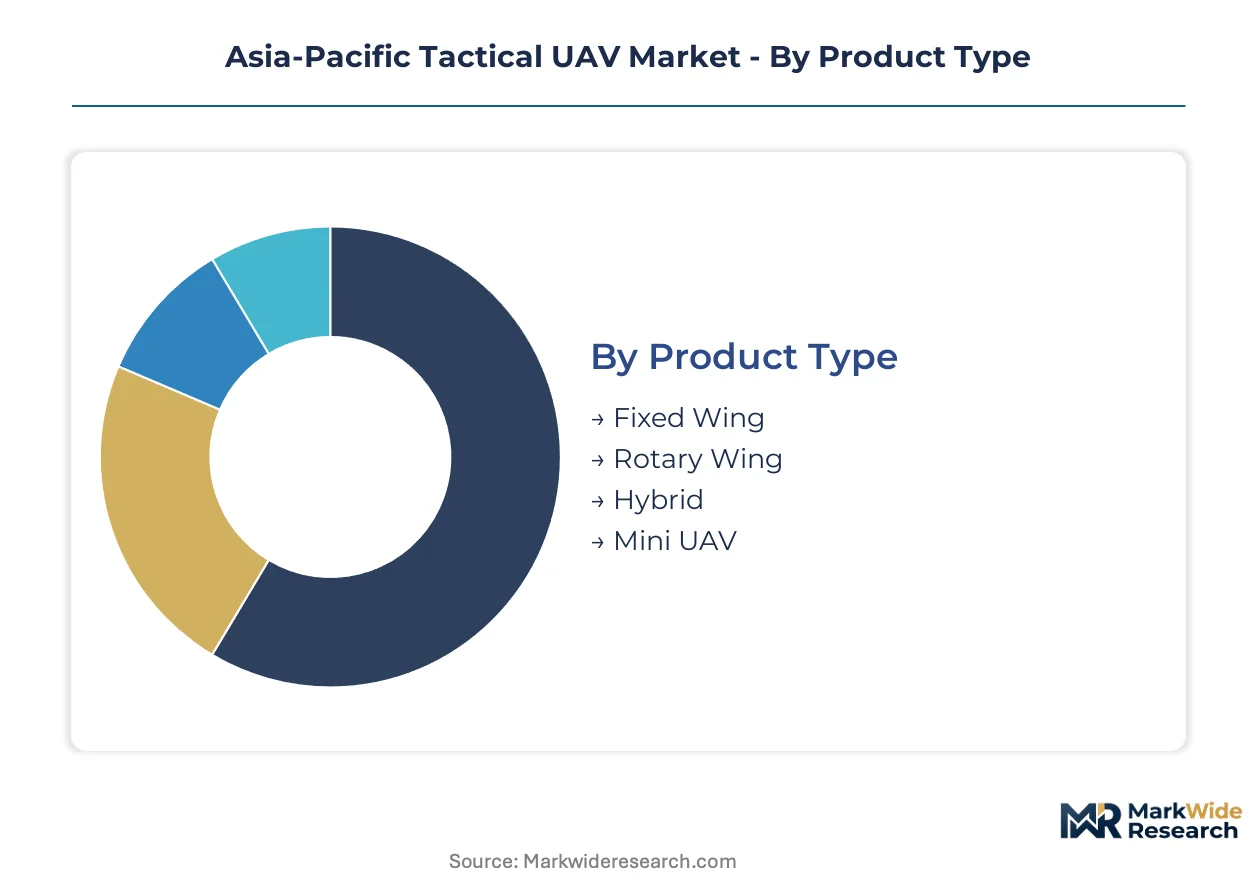
Segmentation in the Asia-Pacific tactical UAV market reveals how procurement priorities diverge across sovereign capability mandates and operational theaters. Platform configuration, autonomy level, and mission profile together determine vendor access and partnership structures in this regulated defense environment.
Product Type:
Fixed-wing platforms dominate sovereign fleet programs across Indonesia and Australia, while rotary-wing systems concentrate in shipborne naval applications. Hybrid architectures remain largely developmental outside China's state-funded pipeline.
- Fixed Wing:These endurance-optimized airframes with high-aspect-ratio wings carry electro-optical/infrared and synthetic aperture radar payloads for maritime patrol. Demand concentrates in Indonesia's archipelagic navy commands and the Philippine Coast Guard for exclusive economic zone surveillance, driven by fleet replacement timelines and EEZ enforcement mandates.
- Rotary Wing:Vertical take-off and landing capability enables deployment from frigate flight decks and austere forward operating bases without runway infrastructure. Japan's Maritime Self-Defense Force and South Korean naval aviation units are expanding rotary-wing procurement for distributed island chain operations, constrained by limited domestic VTOL engine options.
- Hybrid:Tilt-rotor and tail-sitter configurations combining fixed-wing efficiency with VTOL flexibility are advancing through DRDO and KAI development programs, though operational certification lags behind conventional architectures.
- Mini UAV:Hand-launched systems under 25kg serve platoon-level reconnaissance and urban warfare training; Australia's DSTG and Singapore's DSTA evaluate these for dismounted soldier programs with limited payload interchangeability.
Fixed Wing commands the established base across Southeast Asian maritime commands. The steepest expansion runs through Rotary Wing as shipborne deployment requirements multiply across the region's littoral navies.
Technology:
Cost tiers separate sovereign-funded autonomous development from commercial remote-piloted imports, with AI-enabled systems commanding premium positioning in suppression of enemy air defense contracts.
- Autonomous:Pre-programmed waypoint navigation with limited real-time decision authority serves established military users with conservative certification requirements. Thailand's Royal Thai Armed Forces and Malaysia's defense procurement maintain autonomous systems as the default specification for operational reliability.
- Remote Piloted:Continuous human-in-the-loop control via C-band or Ku-band datalinks dominates current operational fleets across Vietnam and the Philippines, where encrypted link infrastructure remains underdeveloped for higher-autonomy transitions.
- AI-Enabled:Onboard target recognition and dynamic route replanning are gaining traction in Australia's northern defense corridor for contested electromagnetic environments, though procurement offices lack personnel trained to evaluate autonomous decision algorithms under accelerated timelines.
- Networked:Swarming protocols enabling cooperative engagement by multiple platforms are specified in emerging Japanese and Australian tenders for suppression of enemy air defense scenarios, creating entry points for commercial software houses outside traditional defense supply chains.
Remote Piloted systems anchor current fleet composition across less digitally mature defense ministries. AI-Enabled platforms are climbing the fastest as software-first certification pathways mature under DRDO and DSTG supervision.
End User:
Customer type determines funding source stability and technology access tier, with military procurement offering volume scale and homeland security contracts enabling faster foreign vendor entry.
- Military:Army, navy, and air force operational requirements drive the largest program scale across India's Defense Acquisition Procedure and Australia's sovereign capability frameworks, subject to stringent domestic content mandates and export control compliance.
- Homeland Security:Coast guard and border patrol agencies in Indonesia, the Philippines, and Vietnam procure under dual-use frameworks with relaxed technology transfer restrictions, enabling faster fielding of foreign platforms for maritime domain awareness.
- Commercial:Infrastructure inspection and agricultural monitoring applications remain peripheral to defense-centric market definitions, though synthetic aperture radar miniaturization from commercial remote sensing crosses into tactical payload specifications.
- Research:University and national laboratory programs in Japan, South Korea, and Australia support technology maturation for subsequent military transition, funded through science ministry budgets separate from defense procurement channels.
Military end users command the established base through sovereign fleet modernization cycles. The steepest expansion runs through Homeland Security as coast guard procurement accelerates across Southeast Asian archipelagic states.
Application:
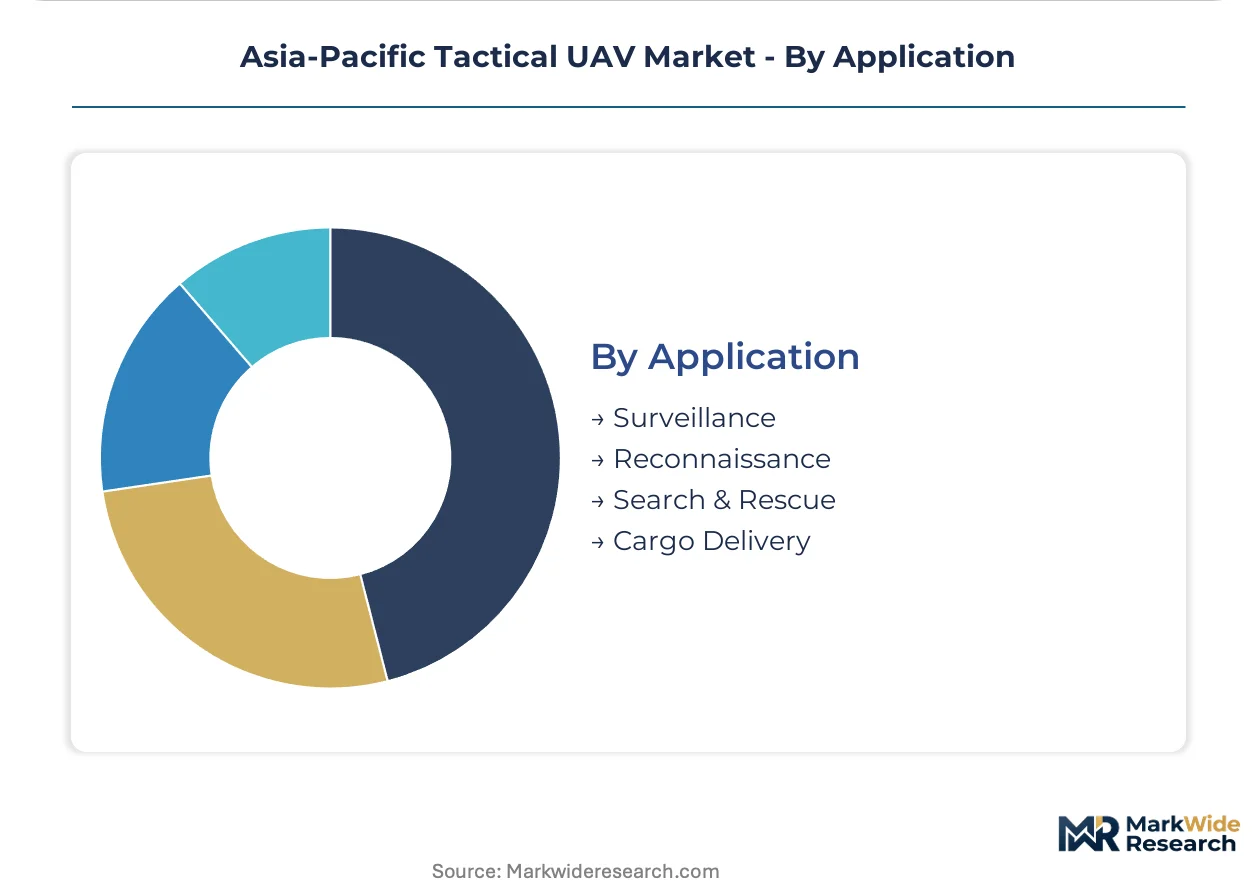
Volume concentration in surveillance reflects maritime patrol priorities, while reconnaissance and search and rescue segments show divergent margin profiles based on sensor payload complexity.
- Surveillance:Persistent electro-optical/infrared and radar coverage of maritime approaches and border regions constitutes the dominant operational requirement. Fused multi-spectral gimbal specifications from the Royal Australian Navy and Japan Maritime Self-Defense Force now displace standalone electro-optical configurations in archipelagic tenders.
- Reconnaissance:Time-sensitive target acquisition and battle damage assessment missions demand higher-resolution synthetic aperture radar and signals intelligence packages. These payload specifications concentrate in Indian Army and People's Liberation Army Theater Command procurement with compressed timeline requirements.
- Search & Rescue:Disaster response and humanitarian assistance missions leverage common airframes with surveillance configurations but require interoperable datalinks with civilian emergency management networks, creating integration complexity in Indonesia and the Philippines.
- Cargo Delivery:Last-mile resupply to distributed island garrisons and forward operating bases remains experimental across Australian and Japanese defense programs, constrained by payload-weight limitations and contested airspace survivability concerns.
Surveillance commands the established base through maritime patrol fleet replacement cycles. The steepest expansion runs through Reconnaissance as multi-spectral payload specifications advance under Indo-Pacific theater operational concepts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in tactical UAV subsystems are reshaping partnership structures across the Asia-Pacific, with sovereign capability mandates forcing foreign primes into joint venture configurations to access restricted procurement channels.
Australia
Defence Trade Controls Act amendments mandate domestic subsystem assembly percentages for sovereign capability programs. The northern defense corridor concentrates demand for interoperable tactical UAV relay nodes, with Korean and Israeli vendors establishing joint venture entities with Australian engineering firms to satisfy local content thresholds.
Japan
Maritime Self-Defense Force procurement specifications for fused multi-spectral gimbal systems are displacing standalone electro-optical configurations in archipelagic surveillance tenders. METI coordinates export control frameworks affecting cross-border subsystem transfers, while southwestern island chain surveillance networks deploy distributed sensor grids requiring networked protocol architectures.
India
Army and Air Force operational requirements drive accelerated certification timelines under DRDO supervision through revised Defense Acquisition Procedure guidelines. Indigenous platform mandates compress development schedules for locally developed tactical UAV systems, with Bangalore and Hyderabad hosting concentrated defense research clusters advancing autonomous waypoint navigation capabilities.
South Korea
Ministry of Trade, Industry and Energy coordinates divergent technology transfer frameworks with Japanese counterparts, fragmenting cross-border subsystem sourcing for foreign primes. Naval aviation units expand rotary-wing procurement for distributed island chain operations, constrained by limited domestic VTOL engine options and concentrated shipborne deployment requirements.
Indonesia
Archipelagic navy commands accelerate fleet replacement programs for endurance-intensive fixed-wing platforms covering exclusive economic zone surveillance. Dual-use procurement frameworks enable faster foreign vendor entry for coast guard maritime domain awareness programs, with third-party technical support bids now outnumbering integrated prime offerings in unbundled through-life support contracts.
Asia-Pacific Tactical UAV Market Competitive Environment
Concentration sits with sovereign-backed primes and defense-heritage conglomerates that control captive production of flight control computers and encrypted datalinks. The vendor hierarchy separates vertically integrated avionics houses from commercial spin-offs seeking entry through software-first certification pathways. Three archetypes dominate: state-funded aerospace conglomerates with guaranteed procurement pipelines, Israeli defense primes leveraging subsystem integration expertise, and Korean industrial chaebols with shipborne platform specialization. Competitive moves center on joint venture establishment for local content compliance and strategic partnerships for encrypted datalink standardization.
Within the sovereign-prime tier, Elbit Systems Ltd and Israel Aerospace Industries exemplify vertically integrated avionics houses sustaining margin pools through in-house payload subsystem production. China Aerospace Science and Technology Corporation anchors state-funded production scale for rotary-wing platforms serving domestic theater commands. Korean Aerospace Industries Ltd occupies a position bridging shipborne deployment requirements with limited domestic engine supply chains, representing the industrial chaebol archetype navigating VTOL certification constraints.
| Leading Market Players |
|---|
| Elbit Systems Ltd |
| Israel Aerospace Industries (IAI) |
| China Aerospace Science and Technology Corporation |
| Korean Aerospace Industries Ltd |
| AeroVironment Inc |
| Defense Research and Development Organization (DRDO) |
| General Atomics |
| SZ DJI Technology Co Ltd |
| Textron Inc |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for encrypted datalink subsystems lock in supply access and price visibility for Australian and Japanese defense primes navigating sovereign capability mandates. These arrangements insulate flight control computer procurement from spot-market volatility while committing buyers to minimum volume thresholds across multi-year fleet modernization cycles.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in Asia-Pacific tactical UAV procurement. Premium tiers command certification-grade avionics from Israeli and Chinese sovereign-backed primes, while economy tiers source commercial remote-piloted platforms for Southeast Asian coast guard dual-use programs. Cost compression in standard-tier fixed-wing surveillance contracts intensifies as Indonesian and Philippine fleet replacement programs consolidate volume awards. Homeland security agencies exhibit highest price sensitivity due to dual-use procurement frameworks, whereas military end users prioritize performance benchmarks over unit economics.
Supply Chain Analysis
Israel and China anchor captive production of flight control computers and encrypted datalinks for tactical UAV systems serving domestic and export defense programs. Taiwan and South Korea supply advanced semiconductor components for edge-computing payload architectures, while Australia and Japan concentrate final assembly for sovereign capability compliance. Raw material dependencies span gallium nitride for radar transmitters, carbon fiber composites for airframes, and rare earth elements for sensor stabilization systems. Single-source vulnerability concentrates in Israeli encrypted waveform standards, with distribution running through defense ministry procurement offices and joint venture entities established for local content thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Through-life support contracts and third-party technical service agreements are expanding faster than platform hardware sales across Indonesian and Philippine defense procurement. This service-attach dynamic rewards regional MRO networks with established depot infrastructure over foreign OEMs lacking local facility investments.
For Market Incumbents: Consolidate encrypted datalink standardization partnerships to defend against commercial software houses entering AI-enabled swarming protocol development. Deepen backward integration into multi-spectral gimbal production as Royal Australian Navy and Japan Maritime Self-Defense Force specifications displace standalone electro-optical configurations. Secure capacity reservation agreements with Taiwanese semiconductor foundries to mitigate gallium nitride component shortages affecting radar payload delivery timelines. For New Entrants and Emerging Players: DRDO accelerated certification pathways under India's revised Defense Acquisition Procedure offer entry points for autonomous waypoint navigation software vendors. Rotary-wing maritime applications remain underpenetrated in Vietnam and Malaysia compared to fixed-wing saturation in Indonesia, presenting white-space opportunities for vertical take-off and landing platform specialists. Target coast guard procurement channels in archipelagic Southeast Asian states where dual-use frameworks relax technology transfer restrictions and enable faster fielding than military tender processes. For Investors and Strategic Acquirers: Capital is best deployed toward regional MRO networks with established depot infrastructure and sovereign capability joint venture entities possessing Australian Defence Trade Controls Act compliance credentials. Long-term viability across the analysis window hinges on positioning for unbundled through-life support contract expansion rather than integrated prime offerings. Monitor Indonesian Navy and Philippine Coast Guard procurement office staffing levels as inflection indicator for accelerated third-party technical support bid evaluation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Establishment | Korean and Israeli vendors form Australian engineering partnerships to satisfy Defence Trade Controls Act local content thresholds. |
| Software-First Certification Pathway | Commercial software houses bypass traditional defense supply chains through AI-enabled swarming protocol development for Australian SEAD scenarios. |
| Backward Integration into Gimbal Production | Avionics integrators with in-house radar development capture margin pools as fused multi-spectral specifications displace electro-optical-only vendors. |
| Regional MRO Network Acquisition | Third-party technical support providers outnumber integrated prime offerings in Indonesian Navy unbundled procurement structures. |
| Encrypted Datalink Standardization Partnership | Legacy command system hardware retrofits in Thailand and Malaysia create extended deployment schedules for waveform-compatible suppliers. |
Study Parameters
Desk research of defense procurement databases, customs trade records, and regulatory filing repositories preceded structured interviews with program managers at Southeast Asian navy commands, procurement officers at Australian DSTG, and technical directors at Israeli avionics houses. Secondary validation drew from DRDO certification timelines, METI export control frameworks, and Defence Trade Controls Act amendment records. Bottom-up platform deployment estimates triangulated against top-down defense budget allocation analysis across the analysis window.
Variance-decomposition framing separated volume drivers from price realization factors across platform configuration, autonomy level, and end-user segments. Modeled dimensions span fixed-wing versus rotary-wing architecture, remote-piloted versus AI-enabled technology tiers, and military versus homeland security customer channels. CAGRs derived from logistic diffusion curves fitted to fleet replacement timelines and sovereign capability procurement cycles. Industry-specific inputs include encrypted datalink infrastructure development rates and software-first certification pathway adoption curves.
Underlying assumptions cover sustained defense budget commitments across Indo-Pacific theater commands, with deviation risk concentrated in export control framework harmonization between Japan's METI and South Korea's MOTIE. Forecasts reflect procurement cycle acceleration under DRDO supervision and Australian sovereign capability mandates. Recalibration cycles align with material shifts in AI-enabled swarming protocol maturation and unbundled through-life support contract prevalence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Europe Tethered Drone Market
UAV
Middle-East and Africa Small UAV Market
UAV
Auto-Follow Drone Market
UAV
Short-Range Delivery Drone Market
UAV
Micro Drone Market
UAV
UAV Drones Market
UAV
Drone Data Management Market
UAV
Drone Flight Controller System Market
UAV
Asia-Pacific Tethered Drone Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Toy Drones Market
UAV
Global Drone Services Market
UAV
Global Target Drone Market
UAV
Global VTOL UAV Market
UAV
United States Drone Services Market
UAV
Global Aerial Imaging Market