
 Portable Drone Market | 2026-2036
Portable Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Drone Market Insights
A capital-intensity divergence between integrated sensor manufacturers and assembly-focused OEMs is unwinding competitive stability in the portable drone sector. DJI leverages captive production of gimbals and flight controllers to sustain margin compression that smaller rivals cannot absorb. Skydio differentiates through proprietary autonomy stacks that dominate enterprise security surveillance contracts. Parrot Drone SAS anchors its position in European defense and environmental research channels where national procurement preferences create defensive moats.
Portable drones are compact unmanned aerial vehicles typically weighing under 25 kilograms with foldable airframes, integrated GPS navigation, and battery-powered propulsion designed for rapid field deployment without dedicated launch infrastructure. Quadcopter configurations lead commercial volumes due to mechanical simplicity and vertical takeoff capability, while fixed-wing variants command premium pricing in surveying and mapping applications where endurance exceeds rotorcraft limits. Optical flow and lidar technology segments attract the fastest investment as infrastructure assessment and construction inspection buyers demand centimeter-level accuracy without ground control points. GPS navigation remains the mature baseline across all price tiers, though ultrasonic sensor integration is concentrating in personal recreation units where obstacle avoidance drives consumer preference.
FAA Part 107 mandates in the United States and EASA open-category frameworks in Europe impose operational altitude limits, remote identification requirements, and pilot certification standards that filter market entry and elevate compliance costs for new entrants. China's Civil Aviation Administration implements GB standards and real-name registration protocols that shape domestic product specifications and export certification pathways. Stakeholders must monitor evolving beyond-visual-line-of-sight rulemakings across these jurisdictions to anticipate which technology investments will unlock enterprise scaling opportunities.
Market Dynamics
Regulatory fragmentation across major aviation authorities is fragmenting product roadmaps, forcing manufacturers to engineer modular compliance architectures rather than unified global platforms. This structural pressure elevates engineering overhead while creating defensive moats for incumbents with established certification pathways.
Growth Catalysts
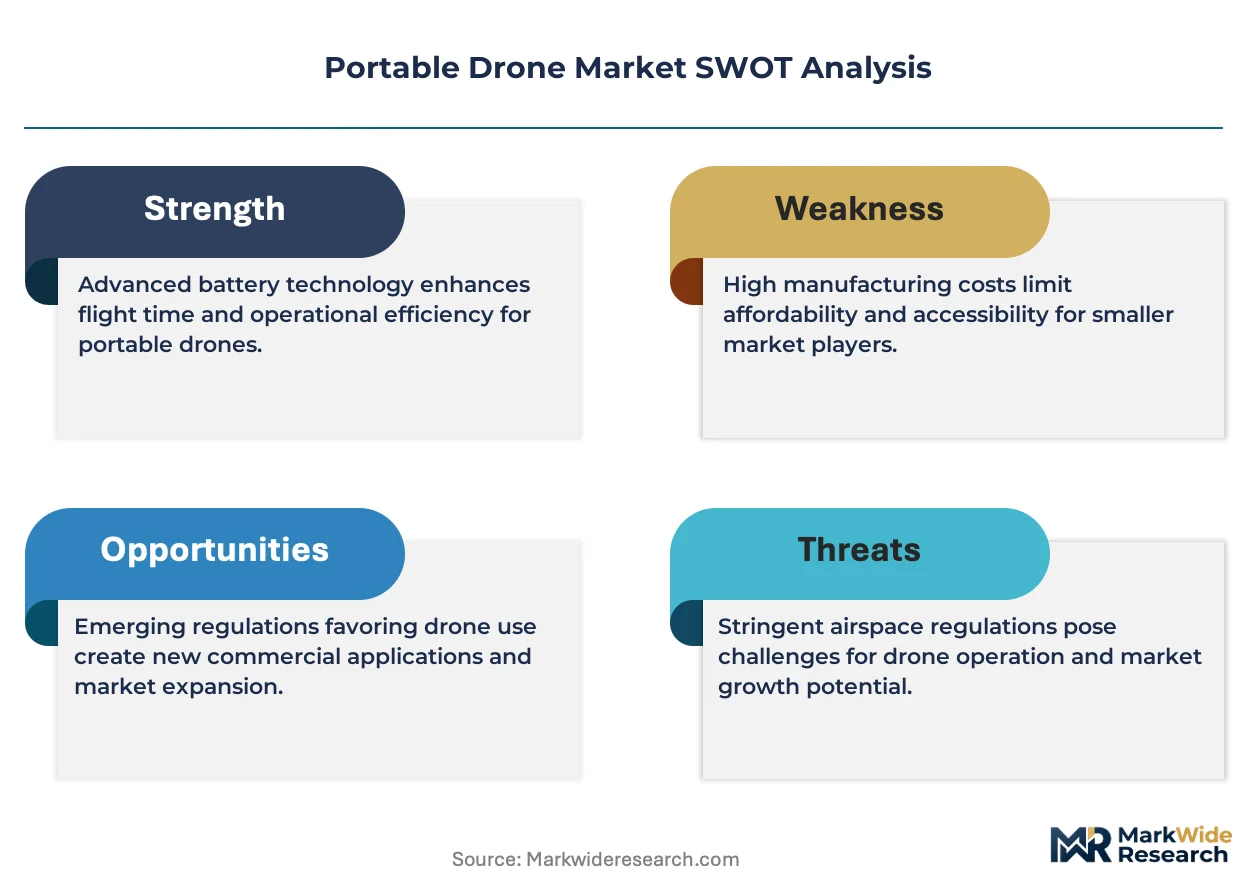
- Beyond-Visual-Line-of-Sight rulemakings:FAA and EASA pilot programs for BVLOS operations in controlled airspace unlock enterprise inspection contracts in energy infrastructure and telecommunications.
- Agriculture sector digitization:Farmers deploy multispectral imaging payloads for nitrogen stress mapping and irrigation optimization, converting drone hardware into precision agriculture input.
- China:Civil Aviation Administration clarity on GB standards and real-name registration accelerates domestic commercial deployment across emergency response and surveying applications.
Market Restraints
- Supply concentration in rare earth magnet processing:Permanent magnet motors depend on concentrated refining capacity, exposing motor manufacturers to input volatility and export restriction risk.
- Technical limitation in solid-state battery energy density:Current lithium-polymer alternatives constrain flight endurance below 45 minutes for sub-2kg platforms, limiting mapping mission economics.
- Regulatory friction from Remote ID mandates:FAA and EASA broadcast requirements impose hardware retrofit costs on legacy fleet operators and certification delays for new entrants.
Strategic Opportunities
- Underpenetrated sub-Saharan Africa:Agricultural extension services and mineral exploration operations lack aerial survey infrastructure, creating first-mover advantages for ruggedized, low-maintenance platforms.
- Technology convergence of edge AI and 4G/5G mesh networking:Onboard inference combined with distributed relay architectures enables swarm coordination for search-and-rescue and wildfire monitoring.
- India PLI scheme:Production-linked incentives for electronics manufacturing attract component assembly and testing facilities, reshaping regional supply configuration.
Industry Challenges
- Certification timeline compression:EASA specific-category and FAA Part 107 waiver processes demand 12-18 month validation cycles that outpace product refresh rates.
- Integration complexity with legacy GIS workflows:Surveying and construction buyers require seamless data pipeline compatibility with established photogrammetry software suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Drone Market |
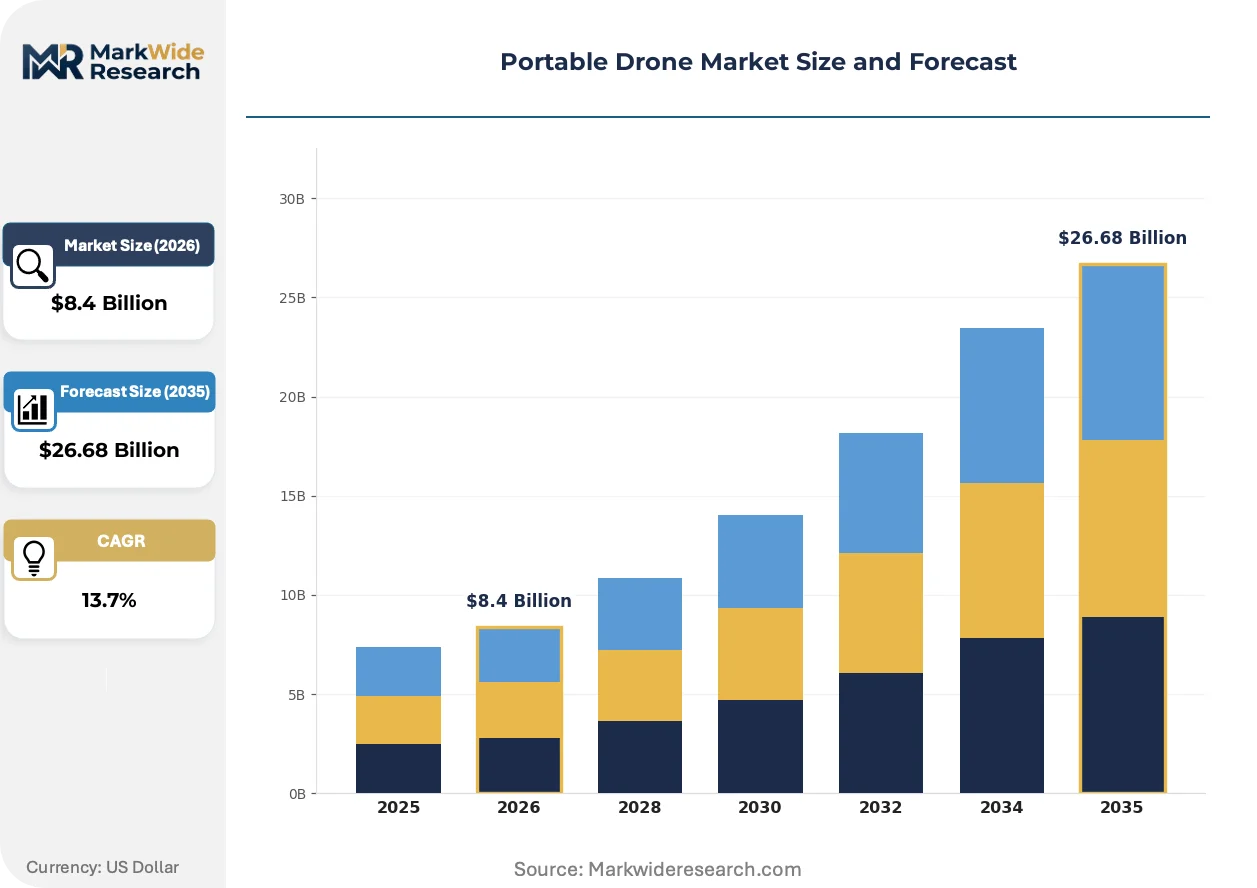
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadcopter, Fixed-Wing, Hybrid, Single-Rotor, Multi-Rotor Technology: GPS Navigation, Optical Flow, Infrared Sensors, Lidar, Ultrasonic Sensors Application: Surveying & Mapping, Construction Inspection, Agriculture, Emergency Response, Security Surveillance End User: Aerial Cinematography, Wildlife Monitoring, Infrastructure Assessment, Personal Recreation, Environmental Research |
| Companies Covered | DJI, Parrot Drone SAS, Yuneec International, Autel Robotics, AeroVironment, Skydio, Hubsan, Horizon Hobby, 3D Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Drone Market Trends and Innovations
Autonomy stacks and sensor miniaturization are compressing the performance gap between consumer and professional-grade platforms, while regulatory clarity on operational categories is unlocking enterprise deployment at scale.
Optical flow positioning systems paired with lightweight lidar modules is supplanting traditional GPS-dependent navigation in GPS-denied environments such as indoor warehouses and dense urban canyons. Mining operators and security integrators in Australia and Canada are adopting these configurations for underground inspection and perimeter monitoring. This convergence is compressing the addressable market for dedicated indoor drone specialists while elevating baseline capability expectations across all price tiers.
EASA open-category framework and FAA Remote ID final rule are mandating broadcast identification and geofencing compliance that filter non-compliant hardware from commercial channels. Hardware manufacturers must redesign flight controllers and firmware architectures to satisfy real-time telemetry requirements. European environmental monitoring contracts and US infrastructure inspection bids now specify Remote ID readiness as a mandatory qualification criterion.
Enterprise buyers are consolidating vendor relationships through multi-year fleet management agreements that bundle hardware, software, maintenance, and pilot training. Agricultural cooperatives and utility operators in Brazil and Spain are displacing transactional equipment purchases with subscription-based service models. This reconfiguration concentrates procurement influence with integrators capable of delivering regulatory compliance and operational support as unified offerings.
Portable Drone Market Segmentation
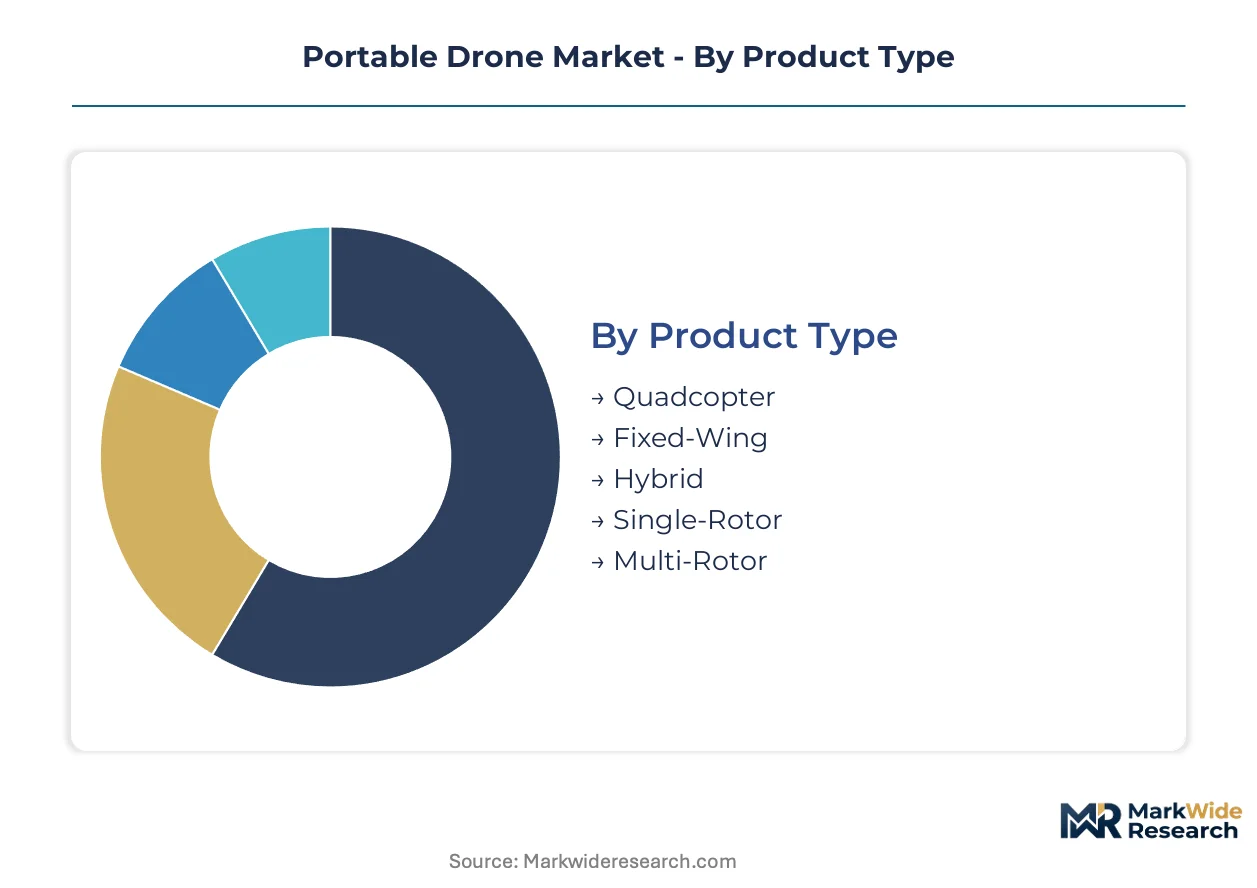
Portable drone procurement patterns diverge sharply across operational contexts, with regulatory compliance requirements and payload specifications filtering buyer choices into distinct technical tiers. Segment boundaries are hardening as EASA open-category and FAA Part 107 mandates elevate baseline capability floors for commercial eligibility.
Product Type:
FAA Part 107 certification pathways and EASA specific-category approvals concentrate engineering investment on configurations with proven airworthiness documentation, favoring established mechanical architectures over experimental formats.
- Quadcopter:Four-rotor systems with foldable airframes dominate commercial volumes through mechanical simplicity and vertical takeoff capability. Demand clusters in agriculture across Brazil and Spain where cooperatives deploy multispectral payloads for nitrogen stress mapping, though 45-minute endurance ceilings constrain large-field economics.
- Fixed-Wing:Aerodynamic airframes with pusher or tractor propulsion achieve 90-120 minute flight durations on equivalent battery mass. Surveying contractors in Australia and Canada pay premium pricing for corridor mapping missions where endurance exceeds rotorcraft limits, though catapult or hand-launch requirements restrict rapid deployment scenarios.
- Hybrid:Tilt-rotor or tail-sitter configurations combine vertical takeoff with fixed-wing cruise efficiency. Mining operators in Chile evaluate these for pit rim inspection where launch terrain is irregular.
- Single-Rotor:Helicopter-style platforms with collective pitch control offer heavy-lift capacity for industrial sensor packages. Forestry services in Scandinavia deploy these for lidar bathymetry where payload mass exceeds multi-rotor limits.
- Multi-Rotor:Hexacopter and octocopter variants provide redundancy for over-water or populated area operations. Offshore wind technicians in the North Sea specify these for turbine blade inspection where single-point-of-failure risk is unacceptable.
Established volume favors quadcopter configurations; emerging adoption favors hybrid architectures.
Technology:
Cost tier stratification separates commodity navigation stacks from precision positioning systems that unlock enterprise contract eligibility.
- GPS Navigation:Multi-constellation receivers providing 2-5 meter accuracy serve as the baseline across all price tiers. Agricultural buyers in the US Midwest accept this precision for broad-acre crop scouting where absolute geolocation tolerance is relaxed.
- Optical Flow:Downward-facing camera arrays compute velocity vectors for position hold without satellite lock. Warehouse operators in Germany deploy these for indoor inventory inspection where GPS denial is absolute.
- Infrared Sensors:Thermal imaging cores detect heat signatures for search-and-rescue and photovoltaic panel defect identification. Emergency response agencies in Italy specify these for wildfire perimeter monitoring during overnight operations.
- Lidar:Solid-state or mechanical scanning modules generate dense point clouds for centimeter-level terrain modeling. Surveying firms in the UK demand these for rail corridor clearance verification where vegetation encroachment liability is severe.
- Ultrasonic Sensors:Time-of-flight rangefinders provide low-altitude obstacle avoidance at minimal cost. Consumer recreation buyers in Japan prioritize these for beginner-friendly operation in confined spaces.
Commodity GPS dominates unit economics; lidar modules command the steepest expansion trajectory in enterprise procurement.
Application:
Customer type fragmentation separates transactional equipment purchasers from integrators bundling compliance and operational support.
- Surveying & Mapping:Photogrammetry and lidar payload integration for cadastral and topographic deliverables. Engineering consultancies in South Africa adopt these for mining lease boundary verification where terrestrial access is restricted.
- Construction Inspection:Progress monitoring and structural defect detection for vertical infrastructure. General contractors in the UAE deploy these for megaproject documentation where manual scaffolding inspection delays critical path schedules.
- Agriculture:Multispectral and thermal imaging for precision input optimization. Cooperative extension services in Argentina evaluate subscription models that bundle hardware, analytics, and agronomic advisory.
- Emergency Response:Rapid deployment for disaster assessment and search coordination. Civil defense agencies in Turkey specify ruggedized platforms with 15-minute readiness intervals.
- Security Surveillance:Perimeter monitoring and event overwatch for critical infrastructure. Port authorities in Singapore deploy these for container yard intrusion detection where ground patrol coverage gaps persist.
Surveying and mapping anchors current procurement volume; agriculture is gaining share fastest through service-model conversion.
End User:
Application maturity determines whether buyers prioritize acquisition cost or total cost of ownership across training, maintenance, and regulatory compliance.
- Aerial Cinematography:Professional camera stabilization for film and broadcast production. Production houses in South Korea specify gimbal compatibility with cinema-grade payloads where dynamic range requirements exceed consumer sensor limits.
- Wildlife Monitoring:Non-invasive population census and anti-poaching patrol support. Conservation NGOs in Kenya deploy these for elephant herd tracking where ground vehicle disturbance alters behavioral data.
- Infrastructure Assessment:Linear asset inspection for power transmission and pipeline corridors. Utility operators in Norway contract these for hydroelectric penstock examination where confined space entry risks are prohibitive.
- Personal Recreation:Hobbyist flight and aerial photography without commercial intent. Regulatory clarity from the Civil Aviation Administration of China has concentrated domestic demand in tier-one cities where registration compliance is enforceable.
- Environmental Research:Atmospheric sampling and glacial change detection for academic institutions. Polar research stations in Antarctica deploy fixed-wing variants for ice shelf calving monitoring where satellite revisit frequency is inadequate.
Personal recreation represents mature volume concentration; infrastructure assessment is expanding most quickly through utility fleet modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Chinese buyers prioritize unit economics for high-volume deployment, while European and North American procurement emphasizes regulatory compliance and total cost of ownership over acquisition price.
United States
Energy infrastructure inspection and agricultural precision farming drive commercial uptake. FAA Part 107 certification mandates and Remote ID broadcast requirements filter non-compliant hardware from federal contracting channels. Houston-based energy service companies deploy quadcopter fleets for pipeline corridor monitoring where manual inspection costs exceed aerial alternatives by factors of five.
China
Domestic emergency response coordination and large-scale surveying operations absorb manufacturing output. Civil Aviation Administration GB standards and real-name registration protocols accelerate commercial deployment clarity. Shenzhen's manufacturing ecosystem supplies flight controllers and gimbals to integrators across Pearl River Delta assembly facilities.
Germany
Industrial facility inspection and warehouse automation anchor enterprise demand. EASA open-category altitude limits and specific-category certification pathways shape product development timelines. Bavarian automotive suppliers evaluate indoor navigation platforms for inventory management in GPS-denied factory environments.
Australia
Mining pit rim assessment and linear infrastructure inspection dominate procurement. Civil Aviation Safety Association operational guidelines for beyond-visual-line-of-sight activities enable remote site surveying. Perth-based mineral operators deploy fixed-wing variants for lease boundary verification across Western Australia extraction zones.
Brazil
Agricultural cooperative extension services and mega-project construction documentation expand addressable market. National Civil Aviation Agency regulatory harmonization with EASA frameworks reduces certification friction for imported platforms. São Paulo state agritech clusters pilot subscription service models bundling hardware, analytics, and agronomic advisory.
Portable Drone Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with competitive stability unwinding as captive component production advantages compound. Tier-one positions concentrate with manufacturers controlling upstream flight controller and gimbal supply. Specialist tiers fragment across autonomy software, defense channels, and regional assembly. Dominant competitive moves include backward integration into sensor modules and strategic partnerships with enterprise fleet management platforms.
Within the integrated manufacturing tier, DJI anchors volume leadership through Shenzhen-based captive production ecosystems. Parrot Drone SAS occupies a defensive position in European defense and environmental research procurement channels where national sourcing preferences create structural moats. Skydio exemplifies the autonomy-stack differentiation archetype, representing how proprietary perception systems capture enterprise security surveillance contracts against hardware-commoditized rivals.
| Leading Market Players |
|---|
| DJI |
| Parrot Drone SAS |
| Yuneec International |
| Autel Robotics |
| AeroVironment |
| Skydio |
| Hubsan |
| Horizon Hobby |
| 3D Robotics |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's manufacturing cluster achieves 40-60% unit cost advantages through captive flight controller and gimbal production, compressing price floors for commodity quadcopters while elevating margin capture for integrated sensor bundles. This scale concentration forces assembly-focused OEMs into low-margin hardware trading or niche autonomy software specialization.
Pricing Analysis
Fleet management subscriptions and multi-year service contracts now drive lifetime value beyond transactional hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates EASA specific-category certified platforms from open-category consumer units. Price differentiation rests on Remote ID compliance hardware and BVLOS waiver documentation. Cost compression in entry-level quadcopters intensifies because Shenzhen ecosystem rivals absorb margin erosion that Western assemblers cannot match. Agricultural cooperatives in Brazil exhibit highest price sensitivity; offshore wind operators in the North Sea prioritize redundancy over acquisition cost.
Supply Chain Analysis
China dominates flight controller fabrication and rare earth magnet processing, while Taiwan and South Korea anchor semiconductor supply for autonomy chips. Permanent magnet motors draw from concentrated neodymium refining capacity in Jiangxi province. Solid-state lidar modules and lithium-polymer cells hinge on Japanese and South Korean chemical processing. Single-source vulnerability in rare earth separation exposes motor manufacturers to export restriction risk. Distribution runs through integrator channels bundling regulatory compliance with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from terrestrial robotics and satellite imagery analytics that capture overlapping inspection use cases. The substitution threat intensifies as ground-based sensors achieve comparable survey economics without airspace compliance burdens.
For Market Incumbents: Secure backward integration into solid-state lidar and edge AI chipsets to preserve margin capture against hardware commoditization. Lock EASA and FAA certification pathways as defensive moats against emerging autonomy-stack rivals. Prioritize fleet management platform control to convert transactional buyers into recurring revenue relationships.
For New Entrants and Emerging Players: Lead with ruggedized fixed-wing platforms for sub-Saharan African agricultural extension and mineral exploration where infrastructure gaps eliminate incumbent service advantages. Target subscription bundling of hardware, analytics, and agronomic advisory to bypass capital-constrained buyer segments. Anchor go-to-market through national civil aviation agency pilot programs accelerating BVLOS regulatory clarity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors autonomy software specialists with proven perception stacks over hardware-commoditized assemblers. Long-term viability hinges on regulatory compliance architecture and enterprise fleet management platform adoption. Watch EASA and FAA beyond-visual-line-of-sight rulemaking timelines as the critical inflection signal for enterprise scaling economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomy Stack Acquisition | Proprietary perception systems capture enterprise security contracts against hardware rivals. |
| Remote ID Hardware Retrofit | FAA and EASA mandates filter non-compliant legacy fleets from commercial channels. |
| Fleet Management Platform Launch | Subscription bundling converts Brazilian agricultural cooperatives from transactional purchasing. |
| BVLOS Certification Investment | EASA specific-category pathways unlock energy infrastructure inspection contract eligibility. |
| Edge AI Chipset Partnership | Onboard inference enables swarm coordination for wildfire monitoring without ground infrastructure. |
Research Methodology
The analysis maps quadcopter, fixed-wing, and hybrid configurations alongside GPS, optical flow, and lidar technology tiers, each validated through flight operations directors at agricultural cooperatives, energy infrastructure inspectors, and civil aviation regulatory officers. Primary fieldwork with OEM product managers and enterprise fleet operators combined with secondary validation against FAA Part 107 waiver databases, EASA open-category compliance registries, and Civil Aviation Administration GB standard filings. Bottom-up unit shipment modeling triangulated against top-down procurement budget analysis across utility operators and surveying contractors.
Consistency checks validated volume and value outputs against customs trade data for flight controller and gimbal component flows, plus hyperscaler capex disclosures for edge AI inference investment. The analytical framework segments by product architecture, navigation technology precision tier, and application maturity across the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves incorporating regulatory clarity timelines and battery energy density improvement trajectories. Modeled inputs include EASA specific-category certification queue lengths and agricultural subsidy program disbursement patterns.
The analysis sits within stated boundaries; outcomes outside sustained FAA and EASA rulemaking momentum or breakthrough solid-state battery commercialization would require recalibration. Forecasts reflect documented assumptions on operator training pipeline capacity and rare earth magnet supply continuity. Recalibration cycles align with material shifts in beyond-visual-line-of-sight regulatory frameworks and enterprise fleet management platform consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
GCC Drones Market
UAV
Ultra Micro Drone Market
UAV
Anti-Drone Technology Market
UAV
Drone Leasing Market
UAV
Racing Drone Market
UAV
Solar-Powered UAV Market
UAV
Enterprise Drone Management Solutions Market
UAV
UAV Simulator Software Market
UAV
Rotary Blade UAV Drones Market
UAV
Europe Drone Light Shows Market
UAV
UAV Simulator Market
UAV
Drones Market
UAV
UAV Market
UAV
North America Tactical UAV Market
UAV
Commercial Drone Market
UAV
North America Small UAV Market