
 Fuel Cell UAV Market | 2026-2036
Fuel Cell UAV Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell UAV Market Analysis
South Korean fuel cell stack manufacturing is broadening the supplier base for extended-endurance unmanned platforms. Doosan Mobility Innovation leverages its proton exchange membrane expertise to dominate commercial inspection deployments. Intelligent Energy Limited anchors European supply chains with lightweight hydrogen power modules designed for rotary-wing applications. Heven Aerotech specializes in heavy-lift fuel cell drones for Israeli defense and agricultural markets.
A fuel cell UAV converts hydrogen into electrical energy through an electrochemical reaction, typically achieving 2-5 hours of flight endurance with water vapor as the sole emission, primarily serving missions where battery limitations constrain operational range. Fixed-wing configurations lead in endurance-critical segments such as environmental monitoring and infrastructure inspection, where hydrogen energy density enables coverage of vast linear assets. Military end users represent the fastest-growing demand pool, driven by silent propulsion requirements and reduced thermal signatures in surveillance operations. Quadcopter platforms occupy the commercial logistics segment, though payload trade-offs continue to challenge route economics for last-mile delivery.
The FAA governs airworthiness certification and beyond-visual-line-of-sight waivers for hydrogen-powered unmanned systems in United States airspace, while South Korea's Ministry of Trade, Industry and Energy (METI-equivalent industrial policy body) directs national hydrogen economy roadmaps that subsidize fuel cell aviation R&D. EASA's SC-VTOL and special condition frameworks for hydrogen propulsion are reshaping type certification requirements across European markets, directly influencing product development timelines and market access conditions. Stakeholders must monitor regulatory divergence between hydrogen storage safety standards and airspace integration protocols to anticipate certification bottlenecks.
Market Dynamics
The fuel cell UAV market is compressing around hydrogen storage density breakthroughs and the FAA's Part 107 waiver pipeline for beyond-visual-line-of-sight operations, which together determine which platforms achieve commercial scale first.
Growth Catalysts
- Beyond-visual-line-of-sight waivers:The FAA's evolving Part 107 framework creates regulatory runway for extended-endurance hydrogen platforms in commercial logistics trials across United States airspace.
- Silent propulsion requirements:Military end users in surveillance operations prioritize fuel cell systems for reduced acoustic and thermal signatures during extended missions.
- Proton exchange membrane advances:South Korean manufacturing scale in fuel cell stack production broadens supplier availability for commercial inspection deployments.
Market Restraints
- Hydrogen storage weight penalties:Composite tank systems add 15-25% payload displacement, constraining quadcopter route economics in last-mile delivery segments.
- Supply concentration in East Asian membrane production:Nafion-equivalent proton exchange materials depend on concentrated polymer electrolyte manufacturing capacity.
- EASA certification timelines:The European Union Aviation Safety Agency's SC-VTOL special conditions for hydrogen propulsion extend type certification cycles by 18-24 months versus conventional powertrains.
Strategic Opportunities
- Israeli defense agricultural convergence:Heavy-lift fuel cell platforms address dual-use requirements in precision agriculture and border surveillance applications.
- United Kingdom hydrogen aviation subsidies:The country's industrial strategy directs public R&D funding toward fuel cell aviation demonstrators through Aerospace Technology Institute channels.
- Artificial intelligence flight planning integration:Machine learning-optimized hydrogen consumption algorithms extend effective range without hardware modification.
Industry Challenges
- Hydrogen handling certification gaps:Ground crew training and fueling infrastructure standards lag platform airworthiness approvals, creating operational bottlenecks at deployment sites.
- Cross-border tank recertification:Pressure vessel standards diverge between DOT/PHMSA in the United States and UN/ISO frameworks in European markets, fragmenting fleet interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell UAV Market |
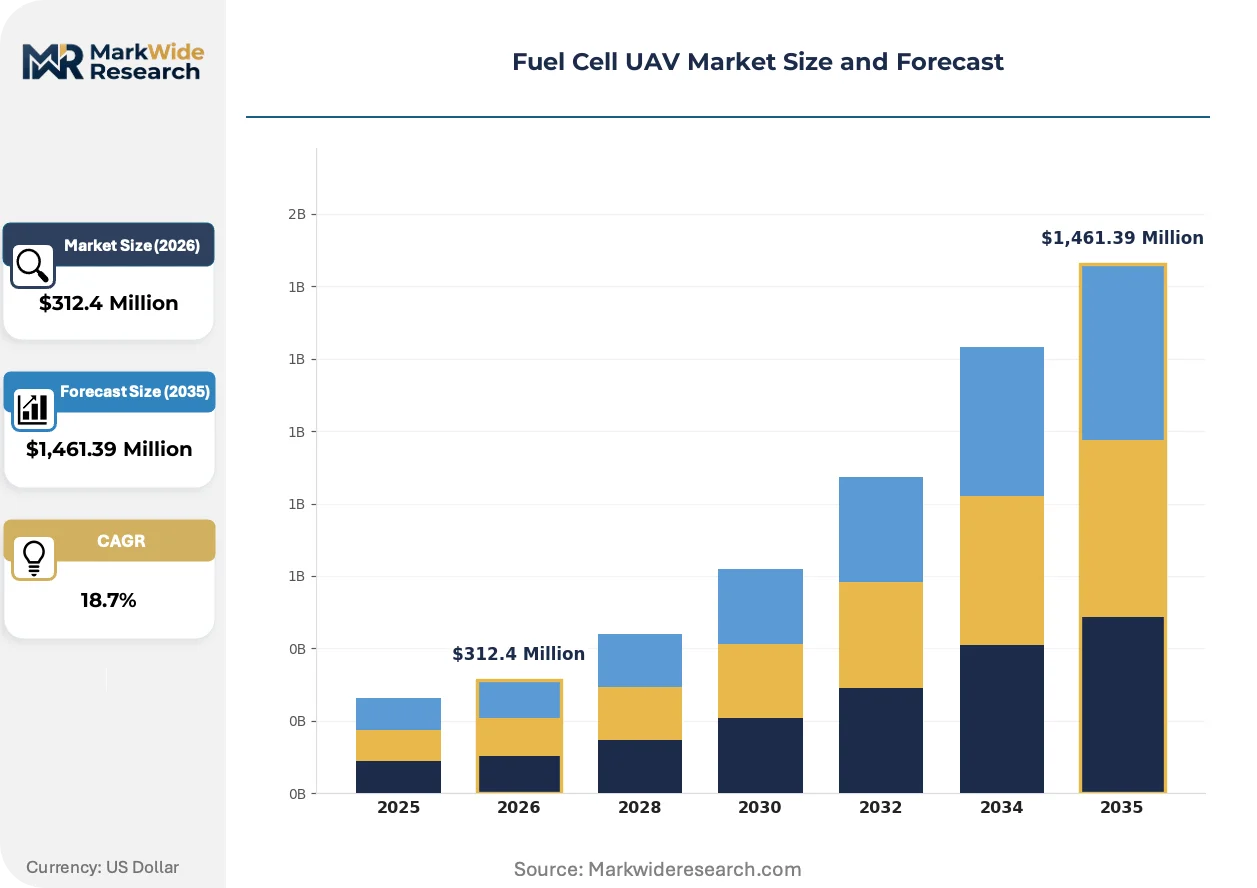
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Quadcopter, Hexacopter, UAV Drone End User: Agriculture, Military, Surveillance, Logistics Component: Fuel Stack, Battery, Propulsion System, Control System Application: Environmental Monitoring, Infrastructure Inspection, Disaster Relief, Aerial Photography |
| Companies Covered | Doosan Mobility Innovation, Heven Aerotech, Israel Aerospace Industries Ltd., Lockheed Martin Corporation, Cellen, AeroVironment, Inc., Intelligent Energy Limited, ISS Group Ltd., Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell UAV Market Emerging Trajectories
Electrochemical propulsion architectures are absorbing investment flows previously directed toward battery energy density improvements, while regulatory frameworks crystallize around hydrogen-specific airworthiness standards rather than adapted combustion rules.
Solid-state hydrogen storage in metal hydride matrices is absorbing technical development resources from compressed gas tank systems. Military procurement programs in the United States and Israel are piloting these configurations for tactical resupply missions where volume constraints outweigh weight penalties. The shift is compressing supply chain complexity by eliminating high-pressure composite manufacturing dependencies.
EASA's special condition framework for hydrogen propulsion in VTOL platforms is forcing redesign cycles across European development programs. The regulations mandate redundant fuel cell isolation systems and thermal runaway containment protocols that exceed existing battery safety requirements. Rotary-wing manufacturers in Germany and France are restructuring certification timelines to accommodate these prescriptive standards.
Defense agencies are consolidating procurement specifications around interchangeable hydrogen modules rather than integrated powertrain designs. The United States Department of Defense and Israeli Ministry of Defense are driving this standardization to enable multi-vendor fleet interoperability. Commercial operators in logistics and inspection verticals are adopting these military-derived specifications to access secondary equipment markets.
Fuel Cell UAV Market Segmentation
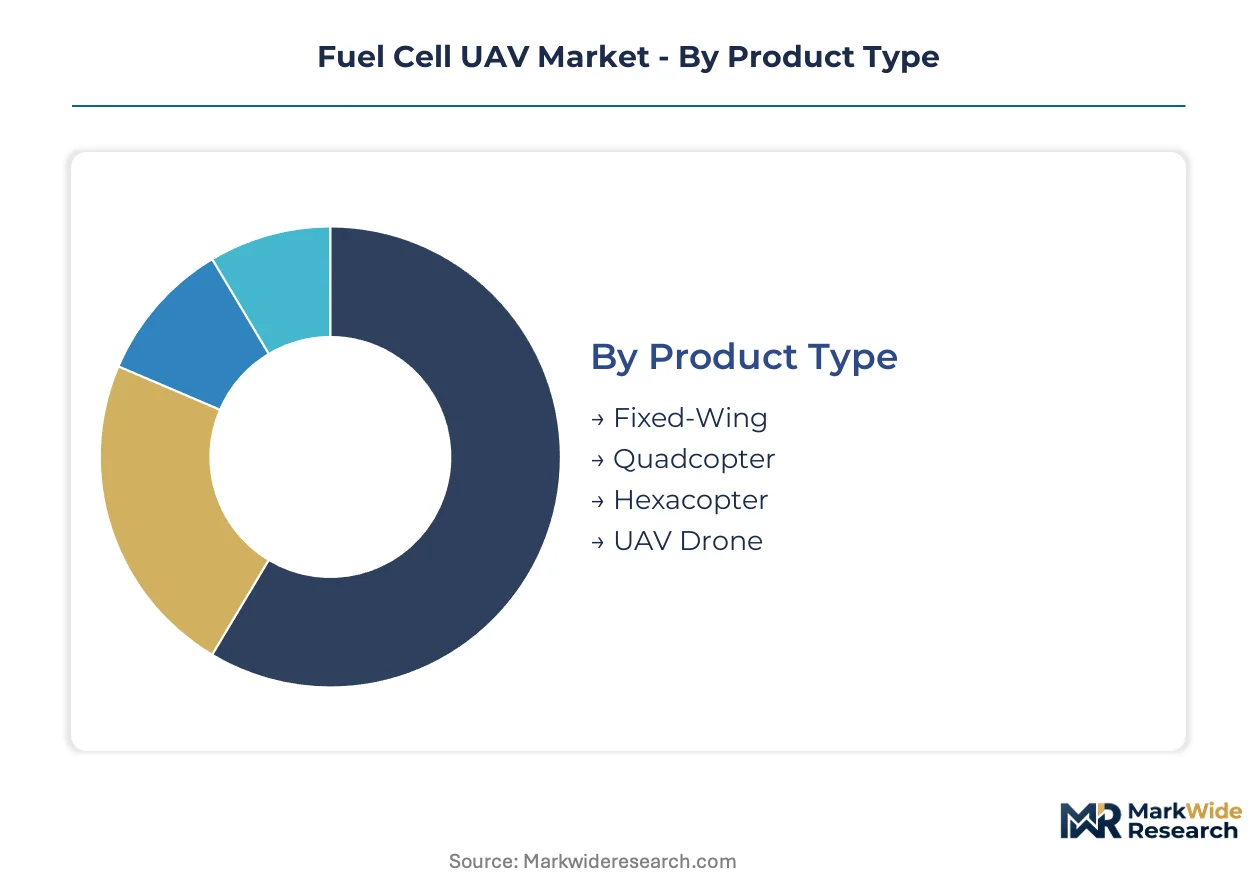
Fuel cell UAV architectures diverge sharply across mission profiles, with hydrogen storage constraints dictating platform geometry and powertrain configuration. End-use requirements for endurance, payload, and stealth create distinct procurement specifications that segment manufacturing specialization.
Product Type:
Platform geometry determines hydrogen tank integration feasibility and aerodynamic efficiency trade-offs.
- Fixed-Wing:Extended fuselage volume accommodates cylindrical composite hydrogen tanks without payload displacement. Environmental monitoring contracts in the United States favor these configurations for linear infrastructure coverage exceeding 200 kilometers.
- Quadcopter:Vertical thrust architecture limits tank volume to compact toroidal or conformal geometries, constraining flight duration to 90-150 minutes. Last-mile logistics trials in South Korea concentrate demand here despite payload penalties.
- Hexacopter:Six-rotor redundancy permits heavier fuel cell modules for agricultural spraying missions where hover stability outweighs endurance maximization.
- UAV Drone:Generic classification captures hybrid tilt-rotor and transitional platforms under development for military resupply applications.
Mature deployment sits with Fixed-Wing platforms. Newer deployment is concentrated in Quadcopter logistics trials.
End User:
Procurement authority and mission criticality shape hydrogen handling infrastructure investment and certification urgency.
- Military:Silent propulsion and reduced thermal signatures drive surveillance procurement from the United States Department of Defense and Israeli Ministry of Defense. Fuel cell isolation redundancy exceeds commercial aviation standards.
- Surveillance:Border patrol and critical infrastructure monitoring agencies in Germany and France prioritize endurance over speed for persistent coverage missions. EASA certification timelines delay fleet deployment.
- Agriculture:Precision spraying and crop monitoring in Israel deploy heavy-lift hexacopters with modular hydrogen swapping systems.
- Logistics:Commercial package delivery operators in South Korea pilot quadcopter networks with ground-based electrolysis fueling stations.
Volume concentration favors Military procurement. Margin expansion is strongest in Surveillance services.
Component:
Supply chain maturity varies dramatically across electrochemical and mechanical subsystems.
- Fuel Stack:Proton exchange membrane assemblies from South Korean manufacturers dominate commercial procurement. Stack power density of 2-3 kW/kg determines platform gross weight allocation.
- Propulsion System:Electric motor and hydrogen recirculation pump integration requires thermal management specialization. German aerospace suppliers anchor European sourcing.
- Battery:Hybrid architectures retain lithium-ion buffers for peak power demands during takeoff and maneuvering.
- Control System:Flight computers manage fuel cell thermal cycling and hydrogen pressure regulation through proprietary algorithms.
Technology leadership concentrates in Fuel Stack manufacturing. Integration complexity is highest in Propulsion System development.
Application:
Mission duration and sensor payload requirements segment hydrogen consumption profiles and tank sizing.
- Infrastructure Inspection:Linear asset coverage—power lines, pipelines, railways—demands 4-6 hour endurance that batteries cannot deliver. United States utility operators lead commercial adoption.
- Environmental Monitoring:Atmospheric sampling and wildlife tracking missions prioritize emission-free operation. Research agencies in the United Kingdom fund demonstrator programs.
- Disaster Relief:Rapid deployment requirements clash with hydrogen logistics complexity, limiting emergency response adoption.
- Aerial Photography:Commercial cinematography applications rarely justify hydrogen infrastructure investment given mission brevity.
Revenue stability sits with Infrastructure Inspection. Steepest expansion trajectory is concentrated in Environmental Monitoring research contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Proton exchange membrane manufacturing clusters in South Korea supply critical fuel cell stack components to UAV integrators worldwide. Defense procurement programs and commercial logistics trials concentrate demand across four national markets with distinct regulatory frameworks and infrastructure investment patterns.
United States
The FAA's Part 107 beyond-visual-line-of-sight waiver pipeline accelerates commercial hydrogen platform certification. Military surveillance contracts from the Department of Defense prioritize silent propulsion systems for extended endurance missions. California and Texas host the primary logistics trial corridors where fuel cell quadcopter networks undergo operational testing.
South Korea
Doosan Mobility Innovation anchors domestic fuel cell stack production for commercial inspection deployments. The Ministry of Trade, Industry and Energy directs national hydrogen economy roadmaps that subsidize aviation R&D through targeted grant programs. Seoul Capital Area and Busan-Ulsan concentrate manufacturing capacity and pilot project infrastructure.
Israel
Dual-use demand from defense and agricultural sectors drives heavy-lift hexacopter development for border surveillance and precision spraying. The Israeli Ministry of Defense standardizes procurement specifications around interchangeable hydrogen modules. Tel Aviv and Haifa host the primary development clusters where military-derived specifications transfer to commercial platforms.
Germany
EASA's SC-VTOL special conditions for hydrogen propulsion extend certification timelines for rotary-wing manufacturers. Environmental monitoring agencies prioritize emission-free atmospheric sampling missions. Bavaria and Baden-Württemberg concentrate aerospace supplier networks adapting to redundant fuel cell isolation mandates.
United Kingdom
Aerospace Technology Institute channels public R&D funding toward fuel cell aviation demonstrators. Research agencies fund environmental monitoring programs requiring extended-range emission-free operation. The Midlands and Southeast England host the primary development clusters where hydrogen handling infrastructure receives coordinated investment.
Fuel Cell UAV Market Vendor Landscape
Global majors compete with regional champions across defense contracting and commercial inspection verticals. The vendor base separates into tiered positions based on membrane manufacturing scale and military certification depth. Three archetypes dominate: South Korean stack specialists, Israeli dual-use platform integrators, and European power module designers. Capacity expansion and strategic partnerships constitute the primary competitive moves as firms position for FAA and EASA certification timelines.
Among South Korean manufacturers, Doosan Mobility Innovation exemplifies the stack-specialist archetype with integrated proton exchange membrane expertise. Heven Aerotech represents Israeli dual-use platform development bridging defense surveillance and agricultural heavy-lift applications. Intelligent Energy Limited anchors European positioning as a lightweight power module supplier for rotary-wing configurations. These three firms occupy distinct competitive positions shaped by national industrial policy support and regulatory pathway alignment.
| Leading Market Players |
|---|
| Doosan Mobility Innovation |
| Heven Aerotech |
| Israel Aerospace Industries Ltd. |
| Lockheed Martin Corporation |
| Cellen |
| AeroVironment, Inc. |
| Intelligent Energy Limited |
| ISS Group Ltd. |
| Elbit Systems Ltd. |
| Others |
Supply Flow & Price Mechanics
EASA's SC-VTOL hydrogen propulsion mandates gate qualified supply for premium-tier fuel cell UAV platforms, compressing vendor pools capable of meeting redundant fuel cell isolation standards while enabling pricing power for certified European suppliers. Military procurement specifications from the United States Department of Defense and Israeli Ministry of Defense further stratify access through interchangeable hydrogen module requirements that only stack-integrated manufacturers can satisfy.
Pricing Analysis
Warranty and field service bundling separates fuel cell UAV pricing tiers, with military contracts demanding comprehensive maintenance packages that commercial inspection operators often unbundle to reduce upfront acquisition costs. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth—FAA Part 107 waiver-ready platforms command premiums over pre-certified development units, while EASA SC-VTOL compliance adds additional cost layers for European market access. Pricing pressure stems from South Korean proton exchange membrane manufacturing scale broadening stack supplier availability and compressing power module margins. Military end users exhibit lowest price sensitivity given mission-critical requirements, whereas commercial logistics operators in last-mile delivery trials prioritize capital efficiency over performance specifications.
Supply Chain Analysis
Specialized aerospace technician availability in South Korea, Germany, and Israel constrains fuel cell stack and propulsion system manufacturing expansion, with proton exchange membrane fabrication requiring electrochemical engineering expertise concentrated in Busan-Ulsan and Bavaria. Raw material dependencies center on Nafion-equivalent polymer electrolytes, platinum-group catalysts, and carbon fiber composite pressure vessels. Single-source vulnerability runs through concentrated East Asian membrane production capacity, where geopolitical friction or export licensing shifts could disrupt global UAV powertrain supply. Distribution runs through defense procurement channels for military platforms and direct OEM relationships for commercial inspection deployments, with hydrogen handling infrastructure partnerships increasingly determining downstream market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel cell UAV markets sit in a technology-transition phase where solid-state hydrogen storage in metal hydride matrices is displacing compressed gas tank systems for tactical resupply missions. This shift compresses supply chain complexity and reshapes competitive positioning around volume-constrained rather than weight-optimized platform design.
For Market Incumbents: To counter South Korean proton exchange membrane manufacturing scale, deepen captive supply of fuel cell stack components through backward integration into catalyst-coated membrane production or secure long-term offtake agreements with Busan-Ulsan suppliers. Accelerate FAA Part 107 waiver acquisition for beyond-visual-line-of-sight operations to lock in commercial logistics trial positions before EASA SC-VTOL timelines extend European competitive windows. For New Entrants and Emerging Players: Begin with environmental monitoring research contracts in the United Kingdom where Aerospace Technology Institute funding reduces customer acquisition costs and extends runway for certification investment. Agricultural spraying applications in Israel offer the most penetrable segment given dual-use demand convergence and modular hydrogen swapping system standardization. Partner with existing hydrogen infrastructure operators rather than building captive fueling networks to preserve capital for airworthiness certification. For Investors and Strategic Acquirers: Israeli Ministry of Defense interchangeable hydrogen module standardization is the leading indicator that military-derived specifications will transfer to commercial platforms and consolidate vendor pools around certified integrators. Long-term viability favors firms with demonstrated EASA SC-VTOL compliance progress and established South Korean or European manufacturing partnerships. Watch for FAA Part 107 waiver approval velocity as the signal that commercial scale timing is compressing or extending.| Strategic Initiative | Industry Significance |
|---|---|
| Proton Exchange Membrane Capacity Expansion | South Korean manufacturing scale broadens supplier availability for commercial UAV inspection deployments. |
| FAA Part 107 Waiver Acquisition | Beyond-visual-line-of-sight certification accelerates commercial logistics trial participation in United States airspace. |
| Solid-State Hydrogen Storage Development | Metal hydride matrices eliminate high-pressure tank dependencies for tactical resupply missions. |
| EASA SC-VTOL Compliance Investment | Redundant fuel cell isolation systems enable European rotary-wing market access despite extended timelines. |
| Interchangeable Module Standardization | Military procurement specifications from United States and Israeli defense agencies drive multi-vendor fleet interoperability. |
Methodological Framework
Regulatory filings from the FAA, EASA, and South Korean Ministry of Trade, Industry and Energy formed the secondary backbone, supplemented by defense procurement databases and hydrogen economy roadmap documents. Primary interviews with fuel cell stack engineering directors, UAV platform integrators, military procurement officers, and commercial logistics operators combined with secondary validation to build segment-level demand estimates. Bottom-up platform deployment counts and top-down hydrogen consumption projections were triangulated against aerospace supplier capacity disclosures.
Historical trendline analysis across fuel cell power density improvements and hydrogen storage weight reduction trajectories informed projection assumptions over the analysis window. Segmentation dimensions modeled include platform geometry, end-use procurement authority, component supply chain maturity, and mission duration requirements. CAGRs derived from fitted growth curves were stress-tested against military budget allocation patterns and commercial logistics trial expansion rates.
Regulatory divergence between hydrogen storage safety standards, airspace integration protocol shifts, and proton exchange membrane supply concentration are the dominant revision risks to forecast assumptions. Material deviation in any named trigger warrants pause and re-evaluation of platform deployment timelines and vendor competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Data Management Market
UAV
Toy Drones Market
UAV
Asia Pacific Small UAV Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Commercial UAV Market
UAV
UAV Payload Market
UAV
Military UAV Sensor Market
UAV
North America Drone Services Market
UAV
Asia-Pacific Tethered Drone Market
UAV
Passenger Drones Market
UAV
Commercial Drone Market
UAV
Small Drone Market
UAV
Global Drone Software Market
UAV
North America Fuel Cell UAV Market
UAV
Ultra-Long Endurance Drone Market
UAV
Latin America Small UAV Market