
 Unmanned Aerial Vehicle Fuel Cell Market | 2026-2036
Unmanned Aerial Vehicle Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Unmanned Aerial Vehicle Fuel Cell Market Insights
Buyer concentration among defense procurement agencies is hardening as NATO members consolidate hydrogen-powered UAV contracts under fewer prime integrators. AeroVironment Inc. leverages its Pentagon relationships to sustain fixed-wing fuel cell drone programs for tactical units. Ballard Power Systems anchors the propulsion subsystem supply through its proton exchange membrane stack specialization for aerospace duty cycles. Doosan Corporation competes in rotary-wing configurations with its compact fuel cell modules designed for extended hover endurance.
An unmanned aerial vehicle fuel cell is an electrochemical power plant that converts hydrogen and oxygen into electricity through a proton exchange membrane or solid oxide stack, yielding water vapor as the sole exhaust while delivering energy densities of 500-1,000 Wh/kg—roughly three to five times that of lithium-ion batteries. This technology enables commercial and military drones to achieve flight durations exceeding eight hours for persistent surveillance, precision agriculture mapping, and beyond-visual-line-of-sight logistics. Proton exchange membrane systems dominate current procurement due to their cold-start reliability and modular scaling, while solid oxide variants attract R&D investment for their higher thermal efficiency in large fixed-wing platforms. Delivery services represent the fastest-growing application segment as logistics providers seek FAA certification for hydrogen-powered last-mile UAV networks.
The FAA's hydrogen storage and venting standards for unmanned aircraft, combined with EU REACH compliance for fuel cell catalyst materials, shape product design cycles and cross-border market access for stack manufacturers. Military end users navigate ITAR export controls and DoD MIL-STD-810G environmental qualification requirements that extend validation timelines but lock in supplier relationships. Stakeholders must monitor the divergence between FAA type certification pathways for hydrogen UAVs and EASA's emerging SC-VTOL special conditions, as regulatory misalignment threatens to fragment platform development investments across Atlantic supply chains.
Market Dynamics
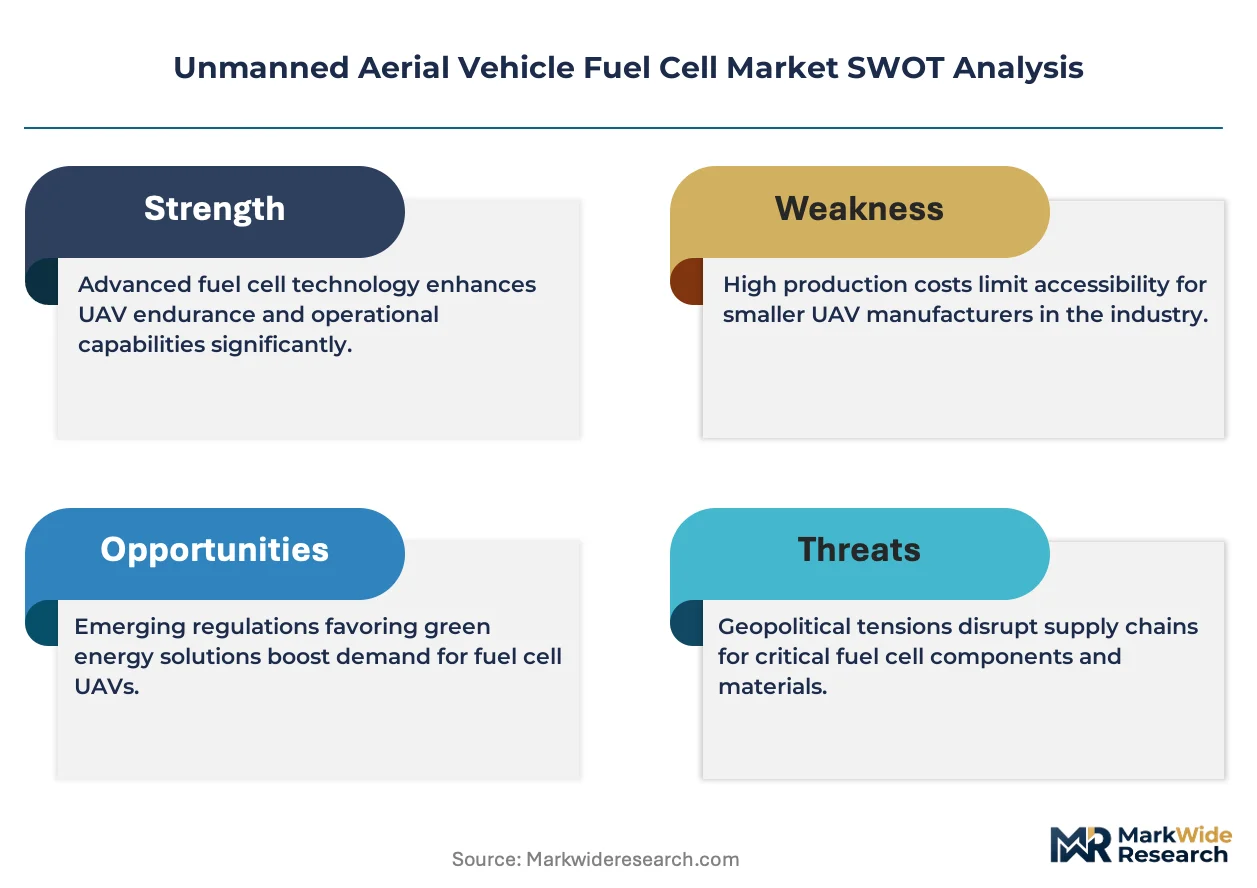
Defense procurement consolidation around NATO hydrogen-powered ISR programs is compressing supplier margins while accelerating airworthiness validation cycles under FAA hydrogen storage standards.
Growth Catalysts
- Extended-duration ISR missions:NATO member states are expanding hydrogen-powered UAV fleets for persistent surveillance operations requiring flight times exceeding eight hours.
- FAA type certification acceleration:The evolving framework for hydrogen-propelled unmanned aircraft is reducing validation timelines for commercial logistics applications.
- Proton exchange membrane reliability:Cold-start performance and modular scaling characteristics are driving procurement preference in tactical rotary-wing deployments.
Market Restraints
- ITAR export control complexity:Military qualification requirements under DoD MIL-STD-810G extend supplier validation timelines and fragment international component sourcing.
- Hydrogen storage infrastructure gaps:Ground support equipment for high-pressure composite tanks concentrates deployment feasibility near established fueling corridors in the United States.
- Lithium-ion substitution persistence:Established battery supply chains and lower upfront platform costs continue to dominate short-duration commercial applications.
Strategic Opportunities
- Last-mile logistics networks:Delivery services are pursuing FAA certification for hydrogen-powered beyond-visual-line-of-sight operations in urban air mobility corridors.
- Solid oxide fuel cell convergence:Higher thermal efficiency variants attract R&D investment for large fixed-wing platforms requiring extended range endurance.
- EU REACH compliance differentiation:Catalyst material sourcing standards create competitive positioning for stack manufacturers with verified supply chain documentation.
Industry Challenges
- Cross-regulatory divergence friction:Stakeholders must reconcile FAA type certification pathways with EASA emerging SC-VTOL special conditions, fragmenting platform development investments.
- Environmental qualification capex intensity:MIL-STD-810G testing for temperature, vibration, and altitude extremes requires substantial validation infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unmanned Aerial Vehicle Fuel Cell Market |
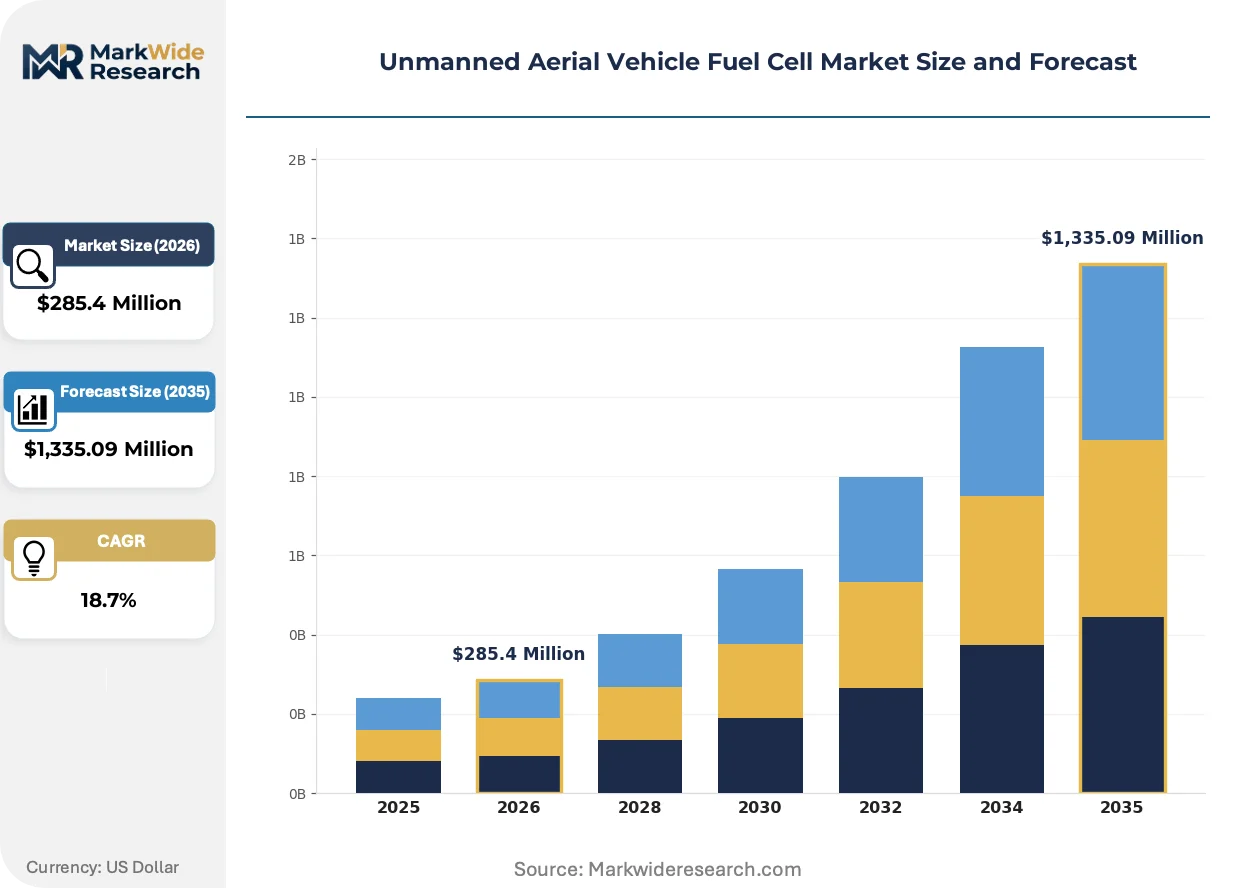
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,335.09 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Cell Type: Proton Exchange Membrane, Solid Oxide, Phosphoric Acid, Alkaline, Molten Carbonate Application: Surveillance, Mapping, Agriculture Monitoring, Environmental Assessment, Delivery Services End User: Defense Forces, Research Institutions, Logistics Providers, Environmental Agencies, Disaster Management Deployment Mode: Fixed Wing UAVs, Rotary Wing UAVs, Hybrid UAVs, Tethered UAVs |
| Companies Covered | Intelligent Energy Limited, AeroVironment Inc., Horizon Fuel Cell Technologies, Israel Aerospace Industries Ltd, Ballard Power Systems, Doosan Corporation, Elbit Systems Ltd, Northrop Grumman Corporation, General Atomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unmanned Aerial Vehicle Fuel Cell Market Trends and Innovations
Technology maturation in fuel cell stack architectures is converging with regulatory pathway clarification to reshape competitive positioning across defense and commercial segments.
Solid oxide fuel cell systems are overtaking proton exchange membrane alternatives in large fixed-wing platform development due to superior thermal efficiency at scale. Defense integrators are prioritizing these configurations for strategic ISR programs requiring multi-day endurance. The technology is overtaking incumbent battery-electric architectures in mission profiles above six hours, compressing addressable market boundaries for lithium-ion suppliers.
EASA's emerging SC-VTOL special conditions for hydrogen-powered unmanned aircraft are creating parallel certification requirements distinct from FAA frameworks. This regulatory divergence is forcing stack manufacturers to maintain dual qualification documentation for transatlantic market access. European defense procurement agencies are responding by consolidating requirements under fewer prime integrators capable of navigating both regulatory environments.
Defense procurement agencies are consolidating hydrogen-powered UAV contracts under extended-performance-based agreements rather than discrete hardware purchases. Prime integrators are absorbing lifecycle fueling infrastructure and maintenance obligations previously borne by end-users. This shift is most visible in United States tactical unit deployments, where Pentagon R&D spending prioritizes operational availability metrics over platform acquisition cost.
Unmanned Aerial Vehicle Fuel Cell Market Segmentation
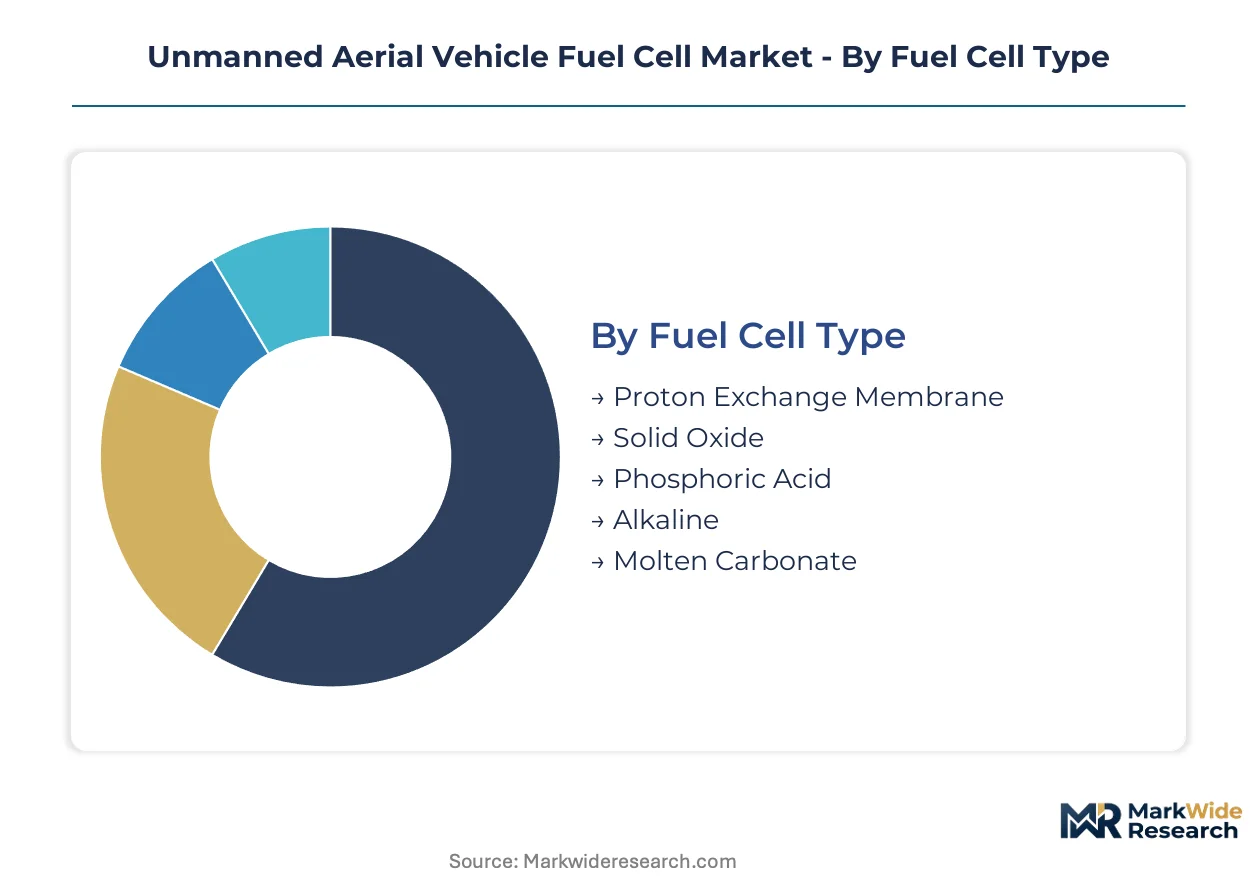
Segmentation in the UAV fuel cell market reveals divergent technology maturity curves and procurement patterns across military and commercial end uses. Each dimension exposes distinct supply chain configurations and certification requirements that shape vendor positioning.
Fuel Cell Type:
Standardization dominates proton exchange membrane stacks while solid oxide variants demand extensive customization for aerospace duty cycles.
- Proton Exchange Membrane:Polymer electrolyte architecture operating at 60-80°C delivers cold-start reliability under 30 seconds. Defense procurement agencies in the United States prioritize this chemistry for tactical rotary-wing deployments requiring rapid response capabilities.
- Solid Oxide:Ceramic electrolyte systems achieve 60% electrical efficiency at 600-1000°C operating temperatures. Large fixed-wing ISR platforms requiring multi-day endurance drive concentrated R&D investment from NATO defense integrators.
- Phosphoric Acid:Liquid electrolyte design offers established commercial maturity from stationary power applications.
- Alkaline:Aqueous potassium hydroxide electrolyte provides cost advantages in low-temperature laboratory environments.
- Molten Carbonate:High-temperature carbonate salt electrolyte suits stationary applications with waste heat recovery potential.
Leading the category by volume: Proton Exchange Membrane. Expanding most quickly: Solid Oxide.
Application:
Cost tier stratification separates capital-intensive defense surveillance from emerging commercial logistics networks with infrastructure-dependent unit economics.
- Surveillance:Persistent ISR missions exceeding eight hours demand redundant fuel cell architectures with MIL-STD-810G environmental qualification. Pentagon R&D spending concentrates procurement volume among fixed-wing platforms for border patrol and battlefield monitoring.
- Delivery Services:Beyond-visual-line-of-sight logistics networks require FAA type certification for hydrogen storage and venting systems. Urban air mobility corridors near established fueling infrastructure in the United States attract initial commercial deployment.
- Mapping:Precision photogrammetry applications prioritize payload capacity over endurance duration.
- Agriculture Monitoring:Multi-spectral crop assessment drives demand for rotary-wing hover endurance.
- Environmental Assessment:Emissions monitoring missions leverage fuel cell water vapor exhaust for sensitive ecosystem access.
Highest procurement value concentrates in: Surveillance. Steepest expansion trajectory: Delivery Services.
End User:
Customer type fragmentation spans classified defense programs with extended validation timelines versus commercial logistics providers seeking accelerated certification pathways.
- Defense Forces:ITAR-controlled procurement consolidates under prime integrators capable of navigating MIL-STD-810G temperature, vibration, and altitude qualification. NATO member states are expanding hydrogen-powered fleet contracts with lifecycle fueling infrastructure obligations.
- Logistics Providers:Last-mile delivery networks pursue FAA certification for urban air mobility corridors with hydrogen ground support equipment co-investment requirements.
- Research Institutions:Academic and government laboratories validate novel stack architectures with reduced environmental qualification burdens.
- Environmental Agencies:Regulatory compliance monitoring missions prioritize zero-emission propulsion for sensitive habitat access.
- Disaster Management:Emergency response coordination requires rapid deployment capabilities with modular fueling logistics.
Dominant procurement volume: Defense Forces. Gaining share fastest: Logistics Providers.
Deployment Mode:
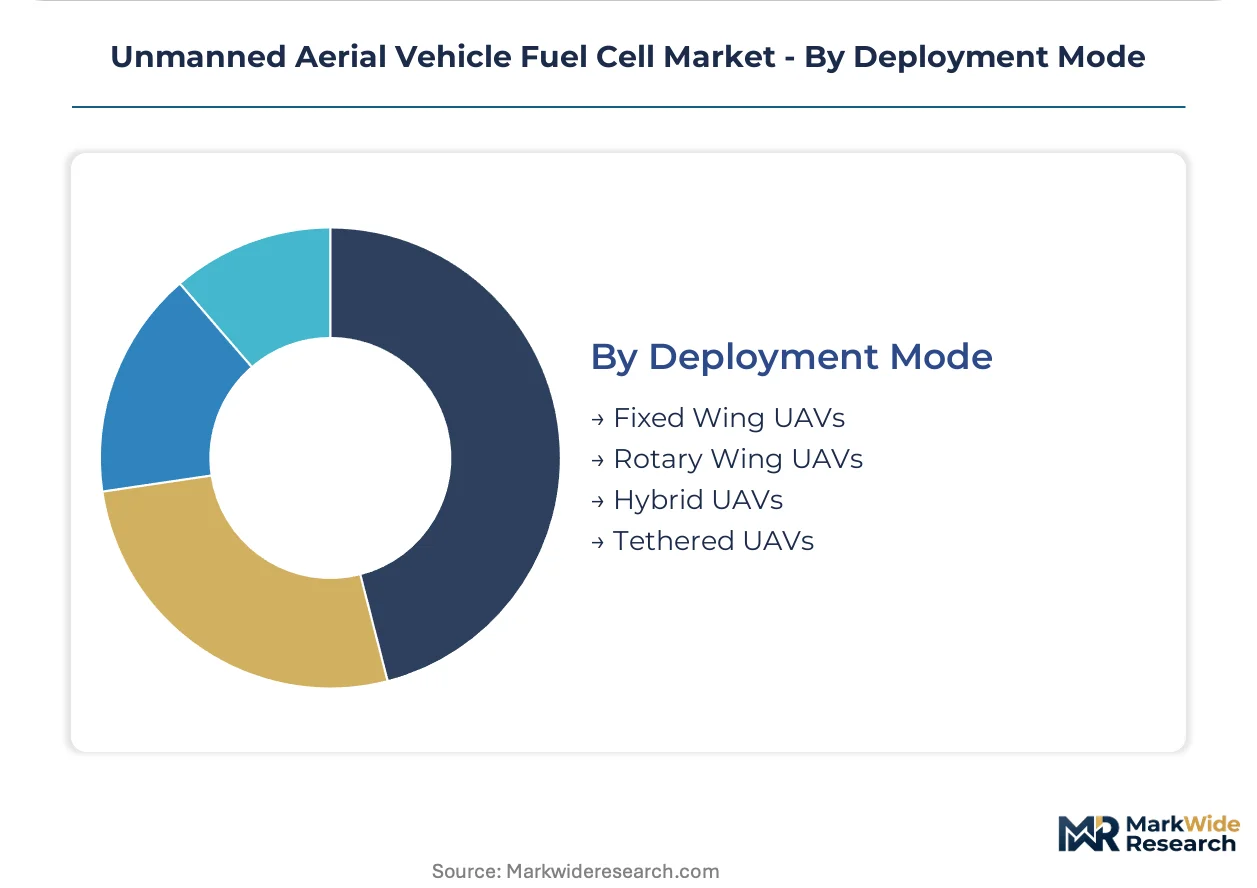
Supply concentration in fixed-wing configurations contrasts with emerging hybrid architectures requiring dual qualification documentation for transatlantic regulatory divergence.
- Fixed Wing UAVs:Aerodynamic efficiency maximizes fuel cell energy density advantages for long-endurance missions. Strategic ISR programs in the United States prioritize these platforms for persistent surveillance with solid oxide stack integration.
- Rotary Wing UAVs:Hover endurance demands compact proton exchange membrane modules with rapid throttle response. Tactical unit deployments favor these configurations for vertical takeoff and landing flexibility in contested environments.
- Hybrid UAVs:Combined fixed and rotary lift systems require complex control surface integration with fuel cell thermal management.
- Tethered UAVs:Ground-connected power delivery eliminates onboard hydrogen storage for stationary observation posts.
Highest platform deployment: Fixed Wing UAVs. Fastest technology convergence: Hybrid UAVs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement agencies in the United States concentrate hydrogen-powered UAV demand through Pentagon R&D spending on extended-duration ISR missions. Commercial logistics providers in select European and Asia-Pacific markets pursue parallel certification pathways, creating fragmented infrastructure investment patterns.
United States
The Pentagon dominates procurement volume through tactical unit deployments and strategic ISR programs requiring flight times exceeding eight hours. FAA hydrogen storage and venting standards for unmanned aircraft accelerate airworthiness validation timelines for both defense and commercial applicants. Greater Boston and Pacific Northwest clusters host fuel cell stack manufacturers serving military qualification requirements.
Germany
EASA's emerging SC-VTOL special conditions for hydrogen-powered unmanned aircraft shape certification requirements distinct from FAA frameworks. EU REACH compliance for fuel cell catalyst materials influences stack manufacturer supply chain documentation and cross-border market access. Bavaria's aerospace engineering concentration supports defense integrators navigating dual regulatory environments.
United Kingdom
Border patrol and battlefield monitoring missions drive fixed-wing platform procurement with solid oxide stack integration for multi-day endurance. Ministry of Defence procurement consolidates under prime integrators capable of managing lifecycle fueling infrastructure obligations. Southwest England hosts unmanned systems test corridors for hydrogen propulsion validation.
Israel
Contested environment tactical deployments favor rotary-wing configurations with rapid throttle response and vertical takeoff flexibility. National security procurement operates under classified program structures with extended validation timelines. Tel Aviv metropolitan area concentrates defense electronics integration expertise for fuel cell thermal management systems.
South Korea
Urban air mobility corridor planning incorporates hydrogen ground support equipment co-investment requirements for last-mile logistics networks. The country's national aviation regulator develops type certification pathways parallel to FAA and EASA frameworks. Seoul Capital Area hosts demonstration programs for beyond-visual-line-of-sight hydrogen UAV operations.
Unmanned Aerial Vehicle Fuel Cell Market Competitive Landscape
United States producers anchor the defense-tier supply base; South Korean and Israeli specialists hold positions in compact module configurations for tactical deployments. The vendor structure concentrates around prime integrators absorbing lifecycle fueling obligations, with proton exchange membrane stack manufacturers and solid oxide R&D providers occupying distinct technology tiers. Two strategic archetypes dominate: Pentagon-linked defense integrators and commercial logistics-focused certification specialists. Competitive moves center on strategic partnerships for fueling infrastructure deployment and technology licensing for dual regulatory qualification.
Within the defense integrator tier, AeroVironment Inc. and Northrop Grumman Corporation represent Pentagon-linked prime contractors managing extended-performance-based agreements. Ballard Power Systems anchors the propulsion subsystem supply through its proton exchange membrane specialization. Doosan Corporation occupies a position among compact fuel cell module providers for rotary-wing endurance applications.
| Leading Market Players |
|---|
| Intelligent Energy Limited |
| AeroVironment Inc. |
| Horizon Fuel Cell Technologies |
| Israel Aerospace Industries Ltd |
| Ballard Power Systems |
| Doosan Corporation |
| Elbit Systems Ltd |
| Northrop Grumman Corporation |
| General Atomics |
| Others |
Pricing and Supply Chain Analysis
Solid oxide fuel cell maturation for large fixed-wing platforms simultaneously compresses per-kilowatt manufacturing costs and concentrates procurement leverage among Pentagon-linked prime integrators absorbing lifecycle fueling obligations. This technology transition rewards stack manufacturers with MIL-STD-810G qualification infrastructure while squeezing margins for unqualified component suppliers.
Pricing Analysis
Volume concentrates in defense-tier proton exchange membrane stacks with compressed margins, while solid oxide R&D commands premium pricing for multi-day endurance applications. Price differentiation rests on FAA certification status and ITAR compliance tier, with validated suppliers capturing three-to-five-year performance-based agreements. Cost compression in commercial logistics tiers is intensifying because lithium-ion substitution persists for short-duration missions. Logistics providers exhibit highest price sensitivity due to infrastructure co-investment requirements, whereas defense procurement agencies prioritize operational availability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale defense procurement demand, with prime integrators managing subsystem integration and lifecycle service obligations. Manufacturing concentrates in the United States, Germany, and South Korea, with each cluster specializing in distinct qualification regimes. The supply chain draws from platinum-group catalyst suppliers, high-pressure composite tank manufacturers, and proton exchange membrane material providers. Single-source vulnerability in aerospace-grade membrane supply creates structural risk for tier-two stack assemblers. Distribution runs through defense procurement agencies and commercial logistics consortiums pursuing coordinated fueling infrastructure deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement consolidation around NATO hydrogen-powered ISR programs is forcing subscale stack manufacturers toward acquisition or exit, with MIL-STD-810G qualification capex serving as the primary barrier to sustained participation.
For Market Incumbents: Hedge against solid oxide disruption by maintaining dual-stack development capabilities while deepening Pentagon relationships through lifecycle fueling infrastructure commitments. Absorb environmental qualification testing burdens for tier-two component suppliers to lock in supply chain control. Prioritize EASA SC-VTOL parallel certification investment to defend transatlantic market access against regulatory divergence. For New Entrants and Emerging Players: FAA type certification acceleration for hydrogen-propelled unmanned aircraft opens a window for logistics-focused stack manufacturers to establish commercial reference accounts before defense-tier primes pivot downstream. Target urban air mobility corridors in the United States with compact proton exchange membrane modules designed for rapid refueling turnaround. Pursue strategic partnerships with ground support equipment providers to bundle fueling infrastructure with stack sales. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime integrators seeking vertical integration into propulsion subsystems, with acquisition premiums attaching to MIL-STD-810G qualified manufacturing assets. Long-term viability favors stack manufacturers with demonstrated regulatory navigation across both FAA and EASA frameworks. Watch for solid oxide fuel cell convergence in large fixed-wing platforms as the inflection signal for technology tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Regulatory Qualification Investment | EASA SC-VTOL and FAA certification capabilities unlock transatlantic defense and commercial procurement access. |
| Lifecycle Fueling Infrastructure Partnership | Performance-based agreements with Pentagon procurement agencies secure multi-year revenue visibility and supplier lock-in. |
| Solid Oxide Stack R&D Scale-Up | Higher thermal efficiency variants capture strategic ISR programs requiring multi-day endurance beyond battery-electric limits. |
| Commercial Logistics Certification Pathway | FAA type certification for urban air mobility corridors establishes reference accounts ahead of defense prime downstream expansion. |
| Platinum-Group Catalyst Supply Security | EU REACH compliant supply chain documentation differentiates stack manufacturers in European procurement competitions. |
Research Methodology
Defense procurement databases, FAA certification filings, and EASA regulatory notices formed the secondary backbone, supplemented by customs records tracking fuel cell component trade flows. Primary interviews with Pentagon program officers, fuel cell stack engineering directors, logistics provider fleet managers, and hydrogen infrastructure developers validated demand assumptions and procurement timeline estimates. Bottom-up platform deployment forecasts and top-down defense R&D appropriation analysis were triangulated to anchor market sizing.
Bottom-up modeling segmented the market by fuel cell chemistry, application endurance requirement, and end-user qualification tier across the projection horizon. The analytical framework incorporated proton exchange membrane cold-start performance curves, solid oxide thermal efficiency trajectories, and hydrogen storage mass fraction improvements as technology-specific forecast inputs. CAGRs were derived from deployment ramp rates observed in analogous aerospace electrification transitions, adjusted for regulatory pathway clarity and infrastructure investment cycles.
Caveats apply where FAA-EASA regulatory divergence or lithium-ion energy density breakthroughs could materially shift the outlook for hydrogen propulsion adoption timelines. Forecasts reflect assumptions regarding defense budget continuity, hydrogen fueling corridor buildout pace, and stack manufacturing yield improvements. Periodic stress-testing of base assumptions against Pentagon R&D appropriation shifts and commercial logistics certification milestone achievement is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Electric Glider Market
UAV
Drones Market
UAV
North America Fuel Cell UAV Market
UAV
Anti-Drone Technology Market
UAV
Global Drone Software Market
UAV
Delivery Drones Market
UAV
Stratospheric Flying Drone Market
UAV
Aerial Smart Weapons Market
UAV
Asia-Pacific Drones Market
UAV
Toy Drones Market
UAV
Global Aerial Survey Services Market
UAV
Global Drone Services Market
UAV
Small Drone Market
UAV
Drone Leasing Market
UAV
Airborne Digital Battlefield Market
UAV
Global Smart Commercial Drones Market