
 Auto-Follow Drone Market | 2026-2036
Auto-Follow Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Auto-Follow Drone Market Insights
FAA Part 107 remote pilot certification is unwinding the competitive landscape for commercial auto-follow operators in the United States. DJI leverages its Shenzhen manufacturing scale to dominate consumer and prosumer camera drone channels across North America. Skydio differentiates through proprietary computer-vision autonomy stacks that anchor its position in infrastructure inspection and defense-adjacent applications.
An auto-follow drone is an unmanned aerial vehicle equipped with GPS tracking, computer vision, or sensor fusion systems that enable autonomous subject tracking without manual piloting, typically operating at ranges of several hundred meters with real-time obstacle avoidance. These systems serve film production, sports analytics, and industrial inspection by capturing dynamic aerial footage or data while eliminating the need for dedicated remote operators. Camera drones lead product-type revenue pools due to their penetration across consumer and commercial segments, while computer-vision technology captures the fastest expansion as neural-network-based tracking supplants GPS-dependent systems in complex environments. Delivery drones remain structurally immature outside limited pilot zones, with margin concentration sitting in industrial drones purpose-built for agricultural monitoring and infrastructure inspection.
FAA Part 107, EASA open-category regulations, and CE marking requirements collectively shape market access by mandating operator certification, geofencing compliance, and product safety validation across the United States and European Union. China's MIIT and NMPA frameworks impose parallel conformity assessments for radio transmission and aerial platform safety on manufacturers targeting domestic and export markets. Stakeholders must monitor evolving beyond-visual-line-of-sight waiver frameworks and emerging EU AI Act classifications that could reclassify autonomous tracking algorithms as high-risk artificial intelligence systems.
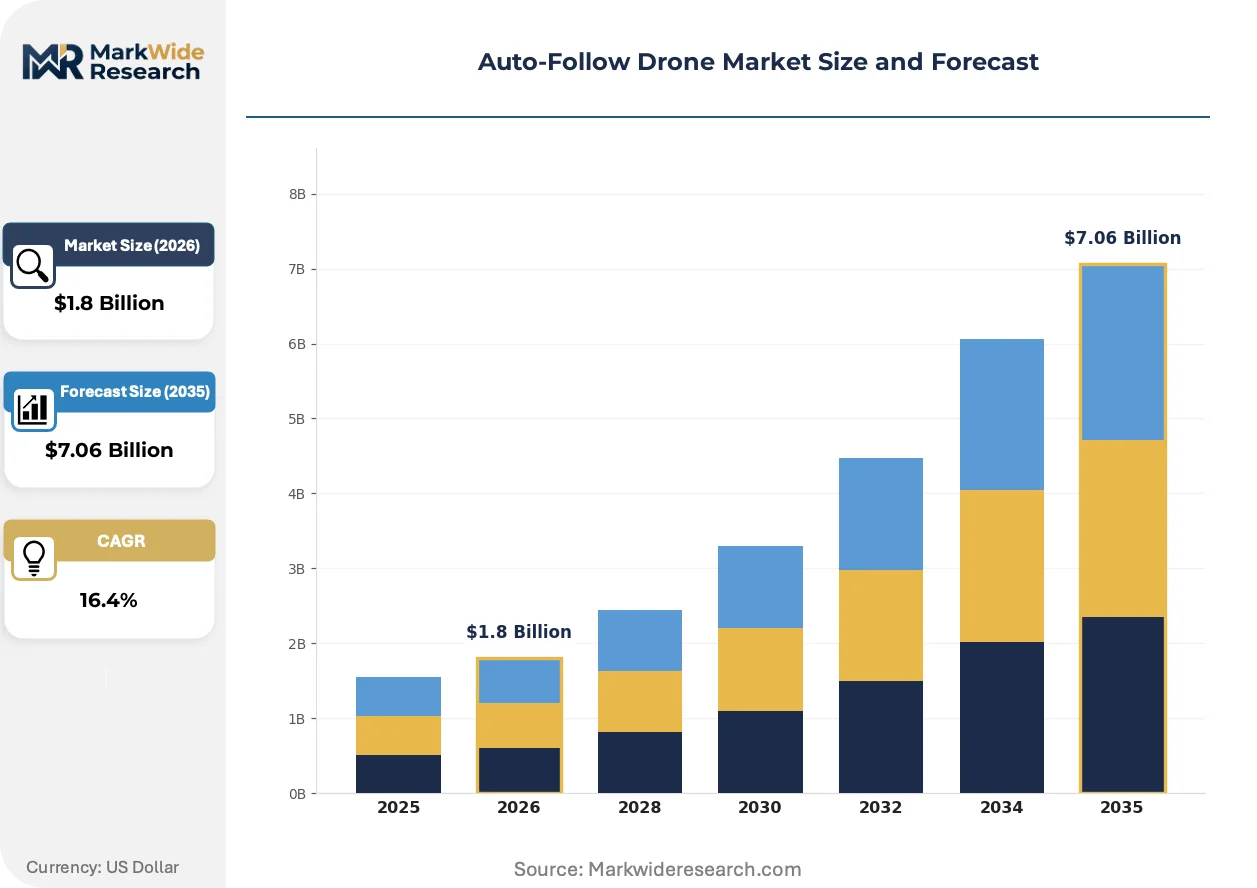
Market Dynamics
Neural-network-based tracking systems are compressing GPS-dependent architectures across outdoor filming and sports analytics, while FAA Part 107 and EASA open-category frameworks tighten operator certification requirements that segment commercial viability by compliance depth.
Growth Catalysts
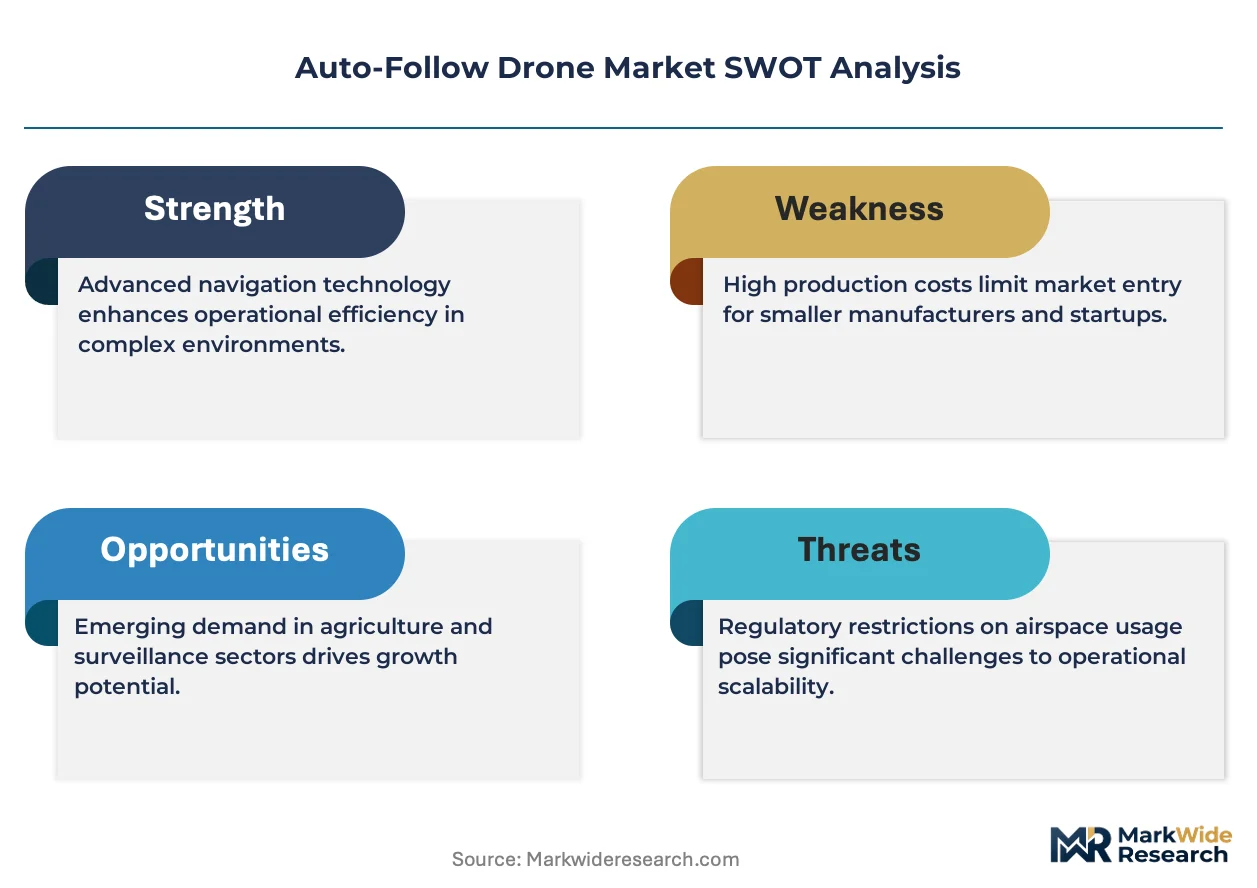
- Computer-vision autonomy:Neural-network tracking enables operation in GPS-denied environments such as dense urban canyons and forested terrain, expanding addressable filming locations beyond traditional broadcast infrastructure.
- FAA Part 107 waivers:Beyond-visual-line-of-sight approvals for certified operators unlock commercial deployments across California film production corridors and Texas sports venues.
- Sports broadcast demand:Athlete-tracking camera drones replace cable-suspended systems in North American professional leagues, generating recurring hardware refresh cycles tied to seasonal procurement calendars.
Market Restraints
- Lithium-polymer battery volatility:Energy density limitations cap flight duration to 25-35 minutes for camera-heavy payloads, constraining continuous tracking sequences without swap infrastructure.
- Shenzhen supply concentration:Critical flight controller and gimbal manufacturing clusters in Guangdong Province expose downstream assemblers to single-point geopolitical and logistics disruption.
- EASA AI Act classification risk:Autonomous tracking algorithms face pending high-risk AI system designation, threatening mandatory conformity assessment cost burdens for EU market entry.
Strategic Opportunities
- India agricultural monitoring:PLI scheme incentives for drone manufacturing create localized assembly advantages for crop-spraying and field-surveying auto-follow platforms.
- Edge-AI inference convergence:Onboard neural processing unit integration with thermal imaging sensors opens livestock monitoring and search-rescue applications without cloud dependency.
- Direct-to-production-house sales:Bypassing traditional broadcast equipment distributors through studio procurement partnerships captures margin and accelerates replacement cycle capture.
Industry Challenges
- Computer-vision engineering scarcity:Specialized talent for real-time obstacle avoidance algorithm development concentrates in Silicon Valley and Tel Aviv, inflating compensation costs for autonomous stack builders.
- FAA certification timeline compression:Remote pilot certificate throughput limits operator pool expansion, creating bottlenecks for fleet-scaling service providers in competitive filming markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto-Follow Drone Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Drones, Racing Drones, Industrial Drones, Delivery Drones, Surveying Drones Technology: GPS Tracking, Computer Vision, LiDAR Sensors, Infrared Sensors, Ultrasonic Sensors Application: Outdoor Filming, Sports Analysis, Agricultural Monitoring, Infrastructure Inspection, Wildlife Tracking End User: Film Production Companies, Sports Teams, Agricultural Firms, Construction Enterprises, Research Institutions |
| Companies Covered | DJI, Skydio, Autel Robotics, Parrot Drones SAS, Draganfly Innovations Inc., GoPro Inc., 3DR, Guangdong Cheerson Hobby Technology Company Limited, HOVERAir, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto-Follow Drone Market Trends and Innovations
Autonomy hardware is compressing into smaller form factors while regulatory frameworks fragment across jurisdictions, and buyer procurement patterns pivot toward integrated service contracts that bundle hardware with certified operator access.
Onboard neural processing units are miniaturizing from rack-mounted server dependencies to sub-10-watt edge modules capable of real-time subject classification and predictive trajectory modeling. Film production houses in California and the United Kingdom are adopting these modules for dynamic aerial cinematography where GPS signal degradation previously mandated manual pilot override. The technology is miniaturizing payload constraints, enabling sub-250-gram platforms that evade stringent operator certification requirements under FAA Part 107 and EASA open-category thresholds.
The EU AI Act is reclassifying autonomous tracking algorithms as potential high-risk artificial intelligence systems, mandating conformity assessments and post-market monitoring obligations for manufacturers deploying in European Union member states. Industrial inspection operators in Germany and France face compliance cost inflation that favors larger vendors with dedicated regulatory affairs capacity. Camera drone segments targeting broadcast applications are responding by bifurcling product roadmaps between EU-compliant restricted-autonomy variants and full-capability releases for less regulated markets.
Studio procurement departments are consolidating vendor relationships through multi-year fleet-service agreements that embed certified remote pilots, maintenance, and liability coverage within per-production pricing. Traditional equipment rental houses in Los Angeles and London are losing share to manufacturer-direct service arms that guarantee regulatory compliance and operator availability. This consolidation is most visible in scripted television production, where compressed shooting schedules eliminate tolerance for pilot certification delays or equipment failure.
Auto-Follow Drone Market Segmentation
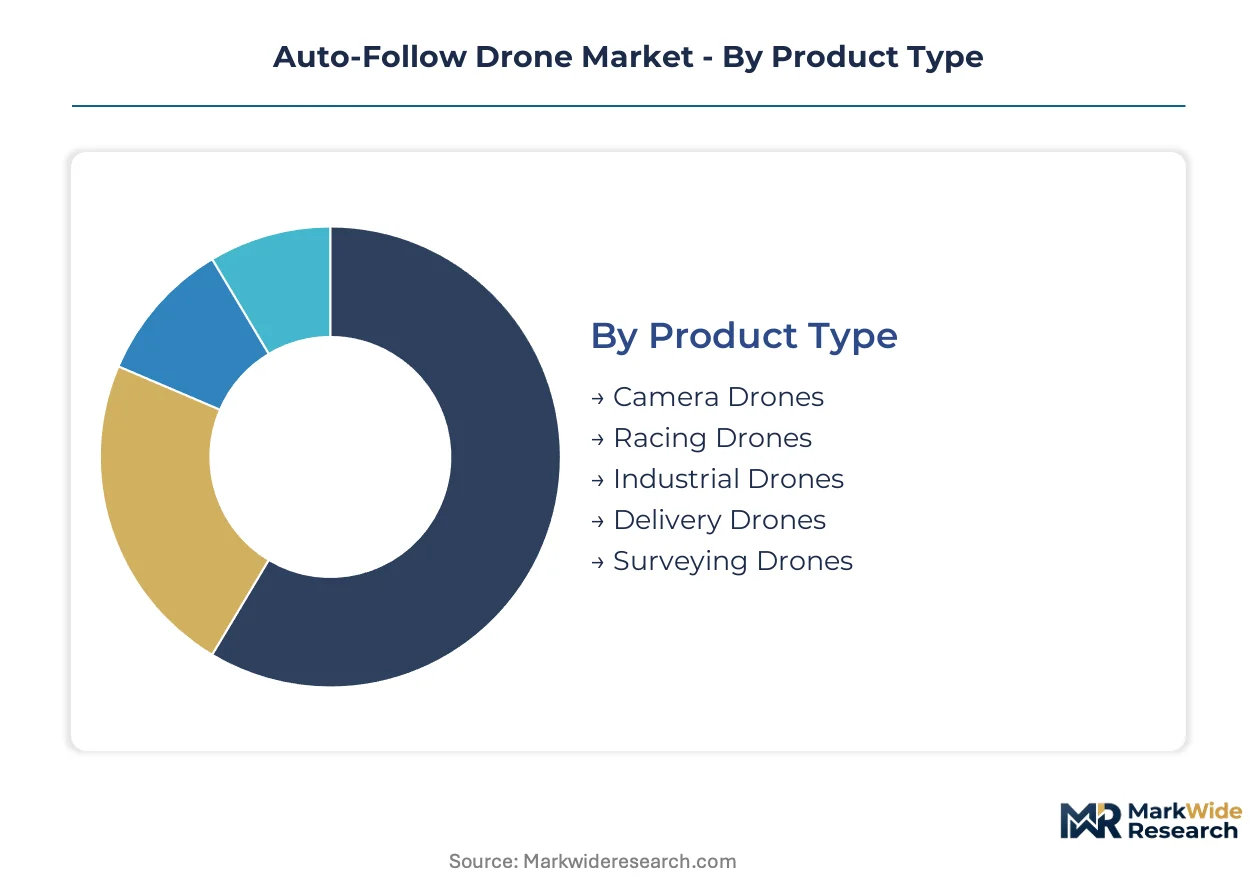
Auto-follow drone procurement patterns diverge sharply across product configurations, sensing architectures, and end-use workflows. Regulatory thresholds for operator certification and payload weight create natural segmentation boundaries that vendors exploit through tiered hardware roadmaps.
Product Type:
FAA Part 107 and EASA open-category weight thresholds stratify product development, with sub-250-gram platforms evading stringent pilot certification while heavier payloads trigger compliance cost burdens.
- Camera Drones:Gimbal-stabilized imaging platforms dominate revenue pools through penetration across consumer and commercial segments. Film production companies in California and the United Kingdom are replacing traditional crane systems with GPS-tracking and computer-vision units for dynamic aerial cinematography, driving recurring hardware refresh cycles.
- Industrial Drones:Purpose-built platforms for agricultural monitoring and infrastructure inspection concentrate margin through specialized sensor payloads and extended flight endurance. Agricultural firms in India's PLI scheme corridors are expanding procurement for crop-spraying and field-surveying auto-follow applications.
- Racing Drones:High-velocity FPV platforms serve competitive leagues and hobbyist channels with minimal autonomous tracking integration.
- Delivery Drones:Last-mile logistics platforms remain structurally immature outside limited pilot zones, constrained by beyond-visual-line-of-sight waiver availability.
- Surveying Drones:Photogrammetry-optimized units serve construction enterprises and research institutions for topographic mapping with automated flight path execution.
Established volume favors camera drones; emerging adoption favors industrial drones.
Technology:
Cost tier differentiation separates premium neural-network stacks from commodity GPS modules, with price-to-performance ratios clustering around computational sophistication rather than hardware material costs.
- Computer Vision:Neural-network-based tracking systems enable operation in GPS-denied environments such as dense urban canyons and forested terrain. Sports teams across North America and Europe are deploying these systems for athlete tracking where satellite signal degradation previously mandated manual pilot override.
- GPS Tracking:Satellite-dependent architectures anchor budget-tier consumer products and outdoor filming applications with clear sky visibility. Film production companies in California rely on GPS-dominant stacks for open-terrain aerial cinematography where signal integrity remains reliable.
- LiDAR Sensors:Laser-ranging modules provide centimeter-precision obstacle avoidance for infrastructure inspection in complex industrial environments.
- Infrared Sensors:Thermal detection arrays enable livestock monitoring and search-rescue applications through edge-AI inference without cloud dependency.
- Ultrasonic Sensors:Short-range proximity detection supplements primary navigation stacks for low-altitude indoor operation and precision landing sequences.
Computer vision is climbing the fastest; GPS tracking retains installed base dominance.
Application:
Customer maturity varies by use case complexity, with broadcast applications demanding turnkey regulatory compliance while agricultural and inspection segments tolerate longer integration timelines.
- Outdoor Filming:Dynamic aerial cinematography for film and television production represents the most compliance-intensive application segment. Studio procurement departments in Los Angeles and London are consolidating vendor relationships through multi-year fleet-service agreements that embed certified remote pilots and liability coverage.
- Sports Analysis:Athlete-tracking camera drones replace cable-suspended systems in professional leagues, generating recurring procurement tied to seasonal calendars. North American professional leagues are expanding deployment across training facilities and broadcast venues.
- Agricultural Monitoring:Crop-spraying and field-surveying platforms benefit from India's PLI scheme incentives for localized drone manufacturing assembly.
- Infrastructure Inspection:Automated bridge, pipeline, and tower assessment serves construction enterprises with predictive maintenance data capture.
- Wildlife Tracking:Non-invasive ecological research applications serve research institutions with thermal-enabled nocturnal observation capabilities.
Outdoor filming commands premium pricing; agricultural monitoring shows steepest expansion trajectory.
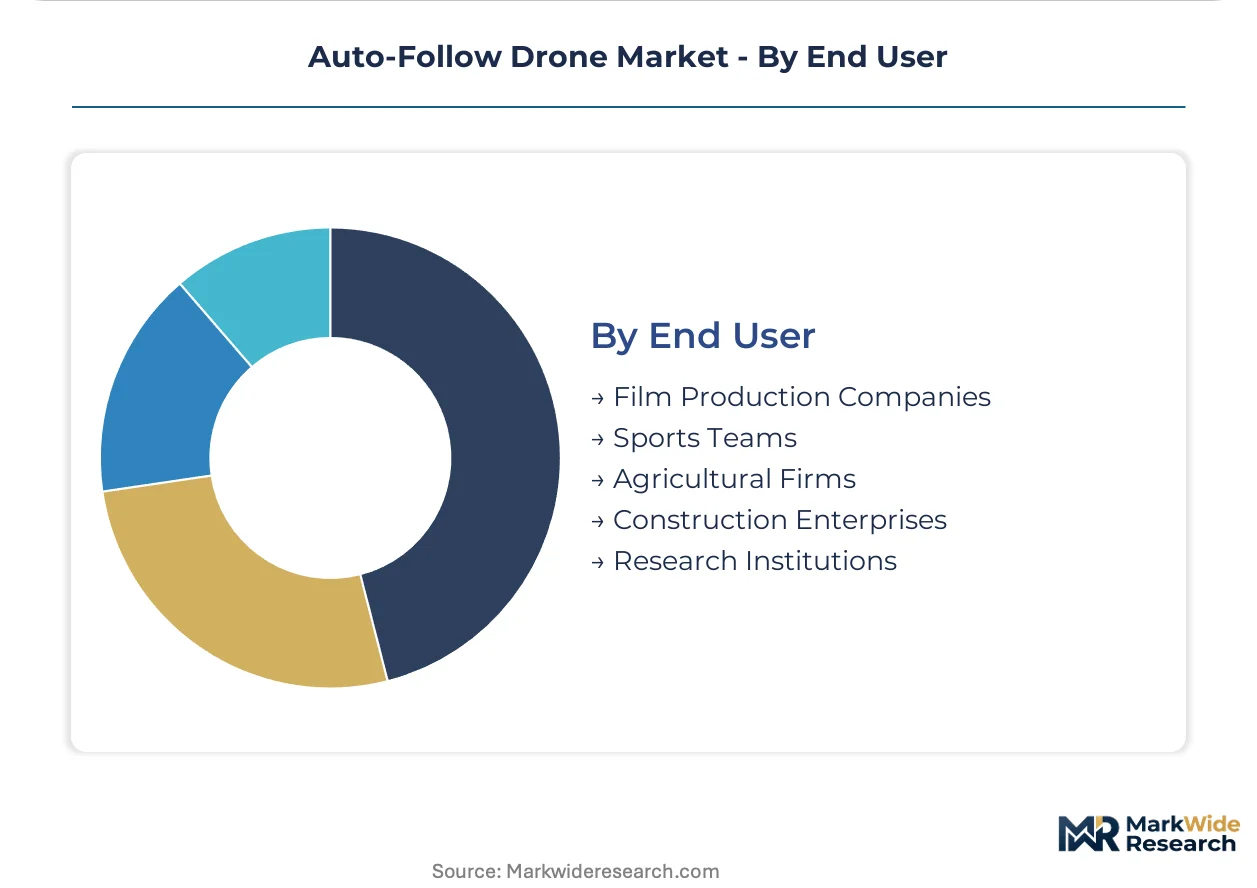
End User:
Procurement authority concentrates differently across segments, with film production houses optimizing for per-production flexibility while agricultural and construction buyers prioritize fleet standardization.
- Film Production Companies:California and United Kingdom studios drive replacement cycles through direct-to-manufacturer procurement partnerships that bypass traditional broadcast equipment distributors. Compressed shooting schedules eliminate tolerance for pilot certification delays or equipment failure.
- Sports Teams:North American and European professional leagues are expanding procurement of camera drones for athlete tracking and broadcast enhancement, with procurement tied to venue-specific waiver approvals.
- Agricultural Firms:India's PLI scheme beneficiaries are localizing assembly for crop-spraying platforms, creating cost advantages in field-surveying auto-follow deployment.
- Construction Enterprises:Infrastructure inspection mandates drive standardized fleet procurement with predictive maintenance integration.
- Research Institutions:Wildlife tracking and ecological monitoring applications prioritize thermal imaging sensor compatibility with open-data archival requirements.
Film production companies anchor near-term revenue; agricultural firms represent the fastest-growing customer expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for drone manufacturing is redirecting procurement gravity toward South Asian assembly corridors, while FAA Part 107 waiver expansions in California and Texas unlock commercial filming scale previously constrained by visual-line-of-sight limits.
United States
Film production houses in Los Angeles and sports broadcasters across Texas are consolidating fleet-service agreements that embed certified remote pilots. FAA Part 107 beyond-visual-line-of-sight waivers for certified operators now cover California film corridors and Texas sports venues. The San Francisco Bay Area concentrates computer-vision engineering talent for real-time obstacle avoidance algorithm development.
China
Guangdong Province flight controller and gimbal manufacturing clusters supply downstream assemblers with critical components for consumer and prosumer camera drones. MIIT and NMPA frameworks impose conformity assessments for radio transmission and aerial platform safety on manufacturers targeting domestic and export markets. Shenzhen's manufacturing scale anchors global supply for GPS-tracking and computer-vision units.
United Kingdom
Studio procurement departments in London are bypassing traditional broadcast equipment distributors through direct-to-manufacturer partnerships. EASA open-category frameworks and emerging EU AI Act classifications shape operational compliance for commercial auto-follow deployments. The M4 corridor film production cluster drives replacement cycles for dynamic aerial cinematography equipment.
Germany
Industrial inspection operators across Bavaria and North Rhine-Westphalia face compliance cost inflation from pending EU AI Act high-risk system designations for autonomous tracking algorithms. EASA open-category geofencing requirements segment commercial viability by compliance depth. Munich and Stuttgart engineering clusters concentrate predictive maintenance integration expertise for infrastructure assessment fleets.
India
Agricultural firms in Maharashtra and Gujarat are expanding procurement of crop-spraying and field-surveying auto-follow platforms under PLI scheme incentives for localized drone manufacturing assembly. The country's national aviation regulator mandates operator certification parallel to FAA and EASA frameworks. Bangalore and Hyderabad technology corridors are developing edge-AI inference capabilities for livestock monitoring applications.
Auto-Follow Drone Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and manufacturing scale, creating a tiered structure where Shenzhen-based volume manufacturers anchor consumer segments while Silicon Valley autonomy stacks capture premium industrial applications. The vendor base stratifies between scale-driven hardware fabricators, computer-vision software specialists, and integrated service providers bundling equipment with certified operator access. Two dominant competitive moves are reshaping positioning: direct-to-production-house sales partnerships that bypass traditional distributors, and edge-AI inference convergence through onboard neural processing unit integration.
Within the autonomy-specialist tier, Skydio exemplifies proprietary computer-vision positioning for infrastructure inspection and defense-adjacent applications, while DJI occupies a position representing Shenzhen manufacturing scale across consumer and prosumer camera drone channels. Among private specialists, Autel Robotics sits within the tier pursuing regulatory differentiation through EASA and FAA compliance-focused product roadmaps.
| Leading Market Players |
|---|
| DJI |
| Skydio |
| Autel Robotics |
| Parrot Drones SAS |
| Draganfly Innovations Inc. |
| GoPro Inc. |
| 3DR |
| Guangdong Cheerson Hobby Technology Company Limited |
| HOVERAir |
| Others |
Pricing and Supply Chain Analysis
Sixty-day flight controller lead times from Guangdong Province suppliers compress inventory buffers for North American assemblers while amplifying pricing power for Shenzhen-based component manufacturers serving premium camera drone tiers.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FAA Part 107-compliant platforms commanding substantial markups over sub-250-gram consumer alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects computational sophistication rather than hardware material costs, with neural-network autonomy stacks anchoring top-tier positioning. Pricing pressure stems from India's PLI scheme incentives accelerating localized assembly cost advantages in agricultural monitoring segments. Film production houses exhibit lowest price sensitivity due to compressed shooting schedule penalties, while agricultural buyers in emerging markets drive hardest bargain negotiations.
Supply Chain Analysis
Inventory compression to forty-five-day gimbal stockpiles exposes downstream vulnerability to Guangdong Province logistics disruptions. Flight controller and neural processing unit manufacturing concentrates in China, South Korea, and Taiwan, with raw material dependencies spanning lithium-polymer cells, rare-earth magnets, and precision optics. Single-source vulnerability concentrates in Shenzhen-based gimbal suppliers serving prosumer camera drone channels. Distribution runs through manufacturer-direct service arms consolidating studio procurement relationships in Los Angeles and London.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neural-network autonomy miniaturization and FAA beyond-visual-line-of-sight waiver expansion are accelerating commercial deployment viability across filming and inspection applications.
For Market Incumbents: Consolidate manufacturing scale advantages through backward integration into flight controller design, insulating against Guangdong supply chokepoints while deepening EASA compliance engineering capacity ahead of EU AI Act high-risk system designations. Capture margin expansion via direct-to-production-house service contracts that embed certified operators and liability coverage. For New Entrants and Emerging Players: Lead with edge-AI inference specialization for livestock monitoring and search-rescue applications where cloud dependency creates performance limitations. Agricultural monitoring in India's PLI scheme corridors offers the most penetrable entry vector, with localized assembly partnerships enabling cost-competitive crop-spraying platform introduction. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because compliance depth separates viable commercial operators from stranded consumer-grade hardware investments. Target acquisition profiles emphasize computer-vision engineering teams with real-time obstacle avoidance expertise concentrated in Silicon Valley and Tel Aviv. Watch FAA waiver throughput velocity as the critical signal for fleet-scaling service provider viability.| Strategic Initiative | Industry Significance |
|---|---|
| Onboard Neural Processing Unit Integration | Enables GPS-denied operation in dense urban canyons for California film productions. |
| EASA Compliance-Focused Product Roadmap | Bifurcates EU-restricted autonomy variants from full-capability releases for less regulated markets. |
| Direct-to-Production-House Sales Partnership | Bypasses Los Angeles broadcast equipment distributors capturing margin and replacement cycle velocity. |
| India PLI Scheme Localized Assembly | Creates cost advantages for agricultural monitoring platforms in Maharashtra and Gujarat corridors. |
| Edge-AI Thermal Imaging Convergence | Opens livestock monitoring applications without cloud dependency for Bangalore technology developers. |
Research Methodology
Operator-level perspectives from remote pilot certification trainers, film production procurement directors, sports broadcast technology officers, and agricultural drone fleet managers anchored the qualitative base. Primary fieldwork combined with secondary validation from FAA Part 107 waiver databases, EASA open-category regulatory filings, and Indian PLI scheme beneficiary disclosures. Customs records from Guangdong export corridors and hyperscaler neural processing unit capex disclosures provided supply-side triangulation. Bottom-up segment sizing and top-down macro constraint checks ensured analytical coherence.
Sensitivity analysis across battery energy density assumptions, waiver approval velocity scenarios, and AI Act classification timelines shaped projection robustness. Segmentation dimensions modeled include product configuration, sensing architecture, end-use workflow, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical penetration benchmarks. Computer-vision engineering talent concentration and lithium-polymer supply elasticity served as industry-specific forecast inputs across the projection horizon.
Underlying assumptions cover sustained FAA waiver expansion, stable Guangdong manufacturing output, and deferred EU AI Act enforcement, with deviation risk concentrated in geopolitical logistics disruption and high-risk AI system reclassification. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Toy Drones Market
UAV
Firefighting Drone Market
UAV
UAV Drones Market
UAV
Europe Drones Market
UAV
Drone Telematics Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
Drone-Based Consulting Services Market
UAV
Asia-Pacific Drone Software Market
UAV
Drone-In-A-Box Market
UAV
Solar Powered Drones Market
UAV
Industrial Drones Market
UAV
Passenger Drones Market
UAV
Drone Tracking Antenna Market
UAV
UAV Simulator Software Market
UAV
Drone Inspection Service Market
UAV
Delivery Drones Market