
 Global Dinotefuran Market | 2026-2036
Global Dinotefuran Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dinotefuran Market Analysis
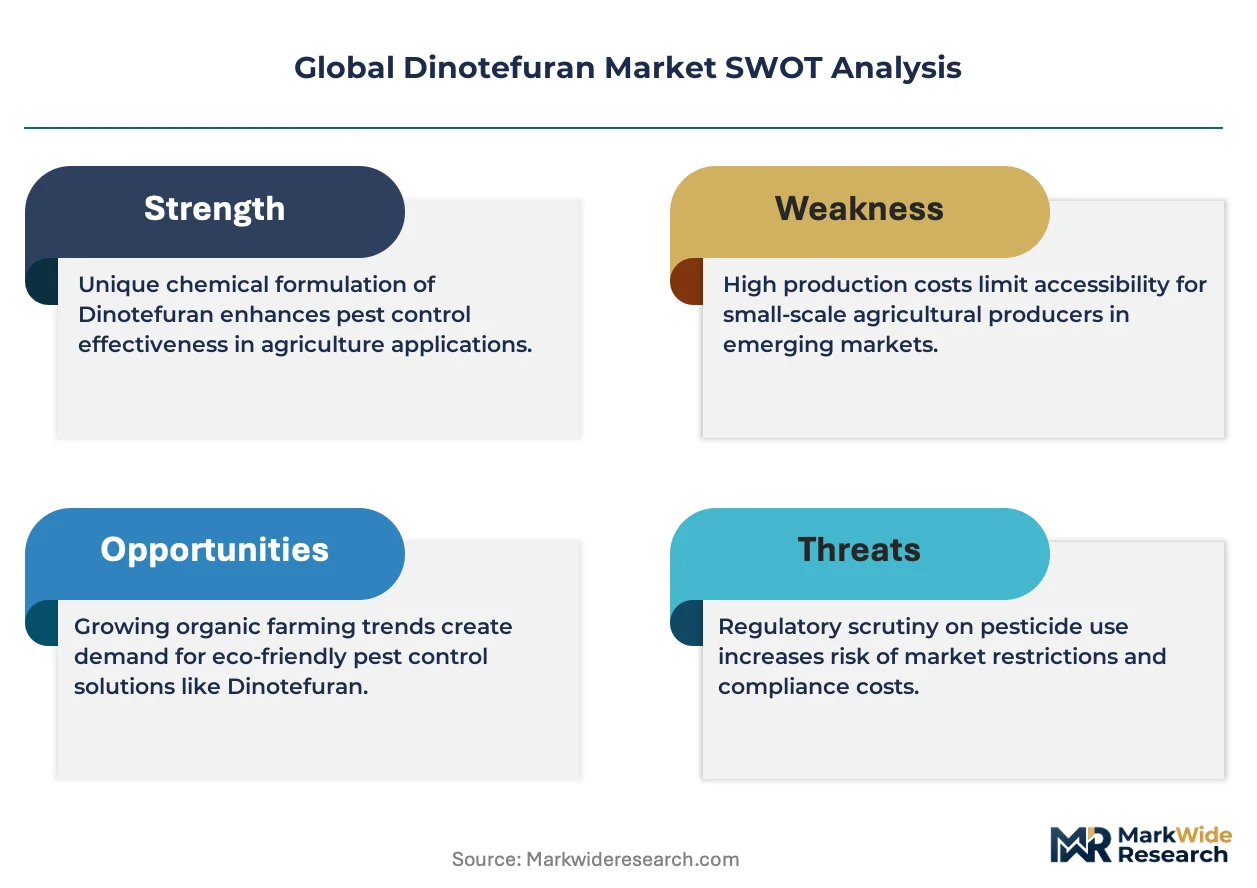
The dinotefuran market is realigning around a sharp split between premium formulated products with enhanced delivery systems and commodity-grade technical material. Mitsui Chemicals leverages its proprietary synthesis route to sustain cost leadership in technical-grade supply. Bayer Crop Science anchors the premium tier through advanced suspension concentrate formulations. Sumitomo Chemical competes via integrated seed-treatment bundling that extends its agricultural channel control.
Dinotefuran is a third-generation neonicotinoid insecticide featuring a tetrahydrofuran ring instead of chlorine or sulfur, granting it superior water solubility of approximately 39.8 g/L at 20°C and systemic mobility through xylem tissues for whole-plant protection against sap-feeding pests. Liquid formulations dominate commercial volumes due to ease of tank-mixing and aerial application compatibility, while granules capture margin pools in specialty horticultural and ornamental segments where controlled-release delivery commands pricing premiums. Agricultural crop protection absorbs the majority of demand as rice, cotton, and vegetable growers prioritize yield preservation against resistant pest populations.
The EPA regulates dinotefuran tolerances and pollinator risk assessments under FIFRA, while the EU Green Deal and REACH restrictions on neonicotinoid class chemistries reshape product registration pathways and export compliance burdens. China's MEE enforces GB standard discharge limits on neonicotinoid manufacturing effluents, raising production cost structures for technical material sourced from the country's agrochemical manufacturing clusters. Stakeholders must monitor evolving pollinator risk mitigation mandates and bioequivalence data requirements that will determine which formulation investments retain market access across jurisdictions.
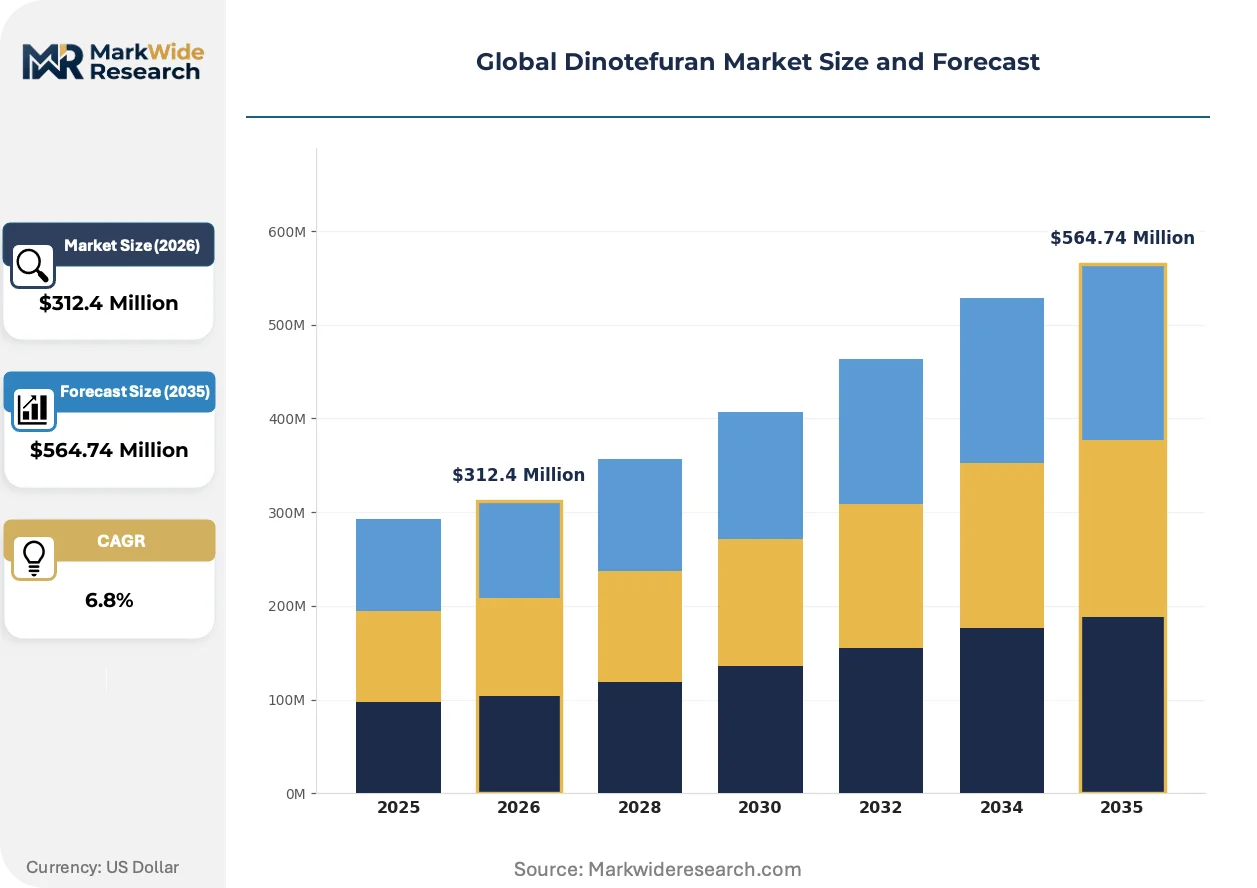
Market Dynamics
The dinotefuran market pivots on regulatory bifurcation between jurisdictions tightening neonicotinoid restrictions and those prioritizing food security over pollinator risk mitigation. This structural tension compresses registration timelines in the EU while accelerating emergency use approvals in Brazil and India.
Growth Catalysts
- EU Green Deal restrictions on bee-toxic chemistries:Farmers in member states face forced transitions away from legacy neonicotinoids, creating substitution demand for dinotefuran's differentiated toxicological profile.
- Brazilian soybean belt expansion:Whitefly pressure in Mato Grosso and Goiás drives systemic insecticide adoption as integrated pest management programs mandate rotation protocols.
- Controlled-release granule technology:Specialty horticultural operations in Japan's greenhouse districts pay premiums for extended protection windows in high-value ornamental production.
Market Restraints
- Technical-grade supply concentration:China's Jiangsu and Zhejiang manufacturing clusters control the majority of active ingredient output, exposing buyers to MEE enforcement actions on effluent discharge.
- Cross-resistance development in brown planthopper populations:Southeast Asian rice systems show declining susceptibility to neonicotinoid modes of action, threatening dinotefuran's efficacy claims.
- REACH registration cost escalation:ECHA bioequivalence data requirements for formulated products impose six-figure euro expenditures that exclude smaller agrochemical distributors.
Strategic Opportunities
- Seed-treatment bundling in India:Cotton-growing states of Maharashtra and Gujarat present underpenetrated channels where integrated pest management packages combine dinotefuran with biological adjuvants.
- Drone application compatibility:Ultra-low volume liquid formulations are converging with aerial spraying infrastructure in Australia's broadacre wheat districts, reducing labor costs per hectare.
- US EPA pollinator risk mitigation mandates:Conditional registrations requiring vegetative filter strips create service-revenue streams for agronomic consultants certifying compliance.
Industry Challenges
- Residue analytical capability gaps:Testing laboratories in secondary agricultural markets lack LC-MS/MS equipment for dinotefuran metabolite quantification at regulatory detection thresholds.
- Formulation patent thickets:Suspension concentrate adjuvant combinations developed by incumbent manufacturers create freedom-to-operate barriers for generic entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dinotefuran Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Liquid Formulation, Spray, Others Application: Agricultural Crop Protection, Pest Control, Household Insecticides, Ornamentals End User: Agricultural Sector, Chemical Manufacturers, Lawn Care Providers, Residential Users Distribution Channel: Online Sales, Specialty Stores, Agricultural Suppliers, Retail Chains |
| Companies Covered | Mitsui Chemicals, Sumitomo Chemical, Bayer Crop Science, Valent U.S.A. Corporation, Nufarm, Syngenta, FMC Corporation, UPL, Corteva Agriscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dinotefuran Market Emerging Trajectories
Formulation chemistry and application technology are compressing the gap between commodity technical supply and premium crop protection outcomes. Three developments are restructuring how value flows through the value chain.
Microencapsulation technology is converging with sustained-release polymer matrices to extend dinotefuran's soil residual activity from weeks to months. Vegetable growers in Spain's Almería greenhouse complex are adopting these formulations to reduce application frequency during high-labor-cost harvest windows. The technology is compressing the total cost of protection per growing cycle despite higher unit prices.
REACH authorization procedures for neonicotinoid class substances are forcing reformulation investments across European portfolios. Manufacturers must submit extended aquatic toxicity datasets to ECHA, diverting R&D resources from new molecule discovery toward label expansion of existing actives. Seed treatment applications face the steepest compliance burden due to dust-off exposure scenarios.
Direct-to-farm digital procurement platforms are displacing traditional distributor networks in Brazil's Mato Grosso do Sul. Large soybean operations now aggregate chemical demand through cooperative buying groups, extracting volume discounts that erode regional distributor margins. This channel shift is most visible among farms exceeding 5,000 hectares where agronomic decision-making centralizes with employed technical staff rather than external advisors.
Global Dinotefuran Market Segmentation
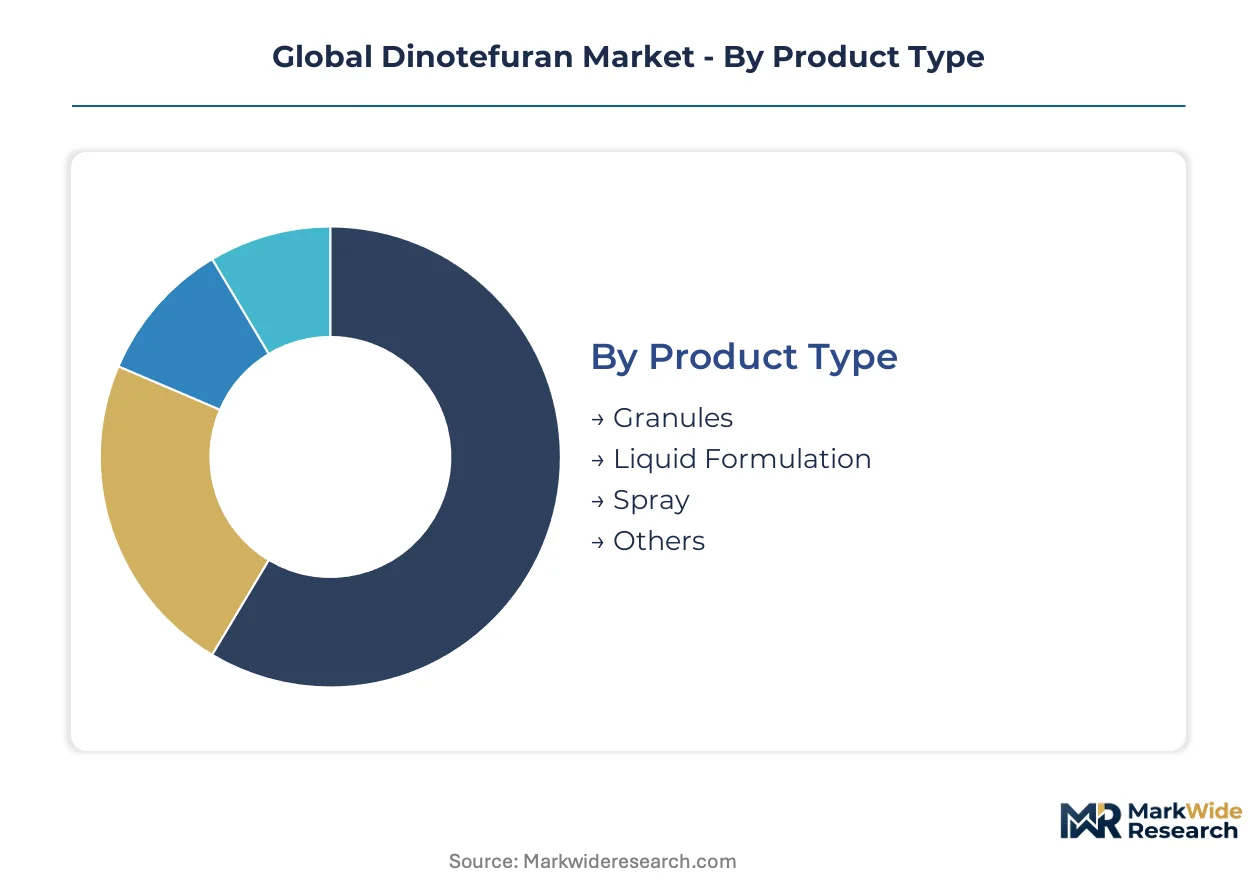
Segmentation in the dinotefuran market reveals how formulation chemistry and channel structure determine margin capture. Product type and application splits expose where technical-grade supply converts to premium pricing versus commodity competition.
Product Type:
Customization intensity varies sharply across physical form factors, with proprietary delivery systems commanding substantial premiums over generic technical material.
- Liquid Formulation:Suspension concentrates and soluble liquids enable systemic uptake through xylem tissues for whole-plant protection. Brazil's Mato Grosso soybean operations drive volume through aerial application compatibility and tank-mix flexibility with fungicides.
- Granules:Polymer-matrix controlled-release formulations extend soil residual activity from weeks to months. Japan's greenhouse ornamental producers pay premiums for labor reduction during high-cost harvest windows.
- Spray:Ready-to-use aqueous solutions target household and professional pest control channels with minimal equipment requirements.
- Others:Seed-treatment powders and water-dispersible granules serve specialized bundling applications in integrated pest management packages.
Most installed capacity flows through liquid formulations. Expansion is steepest in controlled-release granules.
Application:
Margin structures diverge between broadacre commodity crops and protected cultivation systems with intensive input requirements.
- Agricultural Crop Protection:Rice, cotton, and soybean systems absorb the majority of commercial volumes as growers prioritize yield preservation against resistant whitefly and planthopper populations. India's Maharashtra cotton belt and Brazil's Cerrado soybean districts concentrate procurement.
- Ornamentals:High-value greenhouse flower and nursery stock operations in Spain's Almería and the Netherlands' Westland region demand extended protection windows with minimal residue risk.
- Pest Control:Professional and municipal vector management programs deploy dinotefuran against invasive ant species and urban cockroach populations.
- Household Insecticides:Consumer-ready formulations target perimeter and indoor applications with reduced concentration actives.
Volume leadership sits with agricultural crop protection. Ornamentals post the steepest expansion trajectory as greenhouse automation intensifies.
End User:
Procurement sophistication separates large-scale farming operations from fragmented residential demand, with chemical manufacturers occupying a distinct intermediary position.
- Agricultural Sector:Commercial farming enterprises exceeding 500 hectares dominate technical-grade procurement, often negotiating direct supply agreements with Chinese manufacturers to bypass distributor markups.
- Chemical Manufacturers:Formulators purchasing active ingredient for proprietary blend development and private-label production.
- Lawn Care Providers:Professional turf management services in the US Sun Belt and Australian metropolitan regions.
- Residential Users:Small-scale gardeners and homeowners through retail and e-commerce channels.
Primary volume flows through agricultural sector procurement. Chemical manufacturers are gaining share fastest as in-house formulation capabilities spread.
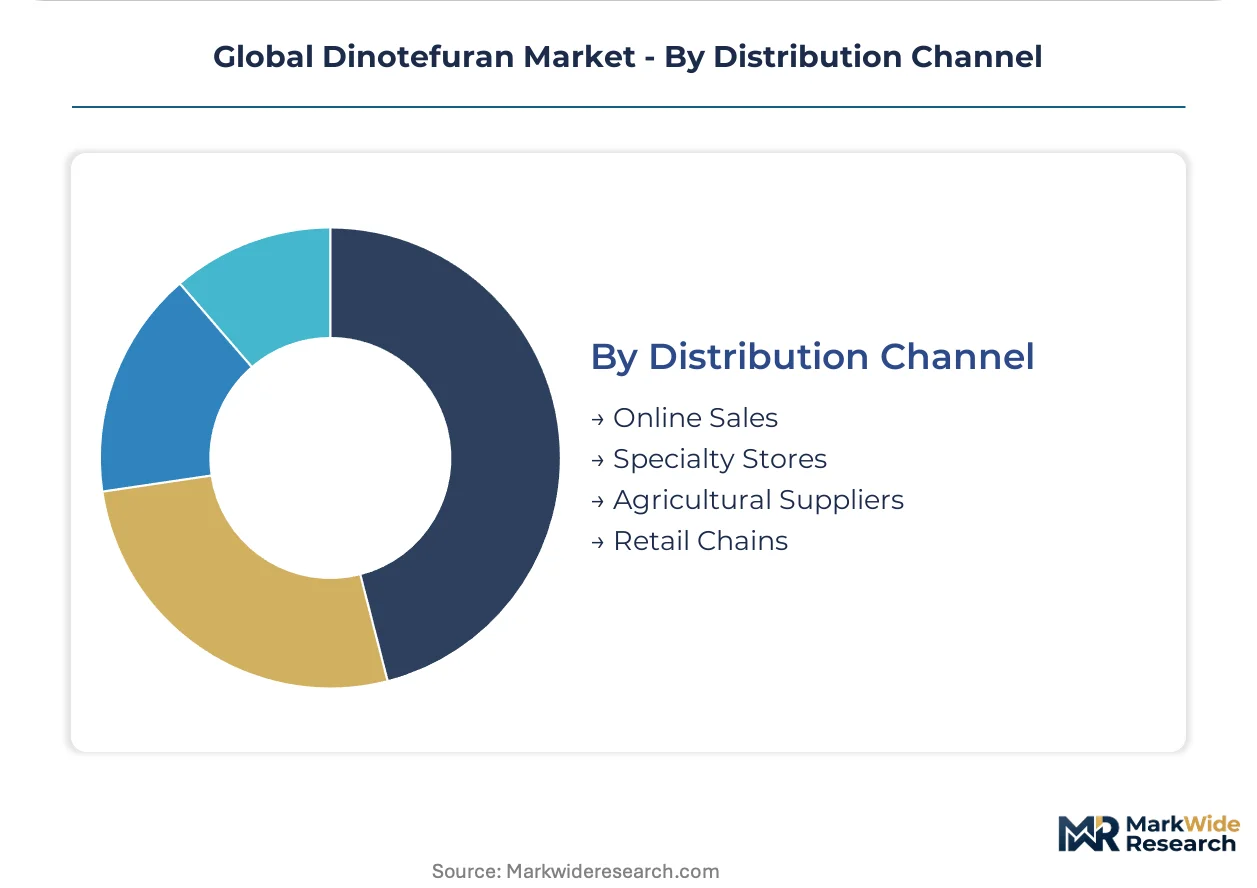
Distribution Channel:
Channel control determines pricing power, with cooperative buying groups and digital platforms compressing traditional distributor margins.
- Agricultural Suppliers:Regional cooperatives and input retailers retain dominance in Brazilian and Indian procurement, though large farms increasingly bypass through direct import arrangements.
- Online Sales:Direct-to-farm platforms and agricultural e-marketplaces aggregate demand for volume discounts, eroding regional distributor margins in Australia's wheat districts.
- Specialty Stores:Professional pest control supply houses and horticultural retailers serving ornamental and greenhouse segments.
- Retail Chains:Mass-market home improvement and garden centers for household and residential lawn applications.
Most commercial volume transits through agricultural suppliers. Online sales channels are climbing the fastest as farm-scale digital procurement platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Mato Grosso soybean belt absorbs technical-grade volumes at scale, while India's Maharashtra cotton growers negotiate direct procurement to bypass distributor markups entirely.
United States
EPA pollinator risk assessments under FIFRA reshape registration pathways for neonicotinoid alternatives. Conditional registrations now mandate vegetative filter strips and buffer zones. California's Central Valley vegetable operations drive suspension concentrate demand for whitefly management in tomato and pepper systems.
Brazil
Whitefly pressure across Mato Grosso and Goiás accelerates systemic insecticide rotation protocols. ANVISA expedites emergency use approvals for food security priorities. The Cerrado soybean belt concentrates procurement through cooperative buying groups exceeding 5,000 hectares.
China
Jiangsu and Zhejiang manufacturing clusters control active ingredient output for global technical supply. MEE enforcement of GB standard discharge limits raises production cost structures. Nantong chemical parks face recurring environmental compliance actions that disrupt export scheduling.
India
Maharashtra and Gujarat cotton states present underpenetrated seed-treatment bundling opportunities. CDSCO bioequivalence requirements for formulated products escalate registration expenditures. Punjab's rice systems show emerging brown planthopper cross-resistance that threatens neonicotinoid efficacy claims.
Japan
Greenhouse ornamental producers in Chiba and Ibaraki prefectures pay premiums for controlled-release granule formulations. METI standards on agricultural chemical residues shape export compliance for domestic manufacturers. The protected cultivation sector drives steepest expansion in polymer-matrix delivery systems.
Global Dinotefuran Market Vendor Landscape
Top-tier vendors anchor premium formulated products with proprietary delivery systems, while commodity-grade technical material concentrates among cost-optimized manufacturers. The market structures around three strategic archetypes: integrated agrochemical conglomerates with seed-treatment bundling capabilities, specialized neonicotinoid formulators with suspension concentrate expertise, and technical-grade suppliers leveraging proprietary synthesis routes. Dominant competitive moves include backward integration into active ingredient production and geographic expansion through direct-to-farm digital procurement platforms.
Within the integrated conglomerate tier, Mitsui Chemicals and Sumitomo Chemical represent Japanese-origin specialists with captive synthesis capabilities and regional channel control. Bayer Crop Science occupies a position exemplifying premium-tier formulation differentiation through advanced delivery systems. These three anchors demonstrate how proprietary technology access separates margin capture from commodity competition in neonicotinoid markets.
| Leading Market Players |
|---|
| Mitsui Chemicals |
| Sumitomo Chemical |
| Bayer Crop Science |
| Valent U.S.A. Corporation |
| Nufarm |
| Syngenta |
| FMC Corporation |
| UPL |
| Corteva Agriscience |
| Others |
Supply Flow & Price Mechanics
Para-xylene feedstock indices from China's Sinopec pricing benchmarks cascade through Jiangsu chemical park intermediates into three-tier pricing stratification across premium formulated products, standard technical grades, and economy spot material. Farmers in Brazil's Mato Grosso negotiate direct offtake agreements that compress distributor markups, while Indian cotton growers face landed cost premiums from CDSCO bioequivalence compliance burdens.
Pricing Analysis
Capacity additions in Zhejiang and Jiangsu provinces are reshaping price floors for technical-grade dinotefuran as MEE enforcement actions on GB standard discharge limits raise marginal production costs. Three-tier pricing structure across premium suspension concentrates, standard soluble liquids, and economy technical material separates Bayer Crop Science's proprietary delivery systems from generic entrants. Cost compression in commodity technical grades is intensifying because Chinese manufacturers absorb environmental compliance expenditures without full pass-through to export markets. Large-scale agricultural operations exceeding 5,000 hectares in Brazil exhibit lowest price sensitivity through cooperative buying power, while fragmented cotton growers in India's secondary districts face highest cost pass-through vulnerability.
Supply Chain Analysis
India's PLI scheme for agrochemical manufacturing and Brazil's ANVISA local-content preferences for emergency use approvals are reshaping sourcing patterns toward regional formulation capacity. Active ingredient output concentrates in China's Nantong and Taizhou chemical parks, with secondary technical supply from India's Gujarat and Maharashtra manufacturing zones. Raw material dependencies span 2-methyltetrahydrofuran for the signature ring structure, nitroguanidine intermediates, and specialized surfactants for suspension concentrate stability. Single-source vulnerability runs through Jiangsu effluent treatment capacity constraints that disrupt export scheduling during MEE inspection cycles. Distribution runs through agricultural supplier cooperatives in Brazil and India, with fastest channel shift toward direct-to-farm digital platforms in Australia's wheat districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dinotefuran market reads as a late-cycle quality story where greenhouse ornamental producers in Japan and Spain's Almería increasingly specify controlled-release granule formulations with extended residual windows, compressing total cost of protection despite higher unit acquisition prices.
For Market Incumbents: Acquire captive synthesis capacity for the tetrahydrofuran ring intermediate to secure cost position against Chinese technical supply volatility. Mitsui Chemicals and Sumitomo Chemical demonstrate how proprietary synthesis routes defend margin structure when MEE enforcement disrupts Jiangsu export flows. Seed-treatment bundling capabilities in India's Maharashtra cotton belt represent the priority channel control lever against generic formulation entrants. For New Entrants and Emerging Players: Enter via drone-application-compatible ultra-low volume formulations for Australia's broadacre wheat districts, where aerial spraying infrastructure convergence creates white-space penetration without incumbent distributor lock-in. India's underpenetrated seed-treatment bundling channels in Gujarat present accessible entry points through biological adjuvant co-formulation partnerships with local agricultural cooperatives. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized neonicotinoid formulators possessing suspension concentrate expertise and ECHA REACH authorization track records. Long-term viability over the projection horizon favors targets with demonstrated pollinator risk mitigation data packages that retain EU market access amid Green Deal tightening. The signal to watch is cross-resistance emergence in Southeast Asian brown planthopper populations, which would accelerate substitution demand for alternative mode-of-action chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tetrahydrofuran Intermediates | Captive supply of the signature ring structure insulates against Chinese petrochemical feedstock volatility. |
| Controlled-Release Granule Capacity Expansion | Polymer-matrix manufacturing lines capture premium pricing from Japan's greenhouse ornamental sector. |
| Seed-Treatment Bundling Partnerships | Integrated pest management packages with biological adjuvants penetrate India's Maharashtra cotton cooperatives. |
| Drone Application Formulation Development | Ultra-low volume liquids align with aerial spraying infrastructure buildout in Australia's wheat districts. |
| ECHA REACH Authorization Investment | Extended aquatic toxicity datasets preserve EU market access under Green Deal neonicotinoid restrictions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with agrochemical plant managers in Jiangsu and Zhejiang, procurement leads at Brazilian soybean cooperatives, distribution channel partners in India's Maharashtra belt, and technical R&D directors at Japanese formulation houses. Secondary validation drew from customs and trade data on neonicotinoid active ingredient flows, China Crop Protection Industry Association capacity reports, EPA FIFRA registration databases, and SEC 10-K disclosures from listed agrochemical conglomerates. Bottom-up volume estimates from country-level crop protection expenditure patterns were triangulated against top-down active ingredient production capacity assessments.
Historical reference periods anchored the forecast window to five-year trailing demand patterns in rice, cotton, and soybean systems, with projection horizons extending through regulatory phase-in timelines for EU Green Deal restrictions. Segmentation dimensions modeled included formulation chemistry tier, crop system application, regional regulatory cluster, and channel structure. CAGRs were derived from slope analysis of adoption curves for systemic insecticide rotation protocols, with industry-specific inputs incorporating whitefly pressure indices in Brazil's Cerrado and planthopper resistance monitoring data from Southeast Asian rice systems.
Inputs from EPA pollinator risk assessments and ECHA bioequivalence guidance documents were available through the study window; gaps in real-time brown planthopper susceptibility monitoring from Punjab's rice systems introduce uncertainty bands around neonicotinoid efficacy duration assumptions. Forecasts reflect documented regulatory trajectories and crop protection expenditure patterns subject to revision from accelerated resistance development or unanticipated MEE enforcement intensity in Chinese chemical parks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Bird Repellent Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Global Agricultural Colorants Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
GCC Feed Premix Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Africa Feed Antioxidants Market