
 Europe Feed Pelletizing Agents Market | 2026-2036
Europe Feed Pelletizing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Pelletizing Agents Market Analysis
Asset-light leasing arrangements for pelletizing agent storage and blending infrastructure is narrowing the capital barrier for mid-sized compound feed producers. BASF leverages its integrated chemical platform to supply lignosulfonate binders across Northwestern European milling corridors. Cargill Inc anchors distribution through port-adjacent blending facilities that shorten lead times for Atlantic-facing customers. Borregaard LignoTech specializes in wood-derived binding chemistry, occupying a defensible niche as sustainability audits intensify.
Europe Feed Pelletizing Agents encompass functional additives—binders, lubricants, and coating agents—formulated to enhance pellet integrity, reduce feed dust, and improve nutrient stability during mechanical compression at 80–120°C conditioning temperatures. The primary commercial purpose centers on minimizing feed waste and optimizing livestock intake consistency across automated feeding systems. Binders command the largest share of type-based revenue as ruminant feed producers prioritize pellet durability for outdoor storage and transport. Aquafeed represents the fastest-expanding application segment, driven by salmon and trout farming expansion in Norway and Scotland where water-stable pellets reduce nutrient leaching. Powder formulations dominate current volume flows, though liquid coating systems are gaining traction in premium poultry and pet food lines for precise nutrient layering.
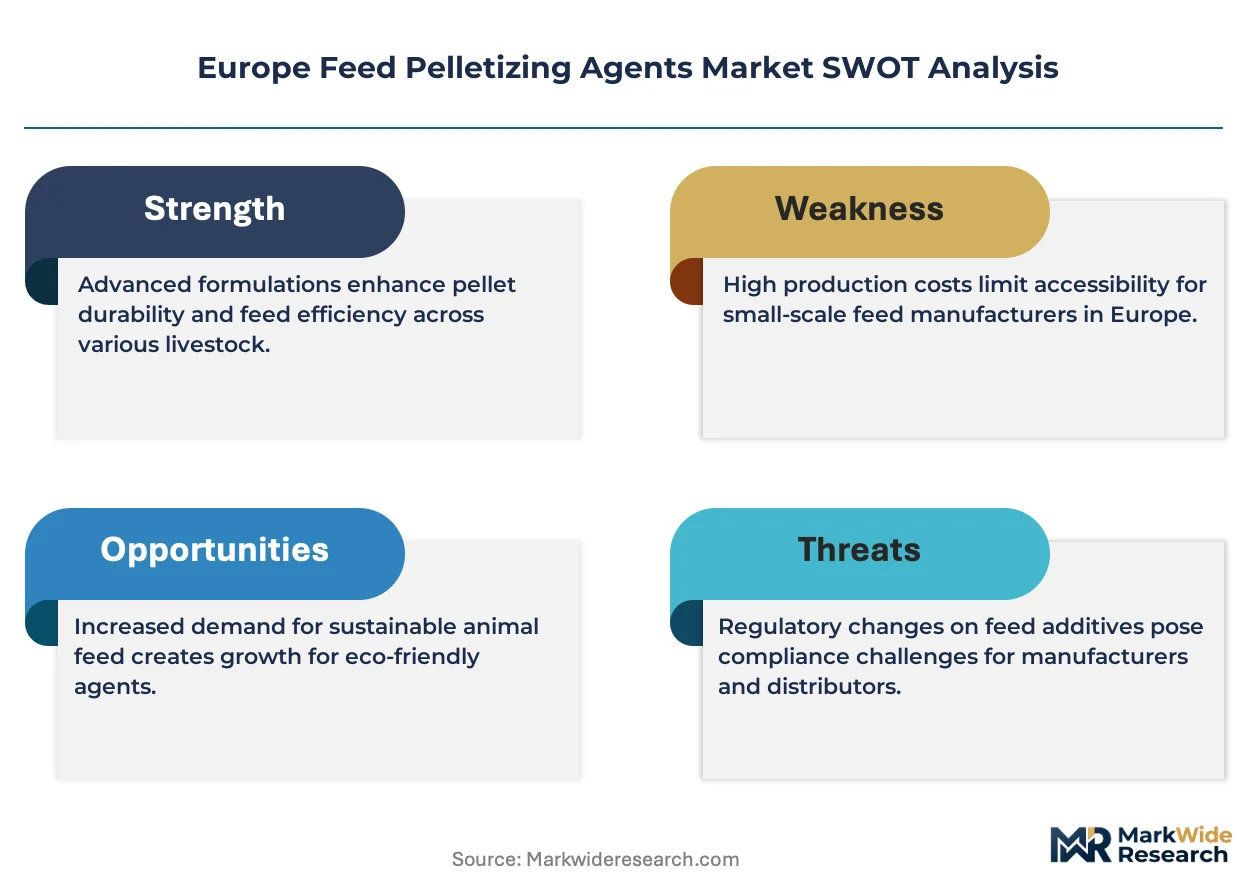
EMA guidelines on feed additive safety assessments, REACH chemical registration requirements, and the EU Green Deal Farm-to-Fork strategy collectively shape product formulation standards and market access conditions across member states. EFSA evaluates novel pelletizing chemistries for residue risks, while REACH compliance costs filter out smaller importers of non-EU sourced binding materials. Stakeholders must monitor pending revisions to the EU Feed Hygiene Regulation and anticipate how circular-economy mandates will redefine acceptable raw material streams for lignin and clay-based binders.
Market Dynamics
The EU Green Deal Farm-to-Fork strategy is compressing formulation timelines for compound feed manufacturers, forcing rapid recertification of pelletizing chemistries while sustainability audits intensify scrutiny of lignin and clay sourcing streams.
Growth Catalysts
- REACH registration thresholds:Consolidated chemical dossiers under ECHA requirements are filtering out non-compliant imports, creating protected demand corridors for EU-registered binder suppliers serving German and French milling clusters.
- Aquafeed water stability mandates:Norwegian and Scottish salmon producers are specifying pelletizing agents that reduce nutrient leaching in marine environments, expanding addressable volume for specialized coating chemistries.
- Automated feeding system penetration:Dairy operations across Denmark and the Netherlands are retrofitting barn infrastructure, generating pull for dust-suppressing pellet formulations that protect pneumatic conveyor mechanisms.
Market Restraints
- Wood pulp input cost volatility:Lignosulfonate binder margins compress when Nordic pulp mill capacity tightens, exposing compound feed producers to quarterly price resets they cannot pass through contractually.
- EFSA residue assessment timelines:Novel binding chemistries face 18-24 month safety evaluation windows that freeze product launches and drain R&D budgets before revenue recognition.
- Mineral clay substitution pressure:Bentonite binders face displacement by fermented protein alternatives in premium ruminant feed lines, threatening volume in traditional durability applications.
Strategic Opportunities
- Poland and Romania feed mill modernization:EU cohesion fund infrastructure grants are enabling mid-sized compounders in Eastern Europe to specify pelletizing agents previously reserved for Western European volume buyers.
- Liquid coating convergence with precision nutrition:Enzyme and probiotic layering technologies are creating hybrid application equipment demand that binds pellet integrity with gut health functionality.
- CSRD supply chain disclosure mandates:Corporate sustainability reporting requirements are rewarding pelletizing agent suppliers with certified circular-economy raw material streams, opening procurement preference windows.
Industry Challenges
- Feed formulation chemist scarcity:Compound manufacturers struggle to recruit specialists who bridge mechanical engineering of pelleting equipment with biochemistry of binding agent interactions at conditioning temperatures.
- Legacy silo integration complexity:Retrofitting liquid coating systems into existing 80-120°C conditioning lines requires custom engineering that extends commissioning timelines and strains maintenance crews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Pelletizing Agents Market |
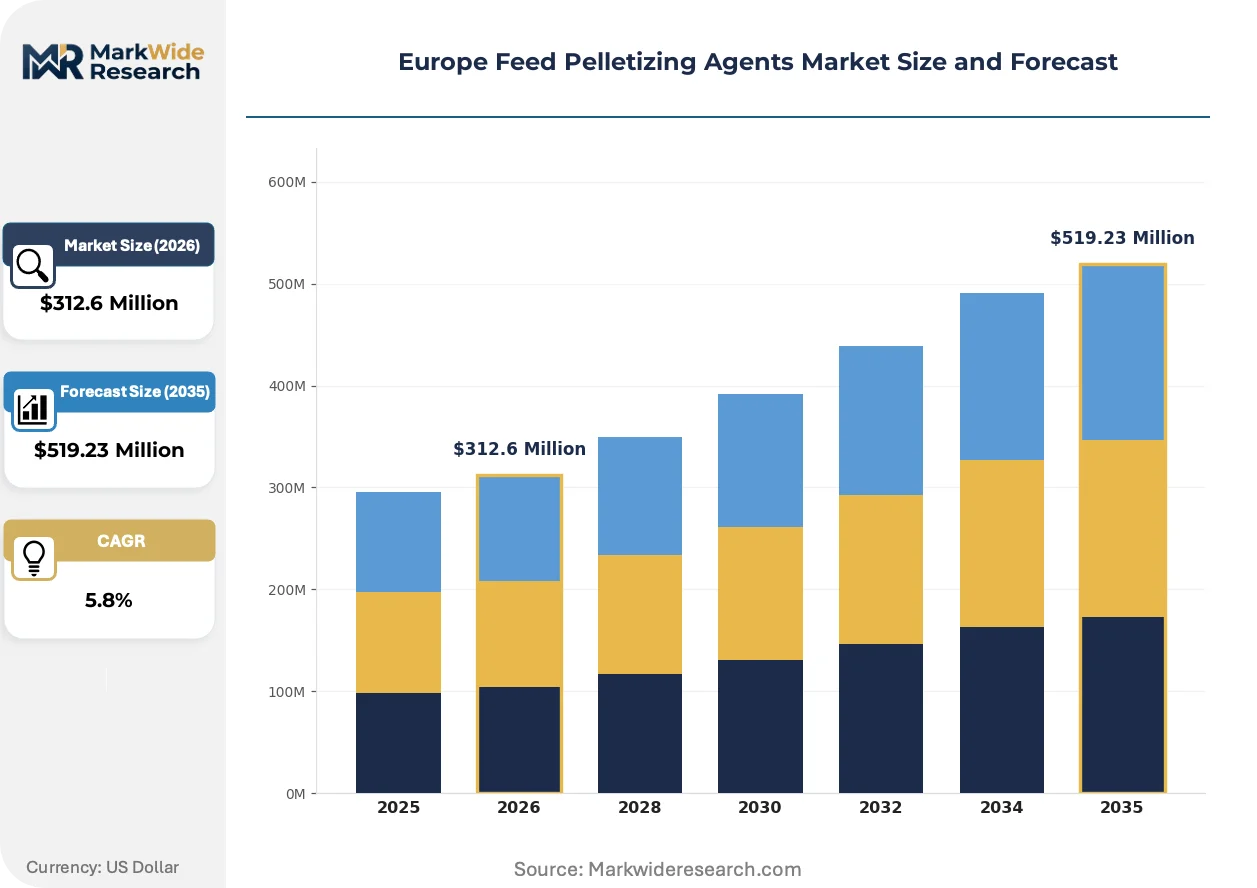
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $519.23 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Binders, Coating Agents, Lubricants, Anti-oxidants Application: Poultry Feed, Ruminant Feed, Aquafeed, Pet Food Form: Granules, Powders, Liquids, Pellets Packaging Type: Bags, Drums, Bulk Containers, Pails |
| Companies Covered | BASF, Archer Daniels Midland Company, Cargill Inc, Uniscope Inc, Borregaard LignoTech, Bentonite Performance Minerals LLC, AllTech, EW Nutrition, Kemin Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Pelletizing Agents Market Emerging Trajectories
Digital formulation platforms are compressing the experimental cycle for pelletizing agent selection, while regulatory disclosure requirements and precision livestock farming converge to reshape specification criteria across European compound feed operations.
Digital twin simulation software for pelleting line optimization is virtualizing the traditional pilot-scale testing phase that once consumed weeks of mill downtime. German and Dutch compound feed engineers now model binder performance across temperature and moisture variables before physical trials, collapsing development cycles from months to days. This capability is virtualizing the competitive advantage of incumbents who previously relied on decades of empirical formulation libraries.
EFSA's pending revisions to feed additive safety guidance are tightening residue monitoring protocols for novel binding chemistries entering ruminant and aquafeed channels. Compound manufacturers must now front-load toxicological data packages before market entry, elevating compliance costs that favor larger chemical suppliers with dedicated regulatory affairs functions. Aquafeed applications in Norway face the steepest documentation burdens as marine ecosystem impact assessments become mandatory.
Consolidated procurement consortiums among Danish and Swedish dairy cooperatives are compressing supplier rosters and demanding outcome-based pellet durability guarantees rather than input-based specifications. These buying groups now contract directly with pelletizing agent formulators, bypassing traditional distributor markups and forcing intermediaries to reposition as logistics service providers. The shift is most visible in Jutland and Skåne regions where cooperative concentration has reached critical scale.
Europe Feed Pelletizing Agents Market Segmentation
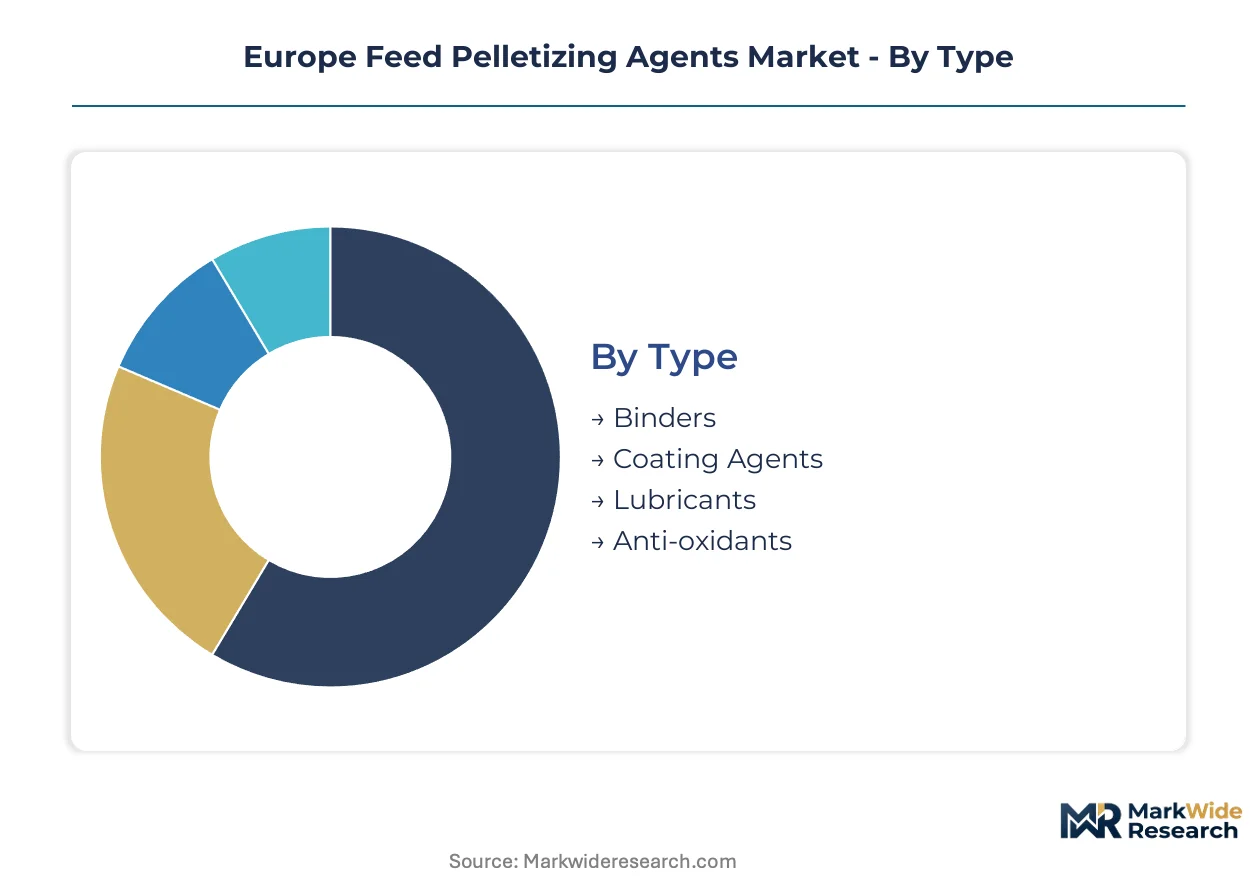
Pelletizing agent specification varies sharply across feed categories, conditioning temperatures, and handling protocols. Compound feed manufacturers align procurement decisions with durability requirements, regulatory exposure, and integration complexity with existing pelleting infrastructure.
Type:
After-sales service intensity escalates with binder chemistry complexity—lignosulfonate formulations demand technical troubleshooting that coating agents rarely require.
- Binders:Lignosulfonates and bentonite clays mechanically interlock feed particles under 80–120°C conditioning. Ruminant feed producers across Germany and France specify these for outdoor storage durability where moisture exposure degrades unprotected pellets. REACH registration costs filter out smaller suppliers, consolidating procurement around ECHA-registered chemical platforms.
- Coating Agents:Specialized chemistries create water-stable barriers that reduce nutrient leaching in marine environments. Norwegian salmon farmers in Bergen and Trondheim corridors specify these for aquafeed applications where pellet integrity directly impacts feed conversion ratios and effluent compliance.
- Lubricants:Reduce die friction and energy consumption in high-throughput pelleting lines.
- Anti-oxidants:Preserve lipid stability in vitamin-fortified poultry and pet food formulations.
Binders hold the largest share; momentum sits with coating agents.
Application:
Volume concentration maps directly to livestock density and automation penetration across national dairy and poultry belts.
- Ruminant Feed:Dairy cooperatives in Denmark and the Netherlands drive specification for dust-suppressing formulations that protect pneumatic conveyor systems in retrofitted barn infrastructure. Pellet durability guarantees have displaced input-based procurement contracts in Jutland and Skåne cooperative clusters.
- Aquafeed:Salmon and trout farming expansion in Norway and Scotland demands water-stable pellets that minimize nutrient leaching into marine ecosystems. EFSA residue assessment timelines stretch 18–24 months for novel chemistries entering this channel, elevating compliance costs that favor established suppliers.
- Poultry Feed:Automated layer and broiler operations prioritize flowability and minimal fines generation.
- Pet Food:Premium kibble lines specify coating systems for precise nutrient layering and palatability enhancement.
Ruminant feed commands the greatest volume; aquafeed is climbing the fastest.
Form:
Physical state determines blending equipment compatibility and conditioning line retrofit requirements.
- Powders:Dominant volume flows through traditional dry-addition systems at compound feed mills. German and French milling clusters favor these for operational simplicity and established handling protocols across legacy infrastructure.
- Liquids:Gaining traction in premium poultry and pet food applications where precise nutrient layering requires spray-coating equipment. Retrofitting 80–120°C conditioning lines demands custom engineering that extends commissioning timelines.
- Granules:Intermediate flow properties suit mid-sized compounders upgrading from powders without full liquid system investment.
- Pellets:Pre-formulated concentrate forms reduce on-site blending complexity for smaller feed operations.
Powders retain the dominant position; liquids are expanding most quickly.
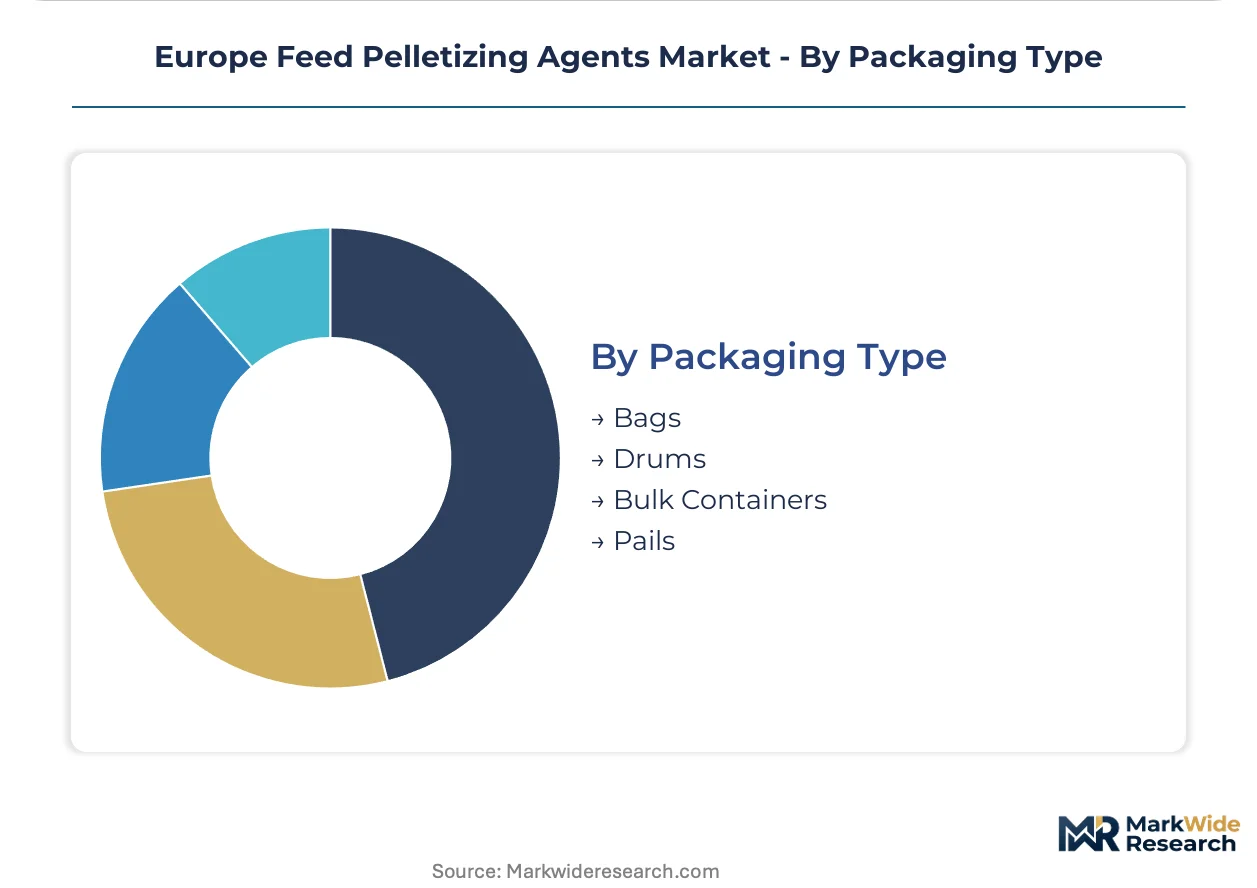
Packaging Type:
Packaging selection reflects procurement scale, storage constraints, and circular-economy audit requirements under CSRD mandates.
- Bulk Containers:Large compound feed manufacturers specify these for port-adjacent blending facilities that shorten lead times for Atlantic-facing customers. Returnable bulk systems score favorably in sustainability disclosures.
- Bags:Mid-sized mills in Poland and Romania rely on these for flexibility as EU cohesion fund grants enable infrastructure modernization.
- Drums:Liquid coating agents and specialized lubricants require sealed containment for stability.
- Pails:Small-batch premium pet food producers favor these for precise inventory management.
Bulk containers capture the largest share; bags show steepest expansion in Eastern European modernization corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal Farm-to-Fork strategy funnels cohesion fund investments toward feed mill modernization, concentrating pelletizing agent procurement in dairy-intensive corridors where automated feeding infrastructure demands dust-suppressing formulations.
Germany
North Rhine-Westphalia and Lower Saxony house Europe's densest compound feed milling clusters, where lignosulfonate binders dominate ruminant feed specifications for outdoor storage durability. REACH registration dossiers filed with ECHA filter out non-compliant imports, protecting domestic chemical platforms. BASF leverages its Ludwigshafen integrated production complex to supply Northwestern European milling corridors with registered binding chemistries.
France
Brittany and Pays de la Loire dairy cooperatives drive specification for pellet durability guarantees that displace input-based procurement contracts. The country's national feed safety regulator enforces residue monitoring protocols that elevate compliance costs for novel binding chemistries. Port-adjacent blending facilities in Nantes and Saint-Nazaire shorten lead times for Atlantic-facing compound feed manufacturers.
Netherlands
Friesland and Gelderland dairy operations retrofit barn infrastructure with pneumatic conveyor systems, generating pull for dust-suppressing pellet formulations. CSRD supply chain disclosure mandates reward pelletizing agent suppliers with certified circular-economy raw material streams. Cooperative procurement consortiums in Jutland-adjacent regions compress supplier rosters and demand outcome-based durability guarantees.
Norway
Bergen and Trondheim salmon farming corridors specify water-stable coating agents that minimize nutrient leaching into marine environments. EFSA residue assessment timelines stretch 18–24 months for novel chemistries entering aquafeed channels, elevating compliance barriers. Marine ecosystem impact assessments have become mandatory for binding chemistries deployed in Norwegian fjord operations.
Poland
Masovia and Greater Poland regions modernize mid-sized compound feed mills through EU cohesion fund infrastructure grants, enabling specification of pelletizing agents previously reserved for Western European volume buyers. The country's feed safety authority aligns with EFSA guidance while maintaining national registration requirements. Poznań and Łódź milling clusters increasingly procure bulk-container delivery systems to match Western handling protocols.
Europe Feed Pelletizing Agents Market Vendor Landscape
Channel-controlling players compete with product-specialist players for procurement relationships with consolidated dairy cooperatives and aquafeed integrators. The vendor base organizes around three archetypes: integrated chemical platforms with REACH-registered dossiers, wood-derived binding specialists with circular-economy certifications, and diversified nutrition companies with precision livestock farming portfolios. Competitive moves concentrate on backward integration into lignin raw material streams and geographic expansion into Eastern European modernization corridors.
Among integrated chemical platforms, BASF and Cargill Inc occupy positions that span binder chemistry production through port-adjacent distribution infrastructure. Borregaard LignoTech exemplifies the wood-derived specialist archetype, leveraging Nordic pulp mill proximity to supply lignosulfonate formulations. These three anchors represent distinct competitive vectors: chemical platform scale, agricultural trading network density, and defensible sustainability positioning under intensifying audit regimes.
| Leading Market Players |
|---|
| BASF |
| Archer Daniels Midland Company |
| Cargill Inc |
| Uniscope Inc |
| Borregaard LignoTech |
| Bentonite Performance Minerals LLC |
| AllTech |
| EW Nutrition |
| Kemin Industries |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp barge freight corridors shape pelletizing agent cost structures across Northwestern European milling clusters, concentrating pricing power among REACH-registered suppliers while forcing downstream differentiation between bulk-container volume buyers and bagged-delivery mid-sized compounders.
Pricing Analysis
Certification level creates the primary spread across ECHA-registered lignosulfonate binders, REACH-compliant bentonite clays, and non-registered import alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA residue assessment completion status, with novel aquafeed coating chemistries commanding premiums pending 18–24 month safety evaluations. Cost compression in standard-grade ruminant binders is intensifying because Nordic pulp mill capacity tightens quarterly. Dairy cooperatives in Denmark and the Netherlands show lowest price sensitivity due to outcome-based durability guarantees, while Polish and Romanian mid-sized compounders remain most cost-conscious as EU cohesion fund grants phase in.
Supply Chain Analysis
Nordic pulp mill output, German chemical platform production, and French bentonite mining operations anchor upstream feedstock availability for lignosulfonate and clay-based binders. Wood pulp lignin, sulfuric acid processing capacity, and mineral clay deposits constitute critical input dependencies. Single-source vulnerability concentrates around Borregaard LignoTech's Nordic pulp mill proximity for premium lignosulfonate grades. Distribution runs through port-adjacent blending facilities in Hamburg, Nantes, and Rotterdam that shorten lead times for Atlantic-facing compound feed manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal Farm-to-Fork strategy implementation is compressing formulation timelines and forcing rapid recertification of pelletizing chemistries, creating high-growth disruption as sustainability audits intensify scrutiny of lignin and clay sourcing streams.
For Market Incumbents: Harden REACH registration dossiers against pending EFSA residue assessment revisions by front-loading toxicological data packages before market entry. Deepen backward integration into certified circular-economy lignin raw material streams to defend margin position against wood pulp input cost volatility. Expand technical service capabilities for liquid coating system retrofits to capture premium poultry and pet food specification shifts.
For New Entrants and Emerging Players: Pursue Poland and Romania feed mill modernization corridors where EU cohesion fund infrastructure grants enable specification of pelletizing agents previously reserved for Western European volume buyers. Target aquafeed coating agent white space in Norwegian salmon farming corridors where water stability mandates outpace incumbent capacity. Lead with digital twin simulation software partnerships that collapse binder development cycles from months to days.
For Investors and Strategic Acquirers: Wood-derived binding specialists with circular-economy certifications and Nordic pulp mill supply agreements represent priority acquisition targets as CSRD supply chain disclosure mandates intensify. Long-term viability hinges on defensible sustainability positioning under intensifying audit regimes rather than commodity chemical scale. Monitor EFSA pending revisions to feed additive safety guidance as the critical inflection signal for compliance cost escalation favoring larger chemical suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Dossier Expansion | ECHA compliance filters out non-compliant imports, protecting domestic chemical platforms in Germany and France. |
| Backward Integration into Lignin Streams | Certified circular-economy raw material sourcing opens procurement preference windows under CSRD mandates. |
| Liquid Coating System Retrofit Services | Custom engineering capabilities capture premium poultry and pet food specification shifts across 80–120°C conditioning lines. |
| Eastern European Distribution Footprint | Port-adjacent blending facilities in Poland shorten lead times for EU cohesion fund-enabled mill modernization. |
| Digital Twin Simulation Partnerships | Virtual pelleting line optimization collapses binder development cycles and displaces empirical formulation libraries. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with compound feed plant managers, procurement leads at dairy cooperatives, pelletizing agent technical R&D directors, and distribution channel partners across German, French, Dutch, Norwegian, and Polish milling clusters. Secondary validation drew from EFSA feed additive safety guidance documents, ECHA REACH registration databases, EU Green Deal Farm-to-Fork strategy implementation reports, and customs trade data for lignosulfonate and bentonite clay imports. Bottom-up volume estimates from individual mill specifications were triangulated against top-down chemical platform production capacity assessments.
Calibration against historical EFSA assessment timeline data and pulp mill capacity utilization rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include binder chemistry type, livestock application category, physical formulation state, and regional regulatory cluster intensity. CAGRs were derived from fitted growth curves incorporating aquafeed water stability mandate penetration rates and automated feeding system retrofit adoption across Danish and Dutch dairy operations. Industry-specific forecast inputs included Nordic pulp mill output projections and EU cohesion fund disbursement schedules for Eastern European feed mill modernization.
Sensitivities concentrate around EFSA residue assessment timeline extensions, Nordic pulp mill capacity constraints, and EU Feed Hygiene Regulation revision scopes. Forecasts reflect documented assumptions regarding regulatory implementation pacing and raw material supply continuity. Cross-checking against Cefic chemical industry production benchmarks and national feed association consumption surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
US Home and Garden Fungicides Market
Agricultural Chemicals
Triazole Fungicides Market
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
US Fungicide Market
Agricultural Chemicals
CBD Plant Nutrients Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market