
 North America Feed Phytogenics Market | 2026-2036
North America Feed Phytogenics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Phytogenics Market Analytics
Subscription-based technical advisory services for phytogenic formulation is pivoting how ingredient suppliers monetize expertise beyond physical product sales. DSM-Firmenich leverages its combined nutrition and fragrance science heritage to anchor premium essential oil positioning in poultry applications. Cargill, Incorporated sustains broad distribution reach through integrated animal nutrition platforms spanning the United States and Canada. ADM competes on backward integration into botanical raw material sourcing, securing supply chain control over key herb and spice inputs.
Feed phytogenics comprise bioactive compounds derived from herbs, spices, essential oils, and plant extracts, typically standardized for phenolic content, terpenoid profiles, or alkaloid concentrations to deliver consistent antimicrobial, antioxidant, or digestive modulation effects in livestock. Their primary commercial purpose centers on replacing or reducing antibiotic growth promoters while maintaining feed efficiency and gut health performance in intensive animal production systems. Essential oils lead product type demand due to concentrated bioactivity and ease of standardization, while poultry dominates end user consumption driven by antibiotic-free certification requirements across major U.S. processing chains. Liquid formulations capture expanding share among integrators seeking automated dosing precision in large-scale feed mills.
The FDA Veterinary Feed Directive and EPA pesticide tolerance frameworks govern phytogenic ingredient approvals and residue monitoring in the United States, while CFIA oversight applies in Canada for novel feed ingredient assessments. These regulatory structures elevate documentation burdens for suppliers but simultaneously accelerate demand for compliant, pre-validated phytogenic solutions among risk-averse livestock operators. Stakeholders must monitor evolving GRAS self-determination pathways and state-level feed labeling requirements as enforcement consistency becomes a commercial differentiator.
Market Dynamics
The FDA Veterinary Feed Directive has permanently altered formulation economics across North American livestock operations, forcing integrators to source validated phytogenic alternatives that satisfy residue monitoring protocols while maintaining feed conversion performance.
Growth Catalysts
- Antibiotic-free certification mandates:Major U.S. poultry processing chains now require documented phytogenic programs, pulling essential oil inclusion rates upward across broiler operations in Georgia, Alabama, and Arkansas.
- CFIA novel feed ingredient pathway:Canada's streamlined assessment framework accelerates commercialization timelines for standardized botanical extracts entering the Canadian market.
- Essential oil standardization technology:Gas chromatography-mass spectrometry profiling now enables batch-to-batch consistency in terpenoid concentrations, reducing performance variability that previously limited adoption.
Market Restraints
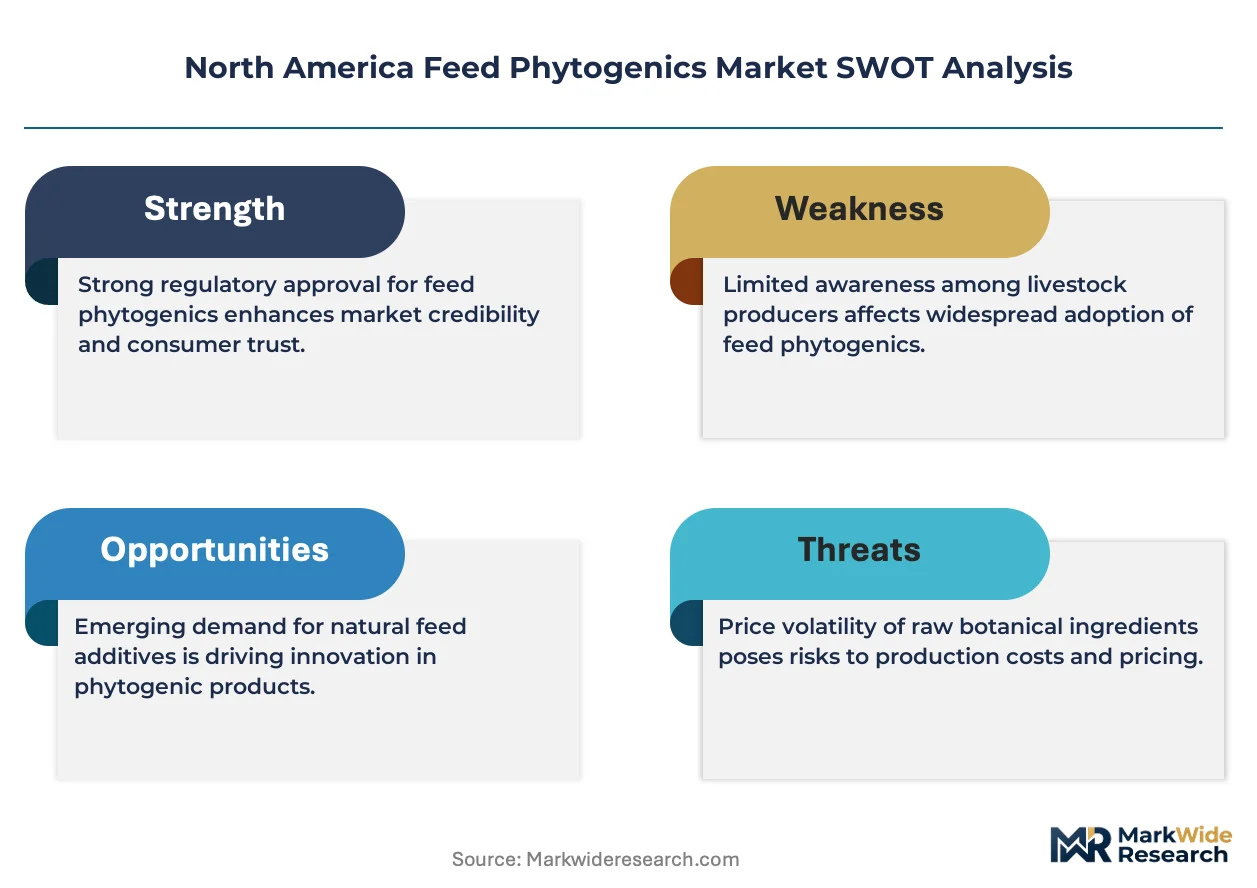
- Botanical raw material volatility:Oregano and thyme harvests concentrate in Mediterranean climates, exposing North American formulators to weather-driven price swings and currency risk.
- EPA pesticide tolerance documentation:Residue monitoring requirements for imported herb and spice inputs create compliance burdens that disqualify smaller suppliers lacking analytical infrastructure.
- Synthetic antioxidant substitution:Butylated hydroxytoluene and ethoxyquin retain cost advantages in swine and ruminant applications where consumer-facing antibiotic-free claims carry less weight.
Strategic Opportunities
- Automated liquid dosing systems:Large-scale feed mills in the Midwestern United States seek precision delivery infrastructure for micro-ingredient inclusion, opening equipment-software-service bundles.
- Subscription formulation advisory:Technical service contracts monetize supplier expertise beyond physical product margins, locking integrators into multi-year optimization partnerships.
- State-level feed labeling harmonization:Inconsistent enforcement across California, Texas, and Iowa creates openings for pre-validated compliance packages that reduce regulatory friction.
Industry Challenges
- Phytochemist talent scarcity:Specialized expertise in plant secondary metabolite extraction and stability engineering concentrates among a handful of academic programs and incumbent suppliers.
- GRAS self-determination documentation:FDA notification pathways demand substantial toxicological and exposure assessment investments that stretch mid-tier ingredient houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Phytogenics Market |
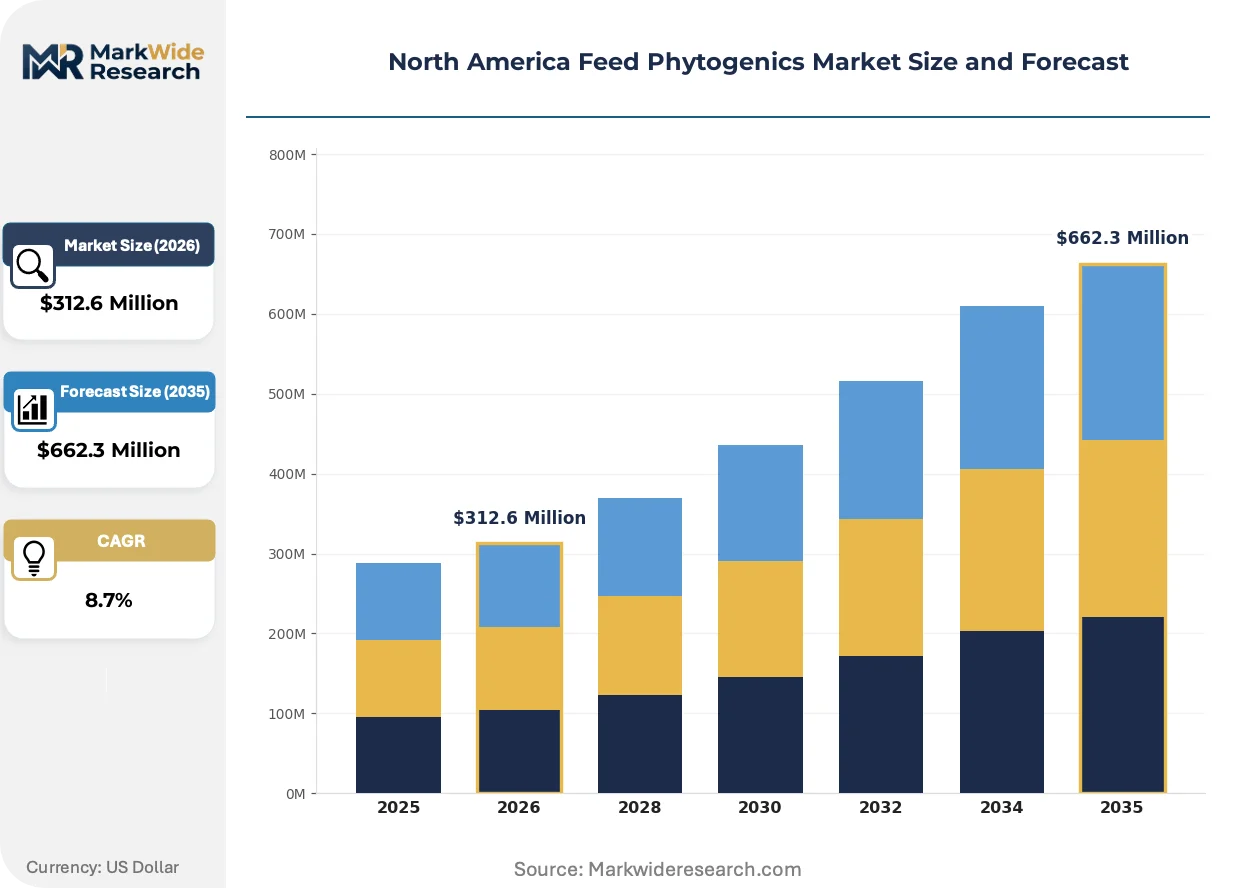
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Herbs, Spices, Plant Extracts End User: Poultry, Ruminants, Swine, Aquaculture Form: Powder, Liquid, Granules, Pellets Application: Growth Promoter, Digestive Health, Immunity Booster, Feed Supplement |
| Companies Covered | DSM-Firmenich, Cargill, Incorporated, ADM, Adisseo, Kemin Industries Inc., Alltech, Nutreco, Natural Remedies, Phytobiotics Futterzusatzstoffe GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Phytogenics Market Evolving Landscape
Formulation science and delivery mechanisms are converging to resolve the historical trade-off between phytogenic bioactivity and manufacturing practicality that constrained earlier adoption waves.
Microencapsulation technology using lipid matrices and spray-dried gum acacia is automating the protection of volatile terpenoids through pelleting temperatures exceeding 85°C. Poultry integrators in the southeastern United States are retrofitting feed mills with precision inclusion systems that meter liquid phytogenics at 50-200 grams per ton. This automation is compressing the performance gap between in-feed application and more labor-intensive water-administered alternatives.
The FDA Veterinary Feed Directive continues tightening documentation requirements for medicated feed alternatives, elevating demand for pre-validated phytogenic portfolios with established safety margins. Feed manufacturers now prioritize suppliers offering complete regulatory dossiers over commodity botanical traders. Poultry operations bear the heaviest compliance burden, driving consolidation toward integrated nutrition platforms with dedicated regulatory affairs functions.
Buyer concentration among top-ten U.S. poultry integrators has compressed supplier negotiation cycles from annual to quarterly review. Technical service contracts now displace transactional spot purchasing, with formulation optimization and on-farm troubleshooting bundled into per-ton pricing. This shift is most visible across the Delmarva Peninsula and Mississippi Delta, where processor-owned feed mills dominate procurement decisions and lock out smaller phytogenic houses lacking dedicated field technical staff.
North America Feed Phytogenics Market Segmentation
Segmentation in feed phytogenics reveals how formulation science, delivery technology, and species-specific regulatory pressures fragment commercial opportunities across North America. Each dimension carries distinct margin profiles and technical barriers that reshape supplier competitive positioning.
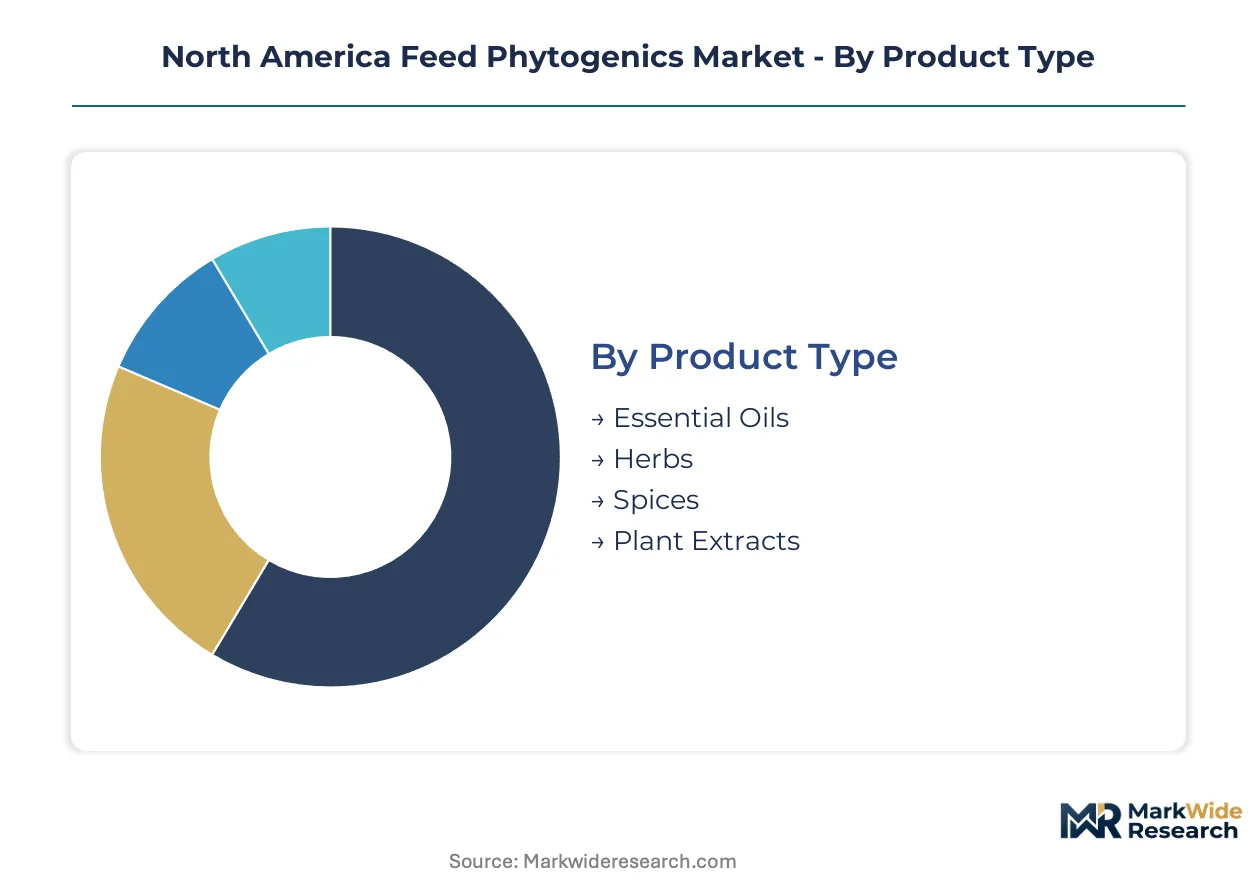
Product Type:
Supply concentration in Mediterranean herb cultivation and essential oil distillation infrastructure concentrates pricing power among integrated processors with captive extraction capacity.
- Essential Oils:Concentrated terpenoid and phenolic compounds standardized through gas chromatography-mass spectrometry profiling. Poultry integrators in Georgia and Arkansas pull demand upward for antibiotic-free programs requiring documented batch-to-batch consistency. Supply volatility in oregano and thyme harvests exposes non-integrated formulators to margin compression.
- Herbs:Dried and milled botanical material retaining whole-plant phytochemical matrices. Ruminant feed manufacturers in the Midwestern United States favor herbs for cost-sensitive applications where volatile oil preservation matters less than bulk fiber contribution. Seasonal harvest windows and drying capacity constraints limit supplier scalability.
- Spices:Pungent botanicals including cinnamon, clove, and capsicum variants selected for antimicrobial potency.
- Plant Extracts:Solvent-extracted or supercritical CO2-concentrated bioactive fractions.
Today's leader: Essential Oils. Tomorrow's challenger: Plant Extracts.
End User:
Species-specific regulatory intensity and consumer-facing certification requirements create divergent willingness-to-pay across livestock categories.
- Poultry:Broiler and layer operations dominate consumption volume, driven by processor mandates for antibiotic-free documentation across the Delmarva Peninsula and Mississippi Delta. FDA Veterinary Feed Directive compliance burdens favor suppliers with pre-validated portfolios and dedicated regulatory affairs staff.
- Swine:Nursery and grow-finish phases utilize phytogenics for gut health modulation, though synthetic antioxidant cost advantages constrain essential oil inclusion rates.
- Ruminants:Beef and dairy applications emphasize methane mitigation and rumen efficiency claims.
- Aquaculture:Salmon and shrimp producers in British Columbia and the Gulf Coast trial phytogenic immunostimulants.
Poultry commands current volume leadership. Aquaculture presents the steepest expansion trajectory as marine certification standards tighten.
Form:
Manufacturing process compatibility and dosing precision requirements segment adoption by feed mill scale and automation maturity.
- Powder:Spray-dried and standardized particulates compatible with conventional batch mixing. Small and mid-sized feed mills across Iowa and Texas rely on powder for operational simplicity.
- Liquid:Oil-based or emulsified formulations enabling automated micro-dosing at 50-200 grams per ton. Large-scale integrators retrofitting Midwestern feed mills drive demand for precision inclusion infrastructure.
- Granules:Agglomerated particles balancing flowability with protection against segregation.
- Pellets:Extruded forms with embedded phytogenics for species requiring complete feed delivery.
Liquid formats gain share fastest among automated operations. Powder retains dominance in legacy mill infrastructure.
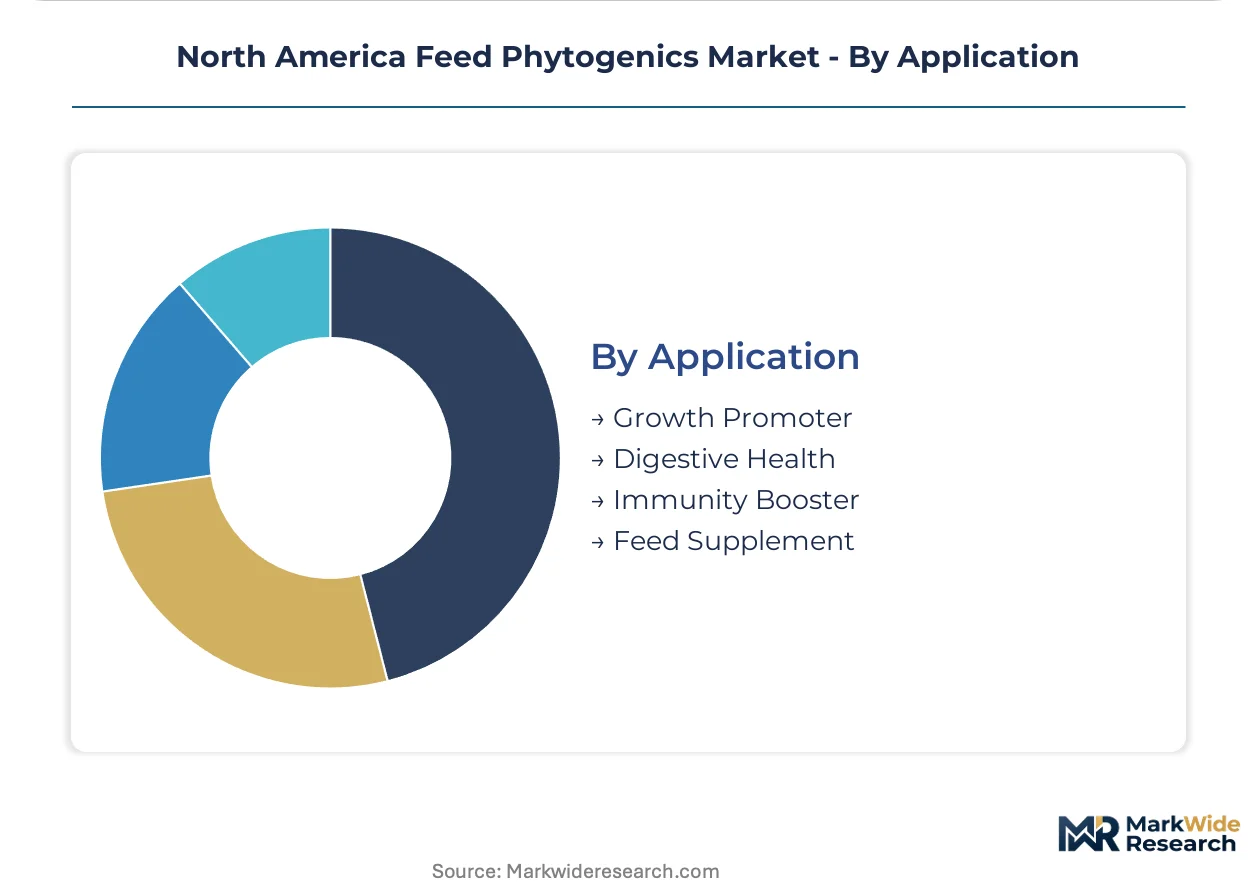
Application:
Functional claim substantiation requirements and residue monitoring protocols differentiate commercial viability across use cases.
- Growth Promoter:Antibiotic growth promoter replacement claims demand rigorous feed conversion documentation. Poultry integrators in Alabama and Georgia require suppliers to demonstrate performance parity with historical AGP benchmarks under CFIA and FDA oversight.
- Digestive Health:Gut microbiome modulation and enteric pathogen inhibition targets. Swine operations prioritize digestive health applications where consumer-facing antibiotic-free claims carry less regulatory weight than in poultry.
- Immunity Booster:Immunostimulant positioning for disease challenge periods.
- Feed Supplement:General nutritional enhancement without specific therapeutic claims.
Growth Promoter applications anchor current revenue. Digestive Health is climbing the fastest as microbiome science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially larger phytogenic consumption volume than Canada, though both markets operate under distinct regulatory frameworks that shape supplier entry strategies and product validation requirements.
United States
Poultry integrators in Georgia, Alabama, and Arkansas drive essential oil demand through antibiotic-free certification mandates from major processing chains. The FDA Veterinary Feed Directive imposes residue monitoring protocols that favor suppliers with pre-validated regulatory dossiers. Automated liquid dosing systems are retrofitting feed mills across the Midwest to enable precision micro-inclusion at 50-200 grams per ton.
Canada
CFIA's streamlined novel feed ingredient assessment framework accelerates commercialization timelines for standardized botanical extracts entering the Canadian market. British Columbia salmon and shrimp producers trial phytogenic immunostimulants as marine certification standards tighten. Prairie Provinces ruminant operations emphasize methane mitigation claims in feed formulation decisions.
Mexico
Poultry production clusters in Jalisco and the Bajío Region source phytogenic additives through cross-border supply chains serving integrated operations. Mexico's national agricultural health authority aligns feed additive regulations with North American trading partner standards to facilitate importation. Guanajuato feed manufacturers increasingly specify documented batch-to-batch consistency in terpenoid concentrations.
North America Feed Phytogenics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated nutrition platforms capturing disproportionate volume in poultry applications while independent botanical houses serve ruminant and swine niches. Three structural tiers have crystallized: global nutrition conglomerates with captive extraction capacity, mid-sized regional formulators with regulatory specialization, and commodity botanical traders competing on raw material sourcing. Consolidation pressure intensifies as buyer concentration among top-ten poultry integrators compresses supplier negotiation cycles from annual to quarterly review. Dominant competitive moves include backward integration into Mediterranean herb cultivation and subscription-based technical service contracts that lock integrators into multi-year optimization partnerships.
Among global nutrition conglomerates, DSM-Firmenich leverages combined nutrition and fragrance science heritage to anchor premium essential oil positioning, while Cargill, Incorporated sustains broad distribution reach through integrated animal nutrition platforms spanning the United States and Canada. ADM competes on upstream control over botanical raw material sourcing, securing supply chain control over key herb and spice inputs.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Cargill, Incorporated |
| ADM |
| Adisseo |
| Kemin Industries Inc. |
| Alltech |
| Nutreco |
| Natural Remedies |
| Phytobiotics Futterzusatzstoffe GmbH |
| Others |
Value Network & Pricing Analysis
Gas chromatography-mass spectrometry standardization technology is compressing batch-to-batch variability costs while simultaneously concentrating extraction capacity among integrated processors with captive analytical infrastructure. This dual effect tightens margins for non-integrated formulators lacking in-house terpenoid profiling capabilities.
Pricing Analysis
Capacity additions in automated liquid dosing infrastructure across the Midwestern United States are reshaping price floors for precision-formulated essential oils. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and commodity botanical tiers separates documented GRAS portfolios from unvalidated raw material traders. Cost compression in the commodity tier is intensifying because Mediterranean herb harvest volatility exposes non-integrated suppliers to margin squeezing. Poultry integrators in Georgia and Arkansas demonstrate the lowest price sensitivity due to antibiotic-free certification mandates, while Midwestern ruminant feed manufacturers exhibit highest sensitivity where synthetic antioxidant alternatives retain cost advantages.
Supply Chain Analysis
Domestic-content preferences embedded in FDA Veterinary Feed Directive documentation requirements are reshaping sourcing patterns toward North American extraction facilities with validated residue monitoring protocols. Mediterranean countries including Turkey, Spain, and Greece anchor oregano and thyme cultivation, while the United States and Canada host growing supercritical CO2 extraction capacity. Supply chain risk centers on weather-driven harvest volatility in Mediterranean climates that feeds into price instability for key terpenoid inputs. Distribution runs through integrated nutrition platforms with captive regulatory affairs functions serving top-ten poultry integrators, displacing commodity botanical traders from premium tier access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between FDA Veterinary Feed Directive compliance costs in the United States and CFIA's streamlined novel feed ingredient pathway in Canada, with the regulatory cost differential favoring Canadian commercialization timelines for standardized botanical extracts.
For Market Incumbents: Cement control over premium tier positioning by deepening backward integration into Mediterranean herb cultivation and locking poultry integrators into multi-year technical service contracts with embedded formulation optimization. Synthetic antioxidant substitution in swine applications represents a named threat requiring defensive capacity allocation toward species-specific digestive health claims.
For New Entrants and Emerging Players: Enter via aquaculture immunostimulant applications in British Columbia and Gulf Coast shrimp operations, where marine certification tightening creates white-space demand absent entrenched incumbent relationships. Precision liquid dosing equipment-software bundles for automated Midwestern feed mills offer the most penetrable go-to-market angle, leveraging technical advisory subscriptions to bypass commodity pricing tiers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized regional formulators with CFIA regulatory specialization but lacking integrated extraction capacity, positioning them as acquisition targets for global nutrition conglomerates seeking North American market access. Long-term viability hinges on phytochemist talent scarcity resolution through academic pipeline investments or captive R&D buildout. Watch for FDA GRAS notification pathway streamlining as the signal indicating accelerated consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mediterranean Cultivation | Captive oregano and thyme supply insulates against weather-driven price volatility. |
| Automated Liquid Dosing Infrastructure Deployment | Precision micro-inclusion at 50-200 grams per ton locks feed mill retrofit demand. |
| CFIA Novel Feed Ingredient Regulatory Investment | Streamlined assessment timelines accelerate Canadian market entry for standardized extracts. |
| Subscription Technical Service Contract Expansion | Multi-year formulation advisory bundles displace transactional spot purchasing among integrators. |
| Microencapsulation Technology Scale-Up | Lipid matrix protection enables pelleting temperature tolerance above 85°C. |
Research Methodology
Multiple input streams — structured interviews with poultry nutrition directors and feed mill operations managers, regulatory affairs specialists at ingredient suppliers, and CFIA novel feed ingredient assessors — were reconciled against FDA Veterinary Feed Directive compliance documentation, EPA pesticide tolerance databases, and trade flow records for Mediterranean herb imports. Bottom-up volume modeling across essential oils, herbs, spices, and plant extracts was cross-validated through top-down expenditure analysis at integrated poultry operations.
Historical capacity utilization patterns at supercritical CO2 extraction facilities were cross-referenced against panel input from botanical raw material procurement leads to anchor growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled encompass product type, end user species, formulation state, and functional application claim, with CAGRs derived from feed conversion performance benchmarking against historical antibiotic growth promoter baselines and regulatory compliance cost indexing.
Inputs from FDA GRAS notification filings and CFIA novel feed ingredient approvals were available through the study window; gaps in real-time Mediterranean harvest yield data introduce uncertainty bands around raw material cost assumptions. Forecasts reflect documented regulatory pathway timelines and integrator procurement cycle compression patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Fungicide Market
Agricultural Chemicals
Bird Repellent Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
North America Agricultural Chemical Packaging Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
South America Feed Antibiotics Market
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
Feed Micronutrients Market
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
Asia-Pacific Swine Feed Premix Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market