
 Grape Fungicides Market | 2026-2036
Grape Fungicides Market Size, Share, and Industry Trends Forecast 2026-2036
Grape Fungicides Market Insights
The EU Green Deal is pivoting vineyard management practices across European wine regions toward reduced chemical residue profiles. BASF SE leverages its R&D pipeline to develop SDHI-based formulations with lower application rates per hectare. Bayer AG anchors its position through biological fungicide platforms targeting organic vineyard certification requirements. Syngenta AG competes on resistance management programs that rotate chemistries across growing seasons.
Grape fungicides comprise synthetic and biological active ingredients formulated to prevent or eradicate fungal pathogens including Plasmopara viticola and Erysiphe necator, typically applied at 7-14 day intervals during vulnerable phenological stages. Systemic fungicides penetrate plant tissue to protect new growth, while contact fungicides form protective surface barriers. Biological fungicides derived from Bacillus subtilis and Trichoderma species represent the fastest-expanding product type as organic vineyard acreage expands. Foliar spray dominates application method selection due to precision targeting and established equipment infrastructure across mature wine regions.
EMA residue limits and REACH chemical authorization requirements shape active ingredient availability across European vineyard markets, while EPA tolerances govern import compliance for treated grapes entering United States distribution channels. France's ANSM coordinates with EFSA on ecotoxicology assessments that delay or accelerate product registrations. Stakeholders must monitor evolving MRL harmonization between EU and third-country trade partners to anticipate competitive displacement of conventional chemistries.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing registration timelines for biological fungicides while tightening residue limits on conventional chemistries, forcing vineyard operators across Mediterranean wine regions to recalibrate procurement portfolios toward lower-toxicity alternatives.
Growth Catalysts
- REACH chemical authorization:ECHA's streamlined data requirements for microbial-based actives are accelerating biological fungicide market entry across European vineyard belts.
- Organic vineyard acreage expansion:Certification demand from Bordeaux, Tuscany, and Rioja appellations is pulling biological formulations into premium wine supply chains.
- Resistance management protocols:Rotational programs combining SDHI, QoI, and biological modes of action are extending product lifecycle viability for vineyard managers.
Market Restraints
- Active ingredient supply concentration:Chinese manufacturers dominate technical-grade azole and strobilurin production, exposing formulators to input cost volatility and trade friction.
- Biological formulation stability:Bacillus subtilis-based products require cold-chain logistics that vineyard cooperatives in southern Spain and Greece lack.
- EMA residue harmonization delays:Divergent MRL negotiations with third-country trade partners are blocking treated grape exports from certain EU regions.
Strategic Opportunities
- Precision application technology:Drone-mounted variable-rate sprayers are automating fungicide deposition in steep-slope vineyards across Portugal's Douro Valley.
- Soil microbiome inoculants:Trichoderma-based root treatments are opening a preventive channel distinct from foliar spray dominance.
- Carbon credit certification:Biological fungicide adoption is qualifying vineyards for EU agricultural carbon offset programs.
Industry Challenges
- Field diagnostics skill gaps:Pathogen identification and resistance monitoring require agronomist training that estate wineries struggle to staff.
- Application equipment retrofit costs:Biological fungicide compatibility demands stainless steel tank and nozzle upgrades for older sprayer fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grape Fungicides Market |
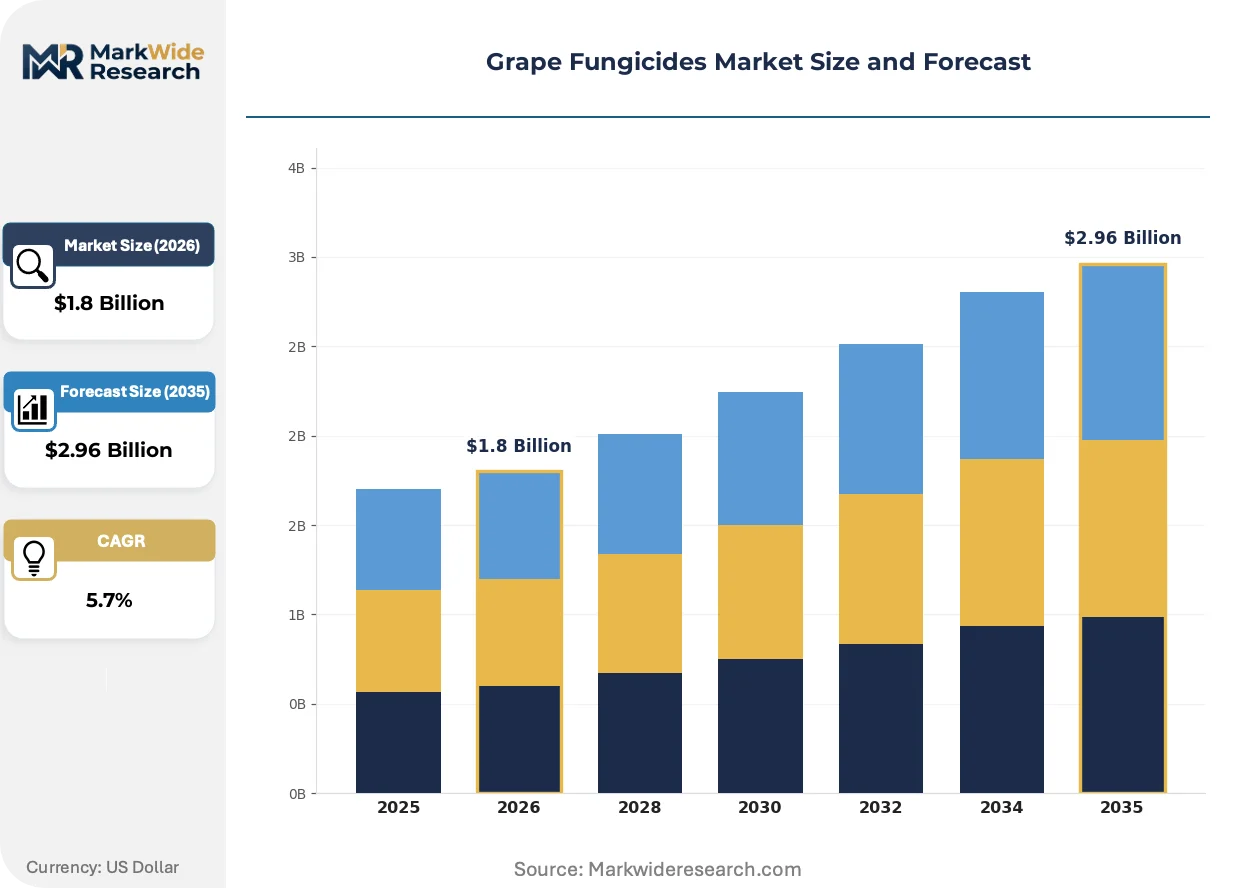
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Fungicides, Systemic Fungicides, Biological Fungicides, Combination Fungicides Application Method: Foliar Spray, Soil Application, Seed Treatment, Granular Application End User: Commercial Growers, Research Institutions, Home Gardeners, Vineyards Formulation Type: Liquid, Powder, Granule, Emulsifiable Concentrate |
| Companies Covered | BASF SE, Bayer AG, Syngenta AG, FMC Corporation, Corteva Agriscience, UPL Ltd., Nufarm Limited, Sumitomo Chemical Co., Ltd., Adama Agricultural Solutions Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grape Fungicides Market Trends and Innovations
Digital vineyard management platforms are converging with biological fungicide development pipelines, creating integrated disease prediction systems that trigger precision interventions before pathogen establishment.
RNA interference fungicides are automating target-specific gene silencing in Plasmopara viticola populations, eliminating off-target effects that constrain conventional chemistry use near watercourses. Champagne houses and premium Rioja estates are piloting these formulations under regulatory derogations. The technology is compressing application frequency from 10-14 day cycles to season-long protection with two treatments.
France's ANSM coordination with EFSA on ecotoxicology data requirements is extending review timelines for novel synthetic actives while fast-tracking microbial derivatives. Vineyard operators in Languedoc and Provence are responding by accelerating biological product trials. The regulatory asymmetry is reallocating R&D investment toward fermentation-derived and plant-extract formulations.
Cooperative procurement consortia are consolidating fungicide purchasing across smallholder vineyard networks in Italy's Veneto and Piedmont regions. These aggregators negotiate volume-based pricing and technical support packages that individual estates cannot secure. The model is displacing direct manufacturer relationships and concentrating distributor influence in regional supply chains.
Grape Fungicides Market Segmentation
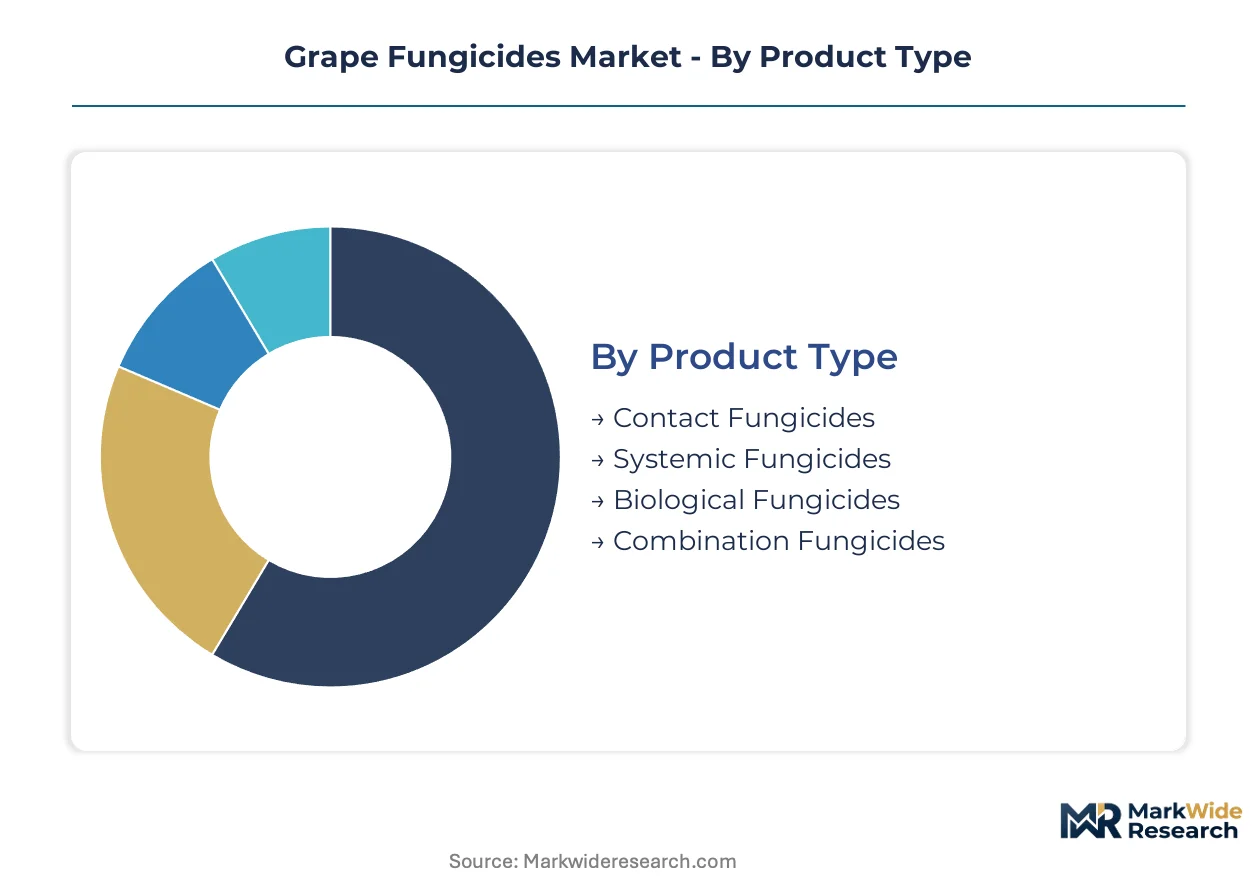
Grape fungicide procurement varies sharply by operational scale and regulatory exposure. Vineyard managers segment their portfolios across chemistry type, application infrastructure, and certification requirements rather than treating fungicides as interchangeable inputs.
Product Type:
Supply concentration in technical-grade azole and strobilurin production shapes procurement risk profiles across formulation categories.
- Contact Fungicides:Sulfur and copper-based formulations form protective surface barriers without plant penetration. Bordeaux châteaux and Rioja cooperatives rely on these for resistance management rotations, though residue limits under EFSA guidelines restrict pre-harvest intervals.
- Systemic Fungicides:Azole, SDHI, and QoI chemistries penetrate vine tissue to protect emergent growth. Demand concentrates in France's Champagne and Burgundy regions where dense planting accelerates disease pressure during vulnerable phenological stages.
- Biological Fungicides:Bacillus subtilis and Trichoderma-derived products are climbing the fastest as organic vineyard acreage expands across Tuscany and Languedoc.
- Combination Fungicides:Pre-mixed formulations blend contact and systemic modes for simplified spray programs. Estate wineries in Portugal's Douro Valley favor these for labor efficiency on steep slopes.
Today's leader: Systemic Fungicides. Tomorrow's challenger: Biological Fungicides.
Application Method:
Equipment infrastructure investments lock vineyard operators into specific application modalities for multiple growing seasons.
- Foliar Spray:Airblast and drone-mounted sprayers deliver precision targeting to canopy surfaces. This method dominates Mediterranean vineyard belts where established dealer networks support equipment maintenance.
- Soil Application:Drench and drip-irrigation delivery position fungicides at root zones for systemic uptake. Adoption is expanding in California's Central Valley vineyards managing trunk disease complexes.
- Seed Treatment:Rootstock dipping protocols protect young vines during establishment phases. Nurseries in Spain's La Rioja region utilize these for grafted plant material destined for export markets.
- Granular Application:Slow-release formulations reduce application frequency in extensive plantings. Large estate holdings in Australia's Riverina region deploy these for operational cost control.
Foliar Spray retains equipment lock-in. Soil Application is gaining share fastest among replanting programs.
End User:
Procurement volume and technical support requirements diverge sharply across operator categories.
- Commercial Growers:Table grape producers in California's San Joaquin Valley and Chile's Central Valley purchase fungicides through distributor programs with volume-based pricing and resistance monitoring services.
- Vineyards:Wine-focused operations in France, Italy, and Spain prioritize residue profile management for export compliance, driving biological formulation trials.
- Research Institutions:INRA and UC Davis field stations evaluate novel actives under controlled conditions, influencing regional extension recommendations.
- Home Gardeners:Small-scale hobby vineyards access fungicides through garden retail channels with simplified application instructions.
Commercial Growers anchor volume procurement. Vineyards are shifting fastest toward biological alternatives.
Formulation Type:
Storage stability and mixing compatibility determine formulation selection for specific vineyard operations.
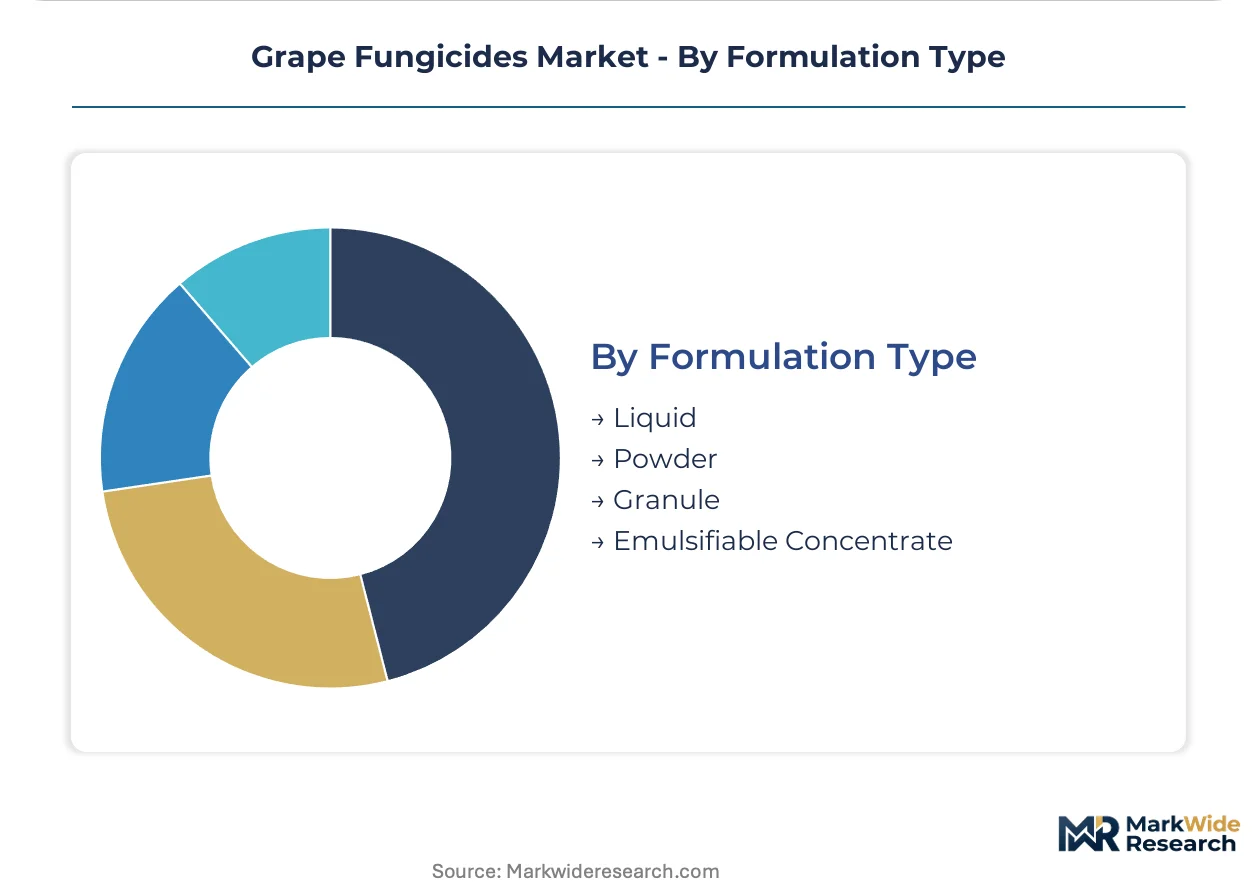
- Liquid:Suspension concentrates and soluble liquids dominate commercial applications for rapid tank mixing and uniform coverage. Cold storage requirements for biological liquids constrain adoption in southern Spain and Greece.
- Emulsifiable Concentrate:Oil-based carriers enhance penetration of systemic actives. These formulations face regulatory pressure under REACH authorization reviews for solvent content.
- Powder:Wettable powders offer extended shelf stability for cooperatives with variable procurement cycles. Dust exposure concerns during handling limit uptake in estate wineries.
- Granule:Dry formulations enable precise metering in mechanical spreaders for soil-directed applications. Adoption concentrates in large-scale Australian and Argentine operations.
Liquid formulations command current infrastructure alignment. Emulsifiable Concentrate faces regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vineyard fungicide use originated in nineteenth-century French viticulture with Bordeaux mixture, spreading through Mediterranean wine belts and New World plantings as commercial grape production industrialized.
France
Champagne houses and Burgundy estates drive procurement of SDHI-based systemic formulations for dense canopy management. ANSM coordinates with EFSA on residue limit harmonization, accelerating biological product trials in Languedoc and Provence. The Bordeaux châteaux cluster anchors resistance management protocols combining copper rotations with novel microbial actives.
Italy
Tuscany's organic certification surge pulls Bacillus subtilis formulations into premium supply chains. EU Green Deal Farm to Fork implementation tightens conventional chemistry windows across Veneto and Piedmont. Cooperative procurement consortia in these northern regions consolidate distributor influence through volume-based technical support packages.
Spain
Rioja cooperatives and Catalonian estates balance export compliance requirements with powdery mildew pressure management. ECHA REACH authorization reviews constrain emulsifiable concentrate availability. Southern regions including Andalusia face cold-chain infrastructure gaps that limit biological fungicide adoption despite acreage expansion.
United States
California's San Joaquin Valley table grape producers anchor commercial volume through distributor resistance monitoring programs. EPA tolerance settings govern import compliance frameworks for treated fruit entering distribution channels. The Central Valley's replanting programs are expanding soil-directed application infrastructure for trunk disease management.
Australia
Riverina region estates deploy granular formulations across extensive holdings for operational cost control. The country's national agricultural chemical regulator coordinates residue harmonization with Asian export markets. New South Wales and Victoria vineyard belts are piloting drone-mounted variable-rate deposition systems on steep slopes.
Grape Fungicides Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the fungicide value chain, with integrated agrochemical conglomerates maintaining captive synthesis capabilities while specialized biological developers outsource fermentation and formulation. The market structure concentrates around six major conglomerates with full R&D-to-distribution pipelines, flanked by regional formulators and microbial technology specialists. Three archetypes dominate: integrated innovators with resistance management platforms, biological specialists pursuing organic certification channels, and generic manufacturers exploiting off-patent azole and strobilurin chemistries. Competitive moves center on biological registration acceleration and precision application technology partnerships.
Within the integrated innovator tier, BASF SE, Bayer AG, and Syngenta AG occupy positions that exemplify divergent strategic responses to regulatory compression. BASF SE anchors the SDHI chemistry vector with lower application rate formulations. Bayer AG represents the biological platform pivot through microbial-derived product pipelines. Syngenta AG sits within resistance management service bundling, rotating chemistries across growing seasons to extend product lifecycle viability.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta AG |
| FMC Corporation |
| Corteva Agriscience |
| UPL Ltd. |
| Nufarm Limited |
| Sumitomo Chemical Co., Ltd. |
| Adama Agricultural Solutions Ltd. |
| Others |
Pricing and Supply Chain Analysis
Cooperative procurement consortia across Italy's Veneto and Piedmont regions negotiate volume-based fungicide pricing that concentrates buyer power against formulator margins. This aggregation model compresses distributor tiers and forces manufacturers to compete on technical service bundling rather than list-price differentiation.
Pricing Analysis
Three-tier pricing structure across premium biological, standard synthetic, and economy generic formulations anchors the grape fungicide market. Price differentiation hinges on organic certification grade and volume procurement scale, with estate wineries in Champagne and Burgundy absorbing premium markups for residue-compliant SDHI formulations. Pricing pressure stems from Chinese azole and strobilurin feedstock volatility that squeezes formulator margins. Commercial table grape growers in California's San Joaquin Valley exhibit highest price sensitivity, while Bordeaux châteaux prioritize performance over unit cost.
Supply Chain Analysis
Direct-to-vineyard technical service channels handle premium estate demand, while cooperative aggregators consolidate smallholder procurement across Mediterranean belts. Technical-grade active ingredient production concentrates in China, India, and Germany, with formulation and packaging distributed through regional hubs in France, Italy, and Spain. Raw material dependencies include azole intermediates, strobilurin precursors, and microbial fermentation substrates. Single-source vulnerability in Chinese strobilurin technical production exposes formulators to trade friction and input cost spikes. Distribution runs through agricultural cooperatives and specialized viticultural dealers with equipment service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
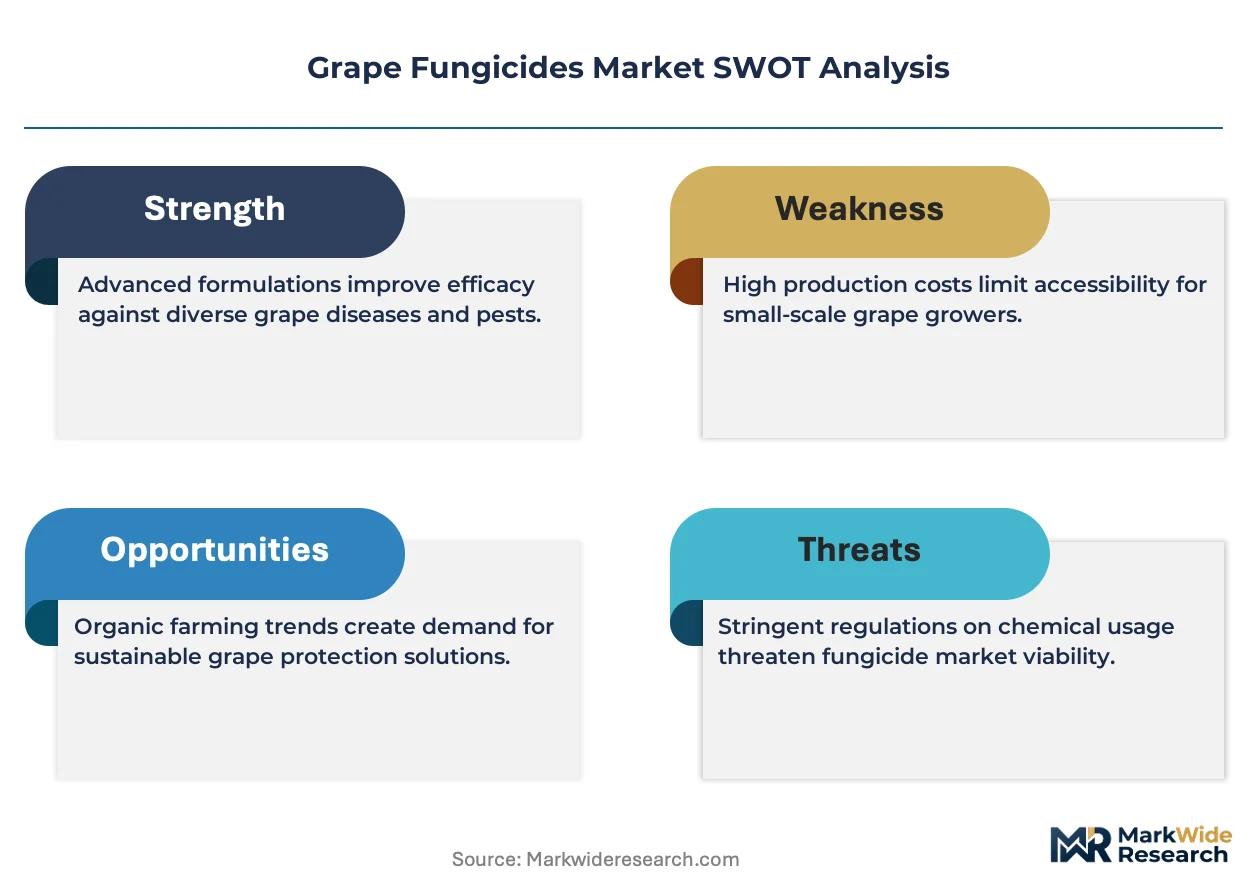
The grape fungicide market functions as a regulatory compounder where EU Green Deal Farm to Fork residue compression accelerates biological product substitution and reshapes procurement portfolios across Mediterranean wine regions.
For Market Incumbents: Anticipate accelerated biological registration timelines by pre-positioning microbial formulation pipelines with ECHA streamlined data packages. EMA residue harmonization delays with third-country trade partners threaten conventional chemistry export volumes, making backward integration into Bacillus subtilis fermentation capacity a defensive priority. Resistance management service bundling extends product lifecycle viability against generic azole displacement.
For New Entrants and Emerging Players: Agricultural drone service providers represent the most accessible channel partnership for precision application technology trials in steep-slope vineyards. Southern Spain and Greece present penetrable geographies where cold-chain infrastructure gaps currently block biological fungicide adoption. A soil microbiome inoculant positioning distinct from foliar spray dominance offers white-space entry with lower equipment retrofit barriers.
For Investors and Strategic Acquirers: Integrated agrochemical conglomerates with captive biological R&D pipelines are the most active acquirers in this space, consolidating microbial technology specialists to fill portfolio gaps. Long-term viability over a multi-decade window hinges on carbon credit certification programs qualifying biological fungicide adoption for EU agricultural offset schemes. Watch for RNA interference fungicide regulatory derogation expansions beyond Champagne and Rioja pilot programs as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Biological Registration Acceleration | ECHA streamlined microbial data requirements compress market entry timelines for fermentation-derived actives. |
| Precision Application Technology Partnership | Drone-mounted variable-rate sprayers automate deposition in Portugal's Douro Valley steep-slope vineyards. |
| Carbon Credit Certification Program | Biological fungicide adoption qualifies vineyards for EU agricultural carbon offset mechanisms. |
| Resistance Management Platform Expansion | Rotational programs combining SDHI, QoI, and biological modes extend product lifecycle viability. |
| Cooperative Procurement Consortium Integration | Volume-based technical service bundling displaces direct manufacturer relationships in Italian northern regions. |
Research Methodology
Direct dialogue with vineyard managers, cooperative procurement officers, agrochemical formulator R&D directors, and ECHA regulatory affairs specialists grounded this analysis in operational realities across Mediterranean wine belts. Secondary validation drew from EFSA residue limit databases, REACH authorization filings, customs trade data for azole and strobilurin imports, and SEC 10-K disclosures from listed agrochemical conglomerates. Bottom-up vineyard acreage and application rate estimates triangulated against top-down formulator revenue segmentation.
Segmented outputs across product type, application method, end user, and formulation type dimensions were generated through the projection horizon. CAGRs were derived from historical procurement volume trajectories adjusted for regulatory compression effects and organic certification adoption curves. Industry-specific forecast inputs included powdery mildew pressure indices, EMA-EU third-country MRL negotiation timelines, and cold-chain infrastructure deployment rates in southern European vineyard belts.
Revisions become necessary when EMA residue harmonization agreements with major trade partners materialize, biological formulation stability breakthroughs eliminate cold-chain dependencies, or RNA interference fungicide regulatory approvals expand beyond derogation pilots. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and organic vineyard acreage conversion rates. Periodic stress-testing of base assumptions against ECHA registration pipeline data and cooperative procurement consolidation trends is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
Tebuconazole Epoxide Market
Crop Protection
Indonesia Fungicide Market
Crop Protection
Isoxaflutole Market
Crop Protection
United States Nematicides Market
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
Vietnam Insecticide Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
North America Acaricides Market
Crop Protection
Global Insecticides Market
Crop Protection
Herbicides Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Europe Nematicide Market
Crop Protection
Latin America Crop Protection Chemicals Market