
 India Fungicide Market | 2026-2036
India Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
India Fungicide Market Insights
Smallholder cooperatives is collapsing as the dominant buyer archetype as commercial horticulture enterprises and contract farming aggregators capture larger volume shares. UPL Limited leverages its pan-India distribution network to sustain direct-to-farmer reach across Maharashtra and Gujarat. Bayer CropScience Limited anchors premium systemic fungicide sales through its breeder seed partnerships. Dhanuka Agritech Ltd competes aggressively on price in the wettable powder segment through regional dealer exclusivity.
Fungicides are crop protection chemicals formulated from active ingredients such as azoles, strobilurins, or biological antagonists that inhibit fungal spore germination, mycelial growth, or toxin production through contact, systemic, or translaminar action. Their primary purpose is to protect yield and quality in food, feed, and fiber crops by preventing or eradicating fungal pathogens that cause diseases like powdery mildew, blast, and rust. Synthetic fungicides still dominate volume offtake but biological fungicides represent the fastest-growing product category as residue-conscious exporters shift procurement specifications. Wettable powders retain cost-sensitive penetration in field crops while suspension concentrates capture margin pools in high-value horticulture applications.
CDSCO regulates fungicide registration under the Insecticides Act, requiring extensive field trial data and toxicology documentation that extends product launch timelines. FSSAI maximum residue limits and state-level agricultural department spraying calendars constrain application windows and active ingredient selection. BIS formulation standards and the central government's PLI scheme for agrochemical manufacturing jointly determine which molecules achieve domestic scale. Stakeholders must monitor how evolving residue protocols in export destination markets interact with domestic regulatory tightening to decide manufacturing and registration priorities.
Market Dynamics
The India Fungicide Market is compressing around residue-compliant formulation capabilities as FSSAI tightens maximum residue limits and EU export protocols force molecule selection at the registration stage.
Growth Catalysts
- Protected Cultivation Expansion:Polyhouse and greenhouse acreage across Maharashtra and Karnataka is accelerating procurement of systemic fungicides for high-value horticulture crops.
- PLI Scheme for Agrochemical Manufacturing:The Indian government's production-linked incentive scheme is reshaping domestic scale economics for technical-grade active ingredient synthesis.
- Biological Fungicide Adoption:Residue-conscious exporters are shifting procurement specifications toward microbial antagonists and botanical extracts for grape and pomegranate consignments.
Market Restraints
- CDSCO Registration Timelines:The Central Drugs Standard Control Organization mandates extensive field trial data and toxicology documentation that extends product launch cycles by 24-36 months.
- Technical-Grade Import Dependence:Domestic manufacturers rely on Chinese and European suppliers for key azole and strobilurin intermediates, exposing margins to currency volatility and supply disruption.
- Generic Substitution Pressure:Patent-expired molecules face rapid price erosion as regional formulators replicate wettable powder and suspension concentrate variants.
Strategic Opportunities
- Contract Farming Aggregator Channel:Direct supply partnerships with organized horticulture enterprises in Gujarat and Andhra Pradesh bypass fragmented dealer networks.
- Drone-Based Application Services:Precision spraying technology is reducing labor costs in rice blast management across Tamil Nadu's Cauvery Delta.
- BIS Formulation Standardization:Bureau of Indian Standards certification for biological fungicides creates quality-based differentiation against unorganized competitors.
Industry Challenges
- Residue Testing Infrastructure Gap:Limited GLP-certified laboratory capacity in western India delays export clearance for grape consignments destined for European markets.
- Dealer Credit Lock-Up:Working capital cycles extend 90-120 days as smallholder farmers depend on post-harvest liquidity to settle agrochemical purchases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Fungicide Market |
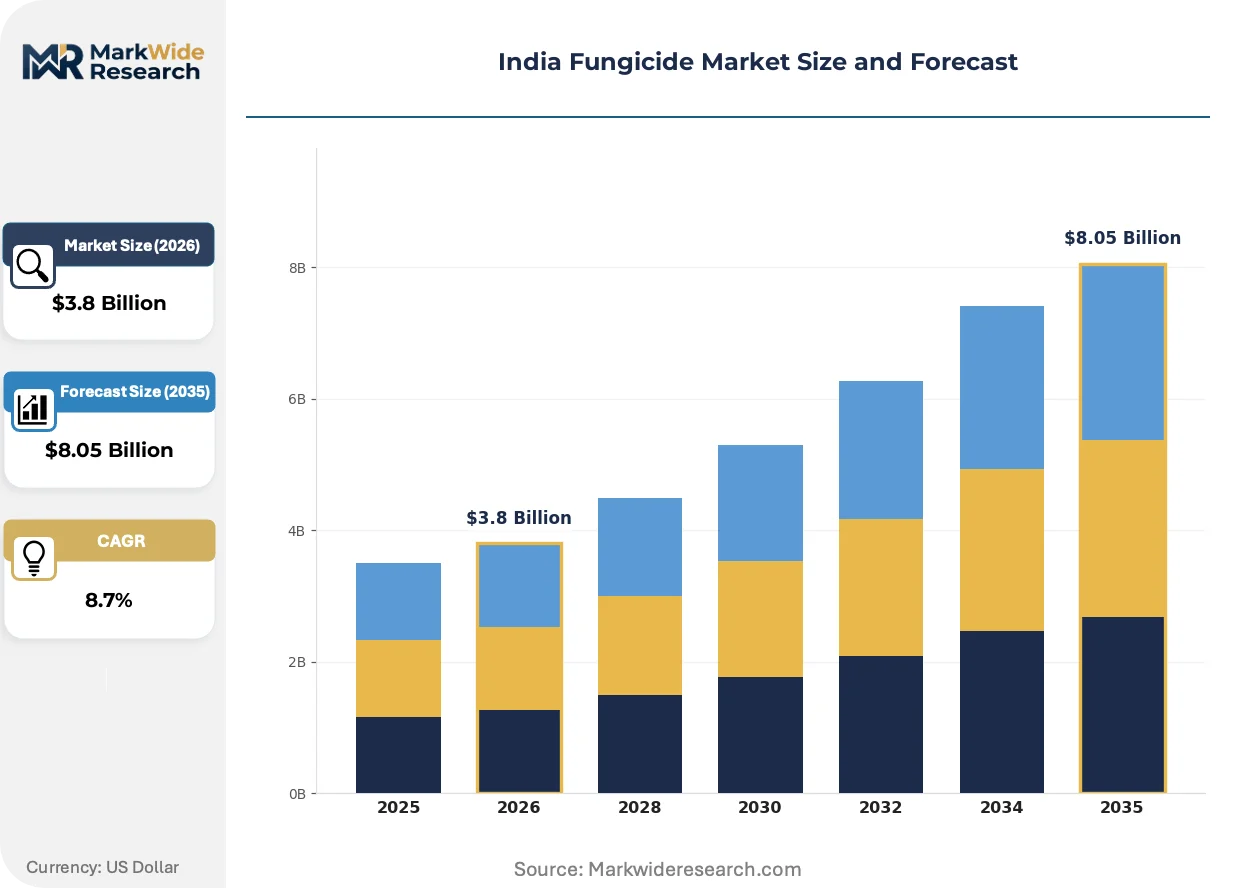
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biological Fungicides, Synthetic Fungicides, Mixtures, Systemic Fungicides Application: Agricultural Crops, Horticultural Crops, Turf Management, Greenhouses Formulation: Wettable Powder, Liquid Formulations, Granules, Suspension Concentrates Distribution Channel: Direct Sales, Online Retail, Agrochemicals Dealers, Distributors |
| Companies Covered | Dhanuka Agritech Ltd, Indofil Industries Limited, UPL Limited, Insecticides India Ltd, PI Industries, Syngenta India Limited, Rallis India Ltd, NACL Industries Ltd, Bayer CropScience Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Fungicide Market Trends and Innovations
Formulation chemistry and application technology are diverging sharply between residue-sensitive export horticulture and cost-driven domestic field crops, creating parallel innovation tracks.
Nano-emulsion delivery systems are fragmenting the conventional suspension concentrate segment by enabling lower active ingredient loading with equivalent field efficacy. Grape and pomegranate growers in Nashik and Sangli are adopting these formulations to meet EU MRL thresholds. The technology is compressing margins on standard EC and SC products while opening premium pricing tiers for registration-compliant alternatives.
FSSAI's 2024 notification revising maximum residue limits for 27 fungicide molecules is forcing reformulation investments across the azole and dithiocarbamate classes. Manufacturers must resubmit stability and efficacy data for existing registrations. The western states of Maharashtra and Gujarat, which account for the bulk of grape and onion exports, are experiencing the most intensive product portfolio restructuring.
Farmer producer organizations are consolidating procurement volumes and negotiating direct supply agreements with technical-grade manufacturers. This channel compression disintermediates traditional multi-tier dealer networks in Karnataka's tomato and chili belts. The shift is most pronounced in districts with active contract farming arrangements for processed food exports.
India Fungicide Market Segmentation
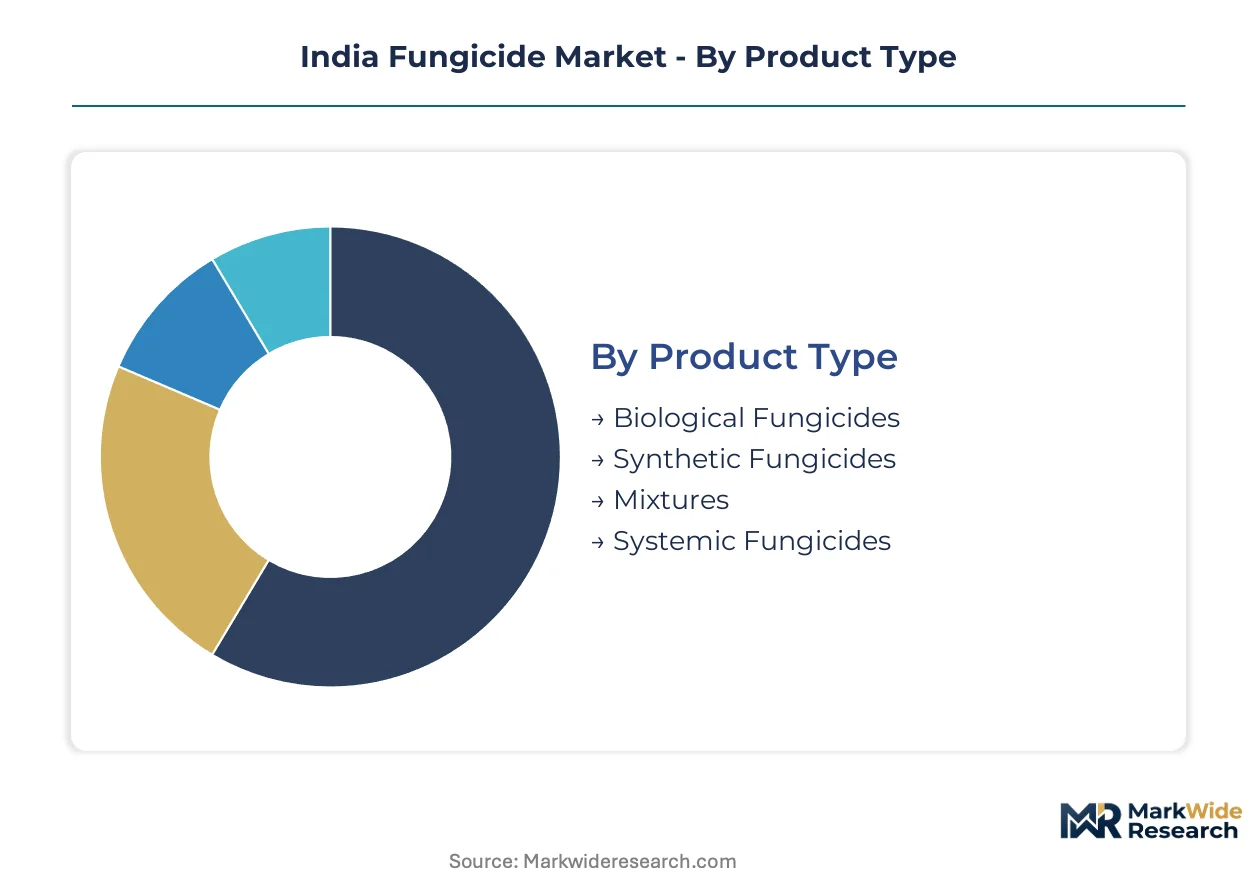
CDSCO registration pathways and FSSAI residue protocols bifurcate fungicide procurement patterns across India's agricultural value chain. Segment boundaries harden where export compliance requirements meet domestic cost constraints.
Product Type:
CDSCO's Insecticides Act mandates distinct toxicology dossiers for biological versus synthetic origin molecules, stretching registration timelines and capital deployment profiles.
- Synthetic Fungicides:Azole, strobilurin, and dithiocarbamate-based chemistries dominate technical-grade manufacturing under PLI scheme incentives. Maharashtra grape growers rely on these molecules for powdery mildew control despite tightening EU MRL scrutiny.
- Biological Fungicides:Microbial antagonists and botanical extracts carry truncated registration pathways through BIS formulation standards. Karnataka pomegranate exporters specify these inputs to satisfy residue-conscious European procurement contracts.
- Systemic Fungicides:Translaminar and xylem-mobile compounds command premium positioning in protected cultivation infrastructure across Nashik and Sangli polyhouse clusters.
- Mixtures:Fixed-ratio combinations of contact and systemic modes address resistance management in Tamil Nadu rice blast belts.
Synthetic fungicides handle the majority of throughput; biological fungicides are expanding most quickly on share.
Application:
Margin pools concentrate where export-facing horticulture enterprises displace fragmented smallholder procurement.
- Horticultural Crops:Grape, pomegranate, and tomato cultivation in Maharashtra and Karnataka drives systemic fungicide absorption. FSSAI's 2024 MRL notification forced active ingredient substitutions across Nashik export belts.
- Agricultural Crops:Rice blast and wheat rust management in Punjab and Haryana sustains wettable powder volumes through dealer credit networks.
- Greenhouses:Polyhouse acreage expansion concentrates demand for low-residue formulations with abbreviated pre-harvest intervals.
- Turf Management:Golf course and sports field maintenance in urban corridors absorbs specialty fungicide imports.
Horticultural crops capture the dominant value share; greenhouse applications are climbing the fastest.
Formulation:
Cost-to-efficacy ratios and application labor availability determine formulation selection across India's heterogeneous farm scales.
- Suspension Concentrates:Nano-emulsion delivery systems enable reduced active ingredient loading for EU MRL compliance. Grape growers in Sangli pay premiums for these registration-aligned alternatives.
- Wettable Powder:Cost-sensitive field crop applications in Gujarat cotton and Andhra Pradesh chili belts sustain this legacy format through regional formulator competition.
- Liquid Formulations:Emulsifiable concentrates and soluble liquids simplify tank-mixing for drone-based application services in Tamil Nadu's Cauvery Delta.
- Granules:Soil-applied formulations address root rot and damping-off in nursery-stage vegetable propagation.
Wettable powder handles the majority of throughput; suspension concentrates are gaining share fastest.
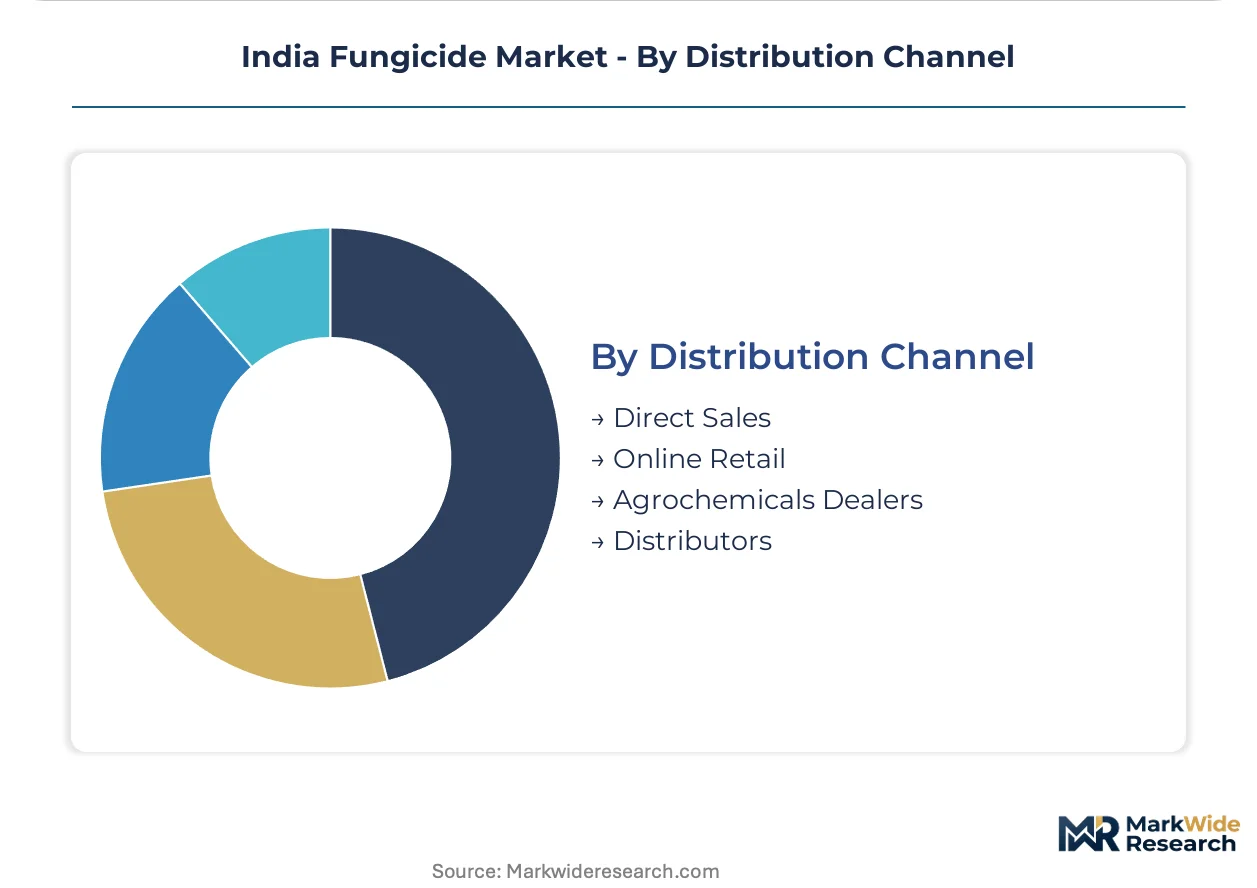
Distribution Channel:
Channel structure fragments where dealer credit lock-ups meet direct supply consolidation by organized buyers.
- Agrochemicals Dealers:Multi-tier networks with 90-120 day working capital cycles dominate smallholder access in Bihar and Uttar Pradesh rice belts. CDSCO-mandated seller licensing constrains unauthorized entrants.
- Direct Sales:Farmer producer organizations in Karnataka's tomato belts negotiate volume contracts that disintermediate traditional dealer markups.
- Distributors:Regional warehousing and credit extension functions concentrate in western India near Gujarat and Maharashtra formulation plants.
- Online Retail:E-commerce penetration remains nascent due to farmer preference for face-to-face technical consultation and credit terms.
Agrochemicals dealers handle the majority of throughput; direct sales channels are expanding most rapidly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grape and pomegranate consignments from Maharashtra and Karnataka flow primarily to European Union markets, where residue compliance requirements dictate molecule selection and formulation chemistry upstream.
Maharashtra
Nashik and Sangli polyhouse clusters drive systemic fungicide absorption for export-oriented table grape cultivation. CDSCO registration timelines stretch 24-36 months for new molecule introductions. Sangli grape growers pay premiums for nano-emulsion formulations that meet EU MRL thresholds.
Karnataka
Bengaluru Rural and Kolar districts anchor protected cultivation expansion for tomato and capsicum exports. FSSAI's 2024 MRL notification forced active ingredient substitutions across contract farming belts. Farmer producer organizations in Kolar negotiate direct supply agreements that bypass traditional dealer networks.
Gujarat
Surat and Navsari districts concentrate wettable powder consumption for cost-sensitive cotton and groundnut field crops. The state's PLI scheme for agrochemical manufacturing attracts technical-grade synthesis investments. Anand formulation plants supply western India through regional warehousing networks.
Tamil Nadu
Thanjavur and Tiruvarur districts in the Cauvery Delta sustain rice blast management through drone-based application services. CDSCO-mandated seller licensing constrains unauthorized agrochemical entrants. Tiruchirappalli dealers extend 90-120 day credit cycles to smallholder paddy growers.
Andhra Pradesh
Guntur and Prakasam chili belts absorb high volumes of contact fungicides for anthracnose control in dryland cultivation. State agricultural department spraying calendars constrain application windows during monsoon periods. Vijayawada distributors coordinate procurement for organized spice processing exporters.
India Fungicide Market Competitive Landscape
Player mix skews toward diversified agrochemical conglomerates with pan-India distribution infrastructure. Market structure concentrates around three strategic tiers: multinational innovators with breeder seed partnerships, domestic formulators with regional dealer exclusivity, and technical-grade manufacturers scaling under PLI incentives. Dominant competitive moves include direct-to-farmer channel compression and residue-compliant formulation investments.
Among domestic agrochemical conglomerates, UPL Limited and Dhanuka Agritech Ltd occupy positions spanning formulation and distribution. UPL exemplifies the pan-India network archetype through sustained direct-to-farmer reach. Dhanuka represents aggressive price competition in legacy wettable powder segments. Bayer CropScience Limited anchors the premium systemic tier through its multinational innovation pipeline.
| Leading Market Players |
|---|
| Dhanuka Agritech Ltd |
| Indofil Industries Limited |
| UPL Limited |
| Insecticides India Ltd |
| PI Industries |
| Syngenta India Limited |
| Rallis India Ltd |
| NACL Industries Ltd |
| Bayer CropScience Limited |
| Others |
Pricing and Supply Chain Analysis
Twenty-four to thirty-six month CDSCO registration timelines compress working capital cycles and amplify pricing power for incumbent technical-grade manufacturers with approved dossiers. Inventory carrying costs for azole and strobilurin intermediates concentrate margin pressure on formulators lacking backward integration into active ingredient synthesis.
Pricing Analysis
Next-generation nano-emulsion formulations command 40-60% premiums over conventional suspension concentrates and emulsifiable concentrates. Three-tier pricing structure across premium, standard, and economy levels separates EU MRL-compliant specialty grades from domestic field crop generics. Price differentiation hinges on FSSAI certification tier and volume scale in procurement contracts. Cost compression in wettable powder generics is intensifying because regional formulators replicate patent-expired molecules. Smallholder cooperatives in Bihar and Uttar Pradesh exhibit highest price sensitivity; export-facing horticulture enterprises in Maharashtra absorb premium tier pricing without volume elasticity.
Supply Chain Analysis
China and Germany anchor technical-grade intermediate manufacturing for azole and strobilurin active ingredients. Domestic formulation draws from imported technicals, indigenous botanical extracts, and microbial culture banks. Single-source vulnerability concentrates in Chinese intermediate supply for strobilurin chemistry. Distribution runs through regional warehousing networks anchored in Gujarat and Maharashtra formulation clusters, with dealer credit extension reaching 90-120 days in eastern and northern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological fungicide substitution threatens synthetic molecule incumbents as FSSAI residue limits tighten and EU export protocols force procurement specification shifts. Incumbents must navigate this substitution defense through formulation chemistry investments and registration portfolio restructuring.
For Market Incumbents: Compound residue-compliant formulation capabilities through nano-emulsion delivery system investments and BIS certification for biological alternatives. Anchor technical-grade synthesis capacity under PLI scheme incentives to reduce import dependence on Chinese intermediates. Prioritize CDSCO registration pipeline for microbial antagonists to defend against biological substitution in Karnataka and Maharashtra export belts.
For New Entrants and Emerging Players: Differentiate on drone-based application service bundling in Tamil Nadu's Cauvery Delta and Andhra Pradesh chili belts. Target farmer producer organization direct supply channels in Karnataka's tomato and capsicum clusters where dealer disintermediation creates white-space. Pursue BIS formulation standardization as quality-based positioning against unorganized regional competitors.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agrochemical conglomerates seeking to monetize non-core fungicide portfolios amid regulatory restructuring costs. Long-term viability centers on residue-compliant formulation capabilities and protected cultivation channel access. Monitor FSSAI MRL notification implementation velocity as inflection indicator for portfolio revaluation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Synthesis | PLI scheme incentives reduce import exposure to Chinese azole and strobilurin intermediate volatility. |
| Nano-Emulsion Formulation Development | Lower active ingredient loading meets EU MRL thresholds for Maharashtra grape export consignments. |
| BIS Biological Fungicide Certification | Quality-based differentiation captures residue-conscious exporter procurement specifications. |
| Farmer Producer Organization Direct Supply | Channel compression bypasses 90-120 day dealer credit lock-ups in Karnataka tomato belts. |
| Drone-Based Application Service Partnership | Precision spraying reduces labor costs in Tamil Nadu rice blast management corridors. |
Research Methodology
Initial hypotheses were tested against primary input from CDSCO registration consultants, FSSAI compliance officers, agrochemical distribution channel heads, and Maharashtra grape export consortium procurement leads and refined through secondary validation. Bottom-up triangulation combined customs import data for technical-grade intermediates, CDSCO registration filings, FSSAI residue limit notifications, and state agricultural department spraying calendars with top-down sectoral demand modeling.
Variance decomposition across synthetic versus biological origin, horticultural versus agricultural crop application, and suspension concentrate versus wettable powder formulation dimensions shaped analytical framework construction. CAGRs derived from segment-level volume and value build-ups incorporating protected cultivation acreage expansion rates, PLI scheme capacity addition timelines, and export destination market residue protocol evolution throughout the forecast period.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme implementation, CDSCO registration timeline compression, or EU MRL protocol stability would require recalibration. Forecasts reflect documented assumptions regarding intermediate import cost trajectories and biological adoption elasticity among export-facing horticulture enterprises. Recalibration cycles align with material shifts in FSSAI notification schedules and EU export protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
China Feed Enzymes Market
Agricultural Chemicals
Global Feed Palatability Enhancers Market
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
CBD Plant Nutrients Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
South America Herbicide Market
Agricultural Chemicals
Europe Feed Pigments Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Neem Extract Market
Agricultural Chemicals
Global Soil Wetting Agents Market