
 France Crop Protection Chemicals Market | 2026-2036
France Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
France Crop Protection Chemicals Market Foresight
Aftermarket service revenue from precision application advisory is narrowing as manufacturers bundle digital tools with chemistry sales. Bayer AG leverages its integrated Crop Science division to sustain bundled digital-agronomy offerings across French wine regions. Syngenta Group anchors its position through biologicals research partnerships with INRAE stations in Montpellier. De Sangosse competes via specialized molluscicide formulations tailored to northwestern France's humid cereal zones.
France crop protection chemicals comprise formulated biocidal and plant-protection products containing active ingredients such as glyphosate, azoxystrobin, or Bacillus thuringiensis, designed to control weeds, fungal pathogens, insect pests, and nematodes in agricultural systems. These products function through contact, systemic, or translaminar modes of action to preserve yield quality and quantity across intensive and specialized farming operations. Herbicides dominate product-type revenue due to perennial weed pressure in winter wheat and maize rotations, while fungicide demand accelerates fastest in viticulture as climate volatility intensifies downy mildew cycles. Liquid formulations lead form-category volumes because tank-mix compatibility reduces application labor costs for large-scale arable cooperatives in Picardy.
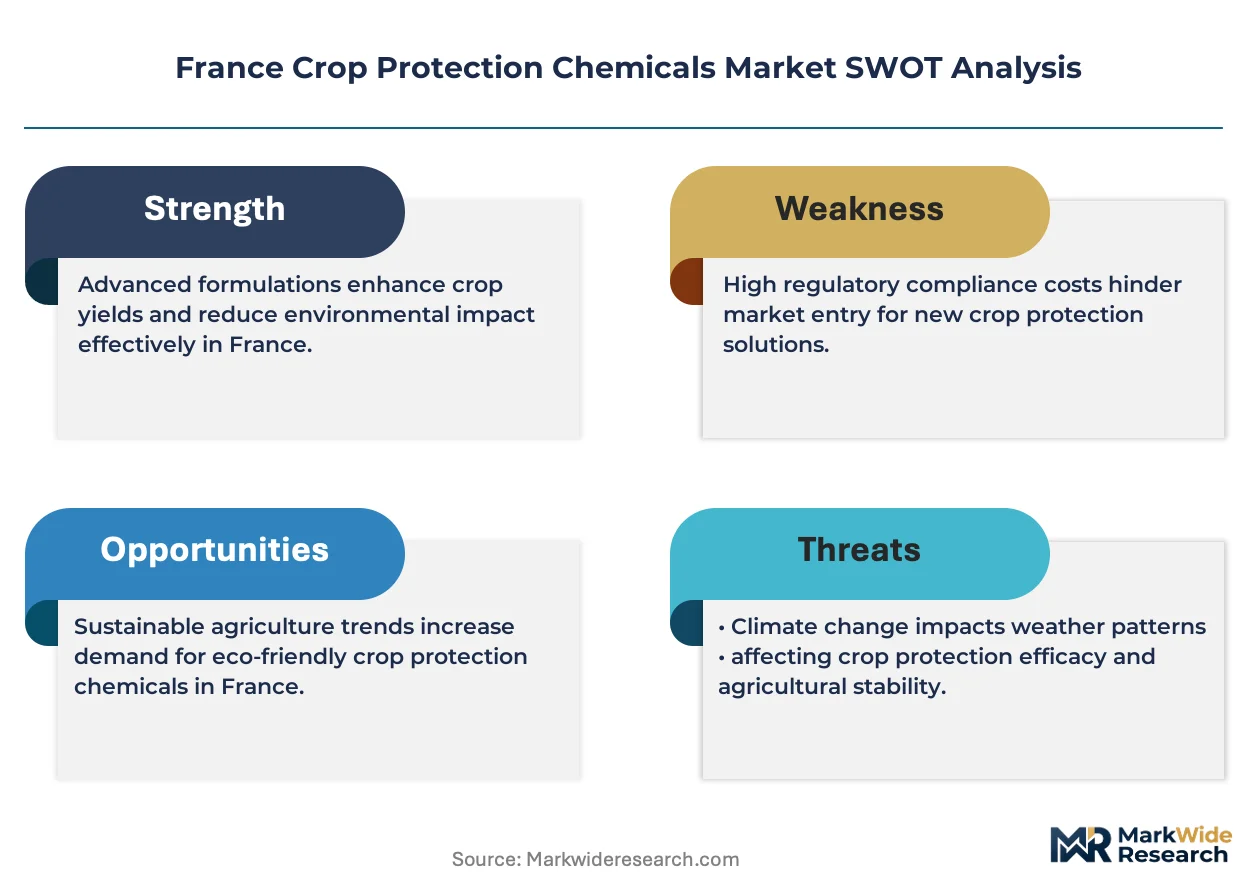
ANSM oversees plant-protection product authorization under EU Regulation 1107/2009, while the EU Green Deal's pesticide reduction targets are forcing reformulation toward low-risk substances and biological alternatives. France's national Ecophyto plan mandates pesticide-use reduction benchmarks that reshape product registration priorities and distributor portfolios. Stakeholders must monitor how the EU's Sustainable Use Regulation recalibrates application equipment standards and buffer-zone requirements.
Market Dynamics
France's crop protection sector faces structural compression from the EU Green Deal's Farm to Fork strategy, which mandates halving chemical pesticide use by 2030 while preserving agricultural output. This regulatory pivot forces reformulation investments and biological substitution across all product categories.
Growth Catalysts
- Ecophyto Plan Mandates:France's national pesticide reduction framework accelerates biologicals registration, creating fast-track pathways for low-risk substances in viticulture and arable farming.
- Climate Volatility in Champagne:Intensified downy mildew pressure drives fungicide demand cycles, with cooperative purchasing groups expanding preventive spray programs across northeastern vineyards.
- Tank-Mix Compatibility Advances:Liquid formulation chemistry reduces application labor costs for Picardy cereal cooperatives, consolidating product preferences among large-scale arable operators.
Market Restraints
- Active Ingredient Supply Concentration:Chinese manufacturers dominate technical-grade glyphosate and azoxystrobin feedstock, exposing French formulators to input cost volatility and shipping disruptions.
- Buffer Zone Expansion:ANSM implementation of EU Sustainable Use Regulation widens untreated margins around watercourses, reducing effective treated acreage per hectare farmed.
- Biological Efficacy Gaps:Bacillus thuringiensis formulations show inconsistent performance against corn borer pressure in Centre-Val de Loire, limiting farmer switching from synthetic insecticides.
Strategic Opportunities
- Grand Est Digital Integration:Precision application advisory bundled with biological products opens service revenue streams among commercial maize and wheat operations.
- INRAE Partnership Channels:Biologicals research collaborations with Montpellier agricultural stations accelerate field-trial data generation, compressing registration timelines for novel microbial agents.
- Northwestern Molluscicide Specialization:Humid cereal zones in Brittany and Normandy present concentrated demand for targeted gastropod control formulations.
Industry Challenges
- Formulation Chemistry Talent Scarcity:EU regulatory complexity requires specialized toxicologists and environmental fate modelers, with French universities producing insufficient graduates for industry demand.
- Equipment Retrofit Costs:Drift-reduction nozzle mandates under Sustainable Use Regulation force cooperatives to replace legacy sprayer fleets, straining capital allocation for smaller farming associations.
- Biological Stability Logistics:Live microbial products require cold-chain distribution infrastructure that depots in Bordeaux and Champagne regions lack, limiting shelf-life assurance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Crop Protection Chemicals Market |
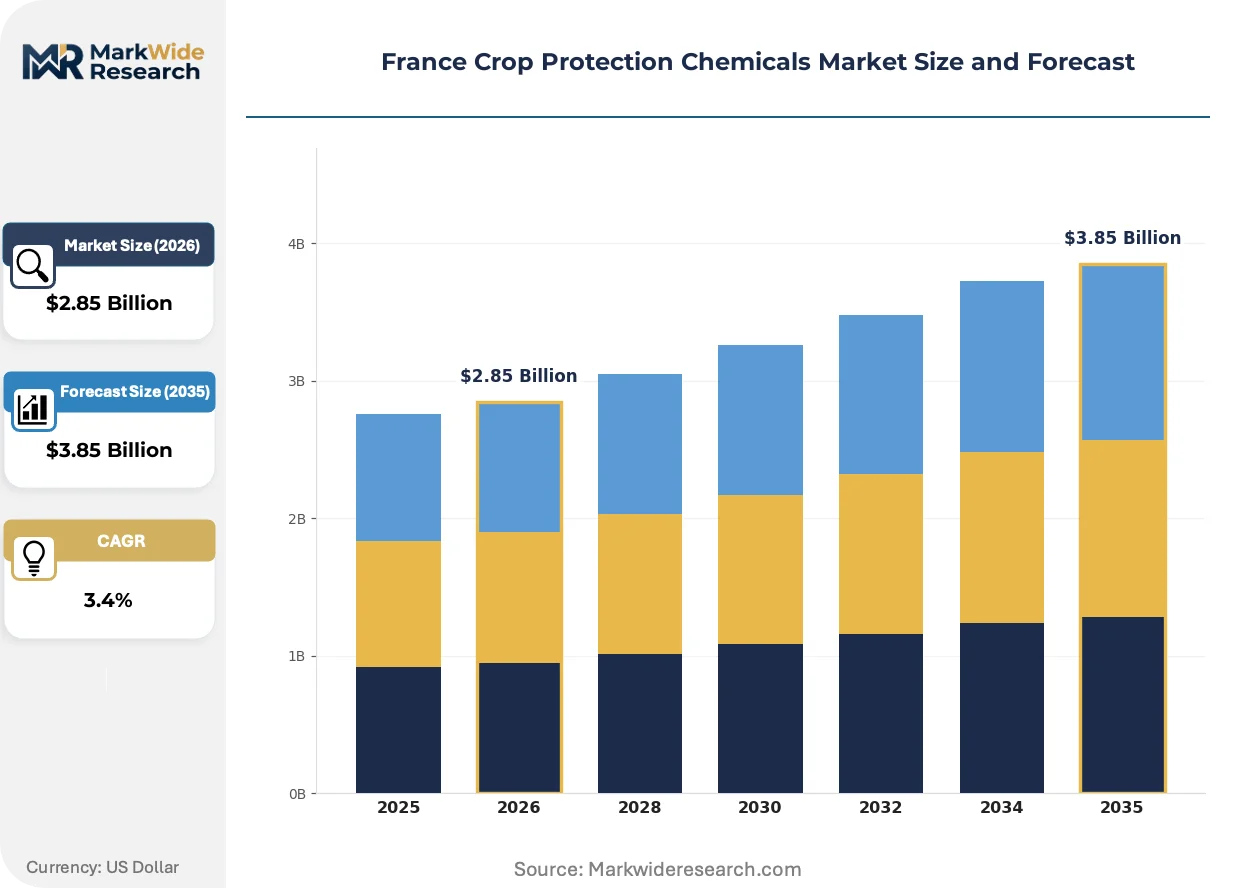
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $3.85 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides, Bactericides Application: Wheat Cultivation, Viticulture, Vegetable Farming, Orchard Care, Field Crops Form: Granules, Liquids, Emulsifiable Concentrates, Wettable Powders, Dusts End User: Agri Cooperatives, Crop Consultants, Organic Farms, Commercial Farmers, Research Institutions |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Corteva Agriscience, Nufarm Ltd, UPL Limited, Sumitomo Chemical, Novozymes, De Sangosse, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Crop Protection Chemicals Market Shifts & Advancements
Biological formulation science and digital agronomy integration are restructuring competitive advantage in French crop protection. Incumbents now compete on data-driven advisory bundling rather than chemistry alone.
RNA interference technology is collapsing the traditional insecticide development timeline. This precision biocontrol mechanism targets specific pest genetics without broad-spectrum collateral damage. Viticulture cooperatives in Champagne are piloting RNAi sprays against grapevine moth larvae. The technology is collapsing conventional pesticide volume requirements per treated hectare.
ANSM enforcement of EU Regulation 1107/2009 low-risk substance criteria is reshaping product registration portfolios. Formulators must demonstrate negligible groundwater leaching and minimal non-target organism toxicity. Herbicide categories face the steepest reformulation burden, with glyphosate alternatives requiring multi-year residue studies.
Cooperative purchasing consolidation is altering distribution channel economics. Large cereal farming groups in Picardy and Centre-Val de Loire now negotiate direct supply contracts, bypassing traditional distributor markups. This concentration compresses margin pools for regional agrochemical retailers while favoring integrated manufacturers with captive distribution assets.
France Crop Protection Chemicals Market Segmentation
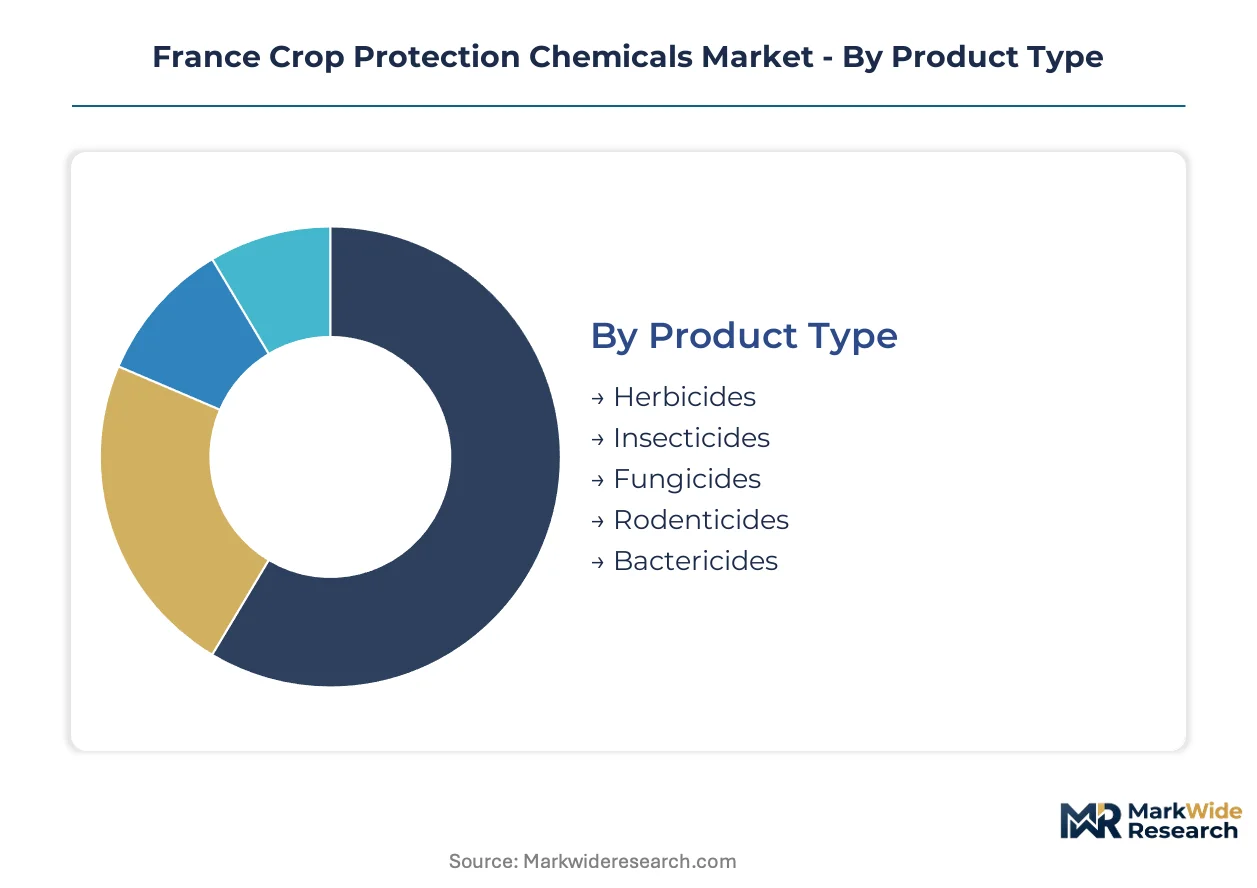
Segmentation in French crop protection reveals distinct demand rhythms across product categories, with reformulation cycles and application timing creating divergent inventory velocities for manufacturers and distributors.
Product Type:
Herbicides turn over fastest due to annual reapplication in cereal rotations, while rodenticides cycle slowest with multi-year baiting intervals in storage facilities.
- Herbicides:Formulations containing glyphosate, mesosulfuron, or pinoxaden target annual and perennial weeds in winter wheat and maize systems. Demand concentrates among commercial farmers in Centre-Val de Loire, where blackgrass resistance drives rotation of chemistries. The Ecophyto plan's reduction mandates force rapid substitution toward low-risk alternatives.
- Fungicides:Azoxystrobin, epoxiconazole, and sulfur-based products control powdery mildew and downy mildew in grape and cereal crops. Viticulture cooperatives in Champagne and Bordeaux expand preventive spray programs as climate volatility compresses infection windows.
- Insecticides:Pyrethroid and neonicotinoid chemistries target aphid and corn borer pressure in arable systems.
- Rodenticides:Anticoagulant and cholecalciferol baits protect stored grain in cooperative silos across Picardy and Grand Est.
- Bactericides:Copper-based and antibiotic formulations address fire blight in pear orchards and bacterial canker in stone fruit.
Herbicides anchor the volume base while fungicides gain share at the steepest rate.
Application:
Cost tiers separate commodity grain applications from premium vineyard inputs, with per-hectare chemistry spend varying by an order of magnitude across these use cases.
- Wheat Cultivation:Winter and spring wheat rotations in Centre-Val de Loire and Grand Est drive herbicide and fungicide bundling. Large cooperatives negotiate direct supply contracts, compressing distributor margins while favoring manufacturers with captive logistics assets.
- Viticulture:Champagne and Bordeaux vineyards require intensive downy mildew and botrytis management with elevated biological substitution rates. The EU Green Deal's Farm to Fork strategy accelerates microbial fungicide adoption here faster than in any other French crop segment.
- Vegetable Farming:Diverse pest pressure in Brittany and Pays de la Loire demands broad-spectrum insecticide and fungicide rotations.
- Orchard Care:Apple and pear operations in Normandy face codling moth and scab cycles requiring precision-timed applications.
- Field Crops:Maize and barley in Picardy rely on tank-mix efficiency for cost control at scale.
Wheat cultivation generates the highest absolute volumes, though viticulture commands the steepest per-hectare value expansion trajectory.
Form:
Volume concentration favors liquid formats compatible with modern sprayer fleets, while specialty applications sustain demand for solid and concentrated alternatives.
- Liquids:Ready-to-use and suspension concentrate formulations dominate cereal cooperative procurement in Picardy due to tank-mix compatibility and reduced labor loading. ANSM drift-reduction mandates favor these low-viscosity products for precision nozzle systems.
- Emulsifiable Concentrates:Oil-in-water systems deliver lipophilic actives across diverse crop canopies. Viticulture operators in Champagne value these formulations for rainfastness during humid growing seasons.
- Granules:Controlled-release matrices suit soil-applied herbicides in maize establishment.
- Wettable Powders:Dry flowables persist in organic farming systems with restricted synthetic options.
- Dusts:Minimal volume remains in seed treatment and greenhouse fumigation niches.
Liquids anchor the volume base while emulsifiable concentrates climb fastest in premium vineyard applications.
End User:
Customer type determines service intensity, with cooperatives demanding bundled advisory while organic farms prioritize certified biological portfolios.
- Agri Cooperatives:Large-scale purchasing groups in Centre-Val de Loire and Grand Est negotiate direct manufacturer contracts. These entities consolidate application equipment investments and precision advisory subscriptions across member farms.
- Commercial Farmers:Individual arable operators in Picardy select products based on per-hectare cost optimization and tank-mix flexibility. Drift-reduction nozzle retrofits under Sustainable Use Regulation strain capital allocation for this segment.
- Crop Consultants:Independent advisors in Bordeaux and Champagne prescribe integrated pest management programs blending synthetic and biological chemistries.
- Organic Farms:Certified operations in Brittany and Provence drive demand for Bacillus thuringiensis and copper-based alternatives.
- Research Institutions:INRAE stations in Montpellier and Versailles conduct field trials accelerating biologicals registration.
Agri cooperatives anchor the volume base while organic farms expand procurement at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crop protection consumption patterns diverge sharply between France's cereal heartlands and its premium vineyard zones, with arable cooperatives prioritizing tank-mix efficiency while viticulture operators absorb per-hectare spends an order of magnitude higher.
Grand Est
Champagne vineyards drive intensive fungicide cycles as climate volatility compresses downy mildew infection windows. ANSM enforces EU Sustainable Use Regulation buffer zones around the Marne River watershed, narrowing effective treated acreage. Cooperative purchasing groups in Reims and Épernay consolidate precision application equipment investments across member estates.
Centre-Val de Loire
Winter wheat and maize rotations generate France's highest herbicide volumes, with blackgrass resistance forcing rapid chemistry rotation. The national Ecophyto plan mandates pesticide-use reduction benchmarks that reshape product registration priorities for Loire Valley formulators. Commercial farming operations around Orléans negotiate direct supply contracts, bypassing traditional distribution channels.
Nouvelle-Aquitaine
Bordeaux viticulture expands biological pesticide adoption faster than any other French crop segment under EU Green Deal Farm to Fork targets. INRAE field stations in Montpellier accelerate microbial fungicide registration through localized trial data. Humid Atlantic conditions intensify botrytis pressure, sustaining preventive spray program demand.
Hauts-de-France
Picardy cereal cooperatives dominate liquid formulation procurement due to tank-mix compatibility and reduced labor loading at scale. Drift-reduction nozzle mandates under Sustainable Use Regulation force legacy sprayer fleet replacement, straining capital allocation for smaller farming associations. Large arable operators consolidate application advisory subscriptions across member farms.
Brittany
Humid northwestern cereal zones sustain concentrated demand for specialized molluscicide formulations targeting gastropod pressure. Organic farming operations in Finistère and Côtes-d'Armor drive Bacillus thuringiensis procurement despite inconsistent performance against corn borer. Cold-chain distribution infrastructure gaps limit live microbial product shelf-life assurance in regional depots.
France Crop Protection Chemicals Market Competitive Landscape
Capability concentration sits with integrated agronomy-chemistry bundlers; scale advantage sits with broad-portfolio multinationals with captive distribution assets. The market structure tiers between global conglomerates with full-seed-to-harvest pipelines and specialized formulators with regional disease expertise. Three archetypes dominate: biologicals innovators with INRAE research partnerships, precision-application bundlers with digital advisory platforms, and niche molluscicide specialists with humid-zone formulation science. Competitive moves concentrate on biologicals registration acceleration and cooperative direct-contract capture.
Within the integrated-multinational tier, Bayer AG anchors bundled digital-agronomy offerings across French wine regions, while Syngenta Group exemplifies biologicals research partnership strategies with Montpellier agricultural stations. De Sangosse occupies a specialized position via targeted gastropod control formulations tailored to northwestern France's humid cereal zones.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Corteva Agriscience |
| Nufarm Ltd |
| UPL Limited |
| Sumitomo Chemical |
| Novozymes |
| De Sangosse |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese glyphosate technical-grade manufacturing is compressing feedstock pricing power for French formulators while simultaneously exposing them to volatility when utilization rates swing. This utilization dynamic forces Bordeaux and Champagne cooperatives into longer contract commitments to secure formulation stability, even as spot markets for biological actives tighten.
Pricing Analysis
Long-term offtake agreements dominate procurement between Picardy cereal cooperatives and integrated manufacturers, insulating buyers from azoxystrobin feedstock volatility while locking in volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates INRAE-certified biological formulations from generic synthetics and commodity generics. Cost compression in standard-tier herbicides is intensifying because blackgrass resistance forces rapid chemistry rotation. Commercial farmers in Centre-Val de Loire exhibit highest price sensitivity due to thin operating margins, while Champagne viticulture cooperatives absorb premium biological pricing with minimal elasticity.
Supply Chain Analysis
Upstream feedstock concentration for technical-grade glyphosate and azoxystrobin centers on Chinese and Indian manufacturers, with German and Swiss firms anchoring proprietary formulation chemistry. French formulators draw from this concentrated base for active ingredients while sourcing adjuvants and packaging materials from regional European suppliers. Single-source vulnerability in Chinese technical-grade production exposes formulators to shipping disruption and tariff exposure. Distribution runs through cooperative purchasing groups in Grand Est and Centre-Val de Loire that consolidate logistics across member farms, bypassing traditional regional agrochemical retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized toxicologists and environmental fate modelers are exiting French university programs faster than industry demand can absorb them, creating a capability bottleneck that will determine competitive survival. This talent scarcity reshapes strategic priorities across all market positions.
For Market Incumbents: Pre-empt biologicals registration acceleration by embedding field-trial teams directly within INRAE Montpellier and Versailles stations, compressing data generation timelines before Ecophyto mandates harden. Acquire cold-chain distribution assets in Brittany and Nouvelle-Aquitaine to resolve live microbial shelf-life failures that currently limit biological penetration. Backward integration into formulation chemistry talent pipelines through endowed university chairs addresses the toxicologist scarcity threatening regulatory submission capacity. For New Entrants and Emerging Players: Northwestern molluscicide specialization in Brittany and Normandy humid cereal zones offers concentrated demand with limited incumbent focus, particularly for gastropod control formulations adapted to Atlantic moisture patterns. INRAE partnership channels provide credibility shortcuts for novel microbial agents, leveraging existing trial infrastructure rather than building proprietary field networks. Direct cooperative contracting in Grand Est bypasses distributor markups that compress margin pools for regional retailers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across biological formulation manufacturing as toll manufacturing networks mature, enabling asset-light entry for specialized players. Acquisition targets should emphasize formulators with captive INRAE data partnerships and established cold-chain logistics in premium vineyard zones. Monitor Ecophyto plan enforcement intensity as the inflection signal; acceleration in reduction benchmarks will displace synthetic incumbents faster than biological supply can backfill.| Strategic Initiative | Industry Significance |
|---|---|
| Biologicals Registration Acceleration | Ecophyto mandates compress approval timelines for low-risk substances in viticulture. |
| Backward Integration into Feedstock | Captive glyphosate technical sourcing insulates formulators from Chinese supply volatility. |
| INRAE Research Partnership | Montpellier field stations generate trial data that shortcuts microbial agent approval pathways. |
| Cold-Chain Distribution Buildout | Brittany depot infrastructure resolves live microbial shelf-life limitations in humid zones. |
| Cooperative Direct Contracting | Grand Est purchasing groups consolidate volume and bypass traditional retailer markups. |
Research Methodology
Cross-validation between ANSM registration databases and INRAE field trial publications anchors the qualitative findings on biologicals efficacy and regulatory trajectory. Primary interviews with formulation chemistry directors, cooperative procurement managers, ANSM regulatory affairs officers, and viticulture technical advisors combined with secondary validation from EU Green Deal implementation reports, Ecophyto plan progress assessments, and customs trade data for technical-grade feedstock imports. Bottom-up triangulation across product-type demand curves and top-down reconciliation against national pesticide sales registries ensures consistency.
Calibration against historical Ecophyto reduction benchmarks and EU Sustainable Use Regulation implementation timelines informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, application crop, formulation form, and end-user archetype, with regional regulatory cluster differentiation for ANSM enforcement intensity. CAGRs derive from curve-fitting across historical sales trajectories and policy-mandated substitution elasticities, incorporating climate volatility indices for downy mildew pressure and blackgrass resistance spread rates.
Practitioners should monitor Ecophyto plan enforcement intensity, EU Sustainable Use Regulation drift-reduction mandate timing, and Chinese feedstock utilization rates for early signals requiring forecast revision. Cross-checking against ANSM quarterly registration approval data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Seed Treatment Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
United States Nematicides Market
Crop Protection
Fumigation Market
Crop Protection
Organic Pesticides Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Pest Control Market
Crop Protection
Europe Fungicide Market
Crop Protection
Indonesia Fungicide Market
Crop Protection
Europe Herbicide Market