
 Global Lab Automation in Genomics Market | 2026-2036
Global Lab Automation in Genomics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lab Automation in Genomics Market Foresight
Aftermarket service revenue is fragmenting across instrument classes as vendors compete for recurring income beyond initial system sales. Thermo Fisher Scientific leverages its installed base of NGS automation platforms to sustain long-term service contracts. Danaher Corporation anchors its genomics portfolio through integrated consumable-instrument bundles that lock in repeat purchases. Illumina Inc competes by controlling proprietary reagent ecosystems tied to its sequencing automation hardware.
Lab automation in genomics encompasses robotic systems, liquid handling workstations, and integrated platforms that execute nucleic acid extraction, library preparation, and sequencing workflows with minimal human intervention, typically operating at throughput rates exceeding hundreds to thousands of samples daily. These systems reduce contamination risk, improve reproducibility, and enable round-the-clock processing in high-volume genetic analysis environments. Robotic liquid handlers occupy the largest product segment due to their deployment across virtually every automated genomics workflow stage. Next-generation sequencing automation platforms represent the fastest-expanding technology category as clinical translation of genomic medicine accelerates. Precision medicine applications concentrate margin pools where pharmaceutical developers and diagnostic laboratories pay premium pricing for validated, regulatory-compliant automation solutions.
The FDA regulates automated genomics instruments as medical devices or IVD components depending on intended clinical use, while the EMA's In Vitro Diagnostic Regulation imposes conformity assessment requirements on systems deployed in European diagnostic settings. ISO 15189 accreditation standards for medical laboratories further shape automation specifications by mandating traceability, quality control integration, and error-handling protocols. Stakeholders must monitor evolving regulatory divergence between jurisdictions to determine whether to pursue unified global platform designs or region-specific compliance variants.
Market Dynamics
Clinical translation of next-generation sequencing workflows is compressing validation timelines and forcing automation vendors to pre-integrate regulatory compliance modules directly into instrument architectures.
Growth Catalysts
- Precision medicine mandates:China's national precision medicine initiative funds high-throughput genomics infrastructure buildouts at domestic biotech firms. This creates sustained demand for automated nucleic acid extraction and library preparation systems.
- ISO 15189 accreditation expansion:Medical laboratories across Europe pursue accreditation requiring traceability, quality control integration, and error-handling protocols that only automated platforms can reliably deliver.
- Sample volume surge:Clinical diagnostic laboratories in the United States face throughput pressures exceeding hundreds of samples daily, necessitating robotic liquid handlers that operate round-the-clock with minimal human intervention.
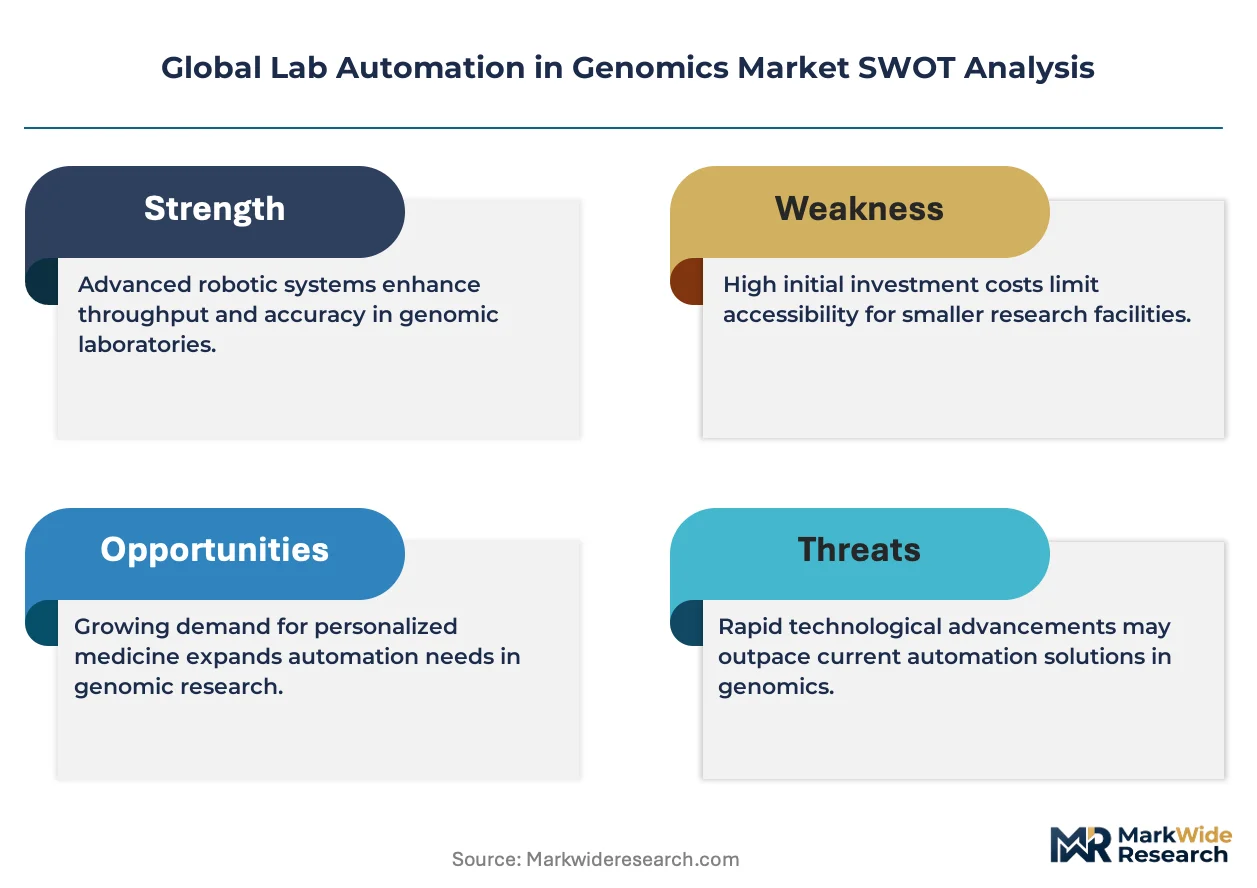
Market Restraints
- Consumable lock-in costs:Proprietary reagent ecosystems tied to specific sequencing automation hardware create recurring expenditure burdens that deter mid-sized laboratory adoption.
- FDA guidance volatility:Evolving FDA guidance on laboratory-developed tests forces repeated instrument revalidation cycles, extending time-to-revenue for automation vendors targeting clinical diagnostic settings.
- Technical integration limits:Legacy laboratory information management systems lack API compatibility with modern automated genomics platforms, requiring costly middleware development.
Strategic Opportunities
- EMA IVDR compliance services:The In Vitro Diagnostic Regulation imposes conformity assessment requirements that create revenue pools for vendors offering bundled validation and documentation support alongside hardware sales.
- Cloud-based remote monitoring:Convergence of automation hardware with predictive analytics platforms enables vendors to offer uptime guarantees and proactive maintenance contracts that expand recurring revenue.
- Pharmaceutical contract research:Drug developers building in-house genomics capabilities represent an underpenetrated buyer segment willing to pay premium pricing for validated, regulatory-compliant automation solutions.
Industry Challenges
- Bioinformatics talent scarcity:Automated genomics platforms require operators with dual competencies in molecular biology and computational pipeline management, a skill combination concentrated at elite academic institutions.
- Cross-platform standardization delays:Absence of universal data formats between competing sequencing automation vendors forces laboratories to maintain redundant workflows, complicating scale-up decisions.
- Capital equipment cycles:Five-to-seven-year depreciation schedules for robotic liquid handlers misalign with three-year technology refresh rates, straining laboratory capital planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lab Automation in Genomics Market |
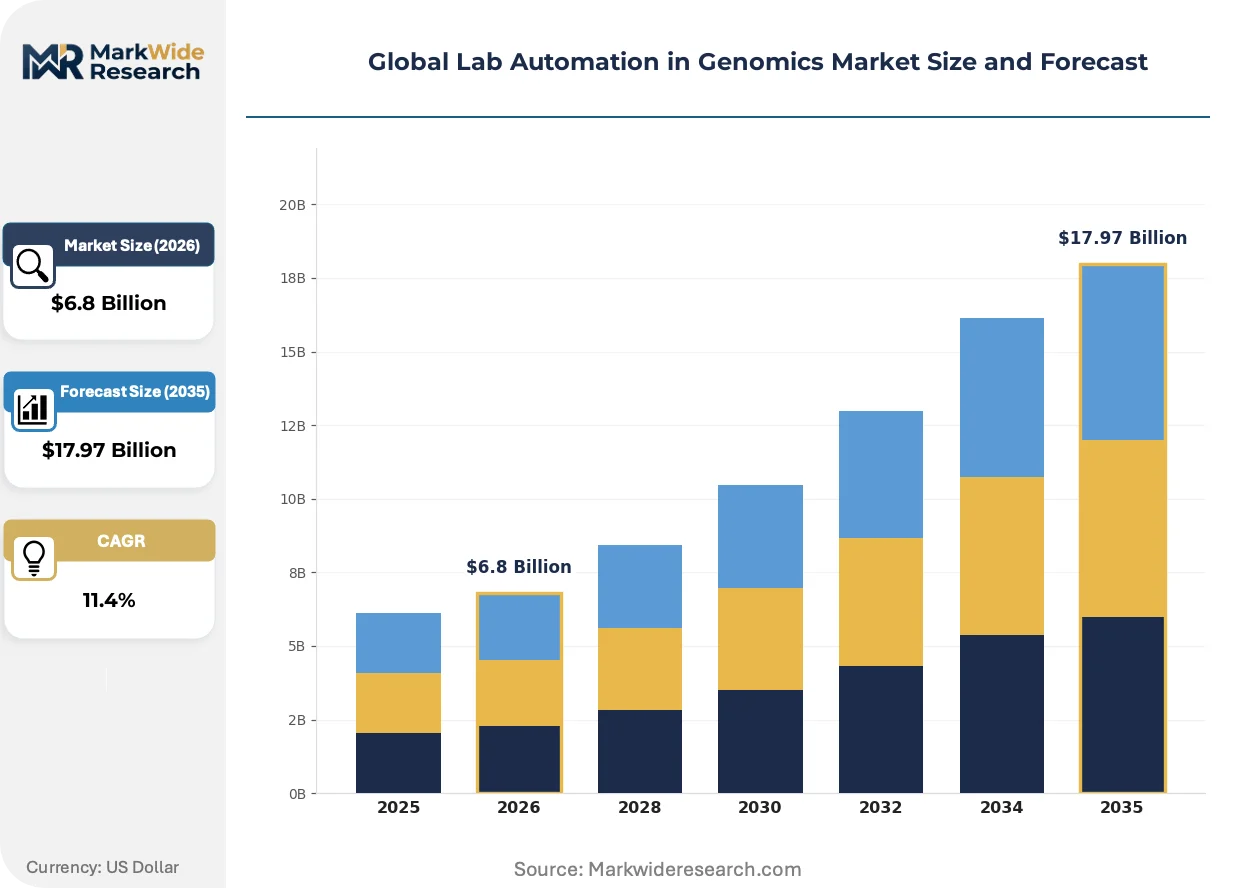
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Liquid Handlers, PCR Automation Systems, Microarray Processors, Automated Sample Prep Instruments, NGS Automation Platforms Technology: Next-Generation Sequencing, Digital PCR, Microfluidics, Optical Mapping, Automated Imaging Application: Genetic Disease Research, Drug Discovery, Precision Medicine, Agricultural Genomics, Forensic Analysis End User: Biotechnology Firms, Academic Research Centers, Contract Research Organizations, Pharmaceutical Developers, Diagnostic Laboratories |
| Companies Covered | Thermo Fisher Scientific Inc, Danaher Corporation, Illumina Inc, F. Hoffmann-La Roche Ltd, Agilent Technologies, PerkinElmer Inc, Siemens Healthineers, Hudson Robotics Inc, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lab Automation in Genomics Market Shifts & Advancements
Artificial intelligence integration is transforming how automated genomics platforms handle error detection, protocol optimization, and predictive maintenance without human oversight.
Digital twin technology is digitizing physical laboratory workflows into virtual replicas that simulate throughput bottlenecks before hardware deployment. Pharmaceutical developers in Germany and Switzerland adopt these simulations to validate automated NGS workflows prior to regulatory submission. This capability compresses commissioning timelines and reduces costly post-installation reconfiguration.
The FDA's evolving guidance on laboratory-developed tests is reshaping instrument validation requirements for systems deployed in United States clinical diagnostic settings. Manufacturers must now embed quality control documentation and traceability features directly into automation software. European vendors pursuing dual-market strategies face divergent compliance architectures that complicate unified platform development.
Service unbundling is fragmenting traditional instrument-consumable-service bundles as buyers demand à la carte maintenance contracts and third-party reagent compatibility. Academic research laboratories in Japan and South Korea lead this behavioral shift, pressuring vendors to open proprietary fluidics protocols. This pattern forces automation suppliers to defend margin positions through software licensing rather than captive consumable sales.
Global Lab Automation in Genomics Market Segmentation
Segmentation in lab automation for genomics reveals how workflow complexity, regulatory burden, and throughput requirements reshape purchasing decisions across product categories and customer types. Understanding these divisions exposes where margin pools concentrate and which technology transitions will drive replacement cycles.
Product Type:
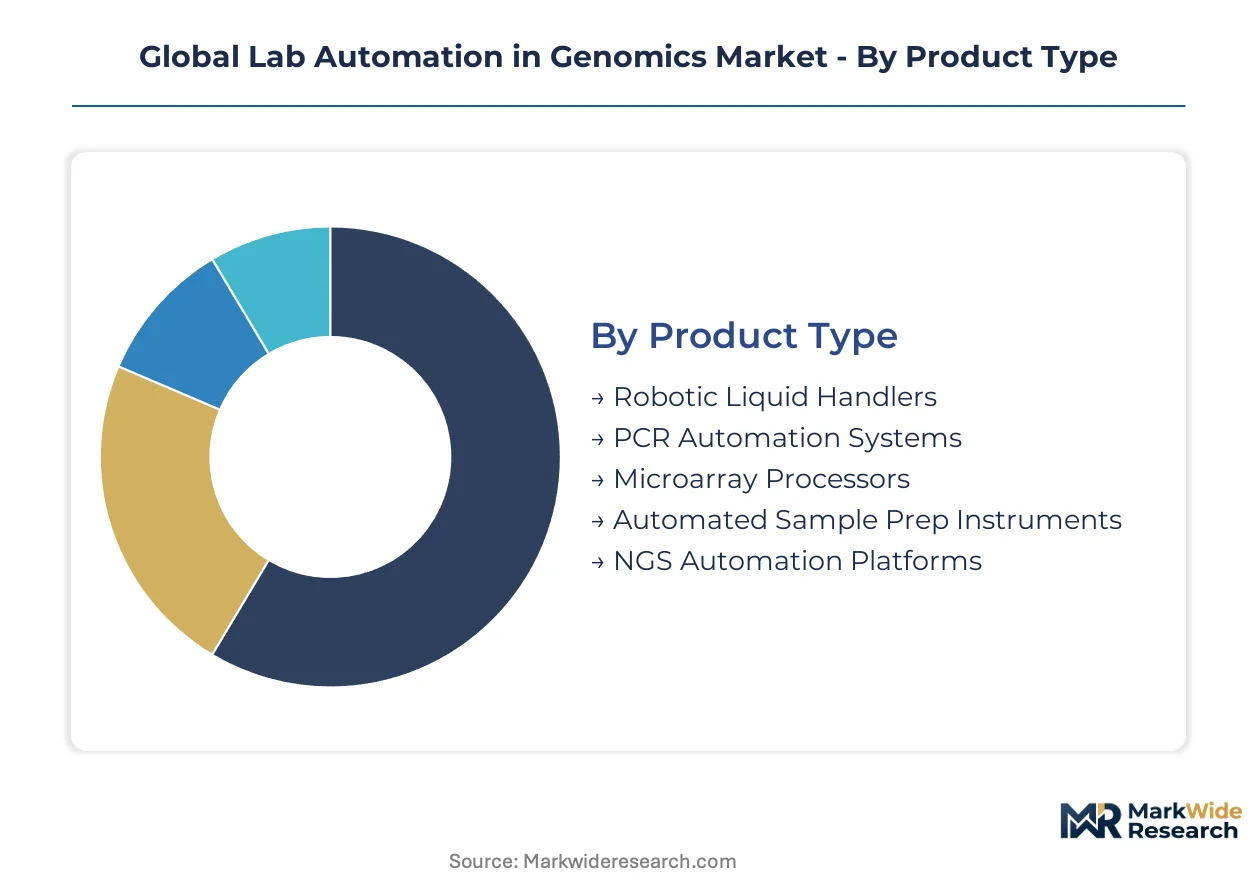
Robotic liquid handlers anchor high-throughput workflows across the entire nucleic acid processing chain from extraction through library normalization.
- Robotic Liquid Handlers:Multi-axis pipetting robots execute repetitive liquid transfers with sub-microliter precision. Demand concentrates at clinical diagnostic laboratories in the United States facing FDA validation requirements for laboratory-developed tests.
- NGS Automation Platforms:Integrated systems orchestrate end-to-end next-generation sequencing workflows including cluster generation and loading. China's domestic biotech firms under national precision medicine initiatives drive fastest adoption.
- PCR Automation Systems:Thermal cycler integration with robotic arms enables walk-away amplification protocols.
- Microarray Processors:Automated hybridization stations manage slide-based genotyping workflows.
- Automated Sample Prep Instruments:Dedicated nucleic acid extraction platforms reduce hands-on time for upstream processing.
Established volume favors robotic liquid handlers; emerging adoption favors NGS automation platforms.
Technology:
Technology selection hinges on analytical sensitivity requirements and the regulatory pathway for intended clinical use.
- Next-Generation Sequencing:Massively parallel sequencing chemistries demand automation for library construction and flow cell loading. Precision medicine applications in pharmaceutical development command premium pricing for validated platforms.
- Digital PCR:Absolute quantification without standard curves suits rare mutation detection. Clinical diagnostic laboratories expanding liquid biopsy programs in Germany and Switzerland favor this technology for its sensitivity.
- Microfluidics:Miniaturized reaction chambers reduce reagent consumption for single-cell genomics.
- Optical Mapping:Long-range structural variation detection requires specialized fluidics automation.
- Automated Imaging:High-content screening integrates with genomics workflows for phenotypic validation.
Next-generation sequencing automation represents the fastest-growing trajectory; digital PCR automation gains share fastest in regulated diagnostic settings.
Application:
Application focus determines the regulatory rigor and throughput specifications that automation vendors must engineer into platform architectures.
- Precision Medicine:Companion diagnostic development and clinical implementation require traceable, error-handling automation compliant with ISO 15189. European medical laboratories pursuing EMA IVDR conformity assessment create sustained demand.
- Drug Discovery:High-throughput target validation and biomarker identification push pharmaceutical developers toward round-the-clock robotic operation.
- Genetic Disease Research:Rare disease cohort studies require flexible automation accommodating variable sample volumes.
- Agricultural Genomics:Crop breeding programs automate marker-assisted selection workflows.
- Forensic Analysis:CODIS database expansion drives standardized DNA processing automation in government laboratories.
Precision medicine commands highest price tiers; drug discovery offers largest volume opportunity.
End User:
End user type shapes procurement patterns from capital equipment cycles to consumable lock-in tolerance.
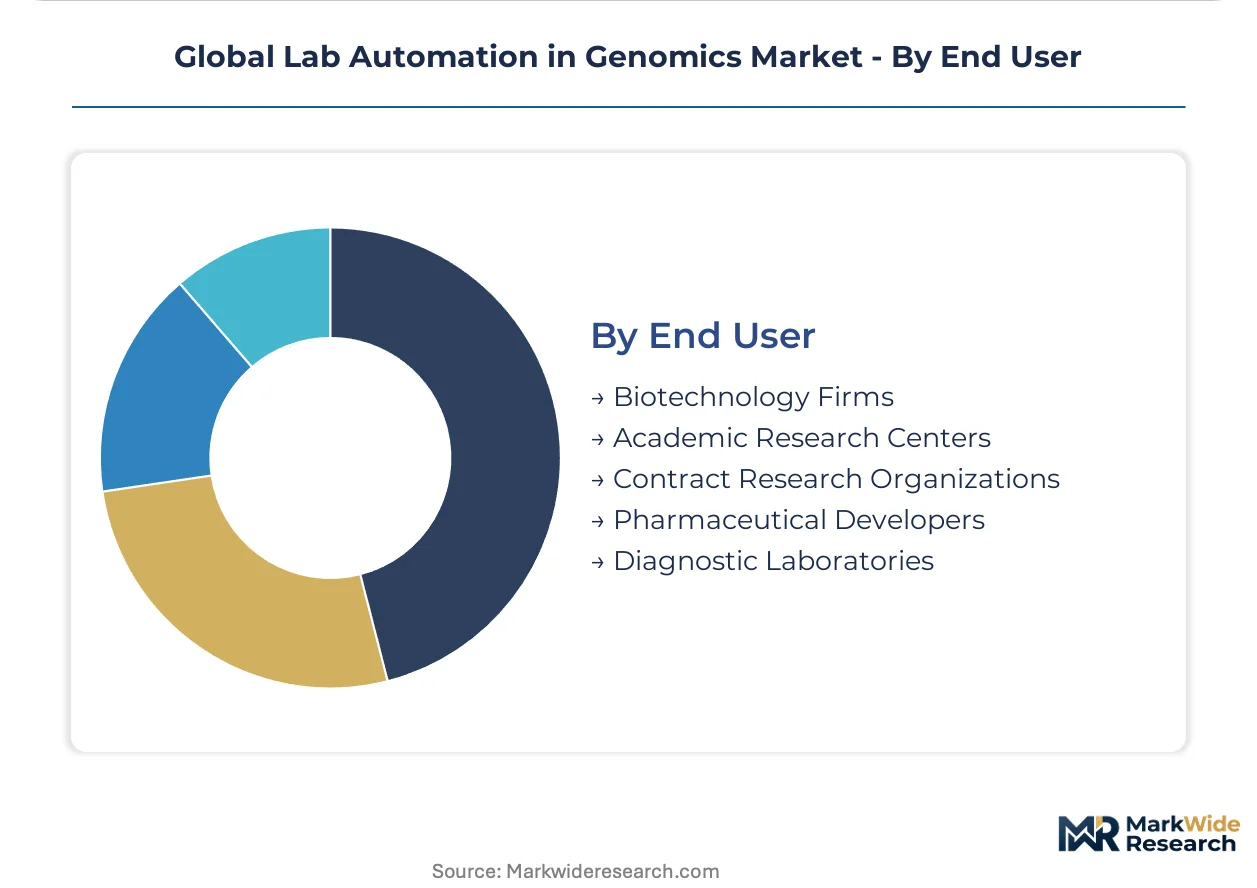
- Diagnostic Laboratories:Clinical translation of genomic testing mandates regulatory-compliant automation with embedded quality control. The FDA's evolving LDT guidance forces these buyers to prioritize pre-validated instrument architectures.
- Pharmaceutical Developers:In-house genomics capabilities at large drug makers represent underpenetrated demand for premium automated platforms.
- Biotechnology Firms:Venture-funded genomics companies balance throughput needs against capital constraints.
- Academic Research Centers:Grant-dependent budgets favor modular automation with third-party reagent flexibility.
- Contract Research Organizations:Service providers demand automation supporting rapid protocol switching across client programs.
Diagnostic laboratories anchor replacement demand; pharmaceutical developers offer steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys lab automation for high-throughput precision medicine infrastructure, while the United States prioritizes FDA-validated clinical diagnostic workflows. Germany concentrates on pharmaceutical-grade compliance systems, and Japan emphasizes modular platforms for academic flexibility. This consumption-mix differential shapes regional vendor strategies and regulatory adaptation requirements.
United States
Clinical diagnostic laboratories drive demand for pre-validated NGS automation platforms that compress time-to-market for laboratory-developed tests. The FDA's evolving LDT guidance forces instrument vendors to embed quality control documentation directly into automation software architectures. The Boston-Cambridge biotech corridor anchors pharmaceutical contract research demand for round-the-clock robotic systems.
China
Domestic biotech firms under the national precision medicine initiative fund high-throughput genomics infrastructure buildouts at unprecedented scale. NMPA regulatory harmonization with international standards accelerates import substitution for automated nucleic acid extraction systems. The Yangtze River Delta biocluster concentrates manufacturing investment for integrated sequencing platforms serving both clinical and research end users.
Germany
Pharmaceutical developers in Baden-Württemberg and Bavaria adopt digital twin simulations to validate automated NGS workflows prior to EMA IVDR submission. The In Vitro Diagnostic Regulation imposes conformity assessment requirements that favor vendors offering bundled validation documentation. The Rhine-Main metropolitan area concentrates contract research organizations demanding rapid protocol-switching automation across client programs.
Switzerland
Precision medicine applications command premium pricing for regulatory-compliant automation solutions validated under Swissmedic oversight. Pharmaceutical headquarters in Basel leverage integrated consumable-instrument bundles to lock in repeat purchases for companion diagnostic development. The country's dual EU-third-country regulatory positioning attracts vendors seeking unified platform architectures serving both European and global markets.
Japan
Academic research centers in the Kanto and Kansai regions lead demand for modular automation with third-party reagent flexibility, pressuring vendors to open proprietary fluidics protocols. METI funding for genomic medicine infrastructure supports adoption of walk-away amplification systems. The Osaka-Kobe biocluster concentrates rare disease cohort studies requiring flexible automation accommodating variable sample volumes.
Global Lab Automation in Genomics Market Competitive Landscape
Capability concentration sits with diversified life science conglomerates; scale advantage sits with sequencing-focused specialists. The market structures around three tiers: integrated platform vendors commanding proprietary reagent ecosystems, modular automation specialists serving open-architecture demand, and regional system integrators addressing price-sensitive academic segments. Dominant competitive moves include consumable-instrument bundling to lock in recurring revenue and cloud-based remote monitoring services that expand service contract attach rates.
Among North American diversified conglomerates, Thermo Fisher Scientific Inc and Danaher Corporation exemplify the integrated platform archetype through installed base leverage and consumable lock-in strategies. Illumina Inc occupies a specialist position controlling proprietary reagent ecosystems tied to sequencing automation hardware. These three anchors represent divergent paths to recurring revenue defense: long-term service contracts, integrated bundles, and captive reagent ecosystems respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Danaher Corporation |
| Illumina Inc |
| F. Hoffmann-La Roche Ltd |
| Agilent Technologies |
| PerkinElmer Inc |
| Siemens Healthineers |
| Hudson Robotics Inc |
| Beckman Coulter |
| Others |
Supply & Pricing Matrix
Undercapacity in precision-grade robotic component manufacturing across Germany and Switzerland is compressing supplier margins while amplifying pricing power for vendors with captive production. This utilization squeeze forces mid-tier automation buyers toward extended service contracts that bundle hardware with multi-year consumable commitments, reshaping how procurement committees evaluate total cost of ownership.
Pricing Analysis
Long-term offtake agreements dominate capital equipment procurement as diagnostic laboratories seek price predictability amid FDA validation uncertainty. Pricing stratifies across FDA-validated premium tiers, ISO 15189-compliant standard tiers, and research-grade economy tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in the economy tier is intensifying because academic buyers increasingly demand third-party reagent compatibility. Contract research organizations exhibit highest price sensitivity due to project-based funding cycles, while pharmaceutical developers show lowest sensitivity given companion diagnostic development timelines.
Supply Chain Analysis
Upstream feedstock for precision motion control systems draws from Japan, Germany, and the United States, with specialized optical sensors and piezoelectric actuators as critical component categories. Supply chain vulnerability centers on single-source dependency for sub-microliter pipetting modules sourced from Swiss and Japanese specialists. Distribution runs through direct field service organizations for clinical diagnostic accounts and distributor networks for academic research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of operators possessing dual competencies in molecular biology and computational pipeline management is constraining platform utilization rates and forcing vendors to embed training services into core offerings. This capability gap rewards suppliers who can deliver validated, walk-away automation with minimal specialist oversight.
For Market Incumbents: Build switching-cost moats through deeper integration of cloud-based remote monitoring with predictive maintenance algorithms that reduce unplanned downtime. Thermo Fisher Scientific and Danaher Corporation should expand validation documentation services for EMA IVDR compliance to capture European diagnostic laboratory replacement cycles. Defend against modular automation specialists by opening selective fluidics protocols to academic buyers in Japan and South Korea.
For New Entrants and Emerging Players: Mid-market biotechnology firms in China's Yangtze River Delta biocluster represent the most penetrable entry point, as these buyers prioritize throughput over brand prestige and show tolerance for emerging vendors with localized service presence. Pharmaceutical contract research divisions in Germany and Switzerland offer secondary white-space, particularly for digital twin-enabled workflow simulation tools. A software-first go-to-market approach—leading with protocol optimization platforms rather than capital hardware—reduces upfront customer commitment and accelerates pilot adoption.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-enabled automation services as vendors shift from hardware-centric to recurring-revenue models. Long-term viability favors platform vendors with installed bases exceeding ten thousand units capable of sustaining consumable lock-in. Acquisition targets should display proprietary reagent ecosystems or validated regulatory compliance modules. The signal to watch is FDA guidance publication velocity on laboratory-developed tests, which will determine revalidation spending requirements and replacement cycle timing. Cross-checking against NMPA harmonization progress in China is advised before commitment-grade decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Remote Monitoring Deployment | Predictive analytics platforms enable uptime guarantees that expand recurring service revenue at Thermo Fisher Scientific and Danaher Corporation. |
| EMA IVDR Compliance Bundling | Validation documentation services capture European diagnostic laboratory demand under conformity assessment requirements. |
| Third-Party Reagent Compatibility Programs | Opening fluidics protocols to academic buyers in Japan and South Korea defends against modular automation specialists. |
| Digital Twin Workflow Simulation | Virtual commissioning tools compress timelines for pharmaceutical developers in Germany and Switzerland prior to regulatory submission. |
| Precision Medicine Infrastructure Partnerships | Domestic biotech firm alliances in China under national initiatives secure long-term platform placement. |
Research Methodology
Cross-validation between primary interviews with laboratory directors, automation platform engineers, regulatory affairs specialists, and clinical diagnostic procurement managers and secondary sources anchors the qualitative findings. FDA 510(k) filings, EMA IVDR technical documentation, ISO 15189 accreditation records, and NMPA registration databases provide regulatory trajectory validation. Bottom-up demand modeling from instrument shipment data and top-down market sizing from consumable revenue disclosures were reconciled to establish baseline estimates.
Calibration against historical replacement cycles for robotic liquid handlers and NGS automation platforms informs the projection framework across the analysis window. Segmentation dimensions include product type, technology category, application focus, and end-user archetype, with regulatory compliance tier as an industry-specific overlay. CAGRs were derived from weighted average growth assumptions applied to each segment, incorporating precision medicine funding flows, diagnostic laboratory accreditation expansion rates, and pharmaceutical R&D automation adoption curves as key inputs.
Practitioners should monitor FDA guidance publication timing on laboratory-developed tests, NMPA import substitution policy shifts, and EMA IVDR implementation enforcement intensity for early signals of forecast revision. Cross-checking against disclosed capital expenditure plans at major diagnostic laboratory chains and pharmaceutical developers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Whole Genome Amplification Market
Genomics
Genomics Personalized Health Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
Agrigenomics Market
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Mitochondrial DNA Market
Genomics
Pharmacogenomics Technology Market
Genomics
Oligonucleotide Pool Market
Genomics
US Direct-To-Consumer Genetic Testing Market
Genomics
Nutrigenomics Testing Market
Genomics
Europe Digital PCR Market
Genomics
Global Molecular Cytogenetics Market