
 Lactic Acid Bacteria Market | 2026-2036
Lactic Acid Bacteria Market Size, Share, and Industry Trends Forecast 2026-2036
Lactic Acid Bacteria Market Insights
The nutraceutical end-user segment is pivoting toward clinically validated probiotic strains. Chr. Hansen Holding leverages its strain library to dominate human microbiome applications. IFF sustains competitive pressure through integrated enzyme and culture platforms. Lallemand specializes in yeast and bacteria synergies that extend its footprint across animal nutrition and human health.
Lactic acid bacteria comprise Gram-positive, non-spore-forming organisms that ferment carbohydrates into lactic acid as the primary metabolic end product, with optimal growth temperatures typically ranging from 30°C to 40°C depending on the species. These organisms serve industrial roles spanning food preservation, flavor development, and gut health modulation through defined colony-forming unit dosages. The Lactobacillus genus anchors the product type landscape through entrenched dairy fermentation demand, while probiotic applications within the application dimension command premium positioning due to clinical substantiation requirements. Powder and freeze-dried forms capture disproportionate margin pools owing to extended shelf stability and cold-chain flexibility.
EFSA novel food and health claim assessments shape European product development timelines, while FDA GRAS notifications govern US market entry for new strains. China's NMPA and national food safety standards increasingly scrutinize probiotic labeling and viable count claims. Stakeholders must monitor evolving strain-specific regulatory classifications that determine permissible health communications and geographic market access.
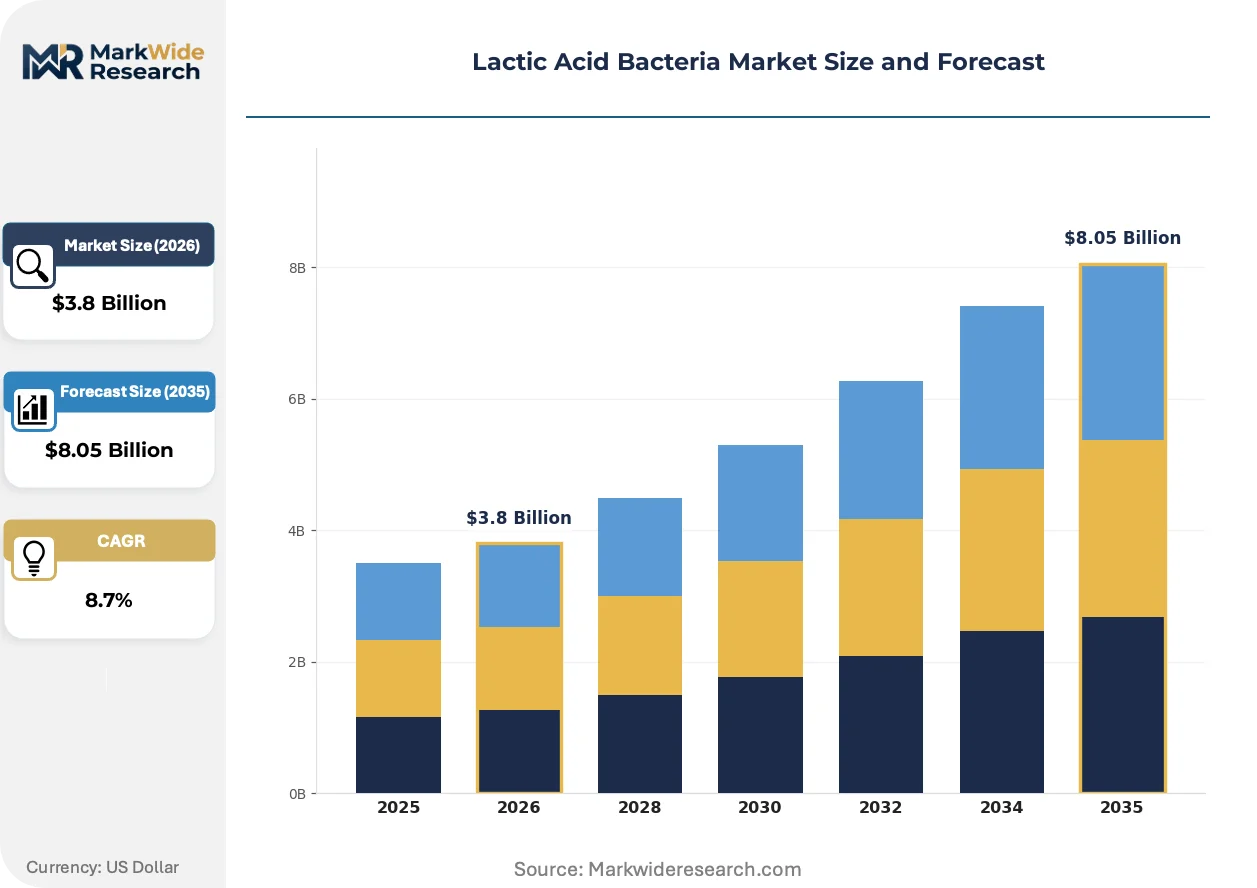
Market Dynamics
Strain-specific health claim substantiation is compressing product development timelines while elevating R&D barriers, forcing manufacturers to build proprietary clinical evidence libraries ahead of regulatory submissions.
Growth Catalysts
- EFSA Qualified Health Claim Pathways:European regulators now permit specific gut microbiome benefit communications for documented strains, incentivizing investment in human intervention studies.
- Fermented Dairy Capacity Expansion:Processing infrastructure buildouts across India and China are absorbing industrial starter culture volumes at scale.
- Freeze-Drying Protocol Advances:Optimized lyophilization methods are extending viable cell stability, reducing cold-chain dependency for probiotic distribution.
Market Restraints
- Raw Material Concentration:High-purity nitrogen sources and specialized growth media rely on a narrow supplier base concentrated in Western Europe.
- Clinical Validation Cost Burden:Human trials required for strain-specific health claims demand capital commitments that exclude smaller culture suppliers.
- Regulatory Asymmetry:Divergent viable count labeling standards between FDA GRAS notifications and China's NMPA requirements fragment formulation strategies.
Strategic Opportunities
- Companion Animal Microbiome:Pet nutrition formulators are integrating canine-specific Lactobacillus strains as functional ingredients in premium feed.
- Precision Fermentation Platforms:Cell-culture-derived metabolite production is converging with traditional fermentation to enable novel bioactive synthesis.
- Direct-to-Consumer Probiotic Channels:Subscription-based microbiome testing services are creating captive demand for personalized strain formulations.
Industry Challenges
- Strain Banking and Bioprospecting Expertise:Isolation and characterization of novel organisms requires rare taxonomic and genomics capabilities.
- Multi-Jurisdiction Registration Timelines:Synchronous approvals across FDA, EFSA, and NMPA systems strain regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactic Acid Bacteria Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactobacillus, Streptococcus, Pediococcus, Leuconostoc, Enterococcus Application: Dairy Fermentation, Meat Processing, Probiotics, Animal Feed, Biopreservation Form: Powder, Liquid, Freeze-Dried, Concentrate, Granules End User: Dairy Producers, Nutraceutical Companies, Animal Health Providers, Food Processors, Beverage Manufacturers |
| Companies Covered | Chr. Hansen Holding, IFF, Lallemand, DSM-Firmenich, Yakult Honsha, DuPont, Arla Foods Ingredients, Probi AB, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactic Acid Bacteria Market Trends and Innovations
Multi-omics characterization tools are redefining how manufacturers differentiate strains, shifting competitive advantage from production scale to biological specificity and mechanistic understanding.
CRISPR-guided strain engineering is electrifying the development pipeline. Dairy and supplement manufacturers are piloting genome-edited cultures with enhanced acid tolerance and bacteriocin output. This precision approach is compressing traditional breeding cycles from years to months while opening avenues for proprietary strain IP.
China's NMPA has tightened viable count verification protocols for imported probiotic formulations. Third-party laboratories now face mandatory accreditation requirements. European exporters are restructuring quality assurance workflows to accommodate batch-level testing documentation.
Ingredient buyers are consolidating supplier relationships around vertically integrated culture houses. Small and mid-sized dairy processors are abandoning spot-market purchasing in favor of multi-year fermentation service contracts. This preference shift is most pronounced in North American contract manufacturing networks.
Lactic Acid Bacteria Market Segmentation
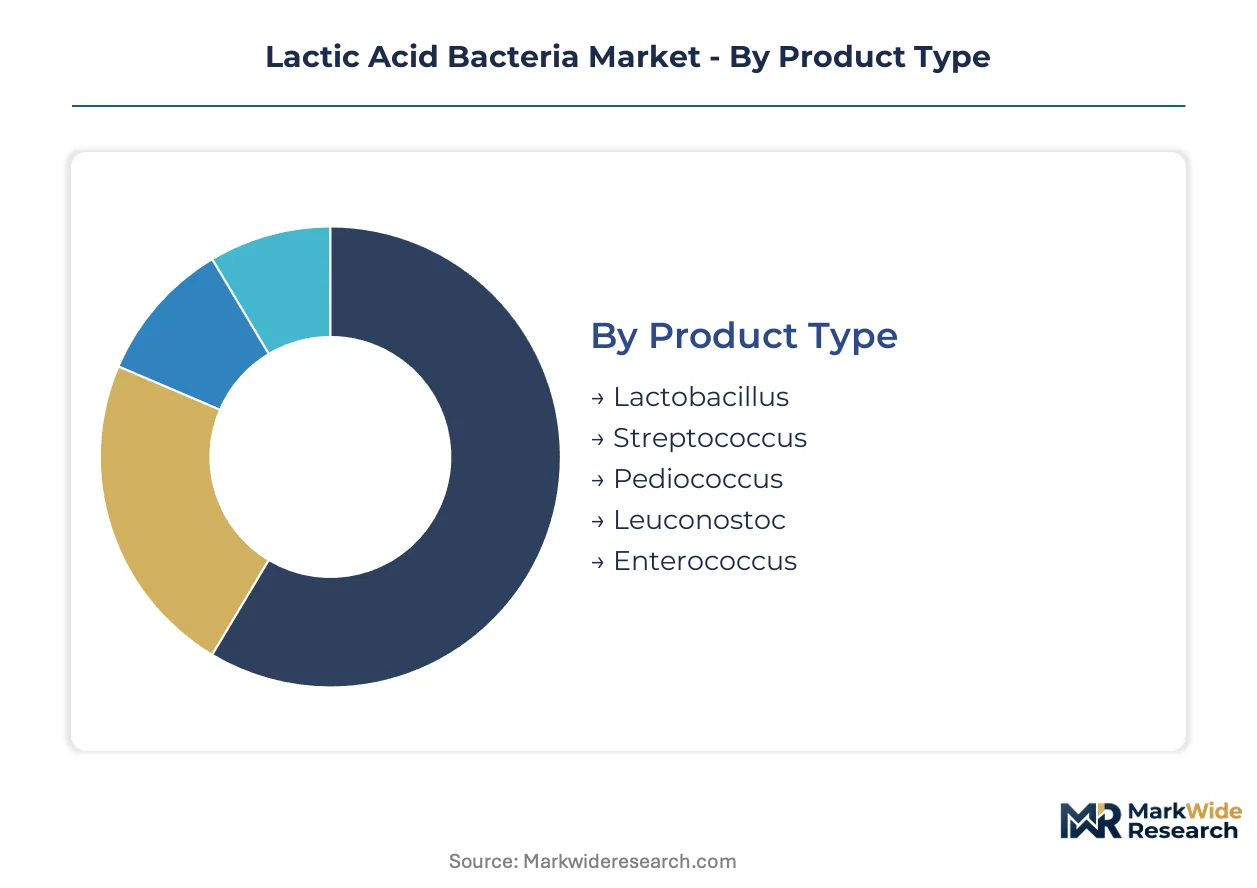
Strategic positioning in lactic acid bacteria hinges on matching strain capabilities to end-use specifications and regulatory pathways. Each segmentation dimension carries distinct margin profiles, certification burdens, and supply chain requirements that determine competitive viability.
Product Type:
EFSA novel food approvals and FDA GRAS notifications cluster heavily around specific genera, creating divergent market access timelines across strain categories.
- Lactobacillus:Gram-positive rods dominating dairy starter cultures and human probiotic formulations. Dairy processors in India and China absorb industrial-scale volumes for yogurt and cheese production, while nutraceutical manufacturers seek clinically documented strains for gut health positioning.
- Streptococcus:Cocci-shaped organisms essential for thermophilic fermentation chains in mozzarella and Swiss-type cheeses. Italian and Greek dairy cooperatives specify defined strain ratios for PDO-protected products, locking suppliers into long-term culture service contracts.
- Pediococcus:Tetracocci arrangements valued in silage inoculants and meat fermentation. US and Brazilian beef processors specify pediocin-producing strains for natural shelf-life extension.
- Leuconostoc:Heterofermentative cocci generating diacetyl and CO2 in butter cultures and vegetable ferments. European artisan dairy operations maintain niche demand for flavor-differentiated mesophilic blends.
- Enterococcus:Facultative anaerobes deployed in artisanal sausage fermentation and targeted probiotic applications. Strain-specific safety documentation requirements limit supplier participation in human health segments.
Lactobacillus sits at the top of the volume ranking, with Pediococcus climbing the fastest as meat processors adopt clean-label preservation strategies.
Application:
Margin capture varies sharply by application, with clinical substantiation requirements creating tiered pricing structures across functional benefit claims.
- Dairy Fermentation:Starter culture systems for cheese, yogurt, and fermented milk production. Large-scale cooperatives in France and the Netherlands negotiate multi-year supply agreements with defined performance specifications for acidification rates and phage resistance.
- Meat Processing:Fermented sausage and cured meat applications leveraging bacteriocin production for safety and flavor development. German and Spanish processors specify strain combinations for traditional product protection.
- Probiotics:Clinically validated strains delivered at defined colony-forming unit thresholds for human microbiome modulation. EFSA health claim assessments and China's NMPA viable count verification impose parallel compliance burdens on exporters.
- Animal Feed:Silage inoculants and direct-fed microbials for ruminant and poultry gut health. US dairy operations and Brazilian feedlots specify strain viability guarantees through storage and application windows.
- Biopreservation:Protective cultures replacing chemical preservatives in ready-to-eat foods. Clean-label demands from UK and Scandinavian retailers accelerate adoption in chilled prepared meals.
Dairy Fermentation commands the largest volume position, with Probiotics gaining share fastest as direct-to-consumer testing services create personalized formulation demand.
Form:
Cold-chain economics and shelf stability requirements drive form selection, with lyophilization capabilities concentrating among specialized culture houses.
- Powder:Spray-dried preparations offering cost-efficient bulk handling for industrial fermentation. Large dairy processors in Australia and Argentina specify powder forms for in-house culture propagation.
- Liquid:Fresh bulk cultures for immediate-use applications with minimal processing steps. Regional cheese plants in Wisconsin and Bavaria prefer liquid delivery for daily production scheduling.
- Freeze-Dried:Lyophilized preparations achieving extended viability without frozen storage. Premium probiotic brands specify freeze-dried forms for ambient distribution in Southeast Asian and Middle Eastern markets.
- Concentrate:High-cell-density preparations for direct vat inoculation. Industrial yogurt manufacturers value concentrates for reduced handling and standardized dosing.
- Granules:Free-flowing particulate forms for feed and agricultural applications. Poultry integrators in the US Southeast specify granule forms for automated delivery systems.
Freeze-Dried occupies the premium tier by margin, with Concentrate expanding most quickly as dairy processors seek operational simplification.
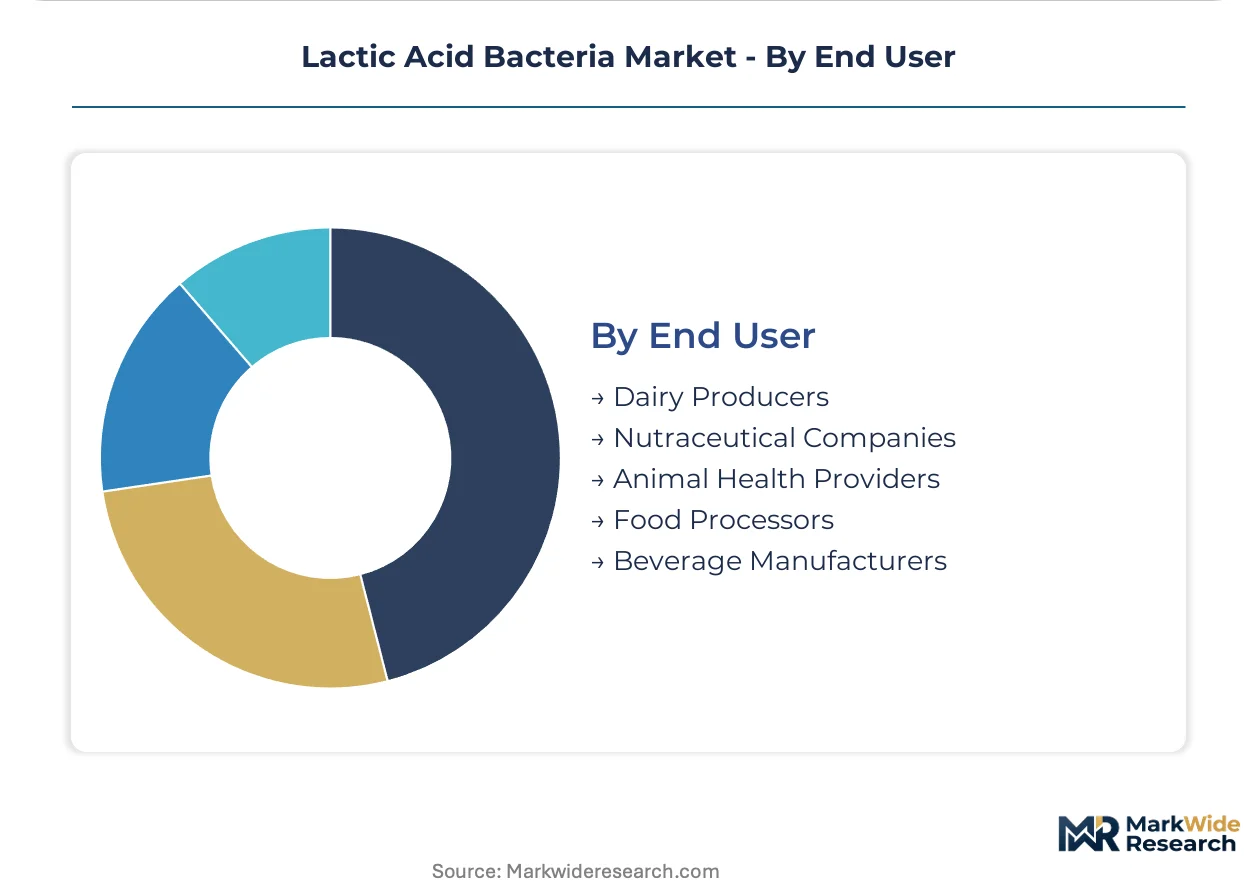
End User:
Procurement sophistication varies dramatically across end-user categories, determining supplier relationship structures and technical service intensity.
- Dairy Producers:Cooperatives and private processors specifying starter culture performance for defined product categories. French and Irish operations maintain technical staff capable of strain-level specification.
- Nutraceutical Companies:Supplement manufacturers requiring documented strain identity, stability data, and regulatory dossiers for health claim submissions. US and European brands invest in proprietary clinical studies to differentiate positioning.
- Animal Health Providers:Feed compounders and veterinary distributors integrating direct-fed microbials into ration formulations. Brazilian and US integrators specify viable count guarantees through feed manufacturing and storage.
- Food Processors:Prepared meal and ingredient manufacturers seeking biopreservation solutions for clean-label positioning. UK retailers drive specifications through approved supplier programs.
- Beverage Manufacturers:Kombucha, kefir, and functional drink producers requiring compatible strain systems for controlled fermentation. Small-batch operations in California and Berlin prioritize flavor consistency over standardization.
Dairy Producers anchor volume demand, with Nutraceutical Companies showing the steepest expansion trajectory as microbiome science advances commercial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting lactic acid bacteria production toward jurisdictions with streamlined strain approval pathways. Manufacturers now site fermentation capacity where viable count verification and novel food dossier requirements impose lower compliance burdens relative to market access value.
United States
FDA GRAS notification pathways for new probiotic strains attract culture houses seeking rapid market entry. The USDA BioPreferred program incentivizes domestic fermentation capacity for biopreservation applications. Wisconsin dairy clusters absorb industrial starter culture volumes through integrated cheese processing networks.
China
NMPA viable count verification protocols for imported probiotics are tightening quality assurance requirements on European exporters. SAMR national food safety standards now mandate batch-level testing documentation for strain identity claims. Yangtze River Delta dairy processors are expanding in-house culture propagation to reduce import dependency.
Germany
EFSA novel food assessments shape strain development timelines for human microbiome applications. The country's pharmaceutical regulator enforces documentation standards for clinical trial data supporting health claim submissions. Bavarian dairy cooperatives maintain technical specifications for defined acidification rates in PDO-protected cheese production.
India
FSSAI food safety standards are formalizing probiotic labeling requirements for domestic and imported formulations. The PLI scheme incentives extend to biotechnology manufacturing infrastructure including fermentation capacity. Gujarat and Maharashtra dairy processing clusters are absorbing industrial-scale starter culture volumes for yogurt and cheese production expansion.
France
ANSM oversight of clinical study protocols influences probiotic strain substantiation investments. The country's national agricultural research institute maintains culture collections supporting artisan dairy fermentation traditions. Normandy and Brittany dairy cooperatives specify strain ratios for AOC-protected products, locking suppliers into multi-year service contracts.
Lactic Acid Bacteria Market Competitive Landscape
Strain library acquisitions dominate the current landscape as manufacturers consolidate biological IP to secure regulatory dossiers. The vendor base stratifies across three tiers: global culture houses with proprietary clinical evidence libraries, regional fermentation specialists serving dairy cooperatives, and precision fermentation startups engineering novel metabolite pathways. Consolidated control concentrates in Scandinavian and North American headquarters. Capacity expansion and geographic licensing agreements represent the dominant competitive moves.
Within the integrated culture house tier, Chr. Hansen Holding and IFF exemplify archetypes built through decades of strain banking and regulatory dossier accumulation. Lallemand occupies a distinct position bridging yeast and bacteria synergies across animal nutrition and human health applications. These three entities anchor the premium tier where clinical substantiation capabilities determine market access.
| Leading Market Players |
|---|
| Chr. Hansen Holding |
| IFF |
| Lallemand |
| DSM-Firmenich |
| Yakult Honsha |
| DuPont |
| Arla Foods Ingredients |
| Probi AB |
| Kerry Group |
| Others |
Pricing and Supply Chain Analysis
Specialized nitrogen sources and growth media originating from Western European suppliers cascade through three distinct pricing tiers before reaching end-users, with cold-chain logistics costs amplifying margin compression for freeze-dried probiotic forms distributed to ambient-temperature markets.
Pricing Analysis
Distributor margins absorb the steepest markup layer for clinical-grade strains requiring batch-level documentation. Contract-based long-term offtake agreements dominate industrial starter culture procurement, while spot purchasing persists for smaller dairy processors. Price differentiation separates GRAS-notified strains from commodity starter cultures through certification investment and clinical substantiation depth. Pricing pressure stems from EFSA health claim validation costs compressing mid-tier supplier margins. Nutraceutical buyers exhibit lowest price sensitivity due to premium positioning requirements, whereas commodity dairy processors negotiate aggressively on per-CFU terms.
Supply Chain Analysis
Strain banking returns and culture collection refurbishment flows remain underdeveloped, creating bioprospecting bottlenecks for novel organism isolation. Supply concentrates in Denmark, France, and the United States where integrated culture houses maintain proprietary fermentation infrastructure. High-purity nitrogen sources, specialized growth media, and lyophilization equipment feed from a narrow Western European supplier base. Single-source vulnerability pervades cryogenic preservation logistics for master cell banks. Distribution runs through direct technical service relationships for large dairy cooperatives, with regional distributors handling smaller food processor accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's Qualified Health Claim Pathways function as a regulatory compounder, accelerating R&D investment as documented strains command premium positioning and exclusive market access.
For Market Incumbents: Cement proprietary clinical evidence libraries ahead of regulatory submissions to defend against precision fermentation startups engineering novel metabolite pathways. Expand backward integration into strain banking capabilities to secure bioprospecting expertise that emerging competitors cannot replicate. Prioritize multi-jurisdiction registration capacity to synchronize FDA, EFSA, and NMPA approvals.
For New Entrants and Emerging Players: Enter via companion animal microbiome applications where canine-specific strain development faces lower regulatory barriers than human health claims. Target Brazilian and US feedlot integrators with direct-fed microbials, as these buyers prioritize viable count guarantees over brand heritage. Pursue precision fermentation platforms converging with traditional culture production to enable novel bioactive synthesis.
For Investors and Strategic Acquirers: Consolidation pressure builds where clinical validation cost burdens exclude smaller culture suppliers from health claim substantiation. Five-to-ten year viability favors vertically integrated culture houses with proprietary strain libraries and regulatory dossier depth. Target acquisition archetypes include regional fermentation specialists with established dairy cooperative relationships and undeveloped probiotic portfolios. Monitor EFSA novel food approval timelines as inflection indicators for strain portfolio valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Acquisition | Consolidates biological IP to secure regulatory dossiers across EFSA and FDA pathways. |
| Precision Fermentation Scale-Up | Enables cell-culture-derived metabolite production converging with traditional fermentation methods. |
| Multi-Jurisdiction Registration Buildout | Expands regulatory affairs bandwidth to synchronize FDA, EFSA, and NMPA approval timelines. |
| Direct-to-Consumer Channel Launch | Captures subscription-based microbiome testing demand for personalized strain formulations. |
| Companion Animal Strain Development | Accesses pet nutrition formulators integrating canine-specific Lactobacillus in premium feed. |
Research Methodology
Direct dialogue with culture house R&D directors, regulatory affairs specialists at probiotic manufacturers, dairy cooperative procurement managers, and animal health feed formulators grounded the qualitative foundation. Secondary validation drew from EFSA novel food registers, FDA GRAS notification databases, NMPA import inspection records, and FSSAI labeling guidelines. Bottom-up strain-level volume estimates and top-down market sizing triangulated across fermentation capacity disclosures and end-use consumption patterns.
Segmentation outputs across product type, application, form, and end-user dimensions fed into the analytical framework over the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory milestone impacts and capacity expansion announcements. Forecast inputs incorporated EFSA health claim approval velocities, NMPA viable count verification protocol changes, and precision fermentation technology maturation curves.
Inputs from regulatory filing databases and culture house technical disclosures were available through the study window; gaps in private strain-level pricing data introduce uncertainty bands around margin estimates. Forecasts reflect assumptions regarding EFSA pathway efficiency, NMPA inspection intensity, and freeze-drying protocol adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Bacillus Subtilis Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Ripening Cultures Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Microbiomes Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Eubiotics Market