
 Acetylglucosamine Market | 2026-2036
Acetylglucosamine Market Size, Share, and Industry Trends Forecast 2026-2036
Acetylglucosamine Market Analysis
China is tilting toward pharmaceutical-grade acetylglucosamine capacity as domestic nutraceutical exports surge. Zhejiang Fengrun Biotech leverages integrated shellfish sourcing to control raw material costs across powder and capsule lines. Merck KGaA anchors European supply through high-purity fermentation routes for research institutions. Kaneka specializes in hyaluronic acid precursor applications, differentiating its acetylglucosamine position in cosmetics-grade segments.
Acetylglucosamine is a monosaccharide derivative of glucose with an acetylated amino group, typically refined to 98-99% purity for pharmaceutical and nutraceutical use through enzymatic hydrolysis of chitin sourced from crustacean shells. It serves primarily as a building block for glycosaminoglycan synthesis in joint health formulations, skin hydration products, and cell culture media. Powder dominates production volumes due to bulk ingredient economics, while capsules capture margin concentration in direct-to-consumer nutraceutical channels. The cosmetics application segment leads value growth as Korean and Japanese skincare brands integrate acetylglucosamine into ceramide-boosting formulations.
FDA dietary supplement GMPs and China's NMPA pharmaceutical purity standards shape product specifications and market access thresholds for acetylglucosamine suppliers. The EU's REACH framework governs chitin derivative imports, with ECHA classification requirements affecting registration costs for non-European manufacturers. Stakeholders must monitor regulatory divergence between pharmaceutical and food-grade pathways, as classification decisions in major jurisdictions will determine which production standards command premium positioning.
Market Dynamics
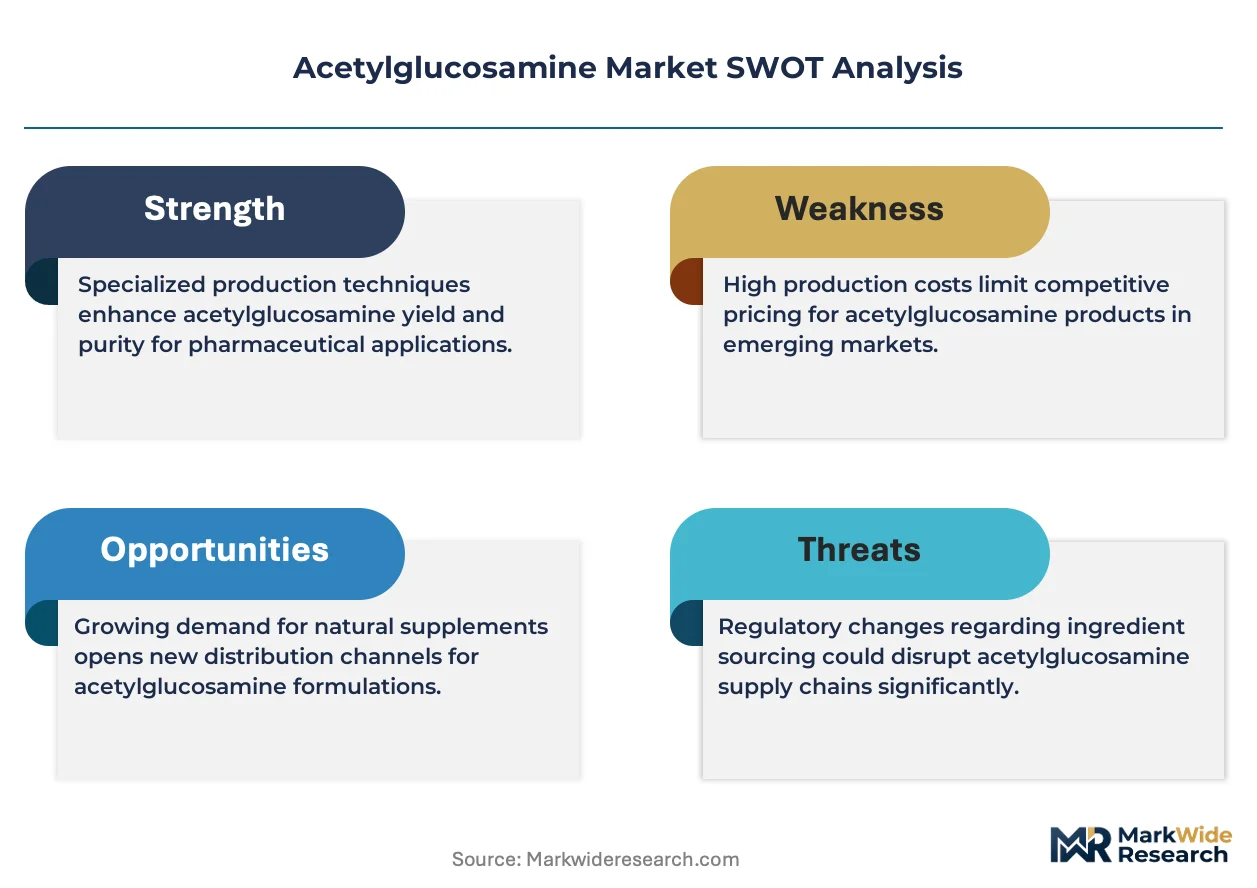
China's NMPA pharmaceutical-grade purity mandates are compressing shellfish-derived acetylglucosamine supply chains, forcing coastal processors to invest in enzymatic refining capacity or exit the API export market entirely.
Growth Catalysts
- Japan's aging demographic:Joint health supplement consumption among adults over 65 is expanding the nutraceutical application base for acetylglucosamine in Tokyo and Osaka metropolitan markets.
- REACH registration pathways:ECHA's streamlined chitin derivative dossier requirements are lowering market access barriers for East Asian fermentation-grade suppliers targeting EU cosmetics formulators.
- Fermentation biotechnology:Microbial synthesis routes are diversifying raw material sourcing beyond crustacean shell dependency, reducing seasonal supply volatility in coastal Zhejiang processing clusters.
Market Restraints
- Chitin input cost volatility:Shrimp and crab shell prices fluctuate with aquaculture harvest cycles in East Asian waters, squeezing margin stability for powder-grade producers.
- Shellfish allergen labeling:FDA and EFSA disclosure requirements for crustacean-derived ingredients limit formulation flexibility in North American and European direct-to-consumer channels.
- Hyaluronic acid substitution:Biosynthetic HA precursors from recombinant yeast are capturing share in premium skincare formulations, pressuring acetylglucosamine's cosmetics-grade positioning.
Strategic Opportunities
- South Korean medical tourism:Seoul-based aesthetic clinics are integrating acetylglucosamine into post-procedure recovery protocols, opening pharmaceutical-grade demand outside traditional supplement channels.
- Cell culture media expansion:Biopharmaceutical contract manufacturers are qualifying acetylglucosamine as a glycosylation modulator in monoclonal antibody production processes.
- China's dual carbon goals:MEE incentives for bio-based chemical processes are accelerating capital allocation toward enzymatic hydrolysis facilities with lower thermal energy intensity.
Industry Challenges
- Pharmaceutical-grade certification timelines:NMPA GMP audits for chitin-derived APIs require 18-24 month validation cycles, delaying revenue recognition for upgraded processing lines.
- Cross-batch enzymatic consistency:Variability in chitinase activity across shellfish substrate sources complicates standardization for research-grade cell culture applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetylglucosamine Market |
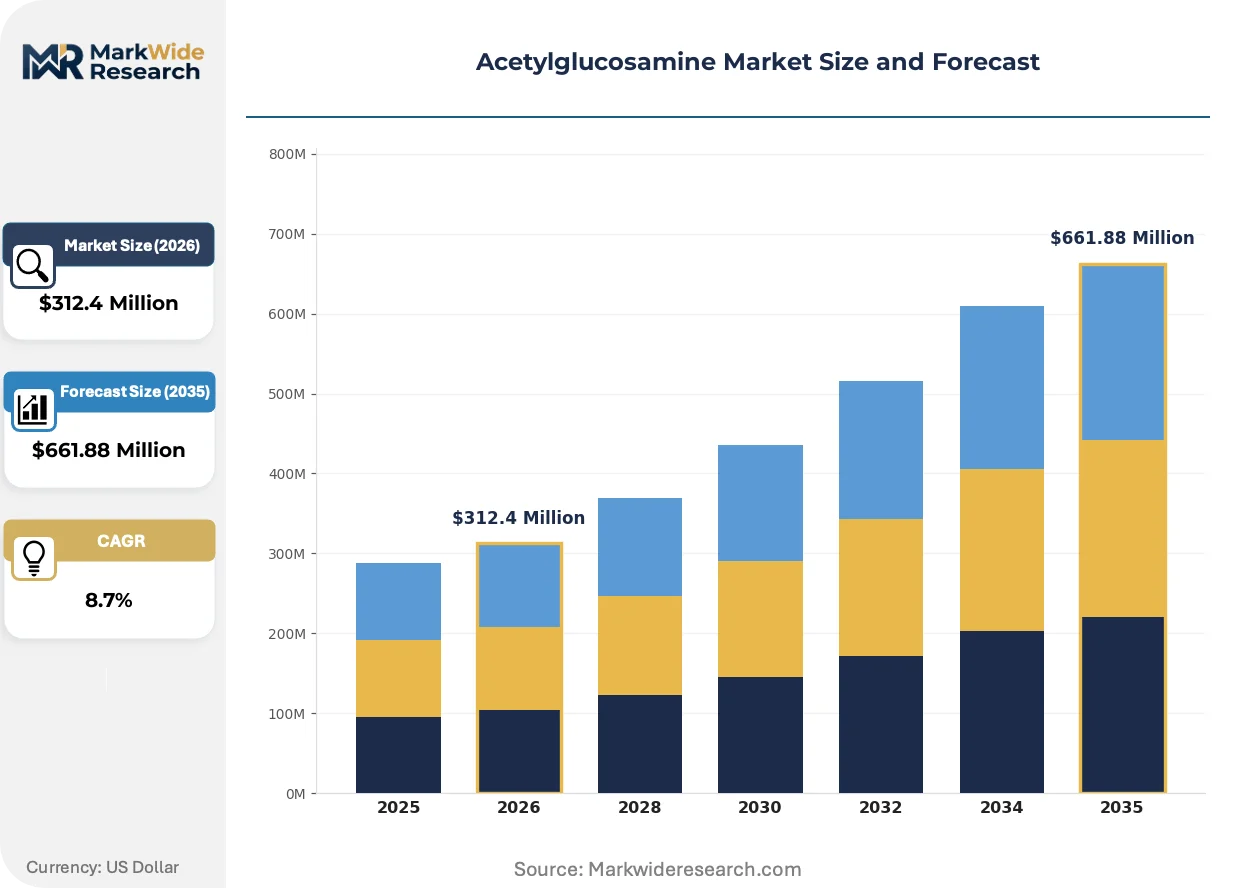
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Tablets, Liquid Application: Nutraceuticals, Pharmaceuticals, Cosmetics, Agriculture End User: Retail Consumers, Healthcare Providers, Research Institutions, Food Manufacturers Distribution Channel: Online, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Merck KGaA, Zhejiang Fengrun Biotech, Yaizu Suisankagaku Industry, Golden-Shell Pharmaceutical, Rixing Biotech, Amicogen, Bio-gen Extracts, Aoxin Group, Kaneka, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetylglucosamine Market Emerging Trajectories
Biotechnology convergence and regulatory stratification are fragmenting acetylglucosamine production into three distinct quality tiers, each serving non-interchangeable end-use specifications with diverging technical requirements.
Microbial fermentation of acetylglucosamine from engineered bacterial strains is rendering obsolete traditional shellfish hydrolysis for cosmetics-grade supply. Korean skincare conglomerates are qualifying fermentation-derived material at 99.5% purity for ceramide-boosting formulations. The structural consequence is a geographic decoupling of production from coastal shellfish processing infrastructure.
REACH Annex XVII amendments on chitin derivative hazard classification are tightening documentation burdens for EU-bound API shipments. German and French formulators are demanding third-party ECHA-registered certificates of analysis as a procurement precondition. Small-scale Zhejiang exporters lacking dedicated regulatory affairs capacity are retreating from European pharmaceutical channels.
Direct-to-consumer capsule brands are unbundling from traditional distributor networks and establishing proprietary e-commerce fulfillment operations. Japanese and South Korean supplement marketers are capturing margin previously allocated to pharmacy retail through subscription-based replenishment models. This channel shift is most pronounced in urban markets where mobile payment penetration exceeds 85%.
Acetylglucosamine Market Segmentation
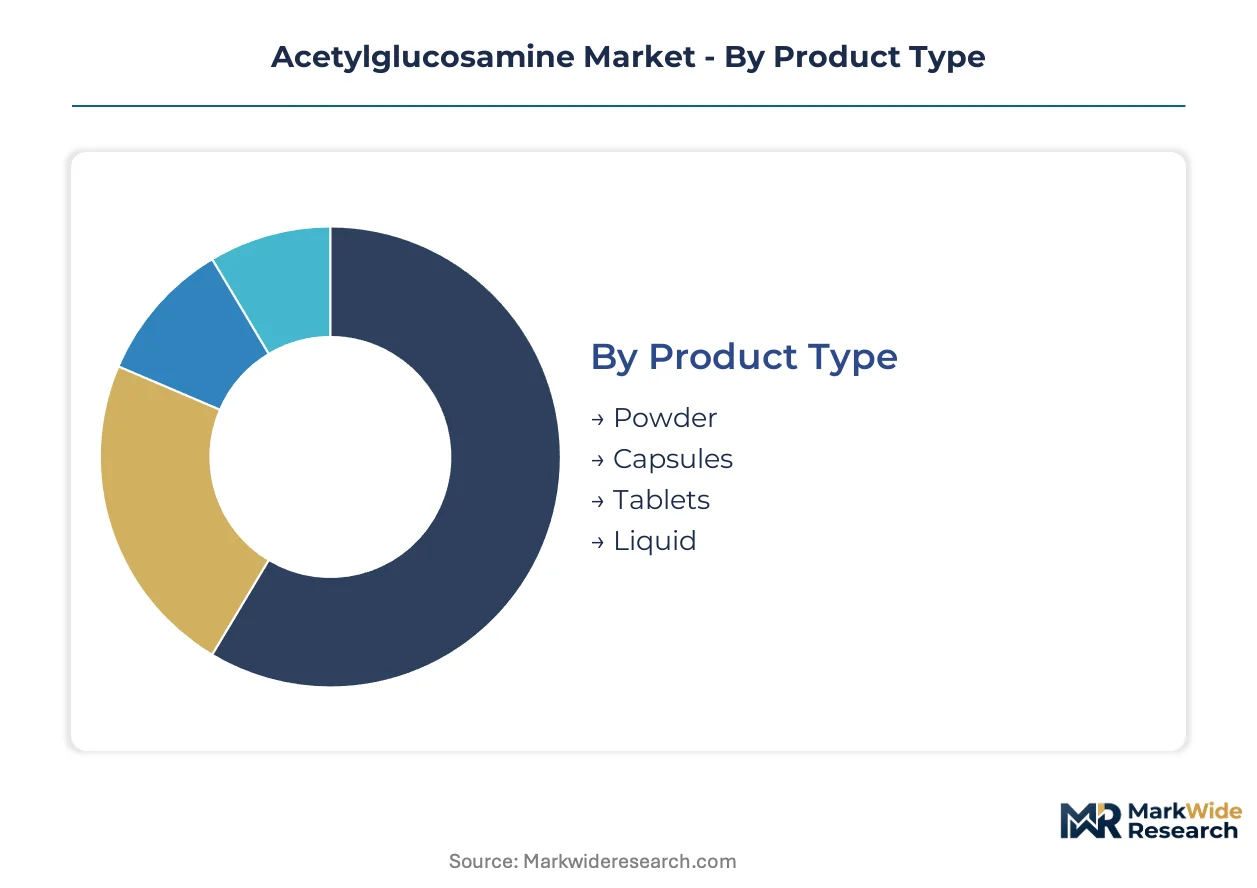
Acetylglucosamine demand fragments across four distinct qualification tiers, each commanding non-interchangeable purity specifications and procurement workflows. Product form and application pathway determine margin capture, while distribution channel selection increasingly separates direct-to-consumer brands from institutional supply relationships.
Product Type:
Powder turns over fastest in bulk ingredient procurement cycles, while finished dosage forms lock in longer manufacturing lead times and higher working capital requirements.
- Powder:Bulk crystalline material at 98-99% purity serves as the foundational feedstock for nutraceutical formulators and pharmaceutical compounders. Demand concentrates in East Asian coastal manufacturing clusters where shellfish processing infrastructure enables integrated enzymatic refining operations.
- Capsules:Encapsulated dosage forms command premium positioning in direct-to-consumer joint health supplements, particularly through Japanese and South Korean e-commerce subscription channels where mobile payment penetration exceeds 85%.
- Tablets:Compressed formulations with binders and coatings target pharmacy retail distribution in European markets governed by EFSA allergen disclosure requirements.
- Liquid:Aqueous solutions and syrups serve pediatric and geriatric populations with swallowing difficulties, primarily through hospital and clinic procurement channels in Seoul and Tokyo metropolitan markets.
Powder anchors the volume base while capsules gain share at the steepest rate.
Application:
Cost tier stratification separates commodity nutraceutical supply from pharmaceutical-grade API qualification, with cosmetics applications occupying a mid-tier purity band with distinct technical documentation requirements.
- Nutraceuticals:Dietary supplement formulations for joint health dominate commercial volumes, with Japanese adults over 65 driving sustained consumption in Tokyo and Osaka metropolitan markets.
- Pharmaceuticals:API-grade material meeting NMPA and FDA GMP standards serves glycosaminoglycan synthesis pathways, requiring 18-24 month validation cycles for upgraded processing lines.
- Cosmetics:Ceramide-boosting skincare formulations from Korean conglomerates are qualifying fermentation-derived material at 99.5% purity, decoupling production from coastal shellfish infrastructure.
- Agriculture:Chitin derivative applications in crop protection and soil amendment represent emerging demand with lower purity thresholds and minimal regulatory documentation burdens.
Nutraceuticals capture the broadest volume base while cosmetics applications expand most quickly.
End User:
Customer type determines procurement sophistication, with research institutions demanding batch-specific certificates of analysis and retail channels prioritizing brand positioning over technical specifications.
- Retail Consumers:Direct purchasers through online and pharmacy channels drive capsule and tablet volumes, with subscription-based replenishment models capturing margin previously allocated to distributor networks.
- Healthcare Providers:Hospitals and aesthetic clinics in Seoul are integrating pharmaceutical-grade acetylglucosamine into post-procedure recovery protocols, opening demand outside traditional supplement channels.
- Research Institutions:Cell culture media applications require glycosylation modulator qualification for monoclonal antibody production, with biopharmaceutical contract manufacturers demanding cross-batch enzymatic consistency.
- Food Manufacturers:Functional ingredient incorporation into fortified foods and beverages operates under food-grade regulatory pathways with lower purity mandates than pharmaceutical channels.
Retail consumers anchor volume throughput while research institutions command the steepest pricing premiums.
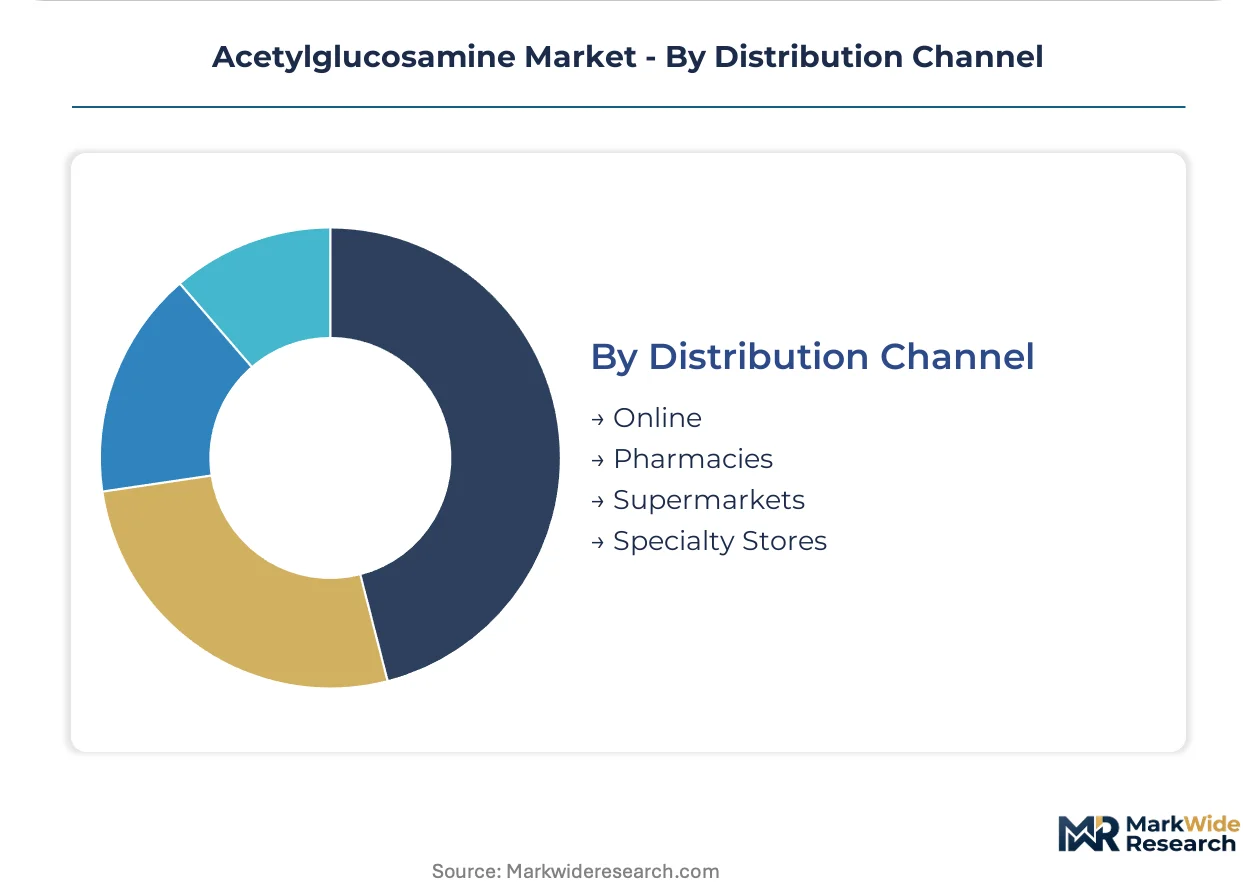
Distribution Channel:
Channel selection increasingly determines margin retention, with direct e-commerce operations unbundling brands from traditional wholesale markups.
- Online:Direct-to-consumer platforms and subscription services are displacing pharmacy retail in Japanese and South Korean urban markets, enabled by integrated logistics networks and mobile payment infrastructure.
- Pharmacies:Brick-and-mortar retail maintains relevance for first-time purchasers seeking professional guidance, particularly in European markets with established pharmacist consultation traditions.
- Supermarkets:Mass-market retail channels distribute economy-tier powder and capsule products with simplified labeling and lower price positioning.
- Specialty Stores:Nutrition and wellness boutiques curate premium formulations with third-party certifications, serving educated consumers in metropolitan markets.
Online channels capture the steepest growth trajectory while pharmacies retain defensive positioning in consultation-dependent purchase decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA pharmaceutical-grade purity mandates in China are compressing shellfish-derived supply chains and forcing coastal processors toward enzymatic refining investments. This regulatory pressure radiates across East Asian manufacturing clusters, reshaping export competitiveness and raw material sourcing patterns.
China
Zhejiang coastal processors dominate enzymatic hydrolysis capacity, feeding nutraceutical export demand. NMPA tightened purity standards for chitin-derived APIs, pushing domestic producers toward pharmaceutical-grade refining or market exit. The Yangtze River Delta manufacturing belt concentrates shellfish processing infrastructure with integrated powder and capsule production lines.
Japan
Adults over 65 in Tokyo and Osaka metropolitan markets sustain joint health supplement consumption. PMDA dietary supplement regulations govern capsule and tablet formulations distributed through pharmacy and direct-to-consumer channels. Kanto and Kansai regions host formulators integrating acetylglucosamine into subscription-based replenishment models.
South Korea
Seoul-based aesthetic clinics are adopting pharmaceutical-grade material for post-procedure recovery protocols outside traditional supplement channels. MFDS cosmetic ingredient regulations shape ceramide-boosting skincare formulation standards. The Seoul Capital Area anchors both medical tourism demand and Korean conglomerate cosmetics-grade qualification programs.
Germany
Research institutions in Bavaria and North Rhine-Westphalia qualify high-purity material for cell culture media applications. ECHA REACH Annex XVII amendments on chitin derivative hazard classification tighten documentation burdens for API shipments. German formulators demand third-party registered certificates of analysis as procurement preconditions.
United States
FDA dietary supplement GMPs govern powder and capsule imports for direct-to-consumer joint health products. Shellfish allergen labeling requirements limit formulation flexibility in retail channels. The dietary supplement contract manufacturing belt in Utah and California processes bulk crystalline material into finished dosage forms.
Acetylglucosamine Market Vendor Landscape
Vertically integrated coastal processors and fermentation biotechnology specialists split the market along raw material sourcing lines. Shellfish-derived supply chains concentrate in East Asian coastal clusters where enzymatic refining infrastructure controls input costs. Microbial synthesis routes are emerging as a second archetype, decoupling production from crustacean shell dependency. Dominant competitive moves include backward integration into shellfish processing infrastructure and technology licensing for bacterial strain engineering.
Within the integrated processor tier, Zhejiang Fengrun Biotech and Golden-Shell Pharmaceutical occupy positions anchored to coastal Zhejiang shellfish sourcing. Merck KGaA exemplifies the fermentation-grade archetype serving European research institutions. Kaneka sits within the cosmetics-grade specialization vector, differentiating through hyaluronic acid precursor applications. These three represent distinct strategic postures without interchangeable competitive positioning.
| Leading Market Players |
|---|
| Merck KGaA |
| Zhejiang Fengrun Biotech |
| Yaizu Suisankagaku Industry |
| Golden-Shell Pharmaceutical |
| Rixing Biotech |
| Amicogen |
| Bio-gen Extracts |
| Aoxin Group |
| Kaneka |
| Others |
Supply Flow & Price Mechanics
Chitin input cost volatility from East Asian aquaculture harvest cycles compresses margin stability for powder-grade producers while simultaneously forcing enzymatic refining investments that widen spreads between pharmaceutical and nutraceutical tiers. This raw material instability determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic clustering of supply chain nodes around coastal shellfish processing infrastructure.
Pricing Analysis
Coastal Zhejiang processors command lower unit economics than European fermentation-grade suppliers due to integrated shellfish sourcing, yet NMPA pharmaceutical-grade certification requirements inflate Chinese API pricing by 40-60% over nutraceutical powder. Price differentiation rests on purity thresholds and regulatory documentation burdens, with cosmetics-grade fermentation material from Korean conglomerates occupying a mid-tier position. Cost compression in standard-grade powder is intensifying because seasonal shellfish price swings erode processor margins. Retail consumers through subscription channels show lowest price sensitivity, while bulk nutraceutical compounders negotiate aggressively on volume.
Supply Chain Analysis
Shrimp and crab shell availability from East Asian coastal waters anchors upstream feedstock concentration, with enzymatic hydrolysis capacity clustering in China's Yangtze River Delta and Japan's Chubu region. Production draws from crustacean processing waste streams, microbial fermentation substrates, and research-grade synthetic routes. Single-source vulnerability persists for shellfish-derived material during aquaculture disease outbreaks or climate-disrupted harvests. Distribution runs through direct e-commerce fulfillment for capsule brands, institutional procurement contracts for pharmaceutical APIs, and third-party logistics networks for bulk powder shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biosynthetic hyaluronic acid precursors from recombinant yeast threaten acetylglucosamine's cosmetics-grade positioning, forcing incumbents to defend through purity differentiation and application-specific qualification rather than cost competition alone.
For Market Incumbents: Pre-empt substitution risk by accelerating fermentation-grade capacity for 99.5% purity cosmetics applications before hyaluronic acid captures additional skincare share. Deepen upstream control over shellfish processing infrastructure in Zhejiang to insulate margin from aquaculture price volatility. Pursue NMPA pharmaceutical-grade certification for upgraded enzymatic refining lines to access premium API export channels before smaller coastal processors exit. For New Entrants and Emerging Players: Seoul-based aesthetic clinic networks represent the most penetrable entry point for pharmaceutical-grade material outside traditional supplement distribution. Cell culture media qualification for monoclonal antibody production offers white-space demand with steep pricing premiums and limited incumbent specialization. Establish direct relationships with biopharmaceutical contract manufacturers rather than competing through nutraceutical commodity channels. For Investors and Strategic Acquirers: NMPA's tightened purity standards for chitin-derived APIs reshape the acquisition landscape toward processors with validated enzymatic refining infrastructure and existing pharmaceutical-grade certification timelines. Long-term viability favors fermentation biotechnology specialists decoupled from crustacean shell dependency. Monitor ECHA REACH Annex XVII amendment implementation as the signal for which East Asian exporters can sustain European market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shellfish Processing | Zhejiang coastal processors secure captive raw material supply against aquaculture price swings. |
| Fermentation Biotechnology Scale-Up | Microbial synthesis routes from engineered bacterial strains reduce seasonal supply volatility. |
| Pharmaceutical-Grade Certification Investment | NMPA GMP validation opens premium API export channels with 18-24 month revenue cycles. |
| Direct-to-Consumer E-Commerce Launch | Japanese subscription models capture margin previously allocated to pharmacy retail networks. |
| Cell Culture Media Qualification | Biopharmaceutical contract manufacturers demand glycosylation modulators for monoclonal antibody production. |
Methodological Framework
Initial hypotheses were tested against primary input from nutraceutical formulators, pharmaceutical API procurement managers, cosmetics R&D directors, and shellfish processing facility operators, then refined through secondary validation against NMPA regulatory filings, ECHA REACH registration databases, MFDS cosmetic ingredient standards, and East Asian customs trade data. Bottom-up volume estimates from enzymatic refining capacity and top-down demand calibration from end-use consumption patterns were triangulated to resolve discrepancies.
Demand-supply-balance modeling across the analysis window incorporated grade tier stratification, application pathway qualification requirements, and regional regulatory cluster differentiation. CAGRs were derived from segmented growth trajectory analysis rather than single-point extrapolation. Forecast inputs included NMPA audit timeline distributions for pharmaceutical-grade certification, ECHA registration cost burdens for EU market access, and fermentation yield improvement curves from microbial synthesis development programs.
Practitioners should monitor NMPA enforcement patterns for pharmaceutical-grade purity mandates and ECHA hazard classification amendments for early signals of supply chain compression or market access restriction. Cross-checking against MFDS cosmetic ingredient qualification trends and Kanto region subscription channel growth rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
Aptamers Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Global Cell Isolation/Cell Separation Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Plasma Feed Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Serine Protease Market
Biotechnology Services
Precast Agarose Gel Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Research Antibodies and Reagents Market